
 ASEAN Road Freight Transport Market | 2026-2036
ASEAN Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Road Freight Transport Market Outlook
Thailand's Phase 2 emission standards for heavy-duty diesel vehicles is realigning procurement priorities across ASEAN fleet operators. DHL Group leverages its integrated network density to sustain cross-border lane dominance between Thailand and Vietnam. CJ Logistics Corporation anchors its Southeast Asian expansion through dedicated automotive logistics corridors serving Hyundai and Kia assembly plants. Gemadept competes on port-to-inland connectivity, controlling container drayage flows through Cai Mep and Laem Chabang.
Road freight transport encompasses the movement of goods via motorized vehicles over paved highway infrastructure, utilizing trucks with gross vehicle weights ranging from 3.5 tonnes to over 40 tonnes, vans under 3.5 tonnes, and specialized trailers designed for containerized or bulk cargo. The primary commercial purpose centers on last-mile delivery, inter-factory parts shuttles, and long-haul distribution between production zones and consumption centers. Full Truck Load services dominate margin pools on major ASEAN corridors due to economies of scale on high-volume lanes, while Less Than Truck Load offerings capture fragmented shipper demand across tier-two cities. E-commerce end users represent the fastest-expanding demand segment as platform fulfillment networks require flexible, high-frequency delivery scheduling.
ASEAN member states operate under the ASEAN Framework Agreement on the Facilitation of Goods in Transit, which harmonizes cross-border road transport permits and customs procedures. Thailand's Department of Land Transport enforces vehicle weight and emission compliance, while Vietnam's Ministry of Transport governs international road freight licensing under bilateral agreements with Cambodia and Laos. Indonesia's National Standardization Agency mandates BIS-equivalent certification for imported commercial vehicle components. Stakeholders must monitor regulatory divergence on driver hours-of-service rules and carbon reporting obligations as these frameworks mature across member states.
Market Dynamics
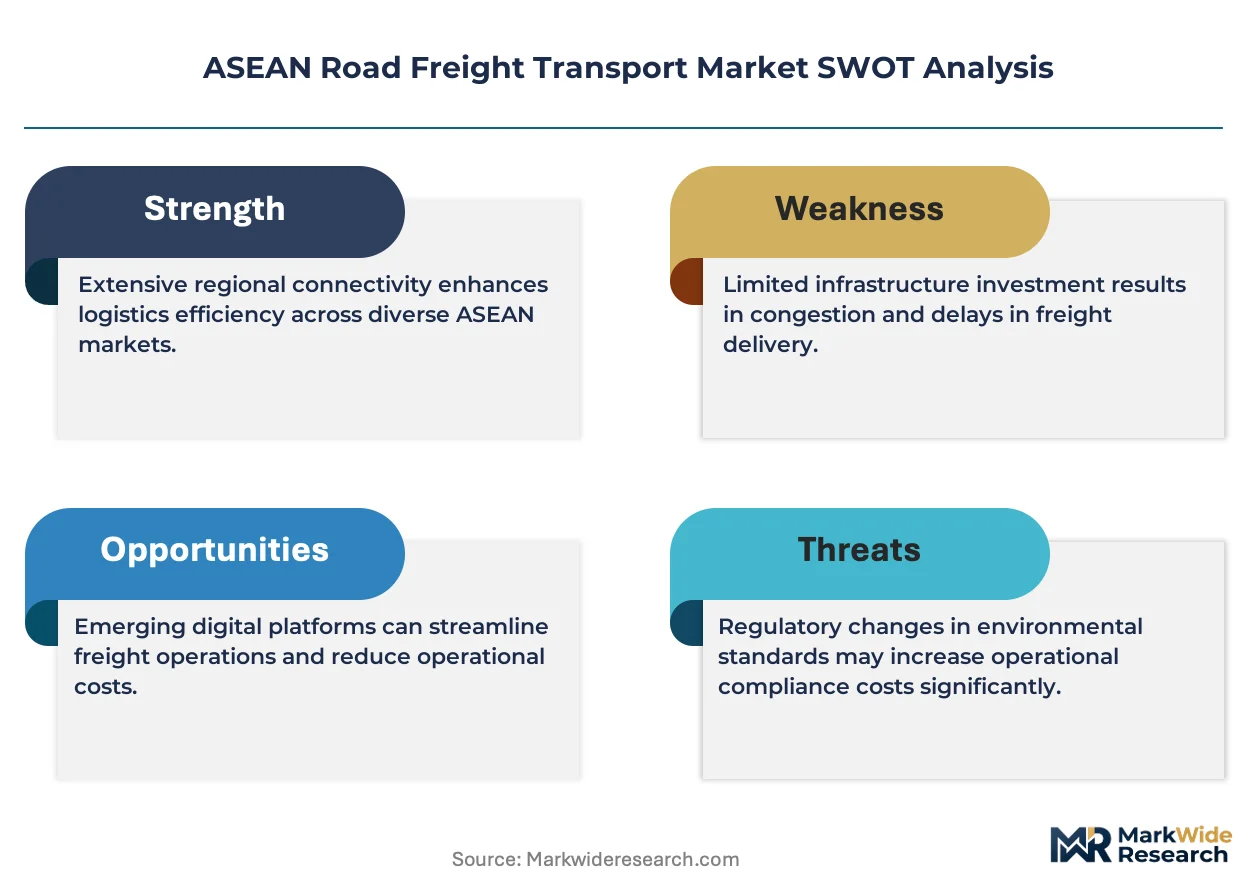
Thailand's Phase 2 emission standards for heavy-duty diesel vehicles are forcing fleet operators across ASEAN to accelerate procurement of Euro 5-compliant trucks and compressed natural gas alternatives, compressing replacement cycles and reshaping supplier relationships.
Growth Catalysts
- E-commerce fulfillment networks:Platform operators in Vietnam and Indonesia are expanding same-day delivery coverage into tier-two cities, creating sustained demand for flexible fleet capacity.
- ASEAN Framework Agreement on the Facilitation of Goods in Transit:Harmonized cross-border permits between Thailand, Vietnam, and Cambodia are reducing customs dwell times on key corridors.
- Manufacturing corridor densification:Industrial parks in Binh Duong and Bac Ninh provinces are generating concentrated inter-factory parts shuttle volumes.
Market Restraints
- Commercial vehicle import duties:Indonesia's National Standardization Agency mandates BIS-equivalent certification for components, adding compliance costs and extending procurement timelines.
- Fuel price volatility:Diesel represents 35-45% of operating costs for ASEAN long-haul operators, with limited hedging instruments available in local currencies.
- Driver shortage concentration:Malaysia's restricted foreign worker permits have tightened qualified driver availability on cross-border lanes serving Singapore.
Strategic Opportunities
- Cold chain underpenetration:Indonesia's archipelago geography leaves pharmaceutical and fresh produce segments underserved by temperature-controlled road freight.
- Digital freight matching platforms:Real-time load-board adoption among small fleet owners in the Philippines is reducing empty backhaul kilometers.
- Carbon border adjustment preparation:Vietnam's Ministry of Transport is piloting emissions tracking protocols that will qualify exporters for EU market access.
Industry Challenges
- Telematics integration complexity:Fleet management system migration from legacy hardware to cloud-native platforms requires specialized IT talent scarce in Laos and Cambodia.
- Cross-border documentation variance:Divergent driver hours-of-service enforcement between Thailand and Vietnam creates compliance scheduling conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Road Freight Transport Market |
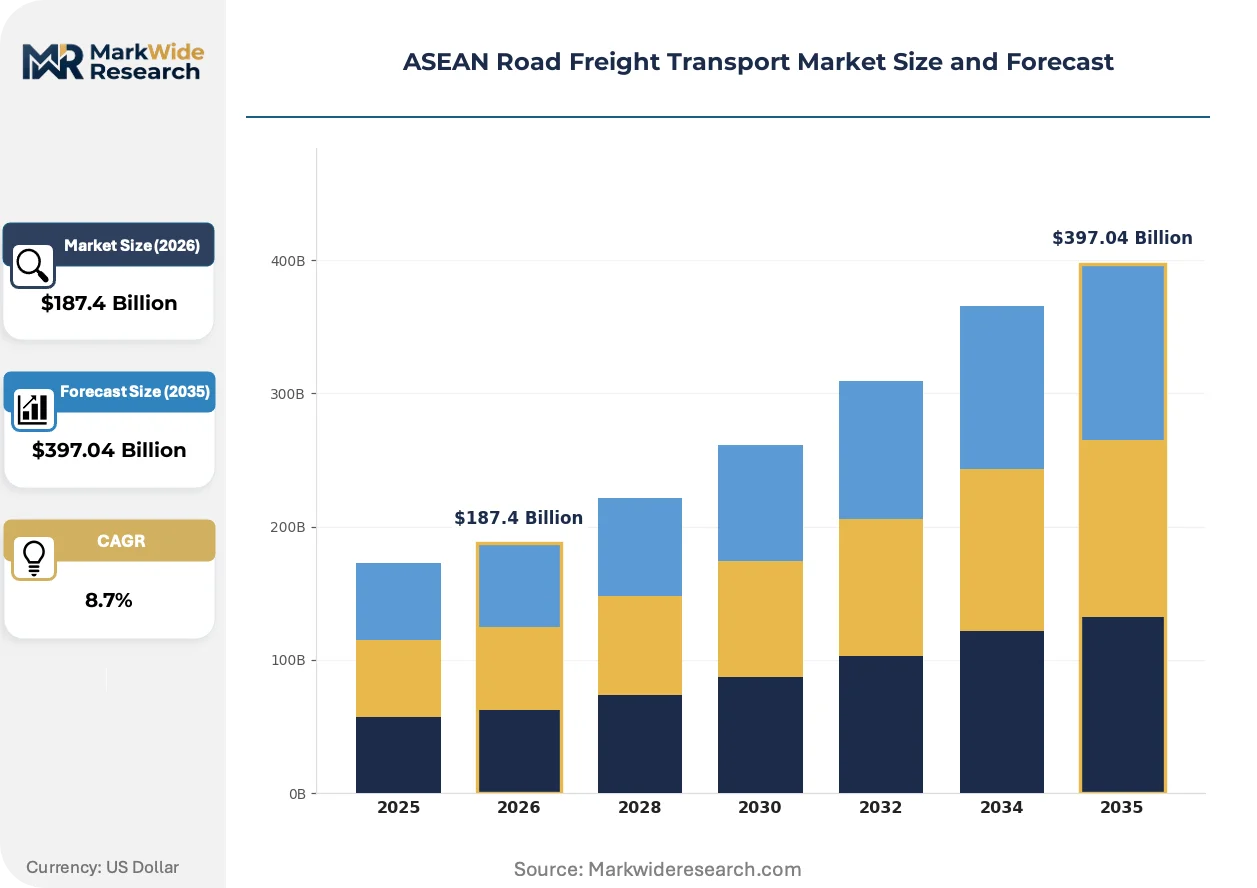
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Truck, Van, Trailer, Container Service Type: Full Truck Load, Less Than Truck Load, Dedicated Freight, Intermodal Industry Vertical: Consumer Goods, Agriculture, Automotive, Pharmaceuticals End User: Manufacturers, Retailers, Distributors, E-commerce |
| Companies Covered | DHL Group, Konoike Group, SF Express (KEX-SF), Tiong Nam Logistics Holdings Bhd, “K” Line Logistics, Ltd., DSV A/S, CJ Logistics Corporation, Gemadept, Profreight Group, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Road Freight Transport Market Strategic Shifts
Digitalization and alternative powertrains are converging to restructure how ASEAN fleet operators manage asset utilization and regulatory compliance across fragmented national markets.
Telematics platforms combining GPS tracking, fuel consumption monitoring, and predictive maintenance algorithms are integrating into fleet management workflows. Large shippers in Thailand's automotive sector are mandating real-time visibility as a contract condition. This capability compression is squeezing smaller operators unable to absorb hardware and subscription costs.
Thailand's Department of Land Transport is accelerating enforcement of vehicle weight and emission compliance through roadside automated inspection stations. Heavy-duty diesel trucks face escalating penalties for non-compliance. Fleet operators are responding by pre-positioning newer assets on high-risk corridors and retiring aging units ahead of schedule.
Shippers in Vietnam's electronics manufacturing sector are consolidating vendor relationships and demanding dedicated contract capacity rather than spot market reliance. Long-term agreements with guaranteed volume commitments are displacing transactional freight procurement in Ho Chi Minh City industrial zones. This concentration pattern is visible across semiconductor and consumer appliance supply chains.
ASEAN Road Freight Transport Market Segmentation
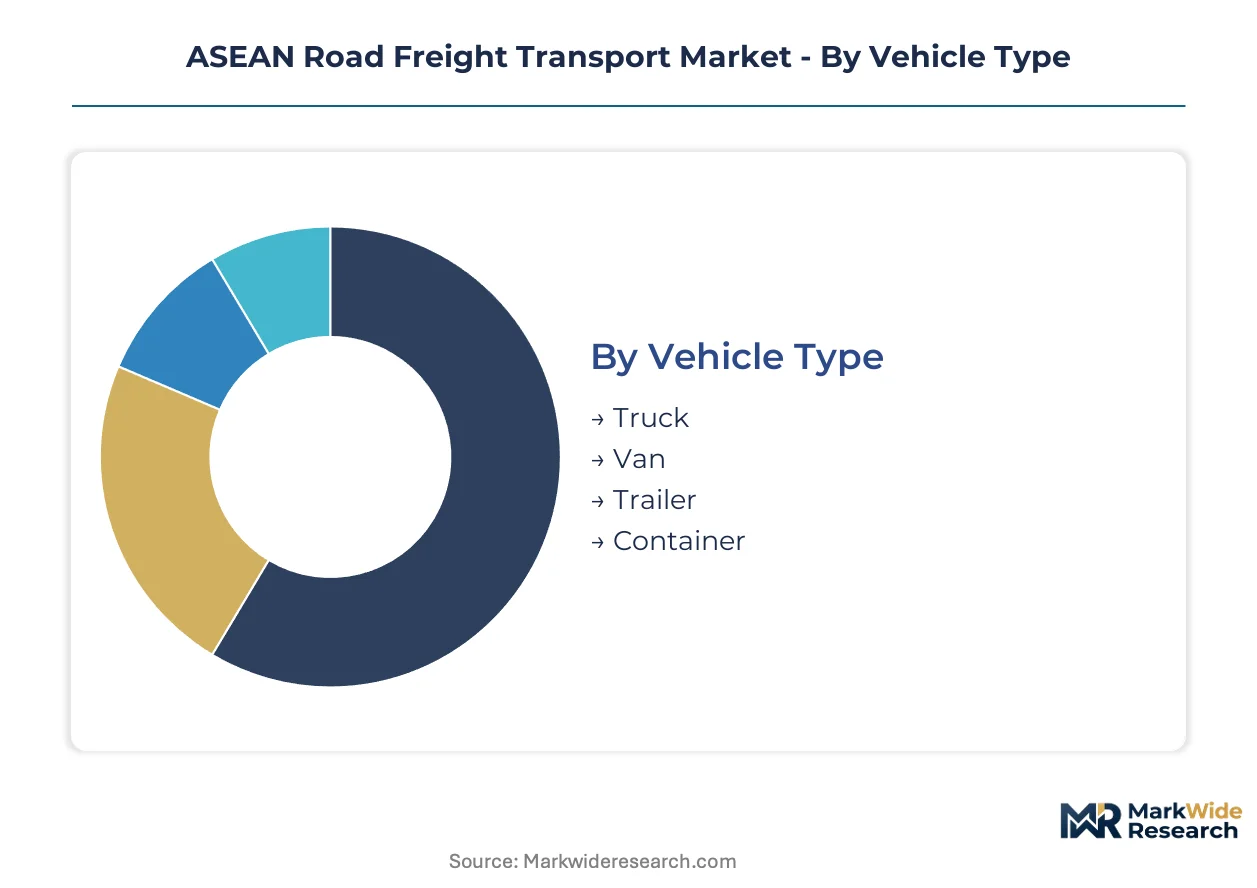
ASEAN road freight segmentation reveals how fleet operators align asset classes with corridor economics and cargo characteristics. Vehicle configuration and service bundling decisions determine margin capture across fragmented national regulatory environments.
Vehicle Type:
Heavy-duty trucks command premium rates on long-haul manufacturing corridors, while lighter vehicles dominate urban last-mile economics.
- Truck:Heavy-duty diesel and CNG-powered units with gross vehicle weights exceeding 12 tonnes handle concentrated manufacturing flows between Thailand's Eastern Economic Corridor and Vietnam's northern industrial provinces. Fleet operators are accelerating Euro 5 procurement ahead of Thailand's Phase 2 enforcement deadlines.
- Van:Vehicles under 3.5 tonnes navigate dense urban delivery networks in Jakarta, Bangkok, and Ho Chi Minh City. E-commerce platforms in Indonesia and Vietnam are contracting dedicated van capacity for same-day fulfillment coverage expansion into tier-two cities.
- Trailer:Flatbed and curtain-sided configurations serve project cargo and non-containerized bulk movements across Mekong Delta manufacturing zones.
- Container:Chassis units optimized for 20-foot and 40-foot ISO container drayage connect Cai Mep and Laem Chabang port hinterlands to inland distribution centers.
Today's leader: Truck. Tomorrow's challenger: Van.
Service Type:
Contract structure determines pricing power and asset utilization predictability across ASEAN's uneven infrastructure quality.
- Full Truck Load:Dedicated vehicle capacity for single-shipper volumes dominates high-frequency lanes between Binh Duong automotive clusters and Laem Chabang export terminals. Margins compress on backhaul legs without return cargo consolidation.
- Less Than Truck Load:Multi-shipper consolidation captures fragmented demand across tier-two Indonesian and Philippine cities where manufacturing density cannot support dedicated truck economics.
- Dedicated Freight:Long-term contracted capacity with guaranteed volume commitments is displacing spot procurement among Vietnam's electronics manufacturers seeking supply chain reliability.
- Intermodal:Road-rail and road-sea combinations reduce fuel exposure on Indonesia's archipelago routes and Thailand's northeastern corridors.
Full Truck Load holds contract value concentration. Less Than Truck Load is gaining share fastest through digital freight matching adoption.
Industry Vertical:
Cargo characteristics dictate equipment specialization and regulatory compliance intensity across ASEAN manufacturing bases.
- Consumer Goods:High-velocity replenishment cycles for electronics and appliances drive demand for flexible scheduling and real-time visibility in Vietnam's northern industrial parks.
- Agriculture:Seasonal harvest flows from Thailand's central plains and Vietnam's Mekong Delta require surge capacity with limited temperature control penetration.
- Automotive:Just-in-time parts shuttles between Thailand's Rayong assembly complexes and component suppliers demand precision timing and dedicated fleet allocation.
- Pharmaceuticals:Cold chain requirements remain underserved across Indonesia's island geography, creating compliance gaps for temperature-sensitive distribution.
Automotive anchors premium service tiers. Pharmaceuticals represents the steepest expansion trajectory as regulatory compliance intensifies.
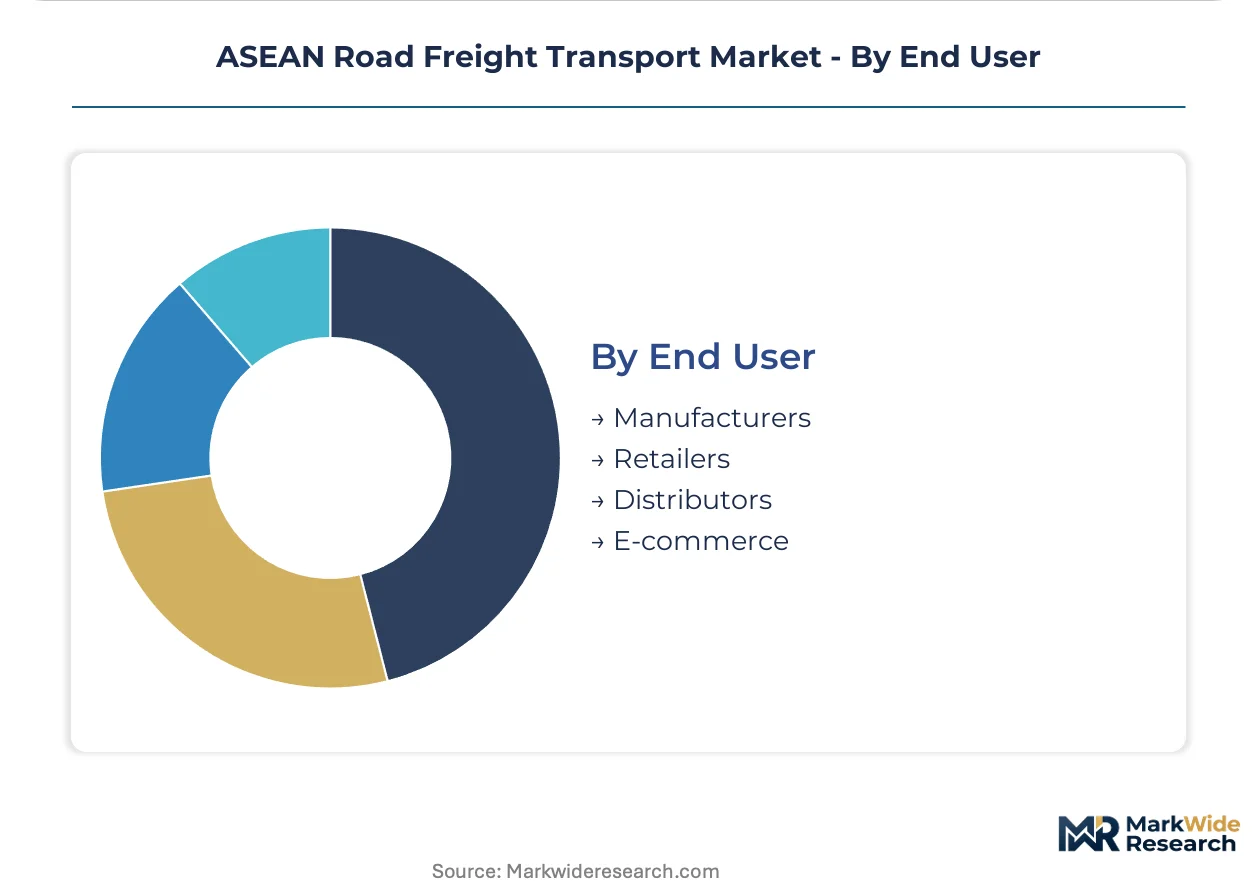
End User:
Procurement sophistication varies sharply between multinational manufacturers and emerging platform operators reshaping last-mile economics.
- Manufacturers:Automotive and electronics producers in Thailand and Vietnam mandate telematics integration and real-time visibility as contract conditions, squeezing operators without digital capabilities.
- Retailers:Modern trade chains in Malaysia and Thailand operate captive distribution networks with centralized warehousing and scheduled delivery windows.
- Distributors:Third-party logistics intermediaries aggregate fragmented shipper demand across Cambodia and Laos where direct carrier relationships remain underdeveloped.
- E-commerce:Platform fulfillment networks in Indonesia and Vietnam are expanding same-day coverage, creating sustained demand for flexible van and small truck capacity with dynamic routing.
E-commerce is reshaping competitive positioning through frequency and flexibility requirements. Manufacturers maintain rate discipline through volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Road freight transport across Southeast Asia emerged from colonial port-to-plantation networks and post-war highway construction programs. Thailand and Malaysia built the region's first modern trucking corridors during the 1960s and 1970s. Today's ASEAN logistics map reflects this infrastructure legacy overlaid with manufacturing zone densification.
Thailand
Automotive assembly plants in Rayong and Chonburi provinces generate concentrated just-in-time parts shuttle demand. The Department of Land Transport enforces Phase 2 emission standards for heavy-duty diesel vehicles, accelerating Euro 5 truck procurement. The Eastern Economic Corridor links Laem Chabang port to inland distribution centers through dedicated freight lanes.
Vietnam
Electronics manufacturers in Bac Ninh and Bac Giang provinces require high-frequency delivery scheduling for semiconductor components. The Ministry of Transport governs international road freight licensing under bilateral agreements with Cambodia and Laos. Ho Chi Minh City's Binh Duong industrial zone anchors southern manufacturing corridor flows.
Indonesia
E-commerce platforms in Jakarta and Surabaya are expanding same-day delivery networks into tier-two cities. The National Standardization Agency mandates BIS-equivalent certification for imported commercial vehicle components, extending procurement timelines. Java's north coast highway connects manufacturing clusters in Bekasi and Karawang to Tanjung Priok port.
Malaysia
Cross-border lanes serving Singapore face qualified driver shortages due to restricted foreign worker permits. The Road Transport Department enforces vehicle weight compliance through roadside inspection stations. The Johor Bahru–Port Klang corridor handles concentrated electronics and palm oil export volumes.
Philippines
Digital freight matching platforms are reducing empty backhaul kilometers among small fleet operators in Metro Manila. The Land Transportation Franchising and Regulatory Board governs commercial vehicle licensing and route authority. Cebu and Davao manufacturing zones generate inter-island container drayage demand.
ASEAN Road Freight Transport Market Competitive Environment
Capital-heavy asset owners compete with asset-light network orchestrators for margin capture across ASEAN corridors. Fleet operators with owned truck and trailer assets face high fuel exposure and depreciation costs, while fourth-party logistics providers rent capacity and optimize routing through software. Three archetypes dominate: integrated global networks with owned infrastructure, regional specialists anchoring specific country pairs, and port-centric operators controlling container drayage. Competitive dynamics center on M&A consolidation of mid-sized national carriers and strategic partnerships linking maritime, air, and road legs.
Among integrated network operators, DHL Group and DSV A/S occupy positions spanning customs brokerage, warehousing, and cross-border road transport. CJ Logistics Corporation exemplifies the regional specialist model with dedicated automotive logistics corridors. Gemadept represents port-centric concentration, anchoring container drayage flows through Vietnamese and Thai deepwater terminals.
| Leading Market Players |
|---|
| DHL Group |
| Konoike Group |
| SF Express (KEX-SF) |
| Tiong Nam Logistics Holdings Bhd |
| "K" Line Logistics, Ltd. |
| DSV A/S |
| CJ Logistics Corporation |
| Gemadept |
| Profreight Group |
| Others |
Value Chain & Pricing Dynamics
Captive fleet ownership across Thailand and Vietnam anchors both supply security and rate-setting power for integrated operators serving automotive and electronics corridors. This vertical integration insulates contract pricing from spot market volatility while concentrating procurement leverage with Euro 5-compliant truck manufacturers.
Pricing Analysis
Contract-based long-term offtake with guaranteed volume commitments dominates pricing structures between Vietnam's electronics manufacturers and dedicated fleet operators. Price differentiation rests on telematics integration depth and emission certification tier, with Phase 2-compliant assets commanding premiums. Cost compression in standard freight tiers is intensifying because diesel exposure remains unhedged in local currencies. E-commerce platform operators exhibit highest price sensitivity due to thin fulfillment margins, while automotive OEMs prioritize reliability over rate negotiation.
Supply Chain Analysis
Indonesia's National Standardization Agency mandates BIS-equivalent certification for imported commercial vehicle components, reshaping sourcing patterns toward domestic assembly partnerships. Component supply concentrates in Thailand, China, and Japan for powertrain systems, telematics hardware, and trailer fabrication. Raw material dependencies span high-strength steel, aluminum alloys, and semiconductor chips for engine management. Single-source vulnerability persists in advanced driver-assistance sensors. Distribution runs through port-centric operators controlling container drayage from Laem Chabang and Cai Mep to inland manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ASEAN road freight transport market functions as a stable compounder underpinned by manufacturing corridor densification across Vietnam and Thailand. E-commerce fulfillment expansion sustains incremental capacity absorption even through demand cyclicality.
For Market Incumbents: Deepen telematics integration partnerships with automotive OEMs to lock in contract renewals before digital freight platforms erode dedicated freight margins. Accelerate Euro 5 fleet turnover ahead of Thailand's Phase 2 enforcement deadlines. Secure captive maintenance facilities in Binh Duong and Bac Ninh provinces to reduce third-party service dependency.
For New Entrants and Emerging Players: Cloud-native freight matching algorithms offer entry leverage against legacy operators lacking real-time optimization capabilities. Target cold chain underpenetration in Indonesia's pharmaceutical distribution corridors where temperature-controlled road freight remains structurally underserved. Pursue white-label fulfillment partnerships with mid-tier e-commerce platforms seeking flexible van capacity without asset ownership.
For Investors and Strategic Acquirers: Roll-up economics work for mid-sized national carriers because regulatory fragmentation across ASEAN member states prevents organic geographic expansion without local licensing expertise. Five-to-ten-year viability hinges on consolidation of Philippines and Indonesia domestic operators with established route authorities. Monitor Vietnam's emissions tracking protocol pilots as inflection signal for carbon-compliant fleet premiums qualifying EU market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Euro 5 Fleet Procurement Acceleration | Thailand's Phase 2 standards penalize non-compliant assets on major corridors. |
| Telematics Platform Integration | Automotive OEMs mandate real-time visibility as contract condition in Rayong cluster. |
| Cold Chain Capacity Buildout | Indonesia's pharmaceutical distribution gaps create compliance arbitrage opportunity. |
| Digital Freight Matching Deployment | Philippines small fleet adoption reduces empty backhaul kilometers through load-board optimization. |
| Cross-Border Permit Harmonization | ASEAN Framework Agreement reduces customs dwell times on Thailand-Vietnam lanes. |
Study Parameters
Direct dialogue with fleet operations managers, logistics procurement leads at automotive OEMs, customs brokerage specialists, and port terminal operators grounded qualitative assessment in operational reality. Secondary validation drew from Thailand Department of Land Transport enforcement bulletins, Vietnam Ministry of Transport licensing records, Indonesia National Standardization Agency certification registries, and ASEAN Secretariat trade facilitation reports. Bottom-up carrier capacity surveys triangulated against top-down manufacturing output projections.
Market sizing outputs segmented across vehicle type, service configuration, industry vertical, and end-user procurement sophistication throughout the forecast period. Modeled dimensions included heavy-duty truck versus van deployment patterns, Full Truck Load contract structures versus Less Than Truck Load consolidation economics, and e-commerce fulfillment frequency against manufacturing just-in-time requirements. CAGRs derived from corridor-specific volume growth rates applied to baseline fleet utilization metrics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to emission standard enforcement timing and cross-border permit harmonization progress. Forecasts reflect documented assumptions regarding fuel price trajectory and manufacturing relocation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
Railcar Unloader Market
Transportation & Logistics
US Tolling Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Boxcar Scars Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
Europe Customs Brokerage Market
Transportation & Logistics
Saudi Arabia Road Freight Transport Market
Transportation & Logistics
United States Road Freight Transport Market