
 Global Motorcycles Brake Caliper Market | 2026-2036
Global Motorcycles Brake Caliper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Motorcycles Brake Caliper Market Outlook
The EU Green Deal's embedded decarbonization mandates for automotive component supply chains is pivoting procurement priorities across European motorcycle OEMs toward low-carbon aluminum and recycled material feedstocks. Brembo leverages its Italian manufacturing base and motorsport heritage to sustain premium positioning in radial caliper architectures. Nissin Kogyo anchors volume supply relationships with Japanese and Southeast Asian OEMs through integrated forging and machining operations. Akebono Brake Industry differentiates through advanced surface treatment processes that extend corrosion resistance in coastal and monsoon climates.
A motorcycle brake caliper is a hydraulically actuated clamping device housing one or more pistons that press brake pads against a rotor to generate friction-based deceleration, typically manufactured from aluminum alloys or cast iron with piston bore tolerances measured in hundredths of a millimeter. Floating calipers dominate entry and mid-tier motorcycle applications due to lower cost and simpler maintenance, while fixed and radial calipers command premium positioning in sport bikes where thermal management and consistent lever feel determine purchasing decisions. Carbon composite material adoption remains nascent but occupies the highest margin tier as weight reduction targets intensify for racing homologation and super sport platforms.
Europe's REACH chemical restrictions and F-Gas Regulation constrain traditional coating and cooling medium formulations, compelling reformulation of caliper finishes and piston seals. Japan's METI enforces JIS standards that govern fatigue testing protocols and salt spray duration requirements for brake system exports. India's BIS certification mandates thermal performance benchmarks that OEMs must clear before factory fitment approval. Stakeholders must monitor evolving material compliance timelines and pre-position localized testing capacity ahead of regulatory enforcement waves.
Market Dynamics
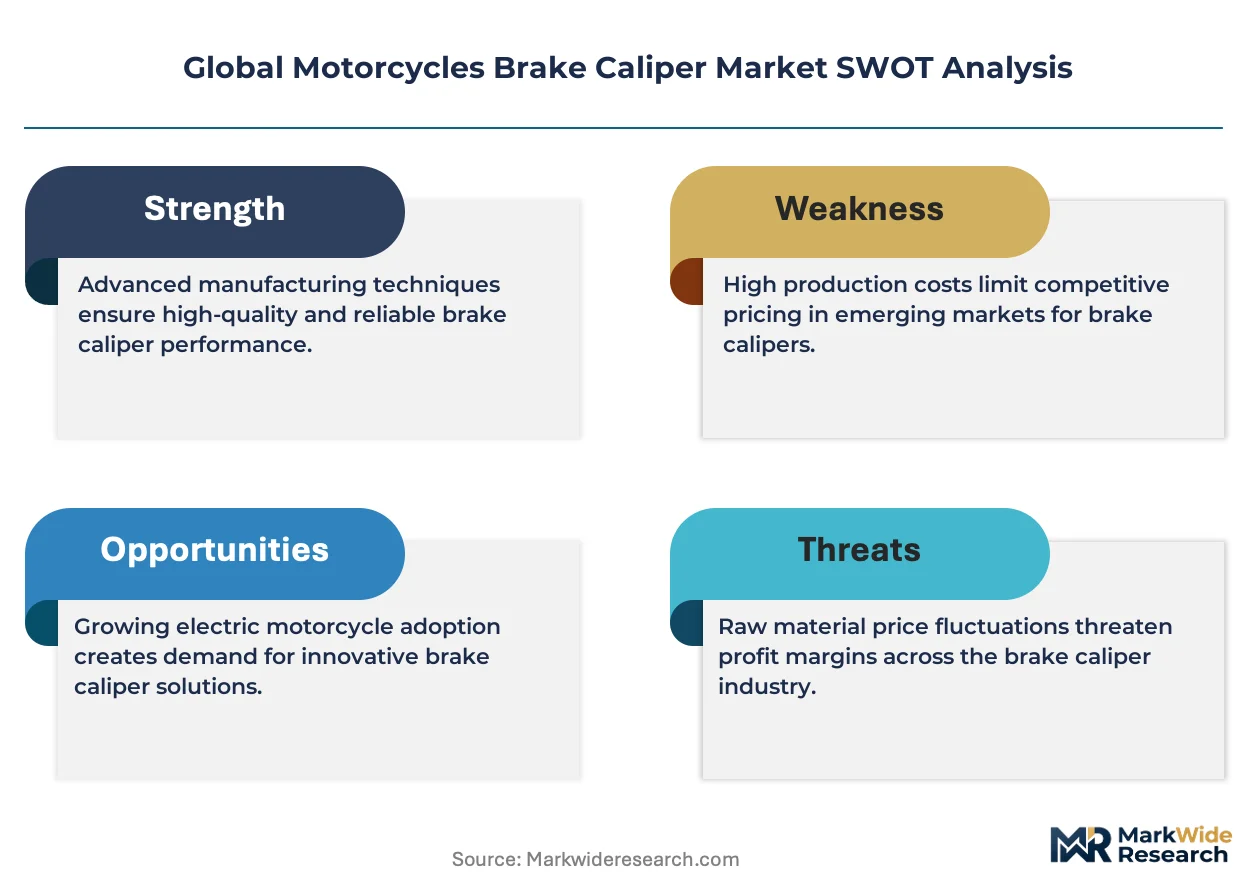
Europe's F-Gas Regulation and REACH compliance frameworks are forcing material substitution away from conventional cast iron architectures toward low-carbon aluminum and recycled feedstocks across motorcycle brake caliper supply chains.
Growth Catalysts
- EU Green Deal decarbonization mandates:Embedded carbon requirements for automotive component supply chains are pivoting procurement priorities across European motorcycle OEMs toward certified low-carbon aluminum sources.
- India and Vietnam production scaling:Domestic motorcycle manufacturing expansion in these countries is concentrating demand as local OEMs upgrade braking system specifications for export market access.
- Radial caliper thermal management:Performance-oriented sport bike manufacturers are expanding procurement of lightweight aluminum and carbon composite calipers to meet racing homologation weight reduction targets.
Market Restraints
- Aluminum alloy input cost volatility:Primary aluminum price swings and energy-intensive smelting economics compress margin buffers for forged caliper producers serving mid-tier motorcycle segments.
- Coating formulation constraints:REACH chemical restrictions on hexavalent chromium and specific solvent-based finishes force costly reformulation of caliper surface treatments and piston seal compounds.
- Carbon composite supply concentration:Prepreg carbon fiber sourcing remains concentrated among specialized Japanese and European suppliers, limiting volume scalability for cost-sensitive motorcycle platforms.
Strategic Opportunities
- India BIS certification localization:Thermal performance benchmark mandates for factory fitment approval create first-mover advantage for suppliers establishing localized testing capacity ahead of enforcement waves.
- Monsoon climate corrosion resistance:Advanced surface treatment processes addressing coastal and high-humidity operating conditions open premium positioning in Southeast Asian replacement markets.
- Recycled material feedstock integration:Closed-loop aluminum scrap recovery systems align with OEM sustainability reporting requirements under EU CSRD disclosure frameworks.
Industry Challenges
- Piston bore tolerance machining expertise:Hundredths-of-a-millimeter precision requirements for hydraulic sealing performance strain available CNC programming and metrology talent pools.
- Multi-regulation certification timeline compression:Simultaneous JIS fatigue testing, BIS thermal benchmarks, and REACH material declarations extend product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Motorcycles Brake Caliper Market |
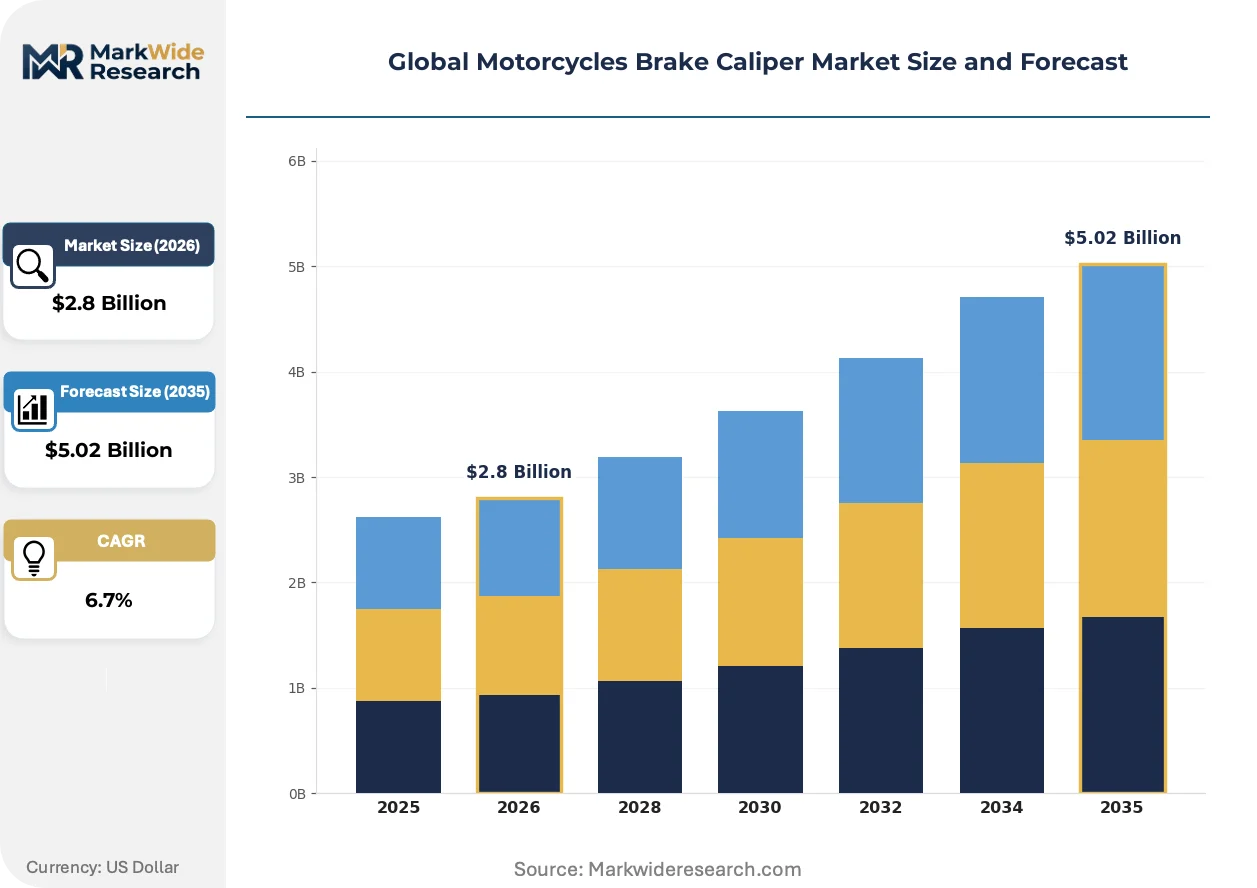
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floating Calipers, Fixed Calipers, Radial Calipers, Piston Calipers End User: OEMs, Aftermarket Providers, Distributors, Retailers Material: Aluminum, Cast Iron, Stainless Steel, Carbon Composite Application: Sport Bikes, Cruiser Bikes, Touring Bikes, Dirt Bikes |
| Companies Covered | Brembo, Nissin Kogyo, Akebono Brake Industry, Bosch, Continental, ZF Friedrichshafen, Aisin, Wilwood Engineering, Mando Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Motorcycles Brake Caliper Market Strategic Shifts
Lightweight material architectures and precision manufacturing techniques are actively reshaping competitive positioning across motorcycle brake caliper tiers, with regulatory pressure accelerating the displacement of legacy cast iron platforms.
Radial-mounted aluminum calipers are overtaking conventional axial floating designs in premium sport bike applications. These architectures deliver superior thermal management and consistent lever feel under track conditions. Japanese and Italian OEMs are now specifying radial mounting standards for their flagship super sport platforms, compressing the addressable market for entry-level floating caliper suppliers.
Europe's F-Gas Regulation constrains hydrofluorocarbon-based cooling medium formulations historically used in caliper thermal testing protocols. Brake system manufacturers must reformulate validation procedures and piston seal compounds to maintain performance certification. Southeast Asian export-oriented OEMs are pre-positioning alternative testing capacity to avoid supply disruption when enforcement timelines synchronize.
Direct procurement relationships between motorcycle OEMs and tier-one caliper specialists are displacing traditional brake system integrator intermediaries. Major manufacturers in India and Vietnam now negotiate forging and machining contracts directly with Japanese and Italian suppliers. This channel compression is most visible in high-volume standard motorcycle segments where specification standardization reduces engineering coordination overhead.
Global Motorcycles Brake Caliper Market Segmentation
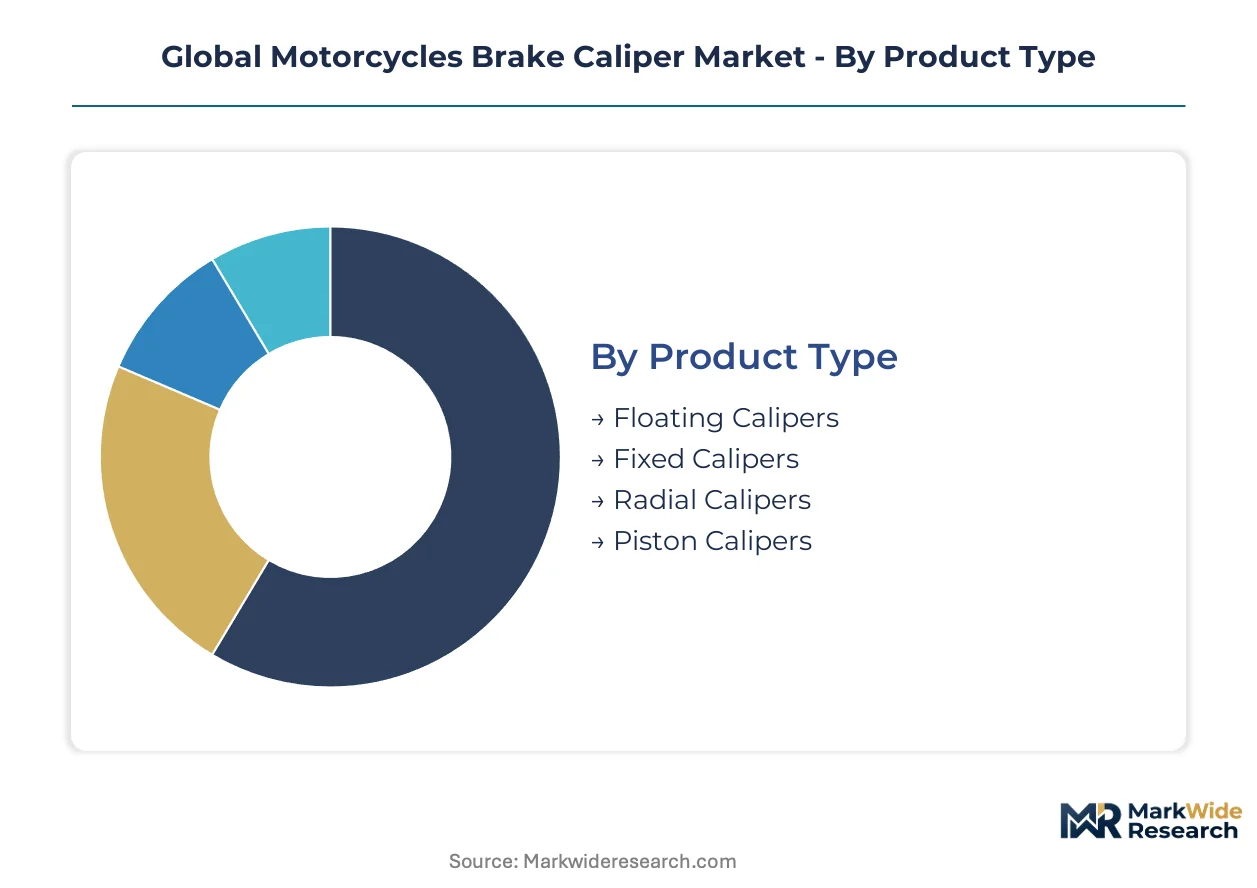
Motorcycle brake caliper segmentation reveals distinct procurement patterns across product architectures, material grades, and end-use applications. Understanding these divisions exposes where thermal performance requirements diverge from cost-sensitive volume manufacturing.
Product Type:
Floating calipers function as standalone bolt-on units for basic braking duty, while fixed and radial architectures embed deeper into fork and wheel carrier systems demanding precision integration.
- Floating Calipers:Single-sided piston housings slide on guide pins to self-center against rotors, utilizing simpler machining and fewer seals. Demand concentrates in India and Vietnam where domestic OEMs supply entry-level commuter motorcycles for price-sensitive urban markets constrained by procurement cost ceilings.
- Radial Calipers:Mounting bosses extend perpendicular to the brake disc plane, transferring braking torque directly through the fork leg rather than the axle. Sport bike manufacturers in Italy and Japan specify these architectures for super sport platforms where consistent lever feel under thermal load determines purchasing decisions and racing homologation compliance.
- Fixed Calipers:Rigid housings straddle the rotor with opposing pistons, eliminating pad knockback and improving modulation precision for touring applications.
- Piston Calipers:Multi-piston configurations distribute clamping force across larger pad surface areas, addressing heat dissipation requirements in heavy cruiser segments.
Volume placements concentrate in floating calipers; the faster expansion belongs to radial calipers.
End User:
Channel structure separates factory-fit procurement with embedded engineering collaboration from replacement market transactions governed by inventory velocity and specification matching.
- OEMs:Motorcycle manufacturers negotiate direct forging and machining contracts with tier-one caliper specialists, bypassing traditional brake system integrators as specification standardization reduces coordination overhead in high-volume standard segments.
- Aftermarket Providers:Independent distributors stock replacement calipers for crash repair and performance upgrades, with demand clustering in coastal Southeast Asian cities where monsoon corrosion accelerates component replacement cycles.
- Distributors:Regional warehousing operations aggregate SKUs across multiple OEM brands to serve multi-franchise repair networks.
- Retailers:Direct-to-consumer channels supply enthusiast-grade caliper upgrades for track day and custom build applications.
OEM direct procurement dominates unit volume; aftermarket providers capture the steepest margin expansion trajectory.
Material:
Material selection trades weight reduction against thermal mass, with regulatory frameworks now embedding carbon intensity requirements into sourcing decisions.
- Aluminum:Forged 6061-T6 and 7075 alloys deliver strength-to-weight ratios enabling unsprung mass reduction. European OEMs pivot toward certified low-carbon aluminum feedstocks as EU Green Deal embedded carbon mandates reshape procurement priorities across automotive component supply chains.
- Carbon Composite:Prepreg carbon fiber reinforced polymer housings achieve maximum weight reduction for racing homologation platforms. Japanese and European suppliers control concentrated sourcing, limiting volume scalability for cost-sensitive motorcycle production.
- Cast Iron:Traditional grey iron architectures persist in utility and agricultural motorcycle segments where thermal capacity outweighs mass considerations.
- Stainless Steel:Corrosion-resistant piston and hardware materials address coastal operating environments with extended salt spray durability.
Cast iron retains the largest installed base; carbon composite materials are climbing the fastest.
Application:
Vehicle duty cycles determine braking energy dissipation requirements, with track use, loaded touring, and off-road abrasion creating divergent caliper specifications.
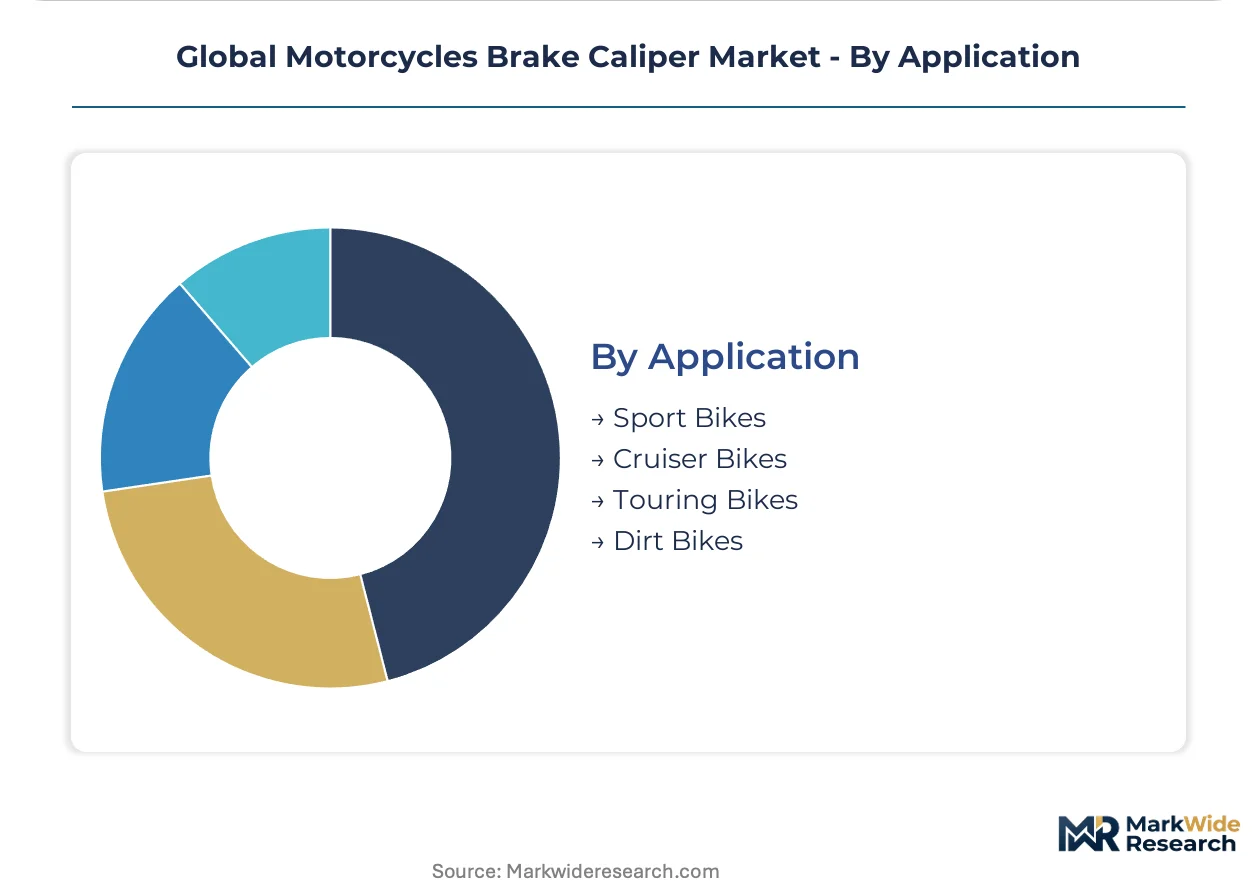
- Sport Bikes:High-performance platforms demand radial-mounted aluminum or carbon composite calipers with multi-piston configurations. Japanese and Italian OEMs now specify radial mounting standards for flagship super sport models, compressing addressable market opportunities for entry-level floating caliper suppliers.
- Dirt Bikes:Off-road applications prioritize mud clearance and impact resistance over thermal capacity, with simpler two-piston floating designs dominating.
- Cruiser Bikes:Heavy touring motorcycles require larger piston bores and thermal mass to manage sustained downhill braking loads.
- Touring Bikes:Long-distance comfort platforms balance weather sealing, ABS integration, and service accessibility in caliper specification.
Sport bikes anchor premium pricing tiers; dirt bikes generate the highest unit volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brembo's Italian manufacturing base in Bergamo anchors European radial caliper production, while Nagoya's integrated forging corridor supplies Japanese OEMs with precision-machined aluminum housings.
Italy
Radial caliper demand from Ducati and MV Agusta drives premium aluminum forging output in the Bergamo-Brescia industrial corridor. REACH compliance deadlines force coating reformulation across surface treatment facilities. Motorsport heritage sustains pricing power for track-homologated caliper architectures.
Japan
Tokyo-based OEMs specify JIS-standard fatigue testing for export-bound brake systems. METI enforcement of salt spray duration requirements shapes piston seal compound selection. Aichi Prefecture's Nagoya manufacturing cluster integrates forging and machining operations for Southeast Asian supply contracts.
India
Domestic motorcycle production scaling in Pune and Chennai concentrates demand for entry-level floating calipers. BIS thermal performance benchmarks mandate localized testing capacity ahead of factory fitment approvals. Gujarat's automotive component corridor attracts tier-one forging investments for export market access.
Vietnam
Hanoi and Ho Chi Minh City assembly plants upgrade braking specifications for European and North American export destinations. Monsoon climate corrosion accelerates replacement cycles in coastal replacement markets. Northern industrial zones develop machining expertise for mid-tier OEM procurement.
Germany
Bavarian engineering centers specify EU Green Deal embedded carbon thresholds for aluminum feedstock certification. KBA type-approval protocols govern brake system homologation for premium touring platforms. Stuttgart's automotive supplier ecosystem integrates recycled material traceability systems.
Global Motorcycles Brake Caliper Market Competitive Environment
The competitive structure tilts toward integrated forging specialists with motorsport credentials. Italian and Japanese manufacturers command premium positioning through radial caliper architectures, while Korean and German conglomerates leverage brake system integration capabilities. Two strategic archetypes dominate: heritage-backed precision forgers and diversified automotive suppliers. Capacity expansion in Southeast Asian machining corridors and direct OEM procurement relationships represent the primary competitive vectors reshaping channel structures.
Within the heritage-forging tier, Brembo exemplifies Italian motorsport-derived positioning, while Nissin Kogyo anchors volume supply relationships through integrated Japanese operations. Akebono Brake Industry occupies the surface treatment specialization segment. Bosch and Continental represent diversified German automotive supplier archetypes with brake system integration capabilities, while ZF Friedrichshafen and Aisin demonstrate conglomerate-scale diversification across chassis component portfolios.
| Leading Market Players |
|---|
| Brembo |
| Nissin Kogyo |
| Akebono Brake Industry |
| Bosch |
| Continental |
| ZF Friedrichshafen |
| Aisin |
| Wilwood Engineering |
| Mando Corporation |
| Others |
Value Chain & Pricing Dynamics
Japanese and Italian OEM direct procurement of radial calipers for super sport platforms anchors value-based pricing to racing homologation compliance and thermal performance outcomes rather than commodity aluminum input costs. This buyer concentration compresses margin buffers for forged caliper producers serving mid-tier segments while elevating premium capture for motorsport-certified suppliers.
Pricing Analysis
Racing homologation thermal performance and consistent lever feel under track conditions anchor value-based pricing for radial-mounted aluminum and carbon composite calipers. Three-tier pricing structure across premium, standard, and economy levels separates Brembo-specified super sport platforms from Nissin Kogyo volume contracts with Southeast Asian OEMs and entry-level floating caliper procurement in Indian commuter markets. Cost compression in mid-tier forged aluminum segments is intensifying because primary aluminum price volatility and energy-intensive smelting economics squeeze producers serving price-sensitive domestic manufacturers. Aftermarket providers in coastal Southeast Asian cities exhibit the highest price sensitivity due to monsoon-driven replacement cycle predictability, while Italian and Japanese OEMs demonstrate the lowest sensitivity given racing pedigree requirements.
Supply Chain Analysis
Remanufacturing flows for brake calipers remain underdeveloped relative to automotive brake systems, though closed-loop aluminum scrap recovery systems are emerging to satisfy EU CSRD disclosure requirements for recycled material feedstock integration. Manufacturing concentration centers on Italy's Bergamo-Brescia corridor for premium radial calipers, Japan's Nagoya-Aichi cluster for integrated forging and machining, and India's Gujarat-Pune automotive component zones for entry-level floating designs. The supply chain draws from primary aluminum smelters, specialized Japanese and European prepreg carbon fiber suppliers, and REACH-compliant coating formulation specialists. Single-source vulnerability in carbon composite prepreg sourcing limits volume scalability for cost-sensitive motorcycle platforms. Distribution runs through direct OEM procurement relationships that displace traditional brake system integrators in high-volume standard segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Motorcycles Brake Caliper Market functions as a cost-of-compliance story where Europe's REACH chemical restrictions and F-Gas Regulation create regulatory moats favoring established players with pre-positioned reformulation capabilities and localized testing infrastructure.
For Market Incumbents: Deepen backward integration into certified low-carbon aluminum feedstocks to defend margin position against primary aluminum price volatility while pre-positioning closed-loop scrap recovery systems ahead of EU CSRD enforcement timelines. Expand localized thermal testing capacity in India and Vietnam to capture first-mover advantage under BIS certification mandates before enforcement waves synchronize. Threat: Emerging Korean and German conglomerates leveraging brake system integration capabilities to compress channel structures. Lever: Motorsport heritage and radial caliper architecture expertise. For New Entrants and Emerging Players: The gap between Brembo-premium radial calipers and Indian economy floating designs offers white-space targeting for mid-tier sport bike OEMs in Vietnam and Indonesia seeking upgrade specifications for European export access. Penetrate the Southeast Asian replacement market through advanced surface treatment processes addressing monsoon corrosion resistance, where Akebono Brake Industry's specialization demonstrates premium positioning viability. Go-to-market angle: Direct forging and machining contracts with domestic OEMs bypassing traditional brake system integrators as specification standardization reduces coordination overhead. For Investors and Strategic Acquirers: The window for entry favors heritage-forging specialists with established JIS fatigue testing protocols and pre-certified REACH-compliant coating formulations. Long-term viability hinges on regulatory compliance capability accumulation rather than pure manufacturing scale. Acquisition target archetype: Italian or Japanese mid-tier caliper specialists with radial architecture expertise and existing Southeast Asian supply relationships. Signal to watch: Synchronization of BIS thermal benchmark enforcement timelines with EU F-Gas Regulation implementation waves as inflection indicator for consolidated supplier positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Localized BIS Certification Testing | First-mover positioning in India's factory fitment approval pipeline ahead of enforcement waves. |
| Low-Carbon Aluminum Feedstock Integration | EU Green Deal embedded carbon mandates reshape procurement priorities across European OEM supply chains. |
| Advanced Surface Treatment Process Development | Monsoon corrosion resistance opens premium replacement market positioning in coastal Southeast Asian cities. |
| Direct OEM Procurement Relationship Establishment | Channel compression in high-volume segments reduces brake system integrator intermediation overhead. |
| Carbon Composite Prepreg Supply Diversification | Reduces single-source vulnerability constraining volume scalability for cost-sensitive motorcycle platforms. |
Study Parameters
Multi-period observation of JIS fatigue testing protocol evolution, REACH chemical restriction implementation timelines, and BIS thermal benchmark enforcement preparations anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors in coastal Southeast Asian markets, and brake system R&D directors at Italian and Japanese manufacturers. Secondary validation drew from vehicle production databases, customs and trade flow records for aluminum alloy inputs, SEC filings of diversified automotive suppliers, and regulatory enforcement notices from METI and ECHA. Bottom-up segment sizing triangulated against top-down OEM procurement pattern analysis.
Segment-weighting across product architectures, material grades, end-use applications, and regional regulatory clusters drove the analytical framework throughout the projection horizon. Modeled dimensions included floating versus radial versus fixed caliper types, aluminum versus carbon composite versus cast iron material tiers, OEM versus aftermarket channel structures, and sport bike versus cruiser versus dirt bike duty cycles. CAGRs were derived from production scaling trajectories in India and Vietnam, thermal performance upgrade specifications for export market access, and racing homologation weight reduction targets. Industry-specific forecast inputs incorporated primary aluminum price volatility assumptions and REACH-compliant coating formulation transition timelines.
Inputs from OEM procurement managers and aftermarket distributors were available through the study window; gaps in real-time carbon composite prepreg supply chain visibility and emerging market localized testing capacity deployment schedules introduce uncertainty bands around volume scaling assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement synchronization and material substitution velocity. Practitioners should monitor BIS certification mandate implementation announcements and EU F-Gas Regulation cooling medium reformulation deadlines for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Aluminum Alloy Bicycle Crankset Market
Bikes and Motorcycles
Europe Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle ADAS Market
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Motorcycle Rider Assistance System Market
Bikes and Motorcycles
Motorcycle Suspension System Market
Bikes and Motorcycles
Two Wheeler Seats Market
Bikes and Motorcycles
Global Bicycle Derailleur Market
Bikes and Motorcycles
Europe E Bike Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
United States E-Bike Market