
 Motorcycle Lighting Market | 2026-2036
Motorcycle Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Lighting Market Intelligence
Aftermarket providers are redrawing demand patterns as riders replace stock lighting with higher-performance LED and adaptive systems. Koito Manufacturing leverages its vertical integration in Japan to sustain premium positioning across OEM channels. Hella GmbH & Co. KGaA competes through specialized adaptive lighting modules for touring and street bike segments. Varroc Engineering Ltd anchors its growth in India through cost-optimized LED assemblies for domestic and export motorcycle programs.
Motorcycle lighting encompasses headlamps, tail lamps, turn indicators, and auxiliary illumination systems engineered to deliver specified lumen output, beam pattern compliance, and vibration resistance under continuous road stress. These assemblies serve the dual purpose of rider visibility and regulatory conformance across diverse operating environments. LED product type leads installed value due to efficiency mandates and thermal management advances, while halogen retains volume in emerging-market commuter segments. Adaptive lighting technology commands the fastest expansion as smart sensors enable dynamic beam shaping for cornering and oncoming traffic detection. OEM end user channels carry higher margin pools tied to platform-specific design integration, though aftermarket providers capture growing retrofit demand from custom builders and performance enthusiasts.
Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces stringent photometric standards that shape headlamp design requirements for domestic and export-bound motorcycles. India's Automotive Research Association and Central Motor Vehicle Rules mandate daytime running lamps and position lights that accelerate LED adoption across displacement classes. Stakeholders must monitor divergence between regional certification regimes and decide whether to pursue modular platform architectures or market-specific product lines.
Market Dynamics
LED thermal management breakthroughs and adaptive beam mandates from Japan's Ministry of Land, Infrastructure, Transport and Tourism are compressing product development cycles while fragmenting certification requirements across export markets.
Growth Catalysts
- Adaptive Beam Regulations:Japan's Ministry of Land, Infrastructure, Transport and Tourism and India's Central Motor Vehicle Rules mandate dynamic headlamp systems for new motorcycle platforms, forcing technology upgrades across OEM supply chains.
- LED Efficiency Mandates:India's Automotive Research Association daytime running lamp requirements accelerate solid-state lighting adoption across 125cc to 500cc displacement categories where halogen previously dominated.
- Aftermarket Retrofit Demand:Performance enthusiasts and custom builders in Germany, Italy, and Thailand replace stock assemblies with higher-lumen LED modules, creating parallel demand streams independent of OEM production schedules.
Market Restraints
- Aluminum Heat Sink Cost Volatility:Raw material price swings for thermal management substrates compress margins on mid-tier LED assemblies where cost optimization already runs thin.
- Optics Supply Concentration:Precision lens molding capacity clusters among Japanese and German tier-two suppliers, creating single-source vulnerability for beam-pattern-critical components.
- Halogen Substitution Ceiling:Price-sensitive commuter segments in Indonesia and Vietnam retain tungsten-halogen architectures where total cost of ownership calculations favor incumbent technology.
Strategic Opportunities
- Software-Defined Beam Shaping:Convergence of camera-based traffic detection and micro-LED matrix arrays enables real-time glare-free high beams without mechanical actuators.
- Latin American Export Expansion:Brazil's ANVISA and Mexico's NOM certification pathways remain underpenetrated by adaptive lighting specialists, offering first-mover positioning before local content rules tighten.
- Direct-to-Rider Digital Channels:Specialized e-commerce platforms bypass traditional distributor markups for aftermarket LED retrofits, capturing margin pools previously absorbed by regional parts wholesalers.
Industry Challenges
- Photometric Calibration Talent Scarcity:Shortage of engineers capable of integrating sensor fusion with beam pattern optimization delays product launches by 8-14 months.
- Multi-Regulatory Certification Parallelism:Simultaneous homologation against Japan's JIS, India's CMVR, and EU UNECE requirements fragments engineering resources and extends validation timelines.
- Legacy Wiring Harness Integration:Retrofit LED modules must interface with analog voltage systems designed for incandescent loads, requiring active load simulation circuits that add cost and failure modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Lighting Market |
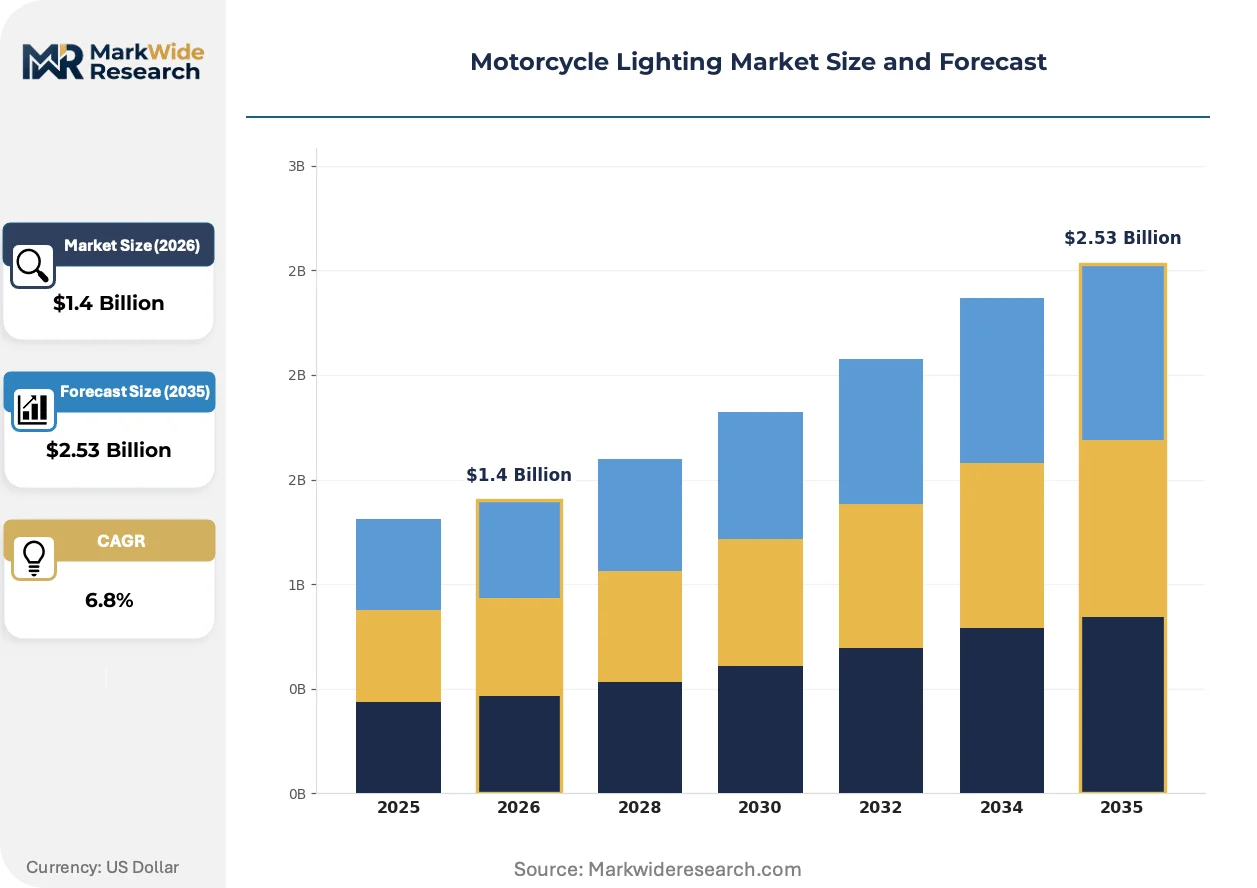
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Incandescent Technology: Adaptive Lighting, Smart Lighting, Laser Lighting, Traditional Lighting End User: OEMs, Aftermarket Providers, Custom Builders, Retailers Application: Street Bikes, Off-road Bikes, Touring Bikes, Cruisers |
| Companies Covered | Koito Manufacturing Co., Ltd., Lumax Industries Limited, Hella GmbH & Co. KGaA, J.W. Speaker Corporation, Varroc Engineering Ltd, Stanley Electric Co., Ltd., Fiem Industries Ltd., Minda Industries Ltd., Osram GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Lighting Market Strategic Shifts & Innovations
Digital beam control architectures are replacing mechanical shutter systems, while regulatory divergence between Asian and European testing protocols forces modular platform strategies over unified global designs.
Micro-LED matrix arrays with individually addressable emitters enable pixel-level beam sculpting without moving parts. Premium touring and adventure bike manufacturers in Germany and Japan adopt these systems for model-year 2026-2027 platforms. Solid-state adaptive lighting is supplanting servo-driven projector mechanisms, eliminating mechanical wear points while enabling faster response to oncoming traffic detection.
India's Central Motor Vehicle Rules amendment mandating automatic headlamp leveling for motorcycles above 125cc takes effect across domestic and export production. This forces integrated sensor-actuator architectures into mass-market cost structures previously reserved for premium displacement categories. Domestic manufacturers and tier-one suppliers accelerate in-house leveling algorithm development to avoid royalty payments to European control module specialists.
Aftermarket procurement is fragmenting as rider communities form buying collectives through specialized forums and social platforms. These groups negotiate volume discounts directly with LED module manufacturers, bypassing traditional parts distributors in Thailand, Malaysia, and Spain. Channel disintermediation concentrates in 400cc-800cc segments where enthusiast density supports minimum order quantities for factory-direct fulfillment.
Motorcycle Lighting Market Segmentation
Segmentation in motorcycle lighting reveals how technology tiers and channel structures create distinct margin pools. Product type and technology choices determine thermal management complexity, while end-user channels dictate certification burdens and pricing power.
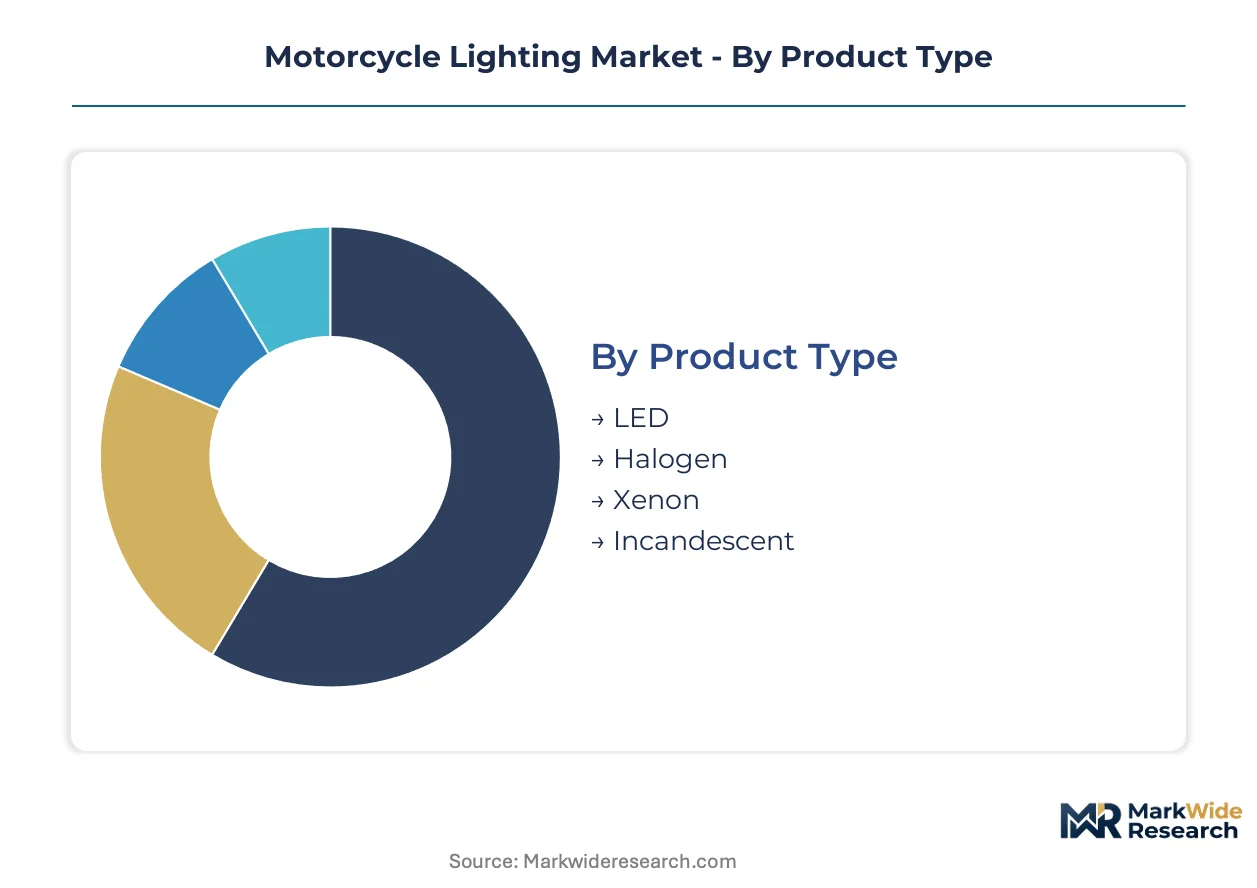
Product Type:
OEM channels favor LED and halogen for platform integration, while aftermarket flows concentrate on LED retrofits and xenon upgrades where wiring compatibility allows.
- LED:Solid-state emitters with aluminum or copper-core PCBs manage junction temperatures above 85°C through active or passive thermal dissipation. India's Central Motor Vehicle Rules mandate daytime running lamps across 125cc-500cc segments where LED now dominates factory fitment.
- Halogen:Tungsten-halogen capsules operate at 3200K color temperature with H4 or HS1 base configurations for direct replacement compatibility. Indonesia and Vietnam commuter segments retain this architecture where total cost of ownership calculations resist LED conversion despite efficiency gaps.
- Xenon:High-intensity discharge systems with ballast-driven arc tubes deliver 3000+ lumen output for premium touring applications.
- Incandescent:Legacy bulb technology persists in ultra-low-cost 100cc segments and replacement markets with minimal electrical system capacity.
By volume, halogen leads in emerging-market factory installations. By growth pace, LED is climbing the fastest as efficiency mandates tighten across Asian manufacturing hubs.
Technology:
Cost tier stratification separates premium adaptive systems from commodity traditional lighting, with smart and laser technologies occupying narrow super-premium niches.
- Adaptive Lighting:Camera-fed sensor arrays dynamically adjust beam patterns for cornering angles and oncoming traffic detection without mechanical actuators. Japan's Ministry of Land, Infrastructure, Transport and Tourism mandates this capability for new motorcycle platforms above 125cc, forcing tier-one suppliers to integrate leveling algorithms in-house.
- Smart Lighting:Connected modules with CAN-bus integration enable diagnostic feedback and over-the-air calibration updates for premium OEM programs.
- Laser Lighting:Phosphor-converted blue laser diodes extend throw distance beyond 600 meters for adventure touring segments.
- Traditional Lighting:Fixed-pattern projector or reflector systems without sensor feedback dominate price-sensitive displacement categories.
Traditional systems retain volume leadership across sub-250cc factory production. Adaptive configurations are expanding most quickly as regulatory deadlines approach in Japan and India.
End User:
Application focus varies sharply: OEMs prioritize platform-specific thermal modeling, while custom builders emphasize lumen density and aesthetic customization over certification compliance.
- OEMs:Motorcycle manufacturers specify lighting modules during platform development with dedicated wiring harness integration and vibration testing protocols.
- Aftermarket Providers:Independent distributors and e-commerce platforms serve retrofit demand from enthusiasts seeking brightness upgrades beyond factory specifications.
- Custom Builders:Specialized fabrication shops in Germany, Italy, and Thailand commission bespoke LED arrays for one-off or limited-production motorcycles.
- Retailers:Brick-and-mortar and online parts sellers stock replacement bulbs and universal-fit LED modules for owner-installed maintenance.
OEM channels command higher per-unit margins through design integration lock-in. Aftermarket providers are gaining share fastest as direct-to-rider digital platforms bypass traditional distribution markups.
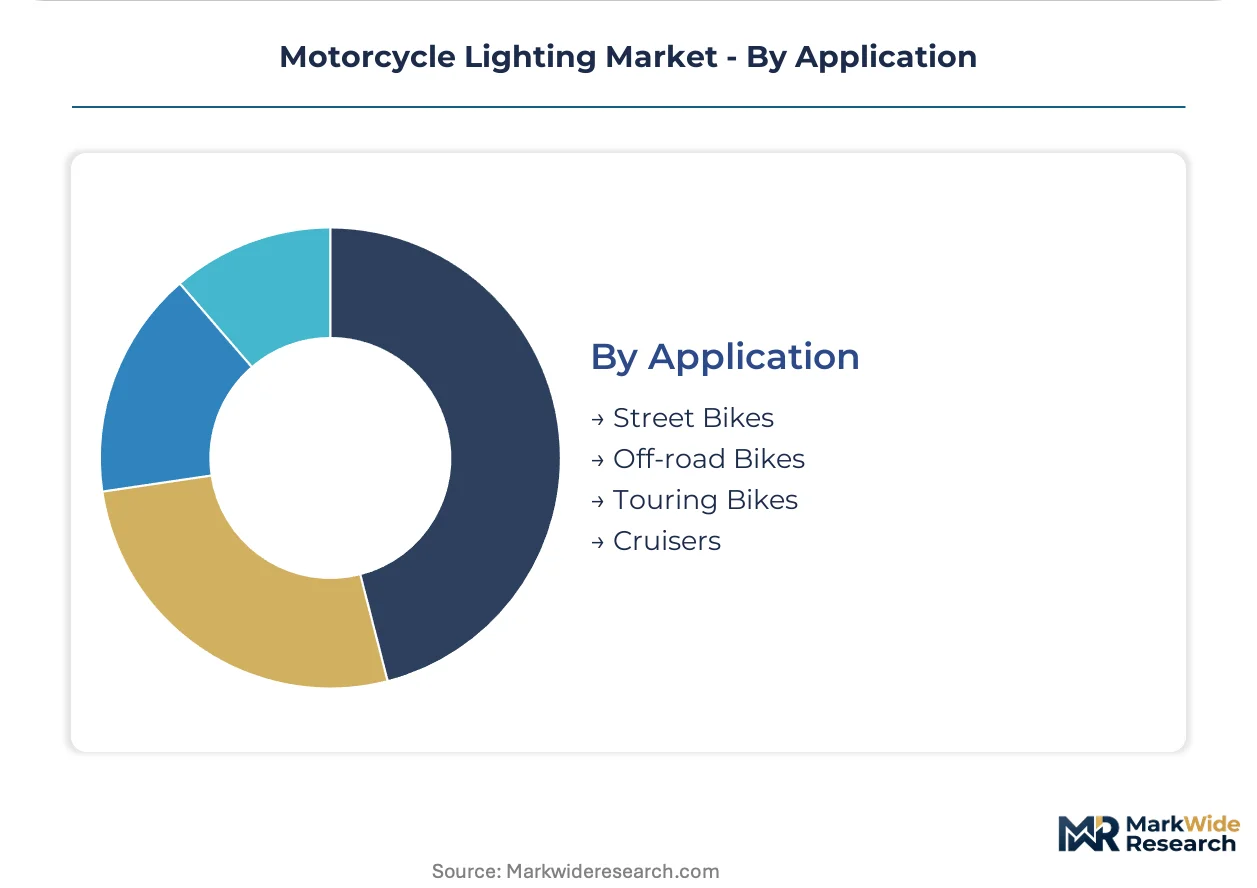
Application:
Volume concentration sits with street bikes, while margin pools concentrate in touring and adventure segments where adaptive technology penetration runs deepest.
- Street Bikes:Urban and suburban motorcycles from 125cc to 1000cc displacement represent the highest-volume installation base for both OEM and replacement lighting.
- Off-road Bikes:Enduro and motocross machines prioritize impact resistance and minimal weight over beam sophistication, favoring compact LED pods over complex adaptive systems.
- Touring Bikes:Long-distance motorcycles above 800cc integrate full adaptive headlamp arrays with cornering lights and automatic leveling as standard equipment.
- Cruisers:Stylistically driven segments emphasize aesthetic housing designs with heritage-inspired beam patterns and chrome or blacked-out finishes.
Street bikes dominate unit volume across all lighting technologies. Touring applications show the steepest technology upgrade trajectory as adaptive mandates expand into premium displacement categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Asian manufacturing hubs where tier-one suppliers cluster around motorcycle OEM production corridors. India, China, and Japan together absorb the majority of LED module output as domestic safety mandates accelerate technology replacement cycles. Regulatory divergence across these markets forces modular platform strategies rather than unified global designs.
India
Domestic motorcycle production exceeding 20 million units annually generates massive pull for cost-optimized LED assemblies. The Central Motor Vehicle Rules mandate automatic headlamp leveling for displacements above 125cc, compressing adoption timelines for adaptive technology into mass-market segments. Pune and Chennai host concentrated supplier parks where Varroc Engineering and Lumax Industries anchor tier-one production clusters serving Hero MotoCorp and Bajaj Auto programs.
Japan
Premium displacement motorcycle exports to North America and Europe drive demand for sophisticated beam-shaping systems. The Ministry of Land, Infrastructure, Transport and Tourism enforces stringent JIS photometric standards that shape headlamp architectures for global platform derivatives. Kansai region suppliers including Koito Manufacturing and Stanley Electric maintain captive thermal management and optics capabilities for integrated OEM supply.
China
Domestic motorcycle electrification and export manufacturing create dual demand streams for LED and adaptive lighting modules. MIIT efficiency standards and GB certification protocols accelerate solid-state lighting adoption across 150cc-400cc commuter platforms. Chongqing and Zhejiang province production corridors concentrate assembly capacity for both indigenous brands and export-bound OEM programs serving Southeast Asian markets.
Germany
Specialized touring and adventure motorcycle segments command premium positioning for adaptive lighting technology. KBA homologation requirements and UNECE beam pattern regulations shape product development for European and export-bound platforms. Bavaria-based Hella GmbH & Co. KGaA anchors development of camera-fed adaptive modules, while southern Baden-Württemberg hosts precision optics suppliers serving premium OEM integration programs.
United States
Aftermarket retrofit demand from custom builders and touring enthusiasts creates parallel revenue streams independent of OEM production schedules. NHTSA Federal Motor Vehicle Safety Standard 108 governs headlamp photometric performance, while state-level inspection regimes vary in enforcement stringency. Wisconsin and Ohio manufacturing corridors concentrate J.W. Speaker Corporation and specialty fabricators serving Harley-Davidson aftermarket channels and independent custom shops.
Motorcycle Lighting Market Key Industry Players
Concentration sits with vertically integrated Japanese and German tier-one suppliers controlling premium OEM channels, while Indian mid-tier specialists capture volume through cost-optimized LED platforms. The market structure tiers across three archetypes: integrated optics-thermal specialists, scale-driven assembly houses, and aftermarket-focused retrofit providers. Dominant competitive moves include backward integration into aluminum heat sink production and strategic partnerships with semiconductor foundries for micro-LED matrix sourcing.
Among Japanese integrated specialists, Koito Manufacturing Co., Ltd. and Stanley Electric Co., Ltd. exemplify the premium OEM archetype through captive supply chain control. Indian scale-driven assemblers Lumax Industries Limited and Varroc Engineering Ltd occupy positions serving high-volume domestic and export motorcycle programs. Hella GmbH & Co. KGaA represents the European adaptive technology specialist tier, while J.W. Speaker Corporation anchors North American aftermarket retrofit positioning.
| Leading Market Players |
|---|
| Koito Manufacturing Co., Ltd. |
| Lumax Industries Limited |
| Hella GmbH & Co. KGaA |
| J.W. Speaker Corporation |
| Varroc Engineering Ltd |
| Stanley Electric Co., Ltd. |
| Fiem Industries Ltd. |
| Minda Industries Ltd. |
| Osram GmbH |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts between tier-one LED module suppliers and Japanese OEMs lock in aluminum heat sink supply and insulate pricing from spot-market volatility in thermal management substrates. These arrangements anchor cost visibility for adaptive lighting platforms while fragmenting procurement leverage for mid-tier assemblers serving Indian commuter segments.
Pricing Analysis
Volume-discount tiering structures stratify pricing across premium adaptive systems, standard LED assemblies, and economy halogen replacements. Premium tiers command markups tied to JIS and UNECE certification grades and captive optics integration, while standard tiers face compression from Indian cost-optimized competitors. Pricing pressure intensifies in mid-tier LED segments where aluminum heat sink costs fluctuate and thermal management IP concentrates among Japanese suppliers. OEM channels exhibit lowest price sensitivity due to platform integration lock-in; aftermarket retrofit buyers show highest elasticity, driving direct-to-rider digital procurement.
Supply Chain Analysis
Inbound logistics costs from Yokohama and Shanghai ports to European assembly plants have tightened container availability for precision lens molding shipments originating from Japanese and German tier-two suppliers. Manufacturing gravity centers on Japan, India, and China, with Kansai region suppliers maintaining captive thermal management capabilities and Pune-Chennai corridors optimizing cost-driven LED assemblies. Supply chains draw from aluminum heat sinks, micro-LED matrix arrays, and phosphor-converted laser diodes as critical inputs. Single-source vulnerability clusters around precision optics molding capacity. Distribution runs through OEM direct supply, tier-one distributor networks, and emerging direct-to-rider e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as software-defined beam architectures decouple hardware margins from recurring calibration and over-the-air update revenues. Interoperability between camera-fed sensor arrays and micro-LED matrix controllers is consolidating control module standards around Japanese and German IP ecosystems.
For Market Incumbents: Fortify captive supply of aluminum heat sink substrates through backward integration or long-term offtake agreements with Japanese smelters to defend margin position against mid-tier Indian cost competition. Deepen in-house leveling algorithm development to eliminate royalty payments to European control module specialists and accelerate JIS-CMVR dual certification timelines.
For New Entrants and Emerging Players: CMVR fast-track certification for automatic headlamp leveling modules presents the most penetrable entry vector into India's 125cc-500cc mass-market segments where domestic algorithm development lags. Target Brazil's ANVISA and Mexico's NOM certification pathways before local content rules tighten, leveraging direct-to-rider digital channels to bypass entrenched distributor markups in Latin American aftermarket flows.
For Investors and Strategic Acquirers: Adaptive lighting software specialists with proven camera-sensor fusion IP represent the highest-conviction acquisition archetype for portfolio exposure to regulatory mandate-driven technology substitution. Monitor divergence between Japan's JIS photometric standards and India's CMVR enforcement timelines as the critical inflection signal for platform standardization versus market-specific product line strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Heat Sink Production | Captive thermal management supply insulates margins from commodity volatility and secures JIS certification timelines. |
| In-House Leveling Algorithm Development | Eliminates royalty outflows to European control module specialists and accelerates CMVR compliance for Indian OEM programs. |
| Direct-to-Rider E-Commerce Platform Launch | Bypasses traditional distributor markups in Thailand and Malaysia, capturing margin pools from enthusiast retrofit demand. |
| Dual JIS-CMVR Certification Investment | Enables unified platform architectures across Japanese premium exports and Indian mass-market production corridors. |
| Micro-LED Matrix Array Partnership | Secures semiconductor foundry allocation for pixel-level beam sculpting in model-year 2026-2027 touring platforms. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade customs data, OEM platform engineering disclosures, and regulatory filing databases. Primary interviews engaged tier-one supplier procurement directors, OEM platform lighting engineers, aftermarket distributor operations heads, and Central Motor Vehicle Rules technical committee members. Secondary validation drew from Japan's Ministry of Land, Infrastructure, Transport and Tourism photometric standard publications, India's Automotive Research Association technical bulletins, and UNECE beam pattern regulation updates. Bottom-up assembly cost modeling and top-down OEM program value aggregation provided triangulation checks.
Segmentation dimensions modeled span product type, technology tier, end-user channel, application displacement class, and regional regulatory cluster across the projection horizon. CAGRs derive from installed base replacement cycles, regulatory mandate effective dates, and technology substitution elasticity parameters. Forecast inputs incorporate LED thermal management cost curves, adaptive sensor fusion adoption rates, and aftermarket digital channel penetration trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained aluminum price volatility and stable JIS-CMVR regulatory divergence; material deviation in either factor would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
LAMEA Motorcycle ADAS Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Mountain Bike Suspension Market
Bikes and Motorcycles
Motorcycle Boot Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
Trike Market
Bikes and Motorcycles
Motorcycle ADAS Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Bicycle Mechanical Disc Brake Market
Bikes and Motorcycles
Electric Cargo Bikes Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Adventure Motorcycle Market