
 Latin America Fuel Cell Bikes Market | 2026-2036
Latin America Fuel Cell Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Fuel Cell Bikes Market Insights
Single-source hydrogen fuel cell procurement is rebalancing toward multi-source supplier networks as Latin American assemblers diversify membrane electrode assembly inputs. Pragma Industries leverages its European fuel cell stack expertise to anchor premium bike production for commercial fleet buyers. EMOV sustains localized system integration capabilities in Mexico, while Azure Bikes competes on cost-optimized hybrid architectures for urban delivery operators.
Fuel cell bikes integrate proton exchange membrane or direct methanol systems with compact hydrogen storage to deliver extended-range zero-emission personal and commercial mobility. These vehicles typically achieve 100-150 kilometers per fill, with refueling completed in under three minutes, positioning them between battery-electric range limits and internal combustion convenience. Electric models dominate current volume given simpler integration requirements, while delivery services represent the fastest-expanding end-user segment as logistics operators seek fleet uptime advantages. Proton exchange membrane technology occupies the primary margin pool due to superior power density and cold-start performance across varied Andean and tropical climates.
Brazil's ANP regulates hydrogen fuel quality and dispensing infrastructure standards, while Mexico's CRE oversees energy transition incentives affecting fleet conversion economics. EMOV and local assemblers navigate permitting timelines for hydrogen retail points in São Paulo, Mexico City, and Santiago. Stakeholders must monitor regulatory harmonization progress between national energy agencies and municipal transit authorities to anticipate infrastructure rollout sequencing and fleet procurement windows.
Market Dynamics
Urban logistics operators across São Paulo and Mexico City are compressing refueling windows to under three minutes, forcing hydrogen infrastructure deployment ahead of consumer demand curves. This operational pressure is restructuring supplier relationships and municipal permitting sequences across Brazilian and Mexican metropolitan corridors.
Growth Catalysts
- Brazil's Inova Energia program:Direct capital allocation for hydrogen mobility pilots accelerates fleet conversion economics for commercial delivery operators in São Paulo and Rio de Janeiro.
- Last-mile logistics electrification mandates:Metropolitan transit authorities in Mexico City and Santiago impose zero-emission zones that exclude battery-electric vehicles with multi-hour charging downtime.
- PEM fuel cell power density gains:Recent membrane electrode assembly improvements enable 40% smaller stack packaging without range sacrifice, opening frame designs previously reserved for electric bicycles.
Market Restraints
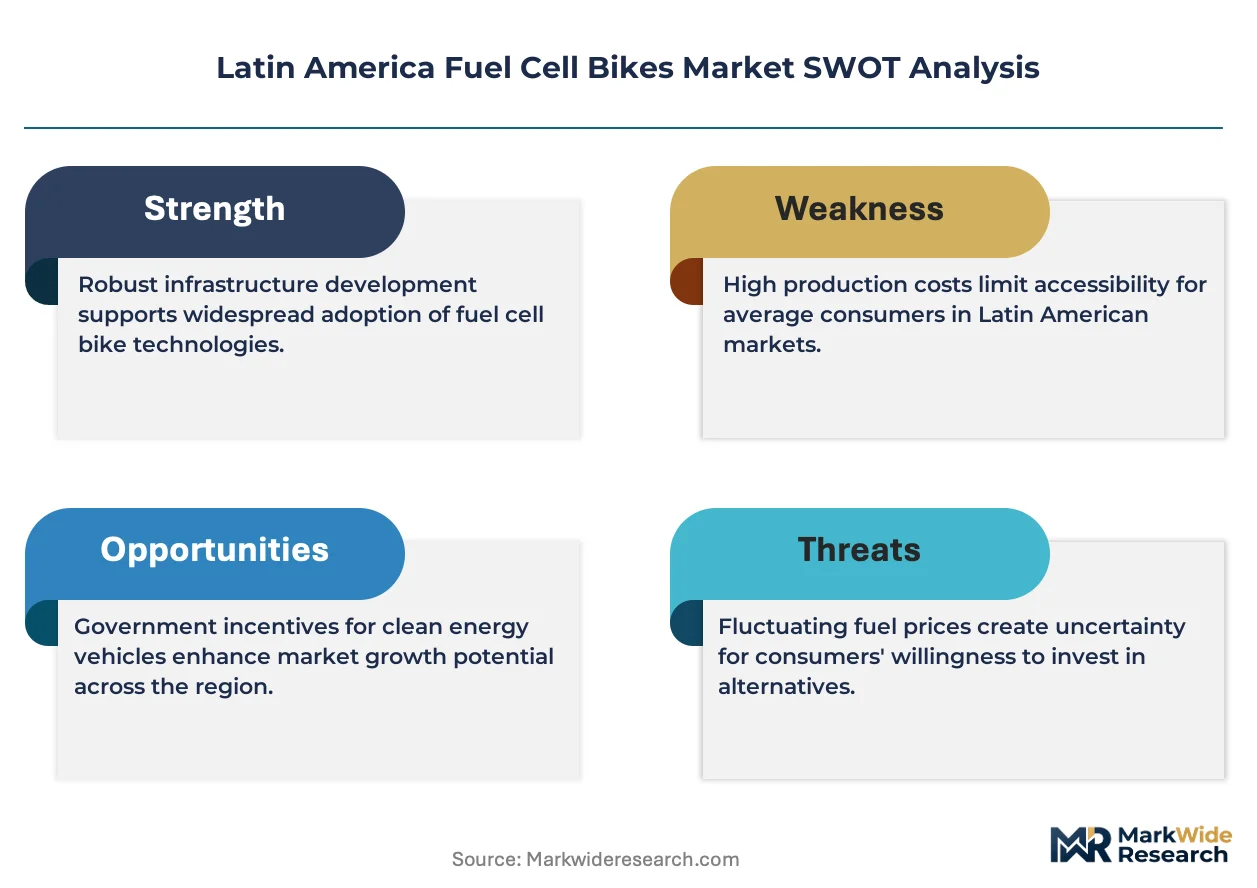
- Platinum group metal cost volatility:PEM catalyst loadings remain exposed to palladium and platinum spot price swings that inflate stack replacement economics for fleet operators.
- Single-source hydrogen supply concentration:Industrial gas majors control 90% of regional electrolyzer output, limiting price negotiation leverage for independent bike assemblers.
- Cryogenic storage technical limitations:Ambient temperature hydrogen compression systems sacrifice volumetric density against liquid alternatives, constraining range extension for Andean altitude deployments.
Strategic Opportunities
- Colombian urban corridor underpenetration:Bogotá and Medellín lack hydrogen retail infrastructure but possess dense informal delivery networks receptive to lease-to-own fuel cell bike models.
- Direct methanol fuel cell convergence with IoT telemetry:Remote fleet monitoring integration enables predictive maintenance contracts that capture recurring revenue streams beyond hardware margins.
- Mexico CRE energy transition incentives:Accelerated depreciation schedules for hydrogen fleet assets improve three-year total cost of ownership calculations against conventional electric alternatives.
Industry Challenges
- Hydrogen safety certification timelines:ANP pressure vessel standards and municipal fire codes require sequential approvals that extend product launch windows by 8-14 months.
- Membrane electrode assembly skill scarcity:Regional technical institutes lack specialized training programs for fuel cell stack assembly, forcing assemblers to import Brazilian or Mexican technicians at premium cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Fuel Cell Bikes Market |
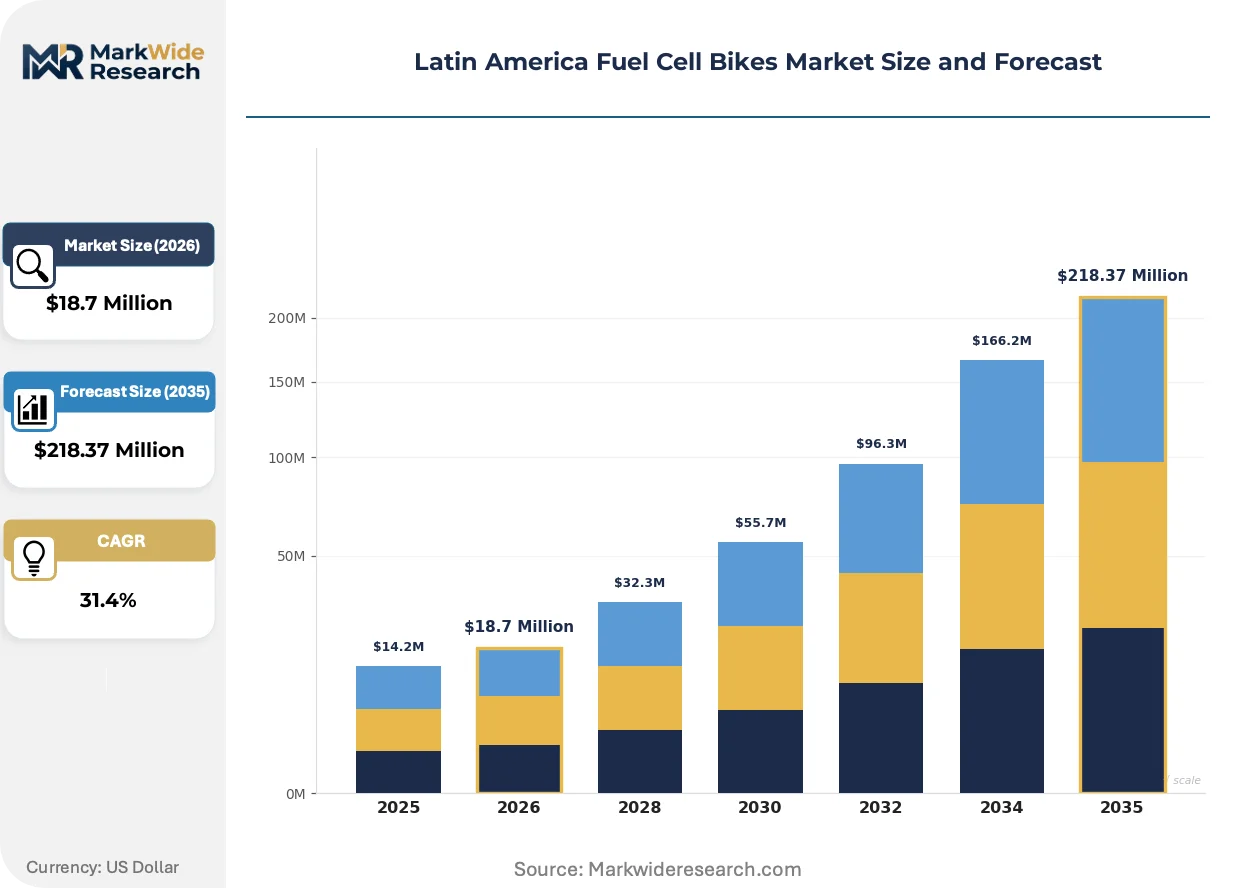
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $218.37 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Models, Hybrid Models, Cargo Types, Racing Bikes End User: Individuals, Delivery Services, Commercial Fleets, Tour Operators Technology: Proton Exchange Membrane, Direct Methanol, Alkaline Fuel Cells, Solid Oxide Distribution Channel: Online Retail, Specialty Stores, Dealerships, Direct Sales |
| Companies Covered | Giant Bicycles Co. Ltd, Trek Bicycle Corporation, EDG, EMOV (Energía en Movimiento), Pedego Electric Bikes, Honda Motor Co. Ltd, Azure Bikes, Mob-ion, Pragma Industries, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Fuel Cell Bikes Market Trends and Innovations
Telematics integration is compressing fleet management cycles across Latin American logistics networks. Three developments are restructuring how fuel cell bikes are deployed, maintained, and monetized in commercial settings.
Automated hydrogen pressure monitoring is automating refueling authorization and leak detection protocols across São Paulo fleet depots. Logistics operators including Mercado Libre fulfillment partners deploy these systems to eliminate manual safety inspections. The technology is automating compliance documentation that previously required dedicated HSE personnel, reducing per-vehicle operational overhead.
Brazil's ANP issued updated hydrogen fuel quality specifications in late 2024 that mandate 99.97% purity thresholds for mobility applications. The regulation forces existing electrolyzer operators to upgrade purification stages, raising wholesale hydrogen costs for early bike fleet adopters. Commercial operators in Rio de Janeiro are responding by negotiating long-term offtake agreements with industrial gas suppliers to lock in pre-upgrade pricing.
Fleet procurement is consolidating under mobility-as-a-service contracts that unbundle vehicle ownership from hydrogen supply and maintenance obligations. Large delivery platforms in Mexico City now specify uptime guarantees rather than capital expenditure limits in vendor selection criteria. This behavioral shift concentrates purchasing power among three major logistics platforms operating across the Mexico City-Querétaro-Puebla triangle.
Latin America Fuel Cell Bikes Market Segmentation
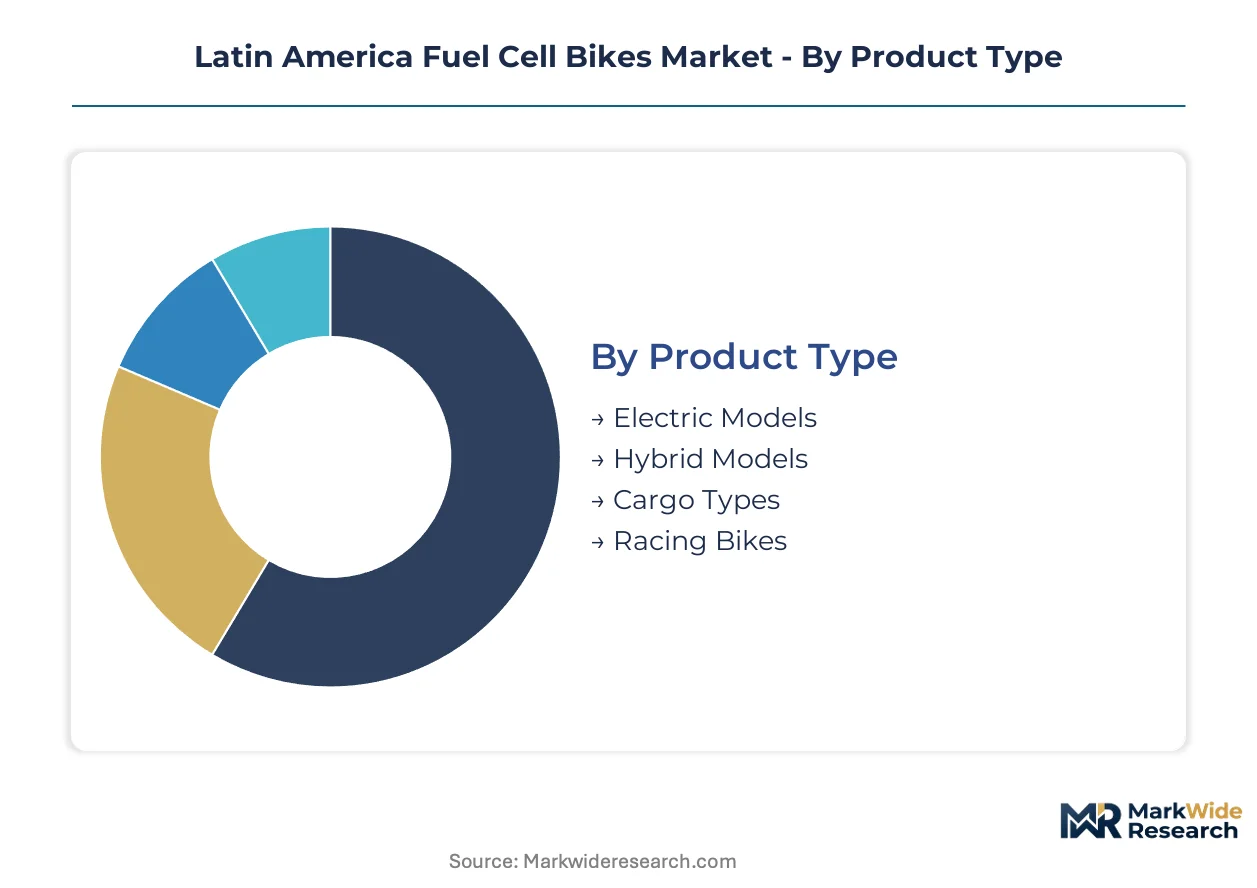
Fuel cell bike segmentation in Latin America reflects competing technical architectures and divergent procurement patterns across consumer and commercial buyers. Category boundaries are blurring as delivery platforms impose uptime requirements that reshape hardware specifications and channel economics.
Product Type:
Frame geometry and powertrain packaging distinguish segments across Brazilian and Mexican assembly lines.
- Electric Models:Pure battery-electric drivetrains dominate current volume due to simpler integration with existing bicycle supply chains. São Paulo metropolitan delivery corridors absorb the majority of units as logistics operators prioritize total cost certainty over range extension.
- Hybrid Models:Combined battery and fuel cell architectures enable flexible refueling strategies across hydrogen-sparse corridors. Mexico City fleet operators specify these configurations to bridge infrastructure gaps while maintaining zero-emission compliance in expanding urban restriction zones.
- Cargo Types:Reinforced frames and extended wheelbases support last-mile freight applications across Rio de Janeiro informal logistics networks.
- Racing Bikes:Lightweight PEM stacks target competitive cycling segments in Chilean and Colombian mountain terrain.
Electric models lead on scale; hybrid models lead on momentum.
End User:
Procurement authority concentrates among platform-mediated buyers with consolidated fleet purchasing power.
- Delivery Services:App-based logistics networks across São Paulo and Mexico City specify fuel cell bikes for routes exceeding battery-electric range limits. Mercado Libre fulfillment partners negotiate uptime-based service contracts rather than capital purchases, shifting vendor economics toward recurring revenue models.
- Commercial Fleets:Corporate mobility programs and postal services deploy standardized vehicle pools with centralized hydrogen procurement. Brazilian postal operator Correios pilots regional hub-and-spoke refueling to amortize infrastructure costs across multiple vehicle categories.
- Individuals:Early adopters in Santiago and Buenos Aires purchase through specialty retailers with technical consultation services.
- Tour Operators:Adventure tourism providers in Patagonia and the Andes lease fuel cell bikes for multi-day expedition support.
Delivery services anchor current demand; commercial fleets drive standardization.
Technology:
Electrochemical system selection determines cold-start performance, power density, and platinum group metal exposure.
- Proton Exchange Membrane:Polymer electrolyte architectures deliver superior power-to-weight ratios and sub-zero startup capability across Andean altitude deployments. Brazilian assemblers source membrane electrode assemblies from European suppliers while negotiating localization timelines under Inova Energia program requirements.
- Direct Methanol:Liquid fuel storage eliminates high-pressure hydrogen handling, appealing to informal delivery operators without depot infrastructure. EMOV integrates these systems for Mexico City street vendors and independent couriers lacking fleet maintenance support.
- Alkaline Fuel Cells:Lower catalyst costs suit stationary charging applications and auxiliary power units rather than primary propulsion.
- Solid Oxide:High-temperature operation limits cycling suitability for bicycle-scale thermal management.
Proton exchange membrane commands margin concentration; direct methanol gains share fastest.
Distribution Channel:
Channel selection reflects buyer technical sophistication and fleet scale procurement centralization.
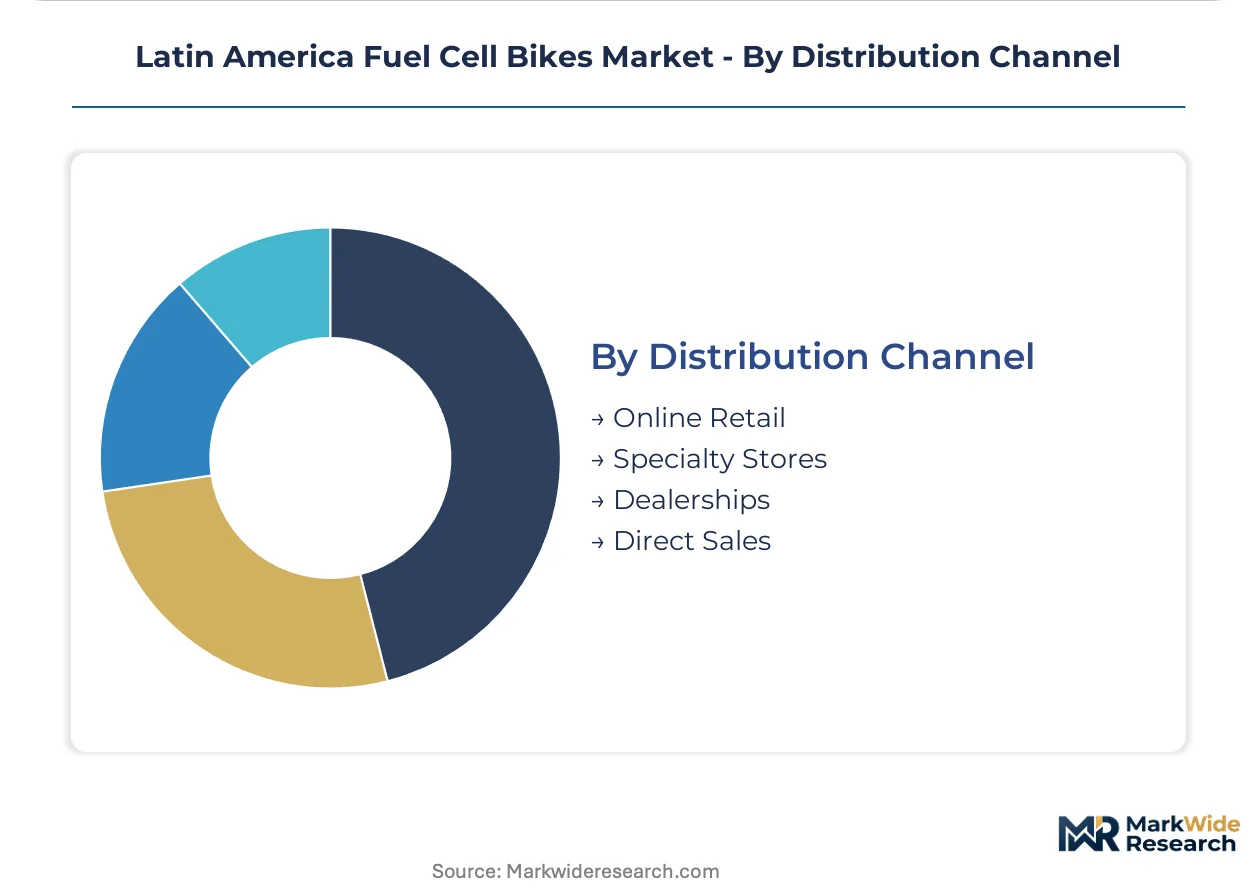
- Direct Sales:Large logistics platforms negotiate manufacturer-direct contracts specifying vehicle uptime, hydrogen supply, and maintenance bundling. These arrangements bypass retail margin stacking and enable customized telemetry integration for fleet management systems.
- Dealerships:Authorized distribution networks provide warranty coverage and service training across Brazilian state capitals. ANP safety certification requirements favor established dealer relationships for pressure vessel inspection and recertification services.
- Specialty Stores:Technical retailers serve enthusiast segments with component-level customization and hydrogen safety education.
- Online Retail:E-commerce penetration remains limited by hazardous materials shipping restrictions and assembly complexity.
Direct sales capture volume concentration; dealerships sustain service monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors Latin American fuel cell bike deployment through concentrated logistics demand and Brazil's Inova Energia program capital flows. Metropolitan corridor electrification mandates across four countries are restructuring procurement geography and infrastructure investment sequencing.
Brazil
Last-mile delivery platforms in São Paulo and Rio de Janeiro compress fleet refueling windows below three minutes, forcing hydrogen infrastructure pre-positioning ahead of consumer adoption curves. ANP pressure vessel standards and municipal fire codes require sequential approvals that extend product launch timelines. Brazilian assemblers source membrane electrode assemblies from European suppliers while negotiating localization timelines under Inova Energia requirements.
Mexico
Mexico City metropolitan transit authorities impose zero-emission zones that exclude battery-electric vehicles with multi-hour charging downtime, redirecting fleet procurement toward fuel cell architectures. CRE oversees energy transition incentives affecting fleet conversion economics through accelerated depreciation schedules for hydrogen assets. EMOV sustains localized system integration capabilities while navigating permitting timelines for hydrogen retail points across the Mexico City-Querétaro-Puebla triangle.
Chile
Santiago early adopters purchase through specialty retailers with technical consultation services, establishing premium consumer segmentation patterns. The country's national energy regulator shapes hydrogen mobility pilot economics through tariff structures for electrolyzer grid connection. Andean altitude deployments favor proton exchange membrane systems for sub-zero startup capability across metropolitan corridors.
Colombia
Bogotá and Medellín lack hydrogen retail infrastructure but possess dense informal delivery networks receptive to lease-to-own fuel cell bike models. The country's national energy agency has yet to issue mobility-specific hydrogen quality standards, creating regulatory uncertainty for assemblers. EMOV integrates direct methanol systems for street vendors and independent couriers lacking fleet maintenance support in these metropolitan clusters.
Argentina
Buenos Aires specialty retailers serve enthusiast segments with component-level customization and hydrogen safety education, anchoring premium positioning. The country's central bank monetary policy volatility complicates long-term fleet financing structures for commercial operators. Patagonia adventure tourism providers lease fuel cell bikes for multi-day expedition support, creating seasonal demand concentration.
Latin America Fuel Cell Bikes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid architecture specialization and localized system integration. The vendor base distributes across three maturity tiers: multinational bicycle manufacturers with fuel cell adaptation programs, regional assemblers with hydrogen supply chain partnerships, and pure-play fuel cell integrators with proprietary stack relationships. Strategic archetypes include logistics-focused fleet solution providers, premium consumer specialists, and infrastructure-integrated mobility service operators. Competitive moves concentrate on strategic partnerships for hydrogen supply security and geographic expansion through municipal pilot program capture.
Within the regional integration tier, EMOV anchors Mexican market presence through localized assembly capabilities and direct methanol fuel cell deployment for informal logistics networks. Pragma Industries exemplifies European technology transfer archetypes, leveraging French fuel cell stack expertise for premium commercial fleet specifications. Azure Bikes occupies cost-optimized positioning, competing on hybrid architecture economics for urban delivery operators across Brazilian metropolitan corridors. These three entities represent divergent strategic bets on technology configuration, geographic focus, and customer segment prioritization.
| Leading Market Players |
|---|
| Giant Bicycles Co. Ltd |
| Trek Bicycle Corporation |
| EDG |
| EMOV (Energía en Movimiento) |
| Pedego Electric Bikes |
| Honda Motor Co. Ltd |
| Azure Bikes |
| Mob-ion |
| Pragma Industries |
| Others |
Pricing and Supply Chain Analysis
Platinum group metal spot prices cascade through membrane electrode assembly costs to stratify fuel cell bike tiers across São Paulo and Mexico City assembly lines. Brazilian assemblers absorb palladium volatility through long-term offtake contracts with industrial gas majors, while Mexican operators leverage CRE depreciation incentives to offset upfront stack premiums.
Pricing Analysis
Input-cost pass-through from platinum group metals concentrates pricing pressure on PEM-equipped fleet specifications. Three-tier pricing structure across premium, standard, and economy levels separates uptime-guaranteed mobility-as-a-service contracts from retail consumer purchases. Price differentiation hinges on certification grade under ANP pressure vessel standards and after-sales service bundling. Fleet operators in Rio de Janeiro exhibit lowest price sensitivity due to uptime-based procurement criteria, while independent couriers in Bogotá face acute cost compression without hydrogen infrastructure scale.
Supply Chain Analysis
Workforce availability constraints in Brazil and Mexico force assemblers to import membrane electrode assembly technicians at premium cost. Supply concentrates in European membrane electrode assembly sources, Chinese hydrogen storage component manufacturers, and regional Brazilian frame fabricators. Raw material dependencies span platinum catalysts, carbon fiber pressure vessels, and polymer electrolyte membranes. Single-source vulnerability persists where industrial gas majors control ninety percent of regional electrolyzer output. Distribution runs through direct sales channels for large logistics platforms and authorized dealerships for warranty-dependent fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America fuel cell bikes market compounds steadily as metropolitan zero-emission zone mandates lock in fleet replacement cycles across São Paulo, Mexico City, and Santiago corridors.
For Market Incumbents: Extend hydrogen supply security through backward integration into captive electrolyzer partnerships or long-term offtake agreements with industrial gas majors. Deepen vertical control over membrane electrode assembly localization timelines under Brazil's Inova Energia program requirements to preempt emerging entrant cost advantages.
For New Entrants and Emerging Players: Capture Bogotá and Medellín's lease-to-own white space before infrastructure buildout raises competitive barriers. Direct methanol fuel cell deployment for informal delivery networks bypasses hydrogen retail dependency and anchors go-to-market through street vendor associations.
For Investors and Strategic Acquirers: Consolidation pressure builds where membrane electrode assembly skill scarcity and single-source hydrogen concentration create acquisition premiums for integrated assemblers. Target firms with CRE incentive access and established municipal pilot relationships. Watch ANP regulatory harmonization progress with municipal transit authorities as fleet procurement window inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrode Assembly Localization | Inova Energia program requirements force Brazilian sourcing transitions from European suppliers. |
| Hydrogen Supply Partnership | Long-term offtake agreements with industrial gas majors lock in pre-upgrade pricing under ANP purity mandates. |
| Direct Methanol System Integration | Liquid fuel storage eliminates high-pressure handling for Mexico City informal delivery operators. |
| Mobility-as-a-Service Contracting | Uptime guarantees replace capital expenditure limits for Mercado Libre fulfillment partners. |
| Telematics Platform Deployment | Automated pressure monitoring reduces HSE personnel requirements across São Paulo fleet depots. |
Research Methodology
Coverage spans Brazil, Mexico, Chile, Colombia, and Argentina, with primary inputs from each national corridor. Fleet procurement managers at delivery platforms, ANP regulatory affairs officers, hydrogen supply specialists at industrial gas majors, and membrane electrode assembly technicians provided structured interviews. Secondary validation drew from ANP hydrogen quality specifications, CRE energy transition incentive filings, metropolitan transit authority electrification mandates, and customs data on fuel cell component imports. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Granularity-level modeling captured product type splits between electric, hybrid, cargo, and racing configurations; end-user segmentation across delivery services, commercial fleets, individuals, and tour operators; technology differentiation between proton exchange membrane and direct methanol systems; and distribution channel dynamics spanning direct sales, dealerships, specialty stores, and online retail. CAGRs derived from logistic curve adoption modeling for fleet procurement and infrastructure deployment sequencing. Forecast inputs incorporated Inova Energia capital allocation schedules and CRE depreciation schedule revisions.
Regulatory harmonization delays, platinum group metal price spikes, and hydrogen infrastructure permitting backlogs are the dominant revision risks to modeled adoption curves. Forecasts reflect documented assumptions on municipal zero-emission zone expansion timelines and electrolyzer capacity commissioning schedules. Material deviation in ANP-CRE regulatory coordination or industrial gas major pricing power warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Germany E-Bike Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
LAMEA Motorcycle ADAS Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Two Wheeler Seats Market
Bikes and Motorcycles
Motorsports Motorcycle Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Asia-Pacific Motorcycle Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Bicycle Crank Motor Market