
 Motorcycle Seat Market | 2026-2036
Motorcycle Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Seat Market Analysis
Buyer concentration among motorcycle enthusiasts is restructuring as custom builders and independent aftermarket retailers fragment what was once OEM-dominated demand. Harley-Davidson, Inc. leverages its captive parts ecosystem to sustain premium seat attach rates across touring models. Honda Motor Co., Ltd. anchors volume through integrated supply chains that feed both factory-fit and replacement channels. Corbin differentiates via made-to-order leather craftsmanship that commands sustained loyalty among long-distance riders.
A motorcycle seat is a rider-support component engineered from foam substrates, cover materials, and structural pans, typically specified by density ratings between 40-80 kg/m³ for cushioning and fatigue resistance, designed to secure ergonomic positioning and vibration isolation during operation. Leather covers command the highest margin pools in the material dimension due to durability premiums and tactile perception among touring and cruiser segments. Sport seats represent the fastest-growing type category as track-day participation and performance-oriented road riding expand across North American and European enthusiast bases. Quick-release mounting styles are gaining structural share in the aftermarket as riders demand tool-free conversion between solo and passenger configurations.
FDA guidelines on skin-contact material biocompatibility, EPA restrictions on volatile organic compound emissions from foam production, and NHTSA Federal Motor Vehicle Safety Standard No. 302 flammability requirements collectively shape material selection and manufacturing location decisions for seats sold into the United States. ECHA REACH substance restrictions and EU RoHS hazardous substance limits further constrain foam chemistry and metal hardware sourcing for European market access. Stakeholders must monitor evolving chemical compliance timelines and decide whether to regionalize foam production or standardize formulations across jurisdictions.
Market Dynamics
Aftermarket retailers are capturing share from OEM channels as rider customization preferences intensify and quick-release mounting systems enable tool-free configuration swaps between solo and passenger setups.
Growth Catalysts
- REACH substance restrictions:ECHA mandates in Europe are accelerating reformulation of foam substrates toward low-emission chemistry, creating first-mover advantages for compliant suppliers.
- Track-day participation:Performance-oriented road riding across North American enthusiast bases is expanding demand for sport seat configurations with enhanced lateral support.
- India replacement volumes:Hero MotoCorp and Honda's local manufacturing operations sustain high aftermarket turnover across both commuter and premium motorcycle segments.
Market Restraints
- Petrochemical input volatility:Polyurethane foam production depends on isocyanate and polyol feedstocks whose pricing fluctuates with crude oil markets.
- European regulatory friction:RoHS hazardous substance limits constrain metal hardware sourcing and extend qualification timelines for pan assemblies.
- Synthetic leather substitution:Advanced vinyl and microfiber covers are eroding margin pools in mid-tier touring segments where durability perception gaps are narrowing.
Strategic Opportunities
- Brazilian aftermarket penetration:ANVISA's streamlined accessory approval pathways are opening distribution channels for premium seat imports in Latin America's largest motorcycle market.
- Tool-free mounting convergence:Integration of quick-release hardware with heated element wiring is creating premium upgrade bundles for touring riders.
- EU Green Deal tailwinds:Circular economy mandates for recyclable foam are positioning bio-based polyurethane producers for OEM qualification.
Industry Challenges
- Fatigue testing capex:NHTSA Federal Motor Vehicle Safety Standard No. 302 flammability validation requires investment in burn-rate testing equipment for US market access.
- Biocompatibility certification timelines:FDA skin-contact material guidelines extend development cycles for seats with integrated heating elements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Seat Market |
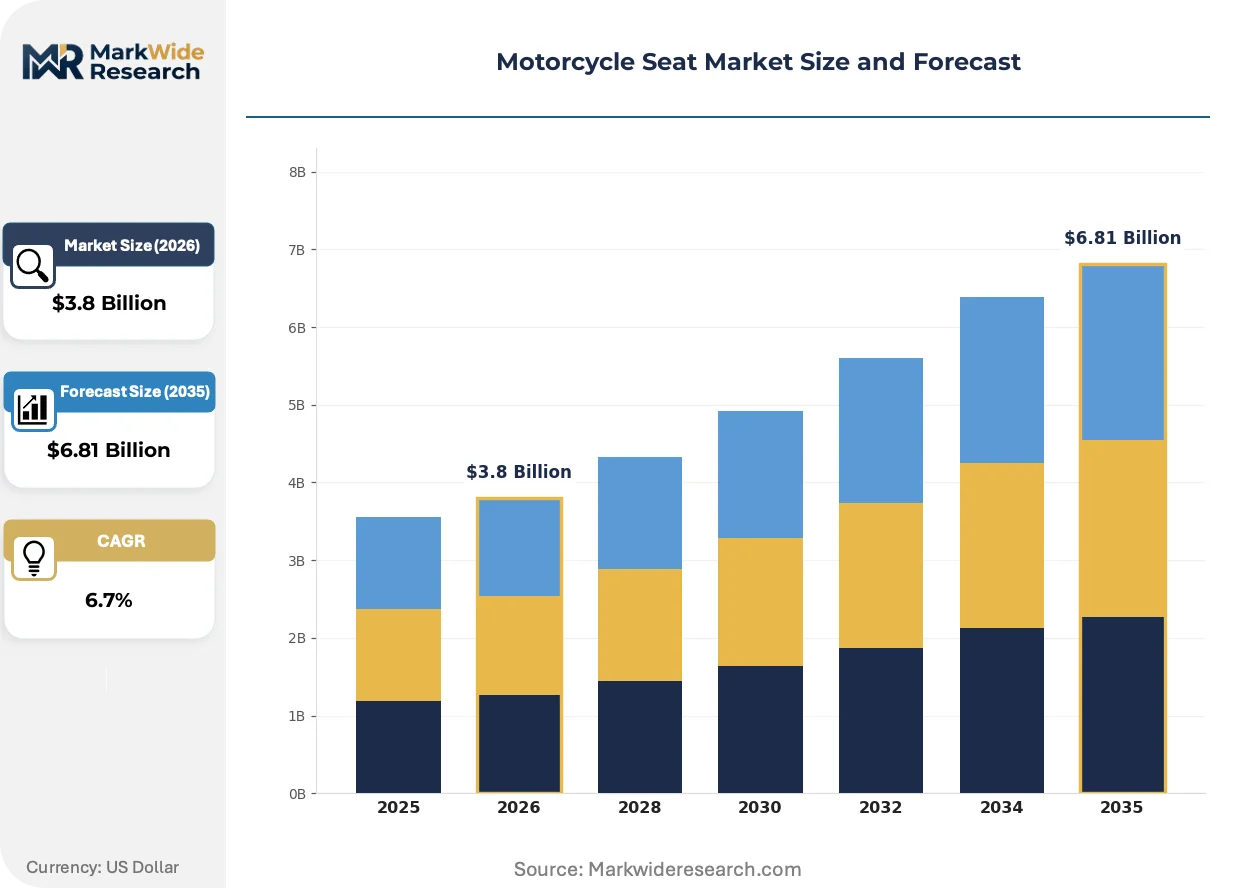
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Leather, Vinyl, Fabric, Gel Type: Double Seat, Solo Seat, Touring Seat, Sport Seat Mounting Style: Bolt-on, Clip-on, Quick-release, Adjustable End User: Motorcycle Enthusiasts, OEMs, Aftermarket Retailers, Custom Builders |
| Companies Covered | Harley-Davidson, Inc., Corbin, Honda Motor Co., Ltd., Sargent Seats, Saddlemen, Yamaha Motor Co., Ltd., Mustang Seats, Kawasaki Heavy Industries, Ltd., Hero MotoCorp Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Seat Market Emerging Trajectories
Material science advances and mounting system modularity are restructuring how seats are specified, produced, and replaced across factory-fit and aftermarket channels.
Gel-infused foam layering is overtaking conventional single-density construction in long-distance touring applications. Premium cruiser buyers are specifying multi-zone cushioning that isolates road vibration across sustained highway operation. This technology is compressing replacement cycles as riders upgrade factory seats within months of vehicle purchase.
EPA restrictions on volatile organic compound emissions from foam production are forcing manufacturing location decisions for seats sold into the United States. Molders are regionalizing production or standardizing low-VOC formulations across jurisdictions to maintain cross-border shipment flexibility. Sport and adventure-touring segments face the steepest compliance cost absorption.
Direct-to-rider e-commerce platforms are fragmenting traditional parts distribution hierarchies. Independent custom builders and enthusiast forums now drive specification conversations that bypass dealer service departments. This channel shift is most pronounced in North American and Australian markets where aftermarket brand loyalty exceeds OEM attachment.
Motorcycle Seat Market Segmentation
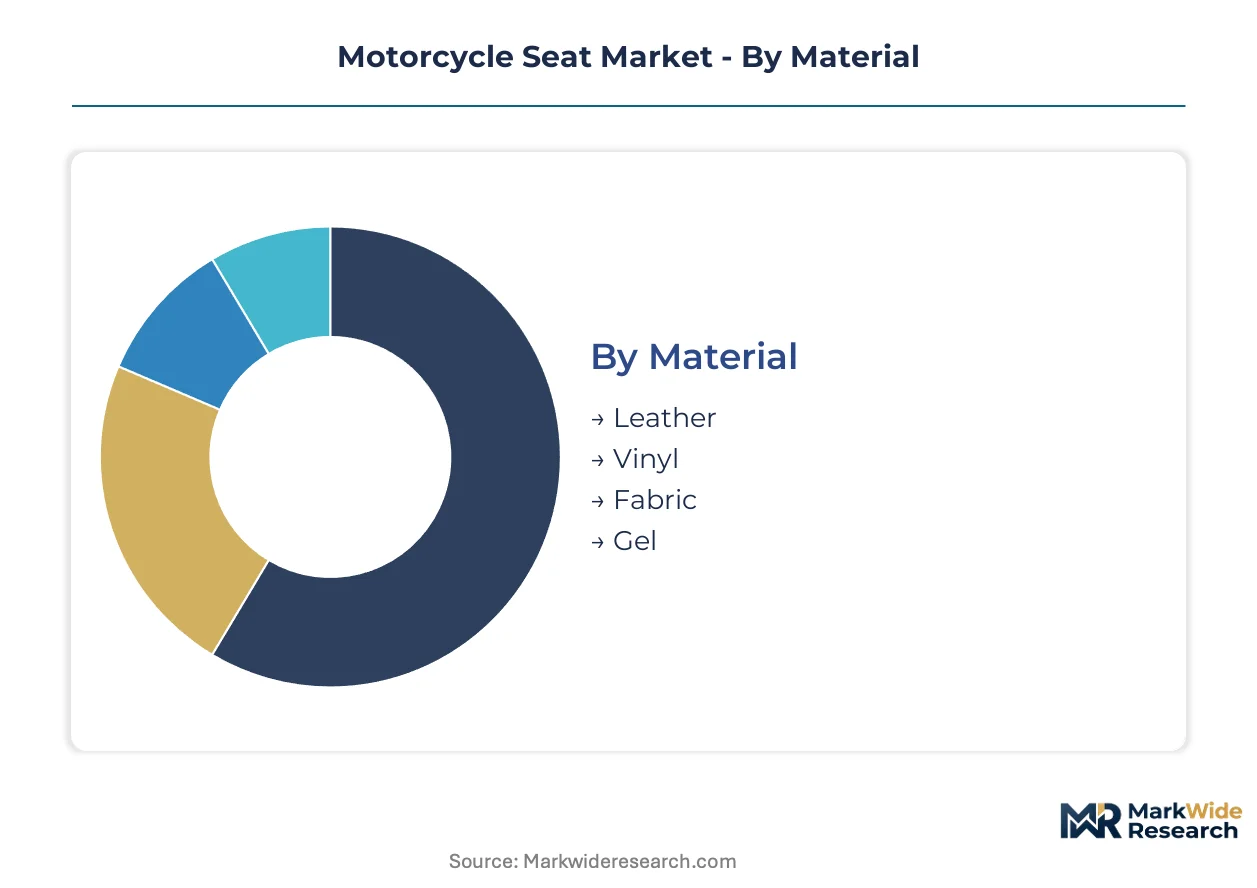
Segmentation in the motorcycle seat market tracks how rider preferences for customization, comfort duration, and mounting flexibility reshape upgrade timing and channel selection. Replacement cycles compress when material technologies improve or when regulatory shifts force foam reformulation.
Material:
Upgrade decisions hinge on tactile durability expectations and climate exposure, with premium covers justifying shorter replacement intervals among touring specialists.
- Leather:Full-grain or top-grain hides with density-rated foam substrates command sustained loyalty among long-distance riders. Demand concentrates in North American and European touring segments where tactile perception and weather resistance justify premium positioning.
- Vinyl:Advanced PVC formulations with UV-stabilized topcoats deliver cost-competitive weatherproofing for commuter replacement cycles. Volume clusters in India and Brazil where OEM-specified vinyl dominates factory-fit channels and price-sensitive aftermarket turnover.
- Fabric:Breathable woven synthetics with moisture-wicking backings suit tropical climates and adventure-touring applications.
- Gel:Viscoelastic polymer layers integrated with polyurethane bases isolate road vibration for sustained highway operation.
Vinyl sits at the top of the volume ranking, with Gel climbing the fastest as vibration isolation becomes a stated purchase criterion.
Type:
Application-specific geometries determine foam density distribution and cover stitching patterns, with performance-oriented designs absorbing disproportionate engineering resources.
- Sport Seat:Aggressive contours with 60-80 kg/m³ high-density foam and anti-slip Alcantara surfaces lock riders during cornering. Demand is accelerating across North American track-day participation and European canyon-carving communities where lateral support reduces fatigue.
- Touring Seat:Multi-zone cushioning with gel-infused layers and heated element integration supports 500+ mile days. Replacement volume concentrates among Harley-Davidson and Honda Gold Wing owners in the United States and Germany where factory seats see upgrade within 12 months of purchase.
- Double Seat:Extended pans with passenger grab rails and dual-density foam construction serve two-up riding configurations.
- Solo Seat:Minimalist profiles with reduced weight and clean lines dominate custom builder specifications.
Touring Seat captures the highest absolute replacement spend, while Sport Seat gains share fastest among enthusiast demographics.
Mounting Style:
Tool-free conversion capability now shapes inventory decisions at independent retailers serving riders who alternate between solo commuting and weekend two-up touring.
- Quick-release:Cam-lock or lever-actuated mechanisms with integrated electrical connectors enable sub-60-second configuration swaps. Demand concentrates in aftermarket channels across Australia and the United States where riders maintain multiple seat sets for different use cases.
- Bolt-on:Threaded fasteners with torque-specified clamping remain the OEM default for factory-fit applications. Volume anchors in India and China where cost minimization overrides convenience premiums in commuter segments.
- Clip-on:Spring-loaded retention systems suit entry-level replacement seats with simplified installation.
- Adjustable:Sliding rail mechanisms with height and angle indexing accommodate multiple rider statures on shared motorcycles.
Bolt-on retains volume leadership in factory-fit channels, with Quick-release expanding most quickly in premium aftermarket distribution.
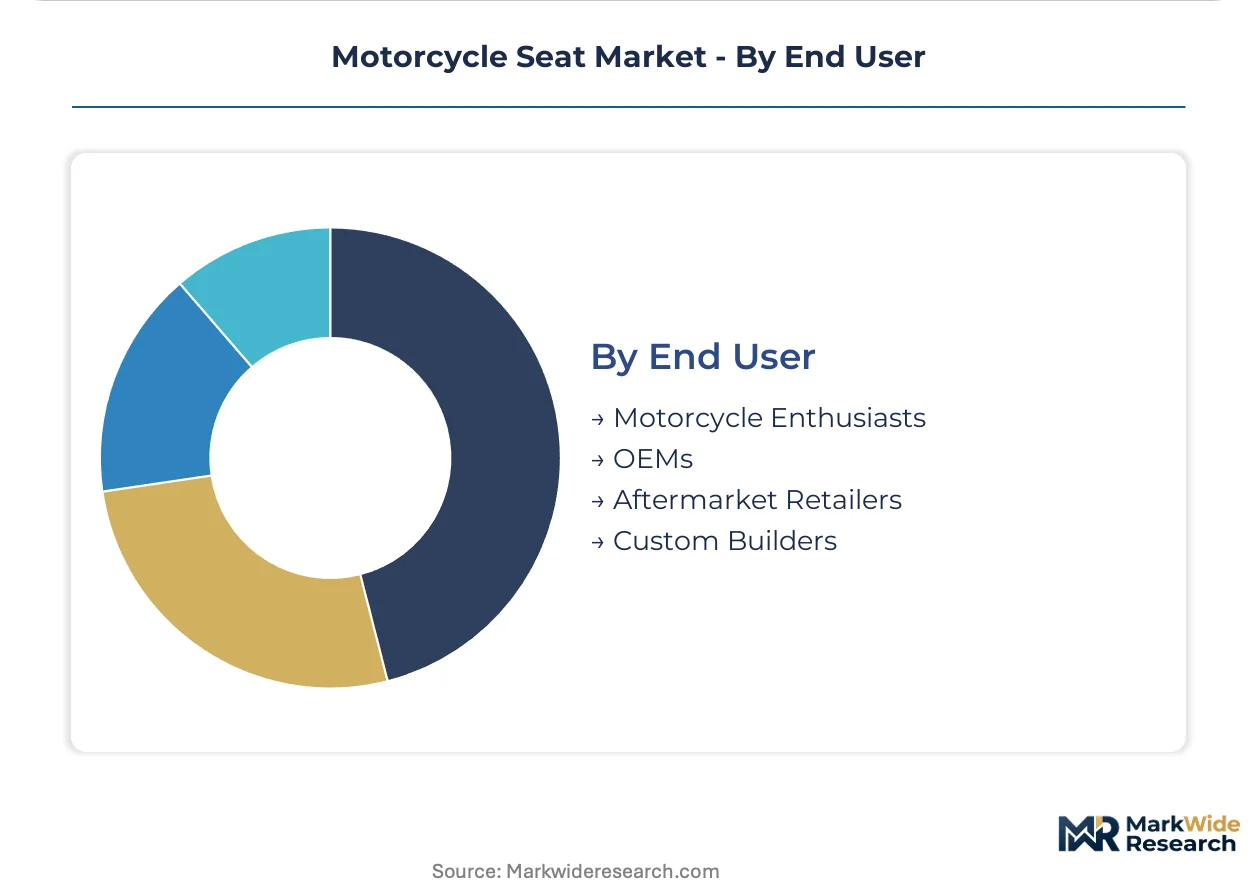
End User:
Channel fragmentation between integrated OEM supply chains and independent customization specialists determines margin capture and specification influence.
- Aftermarket Retailers:Specialized distributors with direct-to-rider e-commerce platforms and forum-driven specification authority. Demand concentrates in North America and Australia where brand loyalty to Corbin and Saddlemen exceeds OEM attachment rates.
- Custom Builders:Independent fabrication shops producing made-to-order seats with rider-specific ergonomic mapping. Volume clusters in California, Texas, and Bavaria where one-off craftsmanship commands 4-6 week lead times and sustained referral networks.
- OEMs:Factory-integrated supply chains feeding just-in-time assembly lines with cost-optimized specifications.
- Motorcycle Enthusiasts:Individual riders conducting direct research and purchase through digital channels.
OEMs anchor absolute volume throughput, with Custom Builders gaining influence fastest as social media documentation drives specification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India generates replacement volumes that outpace Germany's premium upgrade cycles, while Brazil's regulatory streamlining attracts aftermarket entrants seeking Latin American footholds. National motorcycle fleet sizes and local manufacturing depth determine whether demand flows through OEM-integrated channels or fragments toward customization specialists.
United States
Harley-Davidson's captive parts ecosystem sustains premium seat attach rates across touring models, with Gold Wing owners upgrading factory seats within 12 months of purchase. NHTSA Federal Motor Vehicle Safety Standard No. 302 flammability requirements shape material selection and manufacturing location decisions. Wisconsin and Pennsylvania host concentrated aftermarket fabrication clusters serving long-distance riders.
Germany
ECHA REACH substance restrictions and EU RoHS hazardous substance limits constrain foam chemistry and metal hardware sourcing for European market access. Bavarian custom builders command 4-6 week lead times for made-to-order ergonomic mapping. The KBA maintains type-approval pathways that extend qualification timelines for pan assemblies with integrated electronics.
India
Hero MotoCorp and Honda's local manufacturing operations sustain high aftermarket turnover across both commuter and premium motorcycle segments. BIS certification requirements apply to factory-fit specifications while aftermarket channels operate with reduced regulatory friction. Haryana and Tamil Nadu anchor production gravity for domestic supply and regional export.
Brazil
ANVISA's streamlined accessory approval pathways are opening distribution channels for premium seat imports in Latin America's largest motorcycle market. São Paulo-based distributors now stock quick-release configurations for tool-free conversion between solo and passenger setups. Minas Gerais and Rio Grande do Sul concentrate regional assembly operations feeding Mercosur demand.
Japan
METI industrial standards and JIS certification frameworks govern factory-fit specifications for domestic manufacturers. Yamaha Motor Co., Ltd. and Kawasaki Heavy Industries, Ltd. anchor integrated supply chains that feed both OEM assembly and replacement channels. The Kanto region around Tokyo hosts specialized foam molders serving premium export markets.
Motorcycle Seat Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across factory-fit and aftermarket channels. OEM-integrated players leverage captive vehicle platforms to sustain attach rates, while independent fabricators capture margin through customization and ergonomic specialization. Two strategic archetypes dominate: vertically integrated motorcycle manufacturers with captive parts ecosystems, and independent seat specialists with made-to-order craftsmanship capabilities. Competitive moves concentrate on geographic expansion into regulatory-streamlined markets and portfolio diversification toward heated-element integration.
Among the OEM-integrated tier, Harley-Davidson, Inc. and Honda Motor Co., Ltd. exemplify diversified manufacturers with captive supply chains feeding both factory-fit and replacement channels. Corbin occupies a distinct position within the independent specialist archetype, commanding sustained loyalty among long-distance riders through made-to-order leather craftsmanship. These three companies represent the structural split between volume-anchored integrated players and margin-focused customization specialists.
| Leading Market Players |
|---|
| Harley-Davidson, Inc. |
| Corbin |
| Honda Motor Co., Ltd. |
| Sargent Seats |
| Saddlemen |
| Yamaha Motor Co., Ltd. |
| Mustang Seats |
| Kawasaki Heavy Industries, Ltd. |
| Hero MotoCorp Limited |
| Others |
Supply Flow & Price Mechanics
Captive supply chains at Harley-Davidson and Honda anchor both production control and pricing power across factory-fit and replacement channels. This integration pattern compresses margin capture for independent molders while concentrating premium pricing authority with OEM-integrated tiers.
Pricing Analysis
Capacity additions in India and Brazil are reshaping price floors for vinyl and fabric covers as regional foam molders expand output. Three-tier pricing structure across premium, standard, and economy levels separates gel-infused touring configurations from commuter-grade bolt-on replacements. Cost compression in mid-tier synthetic leather is intensifying because advanced microfiber covers narrow durability perception gaps. Commuter segments in India and Brazil exhibit highest price sensitivity, while North American touring specialists absorb premium leather positioning with minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements at major OEMs mandate multi-supplier qualification for foam substrates and metal pan hardware, fragmenting volume across qualified vendors. Manufacturing concentrates in India, China, and Germany, with Haryana and Tamil Nadu anchoring polyurethane molding for regional export. Production draws from isocyanate and polyol feedstocks, leather tanneries in Italy and Mexico, and quick-release hardware from Taiwanese precision metalworkers. Single-source vulnerability in Italian full-grain leather supply creates exposure for premium touring seat makers. Distribution runs through OEM captive parts networks, independent aftermarket retailers, and direct-to-rider e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as rider upgrade cycles compress and gel-infused configurations displace factory-fit foam within months of vehicle purchase.
For Market Incumbents: Extend certification coverage across ECHA REACH and EPA low-VOC formulations to defend against bio-based polyurethane entrants seeking OEM qualification. Deepen backward integration into foam chemistry to offset petrochemical input volatility and protect margin pools in touring segments.
For New Entrants and Emerging Players: Gel-layer integration technology offers a technology-first wedge into the premium aftermarket as vibration isolation becomes a stated purchase criterion. Brazilian distribution through ANVISA-streamlined pathways and Australian quick-release mounting specialization represent the most penetrable white-space targets. Direct-to-rider e-commerce with forum-driven specification authority bypasses dealer service hierarchies.
For Investors and Strategic Acquirers: Roll-up economics work for independent custom builders with made-to-order craftsmanship capabilities because social media documentation drives specification trends that bypass OEM channels. Platform consolidation of Bavarian and California fabrication shops with 4-6 week lead times offers long-term viability across a 5-10 year window. Watch for inflection when bio-based polyurethane producers achieve OEM qualification under EU Green Deal circular economy mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Foam Reformulation | ECHA mandates in Europe accelerate low-emission chemistry adoption, creating first-mover qualification advantages. |
| Quick-Release Hardware Integration | Tool-free mounting with heated element wiring bundles captures premium upgrade spend from touring riders. |
| Direct-to-Rider E-Commerce Launch | Forum-driven specification authority fragments traditional dealer service hierarchies in North America and Australia. |
| Bio-Based Polyurethane Scale-Up | EU Green Deal circular economy mandates position sustainable foam producers for OEM supply chain integration. |
| ANVISA Distribution Expansion | Streamlined Brazilian accessory approval pathways open Latin America's largest motorcycle market to premium imports. |
Methodological Framework
Bottom-up aftermarket retailer and OEM procurement modeling reconciled against top-down foam substrate and cover material production tracking forms the analytical core of this study. Primary interviews with custom fabrication shop owners, aftermarket distribution managers, OEM platform engineers, and regulatory compliance officers at foam molders combined with secondary validation from BIS certification databases, ECHA substance restriction registries, NHTSA Federal Motor Vehicle Safety Standard filings, and customs trade records. Triangulation across these sources ensures coverage of both factory-fit specification flows and fragmented aftermarket channel dynamics.
Historical trendline analysis of replacement cycle compression and material substitution patterns informs the projection framework across the analysis window. Segmentation dimensions modeled include material grade tier, seat type geometry, mounting style complexity, and end-user channel structure. CAGR derivation rests on correlating rider upgrade timing with gel-infusion technology penetration and regulatory compliance cost absorption. Industry-specific forecast inputs incorporate track-day participation growth and quick-release hardware adoption curves.
The model holds under stable petrochemical feedstock pricing and incremental regulatory tightening; deviation in crude oil volatility or accelerated EU Green Deal implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Electric Cargo Bikes Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
Two-Wheeler Services Market
Bikes and Motorcycles
Two Wheeler Handlebars Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
China Two Wheeler Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Trike Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
Motorcycle Fuel Hoses Market
Bikes and Motorcycles
Fuel Cell Bikes Market