
 Fuel Cell Bikes Market | 2026-2036
Fuel Cell Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell Bikes Market Foresight
Multi-source component procurement is consolidating around a tighter circle of qualified fuel cell stack and hydrogen storage suppliers. Toyota Motor Corporation leverages its proprietary proton exchange membrane expertise to anchor high-performance powertrain development. Pragma Industries competes through specialized hydrogen scooter platforms designed for European municipal fleets. Segway differentiates via integrated battery-fuel cell hybrid architectures that extend range without expanding tank volume.
A fuel cell bike integrates a hydrogen-powered electrochemical generator with an electric drivetrain, typically employing proton exchange membrane technology operating at 60-80°C to convert stored hydrogen into electricity with water vapor as the sole emission. The system serves commercial and personal mobility applications requiring extended range beyond conventional battery electric equivalents. Hydrogen scooters lead current deployment volumes due to commercial fleet prioritization, while proton exchange membrane systems capture dominant technology share given their favorable power density and cold-start performance. Delivery services represent the fastest-expanding application segment as logistics operators seek zero-emission alternatives with sub-ten-minute refueling cycles.
The EU Green Deal and F-Gas Regulation shape hydrogen infrastructure investment timelines and component fluorinated gas compliance requirements across European markets. Japan's METI hydrogen society roadmap directly subsidizes fuel cell vehicle procurement including two-wheeler categories, while ISO 14687 hydrogen fuel quality standards govern stack durability and warranty terms. Stakeholders must monitor hydrogen production cost curves and refueling station density thresholds that determine fleet operator total cost of ownership parity against battery electric alternatives.
Market Dynamics
Zero-emission mandates in Amsterdam and Seoul are compressing fleet procurement cycles for hydrogen scooters, while proton exchange membrane stack suppliers consolidate around port-adjacent logistics corridors where refueling density supports commercial viability.
Growth Catalysts
- EU Green Deal infrastructure funding:The framework channels capital toward hydrogen refueling clusters near urban distribution hubs, directly enabling fleet operator total cost of ownership parity calculations.
- Commercial delivery fleet electrification mandates:Municipal procurement rules in dense metropolitan zones prioritize sub-ten-minute refueling cycles that battery alternatives cannot match.
- Japan METI hydrogen society subsidies:Direct fiscal support for fuel cell vehicle categories including two-wheelers accelerates certification timelines and warranty standardization.
Market Restraints
- Platinum group metal cost volatility:Catalyst loading requirements for proton exchange membrane stacks expose manufacturers to palladium and iridium price swings that compress stack margin structures.
- East Asian supply concentration:Qualified hydrogen storage cylinder and high-pressure valve suppliers cluster in Japan and South Korea, creating single-source vulnerability for European assemblers.
- ISO 14687 fuel quality enforcement:Stringent hydrogen purity specifications extend certification timelines and raise warranty reserve requirements for stack manufacturers.
Strategic Opportunities
- Indian metropolitan logistics corridors:Underdeveloped battery swapping infrastructure and severe range anxiety create first-mover advantage for hydrogen scooter fleet trials in Bangalore and Mumbai.
- Battery-fuel cell hybrid architectures:Converging lithium-ion buffer systems with low-pressure hydrogen storage enables range extension without cylindrical tank volume penalties.
- EU F-Gas Regulation compliance pathways:Fluorinated gas restrictions on conventional cooling systems create regulatory tailwind for water-cooled fuel cell thermal management adoption.
Industry Challenges
- Electrochemical systems engineering talent scarcity:Specialized expertise in membrane electrode assembly fabrication and stack sealing protocols commands premium compensation that strains mid-tier manufacturer hiring pipelines.
- Multi-standard certification complexity:Divergent UN ECE R134 hydrogen system approvals, ISO 23273 safety requirements, and national type-approval processes extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell Bikes Market |
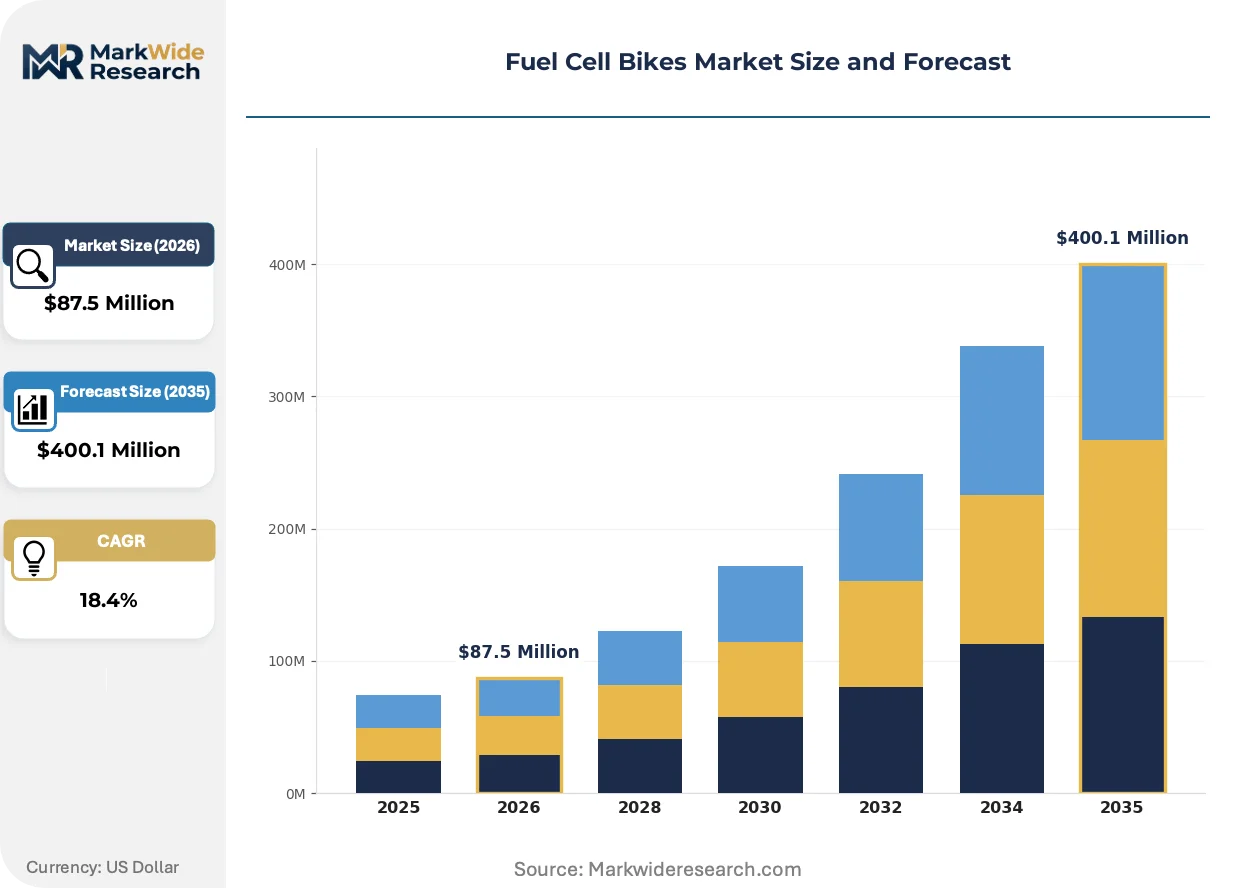
| Market Size in 2026 | $87.5 Million |
| Market Size in 2035 | $400.1 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Motorcycles, Hydrogen Scooters, Hybrid Bicycles, Fuel Cell Mopeds, Battery Electric Bikes Technology: Proton Exchange Membrane, Solid Oxide, Alkaline, Phosphoric Acid, Direct Methanol Application: Personal Commuting, Delivery Services, Police Patrol, Tourist Rentals, Corporate Fleets End User: Individual Consumers, Logistics Companies, Law Enforcement Agencies, Rental Operators |
| Companies Covered | Honda Motor, Hyundai Motor Company, Toyota Motor Corporation, Segway, BMW, Xiaomi, Pragma Industries, Azure Bikes, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell Bikes Market Shifts & Advancements
Proton exchange membrane technology is consolidating its position as the dominant electrochemical conversion platform, while regulatory frameworks in Japan and Europe compress certification timelines and fleet procurement patterns shift toward performance-based contracting.
Membrane electrode assemblies with reduced platinum loading are consolidating as the standard stack architecture for two-wheeler applications. Municipal fleet operators in Amsterdam and Seoul specify these configurations for their favorable cold-start performance below freezing. The technology is consolidating supplier tiers around membrane specialists capable of sub-100-micron thickness consistency.
The EU F-Gas Regulation is tightening fluorinated gas restrictions on thermal management components used in competing battery electric cooling systems. This regulatory pressure elevates water-cooled fuel cell architectures that avoid synthetic refrigerants entirely. European municipal procurement specifications increasingly reference F-Gas compliance as a mandatory evaluation criterion.
Fleet operators are migrating from unit-based purchasing to total cost of ownership performance contracts that bundle vehicle, hydrogen supply, and maintenance into per-kilometer pricing. Logistics providers in Japanese port cities favor this model for its capital expenditure avoidance. The shift is most visible in Tokyo and Osaka metropolitan delivery networks where hydrogen station density supports guaranteed fuel availability clauses.
Fuel Cell Bikes Market Segmentation
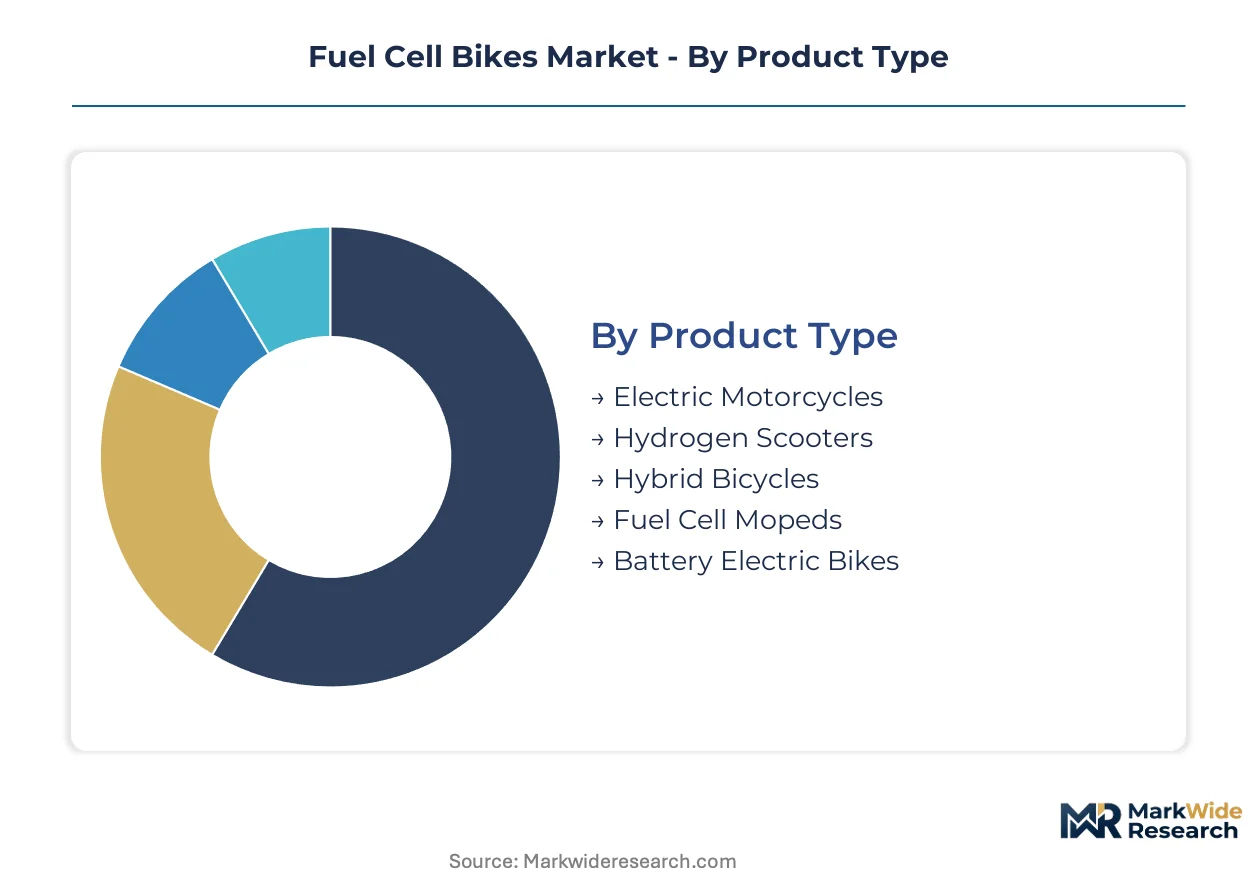
Fuel cell bike procurement patterns diverge sharply across vehicle formats and operational duty cycles. Fleet operators prioritize refueling speed and payload capacity over upfront unit cost, while individual buyers weigh hydrogen station accessibility against range specifications.
Product Type:
Replacement cycles for commercial fleet vehicles compress as municipal zero-emission mandates tighten, accelerating upgrade decisions toward platforms with sub-ten-minute refueling.
- Hydrogen Scooters:Compact two-wheelers integrating proton exchange membrane stacks with compressed hydrogen storage at 350-700 bar. Amsterdam and Seoul municipal delivery fleets specify these for last-mile logistics where battery swapping infrastructure remains underdeveloped.
- Electric Motorcycles:Higher-displacement platforms employing fuel cell range extenders alongside lithium-ion buffers. Japanese port-city logistics corridors concentrate demand for highway-capable speeds with guaranteed fuel availability clauses.
- Fuel Cell Mopeds:Low-speed urban mobility with reduced tank capacity for dense European centers.
- Hybrid Bicycles:Pedal-assist architectures combining small fuel cells with minimal hydrogen storage for tourist rental applications.
- Battery Electric Bikes:Conventional lithium-ion platforms serving as baseline comparison for total cost of ownership calculations in emerging markets.
Volume placements concentrate in Hydrogen Scooters; the faster expansion belongs to Electric Motorcycles.
Technology:
Cost tiers stratify sharply by catalyst loading requirements and thermal management complexity, with premium membrane electrode assemblies commanding threefold stack pricing over alkaline alternatives.
- Proton Exchange Membrane:Low-temperature electrochemical conversion at 60-80°C using perfluorinated sulfonic acid membranes with platinum-based catalysts. Dominant technology share reflects favorable power density for two-wheeler packaging constraints and cold-start performance below freezing.
- Solid Oxide:High-temperature ceramic electrolyte systems operating above 600°C with superior efficiency but extended warm-up periods. Stationary auxiliary power applications in Japanese logistics hubs favor these for combined heat and power recovery.
- Alkaline:Liquid electrolyte architectures with reduced precious metal loading for cost-sensitive fleet trials.
- Phosphoric Acid:Mid-temperature operation at 150-200°C with established stationary deployment experience.
- Direct Methanol:Liquid fuel convenience avoiding compressed hydrogen infrastructure for remote rental operations.
Procurement volumes stack heavily toward Proton Exchange Membrane; Solid Oxide is climbing the fastest as combined heat and power integration spreads.
Application:
Customer type determines specification priorities, with commercial operators accepting higher capital expenditure for guaranteed uptime versus individual buyers optimizing for purchase price.
- Delivery Services:High-utilization fleet operations requiring 200+ kilometer daily range with minimal downtime. Tokyo and Osaka metropolitan networks specify performance-based contracts bundling vehicle, hydrogen supply, and maintenance into per-kilometer pricing.
- Corporate Fleets:Employee mobility programs with centralized refueling at corporate campuses. European port-adjacent logistics clusters concentrate early adoption where station density supports guaranteed availability.
- Personal Commuting:Individual ownership with intermittent usage patterns and range anxiety sensitivity.
- Police Patrol:Municipal enforcement requiring rapid response capability and all-weather reliability.
- Tourist Rentals:Seasonal demand with fixed-route operations and centralized depot refueling.
Deployment volumes center on Delivery Services; Corporate Fleets are gaining share fastest as performance contracting models mature.
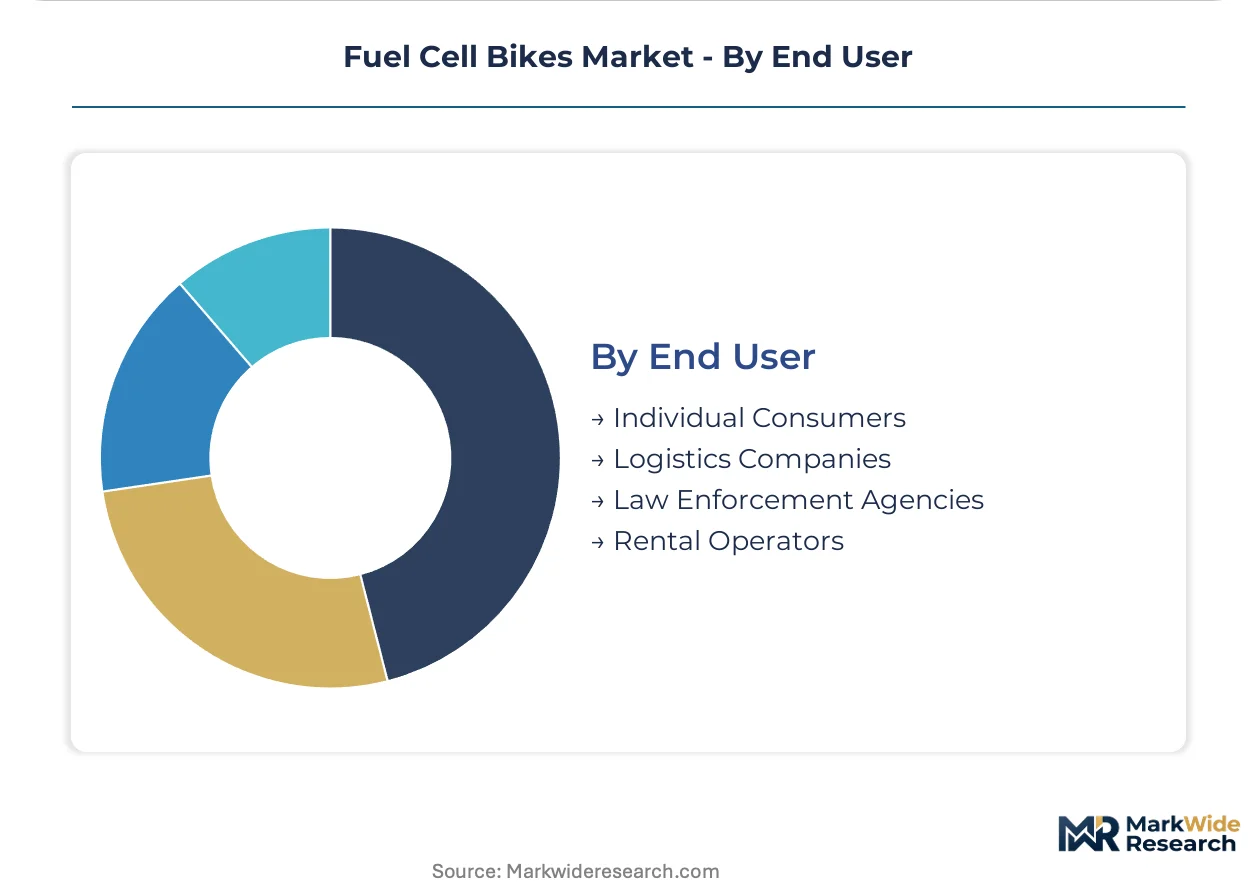
End User:
Supply concentration among qualified fuel cell stack and hydrogen storage vendors shapes procurement access, with logistics companies leveraging volume commitments for priority allocation.
- Logistics Companies:Fleet-scale operators with dedicated procurement teams negotiating hydrogen supply agreements. Amsterdam municipal mandates compress their procurement cycles toward certified platforms with established warranty terms.
- Individual Consumers:Price-sensitive buyers dependent on retail hydrogen pricing and station network density.
- Law Enforcement Agencies:Specification-driven procurement with reliability and rapid refueling as mandatory criteria.
- Rental Operators:Asset-light business models favoring operational leasing with maintenance bundling.
Contract volumes concentrate with Logistics Companies; Rental Operators show the steepest expansion trajectory as tourist corridor hydrogen infrastructure densifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum group metal deposits in South Africa and Russia anchor catalyst supply chains for proton exchange membrane stacks, while hydrogen production clusters in Japan, Germany, and South Korea shape regional deployment trajectories for fuel cell two-wheeler manufacturing.
Japan
Tokyo and Osaka metropolitan delivery networks drive fleet-scale procurement through performance-based hydrogen supply contracts. METI hydrogen society subsidies directly reduce capital expenditure barriers for municipal operators. Nagoya's automotive engineering corridor concentrates stack assembly and membrane electrode fabrication expertise.
Germany
Ruhr Valley logistics operators prioritize refueling speed under EU Green Deal fleet electrification timelines. The F-Gas Regulation accelerates water-cooled thermal management adoption by restricting synthetic refrigerants in competing battery systems. Hamburg's port-adjacent hydrogen clusters enable guaranteed fuel availability clauses for commercial contracts.
Netherlands
Amsterdam municipal zero-emission mandates compress procurement cycles toward certified hydrogen scooter platforms. National infrastructure funding channels capital toward Randstad hydrogen refueling density targets. Eindhoven's high-tech manufacturing ecosystem supports precision membrane electrode assembly production.
South Korea
Seoul metropolitan delivery fleets scale hydrogen scooter deployment under tightening urban emission restrictions. National hydrogen economy roadmaps subsidize fuel cell vehicle categories including two-wheeler segments. Busan-Ulsan port corridors concentrate high-pressure storage cylinder manufacturing and qualified valve supplier networks.
United States
California's Advanced Clean Trucks regulation extends incentive structures to light commercial mobility segments including delivery fleets. EPA emission standards and state-level ZEV mandates create regulatory pressure for zero-emission alternatives. Los Angeles basin logistics operators trial fuel cell platforms where battery swapping infrastructure remains underdeveloped.
Fuel Cell Bikes Market Competitive Landscape
Strategic partnerships dominate the current landscape as stack manufacturers seek guaranteed offtake agreements with fleet operators and hydrogen suppliers. The vendor base stratifies across three tiers: diversified automotive conglomerates with captive fuel cell expertise, specialized two-wheeler electrification firms, and component-focused membrane electrode assembly suppliers. Two competitive vectors define positioning: backward integration into platinum catalyst supply chains, and geographic expansion into port-adjacent logistics corridors with established hydrogen station density.
Within the diversified automotive tier, Toyota Motor Corporation and Hyundai Motor Company exemplify scale-driven platform development anchored by proprietary proton exchange membrane expertise. Honda Motor occupies a position bridging motorcycle manufacturing heritage with fuel cell powertrain adaptation. Among specialized mobility providers, Segway represents integrated hybrid architecture approaches, while Pragma Industries sits within the European municipal fleet specialization segment. Component-focused suppliers concentrate membrane electrode fabrication precision for sub-100-micron consistency requirements.
| Leading Market Players |
|---|
| Honda Motor |
| Hyundai Motor Company |
| Toyota Motor Corporation |
| Segway |
| BMW |
| Xiaomi |
| Pragma Industries |
| Azure Bikes |
| Kawasaki Heavy Industries |
| Others |
Supply & Pricing Matrix
Membrane electrode assembly specialists concentrated in Nagoya and Eindhoven command premium compensation that widens pricing-tier spreads between premium proton exchange membrane stacks and cost-sensitive alkaline alternatives. Labor-cost differentials in stack fabrication directly stratify end-product positioning across municipal fleet and individual buyer segments.
Pricing Analysis
Warranty bundling separates premium-tier proton exchange membrane platforms with extended stack guarantees from economy configurations with limited coverage. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service inclusion. Pricing pressure stems from platinum group metal cost volatility compressing stack margin structures. Municipal fleet operators show lowest price sensitivity due to performance-based contracting models, while individual consumers remain most responsive to upfront capital expenditure.
Supply Chain Analysis
ISO 14687 qualification requirements gate entry for hydrogen storage cylinder suppliers, concentrating qualified vendors in Japan, South Korea, and Germany. Raw material dependencies rest on South African platinum deposits, Japanese perfluorinated membrane substrates, and South Korean high-pressure valve components. Single-source vulnerability in East Asian valve manufacturing exposes European assemblers to supply disruption. Distribution runs through port-adjacent logistics clusters where hydrogen station density validates commercial fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around stack manufacturers with captive membrane electrode assembly capabilities as platinum cost volatility forces pure-play assemblers toward acquisition or exit.
For Market Incumbents: Deploy backward integration into catalyst supply chains to buffer palladium and iridium price swings eroding stack margins. Secure long-term offtake agreements with Amsterdam and Seoul municipal fleets to lock in volume visibility against emerging alkaline competitors. METI subsidy dependency in Japanese demand clusters requires diversified geographic revenue exposure.
For New Entrants and Emerging Players: The price-point gap between premium proton exchange membrane and economy alkaline configurations opens white-space opportunity in Indian metropolitan logistics corridors. Battery-fuel cell hybrid architectures targeting Bangalore and Mumbai fleet trials bypass hydrogen infrastructure density requirements. Partner with existing port-adjacent hydrogen suppliers for guaranteed fuel availability clauses rather than building parallel distribution.
For Investors and Strategic Acquirers: Re-rating potential sits with membrane electrode assembly specialists given EU F-Gas Regulation acceleration of water-cooled thermal management adoption. Five-to-ten-year viability favors component suppliers with sub-100-micron thickness consistency and established warranty reserve structures. Monitor hydrogen production cost curves as the inflection signal for total cost of ownership parity against battery electric alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Supply | Captive platinum sourcing buffers margin compression from South African supply volatility. |
| Performance-Based Fleet Contracting | Per-kilometer pricing with Tokyo logistics operators converts capital expenditure to operational spend. |
| EU F-Gas Compliance Certification | Water-cooled thermal management qualification unlocks Amsterdam municipal procurement specifications. |
| Hybrid Architecture Development | Converged lithium-ion buffer systems extend range without 700-bar cylindrical tank volume penalties. |
| Port-Adjacent Hydrogen Cluster Partnership | Busan-Ulsan corridor alliances secure high-pressure storage cylinder priority allocation. |
Research Methodology
Trade databases, METI hydrogen roadmap publications, and EU Green Deal implementation trackers formed the secondary backbone for demand and infrastructure mapping. Primary interviews with fleet procurement managers at Amsterdam and Seoul municipal authorities, membrane electrode assembly fabrication engineers, and hydrogen station network operators validated deployment timelines and cost structures. Bottom-up unit shipment estimates triangulated against top-down hydrogen consumption projections across the analysis window.
Bottom-up modeling segmented volume and value by product type, technology platform, application duty cycle, and end-user procurement archetype across the projection horizon. Proton exchange membrane stack pricing incorporated platinum loading requirements and thermal management complexity tiers. CAGRs derived from fleet electrification mandate enforcement schedules and refueling station density thresholds in named metropolitan corridors.
Inputs from Japanese port-city logistics operators and European municipal procurement offices were available through the study window; gaps in Indian hydrogen infrastructure development timelines introduce uncertainty bands for emerging market penetration assumptions. Forecasts reflect documented assumptions regarding METI subsidy continuity and ISO 14687 enforcement stringency. A model refresh is warranted upon material change in platinum group metal price trajectories or EU F-Gas Regulation implementation acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Carbon Fiber Bicycle Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
Motorcycles Fuel Tank Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Motorsports Motorcycle Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
Three Wheeled Motorcycle Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Aluminum Alloy Bicycle Crankset Market
Bikes and Motorcycles
Bicycle Mechanical Disc Brake Market
Bikes and Motorcycles
China E-Bike Market
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Motorbike Carburetor Market