
 Wheel Studs Market | 2026-2036
Wheel Studs Market Size, Share, and Industry Trends Forecast 2026-2036
Wheel Studs Market Analytics
The wheel studs category is recalibrating around a widening gap between premium coated alloys and commodity uncoated steel. KAMAX Holding leverages its European forging footprint to dominate high-tensile M14 supply for heavy equipment. Elgin Fastener Group anchors North American aftermarket distribution through captive heat-treatment capacity. Superbolt competes on multi-jackbolt tensioning systems that reduce installation torque variance in military applications.
Wheel studs are threaded fasteners that secure wheels to hub assemblies, typically manufactured through cold forging or thread rolling from medium-carbon or alloy steel with specified tensile strengths exceeding 120,000 psi to withstand cyclic loading. Their primary purpose is maintaining clamp force under vibration, thermal cycling, and cornering stress across commercial and passenger vehicles. Steel product type occupies the volume base due to cost efficiency in M10 and M12 passenger-car specifications, while titanium commands concentrated margin pools in aerospace-adjacent military end use. Automotive manufacturers represent the structural demand anchor, though aftermarket providers show faster growth as fleet operators extend vehicle replacement cycles.
NHTSA wheel retention standards and EPA corrosion regulations shape material and coating requirements for US market access. ISO 898-1 mechanical property classifications and SAE J2530 testing protocols define tensile and fatigue benchmarks that suppliers must certify. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied-carbon tracking reshape sourcing decisions for forged steel feedstock.
Market Dynamics
Commercial vehicle fleets are accelerating orders for corrosion-resistant coated studs as EPA axle-weight scrutiny tightens and thermal cycling durability becomes non-negotiable for extended replacement cycles. This regulatory pressure is compressing the viable supplier base toward certified heat-treatment capacity holders.
Growth Catalysts
- EPA Emissions Enforcement:Axle-weight verification rules are forcing fleet operators toward premium coated alloys that withstand repeated torque cycling without thread galling.
- Cold Forging Automation:Thread-rolling precision improvements are reducing material waste in M14 heavy-equipment specifications while maintaining SAE J2530 fatigue benchmarks.
- Great Lakes Supplier Clustering:Tier-1 stamping plant proximity around Detroit and Cleveland is shortening logistics lead times for just-in-sequence automotive assembly.
Market Restraints
- Alloy Steel Feedstock Volatility:Medium-carbon and chromium-molybdenum bar stock prices fluctuate with scrap metal arbitrage, compressing margin on commodity M10 passenger-car studs.
- European Forging Concentration:High-tensile M14 supply for heavy equipment depends on a narrow base of continental European hot-forge capacity with limited geographic redundancy.
- Uncoated Steel Substitution Ceiling:Budget fleet operators in price-sensitive segments resist coating premiums despite NHTSA corrosion durability expectations.
Strategic Opportunities
- EU Green Deal Embodied-Carbon Tracking:Forged steel feedstock sourcing transparency is becoming a procurement differentiator for OEMs with Scope 3 reduction commitments.
- Multi-Jackbolt Tensioning Systems:Military and aerospace-adjacent applications are adopting distributed clamp-force technologies that reduce installation torque variance and field failure rates.
- Aftermarket E-Commerce Penetration:Independent repair shops are bypassing traditional distribution tiers through direct-platform procurement of certified replacement studs.
Industry Challenges
- ISO 898-1 Certification Timelines:Mechanical property classification testing creates 12-18 month validation gaps for new alloy formulations entering commercial qualification.
- Heat-Treatment Capacity Bottlenecks:Captive furnace availability constrains aftermarket suppliers attempting to match OEM-grade tensile consistency at volume scale.
- Legacy Hub Interface Compatibility:Emerging coated stud geometries require verification against decades of uncoated steel mating surface specifications in existing vehicle parc.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheel Studs Market |
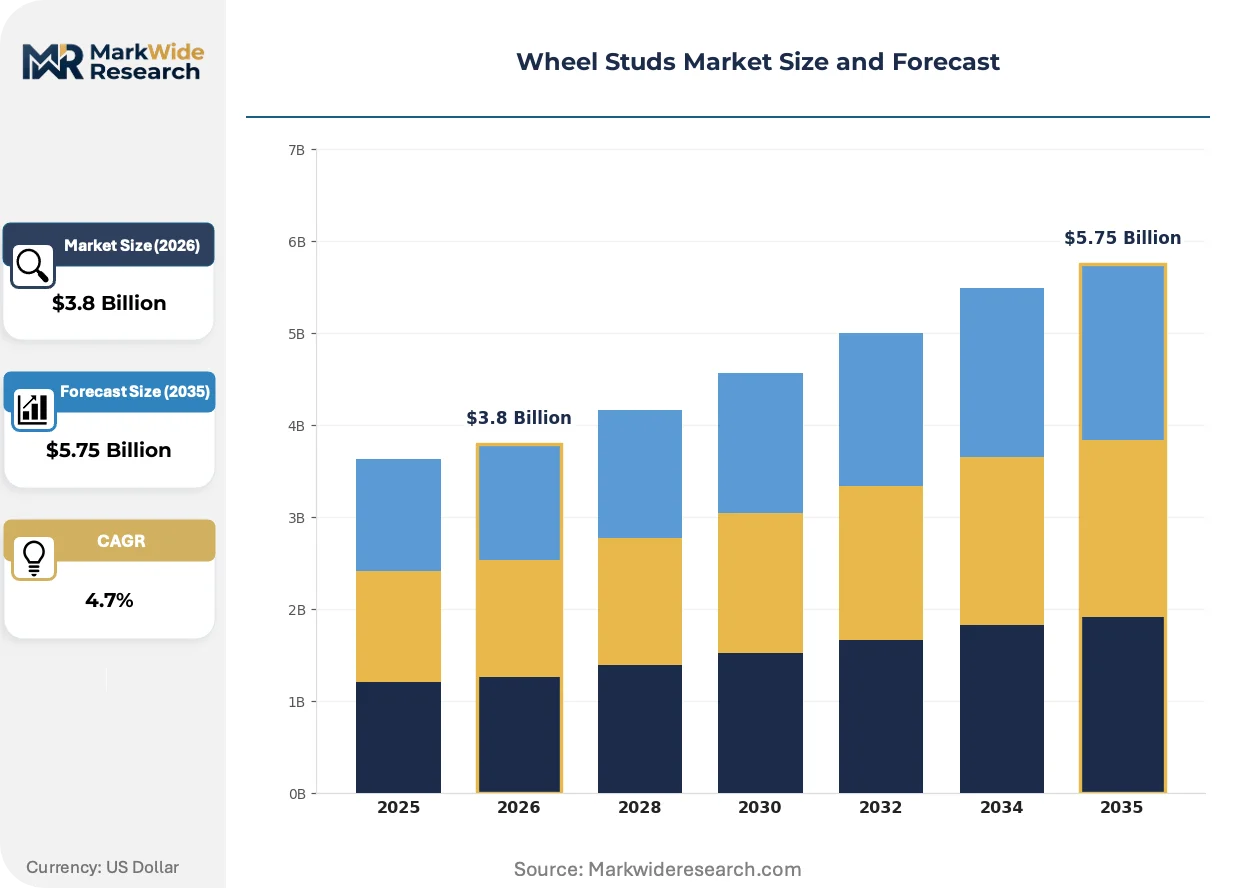
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Carbon Fiber, Titanium End User: Automotive Manufacturers, Aftermarket Providers, Military Vehicles, Heavy Equipment Size: M8, M10, M12, M14 Coating Type: Galvanized, Zinc Plated, Black Oxide, Others |
| Companies Covered | KAMAX Holding, Elgin Fastener Group, Superbolt, Valley Forge & Bolt Manufacturing, Slidematic Industries, Summit Tool, McGee, Beachlawn, B & D Thread Rolling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheel Studs Market Evolving Landscape
Material science advances and regulatory durability mandates are converging to redefine acceptable performance thresholds across passenger and commercial vehicle segments. Suppliers are racing to certify next-generation surface treatments before procurement specifications harden.
Plasma-electrolytic oxidation coatings are expanding into heavy-duty commercial fleet specifications previously dominated by zinc-nickel electroplating. Fleet operators running EPA-compliant weight configurations are specifying these ceramic-derived layers for salt-spray resistance exceeding 1,000 hours. The technology is expanding into price-sensitive M12 segments as coating line throughput improves and unit economics compress toward electroplated baselines.
REACH Annex XVII restrictions on hexavalent chromium conversion coatings are forcing European suppliers toward trivalent and chromium-free passivation chemistries. Surface treatment houses in Germany and Poland are retooling lines to meet ELV directive durability requirements without legacy hexavalent processes. North American exporters to EU assembly plants must mirror these specifications or face technical barrier exclusion from OEM approved vendor lists.
Consolidated fleet procurement departments are unbundling stud replacement from full wheel-end service contracts and negotiating direct volume agreements with certified fastener distributors. Large trucking operators with centralized maintenance operations are bypassing traditional jobber networks for ISO-certified supply with batch traceability. This concentration is most visible across US Class 8 fleet operators with in-house wheel maintenance capabilities and electronic parts catalog integration.
Wheel Studs Market Segmentation
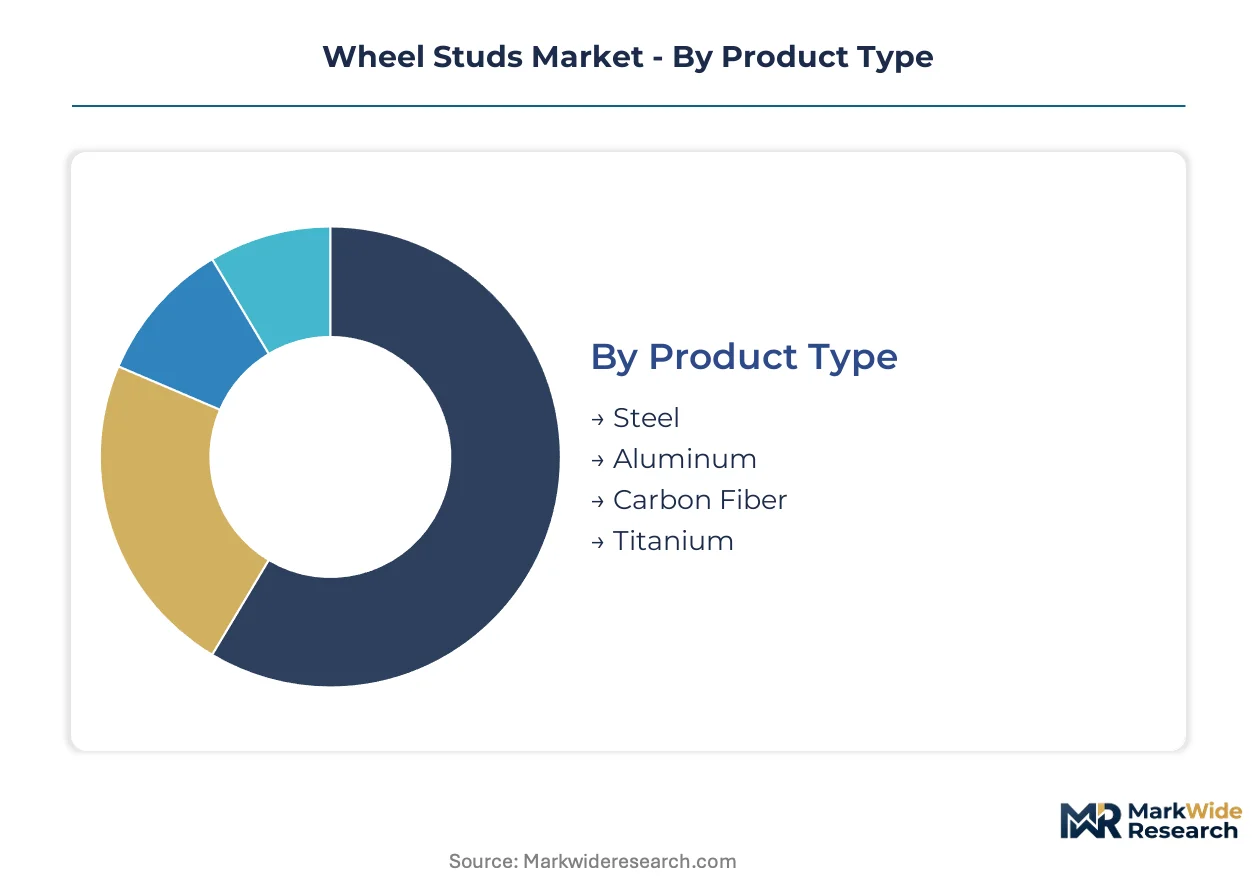
Wheel studs serve both as standalone replacement components and as embedded subsystems within integrated wheel-end assemblies. Understanding where each segment sits on this integration spectrum reveals procurement leverage points and margin concentration across OEM, fleet, and military channels.
Product Type:
Material selection determines whether studs function as discrete service parts or as permanently integrated hub components requiring full assembly replacement.
- Steel:Cold-forged medium-carbon grades dominate M10 and M12 passenger-car specifications where cost efficiency outweighs corrosion concerns. Great Lakes stamping plants around Detroit and Cleveland source these in just-in-sequence volumes for light-vehicle assembly.
- Titanium:Aerospace-grade alloys command concentrated military and aerospace-adjacent applications where strength-to-weight ratios justify unit cost premiums. NHTSA wheel retention standards still apply, but procurement flows through defense contractor qualification channels rather than automotive tier-1 networks.
- Aluminum:Lightweight variants serve racing and specialty vehicle niches requiring reduced unsprung mass.
- Carbon Fiber:Experimental grades appear in prototype electric vehicle programs targeting maximum weight reduction.
Volume placements concentrate in Steel; the faster expansion belongs to Titanium.
End User:
Customer type dictates certification burden, with embedded-system buyers demanding full assembly traceability versus standalone part purchasers prioritizing availability.
- Automotive Manufacturers:Tier-1 suppliers to Detroit and Cleveland assembly plants specify SAE J2530-certified studs with captive heat-treatment batch records. EPA axle-weight verification rules are forcing specification upgrades to corrosion-resistant coated variants even in economy vehicle segments.
- Aftermarket Providers:Independent distributors and direct-platform sellers serve fleet operators extending replacement cycles. E-commerce penetration is accelerating as Class 8 fleet maintenance departments bypass traditional jobber networks for ISO-certified supply with electronic catalog integration.
- Military Vehicles:Multi-jackbolt tensioning systems reduce installation torque variance in armored and tactical applications.
- Heavy Equipment:M14 high-tensile specifications for construction and mining machinery depend on European forging capacity with limited geographic redundancy.
Procurement scale favors Automotive Manufacturers; margin expansion is steepest in Aftermarket Providers.
Size:
Dimensional specifications map directly to vehicle weight class and torque loading requirements, with larger diameters commanding premium alloy grades and specialized heat treatment.
- M14:Heavy-equipment and commercial fleet specifications require tensile strengths exceeding 120,000 psi to withstand cyclic loading under EPA-compliant axle-weight configurations. KAMAX Holding's European forging footprint dominates supply, creating geographic concentration risk.
- M12:Light-truck and van applications balance clamp force requirements with cost constraints. Plasma-electrolytic oxidation coatings are penetrating this segment as throughput improvements compress unit economics toward electroplated baselines.
- M10:Passenger-car volume base where alloy steel feedstock volatility compresses margins.
- M8:Compact vehicle and motorcycle applications with minimal coating penetration.
Unit volume concentrates in M12; value-per-unit expansion is most rapid in M14.
Coating Type:
Surface treatment selection separates replaceable service parts from embedded hub assemblies, with premium coatings extending service intervals and enabling unbundled procurement.
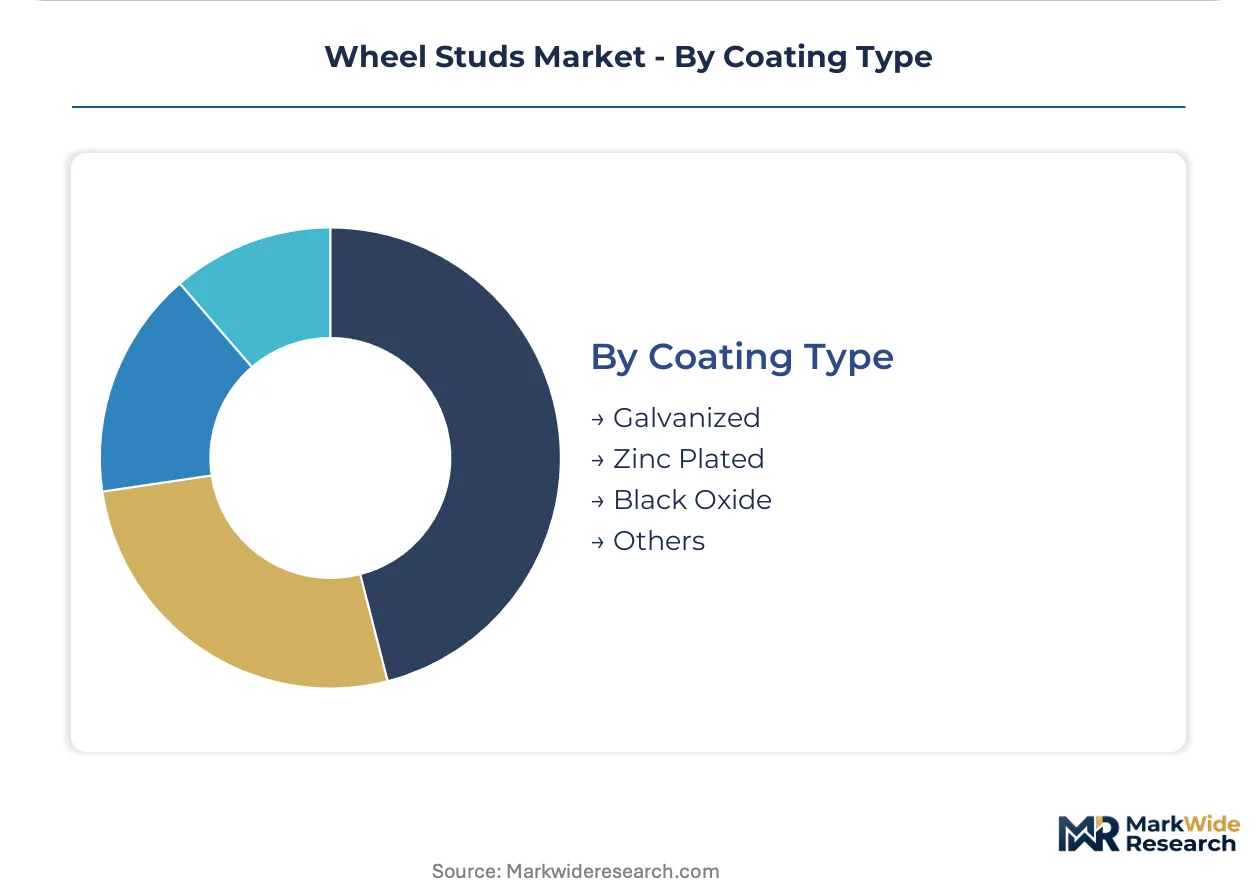
- Zinc Plated:Electrodeposited zinc-nickel layers dominate commercial fleet specifications requiring 1,000+ hour salt-spray resistance under EPA corrosion durability expectations. REACH Annex XVII hexavalent chromium restrictions are forcing European suppliers toward trivalent passivation chemistries.
- Galvanized:Hot-dip processes serve price-sensitive budget fleet segments resisting coating premiums despite NHTSA durability standards.
- Black Oxide:Cosmetic and light-duty applications with minimal corrosion protection requirements.
- Others:Plasma-electrolytic oxidation and ceramic-derived layers emerging in heavy-duty specifications.
Procurement volume clusters in Zinc Plated; specification upgrading is most pronounced in Others.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes automotive corridor stretching from Detroit through Cleveland anchors North American wheel stud procurement, with tier-1 suppliers clustering around stamping plants to serve just-in-sequence assembly schedules for light and commercial vehicles.
United States
EPA axle-weight verification rules are accelerating fleet operator procurement of corrosion-resistant coated studs for thermal cycling durability. NHTSA wheel retention standards shape material specifications across automotive and aftermarket channels. The Detroit-Cleveland corridor concentrates captive heat-treatment capacity serving OEM assembly plants with SAE J2530-certified supply.
Germany
Commercial vehicle manufacturers specify high-tensile M14 studs from continental European forging networks for construction and mining machinery. REACH Annex XVII hexavalent chromium restrictions are forcing surface treatment houses toward trivalent passivation chemistries. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg retool coating lines to maintain ELV directive compliance for OEM approved vendor lists.
China
Domestic heavy-equipment production is absorbing M14 specifications from local forging capacity as infrastructure investment sustains demand. Dual carbon goals are reshaping sourcing decisions for medium-carbon steel feedstock across automotive supply chains. Yangtze River Delta manufacturing zones are developing coated alloy capabilities to meet export durability requirements for European and North American assembly plants.
Japan
Precision thread-rolling automation serves domestic automotive manufacturers with fatigue-benchmarked supply for passenger and light-truck segments. METI industrial standards influence regional specifications for clamp-force consistency under vibration loading. Kansai and Chubu industrial corridors maintain specialized heat-treatment capacity for OEM-tier certification requirements.
India
Expanding commercial vehicle production is driving specification upgrades from commodity uncoated steel toward corrosion-resistant variants for extended replacement cycles. BIS mechanical property classifications provide domestic certification frameworks parallel to ISO 898-1 benchmarks. Maharashtra and Gujarat automotive clusters are developing captive coating capacity to reduce import dependence for premium fleet specifications.
Wheel Studs Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier base where captive heat-treatment capacity separates OEM-grade certification from aftermarket commodity supply. The market structure concentrates around three strategic archetypes: European forging specialists with high-tensile heavy-equipment dominance, North American distributors with captive thermal processing networks, and tensioning-system innovators serving military-aerospace applications. Competitive positioning hardens through geographic proximity to automotive assembly corridors and certification velocity for emerging coating chemistries.
Among the named players, KAMAX Holding exemplifies the European forging archetype with continental capacity for M14 specifications, while Elgin Fastener Group represents North American aftermarket distribution anchored by captive heat-treatment infrastructure. Superbolt occupies a specialized position within multi-jackbolt tensioning systems for reduced installation torque variance. These three companies illustrate how supplier differentiation maps to end-use certification requirements rather than scale alone.
| Leading Market Players |
|---|
| KAMAX Holding |
| Elgin Fastener Group |
| Superbolt |
| Valley Forge & Bolt Manufacturing |
| Slidematic Industries |
| Summit Tool |
| McGee |
| Beachlawn |
| B & D Thread Rolling |
| Others |
Value Network & Pricing Analysis
Tier-1 automotive OEM procurement departments concentrated around Detroit and Cleveland anchor pricing power through captive heat-treatment requirements and SAE J2530 certification mandates. Their volume concentration forces suppliers into long-term contract structures that compress margin on commodity M10 specifications while preserving premium tiers for corrosion-resistant coated variants.
Pricing Analysis
Value-based pricing anchored to thermal cycling durability and salt-spray resistance hours separates premium coated alloys from commodity uncoated steel. Certification tier—ISO 898-1 mechanical property classification versus uncertified aftermarket supply—drives price differentiation alongside captive heat-treatment batch traceability. Cost compression in M10 passenger-car segments is intensifying because alloy steel feedstock volatility passes through scrap metal arbitrage. Budget fleet operators in price-sensitive segments exhibit highest price sensitivity, while military and aerospace-adjacent buyers prioritize torque variance reduction over unit cost.
Supply Chain Analysis
Medium-carbon and chromium-molybdenum bar stock supply rests on German, Chinese, and Japanese specialty steel producers with limited geographic redundancy for high-tensile grades. Cold-forging equipment, thread-rolling precision tooling, and captive heat-treatment furnace capacity constitute critical input dependencies. Single-source vulnerability concentrates in European M14 forging capacity for heavy-equipment specifications. Distribution runs through tier-1 supplier clusters around automotive assembly corridors with just-in-sequence delivery requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wheel studs market sits in a coating-technology transition phase as plasma-electrolytic oxidation displaces zinc-nickel electroplating for heavy-duty commercial fleet specifications. Suppliers must recalibrate capital allocation toward certified surface treatment capacity before procurement specifications harden.
For Market Incumbents: Deepen captive heat-treatment investments in the Great Lakes corridor to defend OEM-tier certification against European forging specialists expanding North American footprint. Prioritize trivalent passivation line retooling ahead of REACH Annex XVII enforcement tightening. Certification velocity for emerging coating chemistries remains the critical defensive lever. For New Entrants and Emerging Players: Independent Class 8 fleet maintenance departments with electronic parts catalog integration represent an underserved buyer archetype bypassing traditional jobber networks. Direct-platform procurement of ISO-certified supply with batch traceability offers the most penetrable entry vector. Target aftermarket e-commerce penetration with certified M12 coated variants for fleet operators extending replacement cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor surface treatment houses with ELV directive compliance capabilities in Germany and Poland. Long-term viability across the analysis window hinges on coating line throughput improvements compressing plasma-electrolytic oxidation unit economics toward electroplated baselines. Watch EPA axle-weight verification rule expansion as the inflection signal for premium coated alloy demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Capacity Expansion | Plasma-electrolytic oxidation throughput improvements enable M12 segment penetration against zinc-nickel baselines. |
| Backward Integration into Heat Treatment | Captive furnace capacity separates OEM-grade SAE J2530 certification from aftermarket commodity supply tiers. |
| Long-term Fleet Supply Agreement | Consolidated Class 8 procurement departments negotiate direct volume contracts bypassing traditional distribution tiers. |
| Joint Venture with European Forging Specialist | Geographic redundancy for high-tensile M14 supply reduces concentration risk in heavy-equipment specifications. |
| Green Manufacturing Transition | Trivalent passivation and chromium-free chemistries align with EU Green Deal embodied-carbon tracking requirements. |
Research Methodology
SEC 10-K filings, automotive production databases, and customs trade records formed the secondary backbone for supplier capacity and procurement pattern analysis. Primary interviews with tier-1 supplier procurement managers, aftermarket distributor operations heads, fleet maintenance directors, and surface treatment house technical directors combined with secondary validation. Bottom-up and top-down triangulation reconciled unit volume estimates with value aggregation across product type, end user, size, and coating type segments.
Bottom-up modeling built from vehicle production forecasts and content-per-vehicle assumptions across passenger, commercial, and heavy-equipment classes. Top-down validation cross-checked against aggregate fastener market sizing and regional automotive output projections. Segmentation dimensions included material grade, dimensional specification, surface treatment chemistry, and end-use certification tier. CAGRs derived from regression analysis of historical replacement cycle patterns and regulatory durability mandate adoption curves. Industry-specific inputs incorporated EPA axle-weight verification rollout timelines and REACH Annex XVII enforcement phase-ins.
Revisions become necessary when alloy steel feedstock volatility exceeds historical bands, European forging capacity experiences disruption, or NHTSA corrosion durability standards tighten beyond current NHTSA wheel retention baselines. Forecasts reflect assumptions about coating technology cost curves and fleet operator procurement centralization trends. A small set of named triggers—EPA rule expansion, REACH enforcement acceleration, and plasma-electrolytic oxidation line commissioning rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
Front Forks Market
Vehicle Components
Car Modification Market
Vehicle Components
Global Bearings Market
Vehicle Components
Air Suspension Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Engine Air Filter Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Car Diffuser Market
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
Transmission Components Market
Vehicle Components
Automotive Aftermarket Shock Absorbers Market