
 Algeria Oil and Gas Market | 2026-2036
Algeria Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Algeria Oil and Gas Market Outlook
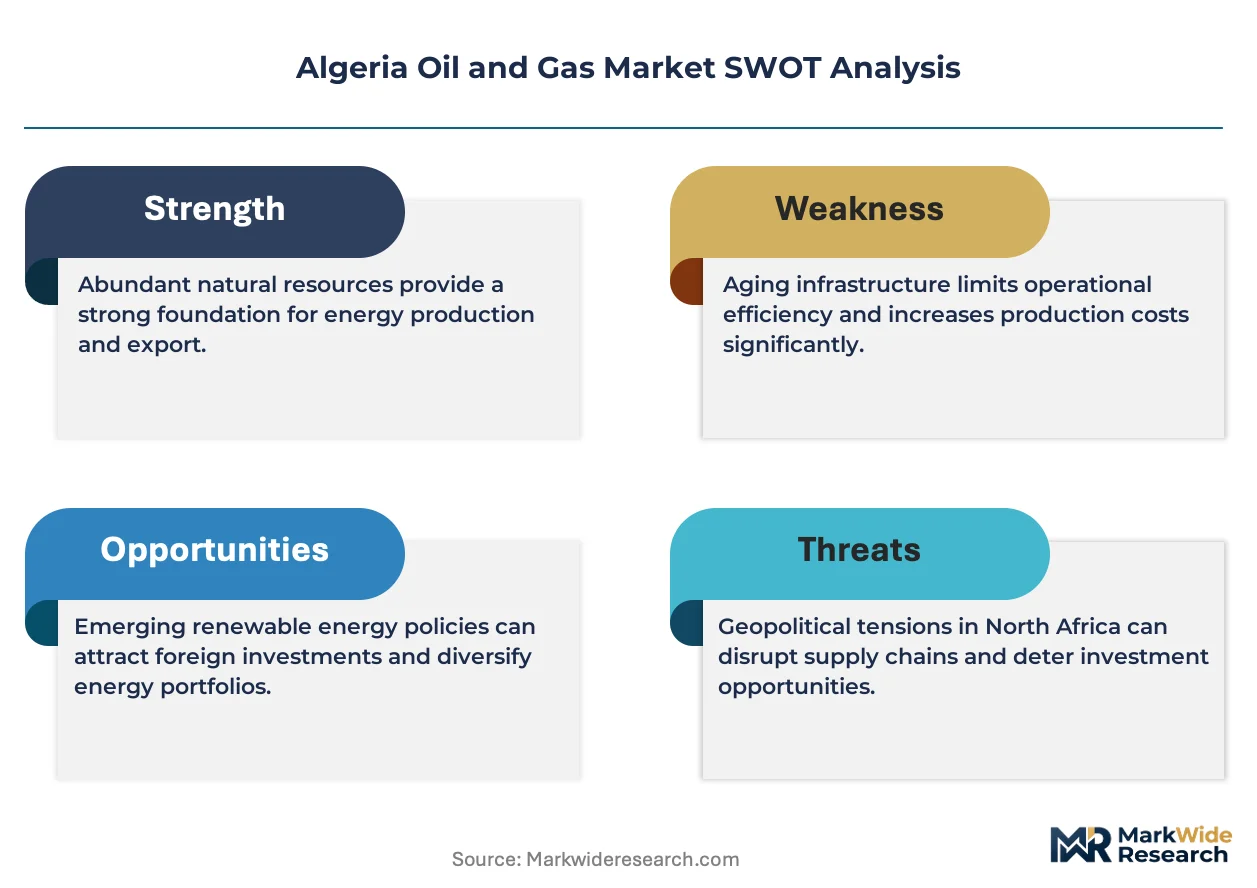
API-grade specification upgrades across Algerian crude streams is unwinding legacy blending practices and opening premium export slots. Sonatrach S.p.A. leverages its integrated pipeline network to sustain term-contract deliveries into European refineries. Eni S.p.A. anchors its position through deepwater exploration partnerships in the Berkine Basin. BP Plc differentiates via digital subsea monitoring systems deployed at its In Salah gas compression facilities.
Algeria oil and gas encompasses crude petroleum, associated and non-associated natural gas, liquefied natural gas, and refined products extracted from onshore and offshore reservoirs using conventional and enhanced recovery techniques, with specifications ranging from 44° API Saharan Blend to heavier 30° API grades from mature fields. The sector serves power generation feedstock, petrochemical cracking stock, industrial process heat, and residential heating across Mediterranean and European offtake markets. Natural gas and LNG dominate structural value capture given pipeline interconnectivity to Italy and Spain plus expanding liquefaction capacity at Skikda and Arzew. Upstream technology segments command capital allocation priority as SONATRACH pursues secondary recovery from maturing sandstone reservoirs and exploratory drilling in deep offshore blocks. Digital solutions are gaining fastest traction across midstream pipeline integrity management and downstream refinery optimization.
Algeria's hydrocarbon sector operates under the 2019 hydrocarbon law administered by the national oil regulator, with fiscal terms revised to attract international participation through production-sharing contracts and reduced state take. Environmental compliance with MEE atmospheric emission standards and offshore discharge protocols shapes drilling permit timelines and facility upgrade obligations. Stakeholders must monitor licensing round outcomes and partnership negotiation dynamics to assess reserve replacement trajectories and infrastructure monetization pathways.
Market Dynamics
SONATRACH's enhanced oil recovery partnerships and the 2019 hydrocarbon law's revised fiscal terms are restructuring field development economics across Algerian basins. International operators now access production-sharing contracts with reduced state take, accelerating capital deployment into mature sandstone reservoirs and deep offshore blocks.
Growth Catalysts
- Petrochemical feedstock demand:Rising consumption from Algeria's domestic petrochemical sector is strengthening offtake volumes for associated gas and condensate streams. This demand concentration anchors long-term production planning.
- 2019 Hydrocarbon Law:Revised fiscal terms under this framework attract international participation through production-sharing contracts and reduced state take, reshaping partnership negotiation dynamics.
- Enhanced recovery techniques:Secondary recovery deployment in maturing Hassi Messaoud fields sustains output from legacy sandstone reservoirs where natural pressure has declined.
Market Restraints
- Mature reservoir geology:Declining reservoir pressure in Hassi Messaoud and other legacy fields necessitates continuous capital injection for artificial lift and waterflooding operations.
- Offshore technical barriers:Deep Mediterranean drilling campaigns face complex subsalt geology and high-pressure formations that extend exploration timelines and elevate technical risk.
- Domestic supply obligation:Regulatory requirements to prioritize local market supply constrain export volume flexibility and term-contract optimization.
Strategic Opportunities
- Berkine Basin deepwater:Unpenetrated deep offshore blocks offer exploratory upside where international partnerships can deploy advanced subsea production systems.
- Liquefaction capacity expansion:Skikda and Arzew facility upgrades enable premium LNG slot capture into Mediterranean and European markets.
- Digital infrastructure convergence:Integration of pipeline integrity management systems with refinery optimization platforms creates operational efficiency gains across SONATRACH's integrated network.
Industry Challenges
- Specialized subsea engineering talent:Scarcity of deepwater drilling and completion expertise constrains campaign acceleration in offshore Mediterranean blocks.
- Legacy system integration:Digital monitoring deployment at mature facilities requires retrofit compatibility with existing SCADA infrastructure and control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algeria Oil and Gas Market |
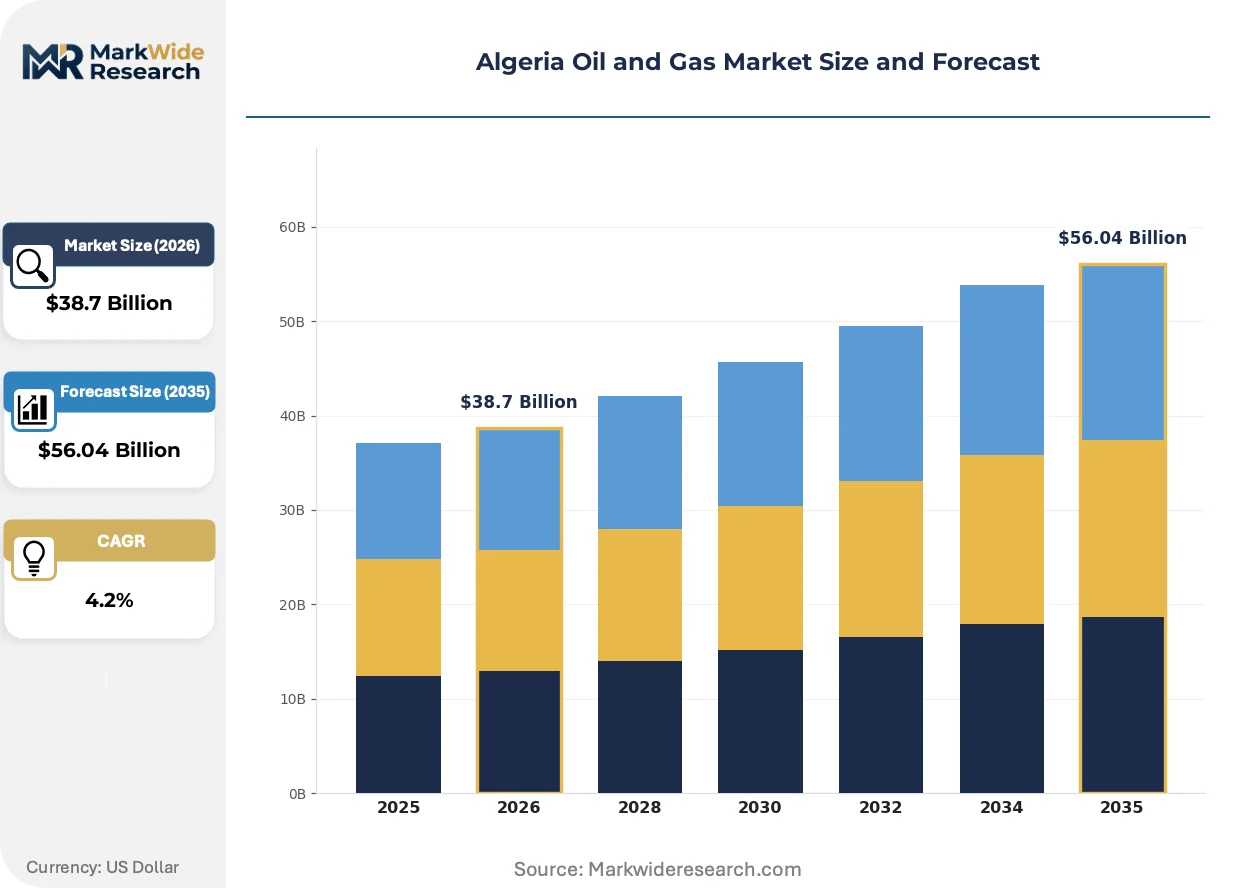
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, LNG, Refined Products Services Offered: Exploration, Drilling, Production, Transportation End User: Power Generation, Petrochemicals, Industrial, Residential Technology: Upstream, Midstream, Downstream, Digital Solutions |
| Companies Covered | Sonatrach S.p.A., Eni S.p.A., BP Plc, TotalEnergies, Equinor ASA, China National Petroleum Corporation, ExxonMobil, Chevron, Occidental, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algeria Oil and Gas Market Strategic Shifts
Digital subsea monitoring and pipeline integrity platforms are compressing operational response times across Algerian production assets. Technology deployment now centers on predictive maintenance and real-time reservoir management.
Advanced subsea monitoring systems is decomposing conventional periodic inspection schedules at gas compression facilities. Offshore operators deploy continuous fiber-optic sensing and autonomous underwater vehicles to track pipeline corrosion and facility integrity. This technology shift is decomposing legacy manned intervention models and reducing unplanned shutdown frequency.
Algeria's 2019 hydrocarbon law and MEE atmospheric emission standards are tightening environmental compliance timelines for drilling permits. Operators must demonstrate emission control technology deployment and offshore discharge protocol adherence before license approval. Upstream project development schedules are compressing to accommodate these layered regulatory checkpoints.
Term-contract unbundling is fragmenting traditional offtake relationships with European refineries. Buyers now negotiate shorter-duration contracts with flexible volume clauses and API-grade specification premiums. Italian and Spanish refineries are driving this preference shift as they optimize crude slate flexibility against carbon border adjustment exposure.
Algeria Oil and Gas Market Segmentation
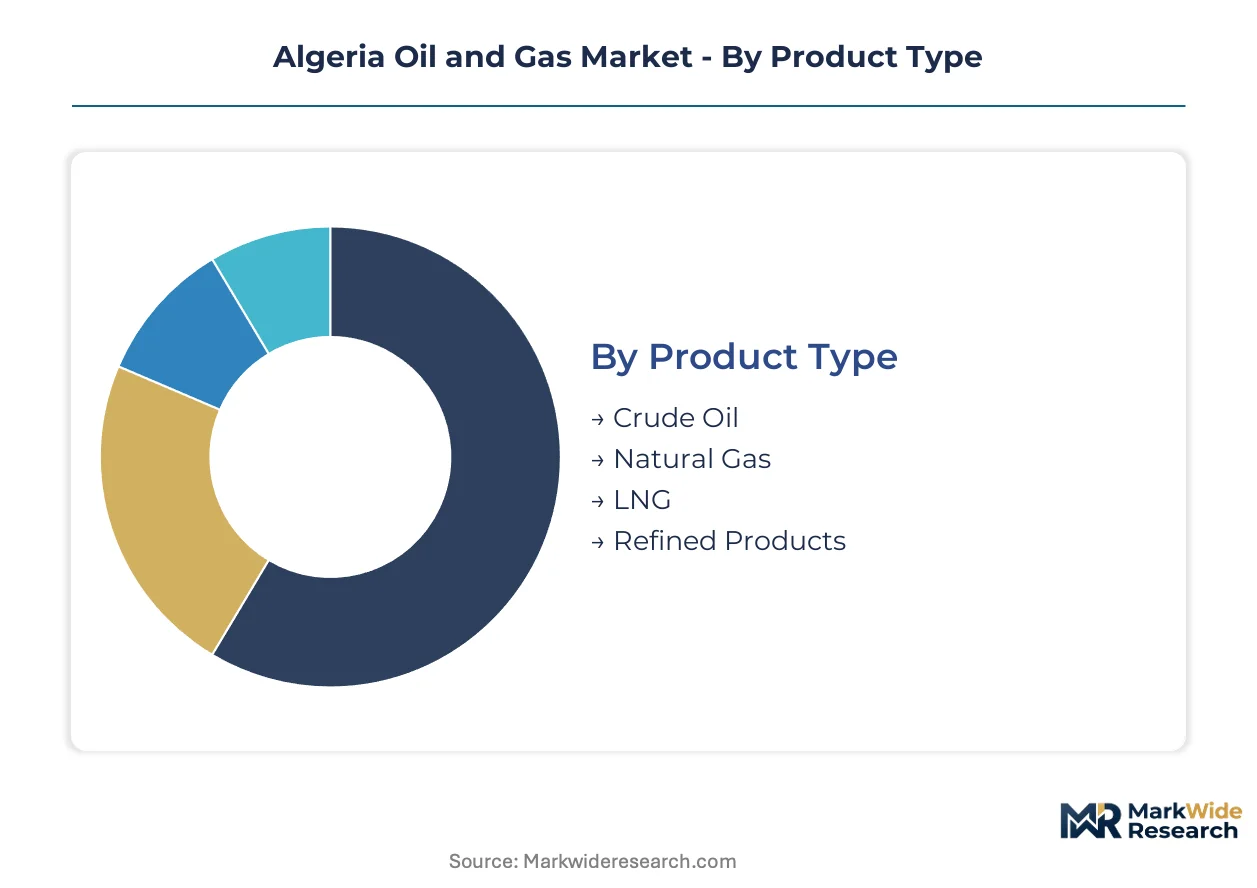
Segmentation in Algeria's hydrocarbon sector reveals how value migrates across the production chain. Product mix and technology deployment determine capital allocation priorities for SONATRACH and its international partners.
Product Type:
Margin pools concentrate in gas-value chain segments where pipeline interconnectivity and liquefaction capacity create structural rent extraction.
- Natural Gas:Non-associated and associated gas streams from Hassi R'Mel and In Salah fields feed domestic power generation and pipeline exports to Italy and Spain. Pipeline tolls and long-term take-or-pay contracts anchor revenue visibility for infrastructure holders.
- LNG:Liquefaction at Skikda and Arzew terminals transforms pipeline-advantaged gas into premium Atlantic Basin and Asian cargoes. Spot market exposure and JKM-linked pricing clauses are expanding share of export revenue.
- Crude Oil:Saharan Blend exports at 44° API command European refinery premiums against heavier Atlantic Basin alternatives.
- Refined Products:Domestic refining at Arzew and Skikda supplies Algerian transport fuel demand with limited exportable surplus.
Natural Gas holds installed capacity. LNG is rotating up the share rankings.
Services Offered:
Service intensity varies sharply by field maturity, with artificial lift and workover demand climbing in Hassi Messaoud's aging sandstone reservoirs.
- Production:Secondary recovery operations including waterflooding and gas reinjection dominate capital deployment in maturing onshore fields. SONATRACH's partnership model with international operators transfers reservoir management expertise.
- Drilling:Deep offshore Mediterranean campaigns require high-specification jack-up and semi-submersible rigs for subsalt targets. Rig availability constraints are extending spud-to-spud timelines.
- Exploration:Seismic acquisition and wildcat drilling concentrate in Berkine Basin deepwater blocks under 2019 hydrocarbon law licensing rounds.
- Transportation:Pipeline integrity management and compression station maintenance sustain throughput on the Trans-Mediterranean and Maghreb-Europe gas lines.
Production commands the largest recurring spend. Drilling is expanding fastest as offshore campaigns accelerate.
End User:
Demand concentration patterns reflect Algeria's industrialization priorities and export contract obligations.
- Power Generation:State utility Sonelgaz offtake anchors domestic gas demand under regulated supply obligations. Combined-cycle capacity additions are tightening fuel specification requirements.
- Petrochemicals:Methanol and ammonia producers at Arzew and Skikda consume associated gas and condensate streams. Feedstock cost pass-through structures determine project economics.
- Industrial:Cement, steel, and fertilizer plants consume fuel oil and natural gas for process heat under interruptible supply contracts.
- Residential:LPG and subsidized natural gas distribution serves household cooking and heating demand with pricing regulated below export netback levels.
Power Generation holds contracted volume. Petrochemicals is climbing the demand rankings fastest.
Technology:
Capital allocation tilts toward digital infrastructure and secondary recovery as mature field economics tighten.
- Upstream:Enhanced oil recovery and deepwater exploration technologies command priority investment. Reservoir simulation and 4D seismic are improving recovery factors in Hassi Messaoud.
- Digital Solutions:Predictive maintenance platforms and SCADA integration are compressing downtime at compression facilities and pipeline networks.
- Midstream:Pipeline integrity management and leak detection systems protect throughput on aging export infrastructure.
- Downstream:Refinery optimization and desulfurization upgrades respond to MEE emission standards and European product specification convergence.
Upstream retains the deepest installed base. Digital Solutions is ascending the investment priority ladder fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Algeria's hydrocarbon export balance tilts toward European pipeline deliveries and Atlantic Basin LNG cargoes, with import dependency limited to specialized drilling equipment and subsea technology. Domestic production from Hassi Messaoud and Hassi R'Mel fields supplies the bulk of regional energy demand across North Africa and Mediterranean markets.
Hassi Messaoud Basin
Crude extraction from maturing sandstone reservoirs drives equipment demand for artificial lift systems and waterflooding infrastructure. The 2019 hydrocarbon law incentivizes international operators through production-sharing contracts with reduced state take. Field service clusters around the Ouargla province support secondary recovery campaigns and well workover operations.
Berkine Basin
Deep offshore exploration targets in subsalt formations attract high-specification rig deployments and subsea production system investments. Environmental permits under MEE atmospheric emission standards govern drilling timelines and facility upgrade obligations. International partnerships concentrate technical resources at coastal supply bases near Annaba for Mediterranean campaign logistics.
Hassi R'Mel Gas Complex
Non-associated gas processing feeds pipeline exports to Italy and Spain plus domestic power generation feedstock for Sonelgaz. Long-term take-or-pay contracts anchor revenue visibility for infrastructure holders across the Trans-Mediterranean and Maghreb-Europe lines. Compression station maintenance and pipeline integrity management sustain throughput on aging export corridors.
Skikda-Arzew Industrial Zone
Liquefaction capacity at Skikda and Arzew terminals transforms pipeline-advantaged gas into premium Atlantic Basin and Asian cargoes. Spot market exposure and JKM-linked pricing clauses expand export revenue diversification beyond term-contract volumes. Petrochemical crackers at Arzew consume associated gas and condensate streams for methanol and ammonia production.
Algiers Administrative Corridor
Regulatory oversight from the national hydrocarbon regulator shapes licensing round outcomes and partnership negotiation frameworks. SONATRACH headquarters coordinates integrated pipeline network operations and term-contract deliveries into European refineries. Digital infrastructure deployment for SCADA integration and predictive maintenance platforms concentrates technical talent in the capital region.
Algeria Oil and Gas Market Competitive Environment
Concentration sits with national oil companies and integrated majors holding production-sharing positions under the 2019 hydrocarbon law. State-backed operators control pipeline infrastructure and liquefaction capacity, while international partners provide technical expertise for enhanced recovery and deepwater exploration. Two strategic archetypes dominate: integrated majors with subsea technology capabilities, and national operators with infrastructure control. Partnership formation and digital technology licensing represent the primary competitive vectors for securing reserve replacement.
Within the integrated major tier, Sonatrach S.p.A. anchors domestic infrastructure control across pipelines and liquefaction terminals, while Eni S.p.A. and BP Plc occupy positions as deepwater exploration partners with subsea technology deployment capabilities. These three entities exemplify the partnership model through which international technical expertise accesses Algerian reserves under revised fiscal terms.
| Leading Market Players |
|---|
| Sonatrach S.p.A. |
| Eni S.p.A. |
| BP Plc |
| TotalEnergies |
| Equinor ASA |
| China National Petroleum Corporation |
| ExxonMobil |
| Chevron |
| Occidental |
| Others |
Value Chain & Pricing Dynamics
Enhanced oil recovery chemical substitution—polymer flooding displacing conventional waterflooding—is compressing supply geography toward European specialty chemical producers while elevating per-barrel lifting cost economics across Hassi Messaoud's mature sandstone reservoirs. This input shift simultaneously tightens SONATRACH's procurement leverage and reshapes term-contract pricing negotiations with international operators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with premium-mid-economy pricing differentiation separating API-grade specification tiers from blending flexibility clauses. Price differentiation hinges on sulfur content certification and volume scale commitments, with spot market exposure expanding fastest at Skikda and Arzew liquefaction terminals. Cost compression in standard-grade crude streams is intensifying because European refinery buyers are unbundling term contracts for shorter-duration, flexible-volume arrangements. State utilities under Sonelgaz offtake agreements demonstrate lowest price sensitivity due to regulated domestic supply obligations, while independent petrochemical producers at Arzew exhibit highest sensitivity to feedstock cost pass-through volatility.
Supply Chain Analysis
Italy and Spain anchor pipeline gas offtake infrastructure, while the United States and Norway concentrate deepwater drilling equipment and subsea production system manufacturing. Algeria's upstream operations draw from imported high-specification jack-up rigs, fiber-optic sensing equipment, and artificial lift systems, with European fabricators dominating compression station components. Single-source vulnerability concentrates in specialized subsea engineering talent pools, where Mediterranean campaign acceleration hinges on Norwegian and UK technical service providers. Distribution runs through SONATRACH's integrated pipeline network to European term-contract refineries, with LNG cargoes diverting to Atlantic Basin spot markets via Skikda and Arzew terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algeria's oil and gas sector presents a service-attach opportunity where predictive maintenance platforms and SCADA integration layers are expanding faster than conventional drilling hardware procurement. Recurring-revenue digital infrastructure contracts now outpace capital equipment sales cycles for international technology providers.
For Market Incumbents: Fortify pipeline integrity management capabilities through backward integration into fiber-optic sensing manufacturing, neutralizing Norwegian equipment supplier leverage. Expand compression station maintenance capacity at Hassi R'Mel to capture Sonelgaz utility outsourcing trends. Defensive positioning must counter emerging digital-native entrants from European industrial software clusters seeking refinery optimization contracts.
For New Entrants and Emerging Players: Subsea engineering talent scarcity in Mediterranean deepwater blocks offers white-space penetration where incumbent oilfield service majors under-serve rapid campaign scaling. Target Berkine Basin exploration support services through Annaba coastal supply base logistics partnerships. Go-to-market positioning should emphasize autonomous underwater vehicle deployment for pipeline inspection, displacing legacy manned intervention models at SONATRACH facilities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European oilfield service specialists holding subsea technology licensing positions. Long-term viability across the analysis window depends on reserve replacement trajectories in offshore blocks and liquefaction capacity utilization at Skikda. Monitor 2019 hydrocarbon law licensing round outcomes as inflection indicator for international operator capital deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Recovery Partnership | SONATRACH's waterflooding collaborations with international operators extend Hassi Messaoud field productive life. |
| Deepwater Licensing Round Participation | Berkine Basin block awards under 2019 fiscal terms attract Eni and BP subsea technology deployment. |
| Liquefaction Capacity Expansion | Skikda terminal upgrades enable JKM-linked spot cargo capture into Asian LNG demand centers. |
| Digital Infrastructure Convergence | SCADA integration across Trans-Mediterranean pipeline network compresses unplanned shutdown frequency. |
| Petrochemical Feedstock Integration | Arzew methanol producers secure associated gas streams through interruptible supply contract structures. |
Study Parameters
Cross-validation between regulatory filing analysis and operator disclosure documents anchors the qualitative findings, with primary interviews conducted across reservoir engineers at SONATRACH, procurement leads at European refineries, subsea technology specialists at integrated majors, pipeline integrity managers, and MEE environmental compliance officers. Secondary sources include Algerian hydrocarbon regulator licensing round announcements, IEA North Africa energy outlooks, SONATRACH annual activity reports, and European gas transmission system operator data. Bottom-up field-level production estimates triangulate against top-down macroeconomic demand projections for Mediterranean energy markets.
Sensitivity analysis across Brent crude price scenarios and European gas demand elasticity assumptions shapes the forecast framework. Segmentation dimensions span product type, service intensity, end-use sector, and technology deployment tier. CAGRs derive from production decline curve analysis in mature fields and exploratory drilling success rate assumptions in offshore blocks. Industry-specific inputs incorporate pipeline take-or-pay contract renegotiation timelines and liquefaction train maintenance schedules.
Underlying assumptions cover sustained 2019 hydrocarbon law fiscal stability, with deviation risk concentrated in MEE environmental permit delays and European carbon border adjustment implementation. Forecasts reflect these conditions with explicit acknowledgment that regulatory framework revisions or subsalt exploration technical setbacks could materially revise projections. Recalibration cycles align with material shifts in licensing round outcomes and international partnership negotiation dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Oilfield Casing Spools Market
Oil & Gas
Oil and Gas Pipeline Management Software Market
Oil & Gas
Italy Oil and Gas Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Desalter Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Russia Oilfield Services Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market