
 Mud Balance Market | 2026-2036
Mud Balance Market Size, Share, and Industry Trends Forecast 2026-2036
Mud Balance Market Insights
Composite sensor housings are decoupling mud balance hardware from traditional metal-dependent cost structures. Fann Instrument Company leverages its long-standing specialization in oilfield testing equipment to sustain premium positioning across North American drilling markets. Schlumberger Limited anchors its mud balance portfolio within integrated drilling fluid service contracts, while Baker Hughes Company differentiates through digital density logging compatibility that extends its addressable scope beyond standalone instruments.
A mud balance measures drilling fluid density through a beam-and-cup mechanism calibrated to API standards, typically resolving to 0.1 pounds per gallon across a 6-24 lb/gal range for wellbore pressure management. Digital mud balance units now capture the fastest upgrade cycle as operators replace mechanical beams with load-cell architectures that transmit real-time data to mud logging systems. Laboratory mud balance demand remains concentrated in service company certification labs, while field testing applications dominate volume through portable units deployed at remote well sites.
API RP 13B governs drilling fluid test procedures in US oilfield operations, while ISO 10414 provides international density measurement protocols that shape product certification requirements for cross-border equipment sales. EPA spill prevention regulations indirectly tighten mud balance calibration frequencies, as inaccurate density readings elevate blowout and uncontrolled release risks that trigger enforcement. Stakeholders must weigh captive versus outsourced density verification as digital sensor drift rates and connectivity standards continue diverging across vendor platforms.
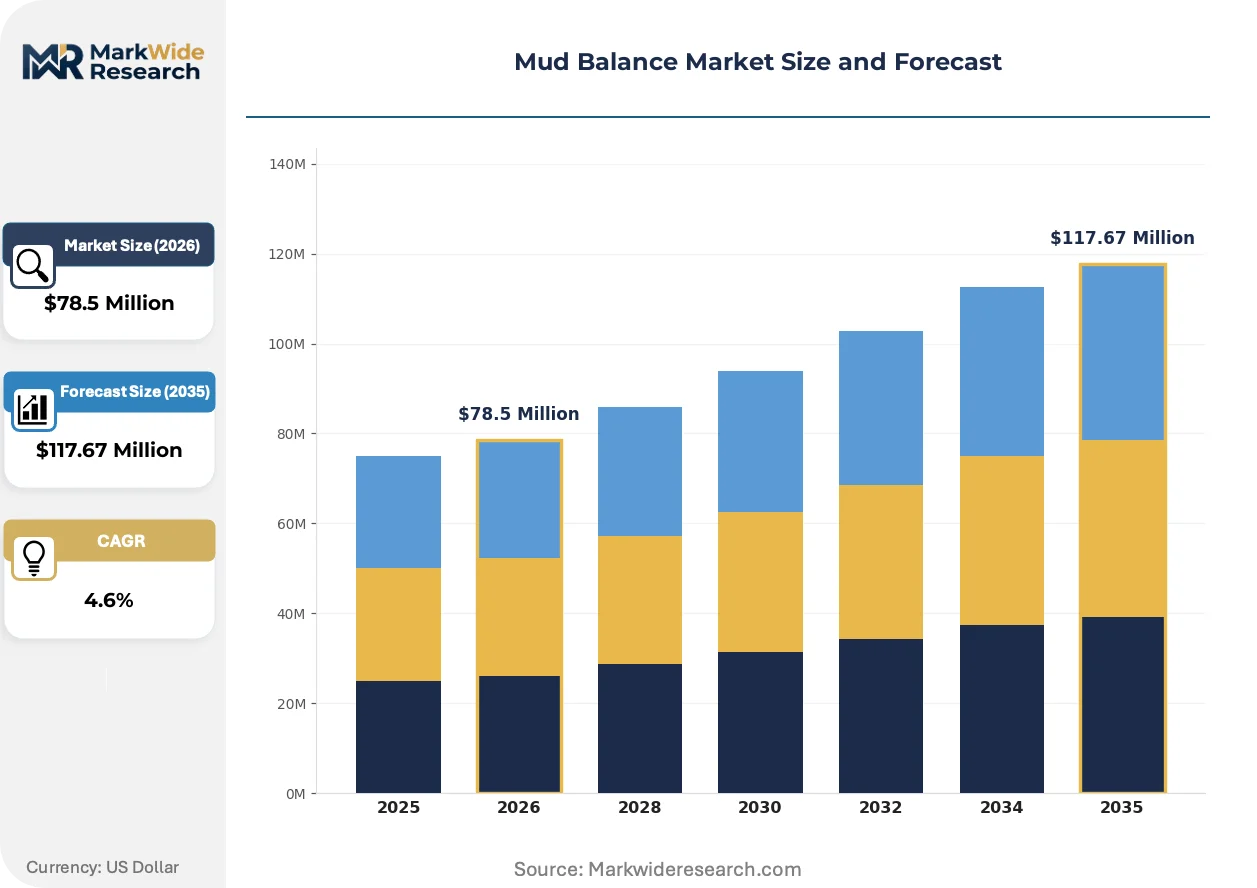
Market Dynamics
Digital sensor architectures are restructuring mud balance procurement, as API RP 13B compliance requirements and real-time data integration demands compress replacement cycles for mechanical beam units across offshore and shale drilling operations.
Growth Catalysts
- Offshore drilling density precision mandates:Deepwater operators in the US Gulf Coast corridor require continuous wellbore pressure monitoring to minimize non-productive time during high-cost offshore campaigns.
- API RP 13B standardization:Uniform test procedures across American oilfield operations create consistent replacement demand for certified equipment as operators refresh field testing inventories.
- Composite sensor housings:Polymer-based materials reduce unit weight and corrosion susceptibility, enabling extended deployment cycles in high-salinity drilling environments.
Market Restraints
- Stainless steel price volatility:Traditional beam-and-cup manufacturing depends on 316-grade stainless feedstock, exposing mechanical unit producers to commodity cost swings.
- Load cell supplier concentration:Precision strain gauge production clusters in German and Japanese specialty electronics corridors, creating single-source vulnerability for digital mud balance assemblers.
- Digital-Analog protocol fragmentation:Proprietary data transmission formats between Schlumberger, Baker Hughes, and independent mud logging systems force redundant sensor investments.
Strategic Opportunities
- Latin American shale development:Argentina's Vaca Muerta formation and Brazil's pre-salt expansion create greenfield demand for portable field testing units without legacy equipment replacement drag.
- EPA spill prevention alignment:Stricter calibration frequency requirements for blowout risk mitigation position certified service providers to capture recurring verification revenue streams.
- IoT-Cloud convergence:Edge computing integration enables predictive maintenance alerts and remote diagnostics, differentiating premium digital units from commodity mechanical alternatives.
Industry Challenges
- API certification timeline compression:Third-party laboratory validation for modified sensor designs extends product launch windows, delaying revenue recognition for digital platform upgrades.
- Legacy mud logging integration:Retrofitting load-cell architectures into existing analog data acquisition systems requires custom signal conditioning hardware and field engineering support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mud Balance Market |
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $117.67 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Mud Balance, Mechanical Mud Balance, Portable Mud Balance, Laboratory Mud Balance End User: Oil & Gas, Mining, Construction, Environmental Services Distribution Channel: Direct Sales, Online Retail, Distributors, Manufacturers Application: Drilling Operations, Geological Surveys, Laboratory Testing, Field Testing |
| Companies Covered | Fann Instrument Company, OFI Testing Equipment, Inc., Halliburton, Schlumberger Limited, Baker Hughes Company, Weatherford International plc, National Oilwell Varco, Inc., Newpark Resources Inc., Tetra Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mud Balance Market Trends and Innovations
Sensor miniaturization and wireless telemetry are collapsing the distinction between laboratory-grade precision and field-portable durability, forcing equipment manufacturers to recalibrate their hardware roadmaps around unified digital platforms rather than segmented mechanical-digital product lines.
MEMS-based density sensing is absorbing the mid-range measurement segment previously served by mechanical beam balances. Shale operators in the Permian and Bakken formations are deploying these solid-state units for continuous circulating system monitoring. The technology is absorbing calibration labor costs while compressing the acceptable error tolerance for automated drilling fluid management systems.
EPA enforcement of spill prevention regulations is tightening calibration documentation requirements for density measurement equipment used in offshore and high-pressure onshore applications. Operators now face elevated penalty exposure from inaccurate readings that contribute to uncontrolled release incidents. Service companies are responding by internalizing verification capabilities rather than relying on third-party certification labs.
Rental and managed-service models are displacing outright equipment purchases among independent drilling contractors. This shift concentrates fleet ownership with integrated service providers who bundle mud balance deployment within broader drilling fluid packages. The transformation is most visible in the US Gulf Coast corridor, where contractor consolidation has reduced the addressable base of standalone instrument buyers.
Mud Balance Market Segmentation
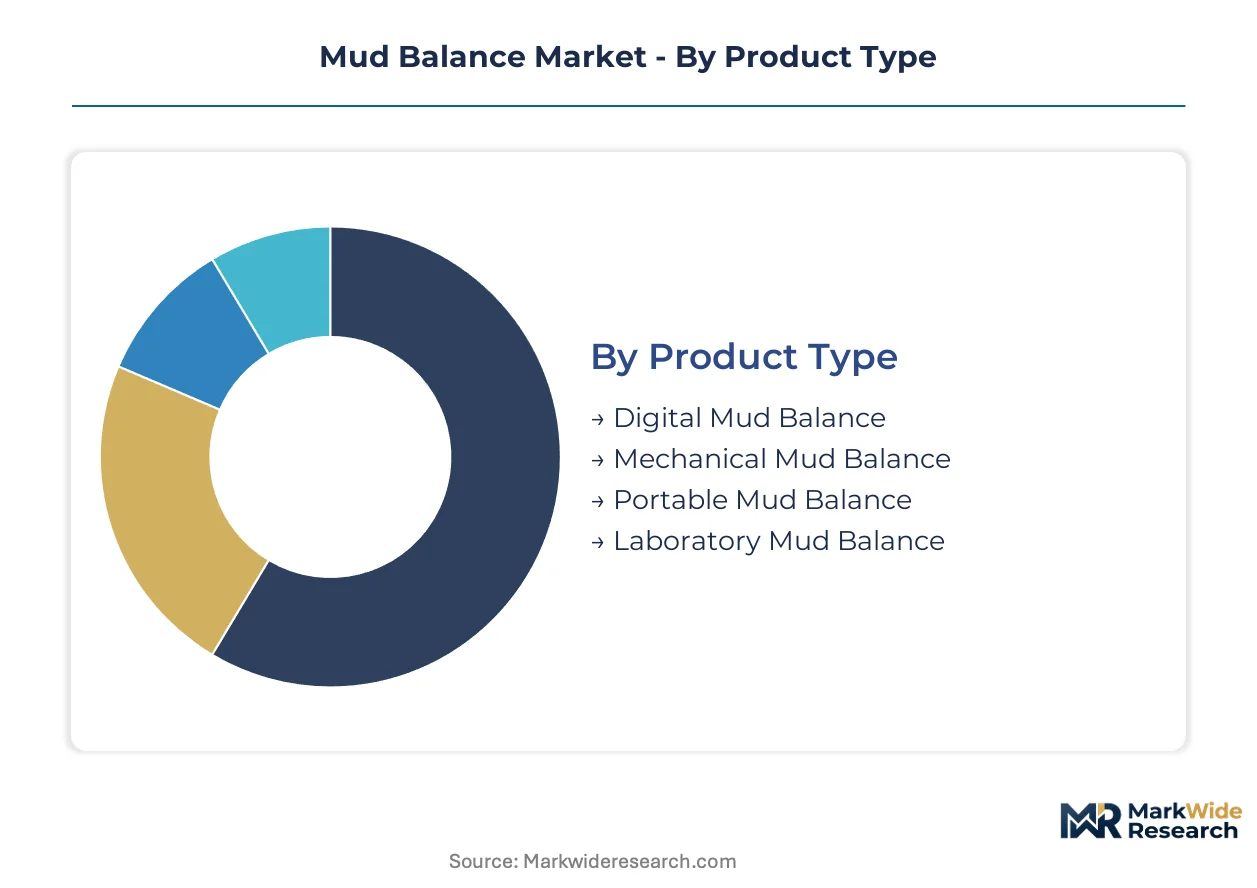
Mud balance procurement patterns fragment sharply across product architectures and deployment contexts. Understanding these divisions reveals where digital sensor investments concentrate versus where mechanical legacy systems persist.
Product Type:
Supply concentration tilts toward digital platforms as API RP 13B compliance costs and real-time data mandates reshape manufacturer priorities.
- Digital Mud Balance:Load-cell architectures transmit density readings directly to mud logging systems via proprietary protocols. Offshore operators in the US Gulf Coast corridor mandate these units for continuous wellbore pressure monitoring during deepwater campaigns.
- Mechanical Mud Balance:Beam-and-cup mechanisms calibrated to API standards dominate replacement cycles in budget-constrained onshore drilling. Stainless steel feedstock volatility compresses margins for producers dependent on 316-grade construction.
- Portable Mud Balance:Field-deployable units serve remote well sites without laboratory infrastructure. Argentina's Vaca Muerta development absorbs volume for greenfield shale operations.
- Laboratory Mud Balance:Certification labs at integrated service companies anchor demand for precision verification equipment. EPA spill prevention alignment tightens calibration frequency requirements for these installations.
Today's leader: Digital Mud Balance. Tomorrow's challenger: Portable Mud Balance.
End User:
Cost tier stratification separates integrated service providers from independent contractors across drilling fluid management budgets.
- Oil & Gas:Dominant demand source spanning offshore platforms, shale basins, and conventional onshore drilling. Schlumberger and Baker Hughes bundle mud balance deployment within integrated drilling fluid service contracts.
- Mining:Mineral exploration and tailings management applications require density measurement for slurry control. Geological survey contractors in Brazil's pre-salt expansion absorb specialized units.
- Construction:Tunnel boring and foundation work drives intermittent procurement for slurry wall monitoring. Project-based purchasing patterns limit fleet standardization.
- Environmental Services:Contaminated site characterization and remediation monitoring creates niche demand for portable field testing. EPA enforcement elevates calibration documentation requirements.
Oil & Gas commands current volume. Environmental Services climbs fastest on regulatory tailwinds.
Distribution Channel:
Volume concentration favors direct manufacturer relationships as rental and managed-service models displace standalone instrument purchases.
- Direct Sales:Integrated service providers negotiate enterprise agreements for fleet standardization. Fann Instrument Company leverages long-standing oilfield relationships to sustain premium positioning.
- Distributors:Regional inventory buffers serve independent drilling contractors with shorter procurement cycles. Latin American shale development channels volume through specialized oilfield equipment distributors.
- Online Retail:Replacement parts and consumables migrate to digital procurement platforms. Standardized mechanical components suit this channel better than calibrated digital sensors.
- Manufacturers:Captive production for internal service company fleets eliminates third-party margin. Baker Hughes internalizes supply for digital density logging compatibility requirements.
Direct Sales anchors revenue. Distributors gain ground where contractor consolidation hasn't eliminated standalone buyers.
Application:
Customer type divergence separates automated drilling fluid management from manual verification workflows.
- Drilling Operations:Continuous circulating system monitoring absorbs MEMS-based density sensing in Permian and Bakken shale formations. Real-time data integration compresses acceptable error tolerance for automated systems.
- Field Testing:Portable deployment at remote well sites dominates unit volume. Composite sensor housings reduce weight and corrosion susceptibility for extended cycles in high-salinity environments.
- Laboratory Testing:Certification and quality control workflows concentrate at service company facilities. ISO 10414 protocols shape product requirements for cross-border equipment sales.
- Geological Surveys:Mineral exploration and site characterization drives intermittent demand for precision density measurement. Project duration uncertainty limits capital commitment.
Drilling Operations leads investment. Field Testing scales fastest on shale development momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Gulf Coast corridor anchors global mud balance procurement, with shale basin density monitoring and offshore drilling precision requirements sustaining replacement cycles for both mechanical and digital units across Texas, Louisiana, and coastal platforms.
United States
EPA spill prevention regulations tighten calibration documentation for density measurement equipment used in offshore and high-pressure onshore applications. The Permian Basin in West Texas absorbs MEMS-based density sensing for continuous circulating system monitoring. Houston's oilfield service cluster concentrates integrated drilling fluid contract bundling.
Brazil
Pre-salt expansion drives greenfield demand for portable field testing units without legacy equipment replacement drag. ANVISA alignment with ISO 10414 protocols shapes product certification requirements for cross-border equipment sales. Rio de Janeiro's offshore service base anchors integrated mud logging system deployments.
Argentina
Vaca Muerta shale development creates fresh procurement for portable mud balance units at remote well sites. The country's national energy regulator enforces wellbore pressure management standards for unconventional drilling campaigns. Neuquén Province concentrates drilling contractor consolidation and rental fleet standardization.
China
Domestic shale gas exploration in Sichuan-Chongqing region absorbs laboratory-grade precision equipment for certification workflows. SAMR oversight of measurement instrument standards elevates compliance costs for imported digital sensor platforms. Xi'an's oilfield equipment manufacturing corridor hosts beam-and-cup component suppliers.
Germany
Precision strain gauge production clusters in German specialty electronics corridors, creating single-source vulnerability for digital mud balance assemblers. REACH compliance requirements for sensor materials shape procurement criteria for EU-bound equipment. Munich's industrial sensor ecosystem supplies load-cell architectures to global oilfield instrument manufacturers.
Mud Balance Market Competitive Landscape
Global majors compete with regional champions across integrated service bundling versus standalone instrument specialization. The vendor base organizes into three tiers: integrated oilfield service conglomerates, dedicated testing equipment specialists, and regional fabrication houses serving replacement part demand. Strategic moves concentrate on rental fleet consolidation and digital platform licensing to mud logging system providers.
Among North American testing equipment specialists, Fann Instrument Company exemplifies premium positioning through long-standing oilfield relationships. Schlumberger Limited and Baker Hughes Company occupy positions within the integrated service tier, anchoring mud balance deployment within broader drilling fluid management contracts rather than standalone instrument sales.
| Leading Market Players |
|---|
| Fann Instrument Company |
| OFI Testing Equipment, Inc. |
| Halliburton |
| Schlumberger Limited |
| Baker Hughes Company |
| Weatherford International plc |
| National Oilwell Varco, Inc. |
| Newpark Resources Inc. |
| Tetra Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
API RP 13B compliance mandates for real-time density data transmission are forcing mechanical beam balance producers toward load-cell architectures, compressing margins as stainless steel feedstock volatility collides with German and Japanese strain gauge supplier concentration.
Pricing Analysis
Input-cost pass-through from 316-grade stainless steel and precision strain gauge feedstock dominates pricing dynamics across mechanical and digital tiers. Three-tier pricing structure across premium, standard, and economy levels separates API-certified laboratory units from portable field models and unbranded replacement components. Cost compression in mechanical beam assemblies is intensifying because composite sensor housings decouple mid-range producers from metal-dependent cost structures. Independent drilling contractors exhibit highest price sensitivity, while integrated service providers prioritize digital platform compatibility over unit economics.
Supply Chain Analysis
Certification and qualification gating through API RP 13B and ISO 10414 protocols constrains supplier entry, anchoring production in the United States, Germany, and China. Precision strain gauge production draws from German specialty electronics corridors, while beam-and-cup fabrication rests on Chinese component suppliers and domestic US assembly. Single-source vulnerability for load-cell architectures creates supply chain risk as Japanese strain gauge producers consolidate output. Distribution runs through direct manufacturer relationships with integrated service providers, supplemented by regional distributors serving independent contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mud balance market functions as a stable compounder, with offshore drilling precision mandates and EPA spill prevention enforcement sustaining replacement cycles regardless of oil price volatility.
For Market Incumbents: Hedge against MEMS-based density sensing substitution by deepening API certification investments for digital platform roadmaps. Acquire captive load-cell production capability to neutralize German and Japanese supplier concentration risk. Bundle predictive maintenance software with hardware deployments to lock in integrated service provider contracts. For New Entrants and Emerging Players: Enter via Argentina's Vaca Muerta and Brazil's pre-salt corridors where greenfield shale development absorbs portable field testing units without legacy replacement drag. Target environmental services contractors facing EPA calibration documentation mandates as the most penetrable segment. Pursue rental fleet partnerships with regional distributors rather than direct sales to consolidated drilling contractors. For Investors and Strategic Acquirers: Asymmetric upside sits with digital sensor specialists possessing IoT-cloud integration capabilities and API certification pipelines. Five-to-ten year viability hinges on regulatory enforcement continuity for blowout risk mitigation equipment. Monitor EPA penalty escalation trends as the inflection signal for accelerated service company internalization of verification capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Load-Cell Architecture Migration | Enables real-time mud logging integration demanded by US Gulf Coast offshore operators. |
| Composite Sensor Housing Adoption | Reduces unit weight and corrosion susceptibility for high-salinity deployment cycles. |
| API Certification Pipeline Investment | Accelerates product launch timelines for modified digital sensor designs. |
| Rental Fleet Consolidation | Captures independent contractor demand displaced from outright equipment purchases. |
| Predictive Maintenance Software Development | Differentiates premium digital units through edge computing and remote diagnostics. |
Research Methodology
Direct dialogue with drilling fluid service executives, mud logging system engineers, API certification laboratory directors, and oilfield procurement managers grounded qualitative insights. Secondary validation drew from EPA enforcement records, API RP 13B documentation, ISO 10414 protocols, and SEC filings of integrated service providers. Bottom-up unit deployment estimates across shale basins and offshore corridors triangulated against top-down drilling activity forecasts.
Segmented outputs across product architecture, end-user tier, distribution channel, and application context were generated across the analysis window. CAGRs were derived from replacement cycle analysis for mechanical versus digital units, calibrated to drilling rig count trajectories and regulatory enforcement intensity. Forecast inputs incorporated MEMS sensor adoption curves and rental model penetration rates by contractor consolidation status.
Inputs from drilling contractor fleet managers and regional equipment distributors were available through the study window; gaps in proprietary mud logging system protocol specifications introduce uncertainty bands around digital platform integration timelines. Forecasts reflect assumptions regarding EPA enforcement continuity and API standard revision schedules. A model refresh is warranted upon material change in offshore drilling permit issuance or load-cell supplier consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil, Gas and Chemicals Software Market
Oil & Gas
North America Natural Gas Market
Oil & Gas
Pumpjack Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Floating Skimmer Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Nigeria Upstream Oil Sector Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Europe Oilfield Services Market
Oil & Gas
Hydrocracking Market