
 Mayonnaise Sauce Market | 2026-2036
Mayonnaise Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Mayonnaise Sauce Market Foresight
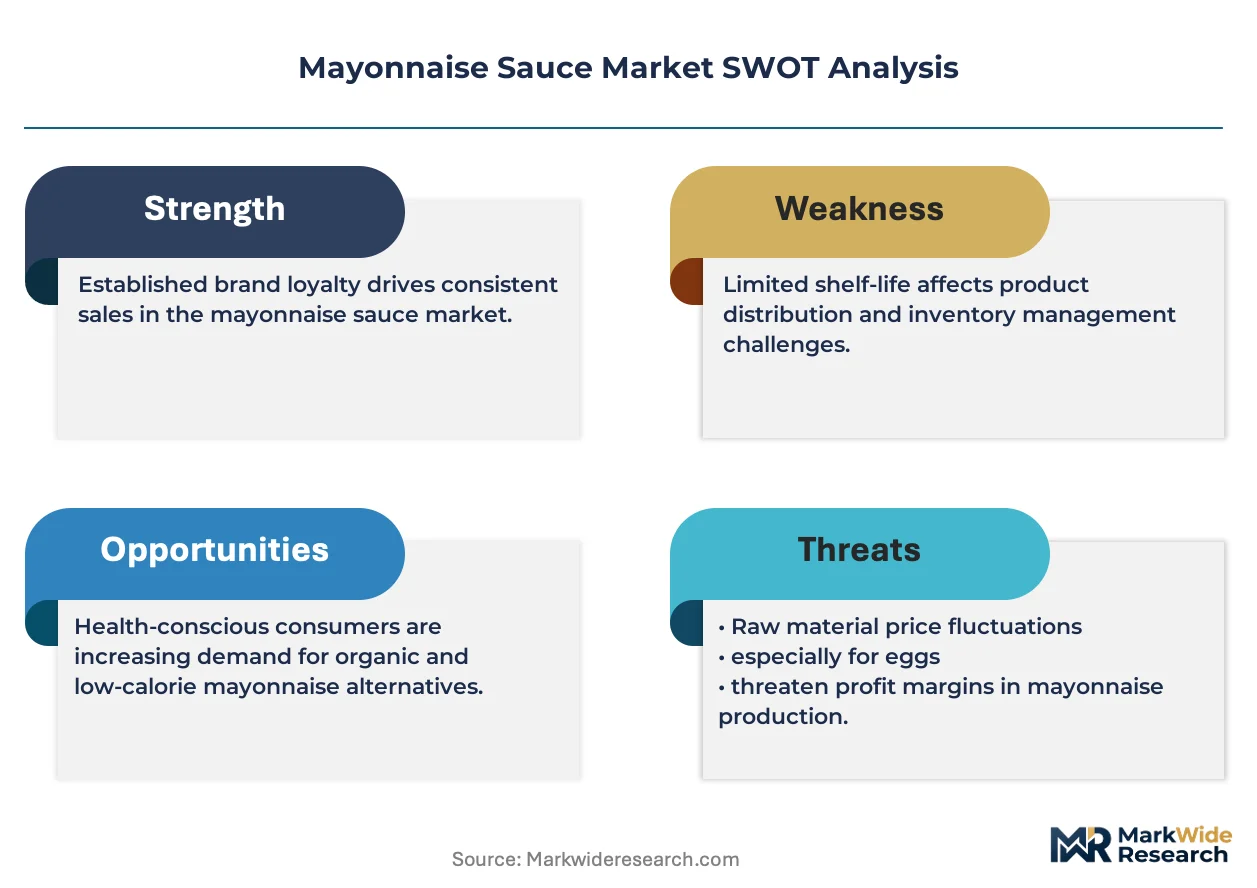
Supermarket shelf space allocation for condiments is narrowing as private-label programs expand. Unilever (Hellmann's) leverages its refrigerated logistics network to sustain nationwide freshness guarantees. Kraft Heinz Company anchors its portfolio through dual-placement strategies spanning conventional and organic sets. Kewpie Corporation differentiates through umami-forward formulations that command premium positioning in specialty retail.
Mayonnaise sauce is an oil-in-water emulsion stabilized by egg yolk lecithin, typically containing sixty-five to eighty percent vegetable oil by weight, produced through high-shear mixing or colloid milling processes. The emulsion functions as a cold sauce base, sandwich spread, and binding matrix across commercial and institutional food preparation. Low-fat variants now lead volume growth as foodservice operators reformulate menus to meet calorie-labeling mandates, while organic certification commands disproportionate margin pools in North American retail. Pouch packaging for single-serve foodservice applications represents the fastest-expanding format as quick-service chains reduce portion waste and labor overhead.
FDA nutritional disclosure requirements and USDA organic certification standards shape product development timelines and label claim substantiation across domestic manufacturing. EFSA health claim evaluations and EU F-Gas Regulation compliance for refrigerated transport create parallel compliance obligations for exporters serving European foodservice accounts. Stakeholders must monitor evolving federal menu-labeling enforcement and state-level packaging waste legislation to anticipate reformulation and material substitution requirements.
Market Dynamics
Clean-label reformulation mandates from the FDA are compressing product development cycles while redirecting R&D budgets toward emulsion stability without synthetic additives. Foodservice operators simultaneously demand calorie-compliant formulations and operational consistency at scale.
Growth Catalysts
- Menu-Labeling Mandates:FDA nutritional disclosure rules force chain restaurants to reformulate proprietary sauces, creating pull for reduced-fat emulsions that maintain mouthfeel through modified starch systems.
- Single-Serve Pouch Adoption:Quick-service chains in the United States are replacing portion cups with flexible pouches to cut labor overhead and waste, expanding addressable packaging demand.
- Umami-Forward Positioning:Specialty retail channels are capturing margin premiums through monosodium glutamate-free formulations that leverage yeast extract and fermented rice vinegar for depth.
Market Restraints
- Egg Yolk Supply Concentration:Midwestern United States layer operations supply the majority of food-grade lecithin, creating input vulnerability to avian influenza cycles and feed cost spikes.
- Refrigerated Transport Cost Structure:EU F-Gas Regulation compliance for cold-chain logistics adds incremental cost per pallet for European export shipments, compressing net margins on transatlantic foodservice contracts.
- Plant-Based Substitution Threat:Aquafaba and modified cellulose emulsions are displacing conventional mayonnaise in vegan menu applications across institutional catering accounts.
Strategic Opportunities
- USDA Organic Certification Tailwind:Premium shelf placement and disproportionate margin pools in North American retail reward certified organic production, though conversion timelines stretch eighteen to twenty-four months.
- Direct-to-Operator Distribution:Foodservice broadline distributors are launching private-label sauce programs that bypass branded intermediaries, opening white space for co-manufacturing partnerships.
- Sous Vide and Prepared Meal Convergence:Ready-to-eat protein kits require heat-stable emulsion coatings that survive pasteurization, creating application expansion beyond cold-sauce traditional boundaries.
Industry Challenges
- Emulsion Science Talent Scarcity:Food chemistry programs produce fewer colloid and interface specialists than formulation labs require, elongating hire timelines for R&D functions.
- Dual-Formula Production Complexity:Manufacturing lines must segregate organic and conventional runs to prevent cross-contamination, reducing effective capacity and complicating scheduling.
- Clean-Label Stability Trade-offs:Removing EDTA and calcium disodium EDTA chelators shortens shelf life, forcing faster inventory turns and tighter distributor coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mayonnaise Sauce Market |
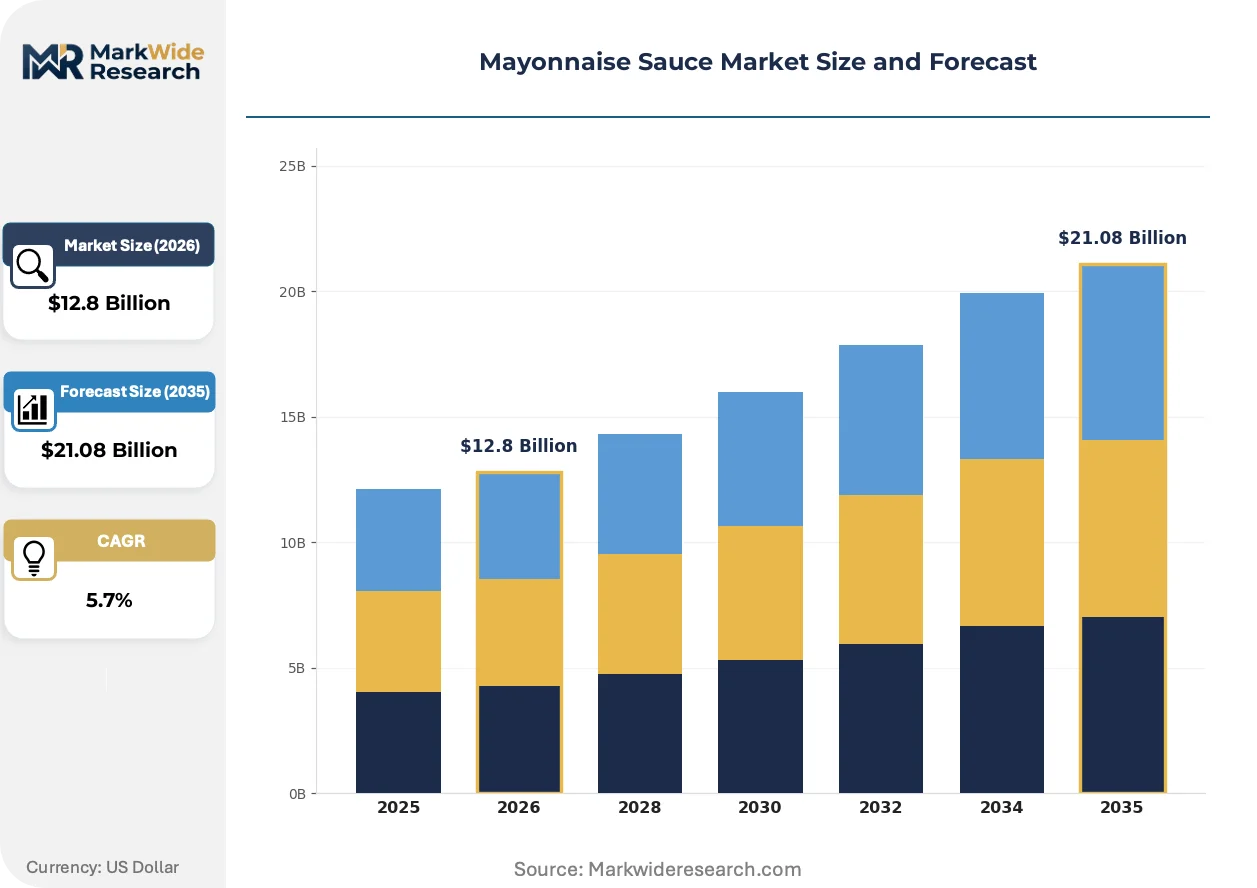
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Low Fat, Organic, Specialty Packaging Type: Bottle, Sachet, Jar, Pouch End User: Households, Restaurants, Foodservice, Manufacturing Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesalers |
| Companies Covered | Nestlé SA, Kewpie Corporation, Unilever (Hellmann's), Remia International, Dr. Oetker, Kraft Heinz Company, Ajinomoto Co., Inc., EFKO Group, McCormick & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mayonnaise Sauce Market Shifts & Advancements
Formulation science is converging with packaging engineering and regulatory compliance systems to redefine how emulsion products reach foodservice and retail endpoints. Three developments are restructuring competitive requirements.
High-pressure processing is hybridizing pasteurization protocols for refrigerated mayonnaise, extending shelf life without thermal degradation of egg yolk proteins. Regional dairy cooperatives in Wisconsin and California are adopting HPP lines for value-added condiment production. This technology is hybridizing the boundary between fresh and shelf-stable categories, enabling retail placement in perimeter departments previously reserved for shorter-dated products.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration fleet turnover across European distribution networks serving export-bound mayonnaise shipments. Cold-chain operators face capital decisions between hydrofluoroolefin retrofits and transcritical CO2 systems. Foodservice exporters to Germany and France are absorbing compliance costs or redirecting volume toward domestic North American accounts.
Chain restaurant procurement departments are consolidating sauce specifications into fewer approved suppliers with national distribution coverage. Quick-service operators now require single-source accountability for formulation consistency across thousands of locations. This concentration is most visible in the United States, where Yum! Brands and Darden-scale portfolios wield specification authority that reshapes manufacturer capacity allocation.
Mayonnaise Sauce Market Segmentation
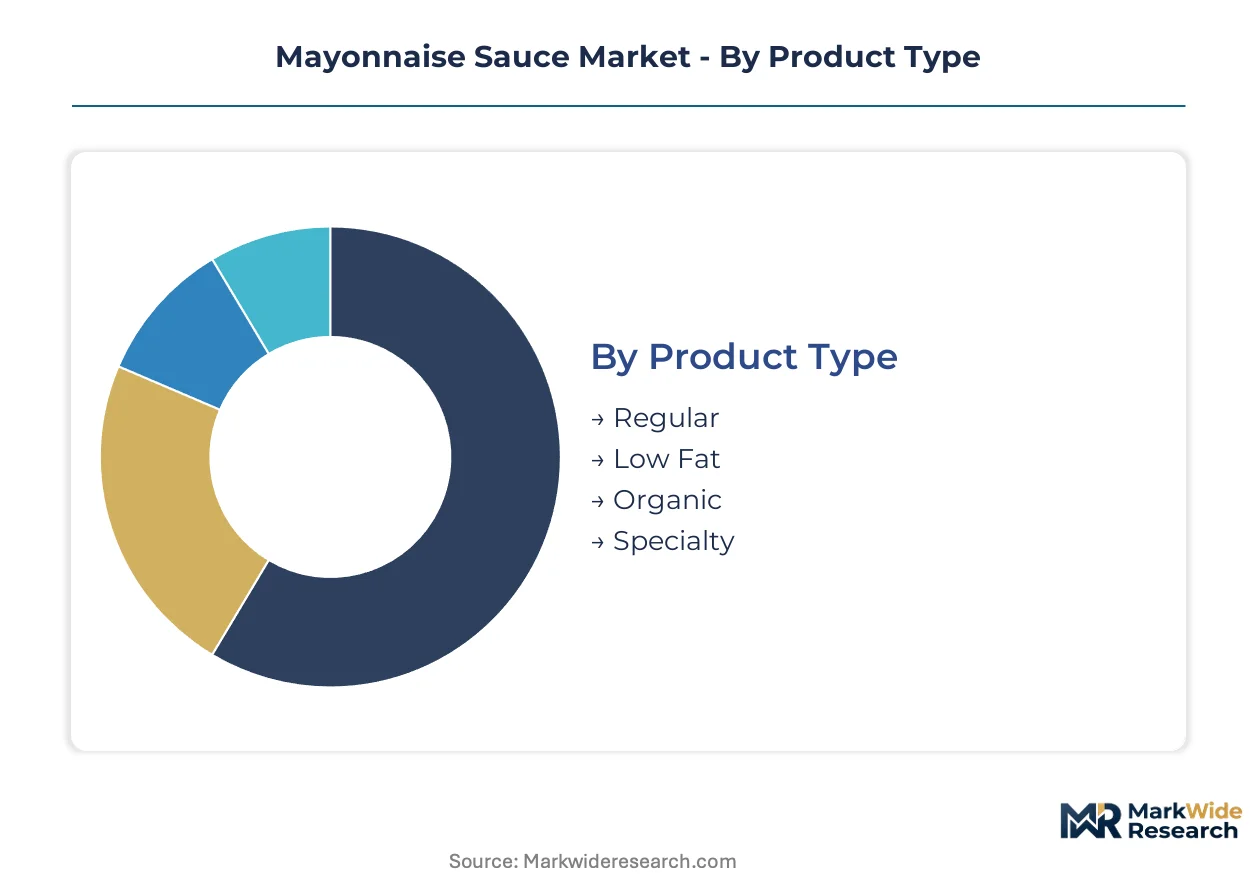
Mayonnaise sauce segmentation reflects divergent velocity profiles across consumption contexts. Product formulations cycle through reformulation faster than packaging formats. End-user concentration shapes margin structure more sharply than channel selection.
Product Type:
Inventory turns separate shelf-stable formulations from refrigerated premium tiers. Regular mayonnaise rotates through retail distribution in under thirty days. Organic SKUs sit sixty to ninety days before depletion.
- Regular:Standard oil-in-water emulsion at sixty-five to eighty percent vegetable oil content anchors volume across conventional retail and institutional foodservice. Demand concentrates in quick-service chain procurement programs where specification standardization overrides premium positioning.
- Low Fat:Modified starch systems and hydrocolloid stabilizers replace oil content to achieve thirty to fifty percent calorie reduction while maintaining viscosity. FDA menu-labeling mandates concentrate demand in United States chain restaurant reformulation programs.
- Organic:USDA-certified production with segregated supply chains and eighteen-to-twenty-four-month conversion timelines commands disproportionate margin pools in specialty retail channels.
- Specialty:Umami-forward formulations leveraging yeast extract and fermented substrates target premium positioning in Asian-market retail and foodservice import channels.
Regular dominates installed base. Low Fat is where expansion concentrates.
Packaging Type:
Format selection tracks operational cost structures across end-use environments. Rigid containers serve high-volume stationary consumption. Flexible formats reduce labor and waste in mobile foodservice contexts.
- Bottle:Polyethylene terephthalate and high-density polyethylene containers dominate retail shelf placement with tamper-evident closures and controlled dispensing. United States supermarket chains prioritize bottle formats for planogram efficiency and brand visibility.
- Sachet:Single-serve laminated film packets target institutional catering and airline meal programs where portion control and shelf stability outweigh unit economics.
- Jar:Glass packaging persists in premium retail positioning and European export markets where material perception influences purchase decisions.
- Pouch:Flexible stand-up and flat pouches with fitment closures are climbing the fastest as quick-service operators replace portion cups to cut labor overhead and packaging waste.
Bottle commands current volume share. Pouch is gaining share fastest.
End User:
Procurement authority determines specification complexity and pricing leverage. Fragmented buyers accept standard formulations. Consolidated operators demand custom development.
- Households:Supermarket and online retail purchases drive volume through repeat-buy loyalty and promotional responsiveness. United States consumers concentrate demand in dual-placement conventional and organic sets.
- Restaurants:Independent and small-chain operators purchase through broadline distributors with limited specification authority, accepting manufacturer-standard formulations.
- Foodservice:National quick-service and casual-dining chains wield consolidated procurement power, demanding proprietary formulations with national distribution coverage and formulation consistency guarantees.
- Manufacturing:Prepared meal and sauce compounders purchase bulk emulsion as ingredient input, prioritizing heat stability and batch-to-batch consistency over branded positioning.
Households anchor absolute volume. Foodservice is where margin expansion concentrates.
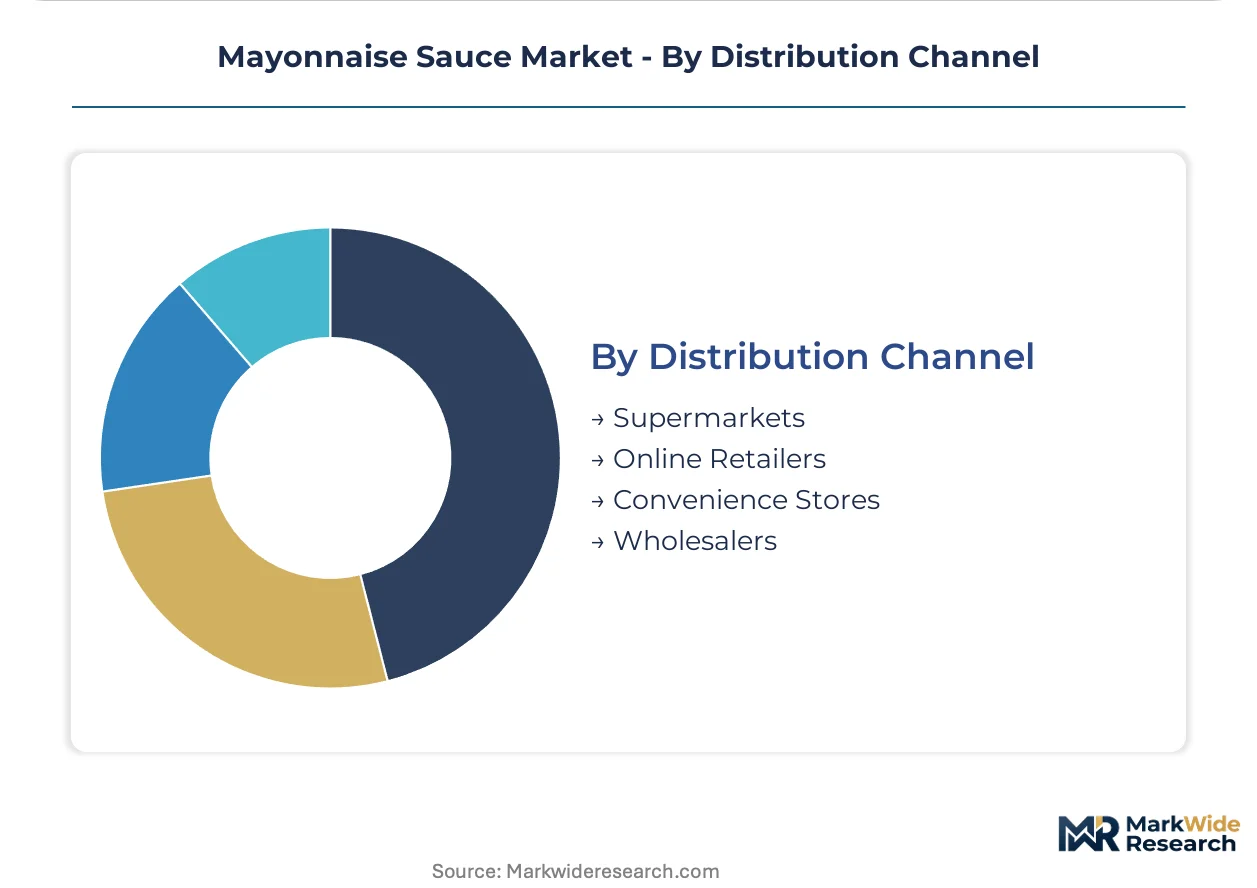
Distribution Channel:
Channel selection determines speed-to-shelf and promotional mechanics. Physical retail maintains immediacy for impulse replenishment. Digital channels capture subscription and bulk purchasing.
- Supermarkets:Conventional and natural grocery chains control planogram placement and private-label expansion, narrowing shelf space for branded entrants while expanding store-brand mayonnaise programs.
- Online Retailers:E-commerce platforms and direct-to-consumer fulfillment capture bulk and subscription purchasing with refrigerated logistics requirements limiting participation to shelf-stable formulations.
- Convenience Stores:Grab-and-go formats target immediate consumption with smaller pack sizes and limited assortment depth.
- Wholesalers:Foodservice broadline distributors aggregate demand from fragmented restaurant and institutional accounts, launching private-label programs that bypass branded intermediaries.
Supermarkets dominate current throughput. Online Retailers show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites European mayonnaise export capacity, while Interstate highway corridors from Chicago to Dallas anchor North American distribution velocity.
United States
Quick-service chain procurement consolidation drives specification standardization across thousands of locations. FDA menu-labeling enforcement compels reformulation toward reduced-fat emulsions. Midwestern layer operations in Iowa and Ohio supply food-grade lecithin, creating input vulnerability to avian influenza cycles.
Germany
Foodservice distributors demand heat-stable formulations for prepared meal applications. EU F-Gas Regulation phase-down schedules accelerate refrigeration fleet turnover across cold-chain networks. The Rhine-Ruhr industrial corridor hosts emulsion processing facilities serving Central European retail accounts.
Japan
Umami-forward positioning commands premium placement in domestic and export specialty channels. METI standards for food additive labeling shape clean-label development timelines. Kewpie Corporation's Yokohama operations anchor fermentation-based formulation expertise.
France
Glass-packaged premium tiers persist in retail channels where material perception influences purchase decisions. ANSM oversight of food contact substances affects imported formulation approvals. The Île-de-France region concentrates foodservice procurement authority for national restaurant chains.
United Kingdom
Private-label expansion narrows branded shelf space in supermarket condiment sets. Post-Brexit import documentation requirements elongate lead times for continental European suppliers. Greater Manchester hosts broadline distribution hubs aggregating foodservice demand from fragmented independent operators.
Mayonnaise Sauce Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in emulsion science and packaging engineering. The vendor base organizes around three tiers: multinational CPG conglomerates with refrigerated logistics networks, mid-cap regional processors with co-manufacturing flexibility, and specialty fermenters leveraging umami-forward positioning. Dominant competitive moves include private-label program launches that bypass branded intermediaries and high-pressure processing technology licensing to extend shelf life without thermal degradation.
Within the multinational tier, Unilever, Kraft Heinz Company, and Nestlé SA exemplify platform-scale operators with nationwide distribution coverage and formulation consistency guarantees. Kewpie Corporation and Ajinomoto Co., Inc. occupy positions in the specialty fermenter archetype, leveraging fermentation-derived depth for premium positioning. Remia International, Dr. Oetker, and EFKO Group represent regional processors with co-manufacturing partnerships serving foodservice broadline distributors. McCormick & Company sits within the flavor-system integrator category, supplying compound formulations to manufacturing accounts.
| Leading Market Players |
|---|
| Nestlé SA |
| Kewpie Corporation |
| Unilever (Hellmann's) |
| Remia International |
| Dr. Oetker |
| Kraft Heinz Company |
| Ajinomoto Co., Inc. |
| EFKO Group |
| McCormick & Company |
| Others |
Supply & Pricing Matrix
Midwestern layer operations in Iowa and Ohio concentrate food-grade lecithin supply, and their capacity constraints translate directly into input cost volatility that squeezes margin pools across emulsion manufacturers serving North American foodservice accounts.
Pricing Analysis
Volume-discount tiering structures separate national quick-service chain procurement from fragmented independent restaurant purchasing, with the former extracting fifteen-to-twenty point spreads through consolidated specification authority. Price differentiation hinges on organic certification grade and refrigerated logistics guarantee tiers, with USDA-certified production commanding shelf placement premiums. Cost compression in conventional emulsion tiers is intensifying because private-label expansion narrows branded pricing power. Independent operators show highest price sensitivity, while consolidated chains prioritize formulation consistency over unit cost.
Supply Chain Analysis
EU F-Gas Regulation phase-down schedules act as export-control regime analogs, restricting refrigerated mayonnaise flows to European foodservice accounts through compliance cost absorption requirements. Supply concentrates in the United States, Germany, and Japan, with Midwestern egg yolk operations, Rhine-Ruhr processing corridors, and Yokohama fermentation facilities anchoring regional capacity. Raw material dependencies span vegetable oil feedstocks, egg-derived lecithin, and modified starch stabilizers. Single-source vulnerability in Midwestern layer operations exposes the chain to avian influenza disruption cycles. Distribution runs through foodservice broadline distributors with private-label bypass capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based emulsion substitutes threaten conventional mayonnaise displacement across institutional catering accounts, forcing incumbents to defend share through differentiation investments that synthetic alternatives cannot replicate.
For Market Incumbents: Build refrigerated logistics moats through captive cold-chain infrastructure that guarantees freshness windows private-label competitors cannot match. Invest in high-pressure processing licensing to extend shelf life without thermal degradation, neutralizing clean-label stability trade-offs. Anchor capacity in USDA-certified organic production to capture disproportionate margin pools as specialty retail placement tightens. For New Entrants and Emerging Players: Geographic underpenetration in direct-to-operator distribution channels offers white space for co-manufacturing partnerships that bypass branded intermediaries. Target foodservice broadline private-label programs with heat-stable emulsion formulations for prepared meal applications. Pursue umami-forward positioning through fermentation-derived depth to command premium placement in Asian-market import channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty fermenters with proprietary yeast extract and fermented substrate capabilities that resist commoditization. Long-term viability rests on clean-label emulsion science talent scarcity that elongates R&D hire timelines for competitors. Watch for inflection signals in FDA menu-labeling enforcement intensity that would accelerate reduced-fat reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Removes synthetic chelators to meet FDA disclosure rules while preserving emulsion stability through modified starch systems. |
| High-Pressure Processing Adoption | Extends refrigerated mayonnaise shelf life without thermal degradation, enabling perimeter department retail placement. |
| USDA Organic Certification Conversion | Unlocks premium shelf placement and disproportionate margin pools in North American specialty retail channels. |
| Single-Serve Pouch Format Expansion | Reduces labor overhead and packaging waste for quick-service chains replacing portion cup systems. |
| Direct-to-Operator Distribution Buildout | Bypasses branded intermediaries through co-manufacturing partnerships with foodservice broadline distributors. |
Research Methodology
Operator-level perspectives from quick-service procurement directors, foodservice broadline category managers, emulsion R&D scientists, and refrigerated logistics coordinators anchored the qualitative base for this study. Primary interviews combined with secondary validation from FDA menu-labeling guidance documents, USDA organic certification standards, EU F-Gas Regulation compliance schedules, and customs trade flow data. Bottom-up demand modeling and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning product type tiers, packaging format evolution, end-user procurement authority concentration, and distribution channel velocity. CAGRs derived from historical trajectory analysis and forward-looking demand driver elasticity modeling. Forecast inputs incorporated FDA enforcement intensity projections and cold-chain logistics cost structure shifts.
Macroeconomic conditions sit as an overlay; deviation in feed grain commodity cycles or avian influenza outbreak frequency would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement continuity and supply chain disruption recurrence patterns. Material shifts in EU F-Gas Regulation phase-down schedules or FDA menu-labeling implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Oriental Sauce Market
Condiments & Sauces
Sun-Dried Tomato Umami Concentrate Systems Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
Oyster Sauce Market
Condiments & Sauces
Hoisin Sauce Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
UK Prepared Mustard Market
Condiments & Sauces
Chocolate Syrup Market
Condiments & Sauces
Mayonnaise Market