
 Global Cervical Dysplasia Market | 2026-2036
Global Cervical Dysplasia Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cervical Dysplasia Market Foresight
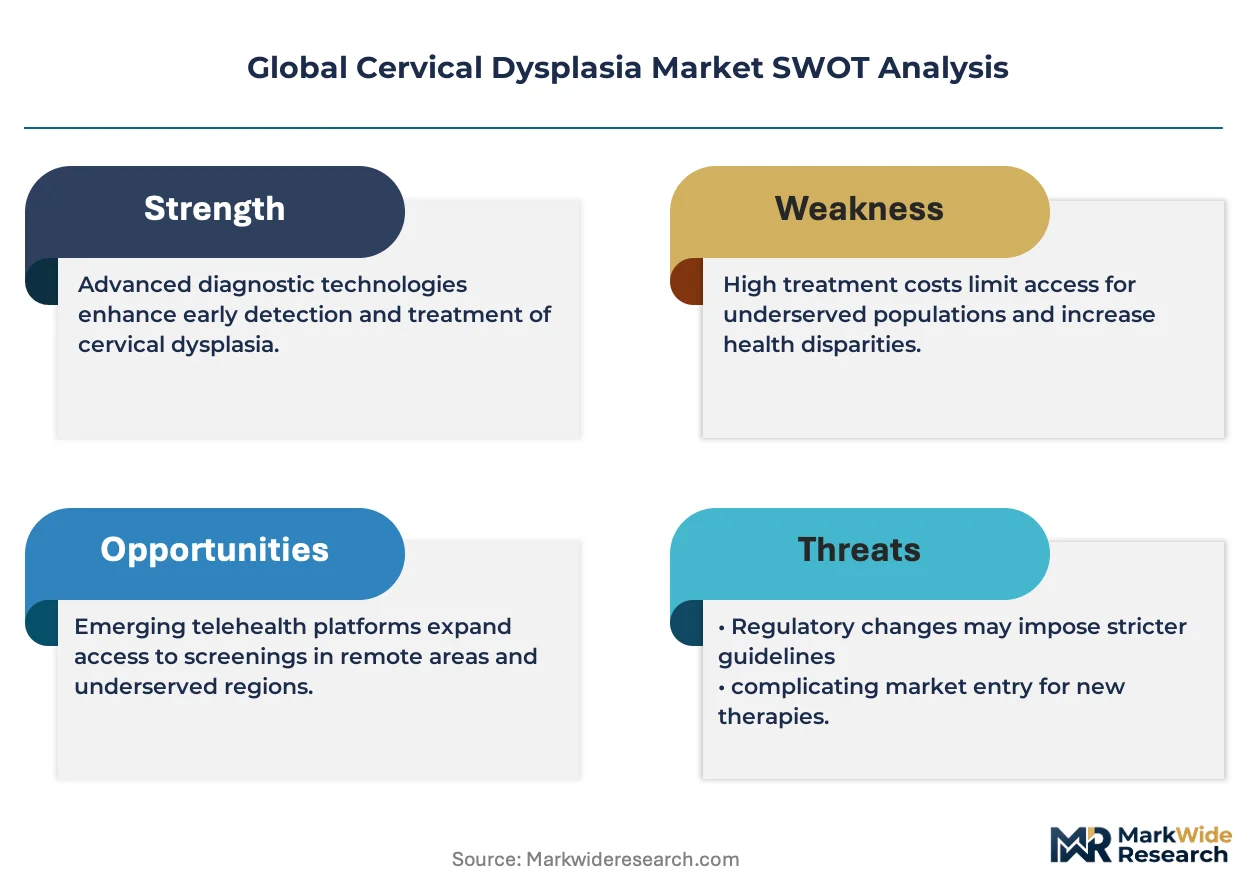
CE marking under the EU MDR is recalibrating the cost-of-entry calculus for cervical dysplasia device manufacturers seeking European market access. Qiagen N.V. leverages its molecular assay portfolio to sustain leadership in HPV DNA testing workflows. Hologic Inc. anchors its position through integrated liquid-based cytology systems that dominate laboratory throughput. Roche competes on automated diagnostic platforms that extend reach into high-volume screening networks.
Cervical dysplasia encompasses premalignant cellular abnormalities of the cervix graded CIN 1 through CIN 3, detected through cytological, histological, or molecular methods requiring colposcopic confirmation and histopathological correlation. HPV DNA Testing leads the technology segment due to superior sensitivity for high-risk oncogenic strains compared with conventional cytology. Colposcopes occupy the premium equipment tier where margin pools concentrate around digital imaging and AI-enhanced optical systems. Early Screening drives application-level demand as national programs shift from opportunistic to organized population-based protocols.
FDA clearance pathways shape product development timelines for US market entry, while WHO prequalification standards govern procurement eligibility in low- and middle-income country programs. EMA's MDR technical documentation requirements and clinical evidence thresholds are forcing portfolio rationalization among smaller device manufacturers. Stakeholders must monitor regulatory divergence between centralized EU conformity assessment and decentralized national approval frameworks as they allocate R&D and registration investments.
Market Dynamics
HPV DNA testing workflows are displacing conventional cytology as the primary screening modality, compressing the addressable market for liquid-based cytology consumables while expanding molecular assay throughput requirements across pathology networks.
Growth Catalysts
- WHO cervical cancer elimination targets:National health ministries in India and China are scaling organized screening programs to meet 2030 coverage benchmarks, creating sustained procurement demand for HPV testing platforms.
- EMA MDR framework:Stricter clinical evidence requirements for CE marking are filtering out marginal device entrants, consolidating volume with established manufacturers who can absorb regulatory compliance costs.
- Digital colposcopy integration:AI-enhanced optical systems are reducing inter-observer variability in CIN grading, accelerating adoption among gynecology clinics seeking standardized diagnostic outputs.
Market Restraints
- Reagent supply concentration:HPV DNA testing workflows depend on polymerase enzymes and probe chemistries sourced from a limited supplier base in Germany and the United States, exposing laboratories to input cost volatility and allocation constraints.
- FDA 510(k) pathway complexity:Novel molecular assays face extended review timelines when predicate devices lack comparable analytical performance claims, delaying US market entry for next-generation screening technologies.
- Self-sampling substitution threat:Vaginal self-collection devices for HPV testing are reducing reliance on clinician-administered cytology, eroding the installed base of liquid-based cytology systems in primary care settings.
Strategic Opportunities
- Underpenetrated rural India:District hospital networks lack molecular diagnostic infrastructure, creating white space for point-of-care HPV testing platforms that bypass cold-chain logistics requirements.
- Technology convergence:Integration of CRISPR-based detection with smartphone-connected readers is enabling decentralized screening in sub-Saharan African markets where laboratory density remains insufficient.
- US IRA preventive services mandate:Expanded insurance coverage for cervical cancer screening without cost-sharing is reducing patient financial barriers, stimulating volume growth in federally qualified health centers.
Industry Challenges
- Cytopathologist workforce scarcity:The pipeline of trained histopathologists is failing to match screening program expansion in China and India, creating diagnostic bottlenecks that delay treatment initiation.
- Legacy LIS integration complexity:Hospital information systems in mature markets rely on decades-old data architectures that resist seamless connectivity with cloud-based AI colposcopy platforms, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cervical Dysplasia Market |
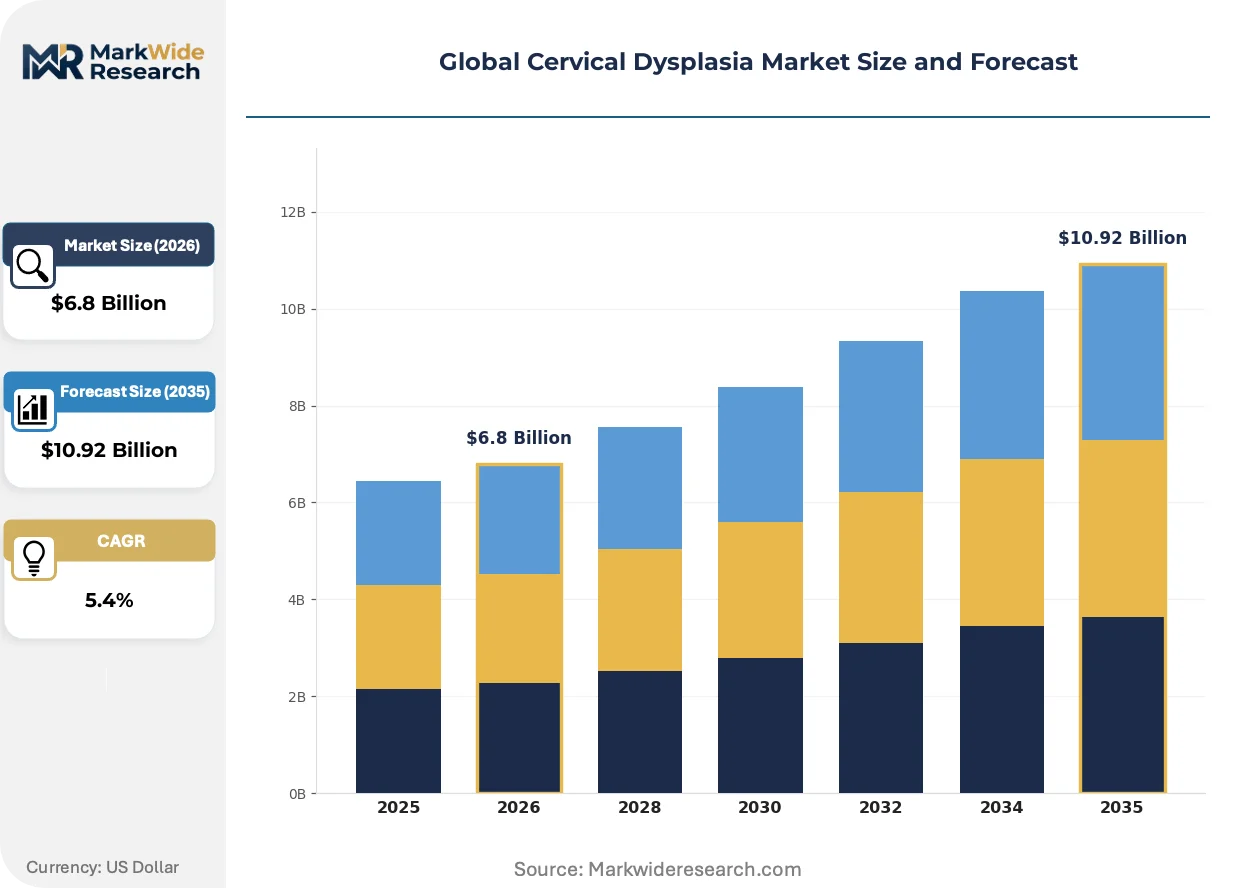
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy Devices, Cryotherapy Instruments, Colposcopes, Loop Electrosurgical Units, Laser Systems Application: Early Screening, Lesion Treatment, Follow-up Care, Risk Assessment, Patient Monitoring End User: Gynecologists, Pathology Laboratories, Diagnostic Centers, Women's Health Clinics Technology: Visual Inspection with Acetic Acid, HPV DNA Testing, Pap Smear, Liquid-based Cytology, Molecular Assays |
| Companies Covered | Qiagen N.V., Hologic Inc., Roche, Quest Diagnostics, Abbott Laboratories, BD, CooperSurgical Inc., DYSIS Medical Ltd., Micromedic Technologies Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cervical Dysplasia Market Shifts & Advancements
Artificial intelligence is penetrating diagnostic workflows at multiple intervention points, from automated cytology screening to real-time colposcopic guidance, compressing skill requirements while raising performance consistency expectations.
Extended genotyping panels for HPV are modularizing laboratory testing menus, allowing pathology services to stratify risk across 14+ high-risk oncogenic subtypes from a single specimen aliquot. Regional hospital networks in France and South Korea are adopting these expanded panels to refine triage protocols for colposcopy referral. The technology is modularizing what previously required sequential testing workflows, reducing per-patient diagnostic costs while improving positive predictive value for CIN 2+ lesions.
EU MDR technical documentation requirements are forcing device manufacturers to generate clinical performance data beyond legacy literature reviews, extending registration timelines by 18-24 months for Class IIa diagnostic devices. Smaller manufacturers are abandoning European market access rather than absorbing notified body fees and post-market surveillance obligations. High-volume screening networks in Germany and the Netherlands are consolidating procurement with suppliers who secured MDR certificates early, locking out competitors still navigating conformity assessment.
Centralized laboratory networks are unbundling after-sales service contracts from instrument procurement, shifting to third-party maintenance providers or in-house biomedical engineering teams. This disintermediation is compressing margin pools for original equipment manufacturers who previously relied on multi-year service agreements. The pattern is most visible in United States health system consolidation, where integrated delivery networks negotiate enterprise-wide service contracts independent of device vendors.
Global Cervical Dysplasia Market Segmentation
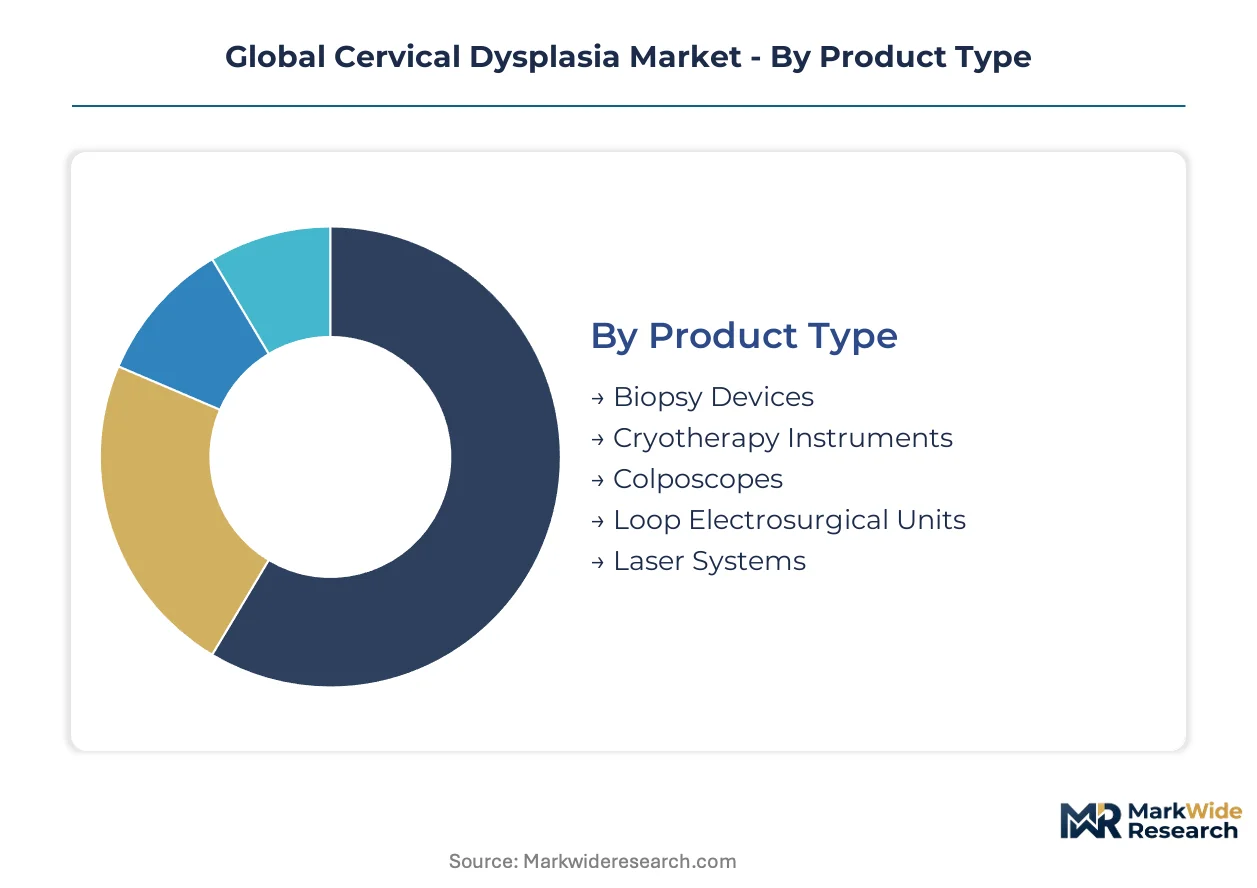
Segmentation reveals how diagnostic workflows fragment across care settings, from centralized pathology laboratories processing molecular assays to point-of-care clinics performing visual screening. Understanding these divides clarifies where procurement budgets concentrate and which technology platforms compete for instrument placement.
Product Type:
Standalone capital equipment dominates hospital procurement cycles, while disposable-embedded systems flow through consumables contracts with diagnostic networks.
- Colposcopes:Optical magnification systems with digital imaging modules enable real-time cervical visualization and biopsy guidance. Demand clusters in United States ambulatory surgery centers and German hospital outpatient departments where AI-enhanced platforms reduce inter-observer variability in CIN grading.
- HPV DNA Testing Platforms:Automated nucleic acid extraction and amplification systems process high-throughput screening volumes. Pathology laboratories in China and India are scaling installed bases to meet WHO elimination coverage targets, compressing capital recovery timelines through reagent rental agreements.
- Biopsy Devices:Disposable punch and endocervical curettage instruments for histological specimen collection.
- Cryotherapy Instruments:Nitrous oxide or carbon dioxide-based ablation systems for CIN 1-2 lesion destruction in low-resource settings.
- Loop Electrosurgical Units:High-frequency excision devices for large-loop excision of the transformation zone procedures.
- Laser Systems:CO2 laser platforms for precision ablation of high-grade lesions with minimal thermal spread.
Colposcopes lead volumes today; HPV DNA Testing Platforms are gaining share fastest.
Application:
Reimbursement pathways split between preventive screening codes and therapeutic intervention procedures, shaping margin structures across the care continuum.
- Early Screening:Population-based detection of asymptomatic cervical abnormalities through cytological or molecular methods. National programs in India and Brazil are shifting from opportunistic to organized protocols, creating sustained procurement demand for high-throughput testing infrastructure.
- Lesion Treatment:Ablative or excisional interventions for confirmed CIN 2+ lesions including cryotherapy, LEEP, or laser conization. United States federally qualified health centers are expanding treatment capacity to reduce loss-to-follow-up rates between screening and therapeutic intervention.
- Follow-up Care:Surveillance protocols for patients post-treatment or with persistent HPV infection requiring repeat colposcopy.
- Risk Assessment:Extended HPV genotyping and biomarker stratification to refine colposcopy referral thresholds.
- Patient Monitoring:Longitudinal tracking of cervical cytology changes in immunocompromised or persistent infection populations.
Early Screening commands the largest addressable base; Lesion Treatment delivers the highest per-procedure revenue capture.
End User:
Customer concentration varies by workflow complexity, from specialized gynecology practices performing colposcopy to centralized laboratories handling molecular diagnostics at scale.
- Pathology Laboratories:High-volume processing centers managing cytology and molecular testing for regional screening networks. Laboratory chains in the United States and hospital-affiliated networks in France are consolidating procurement through multi-year reagent supply agreements.
- Gynecologists:Specialist physicians performing colposcopy, biopsy, and outpatient treatment procedures. Private practice networks in Germany and hospital-based departments in South Korea are adopting digital colposcopy platforms with integrated AI decision support.
- Diagnostic Centers:Independent facilities offering screening and preliminary assessment services without therapeutic capacity.
- Women's Health Clinics:Primary care settings providing screening and basic gynecological services in community health contexts.
Pathology Laboratories anchor molecular testing volumes; Gynecologists control the therapeutic decision gateway.
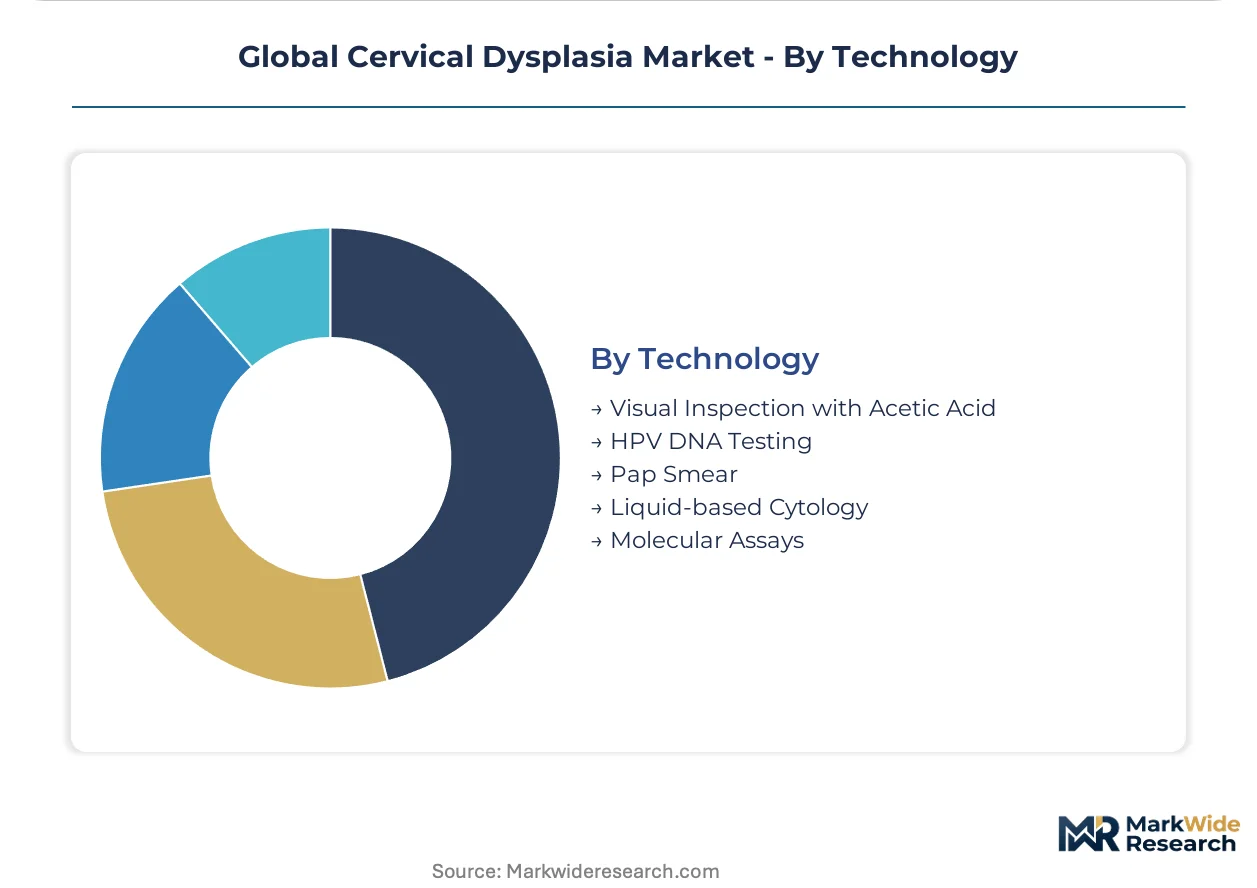
Technology:
Performance tiering separates gold-standard molecular methods from rapid visual techniques suited to resource-constrained deployment.
- HPV DNA Testing:Nucleic acid amplification detection of high-risk oncogenic HPV strains with superior sensitivity for CIN 2+ lesions compared with cytology. National screening programs in Australia and the Netherlands have adopted primary HPV testing protocols, displacing conventional Pap smear workflows.
- Molecular Assays:Extended genotyping panels and mRNA-based biomarker tests for risk stratification beyond binary HPV detection. Regional networks in South Korea and Italy are modularizing testing menus to refine colposcopy referral thresholds.
- Liquid-based Cytology:Automated thin-layer preparation systems improving specimen quality and screening efficiency over conventional smears.
- Pap Smear:Conventional cytology with lower sensitivity but minimal infrastructure requirements for basic screening programs.
- Visual Inspection with Acetic Acid:Low-cost screening method using acetic acid application and naked-eye examination for immediate triage in low-resource settings.
HPV DNA Testing leads clinical adoption; Molecular Assays are climbing the fastest as extended genotyping penetrates risk-stratification protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pathology workforce density varies sharply across geographies, concentrating diagnostic capacity in urban hospital networks while rural districts face specialist shortages that delay screening program scale-up.
United States
Federally qualified health centers are expanding cervical cancer screening capacity to capture IRA-mandated preventive service volumes. FDA 510(k) clearance timelines for novel molecular assays extend 12-18 months when predicate devices lack comparable analytical claims. Laboratory networks in Texas and Florida are consolidating HPV testing procurement through multi-year reagent rental agreements.
Germany
EMA MDR conformity assessment requirements are filtering marginal device entrants from European market access, consolidating procurement with early certificate holders. Notified body fees and post-market surveillance obligations exceed €500,000 for Class IIa diagnostic devices. Hospital outpatient departments in Bavaria and North Rhine-Westphalia are standardizing on AI-enhanced digital colposcopy platforms.
China
National health ministry targets for WHO cervical cancer elimination are driving district hospital procurement of high-throughput HPV DNA testing platforms. NMPA registration pathways for imported molecular diagnostics require local clinical trials, extending market entry timelines. Screening program expansion concentrates in Jiangsu and Zhejiang provinces where pathology laboratory density supports organized population-based protocols.
India
CDSCO medical device rules are harmonizing with international standards for in-vitro diagnostic imports, streamlining registration for established manufacturers. District hospital networks in Maharashtra and Karnataka lack cold-chain logistics for molecular assay storage, creating demand for point-of-care HPV testing platforms. Cytopathologist workforce scarcity in tertiary care centers creates diagnostic bottlenecks that delay treatment initiation.
Brazil
ANVISA regulatory convergence with IMDRF standards is accelerating approval timelines for HPV DNA testing platforms previously cleared by FDA or CE marking. SUS reimbursement expansion for organized screening programs is shifting procurement from opportunistic to population-based models. Diagnostic networks in São Paulo and Minas Gerais are consolidating laboratory infrastructure to capture economies of scale in molecular testing.
Global Cervical Dysplasia Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale-driven instrument manufacturers clash with agile assay developers. The vendor base concentrates around three strategic archetypes: integrated diagnostic platform providers, molecular assay specialists, and point-of-care device innovators. Consolidation pressure intensifies as EMA MDR compliance costs and FDA 510(k) pathway complexity favor balance-sheet capacity. Geographic expansion through distribution partnerships and technology licensing agreements represent the dominant competitive moves.
Within the integrated platform tier, Qiagen N.V., Hologic Inc., and Roche exemplify archetypes spanning molecular assay portfolios, liquid-based cytology systems, and automated diagnostic platforms respectively. These three anchors occupy positions that reflect distinct strategic bets on workflow integration versus assay specialization versus automation scale.
| Leading Market Players |
|---|
| Qiagen N.V. |
| Hologic Inc. |
| Roche |
| Quest Diagnostics |
| Abbott Laboratories |
| BD |
| CooperSurgical Inc. |
| DYSIS Medical Ltd. |
| Micromedic Technologies Ltd. |
| Others |
Supply & Pricing Matrix
Cytopathologist workforce scarcity in Jiangsu province and Maharashtra state generates labor-cost differentials that widen pricing-tier spreads between premium AI-enhanced colposcopy platforms and basic optical systems.
Pricing Analysis
Bundled instrument-service contracts are unbundling as United States integrated delivery networks negotiate enterprise-wide maintenance agreements independent of device vendors. Three-tier pricing structure across premium AI-integrated, standard digital, and economy optical colposcopes reflects certification grade and after-sales service inclusion. Cost compression in the economy tier is intensifying because third-party biomedical engineering teams are replacing manufacturer service networks. Federally qualified health centers exhibit highest price sensitivity; German hospital outpatient departments show lowest sensitivity due to MDR-driven consolidation with early certificate holders.
Supply Chain Analysis
Biomedical engineering talent pools in Germany, the United States, and China constrain manufacturing scale-up for precision optical components. Polymerase enzymes for HPV DNA testing workflows draw from limited supplier bases in Germany and the United States, while digital imaging sensors source from East Asian semiconductor foundries. Single-source vulnerability in probe chemistry supply exposes laboratories to allocation constraints. Distribution runs through regional laboratory networks that consolidate procurement through multi-year reagent rental agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on the shift from liquid-based cytology consumables toward higher-margin molecular assay reagents, compressing per-test costs while capturing premium pricing for extended genotyping panels.
For Market Incumbents: Anchor market position through early MDR certificate acquisition to lock out competitors still navigating notified body queues. Deepen backward integration into probe chemistry manufacturing to reduce exposure to German and United States supplier concentration. Self-sampling device substitution threatens clinician-administered cytology volumes; counter through integrated HPV-to-treatment workflow platforms that capture follow-on procedure revenue.
For New Entrants and Emerging Players: Capture white-space opportunity in rural Indian district hospitals lacking cold-chain logistics for molecular assay storage. Target point-of-care HPV testing platforms with smartphone-connected readers for sub-Saharan African markets where laboratory density remains insufficient. Pursue technology licensing agreements with established manufacturers to bypass extended FDA 510(k) review timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play point-of-care device innovators with CRISPR-based detection platforms. Long-term viability over the projection horizon favors assay developers with WHO prequalification status for low- and middle-income country procurement eligibility. Monitor CDSCO registration pathway harmonization as the signal indicating accelerated market entry for import-dependent Indian diagnostic networks.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Early MDR certificate acquisition locks out competitors in German hospital networks. |
| Hospital System Partnership | Multi-year reagent rental agreements with United States laboratory chains secure instrument placement. |
| Software Companion Development | AI-enhanced colposcopy decision support reduces inter-observer variability in CIN grading. |
| Reimbursement Strategy | IRA preventive services mandate coverage expansion stimulates volume in federally qualified health centers. |
| FDA Submission | Predicate device analytical performance claims determine 510(k) review timeline duration. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Brazil, with primary inputs from each market cluster combined with secondary validation. Interviews with pathology laboratory directors, gynecology department heads, biomedical engineers, and GPO contracts managers informed demand-side dynamics. Secondary sources include FDA 510(k) filings, EMA MDR technical documentation databases, CDSCO registration records, ANVISA approval timelines, and CMS Medicare reimbursement data. Bottom-up instrument placement estimates and top-down national screening program budgets were triangulated to derive market sizing.
Rate-of-change decomposition across the analysis window separates volume growth from pricing dynamics and mix shifts toward molecular assays. Segmentation dimensions modeled include product type, application, end user, technology, and regional regulatory framework. CAGRs were derived from installed base expansion trajectories and reagent throughput per instrument. Forecast inputs incorporate WHO elimination target coverage benchmarks and national health ministry procurement timelines.
Regulatory approval delays, reagent supply disruptions, and cytopathologist workforce pipeline constraints are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about screening program scale-up continuity and reimbursement stability. Material deviation in MDR conformity assessment timelines or HPV testing platform substitution rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Donor Egg IVF Services Market
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
Ovum Egg Banking Market
Reproductive Health
Fertility Treatments Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market
Reproductive Health
Surrogacy Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
US Birth Centers Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Egg Freezing and Embryo Banking Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
Egg Donation Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
Assisted Reproductive Technology (ART) Market