
 France Wound Care Market | 2026-2036
France Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
France Wound Care Market Insights
Home care providers is redrawing procurement patterns across the France wound care landscape, pulling volume away from traditional hospital purchasing. Smith & Nephew plc anchors its position through specialized negative pressure systems for post-acute settings. Mölnlycke Health Care leverages its Nordic manufacturing scale to supply hydrofiber dressings through French distribution networks. Urgo Medical dominates local channel relationships with pharmacy and clinic partnerships that sustain recurring revenue streams.
Wound care encompasses the clinical management of acute and chronic tissue injuries through dressings, devices, and biologic interventions, typically measured by exudate absorption capacity, moisture vapor transmission rate, and bacterial barrier performance to accelerate healing and prevent infection. Advanced dressings command premium positioning due to antimicrobial silver ion release and hydrogel matrix technologies that shorten closure timelines. Chronic wound applications generate durable demand cycles tied to diabetic foot ulcer and venous leg ulcer prevalence, while traditional dressings occupy commoditized volume segments with thinner margin profiles.
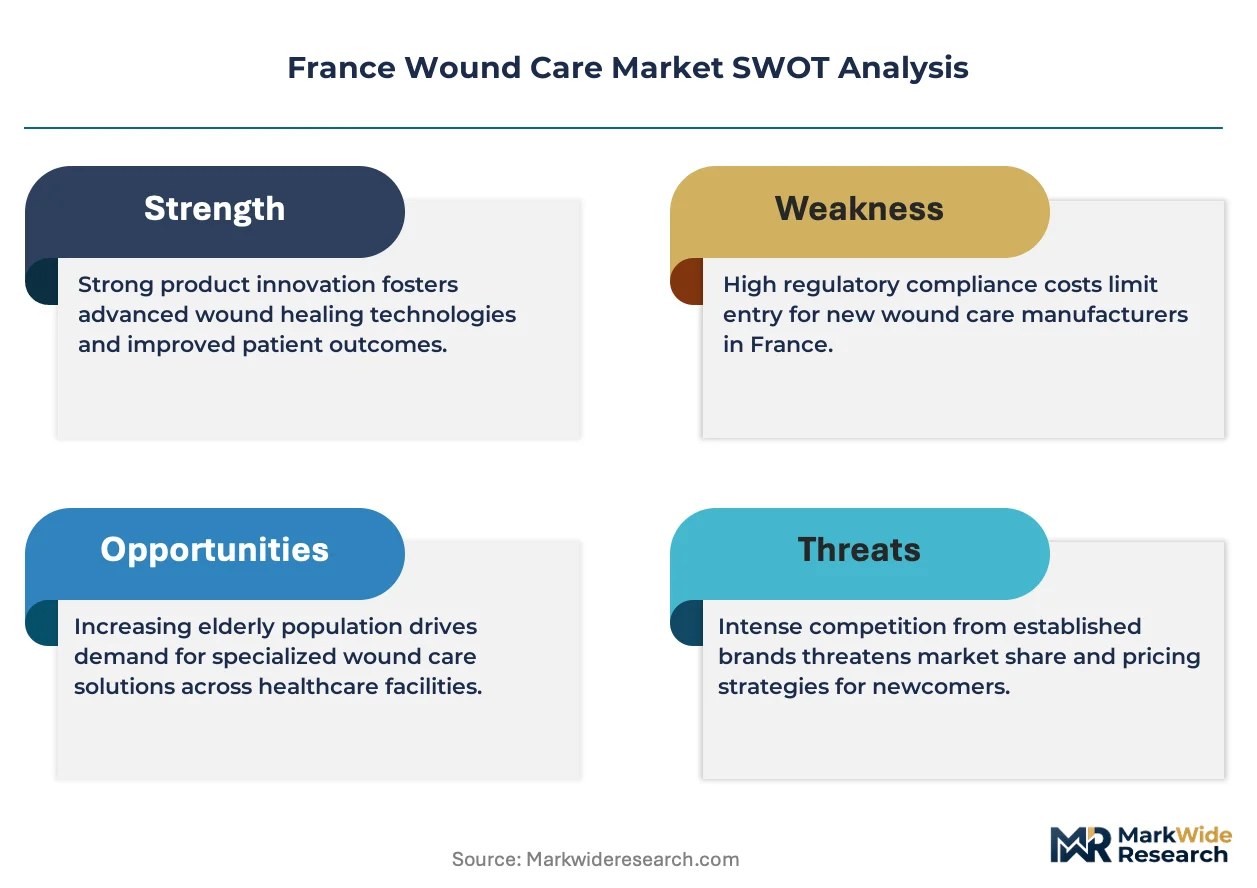
ANSM oversees medical device registration and post-market surveillance for wound care products distributed in France, enforcing CE marking under the EU MDR framework that elevates clinical evidence requirements for biologic and active dressings. EMA guidelines on advanced therapy medicinal products intersect with wound care biologics, creating layered compliance pathways that filter market entrants. Stakeholders must monitor reimbursement shifts under France's national health insurance system as outpatient wound protocols expand and pressure hospital procurement budgets.
Market Dynamics
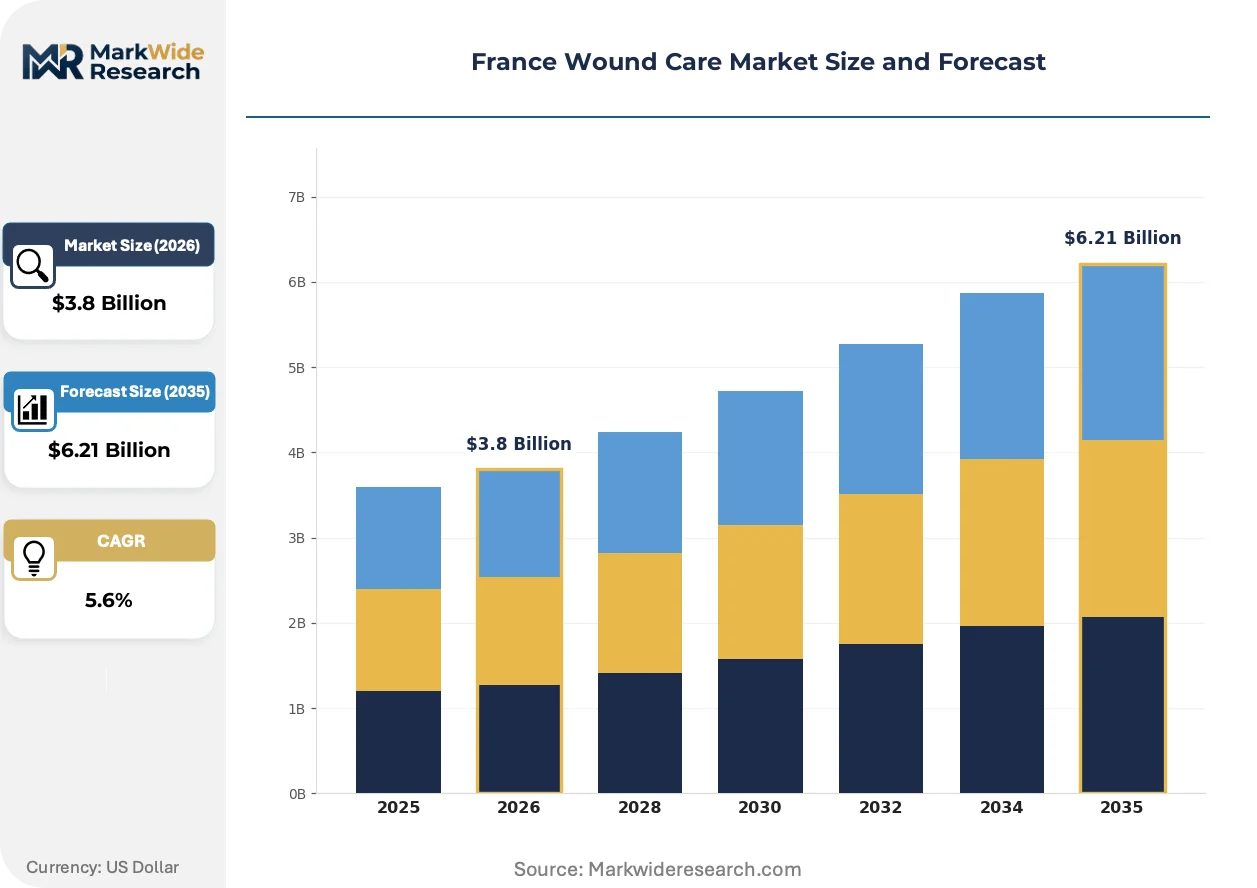
France's wound care market is restructuring around the migration of chronic wound management from inpatient wards to hospital-at-home programs, with Île-de-France's regional health agencies coordinating procurement through centralized purchasing platforms that bypass traditional hospital supply chains.
Growth Catalysts
- EU MDR clinical evidence requirements:Elevated standards for biologic dressings are filtering out marginal competitors and consolidating procurement around certified suppliers with robust technical files.
- Hospital-at-home expansion:French regional health agencies are reimbursing advanced negative pressure therapy delivered in domiciliary settings, extending treatment access beyond acute care boundaries.
- Hydrofiber matrix adoption:Home care nurses are selecting dressings with superior exudate management for diabetic foot ulcers, reducing dressing change frequency and lowering total episode costs.
Market Restraints
- Silver ion input volatility:Antimicrobial dressing manufacturers face fluctuating costs for silver-based compounds sourced from concentrated European chemical suppliers.
- Biologic graft supply concentration:Human-derived tissue substitutes depend on a limited network of French tissue establishments regulated by ANSM, creating single-source vulnerability for advanced wound biologics.
- CE marking timeline friction:EU MDR transition deadlines are extending certification cycles for novel active dressings, delaying market entry for innovative products.
Strategic Opportunities
- Occitanie region underpenetration:Rural wound care access gaps in southwestern France present white space for mobile clinic networks equipped with portable negative pressure devices.
- Telemedicine-integrated dressing systems:Convergence of wearable moisture sensors with remote monitoring platforms enables proactive intervention before wound deterioration.
- Pharmacy channel expansion:French community pharmacies are securing reimbursement codes for chronic wound supply dispensing, creating direct-to-patient revenue streams outside hospital procurement.
Industry Challenges
- Specialized wound care nurse scarcity:French regional health agencies report insufficient trained personnel to staff expanding hospital-at-home programs, constraining service rollout velocity.
- Legacy EHR integration complexity:Wound imaging and measurement tools must interface with heterogeneous hospital information systems across France's public and private care networks, delaying deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Wound Care Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Gels, Adhesives, Antiseptics End User: Hospitals, Clinics, Home Care, Nursing Facilities Application: Chronic Wounds, Surgical Wounds, Burn Care, Traumatic Wounds Technology: Advanced Dressings, Traditional Dressings, Negative Pressure Wound Therapy, Biologics |
| Companies Covered | Coloplast A/S, Mölnlycke Health Care, Smith & Nephew plc, 3M Company, Paul Hartmann AG, ConvaTec Group PLC, Medtronic PLC, Urgo Medical, Solventum Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Wound Care Market Trends and Innovations
Digital wound assessment tools and smart dressing technologies are compressing the feedback loop between clinical observation and intervention decisions, while regulatory convergence around EU MDR is reshaping competitive entry barriers across the French market.
Negative pressure wound therapy systems with integrated exudate volume monitoring are supplanting conventional manual dressing protocols in French post-acute care settings. Home care providers in the Île-de-France region are adopting these systems at accelerating rates for venous leg ulcer management. This technology shift is enabling remote patient monitoring revenue models while compressing margins for traditional dressing suppliers dependent on high-frequency change cycles.
ANSM's enforcement of EU MDR post-market surveillance requirements is elevating clinical data collection obligations for antimicrobial dressings containing silver ions. French manufacturers must now maintain systematic safety registries that track adverse events across distributed care settings. Active dressing categories face the steepest compliance burden, with smaller suppliers exiting rather than absorbing expanded quality management system costs.
Centralized purchasing consortia operated by French regional hospital groups are consolidating vendor relationships for advanced wound care products. Traditional distributor intermediaries are losing position as these consortia negotiate direct supply agreements with manufacturers of hydrofiber and alginate dressings. This concentration is most visible in the Provence-Alpes-Côte d'Azur region, where three hospital groups now control the majority of chronic wound dressing procurement volume.
France Wound Care Market Segmentation
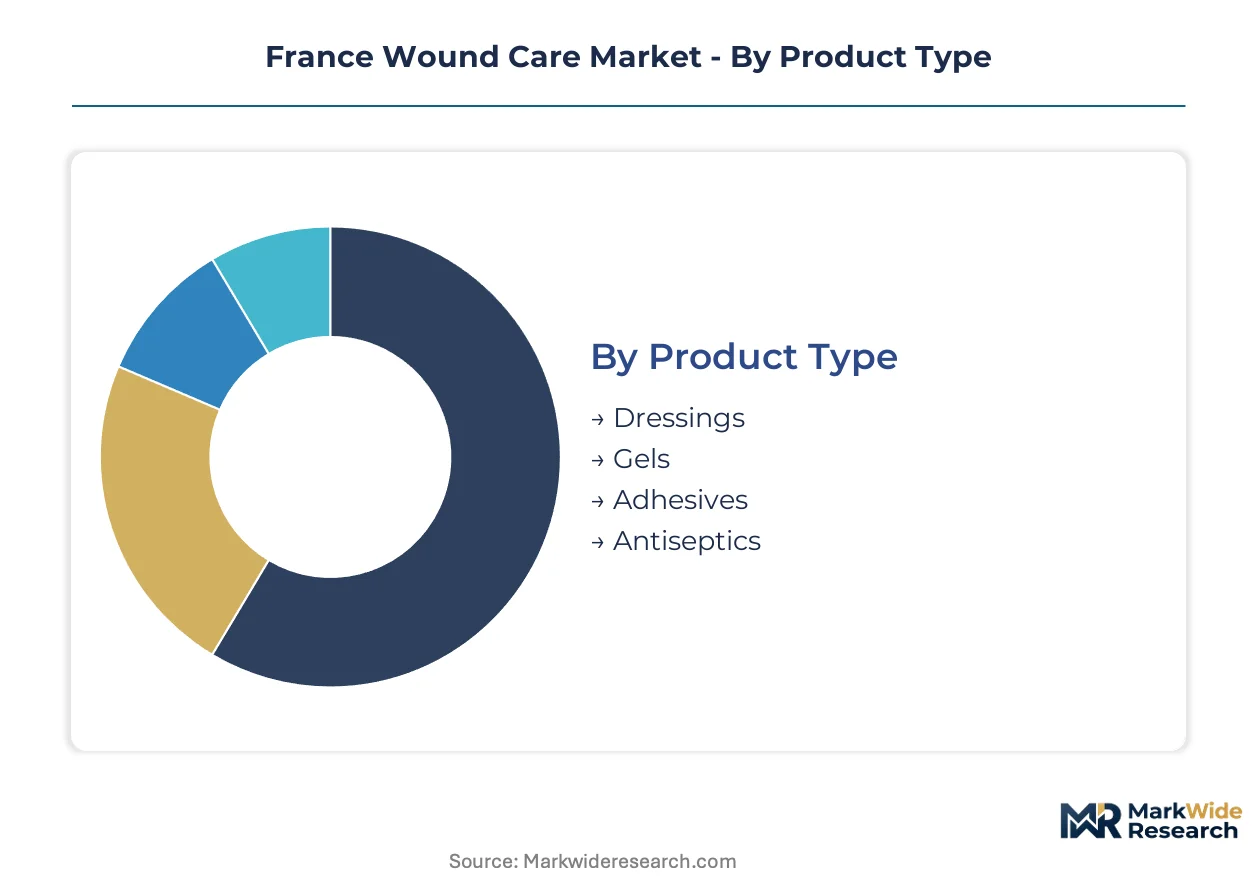
Segmentation in the France wound care market reveals how procurement authority is migrating from acute care facilities toward outpatient and domiciliary channels. Understanding these divides exposes where substitution pressures and margin compression concentrate most intensely.
Product Type:
Dressings face the most acute substitution threat as advanced materials displace conventional gauze and tape combinations across French reimbursement protocols.
- Dressings:Hydrofiber and alginate variants absorb exudate through ionic exchange mechanisms, with home care nurses in Île-de-France selecting these for diabetic foot ulcer protocols to reduce change frequency. ANSM's post-market surveillance requirements now mandate adverse event tracking for antimicrobial silver-releasing variants, elevating compliance costs for smaller suppliers.
- Gels:Hydrogel matrices maintain moist wound environments through controlled vapor transmission, finding concentrated demand in burn units at Paris-area hospitals where eschar management protocols prioritize hydration. The shift toward outpatient burn care is extending gel procurement into pharmacy channels with direct patient dispensing.
- Adhesives:Silicone-based medical adhesives secure dressings across fragile skin surfaces common in elderly populations.
- Antiseptics:Iodine and chlorhexidine solutions remain staple infection prevention agents in emergency departments.
Dressings anchor the volume base while gels gain share at the steepest rate as outpatient protocols expand.
End User:
Cost tier stratification separates capital-intensive hospital purchasing from leaner home care procurement budgets that dominate volume growth.
- Hospitals:Academic medical centers in Lyon and Marseille maintain centralized purchasing for negative pressure systems and biologic grafts, with procurement committees prioritizing total episode cost metrics over unit pricing. EU MDR technical file requirements are filtering vendor pools toward established CE-marked suppliers with robust clinical evidence packages.
- Home Care:Hospital-at-home programs in the Provence-Alpes-Côte d'Azur region coordinate dressing procurement through regional health agency platforms, bypassing traditional distributor markups. Reimbursement expansion for domiciliary negative pressure therapy is accelerating device placement in patient residences.
- Clinics:Specialized wound centers concentrate advanced dressing consumption for chronic ulcer management.
- Nursing Facilities:Long-term care operators face pressure ulcer prevention mandates driving routine dressing turnover.
Hospitals retain the premium tier while home care expands most quickly as regional agencies consolidate outpatient purchasing.
Application:
Volume concentration in chronic indications creates durable demand cycles that contrast with episodic surgical wound consumption.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers generate recurring dressing demand through multi-month healing trajectories, with prevalence concentrated in aging populations across Occitanie and Auvergne-Rhône-Alpes. Telemedicine monitoring integration is enabling proactive intervention before deterioration drives hospital admission.
- Surgical Wounds:Post-operative incision management follows standardized protocols in public hospital networks, with procurement volume tied to elective procedure scheduling that fluctuates with seasonal capacity constraints.
- Burn Care:Specialized centers in Paris and Lyon manage severe thermal injuries with biologic and synthetic skin substitutes.
- Traumatic Wounds:Emergency department presentation drives acute demand for hemostatic dressings and antimicrobial barriers.
Chronic wounds anchor the volume base while surgical applications face margin pressure from standardization.
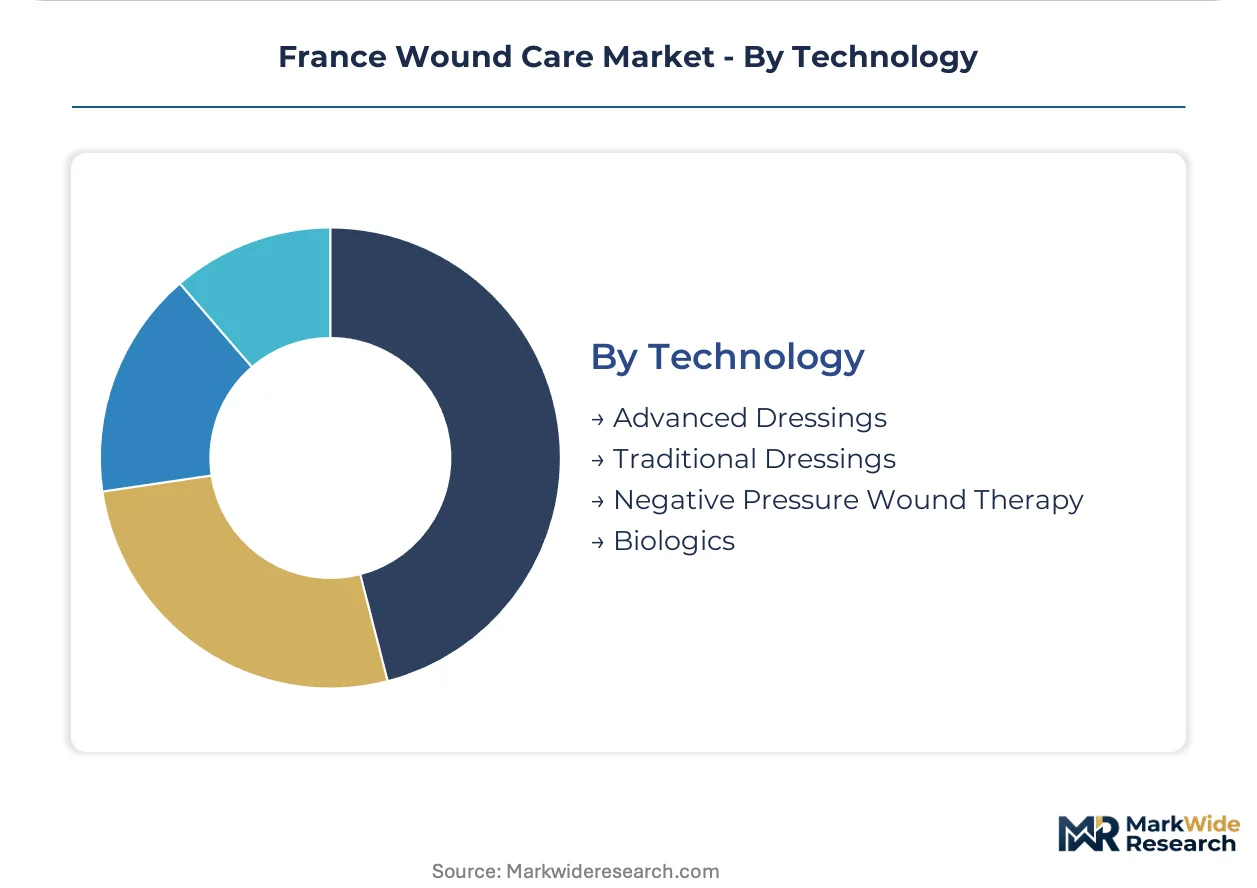
Technology:
Supply concentration among certified manufacturers creates tiered access where advanced categories face steeper entry barriers than commoditized alternatives.
- Advanced Dressings:Silver ion-releasing and hydrofiber technologies command premium positioning through demonstrated healing acceleration, with ANSM enforcement of EU MDR clinical evidence requirements consolidating procurement around suppliers with systematic post-market surveillance registries.
- Negative Pressure Wound Therapy:Portable systems with integrated exudate monitoring are supplanting manual protocols in French post-acute settings, with Île-de-France home care providers adopting at accelerating rates for venous leg ulcer management.
- Traditional Dressings:Gauze and basic adhesive strips occupy commoditized segments with thinner margins.
- Biologics:Human-derived tissue substitutes depend on limited French tissue establishment networks regulated by ANSM.
Traditional dressings anchor the volume base while negative pressure systems gain share at the steepest rate through hospital-at-home expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Île-de-France region anchors France's wound care distribution network through Paris Charles de Gaulle Airport's pharmaceutical cold-chain infrastructure and the dense hospital-at-home program concentration across the metropolitan area.
Île-de-France
Hospital-at-home programs in Paris and inner suburbs coordinate advanced dressing procurement through regional health agency platforms, bypassing traditional distributor networks. ANSM's post-market surveillance requirements for antimicrobial dressings concentrate compliance expertise in this administrative center. The concentration of specialized wound clinics in the Paris metropolitan area drives premium product consumption.
Auvergne-Rhône-Alpes
Lyon's cluster of academic medical centers maintains centralized purchasing for biologic grafts and negative pressure systems, with procurement committees prioritizing total episode cost metrics. Regional health agencies here pilot telemedicine-integrated wound monitoring for rural access extension. The Grenoble-Chambéry corridor hosts medical device distribution hubs serving Alpine home care networks.
Provence-Alpes-Côte d'Azur
Three hospital groups now control the majority of chronic wound dressing procurement volume through centralized purchasing consortia, displacing traditional intermediaries. The region's elderly demographic concentration drives durable demand for pressure ulcer prevention protocols. Marseille's port infrastructure facilitates import logistics for hydrofiber raw materials.
Occitanie
Rural wound care access gaps across southwestern France present expansion opportunities for mobile clinic networks equipped with portable negative pressure devices. The region's diabetic foot ulcer prevalence exceeds national averages, generating recurring dressing demand through extended healing trajectories. Toulouse's aerospace manufacturing spillover sustains precision medical device fabrication capabilities.
Hauts-de-France
The Lille metropolitan area coordinates cross-border procurement with Belgian hospital networks, creating pricing pressure on French reimbursement benchmarks. Industrial restructuring in the former coal basin has redirected workforce training toward specialized nursing qualifications for wound care. Calais-Dunkirk logistics corridors support distribution to northern European markets.
France Wound Care Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates and specialized wound care pure-plays. The vendor base separates into three tiers: multinational device manufacturers with full portfolio coverage, regional dressing specialists with pharmacy channel dominance, and emerging biologic graft developers with tissue establishment partnerships. Competitive moves center on direct contracting with regional hospital purchasing consortia and backward integration into hydrofiber raw material production.
Among the established tier, Smith & Nephew plc, Mölnlycke Health Care, and Urgo Medical occupy positions that exemplify divergent strategic archetypes. Smith & Nephew plc represents the diversified device manufacturer with negative pressure system specialization. Mölnlycke Health Care exemplifies Nordic manufacturing scale leveraged through French distribution networks. Urgo Medical anchors the local channel relationship model with sustained pharmacy and clinic partnerships. These three patterns illustrate how procurement migration toward home care channels rewards distinct capability configurations.
| Leading Market Players |
|---|
| Coloplast A/S |
| Mölnlycke Health Care |
| Smith & Nephew plc |
| 3M Company |
| Paul Hartmann AG |
| ConvaTec Group PLC |
| Medtronic PLC |
| Urgo Medical |
| Solventum Corporation |
| Others |
Pricing and Supply Chain Analysis
Hydrofiber raw material substitution for traditional cotton gauze is simultaneously shifting procurement geography toward Nordic suppliers and compressing margins for commodity dressing manufacturers unable to absorb ionic-exchange polymer cost premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-marked advanced dressings with ANSM post-market surveillance compliance from basic hospital-contract supplies and pharmacy-channel commoditized variants. Price differentiation rests on certification grade and volume scale, with regional hospital purchasing consortia extracting steepest discounts through multi-year offtake commitments. Cost compression in the economy tier is intensifying because centralized procurement platforms bypass traditional distributor markups. Home care providers exhibit highest price sensitivity due to fixed reimbursement ceilings, while academic medical centers prioritize total episode cost metrics over unit pricing.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for silver-ion compounds and synthetic polymer feedstocks essential to antimicrobial dressing production. Manufacturing concentration centers on Sweden, Germany, and Belgium for hydrofiber matrices, while alginate raw materials draw from French coastal harvesting operations. Single-source vulnerability permeates human-derived tissue substitutes tethered to ANSM-regulated tissue establishments. Distribution runs through pharmaceutical cold-chain infrastructure at Paris Charles de Gaulle Airport, with regional health agency platforms displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as hospital-at-home expansion fragments procurement authority across regional health agencies, creating niches for specialized suppliers with compliance agility and channel flexibility.
For Market Incumbents: Consolidate vendor relationships with Île-de-France and Provence-Alpes-Côte d'Azur regional purchasing consortia before competitive density escalates. Backward integration into hydrofiber raw material production defends margin position against Nordic supply concentration. CE marking technical file investment under EU MDR filters marginal competitors and anchors premium tier access.
For New Entrants and Emerging Players: ANSM fast-track pathways for novel active dressings with abbreviated clinical evidence packages enable accelerated market entry against established surveillance registries. Occitanie rural access gaps present the most penetrable geography for mobile clinic networks with portable negative pressure devices. Direct pharmacy channel partnerships bypass hospital procurement gatekeepers entirely.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wound care pure-plays lacking EU MDR transition completion and regional consortia direct contracts. Long-term viability over the next decade hinges on biologic graft tissue establishment partnerships and software-integrated dressing platforms. Watch telemedicine reimbursement code expansion as inflection indicator for remote monitoring revenue model validation.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical file completion unlocks regional hospital consortia procurement eligibility. |
| Hospital System Partnership | Direct contracting with Auvergne-Rhône-Alpes academic centers secures biologic graft volume commitments. |
| Backward Integration | In-house hydrofiber polymer production insulates margin from Nordic supplier concentration. |
| Software Companion Development | Wearable moisture sensor integration enables proactive intervention revenue models. |
| Reimbursement Strategy | Pharmacy dispensing code acquisition creates direct-to-patient revenue outside hospital procurement. |
Research Methodology
The analysis maps advanced dressings, negative pressure systems, biologic grafts, and traditional supplies, each validated through wound care nurses, hospital procurement committee members, regional health agency contracting officers, and ANSM regulatory affairs specialists. Primary interview insights triangulate against ANSM device registration databases, EU MDR technical file disclosures, French national health insurance reimbursement schedules, and hospital group purchasing consortium contract records. Bottom-up demand modeling across end-user channels converges with top-down market sizing through manufacturer shipment data.
Consistency checks validate volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions include product type, end-user channel, wound application category, and technology tier. CAGRs derive from trend extrapolation adjusted for EU MDR transition friction and hospital-at-home reimbursement expansion velocity. Forecast inputs incorporate diabetic foot ulcer prevalence trajectories and silver ion compound cost volatility assumptions.
Decision-makers should treat outputs as directional under stable reimbursement policy and EU MDR enforcement continuity; material deviation in either would warrant model refresh. Specific risks include ANSM post-market surveillance requirement expansion and regional nurse staffing shortages constraining hospital-at-home rollout. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Surgical Wound Care Market
Wound Care
Wound Closure Devices Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Europe Wound Care Market
Wound Care
Liquid Bandages Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Philippines Wound Care Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
Global Silver Wound Dressing Market
Wound Care
Foam Dressing Market
Wound Care
Moist Wound Dressings Market
Wound Care
Global Active Wound Care Market
Wound Care
Global Negative Pressure Wound Therapy (NPWT) Devices Market
Wound Care
Patch Based Wound Healing Products Market
Wound Care
Autologous Wound Patches Market
Wound Care
Antimicrobial Wound Dressings Market