
 Intrauterine Insemination (IUI) Treatment Market | 2026-2036
Intrauterine Insemination (IUI) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Intrauterine Insemination (IUI) Treatment Market Foresight
The gap between premium and commodity tiers is shifting as high-complexity fertility clinics demand catheter systems with advanced sperm preparation protocols while cost-sensitive homecare segments gravitate toward simplified syringe-based kits. Cook Group Incorporated leverages its deep vertical integration in minimally invasive device manufacturing to sustain pricing power across hospital procurement channels. CooperSurgical Inc. anchors its position through specialized distribution networks that dominate North American fertility clinic supply chains.
Intrauterine insemination treatment encompasses the clinical procedure of depositing washed and concentrated sperm directly into the uterine cavity using a flexible catheter, typically performed during the ovulatory window with sperm prepared through density gradient centrifugation or swim-up techniques to optimize motile sperm concentration. The primary purpose centers on overcoming cervical factor infertility, mild male factor infertility, or unexplained infertility by bypassing the cervix and placing gametes in closer proximity to the fallopian tubes. Catheters and culture media command the deepest margin pools within the product type dimension due to recurring consumable demand and proprietary formulation premiums, while fertility clinics outperform hospitals in procedure volume growth as specialized reproductive endocrinology practices consolidate patient referrals. Conventional IUI retains the largest procedure share among patient-accessible options, though donor sperm IUI is expanding fastest among single women and same-sex couples where regulatory frameworks have liberalized gamete access.
The FDA governs IUI devices and sperm processing materials as Class II medical products requiring 510(k) clearance, while the EU Medical Device Regulation imposes stricter clinical evidence standards on catheter biocompatibility and media sterility validations that reshape manufacturer compliance costs. Health Canada and the TGA in Australia maintain parallel oversight of assisted reproductive technology materials, creating a fragmented but converging standards environment for multinational suppliers. Stakeholders must monitor how evolving reimbursement policies for infertility services across Medicare, Medicaid, and private payers in the United States will reshape patient affordability and clinic investment cycles without explicit volume guarantees.
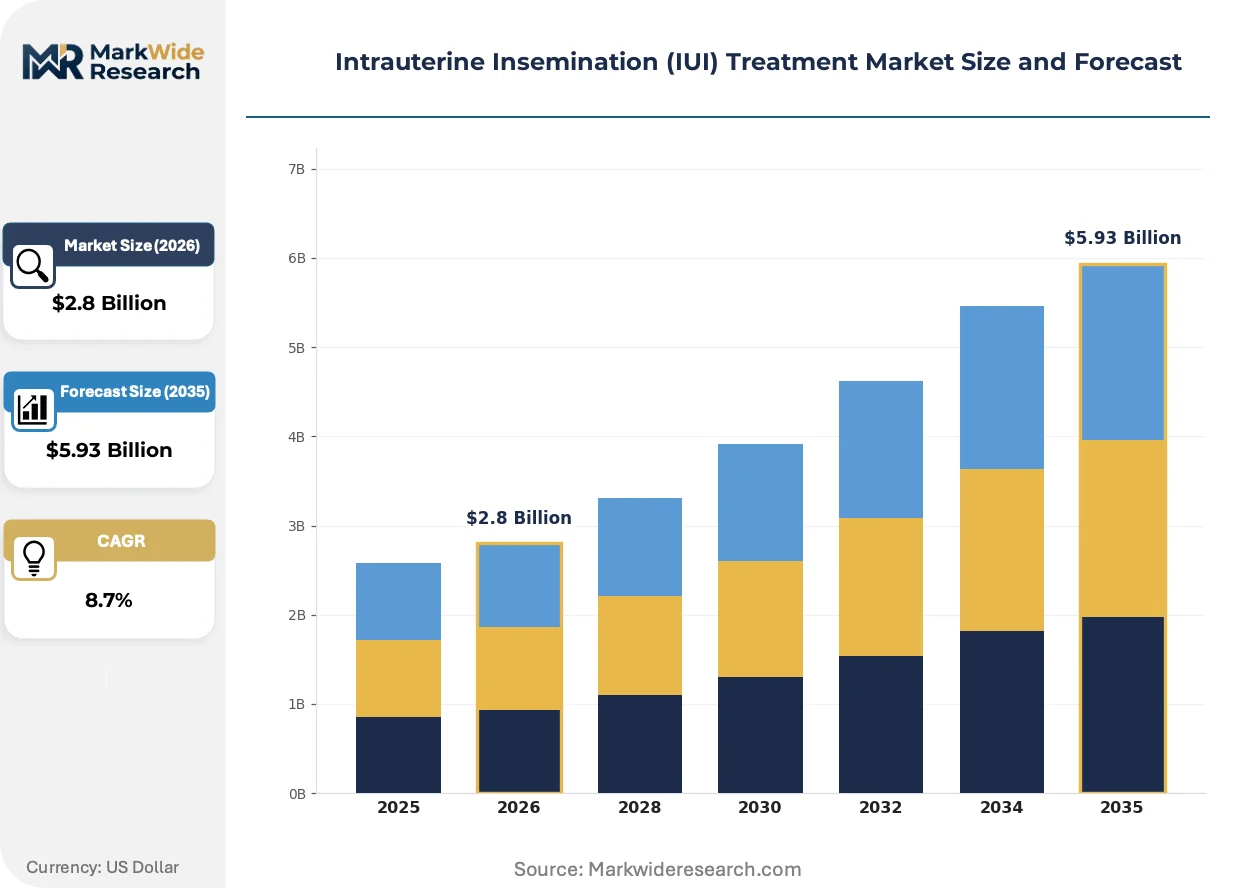
Market Dynamics
Fertility clinics are consolidating patient volumes while demanding catheter systems with integrated sperm preparation protocols, compressing procurement cycles for manufacturers and redrawing competitive boundaries around specialized reproductive endocrinology networks.
Growth Catalysts
- Insurance coverage expansion:United States private payers and state Medicaid programs are broadening infertility benefit mandates, reducing out-of-pocket burdens and accelerating clinic investment in IUI procedure capacity.
- EU Medical Device Regulation (MDR):Stricter clinical evidence requirements for catheter biocompatibility are filtering subscale manufacturers and concentrating supply among validated producers with sterility validation capabilities.
- Density gradient centrifugation:Advanced sperm preparation techniques are improving motile sperm concentration yields, elevating success rates and justifying premium consumable pricing in high-complexity fertility centers.
Market Restraints
- Single-use catheter cost structures:Polymer raw material volatility and ethylene oxide sterilization capacity constraints are squeezing margins for mid-tier manufacturers without captive supply chains.
- Donor sperm regulatory fragmentation:Inconsistent gamete access laws across United States state jurisdictions and European member states create compliance complexity for cross-border fertility tourism.
- Home-based IUI kit limitations:Simplified syringe-based systems lack sperm washing capabilities, capping efficacy and restricting addressable patient populations to cervical factor infertility cases.
Strategic Opportunities
- Same-sex couple and single-woman segments:Liberalized donor sperm access frameworks in Canada, Spain, and Denmark are creating dedicated clinic service lines with tailored counseling and donor matching platforms.
- Telemedicine-integrated monitoring:Remote ovulation tracking and virtual consultation workflows are expanding IUI candidacy screening into underserved rural United States markets without reproductive endocrinology specialists.
- ISO 13485 certification acceleration:Quality management system standardization is enabling emerging market manufacturers to access European and North American procurement channels previously blocked by validation gaps.
Industry Challenges
- Embryologist and andrologist talent pipelines:Specialized reproductive laboratory staffing shortages are constraining clinic procedure throughput and extending patient wait times in high-demand United States metropolitan markets.
- 510(k) clearance timelines:FDA Class II device review backlogs for novel catheter designs are delaying product launches and compressing effective patent life for innovation-dependent manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intrauterine Insemination (IUI) Treatment Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Syringes, Culture Media, Speculum End User: Fertility Clinics, Hospitals, Homecare Settings, Research Institutions Procedure Type: Conventional IUI, Donor Sperm IUI, In Vitro Fertilization IUI, Laparoscopic IUI Patient Type: Infertile Couples, Single Women, Same-Sex Couples, Transgender Individuals |
| Companies Covered | Cook Group Incorporated, CooperSurgical Inc., FUJIFILM Irvine Scientific, Kitazato Corporation, Hamilton Thorne, Rocket Medical PLC, Vitrolife, Prince Medical SAS, Genea Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intrauterine Insemination (IUI) Treatment Market Shifts & Advancements
Digital fertility tracking and at-home diagnostic integration are compressing the interval between initial patient contact and first IUI cycle, while regulatory pressure on device sterility assurance is elevating manufacturing complexity.
Microfluidic sperm sorting technology is expanding into high-volume fertility clinics seeking to replace conventional swim-up methods with automated, standardized motility selection. Reproductive endocrinology practices in Boston and San Francisco are piloting these systems for donor sperm IUI workflows. The shift is expanding into premium service tiers where laboratories can justify capital deployment against improved laboratory efficiency metrics.
The EU Medical Device Regulation's clinical evidence requirements for biocompatibility testing are extending catheter validation timelines and forcing manufacturers to maintain larger safety dossiers. European notified bodies are prioritizing submissions with ISO 10993 series data packages. Smaller manufacturers without dedicated regulatory affairs functions are withdrawing from the European Economic Area rather than absorbing compliance costs.
Patient self-advocacy and direct-to-clinic research are shortening the path from infertility diagnosis to specialist referral. United States fertility networks in Texas and Florida are responding with transparent pricing portals and bundled cycle packages. This behavioral shift is most visible among millennial patients utilizing employer-sponsored fertility benefits who bypass primary care gatekeepers entirely.
Intrauterine Insemination (IUI) Treatment Market Segmentation
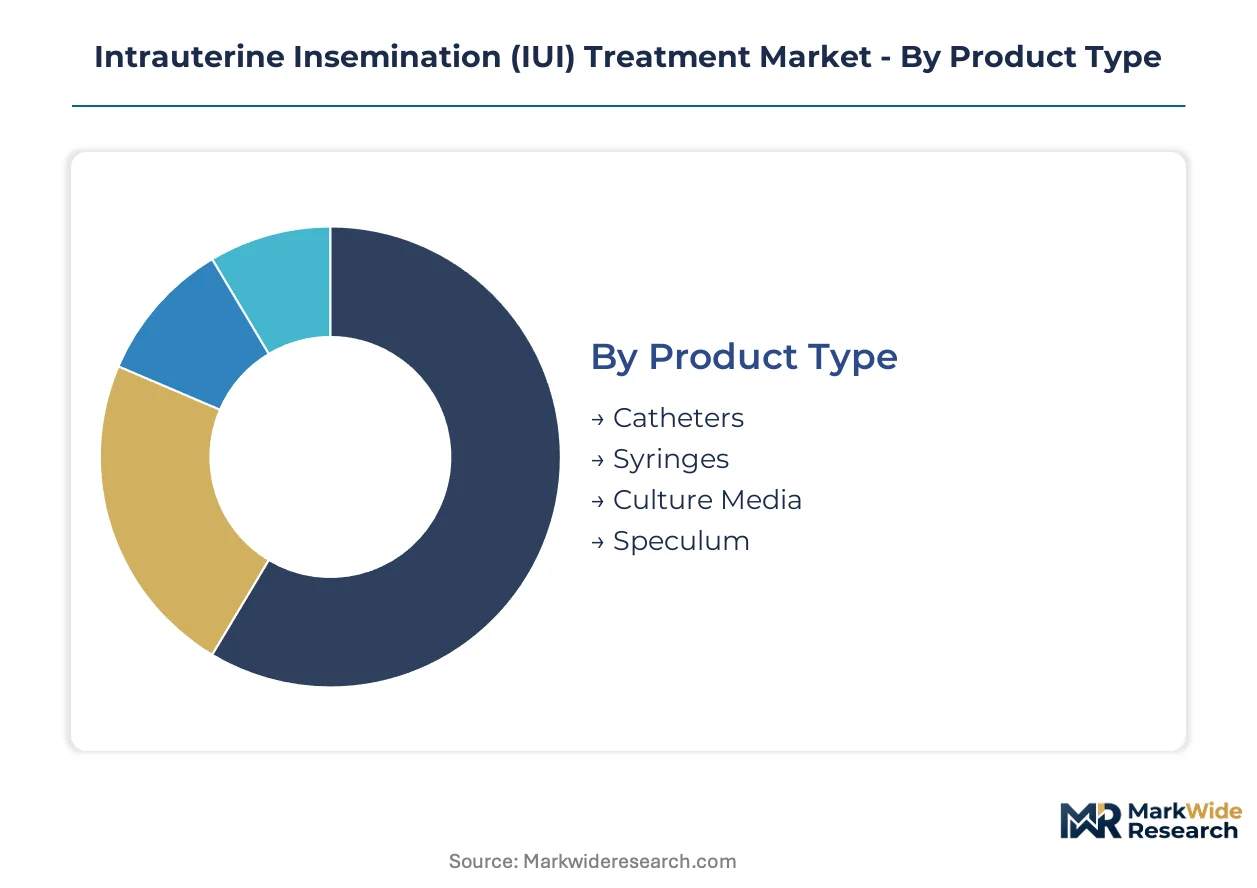
Segmentation in the IUI treatment market reveals how regulatory requirements, clinical complexity, and patient demographics fragment procurement patterns across manufacturers and care settings. Understanding these divides exposes where margin pools concentrate and which segments drive volume expansion.
Product Type:
FDA 510(k) clearance and EU MDR biocompatibility validation requirements vary sharply across these segments, with catheter systems facing the steepest evidentiary burdens while speculum devices navigate lighter Class I pathways.
- Catheters:Flexible polymer delivery systems with proprietary tip geometries dominate high-complexity fertility center procurement. United States reproductive endocrinology networks in Texas and Florida specify integrated sperm preparation compatibility, compressing vendor selection to validated suppliers with captive ethylene oxide sterilization capacity.
- Culture Media:Proprietary buffered formulations for sperm washing and capacitation command recurring consumable revenue streams. European notified bodies under MDR impose expanded sterility validation dossiers on these products, filtering subscale manufacturers from German and Spanish clinic supply chains.
- Syringes:Single-use polypropylene devices for homecare IUI kits face lighter regulatory scrutiny but capped reimbursement.
- Speculum:Standard bivalve examination instruments with minimal differentiation across price tiers.
Catheters sit at the top of the volume ranking, with culture media climbing the fastest.
End User:
Procurement sophistication escalates from homecare direct-to-consumer channels through hospital central supply to fertility clinic specialized buying committees with dedicated reproductive laboratory directors.
- Fertility Clinics:Specialized reproductive endocrinology practices consolidate patient referrals and demand catheter systems with integrated density gradient centrifugation protocols. Boston and San Francisco metropolitan clusters pilot microfluidic sperm sorting workflows, elevating technical specifications above commodity tier.
- Hospitals:General acute care facilities with obstetrics departments perform IUI as ancillary service with lower cycle volumes. Gynecology service lines in United States health systems face pressure from dedicated fertility networks, eroding procedural share despite broader insurance contracting.
- Homecare Settings:Direct-to-patient syringe-based kits lack sperm washing capabilities, restricting addressable populations to cervical factor infertility cases with simplified clinical profiles.
- Research Institutions:Academic medical centers with reproductive biology programs drive protocol innovation but represent minimal commercial volume.
Fertility clinics capture the steepest expansion trajectory, while homecare settings remain constrained by efficacy limitations.
Procedure Type:
Technical complexity and regulatory classification diverge across these modalities, with conventional protocols standardizing fastest and laparoscopic approaches retreating to niche indications.
- Conventional IUI:Transcervical sperm deposition during natural or stimulated cycles retains the largest procedure footprint across accessible care settings. United States clinic networks leverage this standardization for transparent bundled pricing portals targeting employer-sponsored fertility benefit utilization.
- Donor Sperm IUI:Third-party gamete utilization expands fastest among single women and same-sex couples where Canadian, Spanish, and Danish regulatory frameworks liberalized access. Specialized donor matching platforms and counseling service lines differentiate clinic offerings in these segments.
- In Vitro Fertilization IUI:Hybrid protocols bridging IUI and full IVF represent transitional clinical pathways with limited standalone market presence.
- Laparoscopic IUI:Surgical sperm deposition for tubal factor cases has retreated to rare indications with minimal growth momentum.
Conventional IUI maintains volume leadership, with donor sperm IUI gaining share fastest.
Patient Type:
Service line configuration and marketing investment track sharply across these demographics, with fertility clinics developing tailored intake workflows for non-traditional family formation.
- Single Women:Autonomous family planning drives dedicated clinic service lines with donor sperm counseling and legal coordination. Canadian regulatory clarity on gamete access has concentrated specialized provider development in Toronto and Vancouver metropolitan markets.
- Same-Sex Couples:Lesbian couples utilizing donor sperm IUI represent expanding demand segment where Spanish and Danish liberalized frameworks enable cross-border fertility tourism. Clinic networks develop transparent pricing and reciprocal IVF coordination for this population.
- Infertile Couples:Heterosexual couples with male factor or unexplained infertility constitute the traditional core patient base with established clinical pathways.
- Transgender Individuals:Fertility preservation and family formation services for gender-diverse patients require specialized endocrine coordination with emerging protocol standardization.
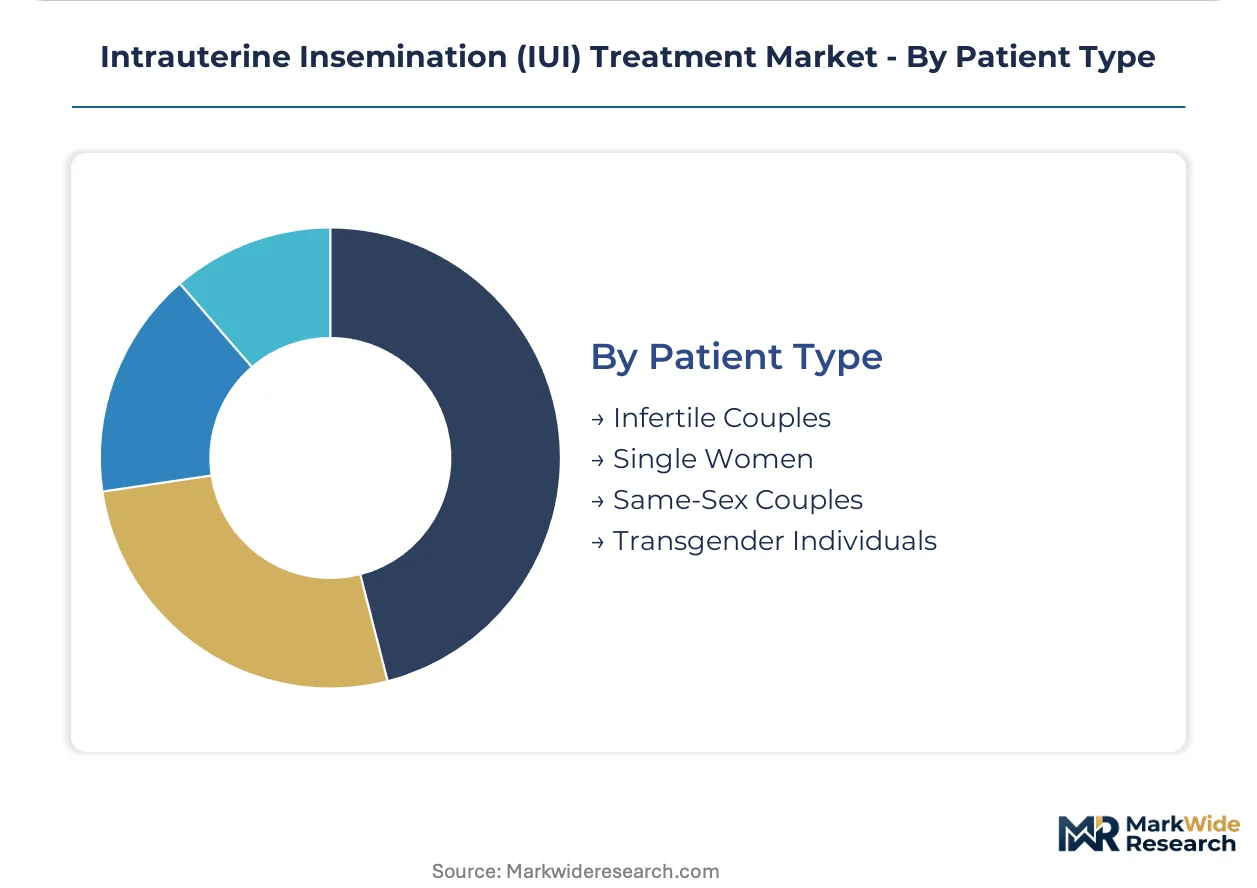
Infertile couples occupy the top volume position, with single women expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reproductive endocrinologists cluster in metropolitan medical centers where fertility networks consolidate patient referrals and drive catheter procurement sophistication. These talent concentrations anchor regional demand patterns across developed healthcare systems.
United States
Employer-sponsored fertility benefits and state Medicaid expansion accelerate clinic investment in IUI capacity. FDA 510(k) clearance requirements for Class II catheters filter device suppliers to validated manufacturers with ethylene oxide sterilization infrastructure. Texas and Florida fertility networks deploy transparent pricing portals that compress patient acquisition cycles.
Germany
Specialized reproductive laboratory staffing shortages constrain clinic throughput despite strong patient demand. EU MDR biocompatibility validation requirements for catheter systems extend regulatory timelines and elevate compliance costs for notified body submissions. Bavarian fertility centers in Munich anchor high-complexity service lines with integrated sperm preparation protocols.
Spain
Liberalized donor sperm access frameworks attract cross-border fertility tourism from restrictive European jurisdictions. EMA oversight of assisted reproductive technology materials converges with national tissue establishment regulations. Barcelona and Madrid clinic networks develop dedicated counseling platforms for single women and same-sex couples.
Canada
Provincial health insurance coverage for infertility services reduces out-of-pocket burdens and expands addressable patient populations. Health Canada parallel review pathways for IUI devices maintain standards alignment with FDA frameworks. Toronto and Vancouver metropolitan markets concentrate specialized provider development with donor matching coordination services.
Australia
TGA oversight of reproductive technology materials imposes sterility validation requirements that reshape manufacturer market access. Urban fertility networks in Sydney and Melbourne consolidate regional patient referrals through telemedicine-integrated monitoring workflows. Remote ovulation tracking expands IUI candidacy screening into underserved rural markets without reproductive endocrinology specialists.
Intrauterine Insemination (IUI) Treatment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across catheter and culture media segments, creating tiered supply dynamics. The vendor base concentrates among validated manufacturers with captive sterilization capacity and specialized distribution networks serving fertility clinic procurement committees. Three archetypes dominate: vertically integrated device conglomerates, reproductive specialty suppliers, and emerging market manufacturers pursuing ISO 13485 certification. Consolidation pressures and regulatory compliance investments drive M&A activity while portfolio diversification into adjacent assisted reproductive technology consumables extends customer lifetime value.
Within the integrated conglomerate tier, Cook Group Incorporated and CooperSurgical Inc. exemplify manufacturers with deep backward integration into polymer processing and sterilization infrastructure. FUJIFILM Irvine Scientific occupies a position bridging diagnostic imaging heritage with reproductive laboratory consumables. These anchors represent divergent strategic postures: medical device lineage versus diversified healthcare portfolio versus imaging-to-biology extension.
| Leading Market Players |
|---|
| Cook Group Incorporated |
| CooperSurgical Inc. |
| FUJIFILM Irvine Scientific |
| Kitazato Corporation |
| Hamilton Thorne |
| Rocket Medical PLC |
| Vitrolife |
| Prince Medical SAS |
| Genea Limited |
| Others |
Supply & Pricing Matrix
Catheter-culture media divergence splits procurement economics between premium fertility center tiers and commoditized homecare segments, with FDA 510(k) clearance tiers and EU MDR biocompatibility dossiers functioning as pricing gatekeepers while ethylene oxide sterilization capacity concentrates supply among validated manufacturers with captive infrastructure.
Pricing Analysis
Bundled cycle packages dominate United States fertility network procurement, while unbundled per-procedure pricing persists in European clinics navigating national reimbursement heterogeneity. Price differentiation rests on sterilization validation tiers and proprietary media formulation IP, with premium catheter systems commanding threefold multiples over commodity syringe-based kits. Cost compression in mid-tier polymer consumables intensifies as ethylene oxide capacity constraints elevate sterilization pass-through costs. Employer-sponsored benefit segments exhibit lowest price sensitivity, while Medicaid-dependent populations and direct-to-consumer homecare buyers drive aggressive vendor negotiation.
Supply Chain Analysis
Polymer resin supply rests on German and United States specialty chemical producers, with catheter-grade silicone and thermoplastic elastomer formulations requiring medical-device-grade certification chains. Ethylene oxide sterilization services concentrate in United States Midwest and Benelux industrial clusters, creating single-source vulnerability for manufacturers lacking captive capacity. Distribution runs through specialized reproductive health distributors in North America and direct hospital system contracts in European national health systems, with fertility clinic buying committees consolidating procurement leverage through multi-year sole-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
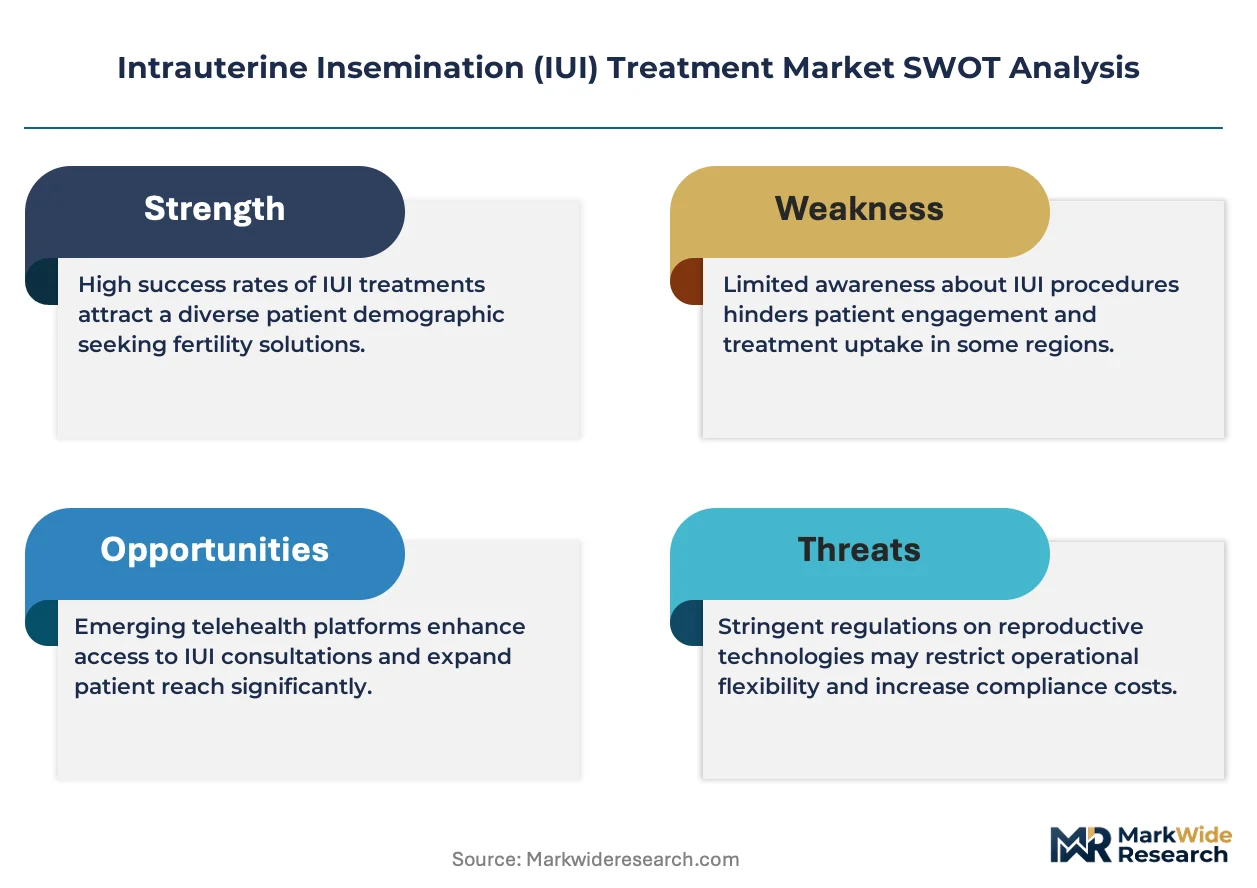
The IUI treatment market compounds regulatory validation burdens into durable competitive moats, with EU MDR clinical evidence requirements and FDA 510(k) backlog timelines accelerating consolidation among manufacturers with dedicated regulatory affairs infrastructure.
For Market Incumbents: Deploy ISO 13485 certification acceleration as a market access lever, extending quality management system standardization into emerging manufacturing geographies to preempt competitor entry. Backward integration into ethylene oxide sterilization capacity insulates margin structures from third-party capacity constraints. Defensive patent clustering around microfluidic sperm sorting interfaces protects against diagnostic technology substitution threats from automated laboratory platforms. For New Entrants and Emerging Players: Fertility clinic group purchasing organizations represent the most penetrable channel archetype, with independent reproductive endocrinology practices in Texas and Florida metropolitan clusters seeking secondary suppliers to diversify sole-source dependencies. Telemedicine-integrated monitoring workflows offer white-space entry points for software-enabled service bundling. Target donor sperm IUI service line development in Canadian and Spanish regulatory jurisdictions with liberalized gamete access frameworks. For Investors and Strategic Acquirers: Consolidation pressure builds where subscale manufacturers face EU MDR compliance cost absorption thresholds exceeding sustainable revenue bases. Long-term viability favors asset-light designers with regulatory dossier libraries over capital-heavy sterilization infrastructure plays. Acquisition target archetypes include ISO 13485-certified emerging market manufacturers with FDA pre-submission pathways and specialized reproductive health distributors with exclusive fertility clinic network relationships. Watch FDA 510(k) review timeline normalization as signal for innovation-dependent valuation recovery.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Biocompatibility validation dossiers filter subscale competitors from German and Spanish clinic supply chains. |
| Telemedicine-Integrated Monitoring Development | Remote ovulation tracking expands IUI candidacy screening into rural United States markets without reproductive endocrinologists. |
| Donor Sperm Service Line Expansion | Specialized counseling platforms capture cross-border fertility tourism from restrictive European jurisdictions into Spain and Denmark. |
| Ethylene Oxide Sterilization Capacity Addition | Captive infrastructure insulates catheter manufacturers from third-party sterilization bottlenecks and polymer raw material volatility. |
| Microfluidic Sperm Sorting Platform Launch | Automated motility selection replaces conventional swim-up methods in Boston and San Francisco high-complexity laboratories. |
Research Methodology
Direct dialogue with reproductive endocrinologists, fertility clinic laboratory directors, medical device regulatory affairs specialists, and group purchasing organization contract managers grounded qualitative insight development. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, hospital procurement contract disclosures, and assisted reproductive technology professional society guidelines. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation across catheter, culture media, and syringe product categories.
Segment-level value outputs emerged from modeling end-user procurement patterns, product type margin structures, and procedure type growth trajectories across the projection horizon. The analytical framework incorporated patient demographic shifts, regulatory framework evolution, and reimbursement policy changes as demand-side drivers alongside manufacturing capacity constraints and raw material cost dynamics on the supply side. CAGRs derived from logarithmic trend fitting across validated historical data points and scenario-weighted forward assumptions.
Revisions become necessary when FDA 510(k) review timeline normalization, EU MDR notified body capacity expansion, or state-level Medicaid infertility benefit rescissions materialize differently than modeled. Forecasts reflect assumptions about sterilization infrastructure investment cycles, embryologist talent pipeline development, and cross-border fertility tourism regulatory stability. A small set of named triggers—FDA review backlog clearance, EU MDR transition deadline enforcement, and employer-sponsored benefit penetration rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Egg Donation Market
Reproductive Health
Global Genital Herpes Treatment Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Contraceptives Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
Fertility Services Market
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Smart Fertility Tracker Market
Reproductive Health
Global Cervical Dysplasia Market
Reproductive Health
Fertility Treatments Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market