
 In Vitro Fertilization (IVF) Market | 2026-2036
In Vitro Fertilization (IVF) Market Size, Share, and Industry Trends Forecast 2026-2036
In Vitro Fertilization (IVF) Market Analytics
Elective fertility preservation among career-focused professionals is bifurcating demand from traditional medical infertility cases. Merck KGaA leverages its pharmaceutical heritage to dominate gonadotropin supply chains across European treatment centers. Thermo Fisher Scientific anchors the laboratory instrumentation layer with integrated genetic analysis platforms. IVIRMA Global extends its clinical network through direct-operated fertility clinics spanning multiple continents.
In vitro fertilization encompasses laboratory-based fertilization of oocytes with sperm outside the body, requiring controlled incubation at 37 degrees Celsius with 5% carbon dioxide and specialized culture media formulations containing glucose, lactate, and pyruvate to support embryo development through blastocyst stage for subsequent uterine transfer. The technology dimension shows time-lapse imaging systems capturing morphokinetic data now commanding premium positioning as clinics compete on live birth rates, while cryopreservation infrastructure underpins elective egg freezing growth among the 30-35 age bracket. End-user concentration favors fertility clinics over hospital settings where operational flexibility and dedicated embryology laboratories concentrate margin capture.
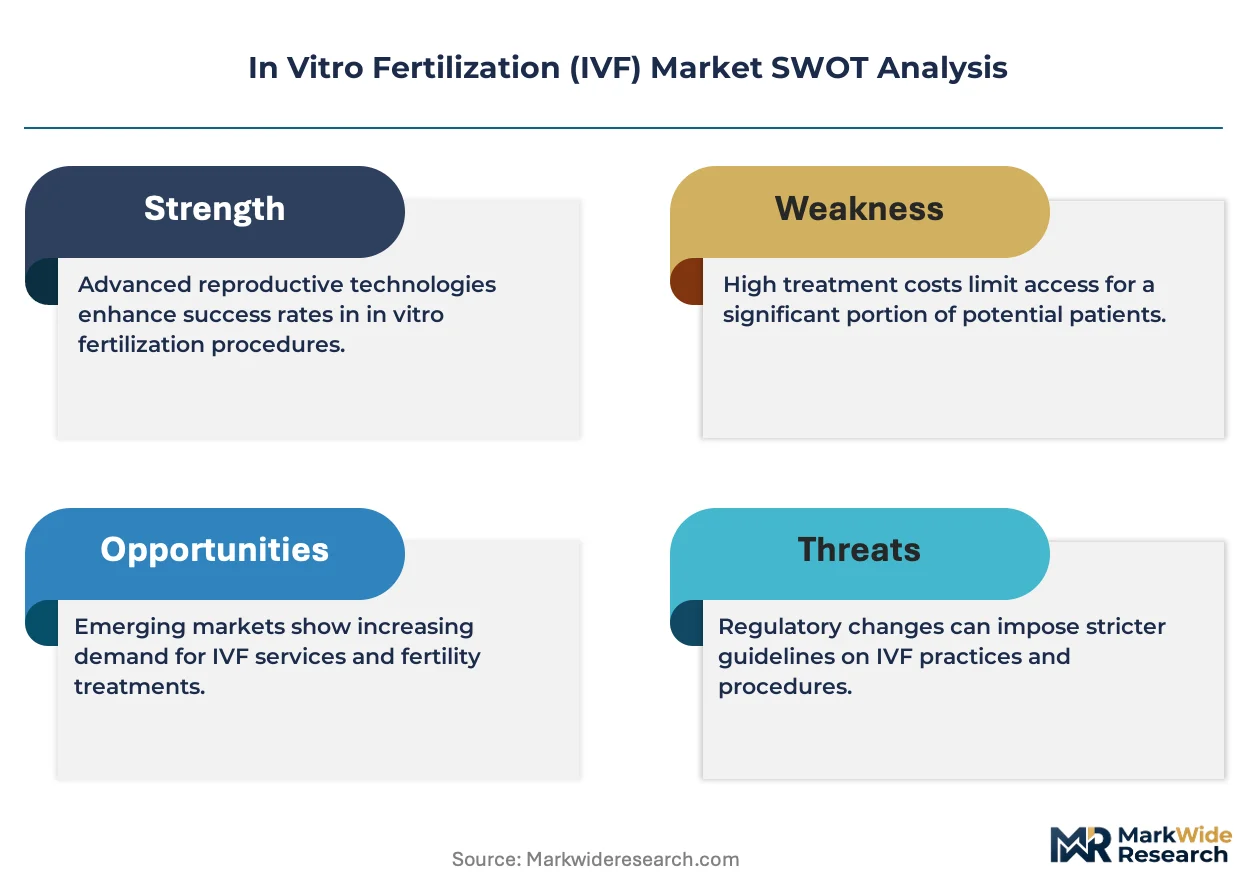
The FDA regulates assisted reproductive technology devices under 21 CFR Part 1271 human cell and tissue regulations while the EMA oversees pharmaceutical adjuncts through centralized marketing authorization procedures, with both agencies intensifying scrutiny of culture media composition and genetic testing validation standards. China's NMPA implements GB standards for medical device registration that foreign manufacturers must navigate for market access alongside evolving population policy incentives. Stakeholders must monitor reimbursement fragmentation across national health systems and private insurance schemes as policy shifts determine addressable patient populations and pricing power.
Market Dynamics
Preimplantation genetic testing and elective fertility preservation are restructuring demand patterns across fertility networks, splitting treatment protocols between medical infertility interventions and proactive reproductive planning among younger patient cohorts. This bifurcation concentrates investment in cryopreservation infrastructure and specialized embryology staffing.
Growth Catalysts
- Delayed childbearing demographics:Career-focused professionals in the United States and Spain are seeking elective egg freezing services, expanding addressable patient pools beyond traditional infertility diagnoses.
- NMPA regulatory modernization:China's streamlined medical device registration pathways for assisted reproductive technology equipment are accelerating foreign manufacturer market entry.
- Time-lapse imaging adoption:Fertility clinics deploy morphokinetic monitoring systems to differentiate on live birth rate performance metrics.
Market Restraints
- Gonadotropin supply concentration:European pharmaceutical sourcing depends on limited recombinant FSH manufacturing capacity, creating vulnerability to production disruptions.
- EMA validation requirements:Strengthened genetic testing platform certification timelines delay new entrant commercialization by 18-24 months.
- Culture media cost volatility:Specialized protein supplement formulations face raw material price instability from bovine serum supply constraints.
Strategic Opportunities
- Underpenetrated Chinese tier-two cities:Provincial fertility centers outside Beijing and Shanghai lack advanced embryology laboratory infrastructure.
- AI-assisted embryo selection:Machine vision algorithms trained on time-lapse image banks converge with existing incubator hardware to automate grading protocols.
- Employer-sponsored fertility benefits:United States corporations expand insurance coverage for IVF cycles as talent retention instruments.
Industry Challenges
- Embryologist training pipeline gaps:Specialized micromanipulation and vitrification certification programs produce insufficient qualified personnel for clinic expansion plans.
- Cleanroom facility capex intensity:ISO 14644 Class 7 laboratory construction and continuous environmental monitoring systems require substantial upfront capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vitro Fertilization (IVF) Market |
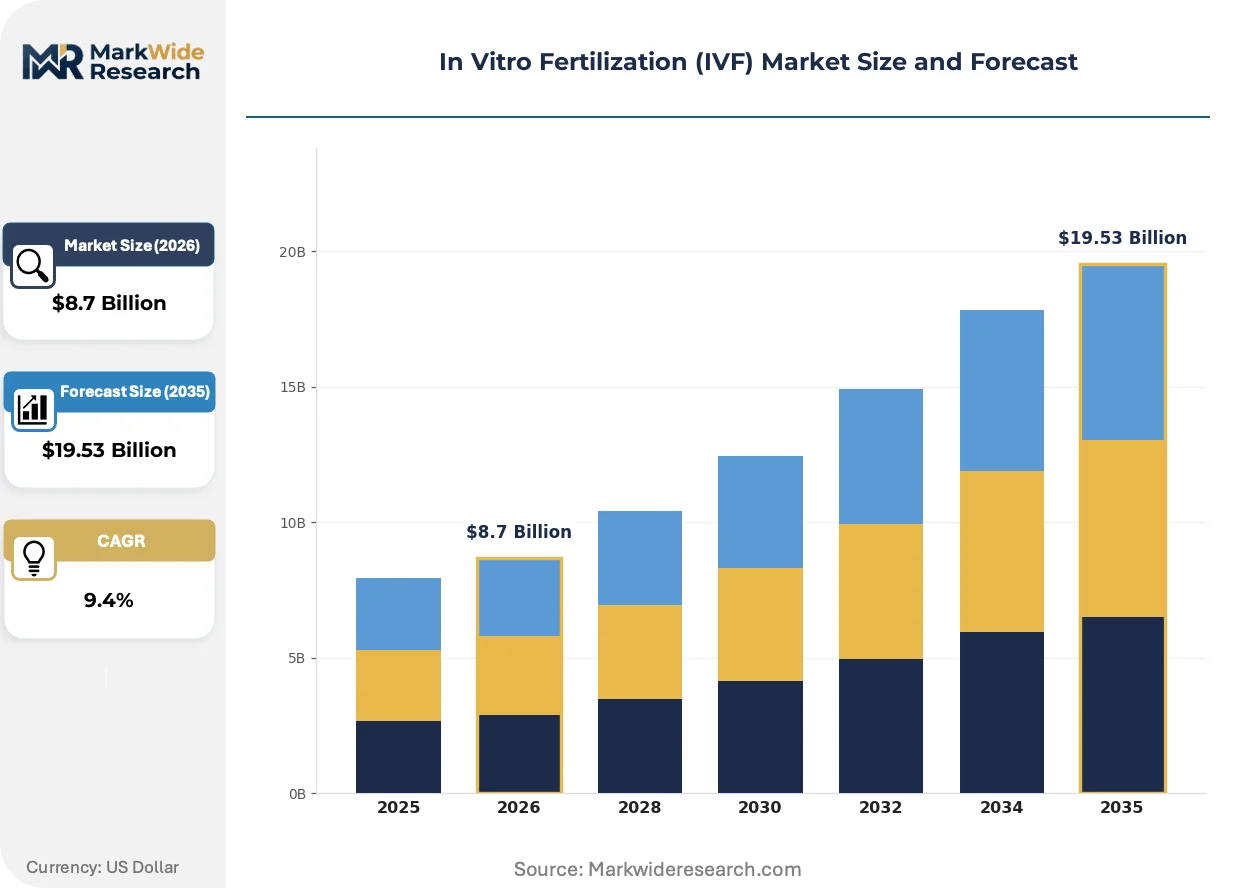
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: ICSI, Conventional IVF, Egg Donation, Frozen Embryo Transfer End User: Fertility Clinics, Hospitals, Research Laboratories, Academic Institutions Technology: Time-Lapse Imaging, Preimplantation Genetic Testing, Cryopreservation, Embryo Culture Media Age Group: Under 30, 30-35, 36-40, Over 40 |
| Companies Covered | CooperSurgical Inc., Vitrolife AB, Cook Medical Inc., Merck KGaA, Thermo Fisher Scientific Inc., FUJIFILM Irvine Scientific, Hamilton Thorne, IVIRMA Global, Monash IVF Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vitro Fertilization (IVF) Market Evolving Landscape
Assisted reproductive technology is experiencing protocol fragmentation as automation, genetic screening depth, and patient-directed care models simultaneously advance. These developments are compressing traditional service delivery timelines while elevating technical complexity requirements.
Time-lapse incubator systems equipped with integrated camera arrays are bifurcating embryo assessment workflows. High-volume fertility clinics in the United States adopt these platforms to reduce manual microscopy labor and standardize morphokinetic annotations. The technology is bifurcating competitive positioning between capital-intensive flagship centers and smaller practices reliant on conventional overnight culture methods.
EMA's tightened oversight of preimplantation genetic testing for aneuploidy validation standards is extending commercialization timelines for new assay platforms. Manufacturers must demonstrate clinical utility through prospective outcome studies rather than retrospective analytic validation. European fertility networks are responding by consolidating purchasing decisions around established IVDR-compliant suppliers with existing clinical evidence portfolios.
Patient financing models are displacing traditional fee-for-service structures in United States fertility markets. Subscription-based multi-cycle packages and refund guarantee programs now dominate patient acquisition channels. This restructuring concentrates most visibly in metropolitan markets where employer fertility benefits and dedicated lending partnerships reduce upfront cost barriers for elective preservation candidates.
In Vitro Fertilization (IVF) Market Segmentation
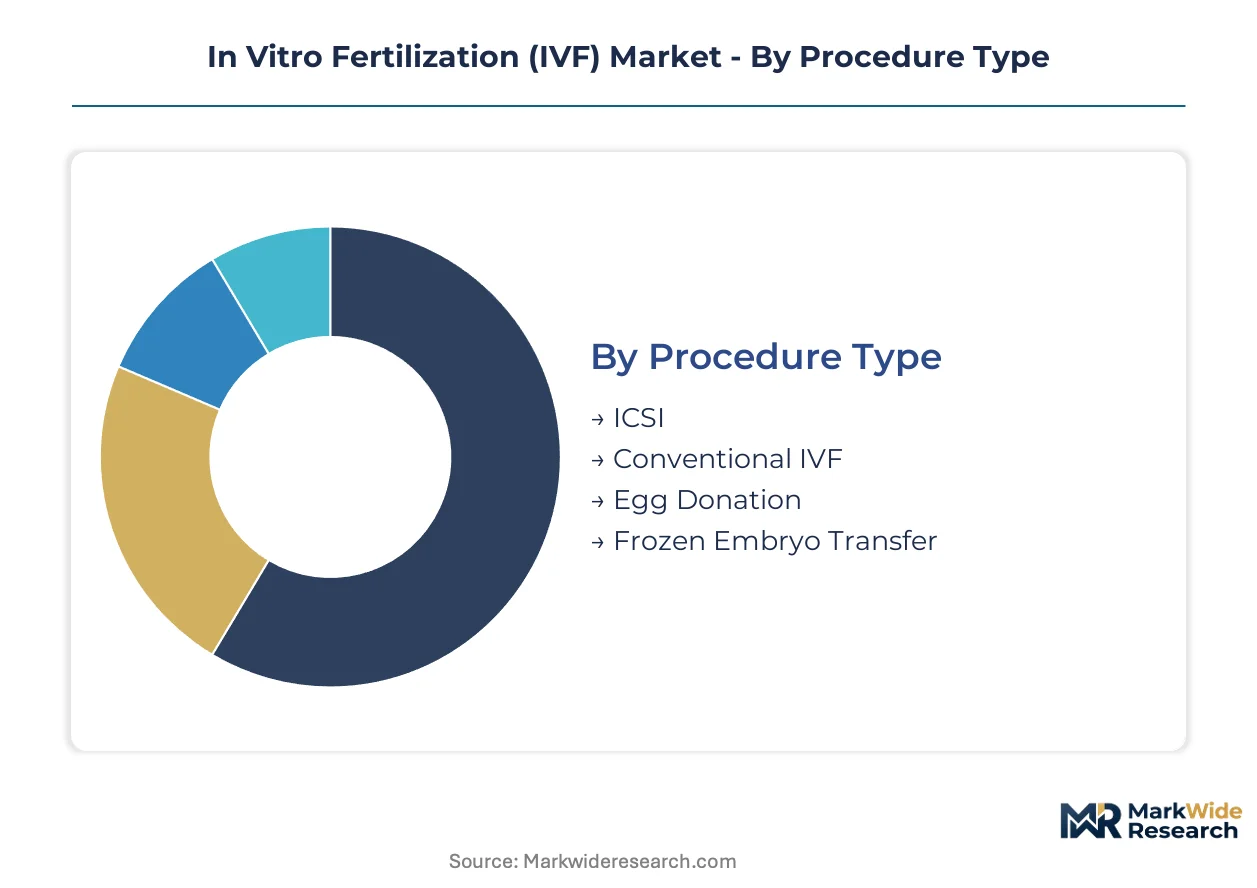
IVF market segmentation reveals how clinical workflows, patient demographics, and laboratory infrastructure investments fragment across distinct operational models. Understanding these divisions exposes where capital deployment concentrates and which patient cohorts drive margin differentiation.
Procedure Type:
Procedure selection determines both reimbursement pathways and pharmaceutical consumption intensity across treatment networks.
- ICSI:Micromanipulation technique injecting single sperm directly into ooplasm addresses male factor infertility with higher gonadotropin requirements per cycle. United States fertility clinics deploy ICSI in over two-thirds of fresh cycles as standard protocol regardless of semen parameters, expanding consumable revenue per patient.
- Conventional IVF:Standard insemination placing oocytes and sperm together in culture medium without micromanipulation remains cost-efficient for tubal factor and unexplained infertility cases. Spanish treatment centers preserve conventional IVF for younger patient cohorts with favorable prognoses, limiting laboratory labor intensity.
- Egg Donation:Third-party oocyte recruitment protocols involve synchronized donor-recipient cycles with specialized legal and psychological screening infrastructure.
- Frozen Embryo Transfer:Cryopreserved embryo warming and uterine placement decouples ovarian stimulation from transfer timing, enabling elective scheduling and improved endometrial preparation.
ICSI dominates installed base. Frozen Embryo Transfer is where expansion concentrates.
End User:
Facility type shapes capital intensity, staffing models, and regulatory exposure across the service delivery landscape.
- Fertility Clinics:Dedicated reproductive medicine centers concentrate embryology expertise and controlled laboratory environments under single-specialty governance. These facilities capture premium pricing through direct patient relationships and operational flexibility unavailable in institutional settings.
- Hospitals:Academic medical centers and general hospitals integrate fertility services within broader obstetrics and gynecology departments, leveraging existing surgical suites and anesthesia support for complex cases. Reimbursement advantages in some national health systems attract patients seeking subsidized access.
- Research Laboratories:Institutional facilities focus on protocol development and training rather than commercial patient services.
- Academic Institutions:University-affiliated programs combine clinical service with fellowship training and investigator-initiated trials.
Fertility Clinics dominate installed base. Hospitals are where expansion concentrates.
Technology:
Technology layering determines competitive differentiation and capital replacement cycles across laboratory infrastructure.
- Time-Lapse Imaging:Continuous embryo monitoring systems capture morphokinetic development without culture disruption, generating predictive algorithms for implantation potential. High-volume United States clinics deploy these platforms as patient acquisition tools, advertising live birth rate transparency.
- Preimplantation Genetic Testing:Blastocyst biopsy with comprehensive chromosomal screening identifies euploid embryos for transfer, reducing miscarriage risk in advanced maternal age patients. EMA validation requirements for aneuploidy testing platforms extend procurement timelines for European networks.
- Cryopreservation:Vitrification protocols and dedicated storage infrastructure enable elective fertility preservation and embryo banking.
- Embryo Culture Media:Proprietary formulations supporting blastocyst development represent recurring consumable expenditure with supply concentration risks.
Embryo Culture Media dominates installed base. Time-Lapse Imaging is where expansion concentrates.
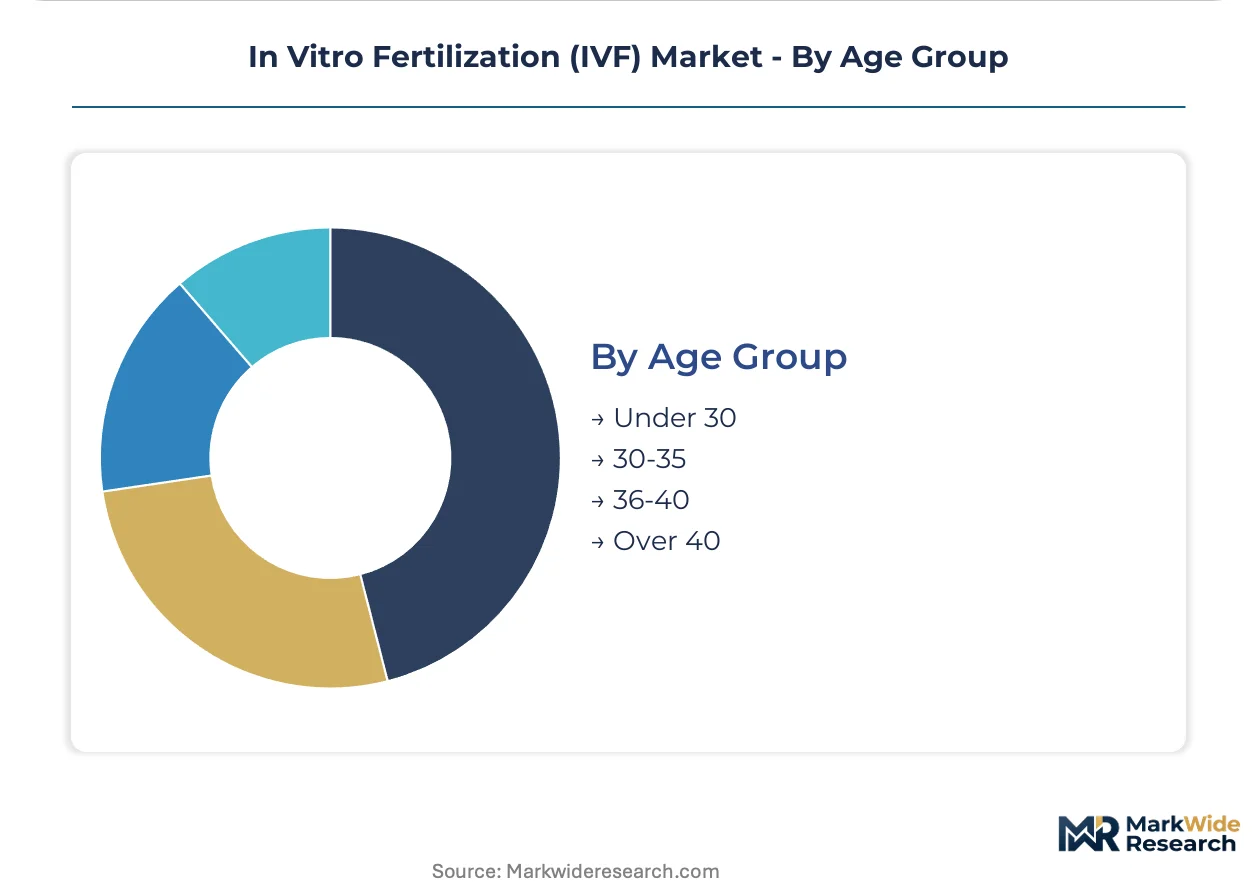
Age Group:
Patient age stratifies treatment complexity, success probability, and service mix across clinical portfolios.
- 30-35:Elective fertility preservation candidates drive cryopreservation volume with highest future utilization potential. Employer-sponsored benefits in the United States concentrate among this demographic, expanding addressable pools beyond medical infertility diagnoses.
- 36-40:Declining ovarian reserve and rising aneuploidy rates shift treatment toward donor egg programs and genetic testing adoption. Chinese provincial centers report fastest patient volume growth in this bracket as delayed marriage patterns mature.
- Under 30:Younger patients present favorable prognoses with conventional protocols and minimal intervention requirements.
- Over 40:Advanced maternal age patients require specialized donor programs and modified stimulation protocols with limited autologous success probability.
36-40 dominates installed base. 30-35 is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic data cable corridors connecting Boston to London and Frankfurt underpin the IVF sector's knowledge transfer infrastructure, enabling real-time embryology consultations and telemedicine protocols across major treatment networks.
United States
Employer-sponsored fertility benefits and elective egg freezing among technology sector professionals drive patient volume expansion. The FDA regulates assisted reproductive technology devices under 21 CFR Part 1271 human cell and tissue regulations. Boston and San Francisco metropolitan clusters concentrate academic medical center networks where time-lapse imaging adoption rates exceed national averages.
Spain
Cross-border reproductive tourism from France, Italy, and the United Kingdom sustains treatment cycle volumes at Barcelona and Madrid fertility centers. The Spanish Medicines and Health Products Agency enforces quality standards for gamete donation registries and cryopreservation facility licensing. The Catalonia region hosts Europe's highest density of private fertility clinics with integrated donor egg programs.
China
Delayed marriage patterns and relaxed family planning policies expand addressable patient pools in provincial tier-two cities. The NMPA implements GB standards for medical device registration that foreign manufacturers navigate for culture media and incubator market entry. The Yangtze River Delta cluster around Shanghai concentrates domestic fertility center chains investing in automated embryology laboratory infrastructure.
Germany
Reimbursement constraints under statutory health insurance limit cycle volumes while driving demand for single-embryo transfer optimization. The Federal Institute for Drugs and Medical Devices oversees IVDR compliance timelines for preimplantation genetic testing platform certification. The Munich-Stuttgart corridor anchors specialized reproductive medicine practices serving cross-border patients from Austria and Switzerland.
Australia
Publicly subsidized IVF access through Medicare creates volume concentration in metropolitan fertility networks. The Therapeutic Goods Administration regulates culture media as medical devices requiring conformity assessment procedures. Sydney and Melbourne clinical clusters dominate national cycle volumes while regional Queensland centers expand cryopreservation capacity for fly-in patients.
In Vitro Fertilization (IVF) Market Competitive Landscape
Concentration sits with diversified life science conglomerates controlling pharmaceutical and laboratory instrumentation supply chains. The market structure fragments across three functional layers: gonadotropin manufacturing, embryology consumables, and clinical service delivery. Strategic archetypes include pharmaceutical heritage players, laboratory technology integrators, and direct-operated fertility clinic networks. Competitive moves center on vertical integration into cryopreservation infrastructure and strategic partnerships for genetic testing platform distribution.
Within the pharmaceutical heritage tier, Merck KGaA exemplifies gonadotropin supply chain dominance across European treatment centers. Among laboratory technology specialists, Thermo Fisher Scientific Inc. occupies a position anchoring integrated genetic analysis platforms. IVIRMA Global represents the direct-operated clinic network archetype, with its multi-continental fertility center footprint demonstrating geographic expansion strategies. These three entities collectively illustrate how market participants defend margin positions through supply chain control, technology platform integration, and patient acquisition channel ownership.
| Leading Market Players |
|---|
| CooperSurgical Inc. |
| Vitrolife AB |
| Cook Medical Inc. |
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| FUJIFILM Irvine Scientific |
| Hamilton Thorne |
| IVIRMA Global |
| Monash IVF Group |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements for recombinant FSH and culture media lock in supply access for European fertility networks while anchoring price visibility against bovine serum volatility. These contractual structures concentrate procurement leverage among high-volume clinic chains operating across Spain and Germany.
Pricing Analysis
Volume-discount tiering separates flagship fertility centers purchasing time-lapse systems in bulk from smaller practices buying consumables on spot terms. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and geographic delivery cost, with EMA-validated genetic testing platforms commanding brand premiums. Pricing pressure stems from employer-sponsored benefit programs demanding cycle bundling discounts. Hospital-based services exhibit highest price sensitivity due to statutory reimbursement constraints.
Supply Chain Analysis
Inventory lead times for specialized protein supplements stretch procurement horizons as bovine serum supply faces intermittent constraints. Manufacturing concentrates in Germany, the United States, and China, with recombinant gonadotropin production anchored in European pharmaceutical facilities. Raw material dependencies include bovine serum albumin, recombinant FSH, and vitrification cryoprotectants. Single-source vulnerability runs through recombinant hormone manufacturing. Distribution runs through direct sales forces serving fertility clinic networks and GPO contracts penetrating hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IVF market operates as a defensive-moat story where regulatory entrenchment creates formidable barriers against new assay platform commercialization. Switching costs for validated embryology protocols further cement incumbent positions.
For Market Incumbents: Secure captive supply of recombinant gonadotropins through backward integration into pharmaceutical manufacturing, insulating margin structures from European production disruptions. Fortify EMA validation portfolios against emerging AI-assisted embryo selection platforms by accelerating prospective outcome studies. Channel control through direct-operated clinic networks defends patient acquisition channels from employer benefit administrators. For New Entrants and Emerging Players: Differentiate on AI-assisted morphokinetic analysis as a software layer compatible with existing incubator hardware, avoiding capital-intensive cleanroom construction. Target Chinese tier-two cities where provincial fertility centers lack advanced embryology infrastructure. Employer-sponsored benefits in the United States present the most penetrable financing model for subscription-based multi-cycle packages. For Investors and Strategic Acquirers: Regional clinic chains with integrated donor egg programs and established cryopreservation infrastructure represent compelling acquisition archetypes. Long-term viability hinges on consolidation around IVDR-compliant suppliers with demonstrated clinical utility evidence. Watch EMA certification timeline extensions as the inflection indicator for platform valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Investment | EMA validation timelines determine competitive positioning for genetic testing platforms across European networks. |
| Cryopreservation Infrastructure Expansion | Vitrification capacity additions capture elective fertility preservation demand among United States professionals. |
| AI Platform Integration | Machine vision algorithms trained on time-lapse image banks automate embryo grading protocols in high-volume clinics. |
| Employer Benefit Partnership | Corporate fertility coverage programs reduce upfront cost barriers and expand addressable patient pools. |
| NMPA Registration Pathway | Streamlined medical device approvals accelerate foreign manufacturer access to Chinese provincial markets. |
Research Methodology
Operator-level perspectives from embryology laboratory directors, fertility clinic procurement managers, pharmaceutical supply chain leads, and hospital reproductive medicine chiefs anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, EMA IVDR submissions, NMPA registration databases, and hospital GPO contract repositories. Bottom-up cycle volume estimates triangulated against top-down pharmaceutical consumption data across the analysis window.
Sensitivity analysis tested forecast robustness across alternative reimbursement scenarios and regulatory approval timelines. Segmentation modeling incorporated procedure type, end-user facility category, technology platform, and patient age bracket dimensions throughout the forecast period. CAGRs derived from fitted growth curves applied to country-level cycle volume projections, with inputs including delayed childbearing demographic shifts and employer benefit penetration rates.
The analysis sits within stated boundaries; outcomes outside EMA validation continuity or NMPA regulatory stability would require recalibration. Forecasts reflect assumptions regarding reimbursement policy persistence and pharmaceutical supply reliability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
Fertility Services Market
Reproductive Health
IVF Services Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
US Contraceptive Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Gamete Preservation Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
Global Gynecology Drugs Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Global Genital Herpes Treatment Market
Reproductive Health
Contraceptives Market
Reproductive Health
US Birth Centers Market