
 Veterinary in Vitro Fertilization Market | 2026-2036
Veterinary in Vitro Fertilization Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary in Vitro Fertilization Market Insights
Buyer concentration across large-scale cattle breeding cooperatives is rebalancing as fragmented companion animal clinics enter the IVF services pool. Hamilton Thorne Inc. leverages proprietary laser systems for embryo biopsy to sustain technology leadership in bovine applications. Minitube Group anchors European supply chains through controlled distribution of media and consumables. Charles River Laboratories competes by extending its research-grade embryo production capabilities into commercial veterinary channels.
Veterinary in vitro fertilization encompasses the extracorporeal fertilization of oocytes with sperm followed by embryo culture and transfer, typically requiring temperature-controlled incubation at 38.5°C with defined gas mixtures and specialized holding media. The procedure serves commercial breeders seeking accelerated genetic gain in livestock populations and conservation programs for endangered species. Equipment and media segments command the deepest margin pools due to recurring consumable demand and instrument replacement cycles, while genetic testing within the indication category captures premium pricing from seedstock producers. Services remain the fastest-growing segment as breeding centers outsource embryo production rather than building in-house laboratories.
The USDA enforces welfare standards for research and commercial embryo production facilities through its Animal and Plant Health Inspection Service, while the FDA regulates animal biologics and assisted reproduction products under the Center for Veterinary Medicine. ISO 17025 accreditation for embryology laboratories shapes market access by differentiating certified providers from informal competitors. Stakeholders must monitor evolving gene-editing oversight frameworks and decide whether to invest in combined IVF-genomic selection platforms or maintain conventional embryo transfer specialization.
Market Dynamics
Commercial breeding centers are consolidating embryo production around laser-assisted biopsy systems and ISO 17025-accredited laboratory networks, compressing the competitive window for informal service providers.
Growth Catalysts
- USDA Animal Welfare Act enforcement:Tighter facility inspection protocols are eliminating substandard competitors and redirecting demand toward certified embryology laboratories.
- Genomic selection convergence:Integration of IVF with high-density SNP arrays enables seedstock producers to compress genetic gain timelines from years to months.
- Texas-Wisconsin dairy corridor concentration:Large-scale Holstein breeding cooperatives are scaling outsourced embryo production contracts to secure elite genetics.
Market Restraints
- Media and consumable cost volatility:Defined holding media and culture reagents face price pressure from pharmaceutical-grade raw material shortages.
- European supply chain concentration:Controlled distribution of specialized media through single-source channels creates procurement vulnerability for North American laboratories.
- Gene-editing regulatory friction:Emerging FDA oversight frameworks for edited embryos extend approval timelines and inflate compliance costs.
Strategic Opportunities
- Companion animal clinic penetration:Fragmented veterinary practices in suburban corridors represent underdeveloped demand for canine and feline reproductive services.
- Conservation program expansion:Endangered species recovery initiatives require specialized embryo cryopreservation and inter-zoo transfer protocols.
- Research-grade-to-commercial channel shift:Charles River Laboratories and similar contract research organizations are leveraging existing embryo production infrastructure to serve commercial breeders.
Industry Challenges
- Embryologist certification scarcity:ISO 17025-accredited laboratory personnel require multi-year training pipelines that lag behind facility expansion.
- Legacy embryo transfer integration:Conventional ET specialists face technical retooling costs to adopt IVF-based production workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary in Vitro Fertilization Market |
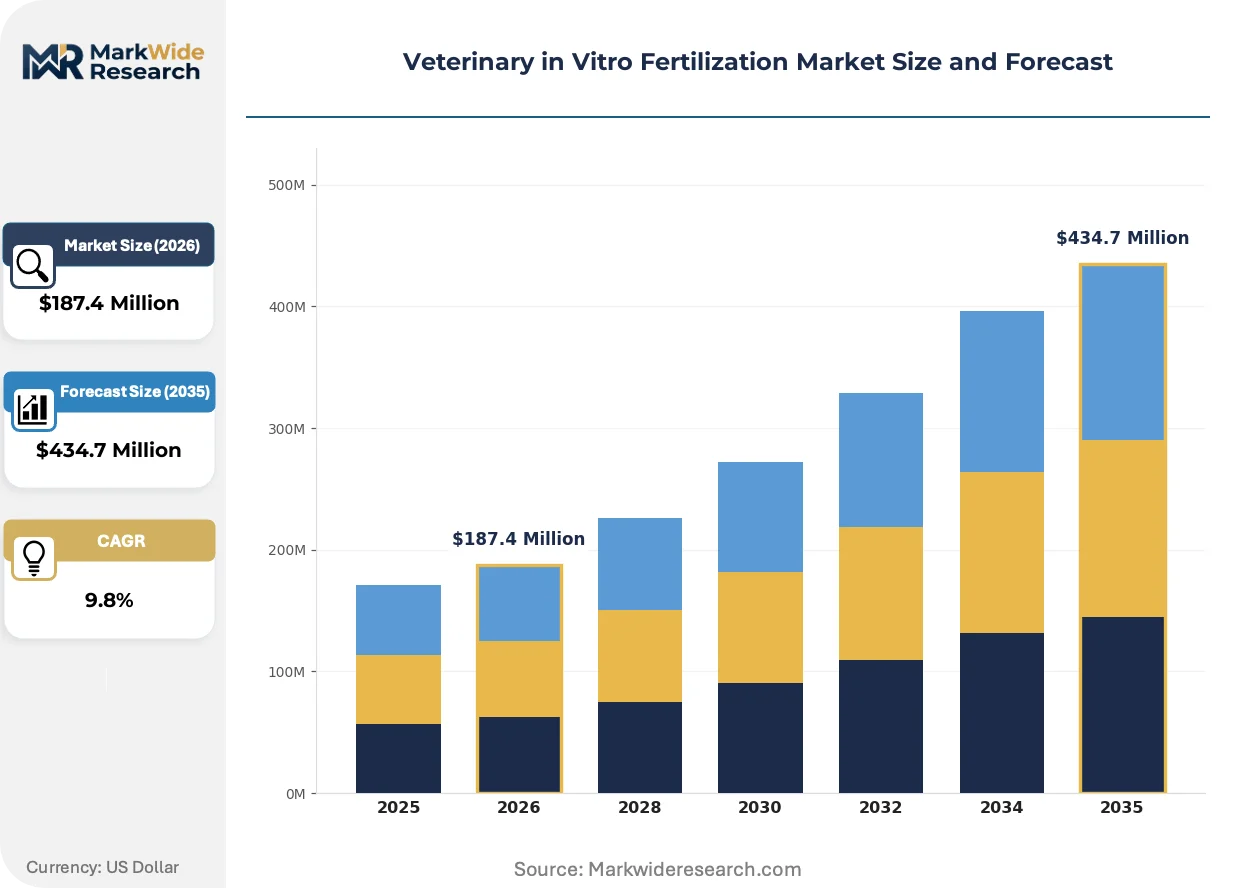
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Media, Kits, Equipment, Services Indication: Artificial Insemination, Embryo Transfer, Oocyte Preservation, Genetic Testing Animal Type: Cattle, Horses, Swine, Companion Animals End User: Veterinary Clinics, Research Institutions, Breeding Centers, Universities |
| Companies Covered | Hamilton Thorne Inc., Esco Medical, Minitube Group, Eppendorf SE, Charles River Laboratories, IVF Technologies, Reproductive Technologies, Vet IVF, IVF Vet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary in Vitro Fertilization Market Trends and Innovations
Portable incubation systems and cloud-based embryo monitoring are redistributing production capacity away from centralized facilities toward on-farm and mobile laboratory configurations.
Laser-assisted embryo biopsy technology is decentralizing genetic testing workflows by enabling real-time sampling at breeding center locations rather than centralized reference laboratories. Large-scale cattle cooperatives in Texas and Wisconsin are deploying these systems at satellite facilities. This capability is compressing the embryo-to-genetic-data cycle from weeks to days.
The FDA's evolving framework for animal biologics and gene-edited embryos is extending pre-market review timelines for combined IVF-genomic selection platforms. Commercial breeders face uncertainty over which edited traits trigger enhanced scrutiny. Seedstock producers are responding by segregating conventional and gene-edited embryo production lines.
Outcome-based service contracts are displacing per-procedure pricing among large breeding cooperatives. Commercial centers now negotiate guaranteed pregnancy rate agreements with IVF service providers. This shift is most visible across the Upper Midwest dairy belt where volume commitments exceed five thousand embryos annually.
Veterinary in Vitro Fertilization Market Segmentation
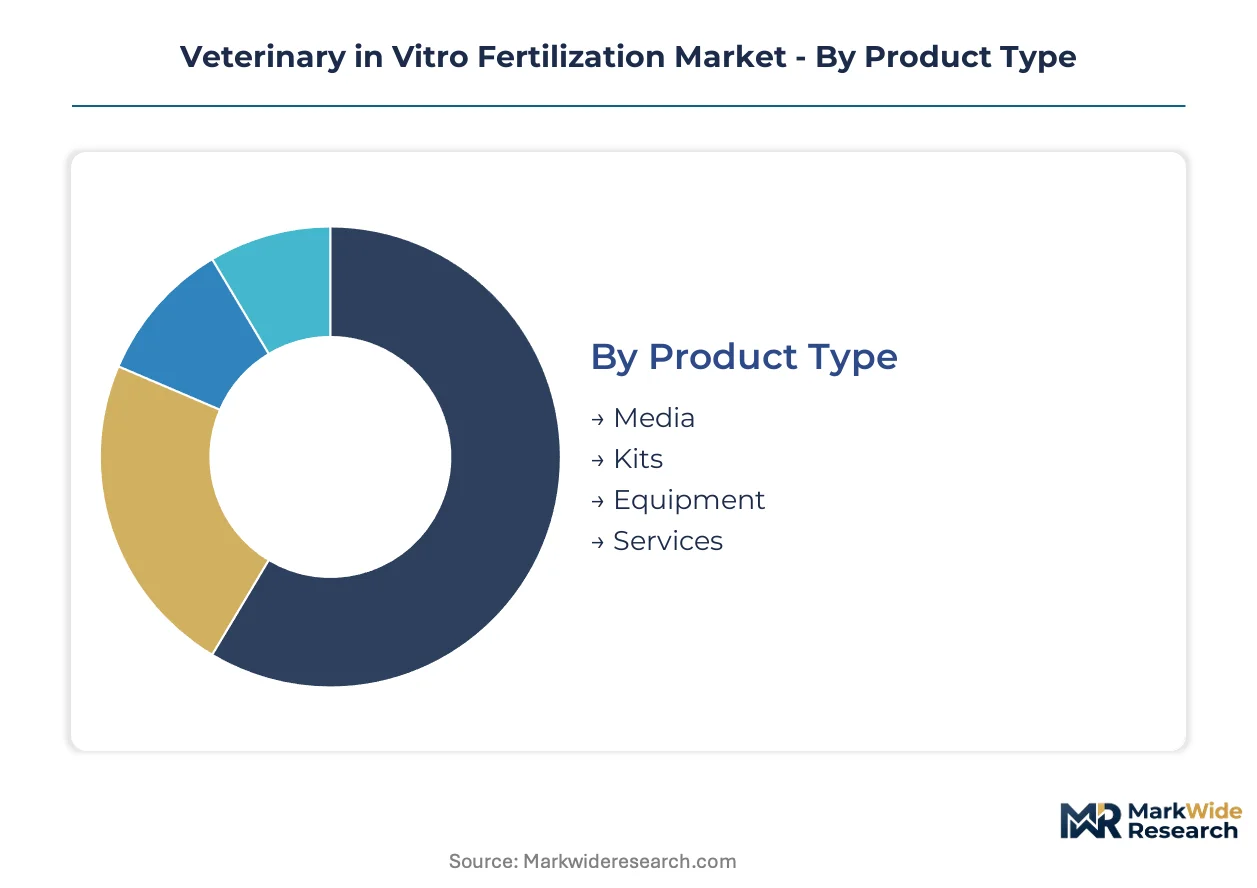
Veterinary IVF segmentation reveals distinct margin architectures across consumables, durable equipment, and labor-intensive services. Each category carries unique replacement cycles and customer concentration patterns that reshape procurement behaviors among breeding centers and research facilities.
Product Type:
Replacement cycles and upgrade intensity vary sharply across this dimension, with consumables demanding continuous replenishment while equipment follows multi-year capital planning horizons.
- Media:Defined holding media and culture reagents require precise formulation at 38.5°C incubation parameters. Demand clusters at ISO 17025-accredited laboratories across Texas and Wisconsin dairy corridors, where large breeding cooperatives negotiate volume contracts to offset pharmaceutical-grade raw material volatility.
- Equipment:Temperature-controlled incubation systems, micromanipulators, and laser-assisted biopsy platforms represent capital-intensive infrastructure with 5-7 year replacement windows. Procurement concentrates among commercial breeding centers consolidating embryo production capacity around Hamilton Thorne laser systems.
- Kits:Pre-configured consumable bundles streamline procurement for mid-scale veterinary clinics entering IVF services. These packaged solutions reduce technical setup barriers for fragmented companion animal practices in suburban markets.
- Services:Outsourced embryo production contracts are gaining share fastest as breeding centers avoid in-house laboratory construction. Outcome-based pricing with guaranteed pregnancy rate agreements is displacing per-procedure fees across Upper Midwest dairy cooperatives.
Volume placements concentrate in Media; the faster expansion belongs to Services.
Indication:
Application maturity spans from established embryo transfer protocols to emerging genetic testing integrations that compress genetic gain timelines.
- Embryo Transfer:The foundational IVF application involving fertilized embryo culture and surgical or non-surgical deposition into recipient females. Commercial cattle breeding centers in Wisconsin and Texas maintain the deepest procedure volumes, though conventional ET specialists face retooling costs to adopt IVF-based workflows.
- Genetic Testing:High-density SNP array integration with IVF enables seedstock producers to evaluate elite genetics within days rather than weeks. Laser-assisted biopsy systems at satellite facilities are decentralizing testing workflows away from centralized reference laboratories.
- Artificial Insemination:Conventional semen deposition remains cost-competitive for commercial dairy operations not pursuing accelerated genetic gain. This indication serves as a gateway technology for breeding centers later upgrading to full IVF protocols.
- Oocyte Preservation:Cryopreservation protocols for endangered species conservation and valuable genetic line banking. Zoological institutions and research facilities deploy specialized vitrification methods for inter-zoo embryo transfer programs.
Embryo Transfer commands current procedure volume; Genetic Testing is climbing the fastest as genomic selection converges with production workflows.
Animal Type:
Species-specific reproductive biology and commercial value per offspring create divergent service economics across veterinary IVF applications.
- Cattle:Holstein and beef seedstock operations generate the deepest revenue pools per procedure, with elite genetics commanding premium pricing. The Texas-Wisconsin dairy corridor anchors North American demand through large-scale cooperative breeding programs.
- Companion Animals:Canine and feline reproductive services represent an underdeveloped channel, with fragmented suburban veterinary clinics only recently entering the IVF services pool. Technical training gaps and lower per-procedure economics have slowed penetration relative to livestock applications.
- Horses:Thoroughbred and sport horse breeding programs utilize IVF to overcome natural mating limitations and preserve valuable genetic lines. Regulatory constraints from breed registries shape permissible technology applications.
- Swine:Commercial pork production systems deploy IVF for genetic improvement and disease-resistant line development, though unit economics favor artificial insemination at commercial scale.
Cattle dominates absolute procedure counts; Companion Animals is gaining share fastest as suburban clinic penetration accelerates.
End User:
Customer sophistication and in-house technical capability determine whether procurement favors consumables, equipment, or outsourced services.
- Breeding Centers:Large-scale commercial operations with dedicated embryology laboratories and ISO 17025 accreditation. These facilities concentrate demand for high-throughput equipment and defined media at volume price tiers.
- Veterinary Clinics:Fragmented general practices and specialty reproductive hospitals with limited in-house laboratory capacity. This segment drives services demand and kit-based consumable procurement.
- Research Institutions:Charles River Laboratories and similar contract research organizations leverage existing embryo production infrastructure for commercial channel expansion. These facilities prioritize research-grade media and genetic testing capabilities.
- Universities:Veterinary schools and agricultural research programs training embryologists while maintaining conservation breeding programs for endangered species. Personnel certification pipelines lag behind facility expansion needs.
Breeding Centers anchor equipment and media volume; Research Institutions are expanding most quickly as CROs commercialize existing capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial breeding centers for elite cattle genetics concentrate procurement of IVF services in specific national corridors, with regulatory enforcement and dairy industry scale determining regional market depth.
United States
Large-scale Holstein breeding cooperatives in Texas and Wisconsin drive the deepest demand for outsourced embryo production contracts. The USDA's Animal and Plant Health Inspection Service enforces welfare standards through tighter facility inspection protocols that eliminate substandard competitors. Dallas-Fort Worth and Madison metropolitan corridors anchor North American equipment procurement for laser-assisted biopsy systems.
Germany
Specialized media manufacturers serve centralized distribution networks across European veterinary laboratories. The EMA and national regulators under EU MDR frameworks shape compliance requirements for embryo production biologics. Bavaria's agricultural research clusters concentrate conservation breeding programs for endangered livestock breeds requiring cryopreservation protocols.
China
State-backed livestock genetic improvement programs deploy IVF for disease-resistant line development in commercial pork and dairy operations. The NMPA regulates animal biologics and assisted reproduction products under evolving national standards. Yangtze River Delta breeding cooperatives scale embryo production capacity to secure protein supply chain security.
Brazil
Beef seedstock operations generate substantial procedure volumes for Nelore and Angus genetic improvement at commercial scale. ANVISA oversees veterinary product registration and facility licensing for embryology laboratories. São Paulo state breeding centers concentrate demand for portable incubation systems serving decentralized ranch operations.
Australia
Merino sheep and Wagyu cattle breeders utilize IVF to accelerate genetic gain in export-oriented livestock populations. The TGA and state agricultural departments coordinate welfare standards for commercial embryo production facilities. New South Wales Riverina district hosts the densest concentration of ISO 17025-accredited veterinary embryology laboratories.
Veterinary in Vitro Fertilization Market Competitive Landscape
North American producers anchor one tier; European specialists hold controlled distribution channels for defined media and culture reagents. The vendor base splits between consolidated equipment manufacturers with multi-year replacement cycles and fragmented service providers competing on outcome-based contracts. Three archetypes dominate: laser-system technology leaders, media supply chain gatekeepers, and research-grade laboratories commercializing into commercial channels. Competitive moves concentrate on strategic partnerships for genomic selection integration and capacity expansion through satellite facility networks.
Within the technology-leader tier, Hamilton Thorne Inc. and Esco Medical represent North American and Singapore-based positions in precision instrumentation. Minitube Group anchors European supply chain control over specialized consumables. Charles River Laboratories exemplifies the research-to-commercial channel shift, leveraging existing embryo production infrastructure to serve breeding center demand.
| Leading Market Players |
|---|
| Hamilton Thorne Inc. |
| Esco Medical |
| Minitube Group |
| Eppendorf SE |
| Charles River Laboratories |
| IVF Technologies |
| Reproductive Technologies |
| Vet IVF |
| IVF Vet |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade raw materials for defined holding media move through controlled European distribution channels before reaching ISO 17025-accredited laboratories across Texas and Wisconsin, with procurement costs stratifying across volume tiers and certification grades.
Pricing Analysis
High-throughput breeding centers command favorable unit economics against fragmented companion animal clinics, with three-tier pricing structure across premium, standard, and economy levels separating ISO-accredited facilities from informal providers. Price differentiation hinges on certification grade and volume scale, with pharmaceutical-grade media formulations carrying premiums over research-grade alternatives. Cost compression in mid-tier equipment is intensifying because raw material shortages propagate through consumable supply chains. Small suburban veterinary practices exhibit the highest price sensitivity, while large cooperative breeding programs leverage multi-year contracts to lock in supply security.
Supply Chain Analysis
Specialized culture media production rests on German and Dutch specialty chemical manufacturers, with laser-assisted biopsy systems drawing from North American precision instrumentation clusters and Singaporean manufacturing hubs. Critical inputs span pharmaceutical-grade reagents, temperature-controlled incubation components, and micromanipulator assemblies. Single-source vulnerability concentrates in European media distribution channels controlled through exclusive distributor agreements. Distribution runs through authorized veterinary supply houses serving accredited laboratory networks, with direct manufacturer relationships reserved for the largest breeding cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Veterinary in Vitro Fertilization Market is executing a technology-transition phase, with laser-assisted embryo biopsy systems displacing conventional embryo transfer workflows and compressing genetic testing timelines from weeks to days.
For Market Incumbents: Hedge against embryologist certification scarcity by building captive training pipelines at university partnerships in Texas and Wisconsin, while securing backward integration into pharmaceutical-grade media formulation to offset European supply chain vulnerability. ISO 17025 accreditation investments create defensive moats as USDA enforcement eliminates substandard competitors.
For New Entrants and Emerging Players: Begin with portable incubation systems targeting fragmented companion animal clinics in suburban corridors, where technical setup barriers have suppressed IVF penetration relative to livestock applications. Outcome-based service contracts with guaranteed pregnancy rates offer the most penetrable go-to-market angle against established per-procedure pricing.
For Investors and Strategic Acquirers: FDA publication of gene-edited embryo oversight frameworks is the leading indicator that regulatory clarity will unlock combined IVF-genomic selection platform valuations. Research-grade laboratories with existing embryo production infrastructure present the most compelling acquisition profile across a five-to-ten-year commercialization horizon. Watch for USDA facility inspection protocol expansions as the signal that certification scarcity is deepening competitive moats.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Laboratory Accreditation | USDA enforcement redirects demand toward certified embryology providers and eliminates informal competitors. |
| Backward Integration into Media Formulation | In-house pharmaceutical-grade reagent production reduces European supply chain concentration vulnerability. |
| Portable Incubation System Launch | On-farm and mobile laboratory configurations redistribute capacity away from centralized facilities. |
| Genomic Selection Platform Partnership | High-density SNP array integration compresses genetic gain timelines for seedstock producers. |
| Embryologist Certification Pipeline Investment | University training partnerships address personnel scarcity lagging behind facility expansion. |
Research Methodology
Document review covered FDA Center for Veterinary Medicine guidance documents, USDA Animal and Plant Health Inspection Service enforcement records, and ISO 17025 accreditation databases, complemented by interviews with embryology laboratory directors, veterinary reproductive specialists, breeding cooperative procurement managers, and pharmaceutical-grade media manufacturers. Secondary sources included trade customs data for specialized equipment imports, SEC filings from publicly traded contract research organizations, and veterinary medical association procedure surveys. Bottom-up demand modeling from individual facility capacity and top-down market sizing from equipment shipment data were cross-validated through triangulation.
Historical capacity expansion patterns were cross-referenced against expert panel input from embryology laboratory directors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, indication category, animal species, and end-user sophistication tier, with regional regulatory clusters capturing USDA, EMA, and NMPA framework variations. CAGRs were derived from fitted trend analysis against documented facility expansion pipelines and procurement contract volumes. Industry-specific forecast inputs incorporated breeding cooperative genetic improvement targets and companion animal clinic penetration rates.
Underlying measurement precision varies by segment; services and equipment carry tighter precision than fragmented companion animal clinic estimates due to consolidated reporting from large breeding cooperatives. Forecasts reflect assumptions about regulatory enforcement intensity, gene-editing oversight timeline clarity, and pharmaceutical-grade raw material supply stability. Gene-editing framework finalization, USDA inspection protocol expansion, and European media supply disruptions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Compression Veterinary Bandages Market
Veterinary
Veterinary Endodontics Market
Veterinary
Veterinary Healthcare Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Global Veterinary Grooming Aids Market
Veterinary
Wearable Sensors for Animal Health Management Market
Veterinary
Veterinary Biomarkers Market
Veterinary
Global Veterinary Point of Care Market
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Pet Hypothyroidism Therapy Market
Veterinary
Veterinary Thermography Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Veterinary Excipients Market