
 Food Antimicrobial Coating Market | 2026-2036
Food Antimicrobial Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Food Antimicrobial Coating Market Analysis
Aftermarket service revenue from coating reapplication and surface monitoring is narrowing as manufacturers shift toward longer-lasting nanotechnology formulations. BASF SE leverages its polymer science portfolio to develop silver-ion embedded coatings for high-throughput meat processing lines. DuPont de Nemours Inc anchors its position through bioactive peptide research aimed at refrigerated dairy applications. 3M Company differentiates via spray-applied systems that reduce application downtime in existing food plants.
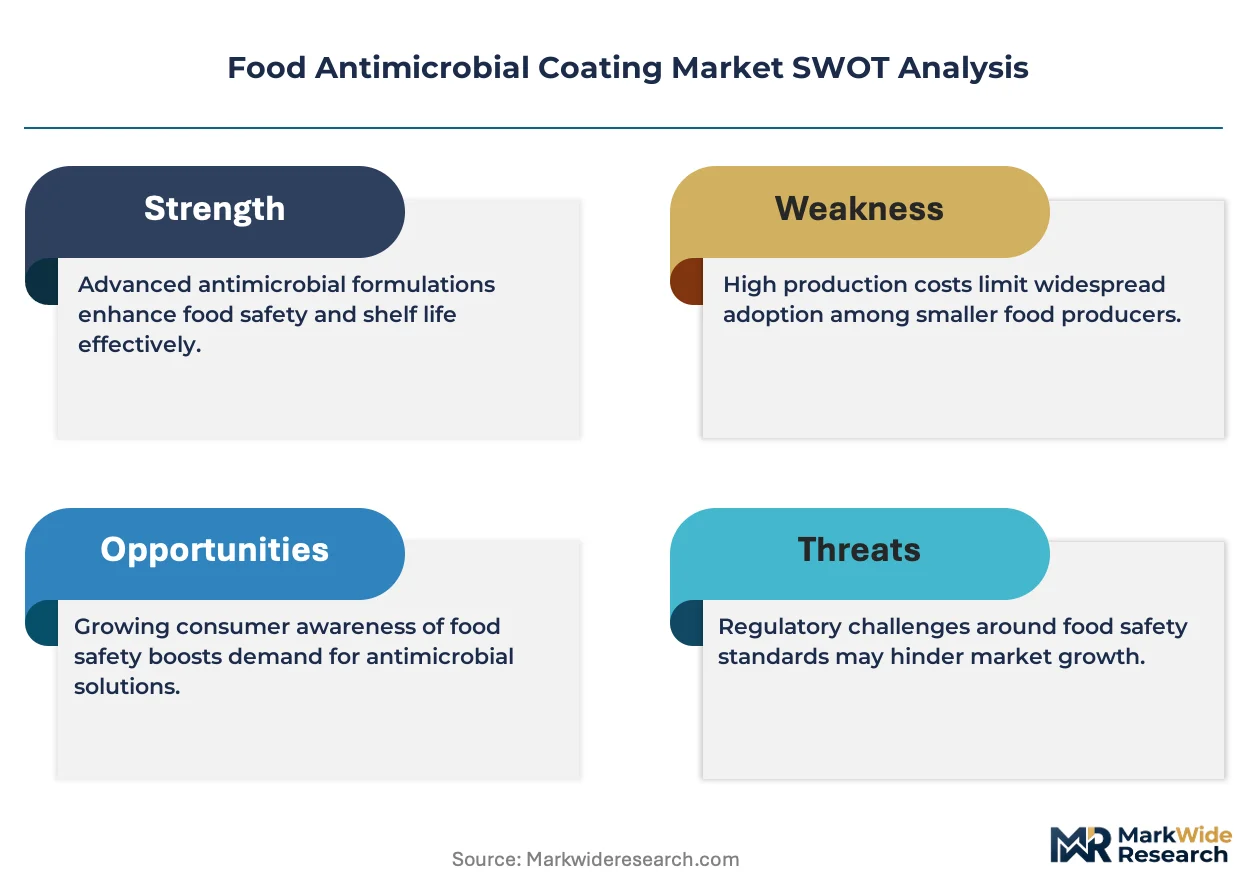
Food antimicrobial coatings constitute thin functional barriers applied to food-contact surfaces or packaging substrates, typically incorporating active agents such as nisin, chitosan, or metallic nanoparticles at concentrations between 0.1% and 5% by weight, to inhibit microbial colonization and extend shelf stability. These coatings serve primarily to reduce pathogen transmission risk and slow spoilage organism proliferation across temperature-variable supply chains. Natural antimicrobials command premium positioning as clean-label pressures intensify among North American and European food manufacturers. Nanotechnology-based application methods represent the fastest-expanding technology segment, though dip coating retains cost advantages for irregular produce geometries. The packaging application category captures the largest volume share, driven by modified-atmosphere film integration requirements.
The FDA governs coating safety through food-contact substance notifications under 21 CFR, while the EPA regulates antimicrobial claims under FIFRA, creating dual compliance pathways that shape product development timelines. The EU's REACH framework and EFSA food-contact material opinions further constrain active agent selection for exporters serving European retail channels. Stakeholders must monitor evolving nanomaterial toxicity classifications, as pending regulatory determinations on nano-silver could abruptly reshape formulation strategies and capital allocation across the supplier base.
Market Dynamics
The shift toward extended-release nanotechnology formulations is compressing aftermarket service cycles and redistributing value capture from reapplication contracts toward upfront material premiums.
Growth Catalysts
- FDA Food Safety Modernization Act:Tightened surface-contact requirements for food processing equipment are mandating antimicrobial barriers in ready-to-eat production facilities.
- Silver-ion embedded polymers:These materials deliver sustained antimicrobial efficacy against Listeria and Salmonella in high-throughput meat processing environments.
- Protein processing clusters in the United States:Geographic concentration of beef and poultry operations generates procurement volumes that justify dedicated coating formulation facilities.
Market Restraints
- Active agent cost volatility:Chitosan and nisin prices fluctuate with agricultural commodity cycles, squeezing margin on natural antimicrobial formulations.
- Dual compliance burden:Coatings must satisfy FDA food-contact substance notifications under 21 CFR alongside EPA FIFRA antimicrobial claims, extending development timelines.
- Plasma-based surface activation:This substitute technology eliminates coating requirements entirely for certain stainless-steel equipment categories.
Strategic Opportunities
- Modified-atmosphere packaging integration:Antimicrobial films that synchronize with controlled-gas environments offer white space in premium produce segments.
- EU Green Deal chemistry restrictions:REACH framework constraints on conventional biocides create openings for bioactive peptide formulations in dairy export applications.
- Convergence of nanospray deposition and inline quality sensing:Real-time thickness monitoring enables just-in-time application adjustments that reduce material waste.
Industry Challenges
- Surface engineering talent scarcity:Food plants lack personnel trained in thin-film adhesion science and microbial validation protocols.
- Legacy equipment compatibility:Retrofitting antimicrobial coatings onto decades-old processing lines requires custom surface preparation without OEM documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Antimicrobial Coating Market |
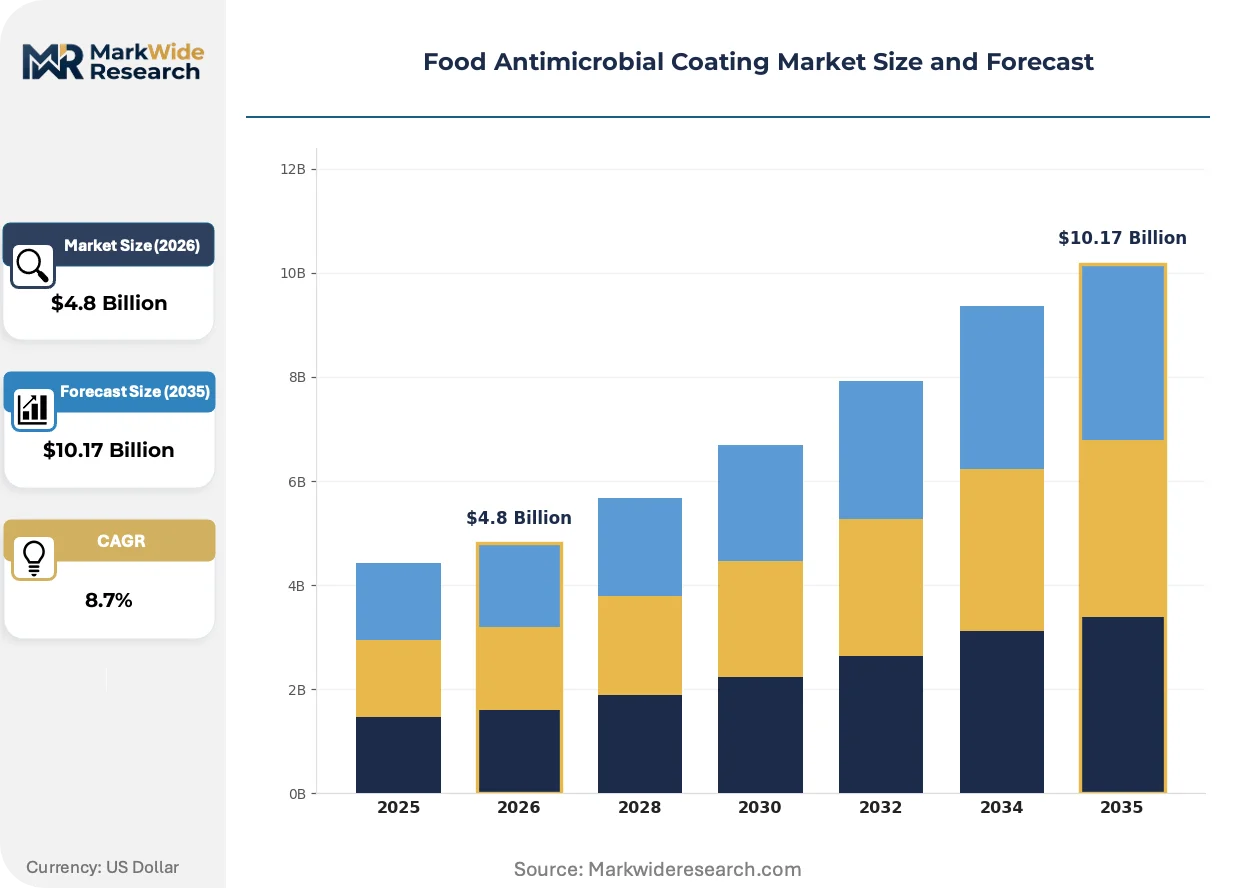
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Antimicrobials, Synthetic Antimicrobials, Enzyme-Based Coatings, Bioactive Coatings Application: Packaging, Fresh Produce, Meat Processing, Dairy Products End User: Food Manufacturers, Retailers, Foodservice Providers, Consumers Technology: Spray Coating, Dip Coating, Surface Modification, Nanotechnology |
| Companies Covered | BASF SE, DuPont de Nemours Inc, 3M Company, AkzoNobel N.V., PPG Industries Inc, Eastman Chemical Company, H.B. Fuller Company, Kraton Corporation, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Antimicrobial Coating Market Emerging Trajectories
Formulation science and application methodology are advancing in parallel, with nanotechnology methods displacing conventional dip and spray processes while regulatory clarity on novel substances remains unresolved.
Electrospun nanofiber matrices loaded with metallic nanoparticles are rendering obsolete conventional dip-coated barriers in produce packaging applications. Fresh-cut salad processors in California and Florida are adopting these materials to extend shelf stability through temperature-variable distribution. The technology is rendering obsolete the 0.1-5% active agent loading paradigm by achieving equivalent microbial inhibition at substantially lower concentrations.
REACH nanomaterial registration requirements are forcing reformulation strategies among suppliers serving European retail channels. The ECHA classification process for nano-silver creates uncertainty that delays capital allocation decisions across the supplier base. Coating developers are responding by accelerating bioactive peptide research to reduce dependency on metallic nanoparticles.
Clean-label certification is redirecting procurement toward natural antimicrobials even where synthetic alternatives demonstrate superior performance metrics. North American ready-to-eat manufacturers are accepting shorter shelf-life claims to retain retail placement with clean-label positioning. The shift is most pronounced in organic produce and natural cheese segments where consumer-facing packaging must communicate additive-free status.
Food Antimicrobial Coating Market Segmentation
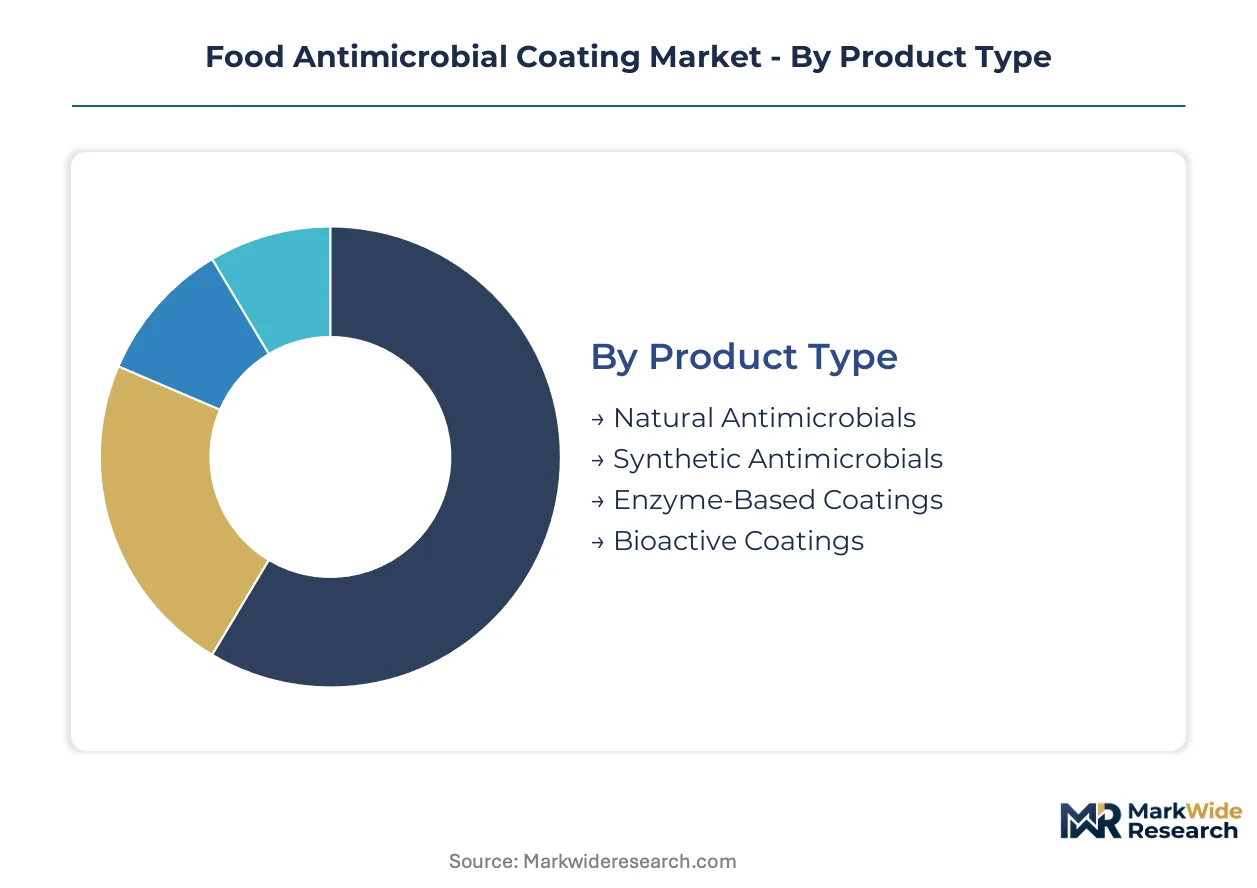
Segmentation in food antimicrobial coatings reveals how formulation chemistry, application method, and end-use environment interact to determine commercial viability. Each dimension carries distinct regulatory pathways and performance requirements that shape supplier positioning.
Product Type:
Mature synthetic formulations coexist with emerging bioactive alternatives as clean-label pressures intensify across North American and European retail channels.
- Natural Antimicrobials:These formulations incorporate chitosan, nisin, or plant-derived extracts at 0.1-5% loading to inhibit spoilage organisms. Clean-label certification requirements in California and Florida fresh-cut operations are accelerating procurement of chitosan-based barriers despite agricultural commodity price volatility.
- Synthetic Antimicrobials:Silver-ion and quaternary ammonium compounds deliver sustained efficacy against Listeria and Salmonella in high-throughput environments. Protein processing clusters in Nebraska and Iowa specify these materials for equipment coatings where extended-release performance outweighs label-positioning concerns.
- Enzyme-Based Coatings:Lysozyme and lactoferrin formulations target Gram-positive pathogens in refrigerated dairy applications with biodegradable degradation profiles.
- Bioactive Coatings:Peptide-engineered surfaces are emerging from DuPont's research pipeline for modified-atmosphere packaging integration in premium produce segments.
Natural Antimicrobials retain volume leadership; Bioactive Coatings hold the steepest expansion curve.
Application:
Cost tier differentiation separates commodity packaging films from precision-applied equipment coatings where downtime minimization commands premium pricing.
- Packaging:Modified-atmosphere films with embedded antimicrobial layers synchronize with controlled-gas environments to extend shelf stability. Fresh-cut salad processors in California and Florida are adopting electrospun nanofiber matrices that achieve equivalent microbial inhibition at lower active agent concentrations than conventional dip-coated barriers.
- Meat Processing:Surface-contact coatings for stainless-steel equipment must satisfy FDA Food Safety Modernization Act requirements for ready-to-eat production facilities. Silver-ion embedded polymers from BASF's portfolio dominate procurement specifications in high-throughput beef and poultry operations.
- Fresh Produce:Irregular geometries favor dip coating cost advantages, though nanospray deposition is displacing conventional methods for premium organic segments.
- Dairy Products:Refrigerated supply chains require coatings compatible with condensation cycling and fat-contact surfaces under 21 CFR food-contact substance notifications.
Packaging commands the broadest installed base; Meat Processing generates the highest per-unit value capture.
End User:
Customer type determines whether procurement prioritizes capital efficiency, regulatory defensibility, or consumer-facing label claims.
- Food Manufacturers:Ready-to-eat segment producers in the United States are accelerating adoption of antimicrobial packaging solutions to satisfy tightened FDA surface-contact requirements. These stakeholders specify coatings based on validation protocols and reapplication cycle economics.
- Retailers:Private-label organic produce programs in North America are accepting shorter shelf-life claims to retain placement with clean-label positioning, redirecting supplier selection toward natural antimicrobial formulations.
- Foodservice Providers:Central kitchen operations prioritize spray-applied systems that reduce application downtime in existing facilities without OEM documentation for legacy equipment.
- Consumers:Direct-to-consumer antimicrobial packaging films remain nascent, concentrated in subscription-based premium produce delivery channels.
Food Manufacturers drive procurement volume; Retailers are gaining influence fastest through specification authority.
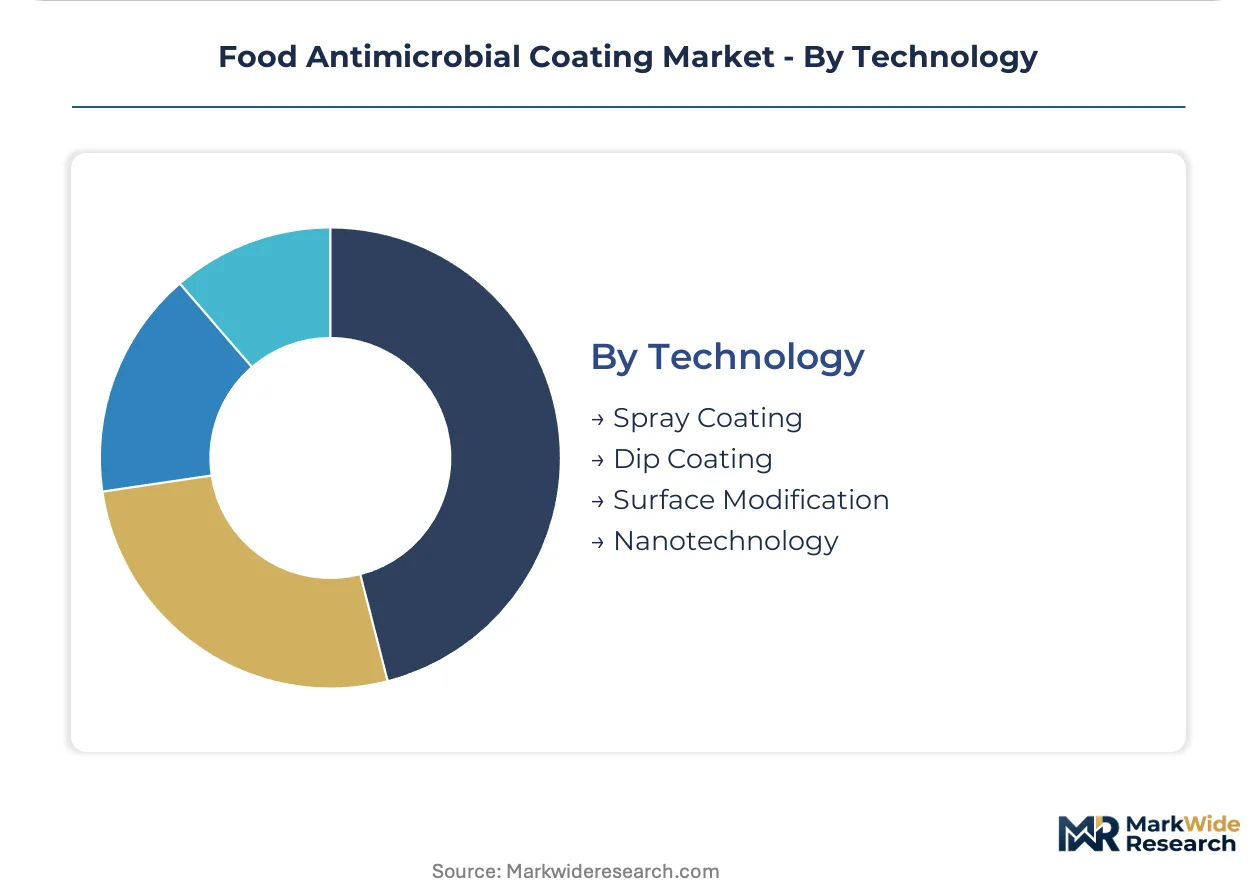
Technology:
Supply concentration among nanotechnology equipment vendors is reshaping competitive dynamics as application methodology becomes the primary differentiation lever.
- Nanotechnology:Electrospun nanofiber matrices and nanospray deposition achieve precise active agent distribution at substantially lower concentrations than conventional methods. 3M's spray-applied systems reduce application downtime while real-time thickness monitoring enables just-in-time adjustments that cut material waste.
- Spray Coating:Inline application systems dominate retrofit installations in decades-old processing lines where surface preparation must proceed without original equipment documentation.
- Dip Coating:Cost advantages persist for irregular produce geometries and batch processing environments with lower throughput requirements.
- Surface Modification:Plasma-based activation eliminates coating requirements entirely for certain stainless-steel equipment categories, functioning as a substitute technology rather than complementary method.
Spray Coating maintains installed base dominance; Nanotechnology is climbing the fastest as formulation and equipment convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature markets where regulatory compliance drives specification authority and emerging markets where cost-sensitive food safety investments dominate procurement criteria.
United States
Protein processing clusters in Nebraska and Iowa generate concentrated coating demand from high-throughput beef and poultry operations. The FDA Food Safety Modernization Act mandates antimicrobial barriers for ready-to-eat production facilities, tightening surface-contact requirements nationwide. Fresh-cut salad processors in California and Florida are adopting electrospun nanofiber matrices to extend shelf stability through temperature-variable distribution channels.
Germany
Precision dairy equipment manufacturers specify coatings compatible with condensation cycling and fat-contact surfaces under stringent hygiene protocols. The EU REACH framework and EFSA food-contact material opinions constrain active agent selection, forcing reformulation strategies among domestic suppliers. Bavarian dairy cooperatives are integrating bioactive peptide formulations into modified-atmosphere packaging for premium cheese export applications.
China
Rapid cold chain expansion is creating coating demand from domestic food manufacturers seeking pathogen control in refrigerated distribution. The country's national food safety regulator enforces evolving standards on food-contact materials that shape local formulation development. Yangtze River Delta food processors are piloting nanospray deposition systems to reduce material waste in high-volume meat processing operations.
Brazil
Beef export certification requirements are accelerating antimicrobial packaging adoption among protein processors serving European and North American retail channels. The national health surveillance agency maintains strict oversight of food-contact substances that influences coating import specifications. São Paulo-state food manufacturers are retrofitting legacy processing lines with spray-applied systems to minimize application downtime.
India
Organized retail expansion in dairy and ready-to-eat segments is generating initial coating demand from quality-conscious food manufacturers. The Food Safety and Standards Authority of India regulates food-contact materials through notification requirements that shape product registration timelines. Maharashtra-based dairy cooperatives are evaluating enzyme-based coatings for refrigerated milk distribution to urban consumption centers.
Food Antimicrobial Coating Market Vendor Landscape
Capability concentration sits with specialized polymer science and nanotechnology developers; scale advantage sits with diversified chemical conglomerates with existing food-contact regulatory dossiers. The market structure fragments across three tiers: global diversified chemical players with integrated polymer portfolios, mid-cap coating specialists with application equipment expertise, and regional compounders serving price-sensitive emerging markets. Dominant competitive moves include backward integration into active agent supply and convergence partnerships between coating formulators and inline quality sensing equipment vendors.
Within the diversified chemical tier, BASF SE and DuPont de Nemours Inc exemplify archetypes that leverage polymer science depth to anchor positions across multiple food processing verticals. 3M Company occupies a distinct position through spray-applied system expertise that addresses retrofit installation requirements in decades-old processing facilities without original equipment documentation. These three entities represent contrasting strategic postures: polymer-centric formulation development, bioactive research specialization, and application methodology differentiation respectively.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours Inc |
| 3M Company |
| AkzoNobel N.V. |
| PPG Industries Inc |
| Eastman Chemical Company |
| H.B. Fuller Company |
| Kraton Corporation |
| SABIC |
| Others |
Supply Flow & Price Mechanics
Chitosan and nisin agricultural commodity volatility compresses margin spreads across natural antimicrobial tiers while forcing coating formulators toward synthetic alternatives or extended-release nanotechnology formulations that reduce per-unit active agent consumption. This input-cost instability widens the gap between premium bioactive peptide formulations and economy-grade dip-coated barriers, reshaping procurement patterns among California fresh-cut processors and Nebraska protein facilities alike.
Pricing Analysis
Long-term offtake contracts dominate procurement between BASF and large meat processing clusters, insulating volume buyers from chitosan spot-market swings while smaller California salad processors absorb spot-price exposure. Three-tier pricing structure across premium bioactive peptide, standard silver-ion embedded, and economy chitosan-dip levels reflects certification grade and volume scale differentiation. Cost compression in natural antimicrobial tiers is intensifying because agricultural commodity cycles outpace formulation efficiency gains. Food manufacturers with ready-to-eat FDA compliance mandates show least price sensitivity; emerging Indian dairy cooperatives exhibit highest.
Supply Chain Analysis
Extended payment terms from German precision dairy equipment manufacturers to coating formulators signal working capital stress as REACH nanomaterial registration costs accumulate. Active agent production concentrates in China for metallic nanoparticles, India for chitosan extraction, and the United States for bioactive peptide synthesis. Formulation chemistry draws from silver nitrate, crustacean shell biomass, and recombinant protein feedstocks. Single-source vulnerability sits with electrospun nanofiber equipment vendors in the United States. Distribution runs through regional chemical distributors with food-contact regulatory dossier expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma-based surface activation threatens coating incumbents by eliminating material requirements entirely for select stainless-steel equipment categories, forcing antimicrobial suppliers to demonstrate irreplaceable performance in temperature-variable supply chains.
For Market Incumbents: Pre-empt plasma substitution by embedding inline quality sensing into spray-applied system offerings, locking retrofit customers into recurring validation protocols. Deepen backward integration into chitosan supply through coastal processing joint ventures to neutralize agricultural commodity volatility. Anchor position in FDA-mandated ready-to-eat segments where regulatory defensibility outweighs price competition. For New Entrants and Emerging Players: Establish a beachhead in Indian dairy refrigerated distribution where enzyme-based coating demand is nascent and FSSAI registration pathways remain navigable. Target Maharashtra-based cooperatives with biodegradable lysozyme formulations that align with urban waste management pressures. Lead with application equipment partnerships that address legacy infrastructure gaps without OEM documentation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap coating specialists with captive nanotechnology application expertise and existing EPA FIFRA dossiers. Long-term viability hinges on regulatory navigation capability across dual FDA-EPA compliance pathways rather than raw formulation science. Watch ECHA nano-silver classification determinations as the signal for capital reallocation toward bioactive peptide alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Agent Supply | Captive chitosan processing insulates margins from agricultural commodity cycles. |
| Convergence Partnership with Inline Sensing Vendors | Real-time thickness monitoring enables just-in-time application adjustments that reduce waste. |
| Dual Dossier Investment for FDA and EPA Compliance | Simultaneous 21 CFR notification and FIFRA registration accelerates product launch timelines. |
| Geographic Manufacturing Footprint in Protein Clusters | Nebraska and Iowa proximity reduces logistics costs for high-throughput beef and poultry operations. |
| Bioactive Peptide R&D Pipeline Expansion | Peptide-engineered surfaces reduce dependency on nano-silver amid ECHA classification uncertainty. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing coating formulation chemists at BASF and DuPont, plant engineers at California fresh-cut processing facilities, procurement leads at Nebraska protein clusters, and regulatory affairs specialists navigating FDA food-contact substance notifications. Secondary validation drew from EPA FIFRA registration databases, EFSA food-contact material opinions, SEC 10-K disclosures from diversified chemical conglomerates, and customs records tracking chitosan and silver nitrate trade flows. Bottom-up volume estimates from application-specific consumption rates were triangulated against top-down market sizing derived from polymer science supplier revenue allocations.
Calibration against historical adoption curves for nanotechnology-based application methods anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, application environment, end-user procurement authority, and technology methodology. CAGRs were derived from regression analysis of coating penetration rates against regulatory enforcement intensity and cold chain expansion metrics. Industry-specific forecast inputs incorporated FDA Food Safety Modernization Act implementation timelines and EU REACH nanomaterial registration completion rates.
Sensitivities concentrate around ECHA nano-silver toxicity reclassification, chitosan supply disruption from crustacean harvest volatility, and plasma-based surface activation cost reduction curves. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and coating-substrate adhesion performance in condensation-cycling dairy environments. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
Mexico Food Hydrocolloids Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
US Food Hydrocolloids Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Modified Starch Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Europe Food Preservatives Market