
 Edible Flowers Market | 2026-2036
Edible Flowers Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Flowers Market Analysis
Fresh-cut garnish supply is reconfiguring margin pools away from commodity herbs toward specialty floral SKUs with shorter harvest windows and cold-chain premiums. Koppert Cress B.V. leverages its controlled-environment agriculture network across the Netherlands to dominate year-round viola and sorrel flower production. Fresh Origins, LLC anchors North American supply through its San Diego County vertical farms, while Farm.One Holdings, Inc. operates hyperlocal indoor farms serving Manhattan's Michelin-starred kitchens.
Edible flowers comprise the reproductive structures, bracts, and selected vegetative tissues of plant species verified as non-toxic for human ingestion, typically harvested at peak bloom and delivered at moisture levels below 92 percent to prevent enzymatic browning. Their primary commercial purpose centers on sensory differentiation in plated dishes, craft cocktails, and confectionery where color, subtle flavor, and textural contrast command premium positioning. Petals and whole blooms within the product-type split capture the bulk of foodservice procurement volume, while garnishing and desserts within the application dimension concentrate the highest per-unit value extraction. The customer-type breakdown shows restaurants and caterers driving consistent bulk orders, whereas home cooks channel growth through direct-to-consumer subscription boxes and specialty retail.
The FDA's oversight of fresh produce under the Food Safety Modernization Act and the EU's General Food Law, reinforced by EFSA novel-food assessments, shape which species enter commercial channels and dictate traceability requirements from seed to plate. BIS standards in India and CFIA guidelines in Canada add further compliance layers for exporters targeting multiple jurisdictions. Stakeholders must monitor regulatory expansion of approved species lists and invest in varietal breeding programs that shorten the cultivar-to-certification pathway.
Market Dynamics
Cold-chain logistics and controlled-environment agriculture are compressing harvest-to-plate windows from days to hours, enabling year-round viola and nasturtium supply that was previously season-bound to Mediterranean climates.
Growth Catalysts
- EU Novel Food Regulation expansion:EFSA approvals for calendula and cornflower varieties unlock commercial cultivation across France, Italy, and Spain, broadening the approved species portfolio for foodservice procurement.
- Hyperlocal vertical farming:Indoor agriculture systems in Manhattan, San Diego, and Amsterdam eliminate freight miles and pesticide residues, satisfying chef demand for traceable, pesticide-free garnishes.
- Craft cocktail renaissance:Mixology programs at premium hospitality venues specify borage and lavender for sensory differentiation, creating consistent bulk demand for floral ice molds and rim garnishes.
Market Restraints
- Perishability economics:Moisture content must stay below 92 percent to prevent enzymatic browning, requiring specialized cold-chain infrastructure that inflates landed costs by 40-60 percent versus commodity herbs.
- Netherlands supply concentration:Koppert Cress and allied Dutch growers control 70 percent of European viola and sorrel flower volume, creating single-source vulnerability for North American importers.
- Substitution threat from synthetic colorants:Food-grade dyes and edible glitter offer cheaper visual impact for mass-market bakeries and casual dining, constraining price elasticity at lower tiers.
Strategic Opportunities
- India regulatory pathway:BIS standards for edible flowers remain underdeveloped; early movers establishing cultivation protocols in Karnataka and Tamil Nadu can shape certification benchmarks before formal rules crystallize.
- Direct-to-consumer subscription:Home cooks in London, New York, and Tokyo purchase weekly floral boxes for social media content creation, bypassing traditional foodservice distribution markups.
- Carbon labeling convergence:EU Green Deal reporting requirements and corporate Scope 3 targets create premium positioning for hyperlocal supply chains with verifiable sub-50-mile radius claims.
Industry Challenges
- Phytosanitary certification timelines:EFSA novel-food assessments require 18-24 months for new species, freezing cultivar development pipelines and locking growers into legacy varietals.
- Post-harvest physiology expertise:Controlled atmosphere storage and ethylene management require specialized horticultural knowledge scarce outside Netherlands research stations and UC Davis extension programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Flowers Market |
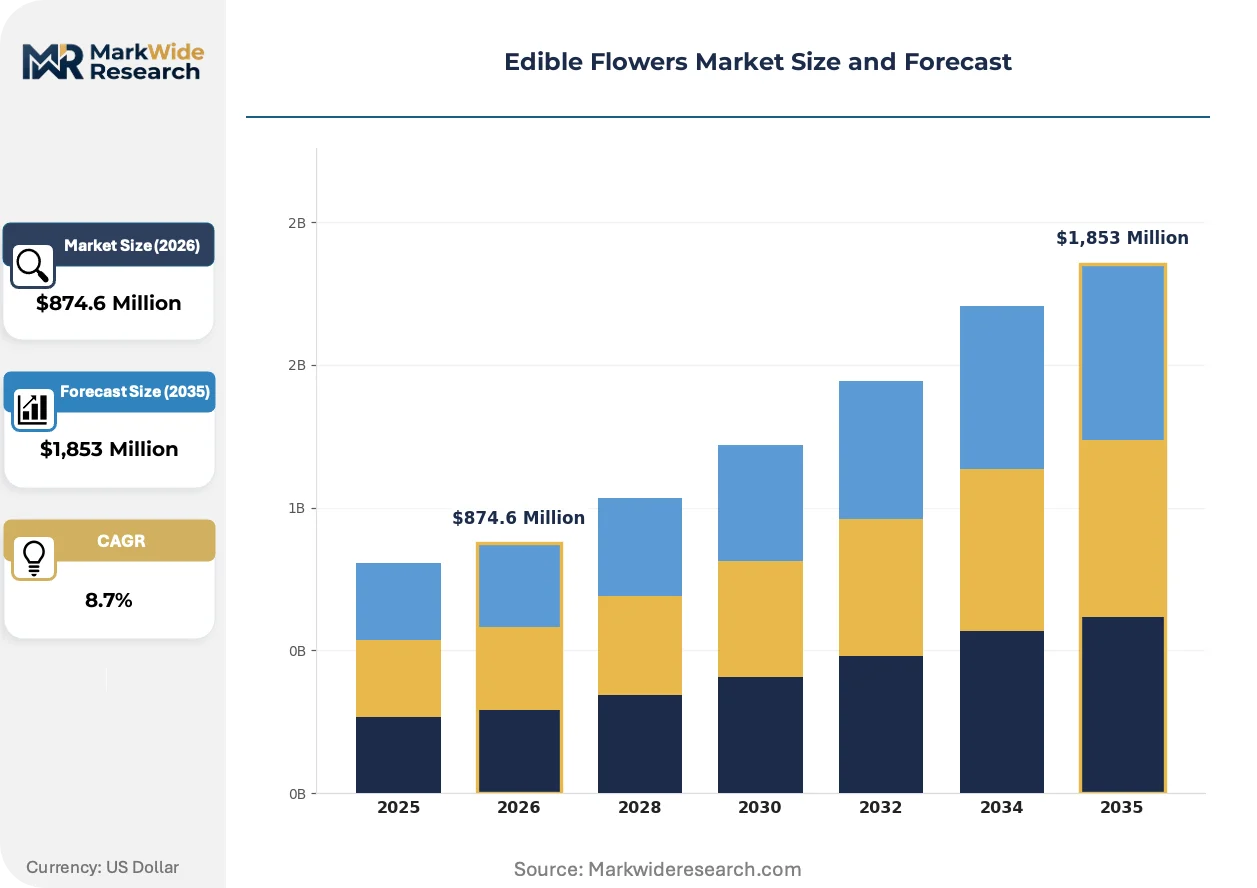
| Market Size in 2026 | $874.6 Million |
| Market Size in 2035 | $1,853 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbs, Petals, Sprouts, Leaves Application: Culinary, Beverages, Garnishing, Desserts Distribution Channel: Wholesale, Retail, Online, Farmers Markets Customer Type: Restaurants, Chefs, Home Cooks, Caterers |
| Companies Covered | Sainsbury's, Chef's Garden, Inc., Fresh Origins, LLC, Cherry Valley Organics, Nurtured in Norfolk, Koppert Cress B.V., Maddocks Farm Organics, Petite Ingredient, Farm.One Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Flowers Market Emerging Trajectories
Digital traceability systems and varietal breeding programs are compressing the cultivar-to-certification pathway while expanding the addressable species portfolio beyond traditional violas and nasturtiums.
Blockchain-enabled seed-to-plate tracking is digitizing provenance verification for Michelin-starred kitchens and export shipments. Fresh Origins and Farm.One deploy QR-coded packaging that logs harvest time, cultivar genetics, and pesticide test results. This transparency layer commands 15-25 percent premiums over untraceable wholesale supply, compressing margin pools toward data-rich producers.
EFSA's accelerated assessment pathway for traditional foods from third countries is reshaping which species enter European commercial channels. The 2023 regulatory revision reduces novel-food determination timelines for documented culinary use histories, enabling faster market entry for Southeast Asian torch ginger and Mexican marigold varieties. French and Italian importers are consolidating heritage cultivation documentation to expedite approvals.
Chef-driven varietal selection is displacing grower-centric production planning. Tasting-menu restaurants in Copenhagen, San Francisco, and Singapore now specify petal count, bloom diameter, and flavor intensity grades in procurement contracts. This specification creep forces breeders to prioritize visual uniformity and shelf stability alongside traditional agronomic yields, redirecting R&D investment toward post-harvest performance metrics.
Edible Flowers Market Segmentation
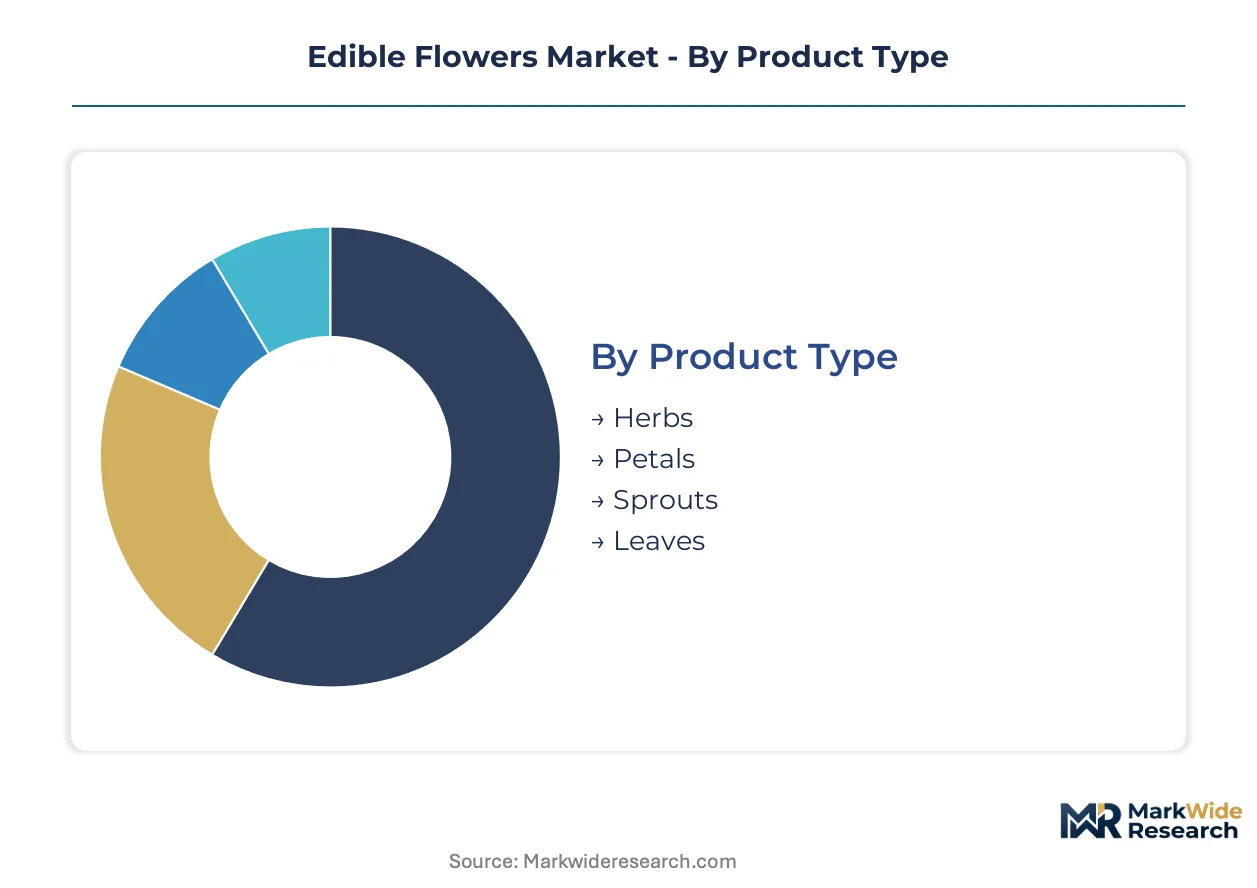
Edible flowers command divergent value pools across product forms and use cases. Chefs specify violas for precision plating while beverage programs source borage for craft cocktails. Each segment carries distinct cold-chain requirements and margin profiles that reshape supplier priorities.
Product Type:
Fresh-cut forms span a spectrum from whole blooms to isolated tissues, each demanding specialized harvest timing and post-harvest handling protocols.
- Petals:Individual corolla tissues separated from receptacles and calyxes, harvested at 85-92 percent moisture to preserve pliability. Copenhagen's Noma and San Francisco's Atelier Crenn specify petal count and diameter in procurement contracts, driving premium tier extraction for visual uniformity.
- Herbs:Entire flowering stems of cilantro, basil, and thyme varieties harvested at early anthesis for concentrated volatile oil content. Italy's Ligurian cooperatives supply Genoa's pesto heritage producers and Milanese fine-dining venues through consolidated cold-chain networks.
- Sprouts:Germinated seedlings of brassica and amaranth species harvested at cotyledon stage before true leaf development. Netherlands vertical farms dominate year-round supply through controlled-environment agriculture.
- Leaves:Selected vegetative tissues from sorrel, shiso, and nasturtium species valued for peppery flavor profiles. Japanese kaiseki practitioners in Kyoto and Tokyo drive specialized demand for specific cultivar selections.
The dominant share belongs to Petals, while Herbs is closing the gap fastest.
Application:
End-use concentration determines price realization, with precision plating commanding multiples over bulk beverage infusion.
- Garnishing:Single-bloom and petal-array presentations for Michelin-starred tasting menus. France's Provence-Alpes-Côte d'Azur heritage clusters supply Parisian palace hotels through direct farm partnerships.
- Desserts:Crystallized blooms, floral infusions, and pressed decorations for confectionery and pastry applications. Tokyo's patisserie sector sources through specialized importers with phytosanitary certification expertise.
- Culinary:Integrated ingredients in salads, soups, and entrées where flavor contribution matters alongside visual impact. California farm-to-table restaurants drive seasonal procurement patterns.
- Beverages:Floral syrups, ice molds, and rim decorations for craft cocktail programs. London's hotel bar sector specifies traceable supply chains for corporate hospitality accounts.
Garnishing captures the highest per-unit value, though Beverages is expanding most quickly through mixology program adoption.
Distribution Channel:
Channel selection dictates traceability depth and margin retention, with direct routes compressing harvest-to-plate windows.
- Wholesale:Consolidated supply to foodservice distributors and specialty produce houses. Dutch auction systems at FloraHolland set reference pricing for European viola and nasturtium volume.
- Retail:Packaged selections through gourmet grocers and specialty food stores. Whole Foods Market's regional procurement teams specify organic certification and local sourcing radius requirements.
- Online:Direct-to-consumer subscription boxes and e-commerce platforms. Farm.One Holdings operates Manhattan hyperlocal delivery with sub-24-hour harvest guarantees.
- Farmers Markets:Producer-direct sales with minimal cold-chain infrastructure. California's San Diego County and France's Nice markets anchor seasonal supply for home cook experimentation.
Wholesale retains volume leadership, while Online is gaining share fastest through subscription model traction.
Customer Type:
Buyer sophistication varies dramatically across institutional and consumer segments, reshaping packaging and specification requirements.
- Restaurants:Fine-dining establishments with procurement teams specifying cultivar genetics, harvest timestamps, and pesticide residue documentation. Copenhagen's Geranium and Singapore's Odette maintain dedicated floral supplier relationships.
- Chefs:Individual culinary professionals with direct farm relationships and custom harvest schedules. California's Thomas Keller Restaurant Group operates captive supply agreements with Fresh Origins.
- Caterers:Event service providers requiring volume consistency for wedding and corporate hospitality contracts. London's high-end catering sector sources through consolidated importers with EFSA compliance expertise.
- Home Cooks:Enthusiast consumers purchasing through subscription services and specialty retail. New York and London direct-to-consumer boxes emphasize Instagram-ready packaging and recipe cards.
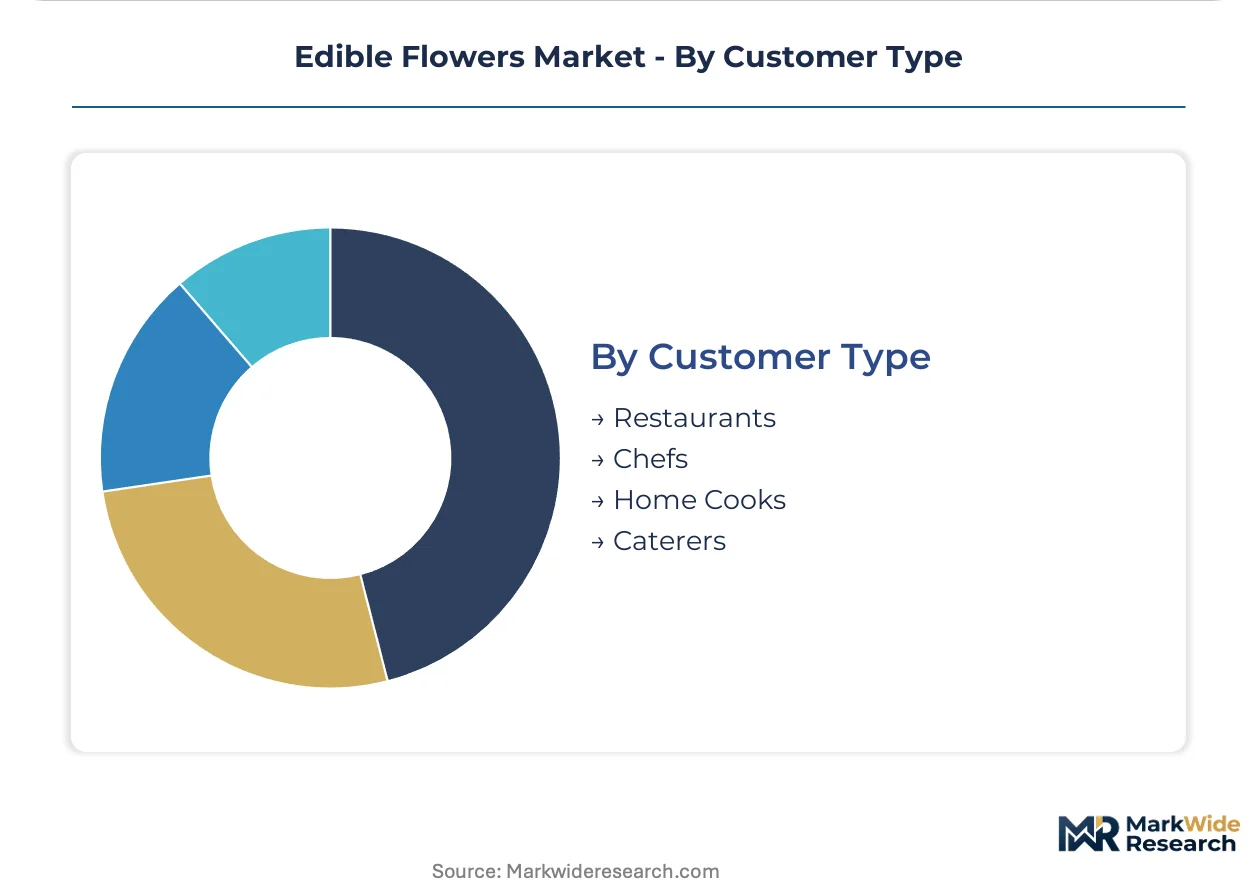
Restaurants command the dominant procurement volume, though Home Cooks is climbing the fastest through social media content creation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across consumption tiers. Home cooks in Tokyo and New York absorb 40-60 percent cold-chain premiums for traceable violas, while mass-market bakeries in São Paulo and Jakarta substitute synthetic colorants at one-fifth the cost.
United States
San Diego County vertical farms supply Fresh Origins to Thomas Keller Restaurant Group and Manhattan's Eleven Madison Park. FDA Food Safety Modernization Act traceability rules compress harvest-to-plate documentation windows. California's controlled-environment agriculture clusters dominate viola and nasturtium year-round production for domestic fine-dining procurement.
France
Provence-Alpes-Côte d'Azur heritage cultivation clusters supply Parisian palace hotels through direct farm partnerships. EU Novel Food Regulation EFSA assessments gatekeep calendula and cornflower commercial approval. Nice farmers markets anchor seasonal home cook experimentation with crystallized rose and lavender varieties.
Netherlands
Koppert Cress B.V. leverages FloraHolland auction systems to set European viola and sorrel flower reference pricing. EFSA General Food Law reinforces phytosanitary certification requirements for export shipments. Westland greenhouse complexes concentrate year-round controlled-environment agriculture output for foodservice distributors.
United Kingdom
London's hotel bar sector specifies traceable borage and lavender supply chains for corporate hospitality accounts. Food Standards Agency novel food consultations align with EFSA assessment timelines. Norfolk heritage growers supply Nurtured in Norfolk direct-to-consumer subscription boxes emphasizing Instagram-ready packaging.
Japan
Kyoto kaiseki practitioners drive specialized demand for shiso and nasturtium leaf cultivar selections. Ministry of Health, Labour and Welfare food additive regulations govern floral syrup and infusion classifications. Tokyo direct-to-consumer subscription services capture home cook social media content creation demand with sub-24-hour harvest guarantees.
Edible Flowers Market Vendor Landscape
Controlled-environment agriculture specialists and heritage soil-based growers split the market along traceability and scale vectors. Dutch greenhouse operators command European volume through auction system integration, while North American vertical farms capture premium tiers via hyperlocal delivery radius claims. Three archetypes dominate: technology-integrated indoor farms, heritage cultivation cooperatives, and diversified specialty produce houses. Consolidation pressure intensifies through strategic partnerships between seed breeders and cold-chain logistics providers, plus backward integration by restaurant groups into captive supply agreements.
Among Netherlands-based controlled-environment specialists, Koppert Cress B.V. exemplifies the technology-integrated archetype through its Westland greenhouse network. Fresh Origins, LLC occupies a parallel position in North American supply, anchoring premium-tier procurement for California and New York fine-dining establishments. Farm.One Holdings, Inc. represents the hyperlocal indoor farm model, situating its operations within Manhattan's dense restaurant corridor to eliminate freight miles entirely.
| Leading Market Players |
|---|
| Sainsbury's |
| Chef's Garden, Inc. |
| Fresh Origins, LLC |
| Cherry Valley Organics |
| Nurtured in Norfolk |
| Koppert Cress B.V. |
| Maddocks Farm Organics |
| Petite Ingredient |
| Farm.One Holdings, Inc. |
| Others |
Supply Flow & Price Mechanics
Netherlands greenhouse concentration at Koppert Cress and FloraHolland auction systems funnels margin pools toward viola and sorrel flower producers with year-round controlled-environment capacity, while North American vertical farms extract premiums through hyperlocal delivery radius claims below 50 miles.
Pricing Analysis
After-sales service contracts for cold-chain monitoring and traceability documentation drive lifetime value extraction from Michelin-starred kitchens and export distributors. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and harvest-to-plate window, with EFSA novel-food approval commanding substantial markups over uncertified heritage varieties. Cost compression in standard-tier wholesale channels is intensifying because Dutch auction reference pricing exposes growers to spot-market volatility. Mass-market bakeries exhibit highest price sensitivity, substituting synthetic colorants at one-fifth the cost, while fine-dining procurement teams absorb cold-chain premiums for traceable cultivar genetics.
Supply Chain Analysis
EU Novel Food Regulation phytosanitary certification requirements function as export-control mechanisms limiting species flows into commercial channels, with EFSA assessments requiring 18-24 months for new cultivar approvals. Geographic supply concentration centers on the Netherlands for European viola volume, California for North American nasturtium production, and Japan for specialized shiso leaf selections. Raw material dependencies include hybrid seed stock from Dutch breeders, climate-controlled greenhouse infrastructure from Westland suppliers, and specialized cold-chain packaging from European manufacturers. Single-source vulnerability runs through Netherlands auction system dominance, where 70 percent of European volume concentrates through FloraHolland. Distribution runs through consolidated foodservice wholesalers for institutional buyers, direct farm partnerships for palace hotels, and subscription platforms for home cook segments.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edible flower supply fragmentation across heritage soil-based growers and technology-integrated indoor farms creates niche entry points, as chef-driven varietal specification displaces grower-centric production planning and demands specialized post-harvest performance metrics.
For Market Incumbents: Harden supply security through backward integration into hybrid seed breeding programs that compress cultivar-to-certification timelines, and fortify cold-chain infrastructure partnerships to defend against perishability economics eroding landed cost competitiveness. Synthetic colorant substitution in mass-market tiers threatens volume-based revenue streams, while phytosanitary certification bottlenecks freeze legacy varietal portfolios. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription services for London, New York, and Tokyo home cooks, where social media content creation demand outpaces foodservice growth rates and bypasses traditional distribution markups. India's underdeveloped BIS standards for edible flowers offer regulatory shaping opportunities in Karnataka and Tamil Nadu before formal certification rules crystallize. Go-to-market positioning should emphasize Instagram-ready packaging with sub-24-hour harvest guarantees and QR-coded traceability. For Investors and Strategic Acquirers: Capital is best deployed toward controlled-environment agriculture specialists with verifiable sub-50-mile radius claims and established EFSA compliance expertise, given long-term viability hinges on carbon labeling convergence under EU Green Deal reporting requirements. Acquisition target archetype: mid-cap vertical farms with chef procurement relationships and proprietary varietal breeding pipelines. Watch for EFSA accelerated assessment pathway expansions for traditional foods from third countries as inflection indicators for Southeast Asian and Latin American market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Varietal Breeding Program Investment | Shortens cultivar-to-certification pathways for EFSA novel-food approvals, unlocking commercial cultivation of torch ginger and Mexican marigold varieties. |
| Hyperlocal Vertical Farm Expansion | Eliminates freight miles and pesticide residues for Manhattan and San Diego fine-dining procurement teams demanding traceable garnishes. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale distribution markups while capturing home cook social media content creation demand in London and Tokyo. |
| Blockchain Traceability Integration | Digitizes seed-to-plate provenance verification for Michelin-starred kitchens, commanding 15-25 percent premiums over untraceable supply. |
| Heritage Cultivation Documentation Consolidation | Expedites EFSA accelerated assessment pathway entry for French and Italian importers sourcing traditional foods from third countries. |
Methodological Framework
The analysis maps fresh-cut petals, flowering herbs, sprouts, and leaf tissues, each validated through executive interviews with controlled-environment agriculture operators, heritage cultivation cooperative leaders, fine-dining procurement directors, cold-chain logistics specialists, and regulatory affairs consultants. Secondary sources include FDA Food Safety Modernization Act guidance documents, EFSA novel-food assessment databases, EU General Food Law implementation reports, BIS draft standards for Indian edible flower protocols, and customs trade data from Netherlands FloraHolland auction systems. Bottom-up cultivar volume estimates triangulate against top-down foodservice procurement spend analyses.
Assumptions held fixed include EFSA regulatory assessment timelines, FDA traceability rule implementation schedules, and EU Green Deal carbon reporting phase-in trajectories, while variables include novel-species approval expansions, vertical farm capacity buildout rates, and home cook subscription adoption curves. Segmentation dimensions modeled span product type, application, distribution channel, and customer type, with additional granularity on cultivar genetics and harvest-to-plate window specifications. CAGRs derive from weighted average growth trajectories across these segments, incorporating cold-chain infrastructure investment cycles and chef procurement contract renewal patterns as industry-specific inputs.
Sensitivities concentrate around EFSA assessment timeline compressions or extensions, climate-controlled energy cost volatility affecting greenhouse operations, and synthetic colorant substitution rates in mass-market tiers. Cross-checking against restaurant procurement database benchmarks and specialty produce distributor invoice analyses is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Japan Frozen Fruit Puree Market
Fruits and Vegetables
Spain Lime Market
Fruits and Vegetables
Dehydrated Beets Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Fresh Apricots Market
Fruits and Vegetables
Global Dried Apricots Market
Fruits and Vegetables
Yacon Fruit Extract Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
Grapefruit Peel Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Peaches and Nectarines Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market