
 Peaches and Nectarines Market | 2026-2036
Peaches and Nectarines Market Size, Share, and Industry Trends Forecast 2026-2036
Peaches and Nectarines Market Analytics
The gap between premium and commodity tiers is broadening as export-grade varieties command冷链 investments while domestic bulk supply faces margin compression. Prima Wawona leverages its California growing base to dominate branded retail placement. Del Monte Produce anchors its position through backward integration into Central American orchards. Stemilt Growers differentiates via proprietary variety development and controlled-atmosphere storage networks.
Peaches and nectarines are deciduous stone fruits of the Prunus persica species, distinguished by their fuzzy or smooth skin and climacteric ripening patterns requiring precise temperature management between 0°C and 2°C to delay ethylene-triggered softening. Commercial production targets fresh consumption, processing into purees, and canning applications where Brix levels and firmness specifications determine grade. Fresh peaches lead volume but face perishability constraints that compress margins; canned peaches occupy stable shelf-stable demand from institutional buyers. Online retail is expanding fastest among distribution channels as direct-to-consumer platforms reduce intermediaries for specialty growers.
The USDA Agricultural Marketing Service administers federal grade standards that determine price differentials across U.S. wholesale terminals. The FDA's Food Safety Modernization Act mandates preventive controls for orchards and packing houses supplying interstate commerce. The EU's Maximum Residue Level regulations under EFSA oversight restrict pesticide applications for fruit entering European ports. Stakeholders must monitor phytosanitary protocol negotiations between major exporting nations and assess climate adaptation investments as growing region viability shifts.
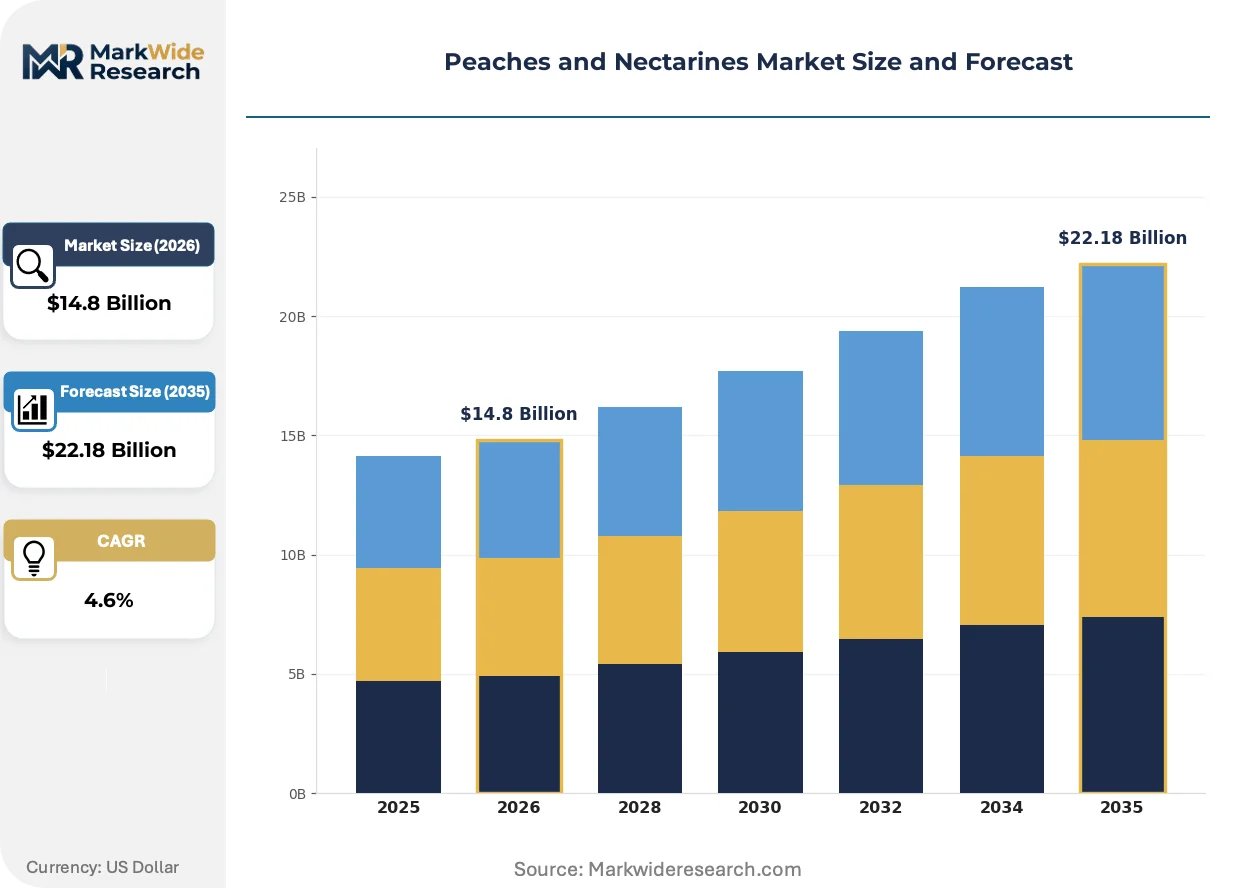
Market Dynamics
Cold-chain infrastructure investment is compressing spoilage windows and enabling premium variety export economics that previously failed at origin. This temperature-controlled logistics expansion is redrawing competitive boundaries between integrated operators and commodity bulk handlers.
Growth Catalysts
- USDA Grade Standard Tightening:The Agricultural Marketing Service's revised firmness and Brix benchmarks for U.S. Fancy and U.S. Extra Fancy classifications are forcing quality upgrades across California and Washington packing houses.
- Food Service Cold-Chain Penetration:Restaurant and hospitality operators are expanding fresh stone fruit procurement as refrigerated last-mile networks reach secondary cities.
- Climacteric Ripening Control:Ethylene scrubbing and controlled-atmosphere storage technologies are extending shelf life for export-grade nectarines bound for East Asian terminals.
Market Restraints
- Input Cost Volatility:Labor availability for hand-thinning and harvest operations in California's Central Valley fluctuates with immigration policy enforcement intensity.
- Supply Concentration Risk:China's dominance in processed peach and nectarine concentrate creates single-source dependency for European canneries and beverage formulators.
- Perishability Technical Limitation:The 0°C to 2°C narrow window for delaying ethylene-triggered softening leaves minimal margin for refrigeration failure in multi-modal shipments.
Strategic Opportunities
- Direct-to-Consumer Channel Expansion:Specialty growers in Oregon and Colorado are bypassing wholesale terminals through subscription box platforms and farm-gate e-commerce.
- EU Maximum Residue Level Alignment:Orchard operators achieving EFSA-compliant pesticide protocols gain automatic preferential access to Rotterdam and Hamburg port inspections.
- Proprietary Variety Development:Controlled breeding programs for low-chill cultivars are opening subtropical production zones in Brazil and northern India previously excluded from commercial stone fruit cultivation.
Industry Challenges
- Phytosanitary Certification Timeline:Export shipments to Japan and South Korea face multi-week protocol verification delays that compress selling windows for peak-harvest fruit.
- Integrated Pest Management Skill Gap:Orchard managers with expertise in mating disruption and biological control agent deployment command wage premiums that strain mid-size operator margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peaches and Nectarines Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Peaches, Canned Peaches, Dried Peaches, Juice Distribution Channel: Supermarkets, Online Retail, Farmers Markets, Wholesale Packaging Type: Boxes, Pouches, Cans, Jars End User: Households, Food Service, Bakeries, Canning Facilities |
| Companies Covered | BeFresh Ltd, Del Monte Produce, Prima Wawona, Sunkist Growers, Stemilt Growers, DLJ Produce Inc, Sun World International LLC, Fresh Del Monte Produce, Dole Food Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peaches and Nectarines Market Evolving Landscape
Precision agriculture and post-harvest biotechnology are converging to rewrite yield-to-quality ratios in stone fruit production. These innovations are shifting competitive advantage toward capital-intensive operators with data infrastructure.
Hyperspectral imaging systems for non-destructive firmness and sugar content assessment are consolidating quality control at packing house infeeds. Major California cooperatives are deploying these units to replace manual USDA grading lines. The technology is consolidating procurement power toward integrated handlers who can amortize equipment across multi-variety seasons.
The EU's Farm to Fork Strategy under the European Green Deal is tightening pesticide reduction targets for fruit entering single-market distribution. Member state authorities are accelerating residue testing frequency at border inspection posts. Spanish and Italian exporters with established organic certification pipelines are capturing shelf space as conventional suppliers face rejection rates at Rotterdam.
Restaurant procurement departments are unbundling produce sourcing from broadline distributors to establish direct relationships with branded growers. This disintermediation is most visible in fast-casual chains with centralized menu development in California and Texas, where specified variety and harvest-date contracts now replace commodity spot purchasing.
Peaches and Nectarines Market Segmentation
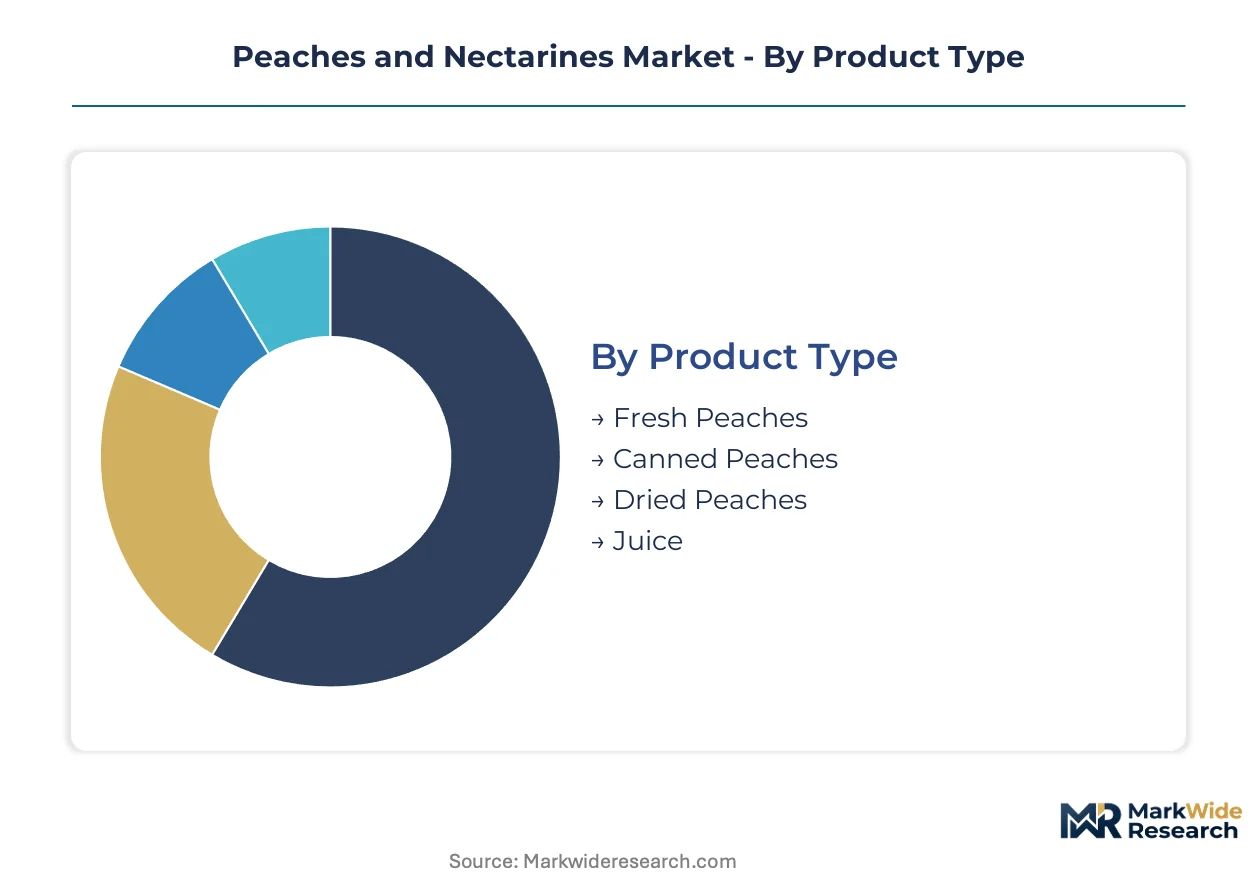
Segmentation in stone fruit markets reveals how perishability constraints and cold-chain economics fragment value capture across handlers. Product form and channel selection determine margin structure more than volume scale for most operators.
Product Type:
Standardization dominates shelf-stable formats while fresh segments demand cultivar-specific customization for Brix and firmness targets.
- Fresh Peaches:Climacteric ripening requires precise 0°C to 2°C cold-chain maintenance from orchard to retail. Demand concentrates in California and Washington supermarket channels where USDA Extra Fancy grade premiums justify controlled-atmosphere storage investments.
- Canned Peaches:Thermal processing stabilizes Brix levels and texture for institutional procurement. Food service operators in Texas and Florida anchor volume as they standardize menu specifications across multi-location chains.
- Dried Peaches:Moisture reduction to 15-20% extends shelf life for snack and baking applications. California processors supply bulk ingredients to cereal manufacturers.
- Juice:Nectar and concentrate production targets beverage formulators seeking stone fruit flavor profiles. Chinese processors dominate international concentrate trade.
Leading the category by volume: Fresh Peaches. Expanding most quickly: Canned Peaches in institutional channels.
Distribution Channel:
Channel selection maps directly to cold-chain infrastructure ownership and customer relationship intensity.
- Supermarkets:Branded variety placement and promotional calendar alignment drive procurement decisions. Retail consolidation in California and Arizona concentrates negotiating power with three chains controlling regional shelf access.
- Online Retail:Direct-to-consumer platforms enable harvest-date specificity and subscription revenue models. Specialty growers in Oregon and Colorado leverage this channel to bypass wholesale terminal price compression.
- Farmers Markets:Farm-gate sales capture full retail margin for small-scale operators with limited cold-chain reach. Urban corridor locations in Denver and Portland generate highest per-pound realization.
- Wholesale:Terminal market auctions price commodity grades for processors and secondary retailers. Los Angeles and Philadelphia terminals set reference pricing for eastern and western supply basins.
Channel commanding highest margins: Online Retail. Volume anchor: Supermarkets.
Packaging Type:
Packaging investment correlates with shelf-life extension requirements and retail presentation standards.
- Boxes:Corrugated containers with modified atmosphere liners protect firmness during multi-day transit. California cooperatives deploy this format for cross-country supermarket replenishment.
- Pouches:Flexible packaging reduces freight cube for dried and processed segments. Snack brands in Texas specify pouch formats for club store multipacks.
- Cans:Tinplate and aluminum containers provide shelf stability for institutional food service procurement. Midwest canneries in Illinois and Ohio source conventional grade fruit for this channel.
- Jars:Glass packaging targets premium preserves and specialty retail positioning. Small-batch processors in Washington and Michigan command price premiums for visible product quality.
Dominant format by tonnage: Boxes. Steepest expansion trajectory: Pouches in direct-to-consumer shipments.
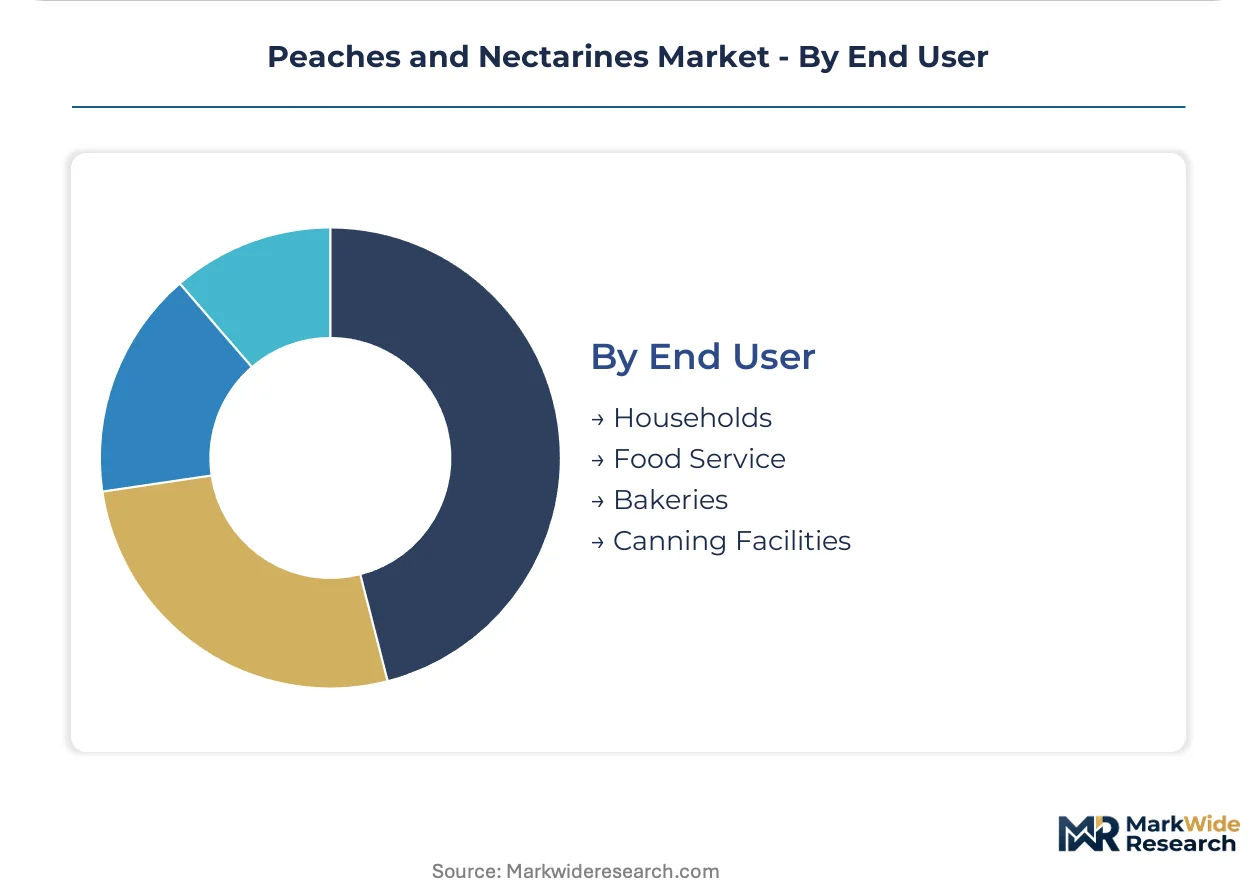
End User:
End-use segmentation separates price-sensitive commodity buyers from specification-driven premium purchasers.
- Households:Fresh consumption drives cultivar preference for eating quality and visual appeal. Urban households in Seattle and San Francisco demonstrate willingness to pay for branded variety provenance.
- Food Service:Restaurant and hospitality operators prioritize consistent sizing and ripeness windows for menu execution. Fast-casual chains in California and Texas are disintermediating broadline distributors for direct grower contracts.
- Bakeries:Processed and dried forms integrate into pastry and dessert manufacturing. Industrial bakeries in Pennsylvania and North Carolina specify moisture content and dice dimensions for automated production lines.
- Canning Facilities:Thermal processing operations require firm-flesh varieties that maintain texture through sterilization. Midwest and Southeast canneries source from California and Georgia growing regions.
Largest volume destination: Households. Gaining share fastest: Food Service direct procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley dominates fresh stone fruit production through its integrated packing houses and controlled-atmosphere storage corridors serving export terminals at Oakland and Long Beach.
United States
USDA Agricultural Marketing Service grade standards tighten firmness and Brix benchmarks for Fancy classifications. California and Washington packing houses upgrade quality systems to maintain supermarket placement. Fresno County clusters integrate hyperspectral grading lines with cold-chain logistics for cross-country distribution.
Spain
Murcia and Lleida growing regions supply European processing demand while expanding fresh exports to Northern Europe. EFSA Maximum Residue Level enforcement accelerates at Rotterdam and Hamburg border posts. Catalan cooperatives invest in organic certification pipelines to capture shelf space from conventional suppliers facing rejection.
China
Shandong and Hebei provinces concentrate processed peach concentrate production for international beverage formulators. National pesticide residue standards under SAMR oversight tighten for export-oriented orchards. Yantai port infrastructure supports concentrate shipments to European canneries.
Italy
Emilia-Romagna and Campania maintain traditional canning operations for institutional European buyers. EU Farm to Fork Strategy pesticide reduction targets pressure conventional growers. Parma-based processors diversify into premium jarred preserves for specialty retail positioning.
Australia
Victoria's Goulburn Valley supplies domestic fresh consumption and limited export volumes to Asian markets. State biosecurity protocols govern interstate movement and international phytosanitary certification. Shepparton packing facilities deploy modified atmosphere packaging for extended shelf-life consignments.
Peaches and Nectarines Market Competitive Landscape
Premium-margin players sit above commodity-margin players across cold-chain infrastructure ownership and proprietary variety access. The vendor base stratifies between integrated operators with backward integration into orchard assets and commodity handlers dependent on spot procurement. Three archetypes dominate: branded retail placement specialists, processing-anchored diversified agribusinesses, and direct-to-consumer subscription platforms. Capacity consolidation through cooperative mergers and controlled-atmosphere storage network expansion represent the primary competitive vectors.
Within the branded retail tier, Prima Wawona and Stemilt Growers exemplify operators leveraging geographic concentration and proprietary development programs. Del Monte Produce occupies a position representing processing-anchored diversification with Central American orchard integration. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| BeFresh Ltd |
| Del Monte Produce |
| Prima Wawona |
| Sunkist Growers |
| Stemilt Growers |
| DLJ Produce Inc |
| Sun World International LLC |
| Fresh Del Monte Produce |
| Dole Food Company |
| Others |
Value Network & Pricing Analysis
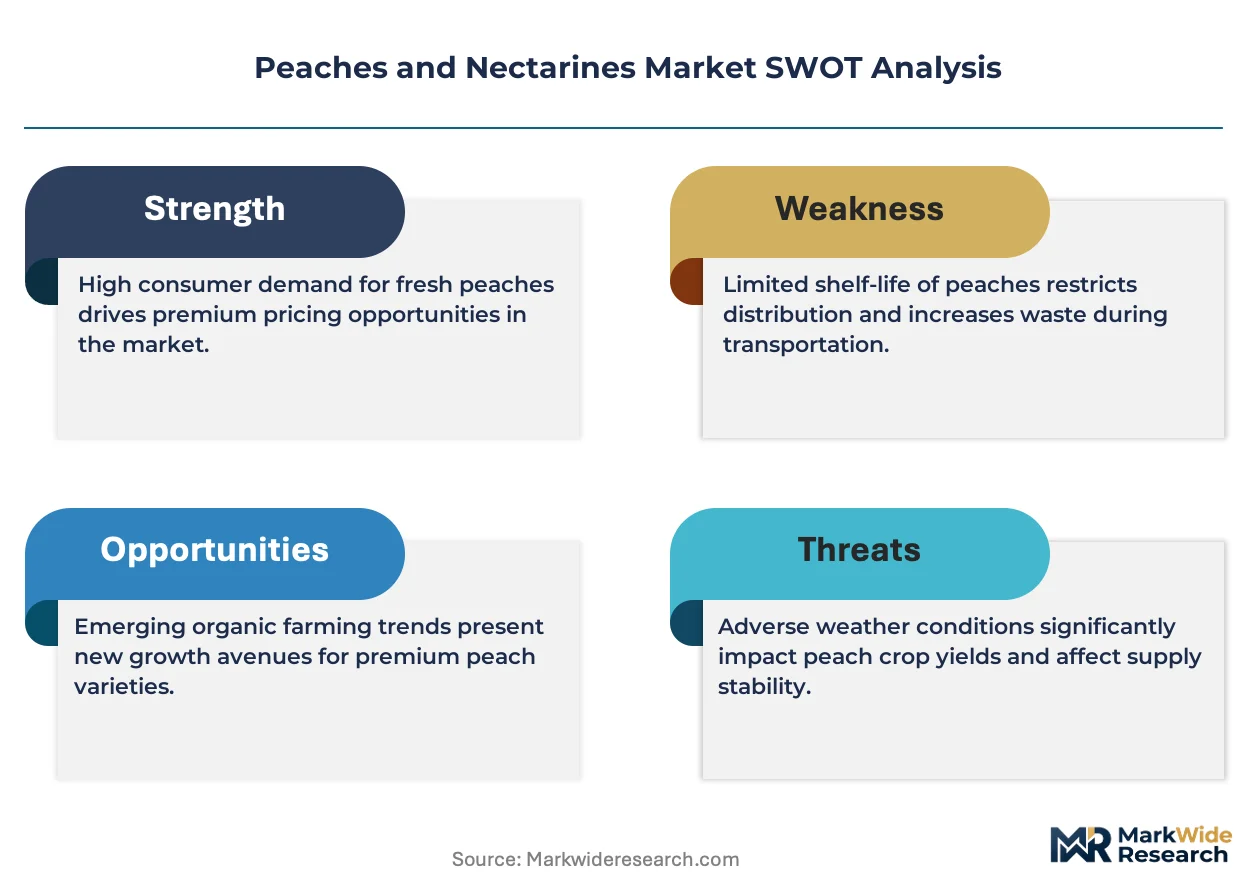
USDA Agricultural Marketing Service grade tightening for U.S. Fancy and U.S. Extra Fancy classifications forces California and Washington packing houses to upgrade quality systems, compressing margins for handlers unable to amortize controlled-atmosphere storage investments across multi-variety seasons.
Pricing Analysis
Yield-per-acre outcomes and harvest-date specificity anchor pricing negotiations between branded growers and fast-casual chains in California and Texas. Three-tier pricing structure across USDA Extra Fancy, U.S. Fancy, and processing grades separates origin-provenanced varieties from commodity terminal fruit. Cost compression in domestic bulk supply intensifies because labor availability fluctuations in California's Central Valley destabilize harvest cost structures. Food service operators demonstrate lowest price sensitivity for specified variety contracts, while wholesale terminal buyers exhibit highest sensitivity to grade discounts.
Supply Chain Analysis
Rejected fruit flows from Rotterdam and Hamburg border posts feed back into European processing channels as Spanish and Italian exporters face EFSA Maximum Residue Level enforcement acceleration. California, Spain, and China concentrate supply across fresh export, European distribution, and processed concentrate production respectively. Cold-chain infrastructure draws from reefer container availability and controlled-atmosphere storage capacity at Oakland and Long Beach terminals. Single-source dependency for Chinese processed peach concentrate creates vulnerability for European canneries. Distribution runs through integrated cooperative networks for branded retail placement and terminal market auctions for commodity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperspectral imaging systems for non-destructive firmness assessment are displacing manual USDA grading lines, concentrating procurement power toward capital-intensive operators with data infrastructure and multi-variety season coverage.
For Market Incumbents: Lock in backward integration into Central American orchards to secure harvest-date specificity for food service direct contracts. Acquire controlled-atmosphere storage corridors serving export terminals before cooperative mergers consolidate regional capacity. Prima Wawona's California growing base demonstrates how geographic concentration defends branded retail placement against commodity handlers. For New Entrants and Emerging Players: The premium-to-economy price gap in subscription box platforms offers white-space entry for specialty growers in Oregon and Colorado with limited cold-chain reach. Farm-gate e-commerce in Denver and Portland urban corridors captures full retail margin unavailable at wholesale terminals. Target institutional canning procurement in Texas and Florida where menu standardization across multi-location chains stabilizes volume commitments. For Investors and Strategic Acquirers: Re-rating potential sits with integrated operators possessing proprietary variety development programs given climacteric ripening control technology expansion into subtropical production zones. Five-to-ten year viability favors handlers with captive cold-chain infrastructure over spot-dependent commodity traders. Monitor phytosanitary protocol negotiations between major exporting nations and Japan or South Korea for early signals of selling window compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Storage Network Expansion | Extends shelf life for export-grade nectarines bound for East Asian terminals through ethylene scrubbing deployment. |
| Proprietary Variety Development Program | Opens subtropical production zones in Brazil and northern India via low-chill cultivar breeding pipelines. |
| Direct-to-Consumer Platform Launch | Bypasses wholesale terminal price compression for specialty growers in Oregon and Colorado through subscription revenue models. |
| Organic Certification Pipeline Investment | Captures shelf space from conventional suppliers facing rejection rates at Rotterdam under EU Farm to Fork Strategy targets. |
| Backward Integration into Orchard Assets | Secures harvest-date specificity for fast-casual chain contracts in California and Texas through Central American growing base control. |
Research Methodology
Independent corroboration across packing house operations managers, food service procurement directors, and cold-chain logistics coordinators underwrites the qualitative findings in this study. Primary interviews with orchard managers, cooperative board members, and USDA Agricultural Marketing Service inspectors combined with secondary validation from FDA Food Safety Modernization Act guidance documents, EFSA Maximum Residue Level databases, and EU Farm to Fork Strategy implementation reports. Bottom-up volume estimates from California and Washington growing region cluster data triangulate against top-down trade flow analysis through Oakland and Long Beach terminals.
Rate-of-change decomposition across the projection horizon separates volume growth from price realization improvement in fresh versus processed segments. The analytical framework models product type, distribution channel, packaging format, and end-user segmentation dimensions alongside regional regulatory cluster variations. CAGRs derive from trend extrapolation of cold-chain penetration rates and food service procurement pattern shifts. Forecast inputs incorporate climacteric ripening technology adoption curves and phytosanitary protocol timeline assumptions.
Inputs from cooperative financial disclosures and port authority throughput statistics were available through the study window; gaps in real-time immigration policy enforcement intensity data introduce uncertainty bands around labor cost assumptions. Forecasts reflect documented assumptions regarding cold-chain infrastructure investment continuity and EU pesticide reduction target enforcement pace. Practitioners should monitor SAMR oversight tightening in Chinese export-oriented orchards and EFSA border inspection post staffing levels for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Apple Concentrate Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Pomegranate Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Europe Dried Mushroom Market
Fruits and Vegetables
Fruit Pulp Market
Fruits and Vegetables
Asia Pacific Olive Market
Fruits and Vegetables
Canada Fruits and Vegetables Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
Oman Fruits and Vegetables Market