
 Dried Kiwi Fruit Market | 2026-2036
Dried Kiwi Fruit Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Kiwi Fruit Market Insights
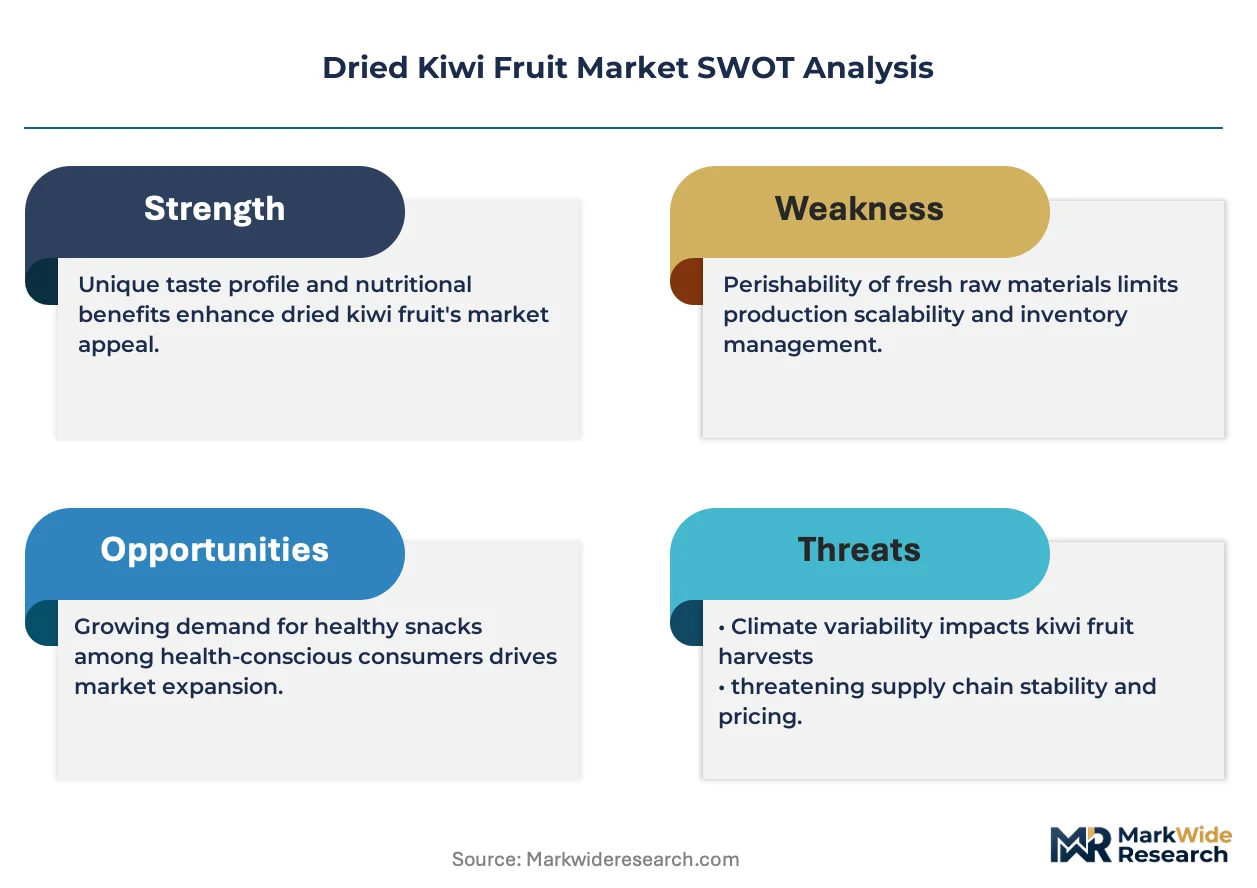
Multi-source procurement for kiwi raw material is decoupling from the historical reliance on New Zealand seasonal supply. FruitsMax leverages diversified Southern Hemisphere contracts to sustain year-round production continuity. Zespri Group Limited anchors its position through proprietary cultivar control and strict quality protocols. Paradise Fruits Solutions GmbH & Co. KG differentiates via advanced osmotic dehydration technology that preserves vitamin C content.
Dried kiwi fruit consists of sliced or whole Actinidia deliciosa subjected to controlled hot-air dehydration at 50–70°C until moisture falls below 20%, yielding a shelf-stable product with concentrated potassium and dietary fiber. The primary commercial purpose centers on supplying clean-label snack ingredients and standalone retail packs for health-conscious consumers. Organic dried kiwi leads product type margins due to certification premiums and supply scarcity, while sugar-free variants represent the fastest-growing category as diabetic-friendly formulations expand. Online retail channels are displacing traditional supermarket dominance in volume growth, though health food stores retain the highest per-unit profitability through curated assortment strategies.
EU Green Deal packaging rules and REACH chemical safety standards shape product compliance costs for European market entry, while FDA food facility registration governs US import pathways. EFSA novel food assessments occasionally delay flavored dried kiwi introductions containing non-traditional additives. Stakeholders must monitor evolving extended producer responsibility laws that shift end-of-life packaging costs onto importers and manufacturers.
Market Dynamics
The EU Green Deal's extended producer responsibility mandates are forcing dried kiwi fruit packagers to absorb end-of-life packaging costs, compressing margins and accelerating format transitions toward compostable materials.
Growth Catalysts
- REACH chemical safety standards:European compliance requirements are filtering out low-grade competitors, creating premium positioning opportunities for certified organic producers.
- Diabetic-friendly snack demand:Sugar-free dried kiwi formulations are capturing shelf space in pharmacy and specialized nutrition retail channels.
- Chile and Italy:Dual-sourcing strategies from these counter-seasonal growing regions are eliminating New Zealand supply monopolies and stabilizing year-round raw material flows.
Market Restraints
- Fresh kiwi price volatility:Weather-driven crop failures in major growing regions transmit directly to dried product input costs with limited hedging mechanisms.
- New Zealand cultivar concentration:Zespri's proprietary Gold3 and Green14 variety control creates licensing bottlenecks for premium dried fruit positioning.
- EFSA novel food assessments:Flavored or fortified dried kiwi introductions face 12-18 month regulatory evaluation timelines that delay commercialization.
Strategic Opportunities
- Compostable pouch mandates:EU Green Deal packaging rules are creating first-mover advantages for suppliers with certified biodegradable film capabilities.
- Direct-to-consumer subscription models:Online retail channels are displacing supermarket intermediaries, enabling margin capture and customer data ownership.
- Osmotic dehydration advancement:Convergence of pulsed electric field pretreatment with vacuum drying is preserving vitamin C at rates matching freeze-drying at lower energy intensity.
Industry Challenges
- Food technologist scarcity:Specialized expertise in low-temperature dehydration protocols for heat-sensitive bioactive compounds remains concentrated in European research institutes.
- Organic certification timelines:Three-year conversion periods for conventional orchards block rapid supply expansion during demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Kiwi Fruit Market |
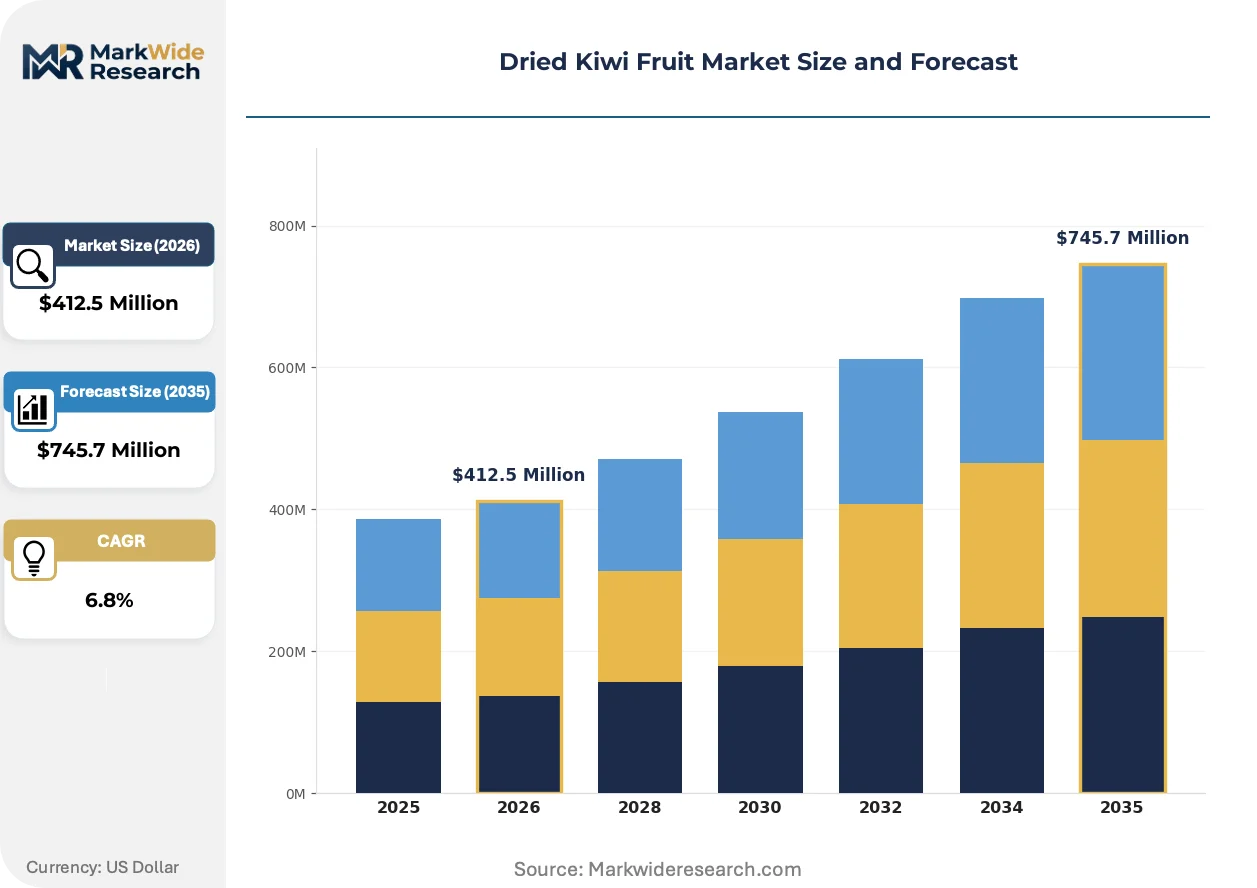
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Dried Kiwi, Conventional Dried Kiwi, Sugar-Free Dried Kiwi, Flavored Dried Kiwi Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops End User: Households, Food Service Industry, Catering Businesses, Snack Manufacturers Packaging Type: Bags, Jars, Pouches, Bulk Packaging |
| Companies Covered | FruitsMax, JAB Dried Fruit Products, Zespri Group Limited, NutraDry, Nature's Delight, Del Monte Foods, Greek Family Farm, Paradise Fruits Solutions GmbH & Co. KG, SunGold Dried Fruits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Kiwi Fruit Market Trends and Innovations
Processing technology convergence and regulatory packaging mandates are reconfiguring competitive advantage away from raw material access toward processing sophistication and format compliance.
Pulsed electric field pretreatment is integrating with conventional hot-air dehydration lines to reduce drying times by 30-40% while preserving polyphenol content. Snack manufacturers in Germany and the Netherlands are retrofitting existing facilities at moderate capital intensity. This technology convergence is integrating mid-tier processors into premium supply chains previously reserved for freeze-drying specialists.
EU Green Deal extended producer responsibility laws are shifting end-of-life packaging costs onto importers and manufacturers, forcing redesign of multi-layer film structures. Compostable pouch formats certified under EN 13432 are displacing conventional metallized laminates in German health food retail. French and Italian distributors are demanding supplier guarantees on packaging recovery infrastructure.
Health-conscious consumers are rotating purchasing toward curated online specialty retailers that provide origin transparency and batch-specific nutritional data. German e-commerce platforms specializing in functional foods are capturing volume growth that outpaces traditional supermarket channels. This channel migration concentrates in urban centers where subscription logistics achieve delivery density.
Dried Kiwi Fruit Market Segmentation
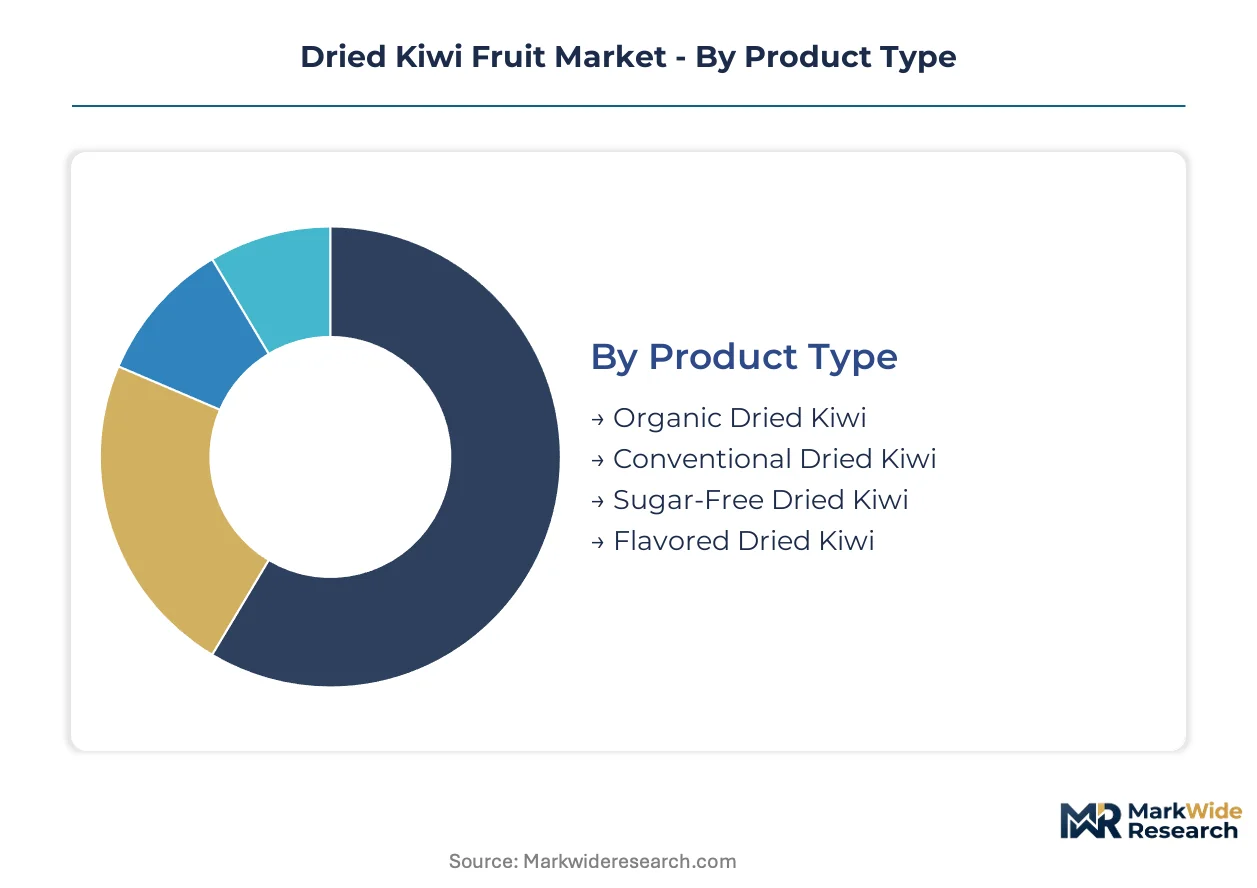
Segmentation in dried kiwi fruit reveals how certification premiums, channel economics, and processing specifications partition commercial opportunity. Product type and packaging format choices determine margin capture, while distribution channel selection governs customer acquisition costs and brand positioning.
Product Type:
Processing intensity and input certification grade define the technology axis across product categories.
- Organic Dried Kiwi:Derived from orchards under three-year conversion protocols with prohibited synthetic inputs. German health food retail channels absorb the majority of EU organic volume, with ECHA REACH compliance adding verification costs that filter out commodity competitors.
- Sugar-Free Dried Kiwi:Formulated through controlled osmotic dehydration without sucrose addition, targeting diabetic-friendly and ketogenic diet segments. Pharmacy retail in the Netherlands and specialized nutrition e-commerce in Germany are expanding shelf space most aggressively.
- Conventional Dried Kiwi:Standard hot-air dehydration of non-certified fruit serves price-sensitive food service procurement.
- Flavored Dried Kiwi:Infused variants with ginger, chili, or citrus coatings face EFSA novel food assessment timelines that delay commercialization.
Mature deployment sits with Conventional Dried Kiwi. Newer deployment is concentrated in Sugar-Free Dried Kiwi.
Distribution Channel:
Customer acquisition economics and logistics density determine channel viability for different product formats.
- Online Retail:Direct-to-consumer platforms enable subscription models with batch-level origin transparency. Urban German logistics clusters achieve delivery density that supports margin capture previously eroded by supermarket intermediaries.
- Health Food Stores:Curated assortment strategies command per-unit profitability premiums through educated staff and certified product positioning.
- Supermarkets:Volume concentration in conventional formats faces slotting fee pressure and private label displacement.
- Specialty Shops:Ethnic grocery and gift retailers serve niche ceremonial and diaspora demand with limited scale.
Volume leadership remains with Supermarkets. Profitability expansion is climbing the fastest in Health Food Stores.
End User:
Application requirements for ingredient functionality versus finished goods consumption partition demand specifications.
- Snack Manufacturers:Industrial buyers require consistent moisture content and uniform slice geometry for automated packaging lines. Clean-label ingredient demand from German and Dutch processors is accelerating contract specifications.
- Households:Direct consumption through retail channels concentrates in urban professional demographics with portable snack preferences.
- Food Service Industry:Bakery and dessert applications prioritize cost-efficient bulk formats with rehydration tolerance.
- Catering Businesses:Event and institutional procurement values visual presentation and portion control in pre-packaged formats.
Contract stability sits with Food Service Industry. Specification tightening is accelerating most sharply in Snack Manufacturers.
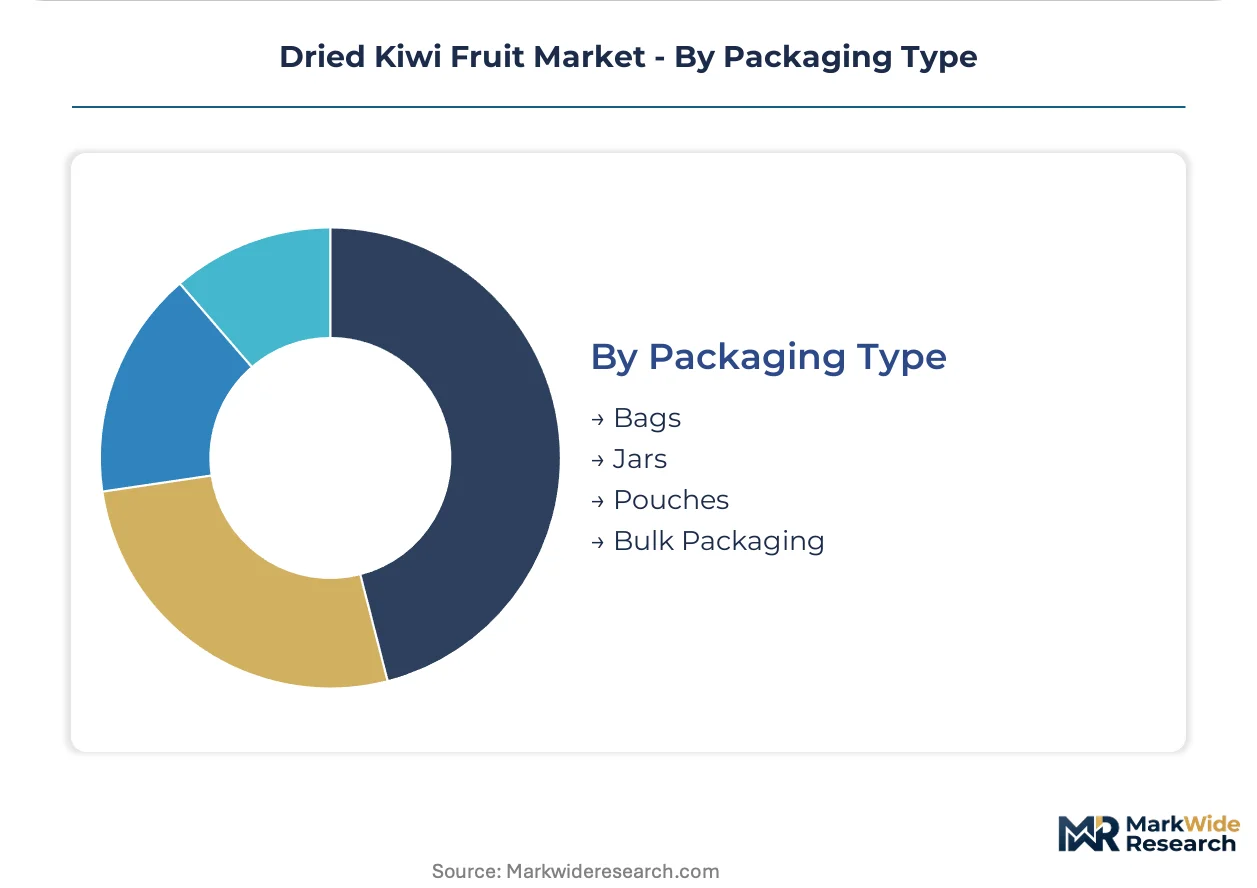
Packaging Type:
EU Green Deal extended producer responsibility mandates are reconfiguring format economics and material selection.
- Pouches:Flexible formats certified under EN 13432 compostability standards are displacing metallized laminates in German retail. Paradise Fruits Solutions and similar processors are securing first-mover positioning through biodegradable film partnerships.
- Bulk Packaging:Food service and industrial ingredient supply chains prioritize cost minimization through multi-kilogram formats with minimal branding overhead.
- Bags:Conventional polyethylene structures face margin compression from end-of-life cost absorption requirements.
- Jars:Glass formats serve premium gift positioning and reusable container preferences in specialty retail.
Regulatory compliance investment sits with Pouches. Cost minimization persists in Bulk Packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's kiwifruit orchards supply the foundational raw material that feeds processing operations across multiple continents, with counter-seasonal sourcing from Chile and Italy now disrupting traditional supply monopolies.
Germany
Health food retail chains in Berlin and Hamburg absorb the majority of EU organic dried kiwi volume, with ECHA REACH compliance adding verification costs that filter out commodity competitors. The EU Green Deal's extended producer responsibility mandates force packagers to absorb end-of-life packaging costs, accelerating transitions toward EN 13432-certified compostable pouches. Munich-based processors are retrofitting facilities with pulsed electric field pretreatment systems to reduce drying times.
United States
FDA food facility registration governs import pathways for dried kiwi entering through West Coast ports, with clean-label snack manufacturers in California and Oregon tightening contract specifications for ingredient functionality. Sugar-free formulations are capturing shelf space in pharmacy retail channels catering to diabetic-friendly diets. Los Angeles logistics clusters support direct-to-consumer subscription models that bypass traditional supermarket intermediaries.
China
Domestic kiwifruit production in Shaanxi and Sichuan provinces supplies regional processing capacity, with SAMR food safety standards governing facility inspections and product labeling. Online retail platforms in Shanghai and Beijing are displacing conventional supermarket channels for premium dried fruit categories. Yangtze River Delta processors are adopting vacuum drying technologies to preserve vitamin C content at lower energy intensity.
Netherlands
Rotterdam's port infrastructure handles bulk imports for redistribution across European snack manufacturing clusters, with EFSA novel food assessments occasionally delaying flavored dried kiwi introductions. Pharmacy retail chains in Amsterdam are expanding sugar-free variant shelf space for ketogenic diet segments. Dutch distributors are demanding supplier guarantees on packaging recovery infrastructure under evolving extended producer responsibility laws.
Chile
Counter-seasonal harvests from central valley orchards supply raw material during New Zealand's off-season, stabilizing year-round flows for international processors. The national agricultural regulator enforces phytosanitary export certifications that align with EU and US import requirements. Santiago-based trading houses coordinate dual-sourcing strategies that eliminate single-origin supply vulnerabilities.
Dried Kiwi Fruit Market Competitive Landscape
Global majors compete with regional champions across cultivar control and processing technology, producing a tiered structure where proprietary variety licensing separates premium positioning from commodity supply. Three archetypes dominate: orchard-integrated operators with cultivar patents, technology-specialized processors with advanced dehydration capabilities, and trading-focused intermediaries with multi-origin sourcing networks. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with M&A activity concentrated in complementary processing technology acquisitions.
Within the technology-specialized tier, Paradise Fruits Solutions GmbH & Co. KG exemplifies European processing sophistication through its German GmbH structure, while Zespri Group Limited anchors the cultivar-control archetype with its proprietary variety management. FruitsMax occupies a position among multi-origin sourcing specialists, representing the trading-intermediary model that leverages diversified Southern Hemisphere contracts.
| Leading Market Players |
|---|
| FruitsMax |
| JAB Dried Fruit Products |
| Zespri Group Limited |
| NutraDry |
| Nature's Delight |
| Del Monte Foods |
| Greek Family Farm |
| Paradise Fruits Solutions GmbH & Co. KG |
| SunGold Dried Fruits |
| Others |
Pricing and Supply Chain Analysis
Specialized food technologists concentrated in European research institutes command wage premiums that widen spreads between premium freeze-dried tiers and commodity hot-air grades. Labor-cost differentials between German processing clusters and Southern Hemisphere sourcing regions stratify pricing across organic certification levels.
Pricing Analysis
Warranty-backed shelf-life guarantees separate bundled premium contracts from unbundled commodity spot purchases. Three-tier pricing structure across organic, sugar-free, and conventional levels reflects certification grade and processing intensity. Price differentiation stems from EU Green Deal compliance costs and osmotic dehydration technology premiums. Cost compression in conventional tiers is intensifying because private-label supermarket procurement erodes branded positioning.
Supply Chain Analysis
EU organic certification and phytosanitary export qualifications gate entry for raw material suppliers from New Zealand, Chile, and Italy. Processing draws from dual-sourcing strategies across counter-seasonal Southern Hemisphere orchards. Supply chain risk centers on single-source vulnerability during Zespri cultivar licensing bottlenecks. Distribution runs through Rotterdam port infrastructure for European redistribution and direct-to-consumer platforms for margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around processing sophistication as EU packaging mandates and cultivar control barriers force commodity traders toward exit. Extended producer responsibility cost absorption eliminates margin-tolerant competitors.
For Market Incumbents: Lock in multi-year organic certification contracts before three-year conversion timelines block rapid supply expansion. Secure pulsed electric field dehydration partnerships to defend against freeze-drying specialists encroaching on mid-tier positioning. Backward integration into Chilean and Italian orchard equity insulates against Zespri licensing bottlenecks.
For New Entrants and Emerging Players: Enter via sugar-free diabetic-friendly formulations in German pharmacy and Dutch specialized nutrition channels where clean-label demand outpaces incumbent capacity. Target direct-to-consumer subscription models with batch-level origin transparency to bypass supermarket slotting fee structures. Leverage compostable pouch certification partnerships as a go-to-market wedge against conventional film-dependent competitors.
For Investors and Strategic Acquirers: Re-rating potential sits with technology-specialized processors given osmotic dehydration advancement convergence preserving vitamin C at lower energy intensity. Long-term viability favors firms with diversified Southern Hemisphere sourcing networks and EN 13432 packaging partnerships. Watch EFSA novel food assessment timeline compression as an inflection signal for flavored variant commercialization acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Equity | Dual-sourcing across Chile and Italy eliminates New Zealand supply monopolies. |
| Compostable Pouch Certification | EN 13432 compliance secures first-mover positioning in German health food retail. |
| Pulsed Electric Field Retrofit | Technology convergence integrates mid-tier processors into premium supply chains. |
| Direct-to-Consumer Subscription Launch | Urban German logistics density enables margin capture from supermarket intermediaries. |
| Sugar-Free Formulation Development | Pharmacy channel expansion captures diabetic-friendly and ketogenic diet segments. |
Research Methodology
Multi-period observation of kiwifruit harvest volumes, processing capacity utilization, and certification conversion timelines anchored the trend analysis, supplemented by interviews with dehydration technology specialists, organic certification auditors, health food retail category buyers, and snack manufacturer procurement directors. Secondary validation drew from customs trade databases, EFSA novel food registers, EU Green Deal implementation trackers, and orchard production statistics across New Zealand, Chile, and Italy. Bottom-up facility capacity modeling and top-down consumption demand estimation provided triangulation.
Segment-weighting across product type, distribution channel, end user, and packaging format dimensions structured the analytical framework across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory phase-in schedules and technology adoption curves. Forecast inputs incorporated EU extended producer responsibility cost trajectories and pulsed electric field equipment deployment rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA regulatory delay scenarios and fresh kiwifruit weather-driven crop failures. A model refresh is warranted upon material change in EU compostable packaging mandate enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Clean Label Fruit and Vegetable Powder Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
Peaches and Nectarines Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Cavendish Banana Market
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Aronia Berries Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market