
 Bamboo Shoots Market | 2026-2036
Bamboo Shoots Market Size, Share, and Industry Trends Forecast 2026-2036
Bamboo Shoots Market Analytics
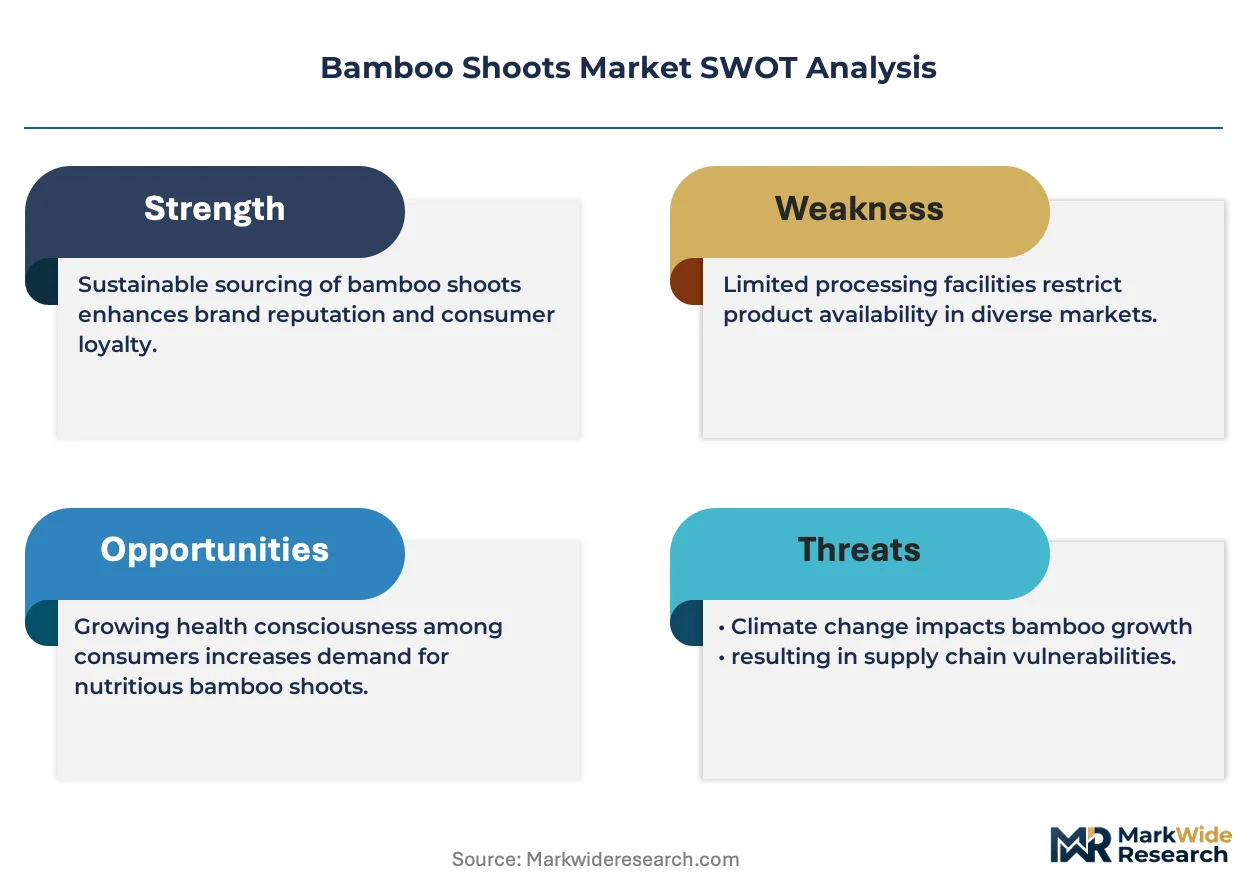
REACH residue limits for pesticide and heavy metal thresholds in imported foods is repositioning the cost-of-entry calculus for Asian exporters serving European buyers. Fujian Jihe Supply Chain Co., Ltd. leverages its integrated cold-chain network across Fujian Province to sustain year-round fresh supply reliability. VIET D.E.L.T.A INDUSTRIAL CO., LTD anchors its operations in Vietnam's bamboo-growing heartland, competing on raw material proximity and labor arbitrage. Dalian Gaishi Food Co., Ltd. dominates the frozen segment through its port-adjacent processing infrastructure, controlling logistics costs for trans-Pacific shipments.
Bamboo shoots are the edible juvenile culms of Bambusoideae grasses, harvested at 7-15 days post-emergence when lignin content remains below 3% and crude fiber stays tender for culinary processing; they serve primarily as a low-calorie, high-fiber ingredient in East Asian cuisines and as a functional food base for dietary fiber extraction. The canned product type leads volume due to shelf stability and institutional procurement patterns, though fresh varieties command premium positioning in specialty retail channels. Food & Beverage end use absorbs the dominant share of output, while pharmaceutical and nutraceutical applications extract bamboo shoot polysaccharides for glycemic control formulations, creating divergent margin pools across value chain tiers.
China's SAMR enforces GB 2762 and GB 2763 contaminant and pesticide maximum residue limits that directly determine export lot acceptance into EU markets governed by EFSA standards. The USDA and FDA jointly regulate bamboo shoot imports into the United States through phytosanitary certification and facility registration requirements under the Food Safety Modernization Act. Stakeholders must monitor regulatory divergence between CODEX-aligned Asian systems and evolving EU Green Deal due diligence rules on deforestation-linked agricultural sourcing.
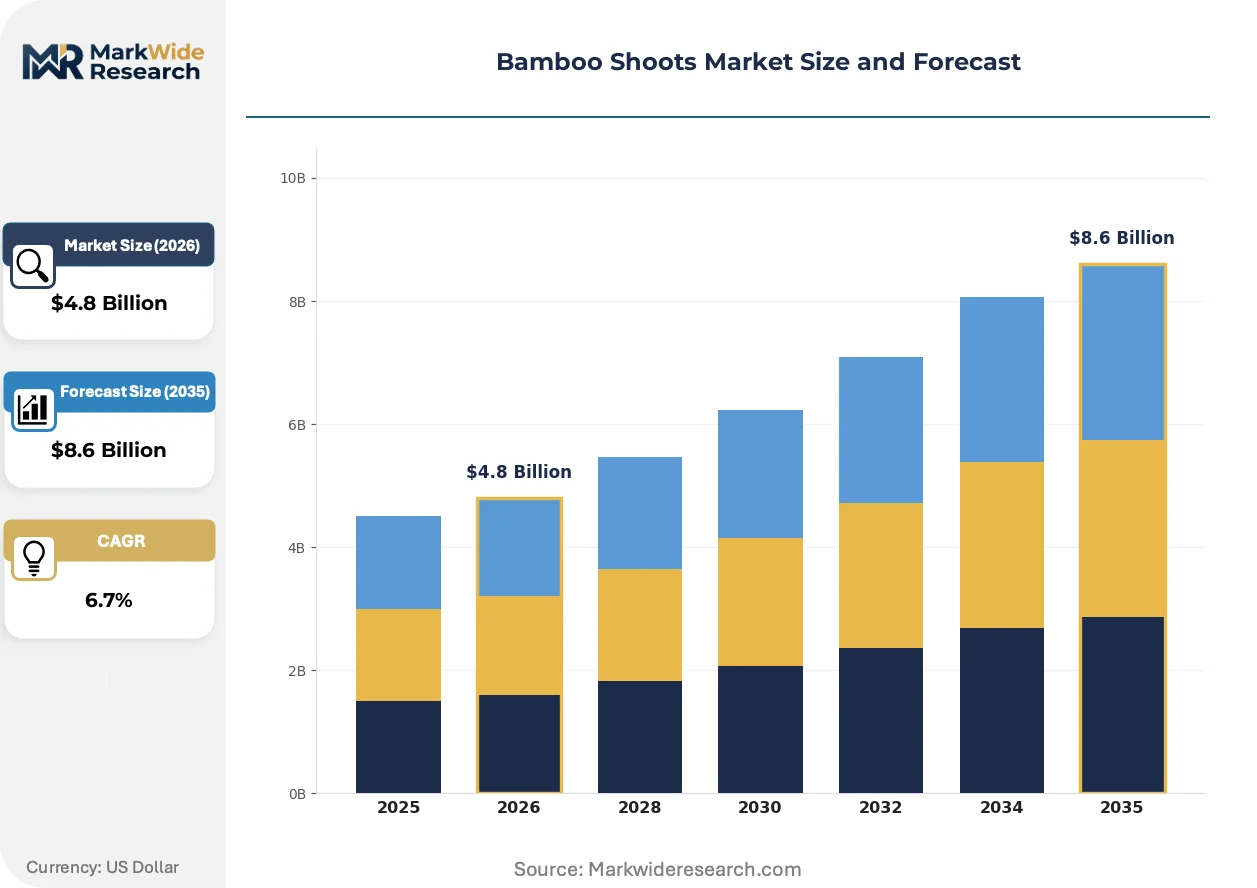
Market Dynamics
The bamboo shoots market faces intensifying regulatory divergence between China's GB standards and EU REACH residue thresholds, forcing processors to bifurcate supply chains and absorb dual certification costs. This structural friction is compressing margins for exporters while creating defensive moats for integrated operators with captive laboratory capacity.
Growth Catalysts
- EU Green Deal due diligence rules:Deforestation-linked sourcing mandates are accelerating traceability investments among Vietnamese canneries serving European retail chains, locking in long-term procurement contracts.
- Pharmaceutical extraction demand:Bamboo shoot polysaccharide isolation for glycemic control formulations is absorbing surplus culm volumes from food-grade processing, creating price floor support for raw material growers.
- Mekong Delta cluster expansion:Regional cannery capacity additions in Vietnam's bamboo-growing heartland are reducing unit logistics costs for trans-European container shipments.
Market Restraints
- Input cost volatility:Lignin testing reagent prices and cold-chain diesel costs fluctuate with energy market swings, squeezing processor margins on fresh varieties.
- Supply concentration risk:Fujian Province's dominance in year-round fresh supply creates single-point vulnerability to climate anomalies and local SAMR enforcement actions.
- Substitution pressure:Konjac root and lotus root fibers displace bamboo shoot demand in low-calorie food formulations where texture tolerance is higher.
Strategic Opportunities
- Underpenetrated nutraceutical channels:North American dietary supplement distributors remain underserved by bamboo polysaccharide suppliers, presenting first-mover positioning for certified exporters.
- Regulatory tailwind from dual carbon goals:China's MEE incentives for carbon-neutral agricultural processing subsidize energy-efficient cannery retrofits in Zhejiang and Fujian.
- Direct-to-retail e-commerce:Fresh bamboo shoot subscription models bypass traditional wholesale layers, capturing margin from specialty Asian grocery chains in Australia and Canada.
Industry Challenges
- Certification timeline compression:EU EFSA novel food approvals for polysaccharide extracts require 18-24 month safety studies, delaying revenue recognition for R&D-heavy processors.
- Cold-chain integration complexity:Legacy fresh shoot distributors lack temperature-controlled last-mile infrastructure, forcing partnerships with third-party logistics providers that erode unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bamboo Shoots Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Canned, Frozen, Pickled End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Packaging Type: Plastic, Glass, Metal, Paper Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Fujian Jihe Supply Chain Co., Ltd., Tianjin Kunyu International Co., Ltd., Dalian Gaishi Food Co., Ltd., VIET D.E.L.T.A INDUSTRIAL CO., LTD, Zhangzhou Hang Fat Import & Export Co., Ltd., Xiamen Sinocharm Co., Ltd., Xiamen Oulay Imp.&Exp. Co., Ltd., Xiamen Sharp Dragon International, Zhangzhou Meisei Foods Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bamboo Shoots Market Evolving Landscape
Processing technology and regulatory compliance systems are converging to reshape competitive advantage in bamboo shoot value chains. Operators now compete on traceability infrastructure and extraction yield rather than raw volume throughput.
Modified atmosphere packaging with oxygen-scavenging films is absorbing the technical risk of fresh shoot shelf-life extension, enabling maritime container shipments to replace air freight for European premium retail. Japanese convenience store chains and South Korean meal-kit operators are adopting these formats at accelerating cadence. The technology is absorbing margin pressure from fuel cost volatility while opening new geographic markets previously inaccessible to fresh product.
REACH substance evaluation protocols for pesticide metabolites are tightening inspection intensity at EU border control posts, redirecting non-compliant Chinese lots to Southeast Asian re-export hubs. Vietnamese processors with SAMR-EFSA dual certification are capturing redirected volume. Frozen segment operators in Dalian are responding with accelerated GB 2763 testing cadences to preempt rejection.
Retail buyer consolidation among European hard discount chains is compressing supplier counts and extending payment terms to 90-120 days. Specialty Asian grocery independents in Germany and the Netherlands are consolidating procurement through regional buying cooperatives to match volume thresholds. The shift is most visible in canned product categories where shelf-stable logistics enable centralized distribution.
Bamboo Shoots Market Segmentation
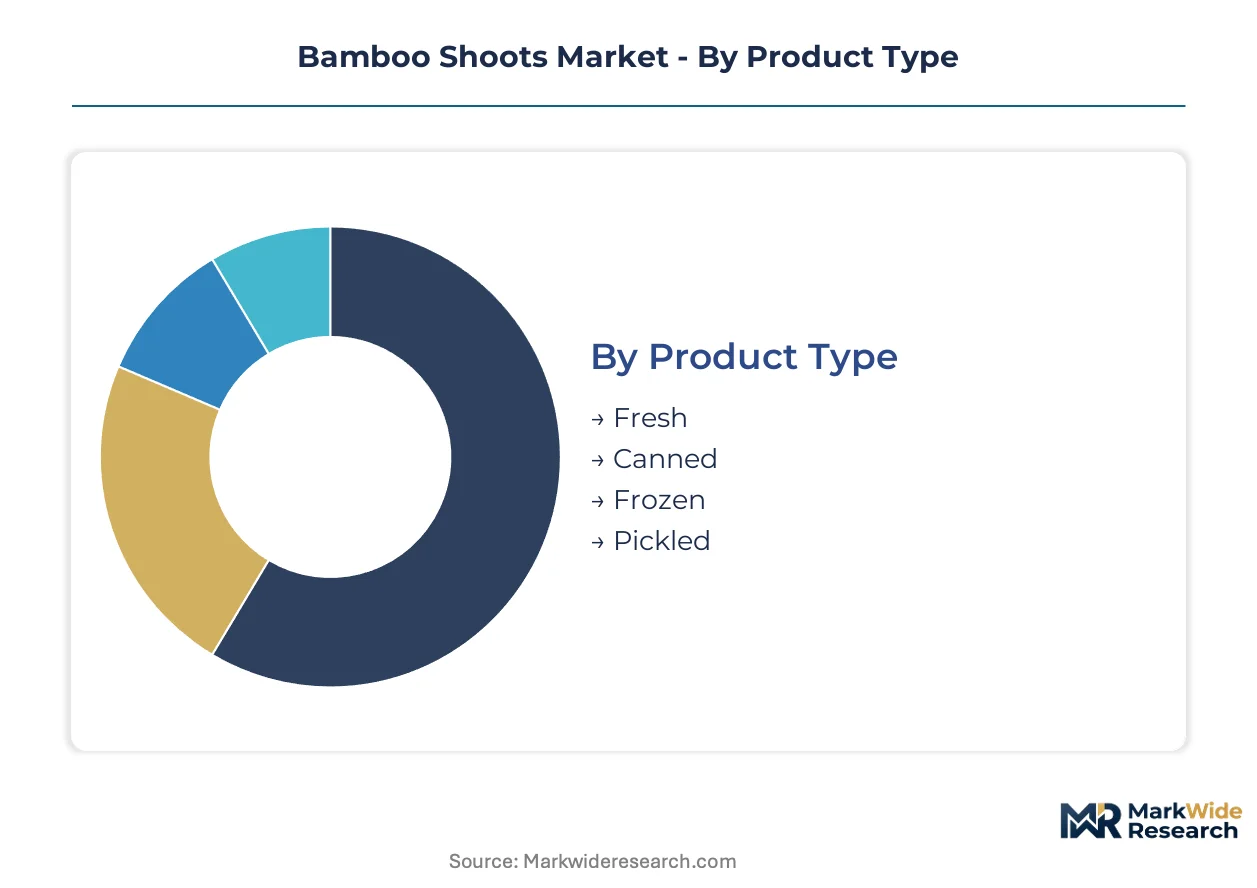
Bamboo shoot processors face divergent certification burdens across product formats, with fresh varieties demanding cold-chain compliance and canned formats requiring dual SAMR-EFSA residue testing. Segmentation strategy determines margin capture and market access velocity.
Product Type:
Canned bamboo shoots carry the heaviest regulatory load, requiring GB 2762/2763 testing plus EFSA border inspections, while fresh varieties demand phytosanitary certification under USDA and FDA protocols.
- Fresh:Harvested at 7-15 days post-emergence when lignin remains below 3%, these shoots command premium positioning in specialty Asian grocery channels. Japanese convenience store chains and South Korean meal-kit operators drive demand concentration for modified atmosphere packaging formats that extend maritime shelf life.
- Canned:Shelf-stable processing enables institutional procurement by European hard discount chains and foodservice distributors. Mekong Delta canneries absorb volume leadership through labor arbitrage and proximity to raw material clusters, though REACH residue protocols compress margins on non-compliant lots.
- Frozen:Port-adjacent infrastructure in Dalian controls trans-Pacific logistics costs for North American buyers.
- Pickled:Fermentation-based preservation serves traditional East Asian cuisine segments with lower certification overhead.
Canned sits at the top of the volume ranking, with fresh climbing the fastest.
End Use Industry:
Margin pools diverge sharply across applications, with pharmaceutical extraction commanding price premiums for polysaccharide isolation while food-grade processing absorbs raw material surpluses.
- Food & Beverage:Institutional buyers and retail chains absorb the dominant output share across canned and frozen formats. Vietnamese canneries serving European supermarkets face EU Green Deal due diligence mandates on deforestation-linked sourcing.
- Pharmaceuticals:Bamboo shoot polysaccharides for glycemic control formulations require 18-24 month EFSA novel food safety studies. North American dietary supplement distributors remain underserved, creating first-mover positioning for certified exporters.
- Cosmetics:Fiber extracts appear in topical formulations with lower regulatory barriers than ingestible applications.
- Nutraceuticals:Functional food positioning bridges food and pharmaceutical compliance frameworks.
Food & Beverage captures the dominant volume position, with pharmaceuticals expanding most quickly.
Packaging Type:
Material selection tracks distribution distance and shelf-life requirements, with metal and glass commanding premium positioning and plastic dominating volume throughput.
- Metal:Tinplate and aluminum cans dominate canned bamboo shoot exports to European retail chains. Extended payment terms of 90-120 days from consolidated buyers pressure working capital for metal-can suppliers.
- Plastic:Modified atmosphere films with oxygen-scavenging layers enable fresh shoot maritime shipments, replacing air freight for premium European markets. Japanese and South Korean adoption rates accelerate format penetration.
- Glass:Pickled varieties and premium retail positioning favor jar formats with higher unit economics.
- Paper:Sustainable packaging mandates in EU markets drive experimental formats with limited current penetration.
Metal leads volume throughput, with plastic gaining share fastest on fresh format adoption.
Distribution Channel:
Channel selection determines margin capture and certification intensity, with wholesale absorbing volume and online retail enabling direct-to-consumer subscription models.
- Supermarkets:European hard discount chains consolidate supplier counts and extend payment terms, favoring large-scale canneries with dual SAMR-EFSA certification. German and Dutch Asian grocery independents respond through regional buying cooperatives.
- Online Retail:Fresh bamboo shoot subscription models bypass traditional wholesale layers, capturing margin from specialty chains in Australia and Canada. Cold-chain last-mile partnerships with third-party logistics providers erode unit economics.
- Specialty Stores:Premium fresh varieties concentrate in urban Asian grocery clusters with higher price tolerance.
- Wholesale:Foodservice and institutional procurement absorbs canned volume at lower per-unit margins.
Supermarkets anchor volume leadership, with online retail climbing the fastest on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bamboo shoot cultivation and processing trace their industrial scale to China's Fujian and Zhejiang provinces during the 1980s export manufacturing boom. These regions established the cold-chain infrastructure and canning technology that now supplies global markets.
China
Fujian Province's integrated cold-chain networks sustain year-round fresh supply reliability for domestic and export markets. SAMR enforces GB 2762 and GB 2763 contaminant limits that determine EU border acceptance. Zhejiang canneries absorb MEE subsidies for carbon-neutral retrofits, tightening cost positions against regional competitors.
Vietnam
Mekong Delta processing clusters expand capacity to serve European retail chains with labor-arbitrage advantages. EU Green Deal due diligence rules on deforestation-linked sourcing accelerate traceability investments among canneries. VIET D.E.L.T.A INDUSTRIAL CO., LTD anchors operations in this bamboo-growing heartland, competing on raw material proximity.
Japan
Convenience store chains and meal-kit operators drive demand concentration for modified atmosphere packaging formats. METI standards for agricultural imports shape procurement specifications for processed shoots. Kanto region distributors control premium fresh variety flows to urban retail clusters.
South Korea
Meal-kit subscription services absorb increasing volumes of packaged fresh shoots with extended shelf-life requirements. MFDS food safety protocols align with CODEX standards while maintaining stricter domestic pesticide thresholds. Seoul Capital Area logistics hubs consolidate imports from Fujian and Vietnamese sources.
Germany
Hard discount retail chains consolidate supplier counts and extend payment terms to 90-120 days, favoring large-scale canneries with dual certification. EFSA border inspection intensity for REACH metabolite compliance redirects non-compliant Asian lots to re-export hubs. Frankfurt and Hamburg distribution centers coordinate European inland flows.
Bamboo Shoots Market Competitive Landscape
The competitive structure tilts toward integrated supply chain operators with captive laboratory capacity and cold-chain control. Fragmentation persists among regional canneries lacking dual SAMR-EFSA certification, compressing margins on rejected lots. Three archetypes dominate: port-adjacent frozen processors, Mekong Delta labor-arbitrage canneries, and Fujian-based fresh distributors with year-round reliability. Capacity expansion and backward integration into raw material sourcing represent the primary competitive moves as processors defend margin positions against regulatory compliance costs.
Among Chinese supply chain operators, Fujian Jihe Supply Chain Co., Ltd. and Dalian Gaishi Food Co., Ltd. exemplify the integrated archetype with geographic positioning advantages. VIET D.E.L.T.A INDUSTRIAL CO., LTD represents the Mekong Delta labor-proximity model. These three occupy positions that reflect divergent strategic bets on certification intensity versus logistics cost control.
| Leading Market Players |
|---|
| Fujian Jihe Supply Chain Co., Ltd. |
| Tianjin Kunyu International Co., Ltd. |
| Dalian Gaishi Food Co., Ltd. |
| VIET D.E.L.T.A INDUSTRIAL CO., LTD |
| Zhangzhou Hang Fat Import & Export Co., Ltd. |
| Xiamen Sinocharm Co., Ltd. |
| Xiamen Oulay Imp.&Exp. Co., Ltd. |
| Xiamen Sharp Dragon International |
| Zhangzhou Meisei Foods Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Backward integration into raw material sourcing anchors both supply reliability and margin defense for bamboo shoot processors facing dual certification burdens. Fujian Province's year-round fresh distributors and Mekong Delta canneries compete on divergent integration models, with captive laboratory capacity determining who captures premium pricing versus who absorbs rejection costs.
Pricing Analysis
Fresh versus canned service unbundling separates premium positioning from commodity volume play. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity: EFSA novel food approval for polysaccharide extracts commands top tier, dual SAMR-EFSA compliance defines standard institutional pricing, and single-certification canned bulk serves economy foodservice. Pricing pressure stems from EU Green Deal due diligence investments forcing traceability cost absorption. European hard discount chains exhibit highest price sensitivity with 90-120 day payment terms, while North American nutraceutical distributors show lowest sensitivity for certified polysaccharide supply.
Supply Chain Analysis
Workforce availability in Vietnam's Mekong Delta processing clusters and Fujian Province's cold-chain corridors shapes competitive positioning. Supply concentrates in China, Vietnam, and Japan, with raw material sourcing drawing from bamboo-growing heartlands in Fujian and the Mekong Delta. Lignin testing reagents and cold-chain diesel feed cost volatility. Single-source vulnerability runs through Fujian's year-round fresh dominance. Distribution runs through port-adjacent frozen infrastructure in Dalian for trans-Pacific flows and regional cannery hubs for European retail consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns for operators mastering regulatory divergence, with EU REACH residue protocols and EFSA novel food pathways serving as the demand-accelerating milestone reshaping competitive tiers.
For Market Incumbents: Lock in dual SAMR-EFSA certification moats through captive laboratory capacity additions in Fujian and Zhejiang. Deepen upstream control over bamboo-growing cooperatives to preempt EU Green Deal deforestation due diligence exposure. Channel control through direct retail partnerships insulates against hard discount chain consolidation.
For New Entrants and Emerging Players: Premium-to-economy price-point gaps in North American nutraceutical distribution present exploitable white space. Target underserved polysaccharide extract demand from dietary supplement distributors lacking certified Asian suppliers. E-commerce subscription models for fresh shoots in Australia and Canada offer go-to-market velocity bypassing wholesale layer compression.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Vietnamese canneries with SAMR-EFSA dual certification because regulatory compliance costs are fragmenting sub-scale competitors. Five-to-ten year viability hinges on traceability infrastructure ownership. Watch EFSA novel food approval timelines as inflection signal for pharmaceutical extraction revenue recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Captive SAMR-EFSA laboratory capacity locks in EU border acceptance velocity. |
| Backward Integration into Sourcing | Direct bamboo cooperative contracts satisfy EU Green Deal traceability mandates. |
| Modified Atmosphere Packaging Scale-Up | Oxygen-scavenging film adoption opens maritime fresh shipments to European premium retail. |
| Polysaccharide Extraction Capacity | Pharmaceutical-grade isolation equipment captures nutraceutical margin premiums. |
| Direct-to-Retail E-Commerce Launch | Subscription models bypass wholesale payment term extension to 90-120 days. |
Research Methodology
Bottom-up food and beverage end-use modeling reconciled against top-down cannery capacity tracking forms the analytical core. Primary interviews with procurement managers at European hard discount chains, regulatory affairs leads at Fujian exporters, cold-chain logistics operators, and Mekong Delta plant managers combined with secondary validation from customs trade records, SAMR enforcement disclosures, EFSA border inspection reports, and CODEX standard updates. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of canned and fresh shipment flows calibrated segment-level growth trajectories across the projection horizon. Modeled dimensions span product format, end-use application, packaging material, and distribution channel, with regional regulatory cluster overlays for EU, North American, and East Asian compliance frameworks. CAGRs derived from capacity expansion announcements, import license trends, and substitution elasticity estimates for konjac and lotus root fiber alternatives.
Caveats apply where EFSA novel food approval delays, SAMR enforcement intensity fluctuations, or EU Green Deal implementation scope changes could materially shift the outlook. Forecasts reflect assumptions about certification timeline stability and cold-chain infrastructure investment continuity. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market
Fruits and Vegetables
Colombia Fruits and Vegetables Market
Fruits and Vegetables
Dehydrated Green Beans Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
Cyanidin Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Banana Puree Market
Fruits and Vegetables
Lycopene Market