
 Mung Beans Market | 2026-2036
Mung Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Mung Beans Market Intelligence
Multi-source procurement across Australian and Canadian growing regions is consolidating as buyers seek supply resilience against climate volatility. AGT Food and Ingredients Inc. leverages its pulse-processing infrastructure across North America to secure volume commitments. Australian Mungbean Company anchors premium-grade supply through identity-preserved traceability systems. Olam Agri Holdings Pte Ltd. competes on origination breadth, operating procurement networks across Myanmar and East Africa.
Mung beans are small green legumes of the Vigna radiata species, typically containing 24-28% protein and 16-20% dietary fiber by dry weight, cultivated as annual crops in warm temperate to tropical climates for human consumption and ingredient processing. The food industry segment dominates value capture through processed formats including noodles, sprouts, and dairy alternatives, while split mung beans sustain the fastest volume trajectory in South Asian diaspora markets. Mung bean flour occupies concentrated margin pools in gluten-free bakery applications, whereas bulk container packaging dominates industrial procurement channels despite pouch growth in health food retail.
Food safety frameworks including FDA oversight in the United States, EFSA standards across European import jurisdictions, and BIS certification requirements in India collectively elevate testing and traceability costs for exporters. REACH compliance in Europe further constrains pesticide residue thresholds, redirecting cultivation investment toward integrated pest management protocols. Stakeholders must monitor evolving allergen labeling mandates and carbon border adjustment mechanisms to preserve market access across priority destinations.
Market Dynamics
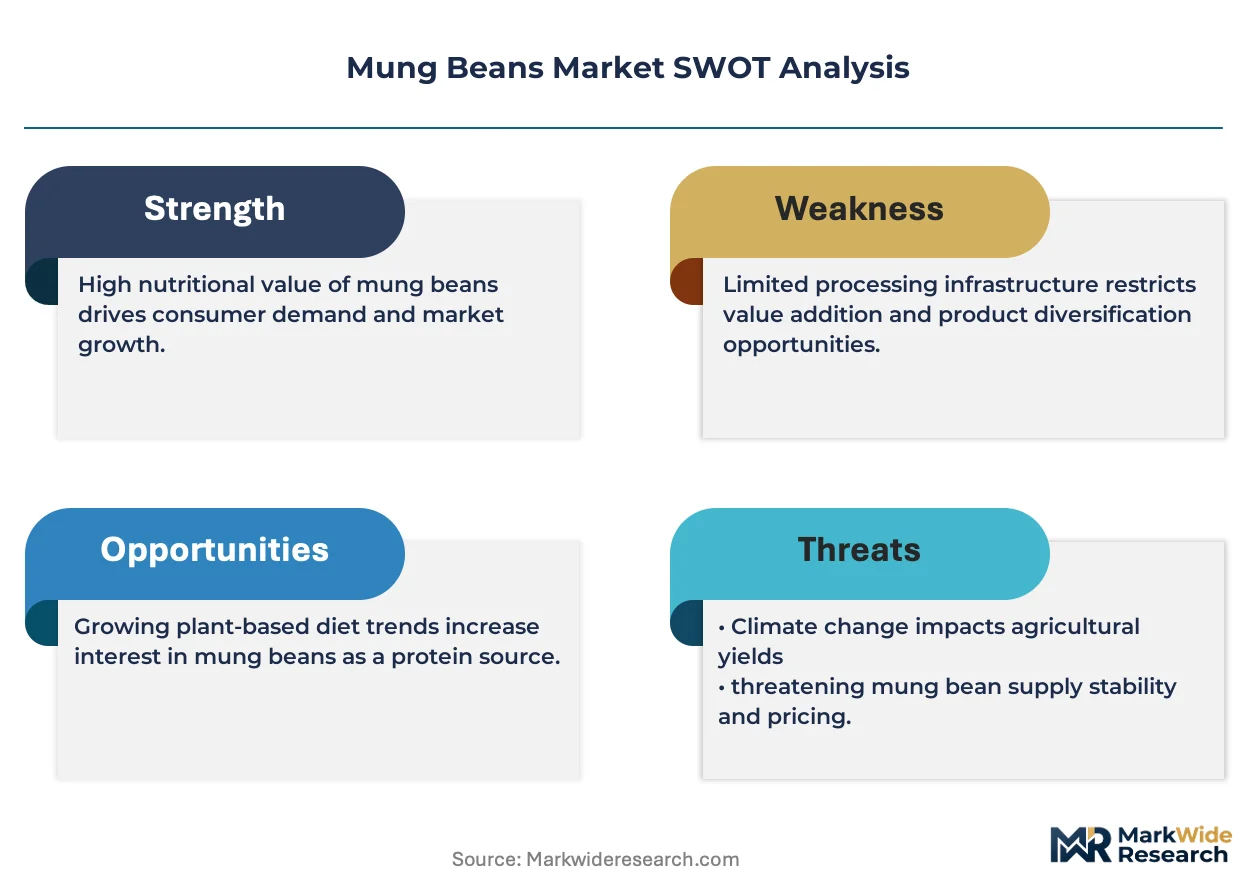
Climate volatility across Australian and Canadian growing belts is forcing buyers toward multi-origin procurement contracts, compressing traditional single-source supply relationships and elevating identity-preserved traceability from premium feature to baseline requirement.
Growth Catalysts
- India's PLI scheme:The Production Linked Incentive program for food processing redirects capital toward pulse value-add infrastructure, expanding domestic mung bean fractionation capacity and reducing import dependency for processed formats.
- Plant-based protein adoption:Nutraceutical formulators are substituting mung bean isolates for soy and pea proteins in clean-label applications, driven by allergen-free positioning and neutral flavor profiles.
- Southeast Asian export corridor consolidation:Vietnam and Myanmar are capturing volume concentration as transshipment and processing hubs, shortening lead times to East Asian destination markets.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings directly compress farm-gate margins, with nitrogen-based inputs representing the largest variable cost component for warm-climate cultivation.
- Supply concentration risk:Myanmar's dominance in certain export grades creates single-point vulnerability to export licensing disruptions and foreign exchange control fluctuations.
- Regulatory friction:REACH compliance in Europe tightens pesticide residue thresholds, disqualifying conventional integrated pest management protocols and forcing cultivation system overhauls.
Strategic Opportunities
- Underpenetrated African origination:East African highland zones offer untapped acreage expansion with complementary growing seasons to Australian and Canadian harvest windows.
- Carbon border adjustment positioning:Early adoption of regenerative cultivation protocols and soil carbon verification creates preferential access to EU markets as CBAM phase-in advances.
- Direct-to-manufacturer channel development:Bypassing commodity aggregators through identity-preserved contracting with gluten-free bakery and dairy-alternative processors captures margin pools currently absorbed by intermediaries.
Industry Challenges
- Traceability system integration:Legacy paper-based lot tracking at origin conflicts with blockchain and IoT-enabled verification demands from European and North American importers, requiring capital-intensive infrastructure retrofit.
- Allergen labeling complexity:Evolving FSSAI, FDA, and EFSA disclosure mandates for legume cross-reactivity create formulation reformulation cycles and packaging redesign burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mung Beans Market |
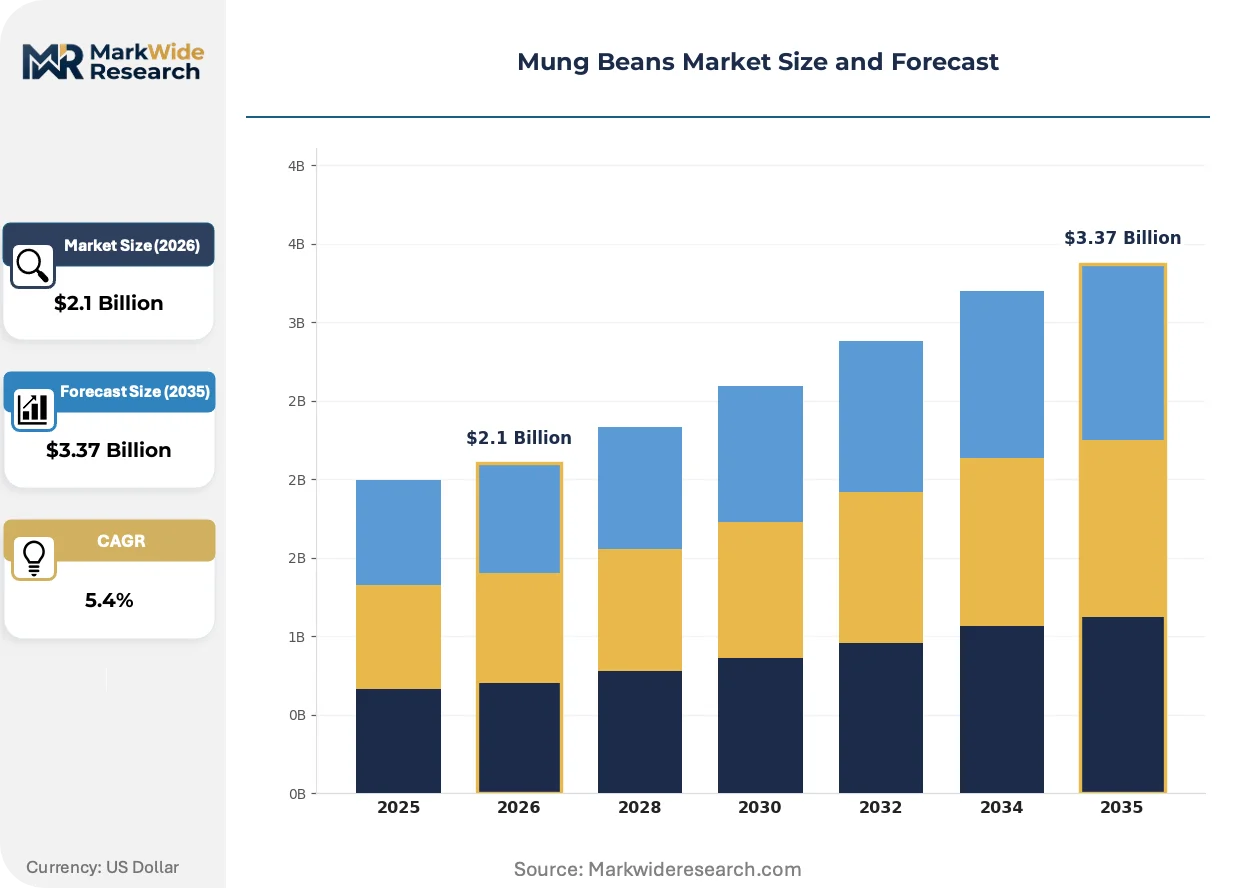
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Mung Beans, Split Mung Beans, Mung Bean Flour, Mung Bean Starch End Use: Food Industry, Animal Feed, Cosmetics, Nutraceuticals Packaging Type: Bags, Tins, Bulk Containers, Pouches Distribution Channel: Online Retail, Supermarkets, Distributors, Health Food Stores |
| Companies Covered | AGT Food and Ingredients Inc., Australian Mungbean Company, Cono Group, ETC Group, Olam Agri Holdings Pte Ltd., Royal Nut Company, Vigna Foods, GreenPulse, Dalian Huaen Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mung Beans Market Strategic Shifts & Innovations
Processing technology and procurement logic are converging to compress traditional value chain stages, with automation and data infrastructure displacing manual quality assessment and speculative inventory holding across origin and destination markets.
Hyperspectral imaging and AI-driven defect detection is integrating into primary processing lines at Australian and Canadian facilities, replacing visual hand-sorting with real-time compositional analysis. Gluten-free bakery and sprout packers are adopting these systems fastest, accepting 15-20% capital premiums for lot-to-lot consistency guarantees. This compression of quality assurance into upstream nodes is reducing destination-market rework and rejection rates.
REACH and the EU Green Deal are tightening residue and carbon intensity thresholds for agricultural imports into European jurisdictions, forcing origin suppliers to document input applications and transport emissions through chain-of-custody systems. Mung bean flour and isolate categories face the steepest compliance ramps, with formulators now requiring batch-level environmental product declarations as standard procurement terms.
Identity-preserved contracting is displacing commodity spot purchasing among North American and European health food manufacturers, with buyers specifying cultivar, origin, and processing method rather than accepting pooled grades. This behavioral shift concentrates volume with processors offering vertical traceability, most visible in the sprout seed and premium flour segments where contamination events carry severe brand risk.
Mung Beans Market Segmentation
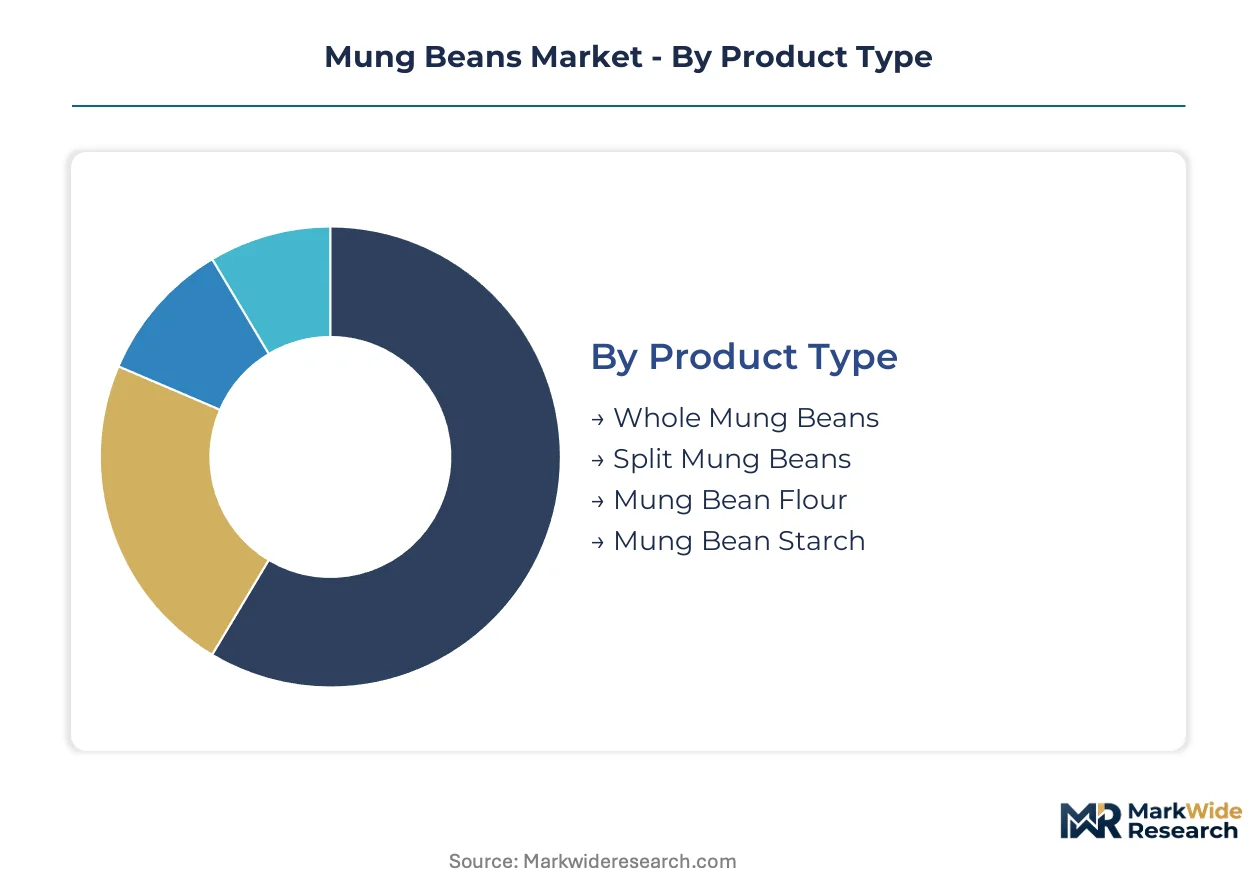
Mung bean value capture varies dramatically by processing depth and destination channel. Segment boundaries determine margin pools, with processed formats commanding premiums over bulk commodity flows and identity-preserved channels extracting rents from traceability requirements.
Product Type:
Supply concentration in Australian and Canadian processing infrastructure favors formats with established fractionation capacity, while Asian-origin whole beans dominate spot commodity flows.
- Whole Mung Beans:Raw seeds retain 24-28% protein by dry weight and serve as the foundational input for sprouting operations and traditional cooking applications. Demand concentrates in Southeast Asian export corridors—particularly Vietnam and Myanmar—where transshipment efficiency shortens lead times to East Asian destination markets, though climate volatility is forcing buyers toward multi-origin procurement contracts.
- Split Mung Beans:Dehulled and split seeds cook faster and absorb flavors more readily, sustaining the steepest expansion trajectory in South Asian diaspora markets across North America and Europe. India's PLI scheme for food processing is expanding domestic fractionation capacity, reducing import dependency for this format.
- Mung Bean Flour:Finely ground flour occupies concentrated margin pools in gluten-free bakery applications, with protein content enabling binding functionality in clean-label formulations.
- Mung Bean Starch:Extracted carbohydrate fraction serves noodle manufacturing and texturizing applications, with Asian processors dominating extraction technology.
Today's leader: Whole Mung Beans. Tomorrow's challenger: Split Mung Beans.
End Use:
Application-driven procurement patterns separate commodity volume plays from premium ingredient positioning, with regulatory friction highest in human-consumption channels.
- Food Industry:Processed formats including noodles, sprouts, and dairy alternatives capture dominant value share, with REACH compliance in Europe tightening pesticide residue thresholds and forcing cultivation system overhauls for exporters.
- Nutraceuticals:Plant-based protein adoption accelerates uptake as formulators substitute mung bean isolates for soy and pea proteins in clean-label applications, driven by allergen-free positioning and neutral flavor profiles.
- Animal Feed:Protein meal applications compete with soybean and canola meal on cost per unit protein, with volume sensitive to crush margin spreads.
- Cosmetics:Extracts targeting skin conditioning applications occupy niche positioning, with Korean and Japanese formulators driving specification development.
Food Industry commands current volume. Nutraceuticals is gaining share fastest.
Packaging Type:
Channel requirements dictate packaging investment, with industrial procurement favoring throughput efficiency and retail channels demanding shelf differentiation.
- Bulk Containers:Industrial procurement channels dominate volume flows, with FCL shipments enabling cost-efficient movement from Myanmar and Australian ports to destination processors.
- Pouches:Health food retail channels show fastest pouch adoption, with resealable formats and transparent windows supporting premium positioning.
- Bags:Traditional woven polypropylene remains standard for commodity-grade whole beans, with printed lot codes satisfying baseline traceability requirements.
- Tins:Canned formats serve foodservice and emergency preparedness segments, with retort processing extending shelf stability.
Bulk Containers anchor industrial procurement. Pouches are climbing fastest in retail channels.
Distribution Channel:
Channel control determines margin retention, with direct relationships compressing intermediary layers and capturing value currently absorbed by commodity aggregators.
- Distributors:Traditional aggregators maintain volume dominance in foodservice and manufacturing procurement, though identity-preserved contracting is displacing commodity spot purchasing among North American and European health food manufacturers.
- Supermarkets:Mass retail chains specify cultivar and origin for private label lines, with contamination events carrying severe brand risk that drives traceability investment.
- Health Food Stores:Specialist retailers command premium shelf positioning for organic and sprout-grade certifications, with batch-level environmental product declarations becoming standard procurement terms.
- Online Retail:Direct-to-consumer channels enable origin storytelling and subscription models, though logistics costs constrain profitability for low-unit-value products.
Distributors hold current volume leadership. Health Food Stores show the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting mung bean processing investment toward jurisdictions with streamlined food safety certification pathways, compressing cost-of-compliance gaps between established and emerging origination zones.
India
FSSAI mandates on allergen labeling and fortification standards are accelerating domestic fractionation capacity buildout. The PLI scheme for food processing redirects capital toward pulse value-add infrastructure, reducing import dependency for split mung bean formats. Processing clusters in Gujarat and Maharashtra are expanding identity-preserved traceability systems to capture premium export positioning.
Australia
Climate volatility across Queensland and New South Wales growing belts is forcing buyers toward multi-origin procurement contracts. TGA-aligned export certification protocols and BIS mutual recognition agreements preserve market access for premium-grade sprout seed. The Australian Mungbean Company anchors identity-preserved supply chains through blockchain-enabled lot tracking.
Myanmar
Export licensing disruptions and foreign exchange control fluctuations are creating single-point vulnerability for certain grade concentrations. Central bank foreign exchange auction mechanisms are redirecting trade flows through informal channels. Yangon and Mandalay transshipment hubs face infrastructure bottlenecks as volume concentrates in Southeast Asian export corridors.
Canada
Health Canada and CFIA residue monitoring protocols are elevating testing costs for exporters targeting European jurisdictions. AGT Food and Ingredients Inc. leverages pulse-processing infrastructure across Saskatchewan and Alberta to secure volume commitments. Prairie province growing windows offer complementary harvest timing to Australian supply.
Vietnam
Transshipment efficiency and port modernization are shortening lead times to East Asian destination markets. SAMR-aligned import documentation for re-export to China is concentrating processing investment in Ho Chi Minh City and Hai Phong logistics zones. Local processors are capturing margin pools through dehulling and splitting operations.
Mung Beans Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue clean-label certification and direct-to-manufacturer channel development. The vendor base stratifies across three maturity tiers: legacy commodity aggregators, mid-cap processors with identity-preserved infrastructure, and venture-backed entrants targeting nutraceutical isolate categories. Dominant competitive moves include backward integration into origination networks and strategic partnerships with gluten-free bakery processors.
Among North American and Asia-Pacific fabricators, AGT Food and Ingredients Inc., Australian Mungbean Company, and Olam Agri Holdings Pte Ltd. exemplify distinct strategic archetypes. AGT Food and Ingredients Inc. represents scale-driven infrastructure consolidation across prairie processing nodes. Australian Mungbean Company occupies a premium-tier position anchored in identity-preserved traceability systems. Olam Agri Holdings Pte Ltd. exemplifies origination-breadth competition through procurement network span.
| Leading Market Players |
|---|
| AGT Food and Ingredients Inc. |
| Australian Mungbean Company |
| Cono Group |
| ETC Group |
| Olam Agri Holdings Pte Ltd. |
| Royal Nut Company |
| Vigna Foods |
| GreenPulse |
| Dalian Huaen Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Health food manufacturers and gluten-free bakery processors command dominant procurement leverage, compressing intermediary margins and forcing identity-preserved contracting premiums into baseline supply terms. This buyer concentration elevates traceability costs into price structures while rewarding direct-to-manufacturer channel bypass.
Pricing Analysis
Distributor margin layers face sustained compression as identity-preserved contracting displaces commodity spot purchasing among North American and European buyers. Pricing stratifies across premium sprout-grade certifications, standard food-industry whole beans, and economy-tier feed applications, with REACH compliance costs widening spreads between European-facing and domestic-market supply. Cost compression in nitrogen-based fertilizer inputs is intensifying farm-gate pressure, though nutraceutical isolates retain pricing power through allergen-free positioning. Small-scale health food retailers exhibit highest price sensitivity, while multinational dairy-alternative processors absorb premiums for lot-to-lot consistency guarantees.
Supply Chain Analysis
Return flows and rejected lots from hyperspectral imaging defect detection are creating secondary commodity streams at Australian and Canadian processing nodes. Geographic supply concentrates in Myanmar, Australia, and Canada, with East African highland zones emerging as complementary harvest window sources. Raw material dependencies rest on nitrogen fertilizer, fuel for warm-climate cultivation, and packaging polymers for retail pouch formats. Single-source vulnerability in Myanmar's export licensing regime poses structural risk. Distribution runs through bulk container FCL shipments to destination processors, with health food retail channels adopting resealable pouch formats fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier ingredient positioning, with identity-preserved traceability investments capturing value pools from clean-label formulation trends.
For Market Incumbents: Lock in origination network control through backward integration into East African highland zones and blockchain-enabled lot tracking infrastructure. AGT Food and Ingredients Inc. exemplifies scale-driven infrastructure consolidation across prairie processing nodes, while Australian Mungbean Company anchors premium positioning through identity-preserved systems. Threat substitution from pea and soy protein isolates demands defensive R&D in neutral-flavor mung bean fractionation. Certification investment in EU Green Deal alignment represents the priority lever for European market access preservation. For New Entrants and Emerging Players: Begin with nutraceutical isolate categories where allergen-free positioning commands premium extraction margins. Underpenetrated African origination offers white-space acreage with complementary growing seasons to established supply windows. Direct-to-manufacturer channel development bypasses commodity aggregators and captures margin pools currently absorbed by intermediaries. Clean-label certification paired with batch-level environmental product declarations provides the most penetrable go-to-market angle for gluten-free bakery and dairy-alternative processors. For Investors and Strategic Acquirers: Mid-cap gluten-free ingredient processors are the most active acquirer in this space, seeking captive supply of identity-preserved pulse inputs. Long-term viability over the coming decade rests on carbon border adjustment positioning and regenerative cultivation protocol adoption. Acquisition targets should exhibit vertical traceability infrastructure and established relationships with health food retail channels. The signal to watch is EU CBAM phase-in acceleration and corresponding premium spreads for verified low-carbon supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination | East African highland zone procurement secures complementary harvest windows to Australian supply. |
| Identity-Preserved Traceability Investment | Blockchain-enabled lot tracking satisfies FSSAI and EFSA disclosure mandates for premium-grade exports. |
| Carbon Border Adjustment Positioning | Regenerative cultivation protocols create preferential EU market access as CBAM phase-in advances. |
| Direct-to-Manufacturer Channel Development | Bypassing commodity aggregators captures margin pools in gluten-free bakery and dairy-alternative processing. |
| Hyperspectral Imaging Integration | AI-driven defect detection reduces destination-market rework and rejection rates for sprout seed segments. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pulse processors, agronomists, and health food retail buyers alongside secondary validation. Stakeholder roles engaged included food safety compliance officers at export facilities, procurement leads at gluten-free bakery manufacturers, distribution channel partners in Southeast Asian transshipment hubs, and regulatory affairs specialists navigating REACH and FSSAI frameworks. Secondary sources encompassed customs and trade flow databases, BIS and TGA certification registries, PLI scheme disbursement records, and EFSA pesticide residue monitoring reports. Bottom-up volume modeling from origination clusters triangulated against top-down demand estimates from end-use segments.
Segment-weighting approaches applied differential growth assumptions across product type, end use, packaging format, and distribution channel dimensions. The analytical framework modeled whole beans, split beans, flour, and starch categories separately, with nutraceutical isolate demand tracked as a distinct trajectory. CAGRs were derived from historical trade flow patterns and projected substitution elasticities for plant-based protein applications. Forecast inputs incorporated climate volatility indices for Australian growing belts and foreign exchange auction mechanisms affecting Myanmar export competitiveness.
Several conditions sit outside the modeled scope, including abrupt export licensing suspensions in Myanmar, rapid shifts in EU carbon border adjustment implementation timelines, and breakthroughs in precision fermentation displacing legume-derived proteins. Forecasts reflect documented assumptions about PLI scheme continuation and REACH residue threshold stability. Practitioners should monitor EU CBAM regulatory drafts and Indian import tariff adjustments for early signals of structural demand redirection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Gold Kiwifruit Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Europe Blueberry Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Infused Dried Fruits Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Global Gooseberry Market
Fruits and Vegetables
Fresh Peaches Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Venezuela Fruits and Vegetable Market