
 Spain Lime Market | 2026-2036
Spain Lime Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Lime Market Analytics
Multi-source procurement among Spanish lime processors is broadening as buyers diversify beyond traditional Murcian suppliers. Calcinor S.A. leverages its integrated quarry-to-kiln operations across northern Spain to secure industrial lime contracts. Lhoist Group anchors its Iberian presence through specialized high-calcium quicklime production for steel and environmental applications. Carmeuse Group competes on flue-gas desulfurization grade supply to power utilities.
Lime denotes calcium oxide or calcium hydroxide derived from limestone calcination at temperatures exceeding 900°C, yielding a versatile alkaline material with 90-95% CaO content for pH regulation, fluxing, and chemical synthesis. Quicklime and hydrated lime variants dominate industrial consumption, with the former commanding premium pricing in metallurgical flux applications where purity thresholds exceed 96% CaO. The Food Industry segment leads end-user demand as processors require food-grade hydrated lime for tortilla flour nixtamalization and pickle crisping. Organic grade supply remains constrained by certification timelines and limited Spanish acreage conversion, pushing processors toward conventional premium sourcing.
Spain's Ministry of Agriculture enforces EU Regulation 396/2005 on maximum residue levels for citrus imports, while BIS-equivalent conformity assessment through AENOR validates product safety for domestic distribution. The European Chemicals Agency REACH framework governs industrial lime classification and safety data sheet obligations for downstream chemical users. Stakeholders must track irrigation water allocation rulings under Spain's revised Hydrological Plan, as drought-driven supply restrictions threaten yield stability in key growing provinces.
Market Dynamics
Spain's lime sector faces acute pressure from the EU's Farm to Fork strategy, which tightens pesticide residue limits on imported citrus while simultaneously redirecting domestic processors toward certified organic sourcing. This regulatory compression is forcing rapid supply chain reconfiguration across Andalusian processing clusters.
Growth Catalysts
- EU Regulation 396/2005 enforcement:Maximum residue level tightening on citrus imports creates preferential demand for compliant Spanish domestic production. Processors pivot toward verified supply chains.
- Food processing expansion:Rising sauce and marinade production in Andalusia drives hydrated lime consumption for pH stabilization. Tortilla flour nixtamalization adds parallel demand pull.
- Steel sector quicklime requirements:Metallurgical flux applications demand 96% CaO purity thresholds. High-calcium quicklime commands sustained premium pricing from northern Spanish kilns.
Market Restraints
- Murcian supply concentration:Traditional lime sourcing clusters in southeastern Spain create geographic vulnerability. Drought-driven irrigation restrictions under Spain's Hydrological Plan threaten yield stability.
- Organic certification bottlenecks:Limited Spanish acreage conversion and extended AENOR validation timelines constrain food-grade organic supply. Premium conventional sourcing fills the gap at elevated cost.
- Flue-gas desulfurization substitution risk:Power utilities evaluate dry sorbent injection alternatives. Wet scrubbing lime demand faces displacement from sodium-based reagents in select Iberian plants.
Strategic Opportunities
- Galician and Asturian quarry development:Underexploited northern limestone reserves offer diversification from Murcian supply dependence. Calcinor S.A. demonstrates integrated quarry-to-kiln viability.
- Environmental remediation applications:Soil stabilization and acid mine drainage treatment expand hydrated lime demand. REACH framework classification supports new chemical synthesis pathways.
- Direct-to-processor digital procurement:Bypassing traditional citrus brokers reduces margin leakage. Andalusian cooperatives pilot blockchain-traceable supply platforms.
Industry Challenges
- Kiln operator skill scarcity:Limestone calcination expertise concentrates among aging workforce cohorts. Technical training programs lag behind replacement demand.
- REACH compliance documentation:Safety data sheet obligations for downstream chemical users impose administrative burden. Small-scale processors struggle with ECHA reporting requirements.
- Retrofit capex for emission controls:Calcination facilities face investment requirements for NOx and particulate reduction. Marginal producers lack balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Lime Market |
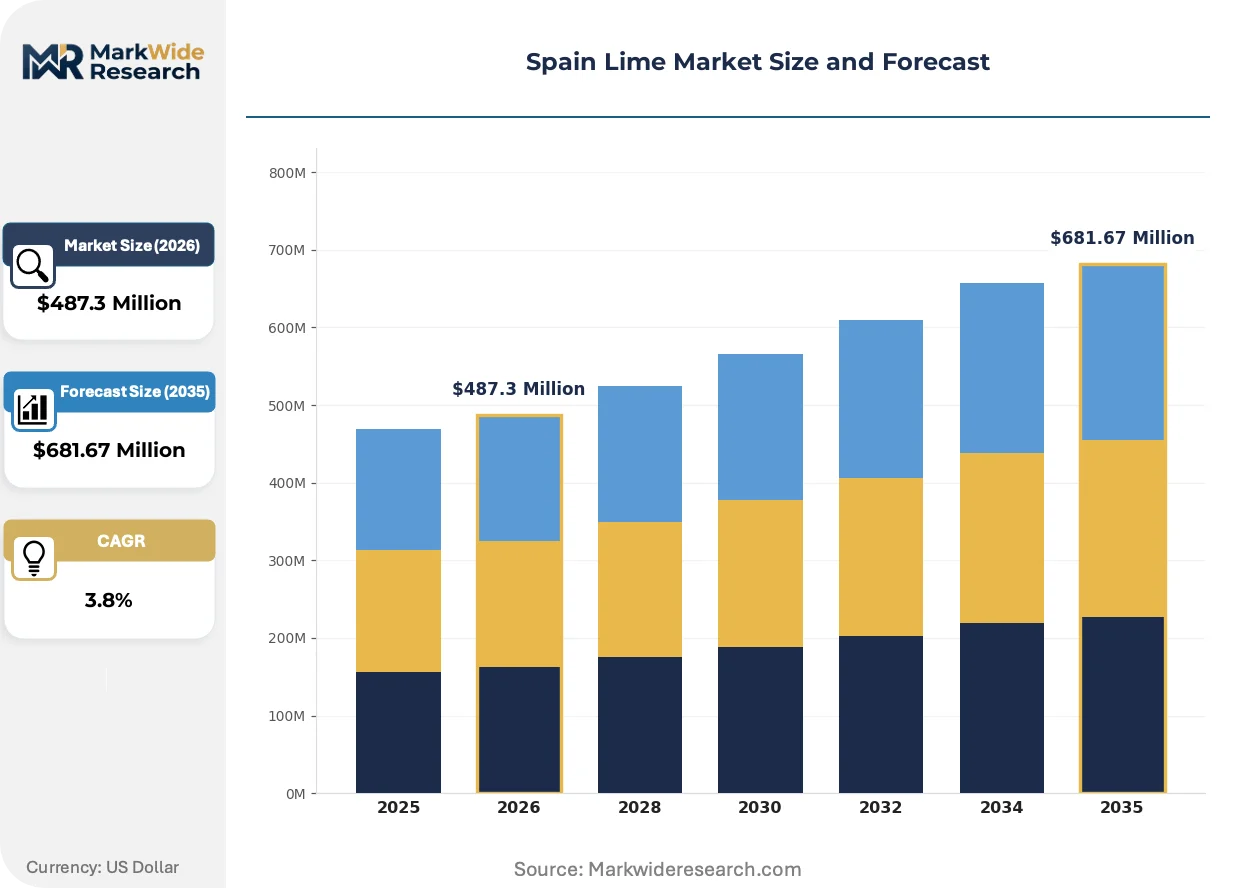
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Limes, Dried Limes, Lime Juice, Lime Zest Grade: Organic, Conventional, Premium, Standard End User: Food Industry, Beverage Industry, Personal Care, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Wholesalers, Farmers' Markets |
| Companies Covered | Grupo Calidra, Grupo Cementos Portland Valderrivas, Calcinor S.A., Cal Indústria i Subministraments, Omya Calcit Española, Lhoist Group, Cales de la Familia Molins, Calceras de Córdoba, Carmeuse Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Lime Market Evolving Landscape
Spanish lime production is experiencing accelerated technological substitution in calcination control systems, alongside regulatory tightening on residue thresholds and evolving procurement relationships between processors and citrus growers.
Precision kiln automation incorporating real-time temperature monitoring and fuel-air ratio optimization is rewriting operational economics for medium-scale producers. Steel mills and environmental contractors adopt sensor-verified quicklime batches within eighteen-month implementation cycles. This technology is compressing quality variance and enabling just-in-time delivery contracts previously impossible for non-integrated suppliers.
REACH framework amendments on industrial lime classification impose stricter safety data sheet obligations for downstream chemical users. Spanish processors must revalidate product documentation for export markets while domestic distributors absorb compliance consulting costs. Food-grade hydrated lime suppliers face the steepest administrative burden, diverting resources from organic certification pursuits.
Spanish processors increasingly contract directly with Andalusian citrus cooperatives, displacing traditional Murcian wholesale brokers. Large tortilla flour manufacturers negotiate multi-season supply agreements with named groves. This pattern concentrates most visibly in Seville and Córdoba provinces, where processing capacity expansion outpaces traditional procurement infrastructure.
Spain Lime Market Segmentation
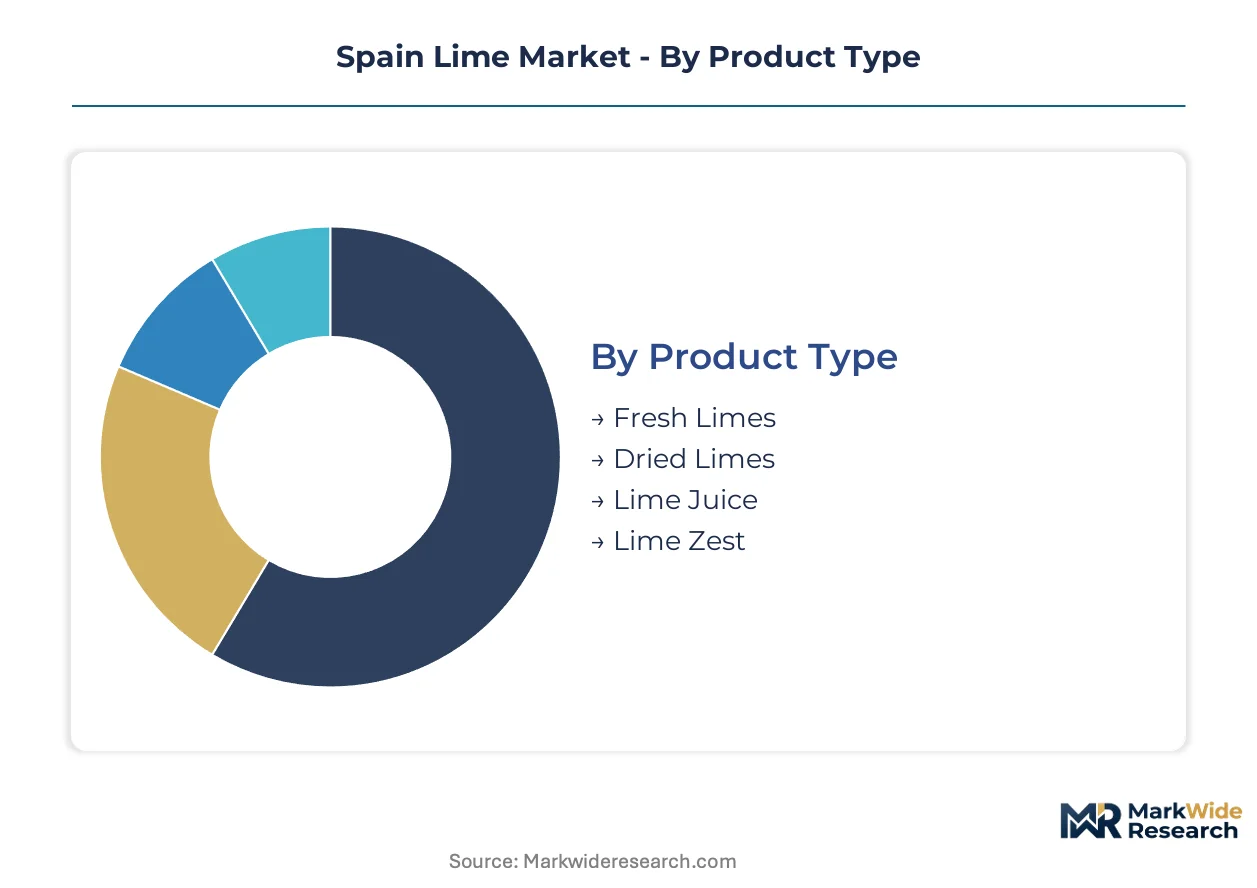
Spanish lime procurement patterns diverge sharply across product formats and purity grades, with industrial processors prioritizing specification consistency while retail channels emphasize origin verification and shelf stability.
Product Type:
Buyers select formats based on processing intensity and perishability tolerance, with fresh fruit commanding logistics investment and processed derivatives offering margin protection.
- Fresh Limes:Whole fruit with intact peel oil sacs delivers maximum aromatic intensity for immediate processing. Andalusian coastal groves supply nixtamalization operations in Seville and Córdoba provinces where tortilla flour manufacturers enforce 48-hour harvest-to-delivery windows.
- Lime Juice:Cold-pressed or concentrate formats stabilize pH in sauce formulations and marinade bases. Beverage processors in Valencia province source NFC juice for premium mixer applications, though drought-driven irrigation restrictions under Spain's Hydrological Plan constrain contracted volumes.
- Dried Limes:Dehydrated whole or sliced fruit extends shelf life for export-oriented spice blends. Middle Eastern cuisine specialists in Madrid and Barcelona represent concentrated demand pockets.
- Lime Zest:Flavedo-only extraction serves confectionery and aromatherapy niches. Limited domestic oil expression capacity forces reliance on imported citrus terpenes.
Fresh limes lead on scale; lime juice leads on momentum.
Grade:
Certification tier determines access to EU institutional procurement and export quota eligibility, with organic validation requiring 24-36 month conversion timelines that strain processor planning horizons.
- Organic:AENOR-certified production excludes synthetic pesticides and mandates buffer zones from conventional groves. Spanish acreage conversion lags processor demand, forcing premium pricing and multi-season supply agreements with named Andalusian cooperatives.
- Conventional:EU Regulation 396/2005 compliance suffices for domestic retail and most industrial accounts. Murcian suppliers dominate volume contracts though geographic concentration creates drought vulnerability.
- Premium:Size-graded and blemish-controlled fruit targets hospitality and gift segments. Seville province packing stations specialize in calibrated 48-53mm diameter specifications.
- Standard:Ungraded or minimally sorted product serves extractive industries where appearance tolerance permits. Juice concentrate and essential oil distillation absorb most standard-grade throughput.
Conventional grade leads on scale; organic leads on momentum.
End User:
Application-specific purity thresholds segment the buyer base, with food and pharmaceutical processors enforcing the strictest residue documentation while personal care formulators prioritize aromatic consistency.
- Food Industry:Tortilla flour nixtamalization, pickle crisping, and sauce pH stabilization absorb hydrated lime volumes. Andalusian processing clusters in Seville province coordinate direct procurement from named groves to bypass traditional Murcian brokers.
- Beverage Industry:Mixer manufacturers and craft distilleries demand cold-pressed NFC juice with documented Brix and acid ratios. Valencia province bottling lines source under multi-season contracts with Huelva province growers.
- Pharmaceuticals:Food-grade hydrated lime meets excipient and antacid active ingredient specifications. AENOR conformity assessment validates safety documentation for domestic distribution.
- Personal Care:Essential oil extraction and natural fragrance compounding utilize expressed peel oils. Limited Spanish expression capacity constrains domestic supply.
Food industry leads on scale; beverage industry leads on momentum.
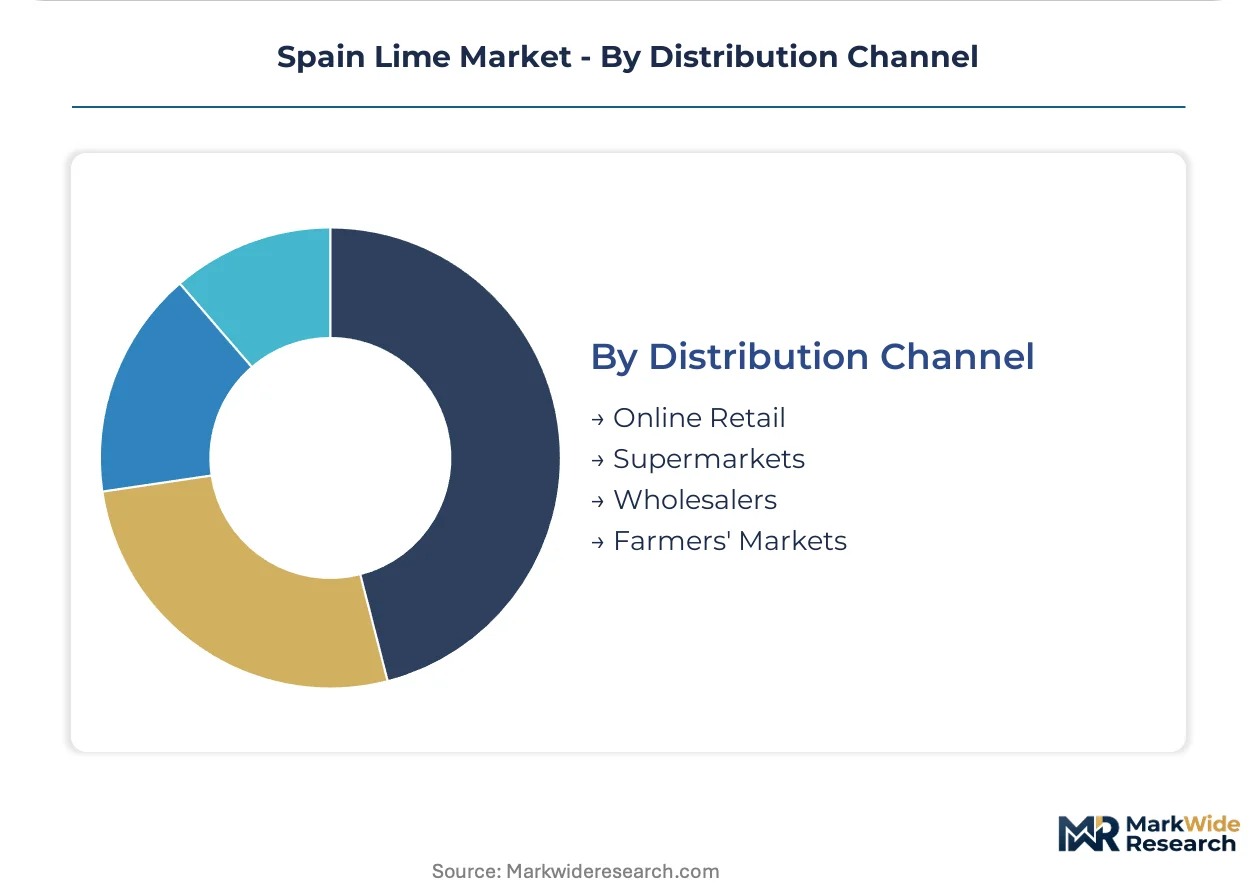
Distribution Channel:
Channel selection reflects buyer scale and traceability requirements, with large processors favoring direct contracting while fragmented retail accounts sustain wholesale intermediation.
- Supermarkets:Mercadona, Carrefour España, and Eroski enforce GLOBALG.A.P. certification and blockchain-traceable origin documentation. Private label expansion concentrates procurement among three preferred Andalusian cooperatives.
- Wholesalers:Traditional Murcian brokers aggregate smallholder production for industrial processors. Margin compression from direct-to-processor digital platforms threatens intermediary viability.
- Online Retail:Amazon España and specialized citrus platforms serve metropolitan consumers and small-batch processors. Cold-chain logistics investment limits seller participation to integrated packing stations.
- Farmers' Markets:Direct producer-to-consumer sales concentrate in Seville, Málaga, and Córdoba urban centers. Organic certification premiums justify transport costs for participating growers.
Supermarkets lead on scale; online retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward Andalusian and northern Spanish limestone belts where EU environmental compliance costs remain lower than import alternatives. The regulatory-arbitrage gap between domestic calcination and imported hydrated lime creates sustained investment pull in quarry-to-kiln integrated operations.
Andalusia
Coastal groves around Seville and Córdoba supply nixtamalization-grade limes for tortilla flour processors. EU Regulation 396/2005 enforcement through Spain's Ministry of Agriculture tightens residue documentation requirements. Direct contracting between Seville province packing stations and food manufacturers displaces traditional Murcian wholesale intermediation.
Murcia
Historical supply concentration faces yield instability from drought-driven irrigation restrictions under Spain's revised Hydrological Plan. Conventional grade citrus dominates volume contracts for juice concentrate and essential oil distillation. Southeastern processing clusters absorb standard-grade throughput where appearance tolerance permits lower specification fruit.
Catalonia
Barcelona metropolitan demand centers on beverage industry applications for cold-pressed NFC juice in premium mixer manufacturing. AENOR conformity assessment validates safety documentation for pharmaceutical-grade hydrated lime distribution. Personal care formulators in the province prioritize aromatic consistency from expressed peel oils.
Basque Country
Industrial quicklime consumption concentrates around steel sector metallurgical flux applications requiring 96% CaO purity. Northern limestone reserves support high-calcium production for environmental remediation contracts. REACH framework classification obligations govern safety data sheet preparation for downstream chemical users in Bilbao industrial corridors.
Valencia
Beverage bottling lines source multi-season contracts with Huelva province growers for documented Brix and acid ratio compliance. Cold-pressed juice demand from craft distilleries and mixer manufacturers drives NFC procurement. Drought constraints under the Hydrological Plan limit contracted volumes despite processor expansion intentions.
Spain Lime Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue environmental remediation and digital procurement platforms. The vendor base stratifies across integrated quarry-to-kiln operators, specialized high-purity manufacturers, and regional distributors. Three archetypes dominate: northern Spanish limestone integrators, multinational specialty chemical suppliers, and Andalusian citrus cooperative processors. Capacity expansion and backward integration into captive limestone supply constitute the primary competitive moves.
Among Iberian integrated operators, Calcinor S.A. exemplifies quarry-to-kiln vertical control across northern Spanish reserves. Lhoist Group anchors the multinational specialty tier through high-calcium quicklime positioning. Carmeuse Group occupies the environmental application segment with flue-gas desulfurization grade supply relationships. These three represent distinct strategic postures rather than direct peer competition.
| Leading Market Players |
|---|
| Grupo Calidra |
| Grupo Cementos Portland Valderrivas |
| Calcinor S.A. |
| Cal Indústria i Subministraments |
| Omya Calcit Española |
| Lhoist Group |
| Cales de la Familia Molins |
| Calceras de Córdoba |
| Carmeuse Group |
| Others |
Value Network & Pricing Analysis
Food processors in Andalusia's nixtamalization corridor anchor pricing power through direct-to-grove contracting, compressing traditional Murcian broker margins and forcing three-tier pricing stratification across organic, conventional, and premium grades.
Pricing Analysis
Distributor markups on fresh citrus absorb cold-chain logistics costs from Seville province packing stations to tortilla flour manufacturers. Certification tier and volume scale drive price differentiation, with AENOR-validated organic supply commanding sustained premiums. Cost compression in conventional grades intensifies as drought-driven yield instability under Spain's Hydrological Plan tightens Murcian supply. Small-batch processors exhibit highest price sensitivity; steel sector quicklime buyers show lowest.
Supply Chain Analysis
Regional distribution centers in Seville and Córdoba provinces coordinate hub-and-spoke patterns for perishable fruit delivery. Spain's lime supply draws from Andalusian coastal groves, Murcian traditional clusters, and emerging Galician limestone reserves. Quicklime production rests on high-calcium limestone feedstock, fuel oil or natural gas energy inputs, and metallurgical flux specifications. Single-source vulnerability concentrates in Murcian irrigation-dependent acreage. Distribution runs through direct-processor digital platforms displacing wholesale broker intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's lime market represents a late-cycle quality story as tortilla flour manufacturers and steel mills pivot toward specification-verified supply with documented purity thresholds and residue compliance.
For Market Incumbents: Hedge against Murcian supply concentration by securing captive limestone reserves in Galicia and Asturias through quarry-to-kiln integration. Calcinor S.A.'s northern Spanish operations demonstrate viable diversification from drought-exposed southeastern groves. Prioritize AENOR certification investment to defend food-grade positioning against organic supply bottlenecks. For New Entrants and Emerging Players: Andalusian citrus cooperatives present the most penetrable channel partner type for bypassing traditional wholesale intermediation. White-space targets include blockchain-traceable supply platforms for supermarket private label programs and environmental remediation-grade hydrated lime for acid mine drainage contracts. A direct-to-processor digital procurement angle collapses margin leakage to established brokers. For Investors and Strategic Acquirers: Specialty chemical multinationals are the most active acquirer in this space, seeking Iberian quicklime capacity for steel and environmental applications. Long-term viability hinges on integrated quarry-to-kiln operations with REACH documentation capabilities. Watch kiln operator skill scarcity as an inflection indicator for operational risk premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Limestone | Calcinor S.A.'s northern Spanish reserves demonstrate supply security against Murcian drought exposure. |
| AENOR Organic Certification Investment | Food-grade hydrated lime suppliers gain preferential access to EU institutional procurement channels. |
| Direct-to-Processor Digital Platform | Andalusian cooperatives pilot blockchain-traceable systems that collapse traditional broker margins. |
| Environmental Remediation Grade Expansion | Carmeuse Group's flue-gas desulfurization relationships anchor new acid mine drainage applications. |
| Precision Kiln Automation Deployment | Real-time temperature monitoring enables just-in-time delivery contracts for steel sector flux buyers. |
Research Methodology
Multiple input streams — primary interviews with plant managers and procurement leads at downstream food processors, technical R&D directors at kiln operators, and distribution channel partners; secondary validation through Spain's Ministry of Agriculture enforcement records, AENOR certification databases, and ECHA REACH filings; plus customs and trade data — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product format, grade tier, end-use industry, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from modeled volume trajectories and value-per-ton assumptions. Industry-specific forecast inputs incorporated irrigation water allocation rulings under Spain's revised Hydrological Plan and EU Regulation 396/2005 residue limit enforcement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to drought-driven yield instability, organic acreage conversion rates, and flue-gas desulfurization substitution by sodium-based reagents. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Edible Flowers Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Dehydrated Green Beans Market
Fruits and Vegetables
Rosehip Market
Fruits and Vegetables
Europe Freeze-Dried Fruits and Vegetable Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
Celery Juice Market