
 Japan Frozen Fruit Puree Market | 2026-2036
Japan Frozen Fruit Puree Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Frozen Fruit Puree Market Outlook
Aging agricultural labor pools in Yamanashi and Wakayama prefectures is reorganizing domestic fruit sourcing networks for puree processors. Kagome Co., Ltd. leverages its extensive tomato and fruit processing infrastructure to secure year-round puree supply stability. Nestlé Japan anchors its dessert and beverage innovation pipeline through captive frozen fruit ingredient channels. Dole Japan competes on tropical fruit puree specialization, drawing on its Philippine and Southeast Asian growing operations.
Frozen fruit puree consists of mechanically processed fresh fruit that is rapidly pasteurized and blast-frozen at temperatures below minus 18 degrees Celsius to preserve cellular structure, color integrity, and enzymatic activity for industrial food production. The product serves as a standardized, shelf-stable ingredient base for manufacturers requiring consistent flavor profiles and reduced spoilage risk across extended production cycles. Berry puree occupies the dominant revenue position within the product type dimension, driven by bakery and confectionery sector procurement intensity. Beverage applications are expanding fastest among end-use categories, fueled by specialty coffee chains and craft cocktail programs seeking clean-label fruit bases. Online retail channels within the distribution structure are capturing disproportionate growth velocity as direct-to-restaurant and small-batch food service procurement migrates to digital platforms.
METI enforces cold chain standards under the Food Sanitation Act, while the Consumer Affairs Agency mandates detailed allergen and origin labeling that elevates compliance costs for imported puree suppliers. JAS organic certification and regional GI designations create tiered market access thresholds that favor domestic processors with established audit relationships. Stakeholders must monitor evolving pesticide residue limits under the Food Safety Commission's positive list system and assess whether HACCP-plus traceability investments justify premium positioning against commodity-grade imports.
Market Dynamics
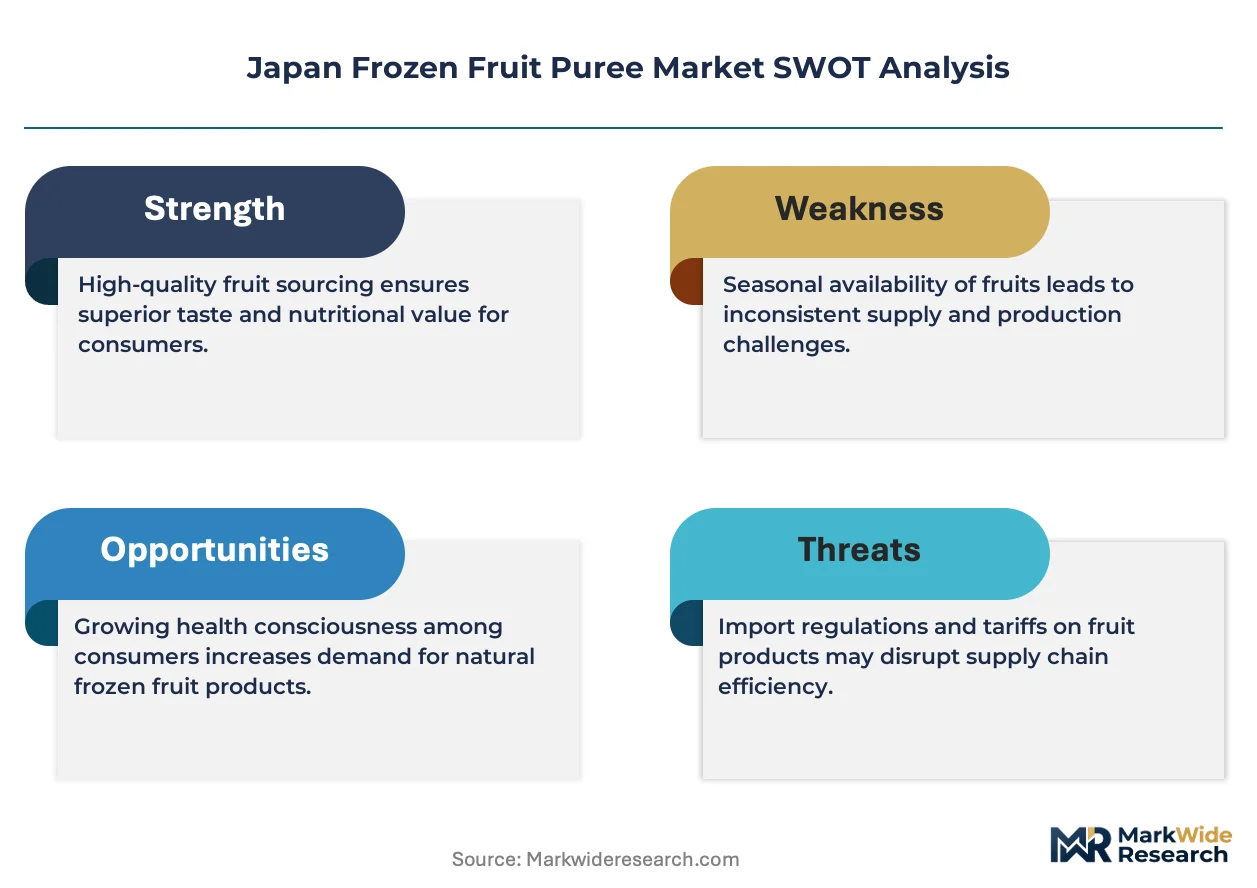
Cold chain efficiency mandates from METI are compressing operating margins for puree processors while accelerating consolidation among distributors unable to upgrade refrigeration infrastructure to compliant standards.
Growth Catalysts
- Consumer Affairs Agency labeling revisions:Stricter traceability requirements favor processors with established domestic audit relationships, creating procurement preference for JAS-certified suppliers.
- Specialty coffee chain expansion:Clean-label beverage programs in Greater Tokyo are standardizing frozen fruit puree as a base ingredient across seasonal menu rotations.
- Blast-freezing technology diffusion:Smaller processors in Yamanashi are adopting rapid freezing systems to preserve cellular integrity in domestic peach and grape purees.
Market Restraints
- Agricultural labor scarcity:Aging picker populations in Wakayama and Yamanashi prefectures constrain raw fruit availability during peak harvest windows.
- Import dependency for tropical varieties:Philippine and Southeast Asian supply concentration exposes processors to shipping disruption and currency fluctuation.
- Positive list pesticide thresholds:Food Safety Commission residue limits create rejection risk for imported puree lots that lack pre-shipment testing documentation.
Strategic Opportunities
- Hokkaido processing corridor:Underutilized dairy infrastructure offers conversion potential for berry puree production serving northern Japan food manufacturers.
- Direct-to-restaurant digital channels:Online procurement platforms are capturing small-batch artisanal beverage concepts previously served by traditional distributors.
- Regional GI designation leverage:Yamanashi peach and Wakayama ume geographic indications enable premium positioning against commodity-grade imports.
Industry Challenges
- HACCP-plus traceability system integration:Small and mid-sized processors face capital requirements for temperature logging and batch-tracking software.
- Cold chain reconfiguration:Distributors must retrofit warehousing and transport fleets to maintain minus 18 degrees Celsius compliance across last-mile delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Frozen Fruit Puree Market |
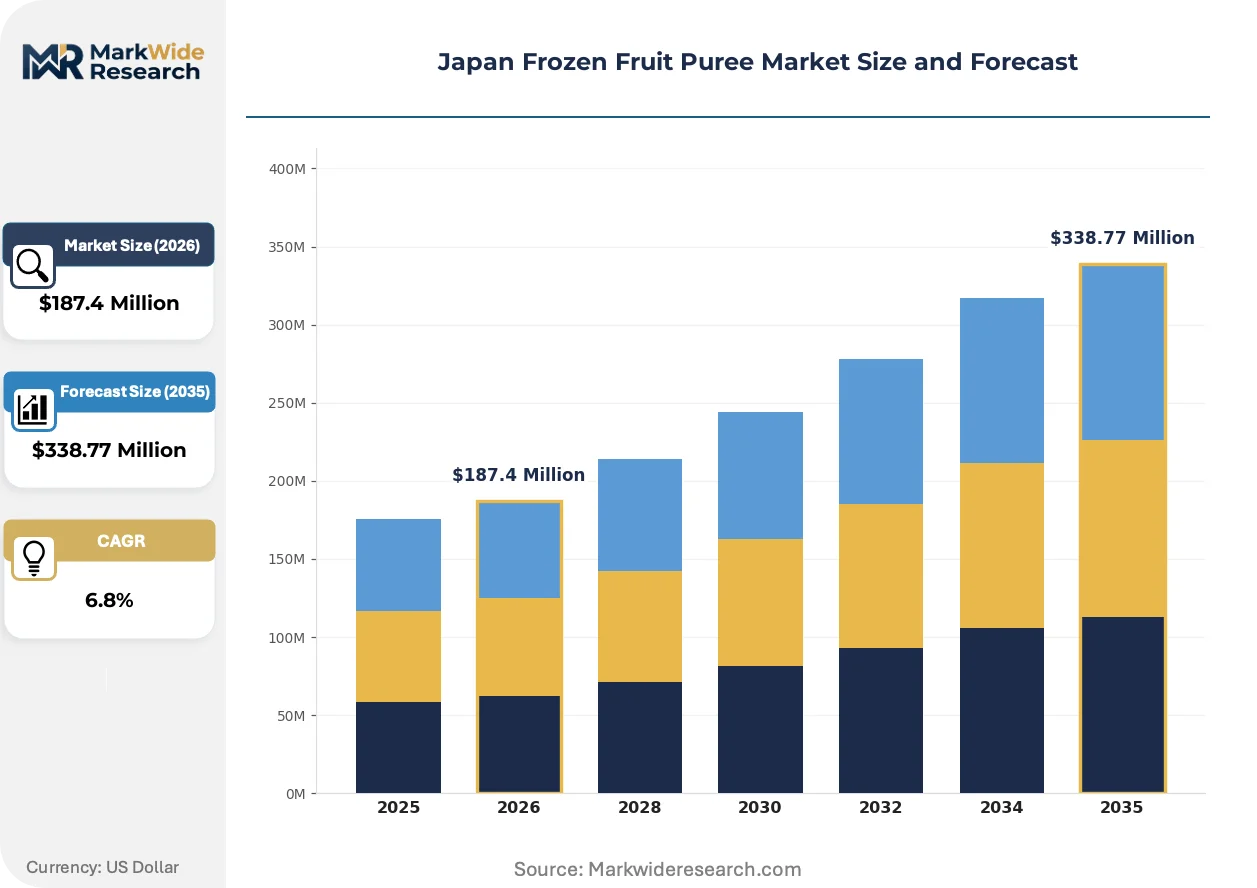
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Berry, Mango, Banana, Peach Application: Desserts, Beverages, Sauces, Baby Food Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores End User: Food Manufacturers, Restaurants, Caterers, Households |
| Companies Covered | ITOCHU Corporation, Asahi Group Holdings, Ltd., Nestlé Japan, Kerry Group, Dole Japan, Kagome Co., Ltd., Kirin Holdings Company, Limited, Olam International, Suntory Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Frozen Fruit Puree Market Strategic Shifts
Processing technology and procurement digitization are restructuring how puree moves from agricultural source to industrial end-use, with regulatory pressure accelerating adoption timelines.
High-pressure processing equipment is supplanting traditional thermal pasteurization in premium puree lines. Specialty dessert manufacturers in Osaka and Fukuoka are installing these systems to claim enzyme activity preservation on product specifications. This shift is compressing the shelf-life advantage previously held by frozen concentrate imports.
METI's cold chain efficiency standards under the Food Sanitation Act are mandating real-time temperature monitoring across transport and storage nodes. Compliance investments are diverting capital from production expansion at mid-sized processors. Kanto region distributors are responding by consolidating warehousing footprints to reduce monitoring point complexity.
Artisanal beverage programs are consolidating supplier relationships around processors offering single-origin puree with documented cultivar and harvest date. Specialty coffee chains in Tokyo and Yokohama are replacing multi-fruit blend suppliers with direct contracts to Yamanashi and Hokkaido processors. This concentration is visible in menu descriptions emphasizing prefecture-level provenance.
Japan Frozen Fruit Puree Market Segmentation
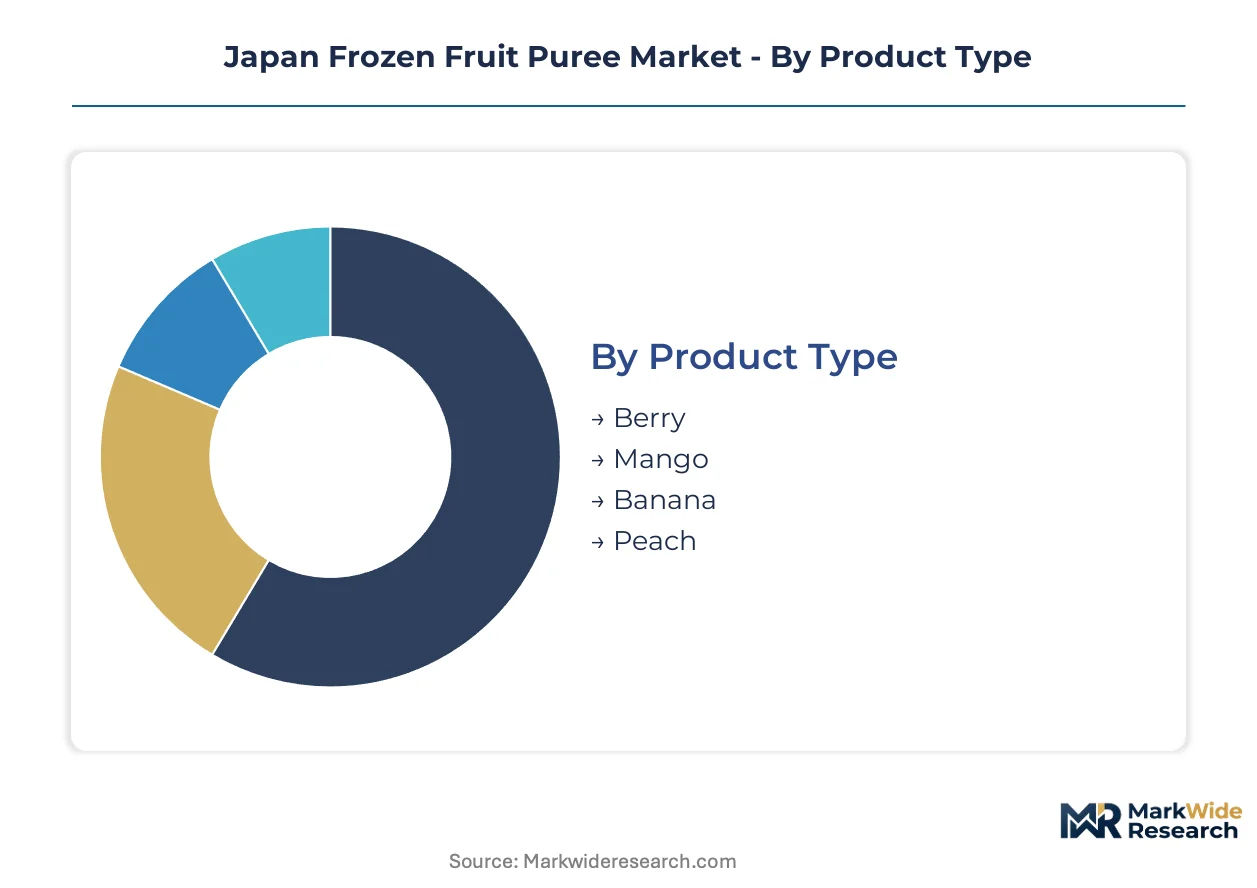
Segmentation in Japan's frozen fruit puree market reveals how procurement channels, application requirements, and end-user scale determine product specifications and supplier relationships. Understanding these dimensions exposes where margin concentrates and where volume flows.
Product Type:
Berry puree moves predominantly through wholesale channels serving industrial bakeries, while tropical varieties concentrate in foodservice direct procurement.
- Berry:Strawberry, blueberry, and raspberry formulations dominate procurement volumes from Yamanashi and Hokkaido processors. Premium dessert chains in Greater Tokyo specify berry puree with documented cultivar and harvest date for clean-label positioning.
- Mango:Philippine-sourced puree carries currency fluctuation exposure that processors hedge through forward contracts. Specialty beverage programs in Osaka and Fukuoka are consolidating supplier relationships around single-origin mango puree with pre-shipment residue testing documentation.
- Banana:Ecuadorian and Philippine supply lines serve baby food manufacturers requiring consistent brix specifications.
- Peach:Yamanashi GI-designated puree commands premium positioning against commodity imports through documented orchard provenance.
By volume, Berry leads. By growth pace, Mango is ahead.
Application:
Application mix determines pasteurization intensity and packaging format, with dessert and beverage segments driving divergent processing investments.
- Desserts:Bakery and confectionery manufacturers require standardized viscosity for consistent recipe execution across production cycles. High-pressure processing equipment installations in Osaka are displacing thermal pasteurization for enzyme-active premium lines.
- Beverages:Specialty coffee chains and craft cocktail programs in Tokyo and Yokohama are standardizing frozen fruit puree as a base ingredient. Clean-label requirements favor domestic processors with JAS certification and documented cold chain compliance.
- Sauces:Food manufacturers blend puree with acidity modifiers for extended ambient shelf stability.
- Baby Food:Positive list pesticide thresholds from the Food Safety Commission create rejection risk for imported lots lacking comprehensive pre-shipment testing.
Desserts captures the largest revenue pool. Beverages is climbing the fastest.
Distribution Channel:
Channel structure reflects customer scale and order frequency, with digital platforms capturing small-batch procurement previously served by traditional distributors.
- Online Retail:Direct-to-restaurant platforms enable artisanal beverage concepts to source single-origin puree with documented traceability. Digital procurement is capturing disproportionate growth velocity as small-batch foodservice operators migrate from traditional distributor relationships.
- Supermarkets:Retail-packaged puree serves household consumers and small caterers in Greater Tokyo and Kansai metropolitan areas.
- Wholesalers:Tsukiji and Osaka central market distributors maintain cold chain infrastructure for industrial food manufacturers requiring pallet-scale procurement.
- Specialty Stores:Regional puree processors in Yamanashi and Wakayama operate direct retail channels for GI-designated products.
Wholesalers handle the greatest tonnage. Online Retail is gaining share fastest.
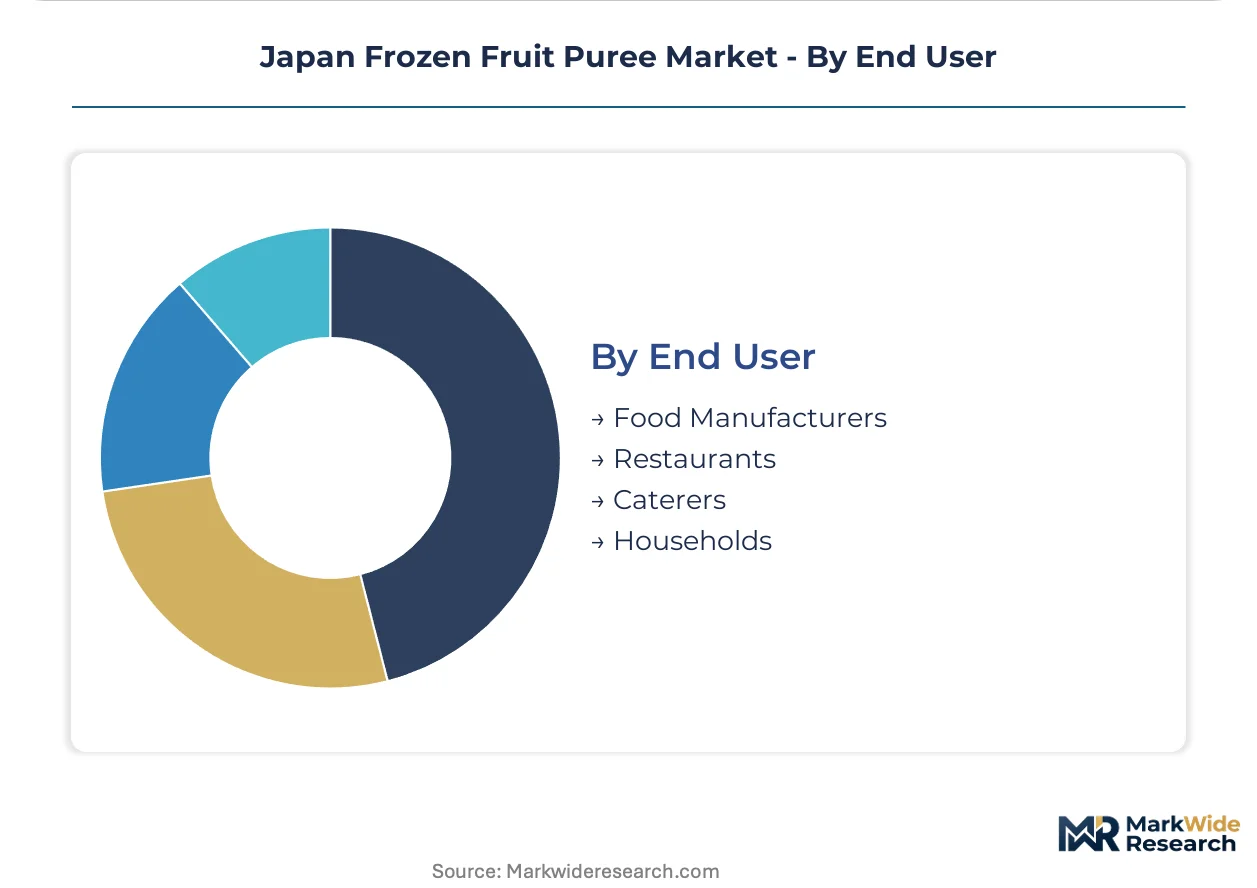
End User:
End-user scale determines contract structure, with food manufacturers negotiating annual volume agreements while restaurants operate on spot procurement.
- Food Manufacturers:Industrial processors require year-round supply stability through multi-source contracting and strategic inventory positioning. Kagome and Nestlé Japan anchor procurement through captive frozen fruit ingredient channels.
- Restaurants:Specialty coffee chains and premium dessert concepts in Greater Tokyo are consolidating supplier relationships around processors offering single-origin puree with prefecture-level provenance documentation.
- Caterers:Event and institutional foodservice operators procure through wholesale channels with seasonal demand fluctuation.
- Households:Retail-format puree serves home baking and smoothie preparation with limited volume contribution.
Food Manufacturers absorb the highest volume. Restaurants are expanding procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's cold chain mandates under the Food Sanitation Act anchor procurement patterns across Japan's frozen fruit puree landscape. Prefecture-level agricultural specialization and metropolitan demand concentration shape regional market dynamics.
Kanto/Tokyo
Specialty coffee chains and premium dessert concepts in Greater Tokyo drive concentrated demand for single-origin puree with documented prefecture-level provenance. Consumer Affairs Agency labeling revisions tighten traceability requirements for suppliers serving this metropolitan cluster. Tsukiji market distributors maintain cold chain infrastructure for industrial food manufacturers requiring pallet-scale procurement.
Kansai/Osaka
Artisanal beverage programs in Osaka and Fukuoka standardize frozen fruit puree as a base ingredient across seasonal menu rotations. High-pressure processing equipment installations in this region displace thermal pasteurization for enzyme-active premium lines. Local processors leverage proximity to Kyoto's traditional confectionery manufacturers for specialty dessert applications.
Chubu/Nagoya
Industrial food manufacturers in Aichi Prefecture require year-round supply stability through multi-source contracting and strategic inventory positioning. METI enforcement of cold chain standards accelerates consolidation among mid-sized distributors unable to upgrade refrigeration infrastructure. Nagoya's central location supports distribution efficiency to both eastern and western markets.
Yamanashi/Wakayama
Aging agricultural labor pools in these prefectures constrain raw fruit availability during peak harvest windows for peach and ume purees. JAS organic certification and regional GI designations create tiered market access thresholds favoring domestic processors with established audit relationships. Direct retail channels for GI-designated products operate alongside traditional wholesale distribution.
Hokkaido
Underutilized dairy infrastructure offers conversion potential for berry puree production serving northern Japan food manufacturers. Blast-freezing technology diffusion among smaller processors preserves cellular integrity in domestic fruit varieties. Sapporo-based distributors capture demand from seafood processors diversifying into fruit-based product lines.
Japan Frozen Fruit Puree Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Japan's frozen fruit puree market. The upper tier commands captive supply channels and year-round procurement stability, while mid-sized processors compete on regional GI designation access and JAS certification compliance. Three archetypes dominate: diversified food conglomerates with frozen fruit divisions, agricultural processors with captive orchards, and import-specialized trading houses. Competitive moves concentrate on backward integration into orchard operations and HACCP-plus traceability system investments.
Among integrated food conglomerates, Kagome Co., Ltd. and Nestlé Japan exemplify archetypes leveraging extensive processing infrastructure to secure supply stability. Dole Japan occupies a position within the tropical specialization tier, drawing on Philippine and Southeast Asian growing operations. Trading house ITOCHU Corporation sits within the import facilitation archetype, connecting international supply lines to domestic distribution networks.
| Leading Market Players |
|---|
| ITOCHU Corporation |
| Asahi Group Holdings, Ltd. |
| Nestlé Japan |
| Kerry Group |
| Dole Japan |
| Kagome Co., Ltd. |
| Kirin Holdings Company, Limited |
| Olam International |
| Suntory Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
High-pressure processing equipment displacing thermal pasteurization in premium puree lines simultaneously redraws Japan's processing geography and compresses price premiums previously commanded by frozen concentrate imports. Domestic processors in Yamanashi and Hokkaido capture margin expansion from shorter cold chains while METI compliance costs filter commodity-grade suppliers from metropolitan procurement channels.
Pricing Analysis
Geographic price spreads between Kanto metropolitan buyers and Hokkaido processors reflect cold chain compliance cost differentials rather than quality variance alone. Three-tier pricing structure across JAS-certified premium, standard domestic, and commodity import levels stratifies procurement channels. Pricing pressure stems from METI's real-time temperature monitoring mandates diverting distributor capital from volume expansion. Small-batch artisanal beverage concepts in Tokyo exhibit lowest price sensitivity while institutional caterers negotiate aggressively on pallet-scale contracts.
Supply Chain Analysis
The Philippines and Ecuador anchor tropical fruit puree supply for Japanese processors, with Philippine mango and Ecuadorian banana feeding baby food and beverage manufacturing lines. Raw material dependencies center on Southeast Asian orchard operations, ocean freight refrigeration capacity, and pre-shipment residue testing documentation. Single-source vulnerability concentrates in Philippine supply lines exposed to shipping disruption and currency fluctuation. Distribution runs through Tsukiji and Osaka central market distributors maintaining minus 18 degrees Celsius infrastructure for industrial food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty coffee chain procurement consolidation around single-origin puree with prefecture-level provenance fragments supplier relationships into cultivar-specific niches, creating entry points for regional processors with documented cold chain compliance.
For Market Incumbents: Compound JAS certification advantages by converting Hokkaido dairy infrastructure into berry puree production corridors serving northern Japan food manufacturers. Deepen backward integration into Yamanashi and Wakayama orchard operations before agricultural labor scarcity accelerates raw fruit cost inflation. METI's cold chain efficiency mandates threaten mid-sized distributors unable to upgrade refrigeration fleets, creating acquisition targets with established last-mile networks. For New Entrants and Emerging Players: Anchor in Hokkaido's underutilized processing capacity for berry puree serving seafood processors diversifying into fruit-based product lines. Target direct-to-restaurant digital channels capturing artisanal beverage concepts migrating from traditional distributor relationships. A go-to-market angle emphasizing single-origin cultivar documentation with harvest-date traceability penetrates specialty coffee chain procurement committees in Greater Tokyo. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors processors with captive orchard relationships and HACCP-plus traceability infrastructure already deployed. Long-term viability over the next decade hinges on backward integration depth and regional GI designation access rather than import trading relationships. Acquisition target archetypes include Yamanashi and Wakayama processors holding peach and ume geographic indications with established Consumer Affairs Agency audit histories. The signal to watch is METI enforcement acceleration forcing distributor bankruptcy waves that release captive customer relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Hokkaido Infrastructure Conversion | Repurposed dairy blast-freezing capacity captures berry puree demand from northern Japan food manufacturers. |
| JAS Organic Certification Investment | Consumer Affairs Agency labeling revisions elevate certified suppliers in specialty coffee chain procurement. |
| Direct-to-Restaurant Digital Platform Launch | Online procurement captures artisanal beverage concepts migrating from traditional Tsukiji distributors. |
| Regional GI Designation Leverage | Yamanashi peach and Wakayama ume provenance documentation commands premium positioning against Philippine imports. |
| HACCP-Plus Traceability System Deployment | Temperature logging and batch-tracking software satisfies METI cold chain mandates for metropolitan buyers. |
Study Parameters
Cross-validation between processor procurement records and Consumer Affairs Agency compliance filings anchors the qualitative findings in documented regulatory exposure. Primary interviews with frozen fruit puree plant managers, specialty coffee chain procurement directors, Tsukiji market distributors, METI cold chain inspectors, and Yamanashi orchard operators combined with secondary validation from customs trade data, Food Safety Commission residue testing records, JAS certification registries, and prefectural agricultural labor statistics. Bottom-up volume estimates from individual processor capacity triangulate against top-down demand aggregation from food manufacturer procurement disclosures.
Sensitivity analysis around agricultural labor availability assumptions and Philippine peso exchange rate volatility bounds the projection uncertainty. Segmentation dimensions modeled include product type, application category, distribution channel, and end-user scale across the analysis window. CAGRs derive from trend extrapolation of procurement intensity ratios adjusted for METI regulatory implementation timelines. Industry-specific forecast inputs incorporate blast-freezing technology diffusion rates in Yamanashi and specialty coffee chain outlet expansion in Greater Tokyo.
Material uncertainties — agricultural labor pool collapse in Wakayama and Yamanashi, Philippine shipping route disruption, Food Safety Commission positive list threshold revisions — sit outside the modeled envelope. Forecasts reflect assumptions about cold chain infrastructure upgrade completion and JAS certification audit capacity expansion. Recalibration cycles align with material shifts in METI enforcement intensity and Consumer Affairs Agency labeling requirement amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Europe Canned Fruits Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Aronia Berries Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Fava Beans Market
Fruits and Vegetables
Jackfruit Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
Asia Pacific Olive Market
Fruits and Vegetables
Gold Kiwifruit Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market