
 Saudi Arabia Container Glass Market | 2026-2036
Saudi Arabia Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Container Glass Market Insights
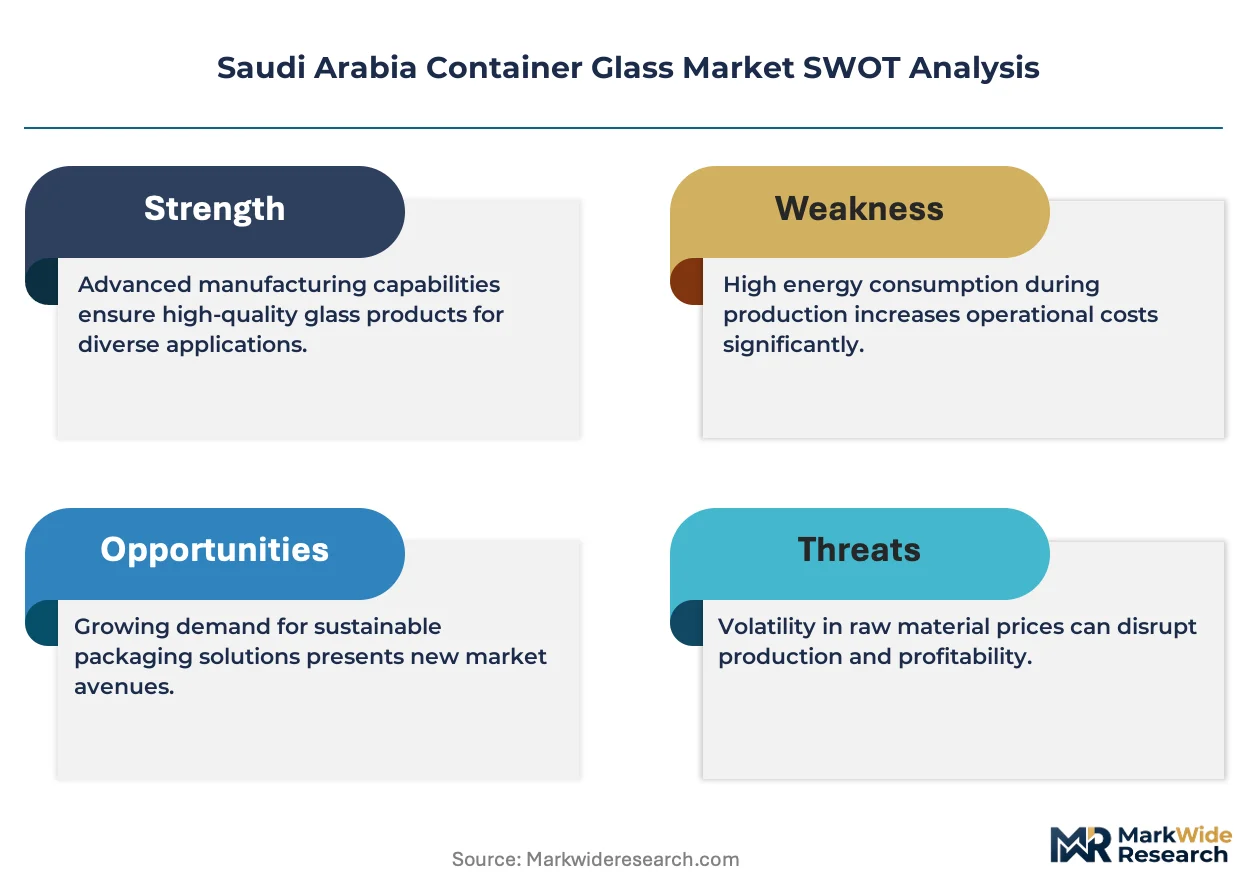
Pharmaceutical-grade borosilicate and Type III soda-lime specifications is redrawing competitive boundaries in the Saudi container glass sector. National Company for Glass Industries (Zoujaj) anchors its position through captive raw material sourcing from the Eastern Province silica belt. Saudi Arabian Glass Company Ltd. differentiates via dedicated furnace lines for amber and flint pharmaceutical vials. Schott AG leverages its German technical licensing to dominate high-barrier ampoule segments for injectable drugs.
Container glass denotes hollow-formed silica-based products manufactured through blow-and-blow or press-and-blow processes, typically containing 70-74% silicon dioxide with sodium carbonate and calcium oxide fluxes, engineered to provide chemical inertness and gas barrier protection for packaged contents. Bottles command the largest volume share as carbonated soft drink and edible oil bottlers expand PET replacement programs. Jars represent the fastest-growing product category as date paste, honey, and tahini processors shift from plastic to glass for export-grade halal certification compliance. The 100ml-500ml capacity band captures disproportionate margin pools through cosmetic serum and pharmaceutical oral liquid applications.
SFDA pharmaceutical packaging regulations and SASO quality mark requirements shape material purity thresholds and migration testing protocols for all domestic production. The Saudi Food and Drug Authority enforces GMP-aligned documentation for glass contact surfaces in drug packaging, while SASO's technical regulations for food-contact materials mandate lead and cadmium leachate limits. MOF's domestic content incentives under the National Industrial Development and Logistics Program redirect procurement toward local furnace operations. Stakeholders must track how Riyadh's industrial cluster expansions and Jeddah port modernization alter logistics economics for imported cullet versus domestic virgin batch.
Market Dynamics
SFDA's pharmaceutical-grade glass mandates are compressing supply-side capacity while redirecting investment toward borosilicate furnace upgrades across the Eastern Province industrial corridor.
Growth Catalysts
- SFDA GMP-aligned documentation requirements:Pharmaceutical packaging rules tighten material purity thresholds, forcing domestic furnace operators to upgrade batch chemistry and quality systems.
- Date paste and tahini exporters:Halal certification compliance for European and Asian markets drives PET-to-glass conversion in food processing clusters around Al-Ahsa and Qassim.
- Jeddah Islamic Port modernization:Expanded container handling capacity reduces landed cost for imported cullet, enabling larger furnace scale economies for virgin batch substitution.
Market Restraints
- Natural gas price volatility:Furnace operations depend on subsidized Saudi Aramco feedstock; any tariff recalibration directly impacts melt cost structures.
- Eastern Province silica concentration:High-purity sand deposits cluster near Jubail, creating single-source dependency for premium flint and amber production.
- Pharmaceutical polymer substitution:Cyclic olefin copolymers and barrier plastics penetrate oral liquid segments where breakage risk outweighs glass barrier benefits.
Strategic Opportunities
- Neom industrial zone development:Greenfield glass manufacturing sites can integrate renewable energy for furnace electrification pilots under Vision 2030 industrial targets.
- Cosmetic serum ampoules:Premium skincare brands in Riyadh and Jeddah seek 5-20ml borosilicate formats for retinol and vitamin C formulations requiring UV and oxygen barrier.
- MOF domestic content incentives:National Industrial Development and Logistics Program procurement rules favor local furnace output for government-funded healthcare infrastructure.
Industry Challenges
- Specialized furnace engineering talent:Borosilicate and neutral glass production requires European or Japanese technical licensing, creating knowledge transfer bottlenecks.
- SFDA migration testing timelines:New product registrations require 12-18 month stability protocols, delaying revenue realization for furnace reconfiguration investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Container Glass Market |
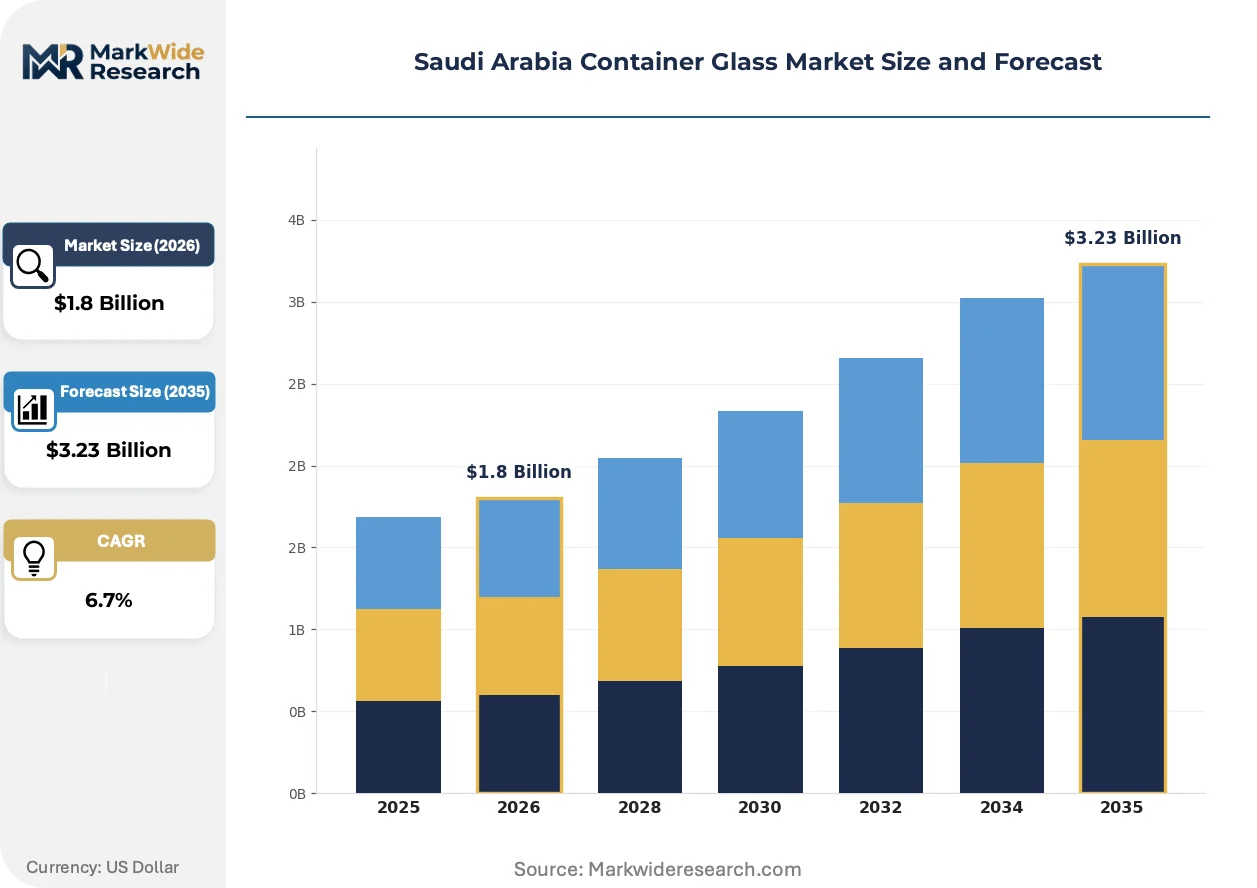
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Tumblers, Containers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Capacity: Less than 100ml, 100ml-500ml, 500ml-1L, Above 1L Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Distributors |
| Companies Covered | Saudi Arabian Glass Company Ltd., National Company for Glass Industries (Zoujaj), Mahmood Saeed Glass Industry Company, Ardagh Packaging Group PLC, Obeikan Glass Company, Feemio Group Co., Ltd., Schott AG, Middle East Glass (MEG), Sonoco Products Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Container Glass Market Trends and Innovations
Electrified furnace technology and closed-loop cullet systems are reshaping capital deployment priorities across Saudi Arabia's container glass sector, with regulatory pressure accelerating the displacement of conventional fossil-fuel melting.
Hybrid oxy-fuel electric melting is supplanting conventional regenerative furnace designs in new installations. Pharmaceutical-grade producers in Jubail Industrial City adopt this technology to meet SFDA carbon intensity documentation requirements while maintaining borosilicate thermal stability. The shift compresses payback periods for furnace investments by reducing natural gas hedge exposure.
SFDA pharmaceutical packaging regulations now mandate extractables and leachables testing protocols aligned with US FDA guidance. Domestic manufacturers must establish in-house analytical chemistry capabilities or contract third-party laboratories in Riyadh. The compliance burden falls heaviest on oral liquid and injectable vial segments, where material purity documentation spans multiple batch records.
Direct procurement contracts between date processors and furnace operators are consolidating channel intermediaries. Large agricultural cooperatives in Al-Ahsa now negotiate volume commitments for 250-500ml amber jars bypassing traditional packaging distributors. This concentration is most visible in export-oriented operations seeking halal audit trail integrity from melt to fill.
Saudi Arabia Container Glass Market Segmentation
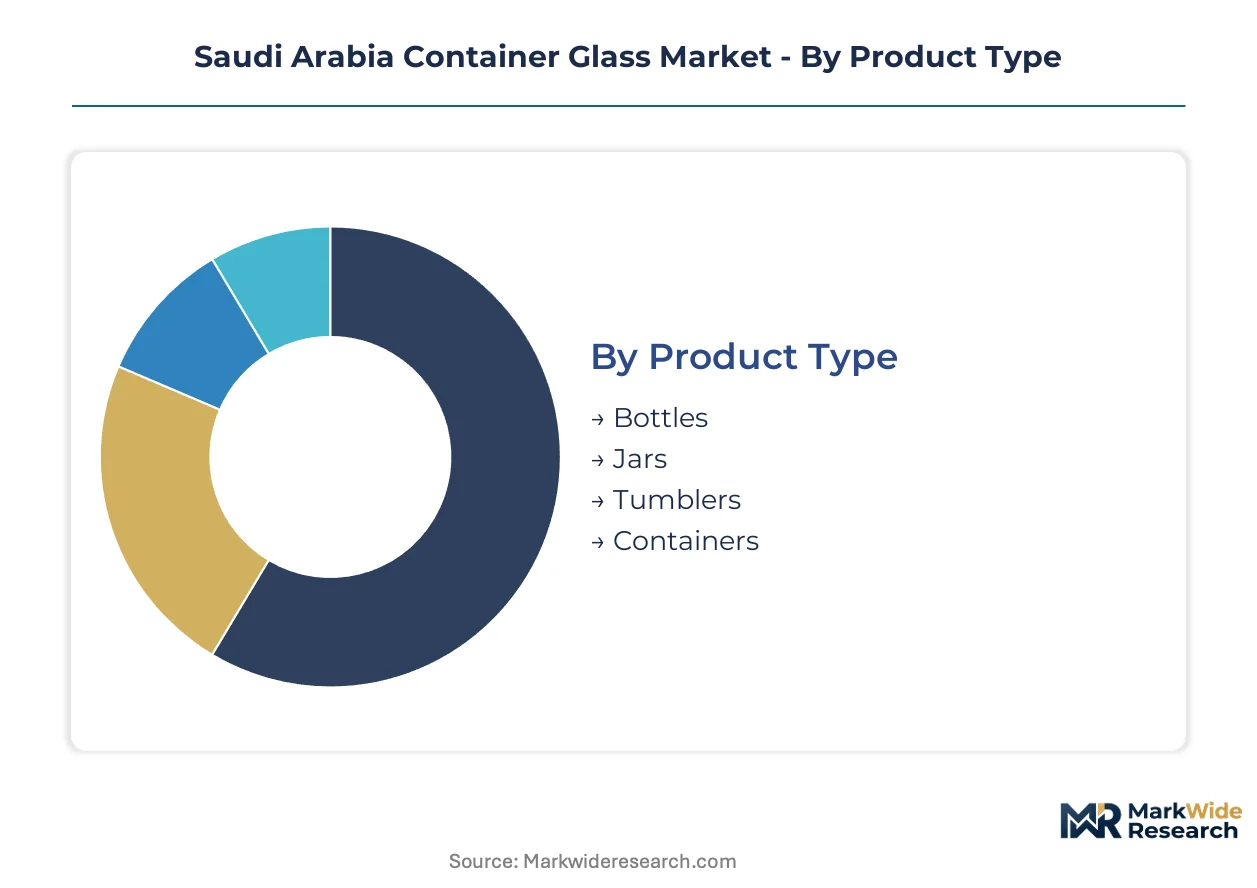
Container glass segmentation in Saudi Arabia tracks divergent margin economics across furnace configurations and regulatory exposure. Pharmaceutical-grade specifications command premium pricing tiers while food packaging volumes anchor capacity utilization.
Product Type:
Margin pools concentrate in pharmaceutical vials and premium cosmetic flint where SFDA documentation requirements create supply scarcity.
- Bottles:Blow-and-blow formed containers with 70-74% silicon dioxide content dominate carbonated soft drink and edible oil packaging. Riyadh-based bottlers are expanding PET replacement programs for premium juice lines, tightening furnace scheduling for clear flint production.
- Jars:Press-and-blow processed wide-mouth containers serve date paste, honey, and tahini processors in Al-Ahsa and Qassim seeking halal certification compliance for European export markets.
- Tumblers:Straight-sided drinking vessels with thickened bases target hospitality procurement in Jeddah and Riyadh hotel construction pipelines.
- Containers:Squat-form pharmaceutical and cosmetic vessels require dedicated amber and cobalt furnace lines for UV-blocking properties.
The dominant share belongs to bottles, while jars are closing the gap fastest.
End User:
Application-driven procurement patterns split between regulated healthcare documentation and commodity food volume commitments.
- Food & Beverage:Dairy, juice, and edible oil processors in Jeddah Industrial City drive demand for lightweighted 250-750ml formats with improved thermal shock resistance for hot-fill operations.
- Pharmaceuticals:Injectable and oral liquid drug manufacturers must source Type III soda-lime or borosilicate vials meeting SFDA GMP-aligned extractables testing protocols.
- Cosmetics:Premium skincare brands in Riyadh seek 5-20ml borosilicate ampoules for retinol formulations requiring oxygen and UV barrier protection.
- Household:Cleaning product and air freshener refill packaging concentrates in private-label supermarket supply chains with lower purity tolerance.
Food and beverage commands installed furnace capacity, though pharmaceuticals is expanding most quickly.
Capacity:
Volume bands align with distinct furnace scheduling economics and downstream filling line configurations.
- Less than 100ml:Miniature vials and ampoules for pharmaceutical injectables and cosmetic serums require precision forming with tight dimensional tolerances.
- 100ml-500ml:Mid-range formats capture disproportionate margin pools through cosmetic serum and pharmaceutical oral liquid applications in Riyadh and Jeddah.
- 500ml-1L:Standard beverage and condiment packaging volumes where lightweighting programs reduce gram weight per unit.
- Above 1L:Bulk edible oil and industrial chemical containers with thicker wall specifications for stacking strength.
The 100ml-500ml band generates premium returns, while sub-100ml formats are gaining share fastest.
Distribution Channel:
Channel structure reflects consolidation pressure from direct procurement contracts and logistics modernization investments.
- Online Retail:E-commerce platforms serve small-batch cosmetic and specialty food brands with fragmented order patterns and higher breakage risk in last-mile delivery.
- Supermarkets:Hypermarket private-label sourcing concentrates volume for standard jar and bottle formats with simplified quality specifications.
- Convenience Stores:Impulse-format beverage and single-serve condiment packaging with higher per-unit distribution costs.
- Distributors:Traditional channel intermediaries face margin compression as Al-Ahsa agricultural cooperatives negotiate direct volume commitments with furnace operators.
Distributors retain volume leadership, though direct procurement is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics shape Saudi Arabia's container glass geography. Domestic furnace output serves internal food and pharmaceutical demand while imported cullet and specialized vials flow through Jeddah Islamic Port. Industrial clustering concentrates capacity in corridors aligned to downstream filling operations and raw material access.
Eastern Province
High-purity silica deposits anchor the kingdom's premium flint and amber production. SFDA pharmaceutical-grade mandates concentrate borosilicate furnace investments in Jubail Industrial City. The region's captive sand sourcing from nearby deposits reduces batch chemistry variability for drug packaging applications.
Riyadh
Carbonated soft drink bottlers and dairy processors drive demand for lightweight 250-750ml clear flint formats. MOF domestic content incentives under NIDLP redirect government healthcare procurement toward local furnace operators. Industrial cluster expansions in the capital corridor tighten logistics networks for just-in-time glass supply.
Western Region
Jeddah's port modernization expands container handling capacity for imported cullet substitution. Date paste and tahini processors in Al-Ahsa and Qassim negotiate direct volume commitments with furnace operators for halal-certified export packaging. Hotel construction pipelines in Jeddah and Mecca sustain hospitality glassware procurement.
NEOM Northwest
Greenfield industrial zone development targets renewable-energy furnace electrification pilots under Vision 2030. The zone's planned manufacturing sites seek to integrate solar-powered melting for reduced carbon intensity documentation. Early-phase infrastructure commitments signal long-term capacity relocation from conventional Eastern Province corridors.
Saudi Arabia Container Glass Market Competitive Landscape
Concentration sits with integrated domestic furnace operators holding captive raw material positions and multinational specialists licensing pharmaceutical-grade technology. The market structure tiers between scale-driven national champions and precision-focused technical licensors. Three archetypes dominate: silica-integrated domestic producers, German-licensed pharmaceutical specialists, and regional packaging conglomerates with diversified material portfolios. Capacity expansion and direct procurement contracting represent the dominant competitive moves as food processors bypass traditional distribution channels.
Among domestic integrated producers, National Company for Glass Industries (Zoujaj) and Saudi Arabian Glass Company Ltd. occupy positions anchored to Eastern Province silica access and dedicated pharmaceutical furnace lines. Schott AG represents the technical-licensor archetype, leveraging German process knowledge for high-barrier ampoule segments. These three exemplify the market's split between volume-scale national production and precision-tier imported technology.
| Leading Market Players |
|---|
| Saudi Arabian Glass Company Ltd. |
| National Company for Glass Industries (Zoujaj) |
| Mahmood Saeed Glass Industry Company |
| Ardagh Packaging Group PLC |
| Obeikan Glass Company |
| Feemio Group Co., Ltd. |
| Schott AG |
| Middle East Glass (MEG) |
| Sonoco Products Company |
| Others |
Pricing and Supply Chain Analysis
Furnace scale economies in the Eastern Province silica belt concentrate pricing power among integrated producers with captive raw material access, while smaller operators face margin compression from batch chemistry upgrade costs and natural gas tariff exposure. This concentration elevates price floors for pharmaceutical-grade amber and flint specifications where SFDA documentation requirements create supply scarcity.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Saudi container glass sector. Pricing stratifies across premium, standard, and economy tiers based on SFDA certification grade and volume scale commitments. Cost compression in mid-range beverage formats is intensifying because PET replacement programs are absorbing excess flint capacity. Pharmaceutical processors show least price sensitivity due to regulatory compliance imperatives, while household cleaning product private-label buyers drive hardest bargain.
Supply Chain Analysis
Just-in-time glass supply dominates Riyadh and Jeddah industrial corridors where downstream filling operations cluster within 150-kilometer radius of furnace sites. Raw material sourcing draws from Eastern Province silica deposits, Egyptian limestone imports, and Jordanian soda ash. Single-source vulnerability concentrates in high-purity sand deposits near Jubail. Distribution runs through direct procurement contracts consolidating traditional distributor intermediaries, particularly for Al-Ahsa date paste cooperatives seeking halal audit integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA pharmaceutical-grade mandates are compressing supply-side capacity while redirecting investment toward borosilicate furnace upgrades, creating a high-growth disruption window for technical licensors and integrated domestic producers.
For Market Incumbents: Compound market position through backward integration into Eastern Province silica mining concessions and dedicated amber furnace lines for injectable vial segments. Pharmaceutical polymer substitution in oral liquid formats threatens glass barrier premiums. SFDA migration testing timelines delay revenue realization; secure early-stage analytical chemistry partnerships in Riyadh to compress registration cycles.
For New Entrants and Emerging Players: SFDA fast-track certification pathways for borosilicate ampoule production represent the most penetrable entry vector. Target cosmetic serum segments in Riyadh where 5-20ml formats command premium oxygen-barrier pricing. Neom greenfield sites offer renewable-energy furnace electrification differentiation for carbon-conscious European export buyers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade furnace operators with locked-in supply agreements from injectable drug manufacturers. Long-term viability centers on technical licensing arrangements with German or Japanese process specialists rather than commodity flint producers. Watch for Jeddah port modernization completion as signal for imported cullet substitution economics shifting competitive moats.
| Strategic Initiative | Industry Significance |
|---|---|
| Borosilicate Furnace Upgrade | SFDA pharmaceutical mandates force batch chemistry investments for Type III compliance. |
| Direct Procurement Contracting | Al-Ahsa agricultural cooperatives bypass distributors for halal-certified amber jar supply. |
| Renewable Energy Electrification | Neom greenfield sites pilot solar-powered melting under Vision 2030 industrial targets. |
| Analytical Chemistry Capability | In-house extractables testing reduces third-party dependency for SFDA registration. |
| Captive Silica Integration | Eastern Province sand deposits anchor batch consistency for premium flint production. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA regulatory filings, SASO technical regulations, and Eastern Province industrial development records. Primary interviews engaged furnace operations managers, pharmaceutical packaging procurement leads at Jeddah drug manufacturers, date paste export coordinators in Al-Ahsa, and logistics directors at Jeddah Islamic Port. Secondary validation drew from Saudi Aramco feedstock pricing disclosures, NIDLP procurement guidelines, and customs trade data on cullet imports. Bottom-up capacity utilization estimates triangulate against top-down demand projections from downstream filling line expansions.
Segmentation dimensions modeled span product type, end-user industry, capacity band, and distribution channel across the projection horizon. CAGRs derive from furnace investment pipelines, SFDA registration backlogs, and PET substitution elasticity in beverage segments. Industry-specific forecast inputs include natural gas tariff sensitivity scenarios and Jeddah port modernization throughput assumptions.
Decision-makers should treat outputs as directional under stable SFDA regulatory timelines and Saudi Aramco feedstock pricing; material deviation would warrant model refresh. Revision becomes warranted when pharmaceutical polymer substitution rates in oral liquid segments cross threshold penetration or Eastern Province silica supply disruptions alter batch economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Chile Container Glass Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
Japan Container Glass Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Cosmetic and Perfume Glass Packaging Market