
 Spain Packaging Market | 2026-2036
Spain Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Packaging Market Analytics
A shift from single-source corrugated supply to multi-material outsourcing is restructuring procurement across Spanish consumer goods manufacturers. Saica leverages integrated recycled-paper mills to anchor cost positions in the Iberian cardboard segment. Smurfit WestRock competes through continental scale in containerboard, while Vidrala dominates glass bottle supply to domestic wine and olive oil exporters.
Packaging encompasses engineered enclosures, barriers, and containment systems fabricated from substrates such as paperboard, polyethylene terephthalate, aluminum, and soda-lime glass, with specifications governing tensile strength, moisture vapor transmission rates, and seal integrity to protect goods through distribution and retail display. Paper-based materials lead volume in Spanish grocery logistics, though flexible plastic formats in bags and wraps capture margin pools in snack and frozen food applications. Rigid glass bottles sustain premium positioning in beverage and cosmetics end uses despite higher unit logistics costs.
Spain's national packaging regulator enforces EU Packaging and Packaging Waste Regulation targets for recyclability and extended producer responsibility, while BSI-equivalent standards laboratories certify food-contact compliance under frameworks aligned with EFSA migration limits. The EU Green Deal's carbon-border adjustments will tighten embodied-emission thresholds for imported packaging substrates. Stakeholders must monitor recycled-content verification protocols and regional sorting-infrastructure gaps to secure compliance cost advantages.
Market Dynamics
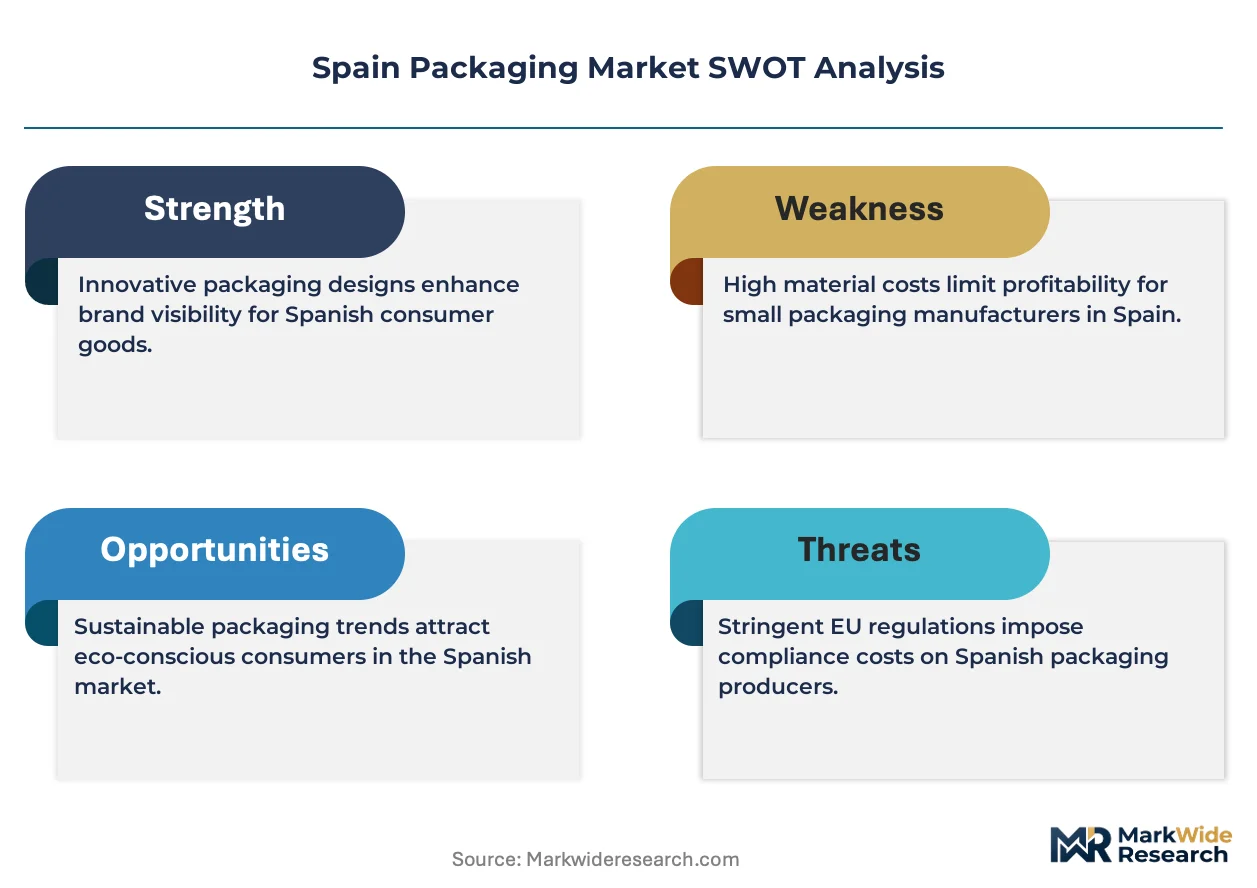
The EU Packaging and Packaging Waste Regulation is compressing design timelines and forcing substrate substitutions across Spanish manufacturing, while Catalonia's corrugated supply concentration creates procurement bottlenecks for national consumer goods brands.
Growth Catalysts
- Recycled-content mandates:The EU Green Deal's carbon-border adjustments are accelerating demand for verified post-consumer fiber in cardboard and flexible formats. Spanish converters with integrated recycling streams capture compliance premiums.
- Premium shelf-ready formats:Food exporters in olive oil and wine are adopting display-ready secondary packaging to reduce retail labor costs. This specification shift favors domestic converters with structural design capabilities.
- Catalonia's industrial corridor:Barcelona's logistics density and port access concentrate packaging demand from multinational consumer goods headquarters. Proximity to manufacturing clusters reduces inbound freight costs for substrate suppliers.
Market Restraints
- Recovered paper cost volatility:OCC (old corrugated containers) pricing fluctuates with Chinese import policy shifts. Spanish mills lack captive pulp sources, exposing margins to global fiber arbitrage.
- Glass logistics burden:Soda-lime bottle weight increases outbound freight costs for wine exporters competing with lightweight PET alternatives. Vidrala's domestic furnace network cannot fully offset this structural disadvantage.
- Sorting infrastructure gaps:Spain's municipal collection systems yield contaminated PET and mixed-fiber streams. EFSA-compliant food-grade recycled content remains scarce, constraining regulatory compliance pathways.
Strategic Opportunities
- Andalusia agricultural packaging:Olive oil and citrus exporters in Jaén and Seville underutilize smart tracking labels. RFID-enabled tertiary packaging could reduce insurance premiums and traceability audit costs.
- Flexible film downgauging:Convergence of metallocene polyethylene and barrier coating technologies enables thinner snack wrappers without shelf-life sacrifice. Converter investment in multilayer extrusion lines captures resin cost savings.
- Extended producer responsibility incentives:Spain's packaging waste management scheme rewards design-for-recycling submissions with reduced compliance fees. Early adopters of mono-material flexible formats secure multi-year cost advantages.
Industry Challenges
- Migration testing backlog:EFSA food-contact compliance certification for novel biobased coatings faces laboratory queue delays of 8-14 months. Product launches stall awaiting analytical reports from BSI-equivalent facilities.
- Legacy ERP integration:Spanish mid-tier converters operate on fragmented MES systems incompatible with customer-mandated supply chain visibility platforms. Cloud migration costs consume 15-20% of annual IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Packaging Market |
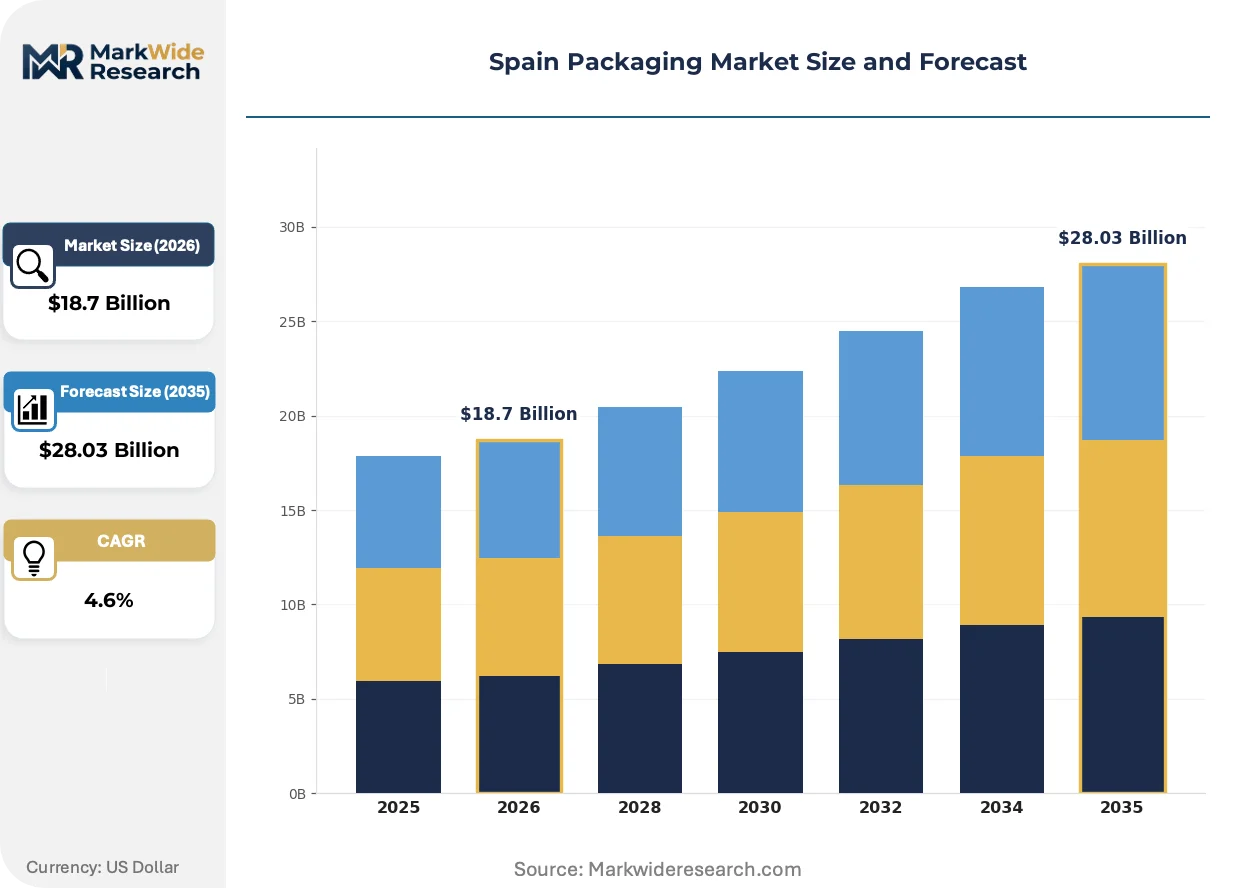
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Metal, Glass Product Type: Bottles, Boxes, Bags, Wraps End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Form Factor: Flexible, Rigid, Resealable, Stackable |
| Companies Covered | International Paper, Saica, Smurfit WestRock, Coveris Holdings, Crown Holdings, Mondi, Vidrala, Quadpack Industries, Amcor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Packaging Market Evolving Landscape
Digital printing and intelligent packaging are converging with regulatory traceability requirements, compressing production runs and enabling batch-level customization previously uneconomical at Spanish volume scales.
Digital flexographic and inkjet systems are integrating variable-data printing for regulatory batch codes and promotional versioning. Olive oil exporters in La Rioja and Catalonia are adopting these presses to manage SKU proliferation across export markets. This capability is integrating short-run economics into categories historically dominated by rotary offset, enabling just-in-time label production that reduces obsolescence risk from regulatory changes.
The EU Green Deal's carbon-border adjustment mechanism tightens embodied-emission documentation requirements for imported aluminum and plastic substrates. Spanish converters sourcing from non-EU suppliers must now secure verified Scope 3 certificates. Glass bottle exporters to Northern Europe face the steepest compliance burden, as furnace energy intensity data becomes mandatory for retail contract eligibility.
Retailers are consolidating packaging specifications to reduce handling complexity in automated distribution centers. Mercadona and Carrefour Spain are pushing standardized case dimensions and display-ready formats onto suppliers. This buyer concentration is visible in Catalonia's corrugated segment, where national accounts now represent 60-70% of volume for integrated mills, compressing margin pools for regional independents.
Spain Packaging Market Segmentation
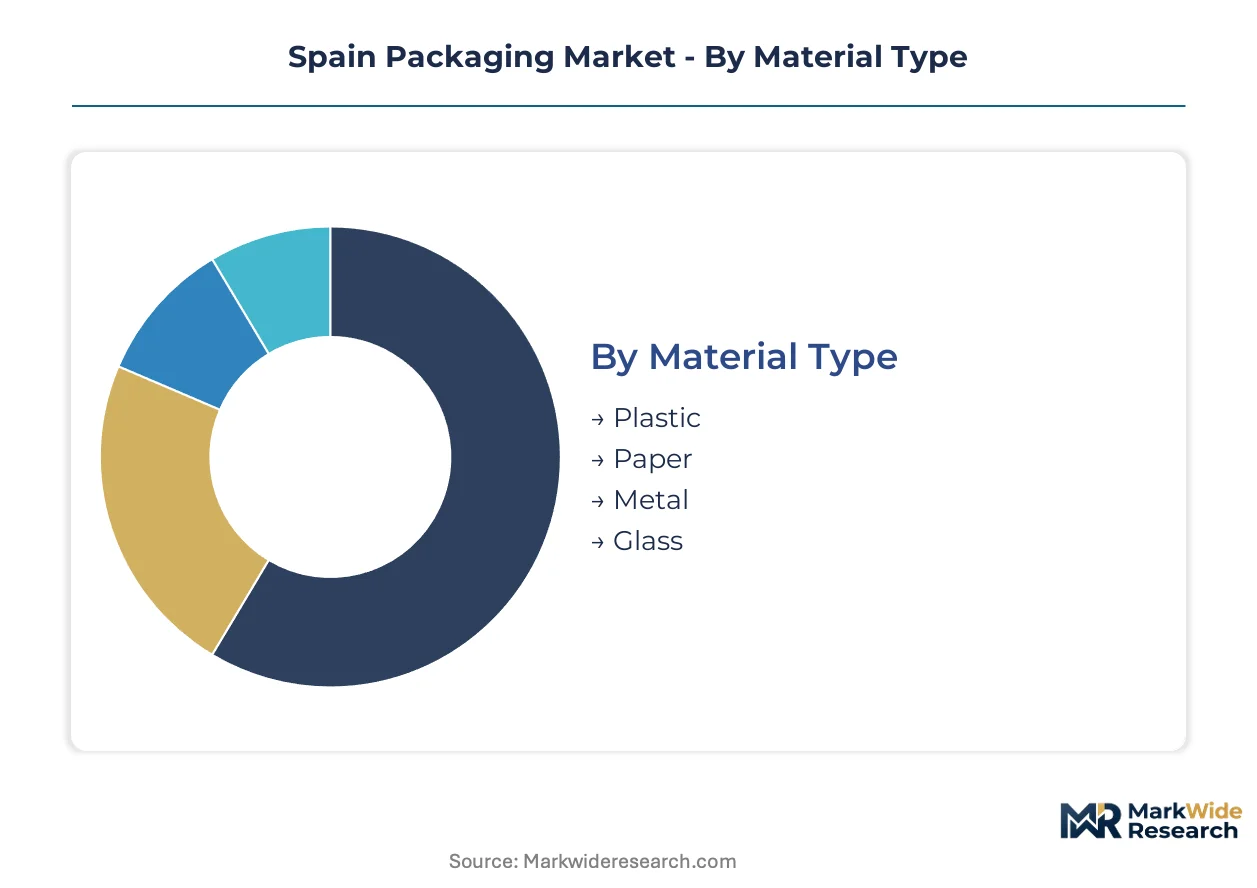
Spain's packaging market fragments across material, product, and end-use dimensions that dictate procurement complexity and margin capture. Each segmentation axis carries distinct regulatory burdens and supply chain geometries that reshape competitive positioning for converters and brand owners.
Material Type:
Paper mills cluster along Catalonia's industrial corridor, while plastic converters distribute more broadly across Valencia and Madrid autonomous communities.
- Plastic:Polyethylene terephthalate and polypropylene formats dominate snack and frozen food applications. Demand concentrates in flexible films for Mercadona's private-label suppliers, though EFSA-compliant recycled-content verification remains scarce due to municipal sorting contamination.
- Paper:Recycled corrugated containerboard anchors Iberian grocery logistics through integrated mills with captive OCC streams. Saica's Zaragoza and Barcelona facilities supply national consumer goods brands facing EU Green Deal carbon-border documentation requirements.
- Metal:Aluminum aerosols and beverage cans serve cosmetics and soft drink manufacturers with lightweight logistics advantages.
- Glass:Soda-lime bottles sustain premium wine and olive oil positioning despite outbound freight cost penalties against PET alternatives.
Today's leader: Paper. Tomorrow's challenger: Plastic — if food-grade recycling infrastructure closes the compliance gap.
Product Type:
Format selection tracks end-use handling requirements and retail automation compatibility, with specification consolidation accelerating among national grocery chains.
- Bottles:Rigid glass and PET containers serve beverage and pharmaceutical liquid dosing. Vidrala's domestic furnace network supplies La Rioja wine exporters with EFSA-migration-certified formats.
- Boxes:Corrugated RSC and display-ready cases dominate dry grocery distribution. Smurfit WestRock's continental scale competes with Saica's integrated recycling cost positions in Catalonia's procurement bottlenecks.
- Bags:Flexible polyethylene and paper formats capture snack and bakery applications with downgauging potential from metallocene resin technologies.
- Wraps:Stretch film and aluminum foil serve pallet containment and foodservice portion control with thinner gauge specifications reducing resin input costs.
Bottles command premium pricing through compliance certification; boxes face margin compression from buyer concentration.
End Use Industry:
Food and beverage procurement volumes shape converter investment priorities, while pharmaceutical and cosmetics segments impose stricter migration testing protocols.
- Food & Beverage:Olive oil, wine, and citrus exporters in Andalusia and Catalonia drive shelf-ready secondary packaging specifications. RFID-enabled tertiary formats could reduce insurance premiums for high-value agricultural shipments.
- Pharmaceuticals:Blister packs and vials require BSI-equivalent laboratory certification with queue delays of 8-14 months for novel biobased coatings.
- Cosmetics:Premium glass bottles and airless pumps sustain brand positioning through Barcelona's design-intensive supplier base.
- Electronics:Anti-static corrugated and molded pulp formats protect high-value components through Iberian distribution centers.
Food and beverage anchors volume; pharmaceuticals extracts compliance premiums through certification scarcity.
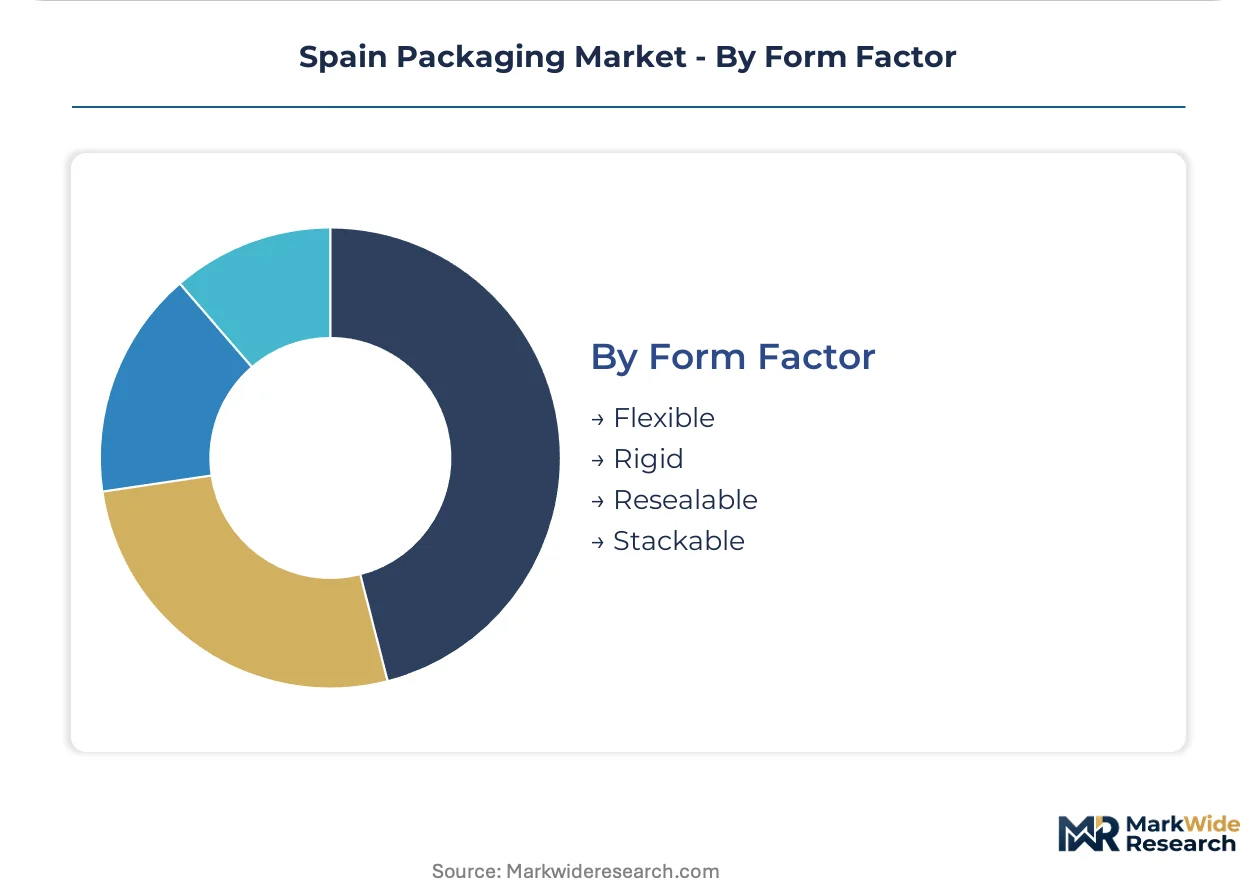
Form Factor:
Structural design capabilities determine converter access to retail consolidation trends, with automated distribution centers favoring standardized handling geometries.
- Flexible:Films and pouches enable source reduction through downgauging while requiring mono-material construction for Spain's extended producer responsibility incentives.
- Rigid:Bottles, jars, and thermoformed trays provide stack stability for automated warehouse systems. Mercadona's specification consolidation targets this format category.
- Resealable:Zipper pouches and lidded containers extend shelf life for convenience-oriented food segments with zipper application equipment driving converter capital requirements.
- Stackable:Modular case dimensions optimize pallet cube utilization for export logistics through Barcelona and Valencia ports.
Flexible formats gain share fastest through resin cost savings; rigid structures defend position through handling automation compatibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalonia's industrial corridor around Barcelona anchors packaging demand through port access and multinational consumer goods headquarters concentration.
Catalonia
Barcelona's logistics density drives corrugated containerboard procurement for grocery distribution networks. The EU Packaging and Packaging Waste Regulation enforces recyclability targets that favor integrated mills with captive OCC streams. Saica's Barcelona facilities supply national brands facing compressed design timelines from regulatory mandates.
Madrid
The capital region concentrates pharmaceutical and cosmetics packaging demand through blister pack and premium glass requirements. EFSA food-contact compliance certification creates laboratory queue bottlenecks for novel biobased coatings. Madrid's mid-tier converters struggle with legacy ERP integration against customer-mandated supply chain visibility platforms.
Andalusia
Jaén and Seville olive oil exporters underutilize smart tracking labels for high-value agricultural shipments. Spain's extended producer responsibility scheme rewards design-for-recycling submissions with reduced compliance fees. Citrus packers in the region could capture insurance premium reductions through RFID-enabled tertiary packaging adoption.
Valencia
Flexible plastic converters distribute across this autonomous community to serve snack and frozen food applications. Municipal collection systems yield contaminated PET streams that constrain EFSA-compliant food-grade recycled content availability. Valencia's port infrastructure supports resin import logistics for metallocene polyethylene downgauging investments.
Basque Country
Industrial machinery and automotive component packaging demand concentrates around Bilbao's manufacturing base. Anti-static corrugated and molded pulp formats protect high-value electronics through Iberian distribution centers. The region's converter base faces cloud migration costs consuming 15-20% of annual IT budgets for supply chain platform compatibility.
Spain Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent specialty formats through technology licensing partnerships. The market structure consolidates around integrated paper mills and continental-scale containerboard operators, with regional independents facing margin compression from buyer concentration. Three archetypes dominate: backward-integrated recyclers with captive fiber streams, scale-driven multinational converters, and premium-tier specialists in compliance-intensive segments. Competitive moves center on M&A for geographic coverage and strategic partnerships for recycled-content verification capabilities.
Within the integrated recycler archetype, Saica exemplifies cost-position anchoring through captive OCC streams. Smurfit WestRock occupies a position representing continental-scale containerboard competition. Vidrala sits within the premium-tier specialist category for EFSA-migration-certified glass supply to wine exporters. These three anchors illustrate how substrate specialization and geographic proximity to Catalonia's demand concentration determine competitive positioning under tightening EU Green Deal carbon-border documentation requirements.
| Leading Market Players |
|---|
| International Paper |
| Saica |
| Smurfit WestRock |
| Coveris Holdings |
| Crown Holdings |
| Mondi |
| Vidrala |
| Quadpack Industries |
| Amcor |
| Others |
Value Network & Pricing Analysis
OCC fiber costs flow from Chinese import policy shifts through Spanish integrated mills to corrugated pricing tiers serving Catalonia's grocery distribution networks. Buyers face compressed margins when global fiber arbitrage spikes, while premium glass bottle formats sustain pricing power through EFSA migration certification scarcity.
Pricing Analysis
Input-cost pass-through from recovered paper volatility anchors corrugated containerboard pricing, with Saica's captive OCC streams buffering margin compression against spot-market exposure. Three-tier pricing structure across premium EFSA-certified, standard food-grade, and economy industrial grades reflects certification investment and volume scale. Pricing pressure stems from buyer concentration among Mercadona and Carrefour Spain national accounts. Regional independent converters show highest price sensitivity due to fragmented MES systems and cloud migration cost burdens.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Barcelona-based multinational consumer goods headquarters, while distributor networks serve mid-tier Andalusian olive oil exporters. Geographic supply concentration centers on Catalonia's integrated paper mills, Valencia's flexible film converters, and La Rioja's glass furnace operations. Raw material dependencies include OCC fiber streams, metallocene polyethylene resin imports, and soda-lime silica batch materials. Supply chain risk concentrates in single-source vulnerability for EFSA-compliant food-grade recycled content. Distribution runs through Barcelona and Valencia port infrastructure for export-oriented wine and olive oil shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in compliance-premium capture and resin cost reduction through metallocene downgauging investments. The EU Packaging and Packaging Waste Regulation's recycled-content mandates reward early verification adopters with multi-year fee advantages.
For Market Incumbents: To counter buyer concentration pressure from Mercadona and Carrefour Spain specification consolidation, anchor position through backward integration into captive OCC recycling streams and certification investment for EFSA food-contact compliance. Cloud migration of legacy ERP systems preserves customer-mandated supply chain visibility platform access.
For New Entrants and Emerging Players: EU Green Deal carbon-border adjustments in Spain open a window for Scope 3 verification service providers and mono-material flexible format converters. Andalusian agricultural packaging shows lowest penetration for RFID-enabled tertiary tracking labels. Go-to-market through olive oil exporter insurance premium reduction value propositions.
For Investors and Strategic Acquirers: Consolidation pressure builds where municipal sorting infrastructure gaps constrain EFSA-compliant food-grade recycled content availability. Long-term viability favors converters with integrated recycling streams and structural design capabilities for shelf-ready formats. Watch migration testing laboratory queue lengths as inflection indicator for novel biobased coating launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Recycling | Saica's captive fiber streams anchor cost positions against global price volatility. |
| EFSA Food-Contact Certification Investment | Queue delays of 8-14 months create scarcity premiums for approved coating suppliers. |
| Metallocene Polyethylene Downgauging | Thinner snack wrappers capture resin savings without shelf-life sacrifice. |
| RFID-Enabled Tertiary Packaging Launch | Andalusian olive oil exporters reduce insurance premiums through traceability audits. |
| Cloud ERP Migration for Visibility Platforms | Mercadona and Carrefour mandate supply chain transparency from converter suppliers. |
Research Methodology
Coverage spans Catalonia, Madrid, Andalusia, Valencia, and Basque Country autonomous communities, with primary inputs from each. Converter operations directors, procurement leads at Mercadona and Carrefour Spain, EFSA compliance laboratory managers, olive oil exporter logistics heads, and flexible film extrusion equipment suppliers provided field perspectives. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, Spanish packaging waste management scheme reports, EFSA migration limit documentation, and customs records for OCC fiber trade flows. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Rate-of-change decomposition separated volume growth from price-mix effects across the analysis window. Segmentation dimensions modeled include material type, product format, end-use industry, and form factor, with regional regulatory cluster as an additional packaging-specific dimension. CAGRs derived from regression analysis of historical demand patterns against EU Green Deal implementation timelines and carbon-border adjustment phase-in schedules. Forecast inputs incorporated municipal sorting infrastructure investment pipelines and laboratory certification capacity expansion plans.
Revisions become necessary when Chinese OCC import policy shifts, EFSA migration testing queue extensions, or cloud platform mandate acceleration materialize beyond base-case assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and recycled-content verification protocol adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Middle East and Africa Pharmaceutical Glass Packaging Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Glass Veil Market
Glass Packaging
North America Amber Glass Packaging Market
Glass Packaging
France Container Glass Market
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Japan Container Glass Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
Benelux Container Glass Market