
 Europe Glass Packaging Market | 2026-2036
Europe Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Glass Packaging Market Analysis
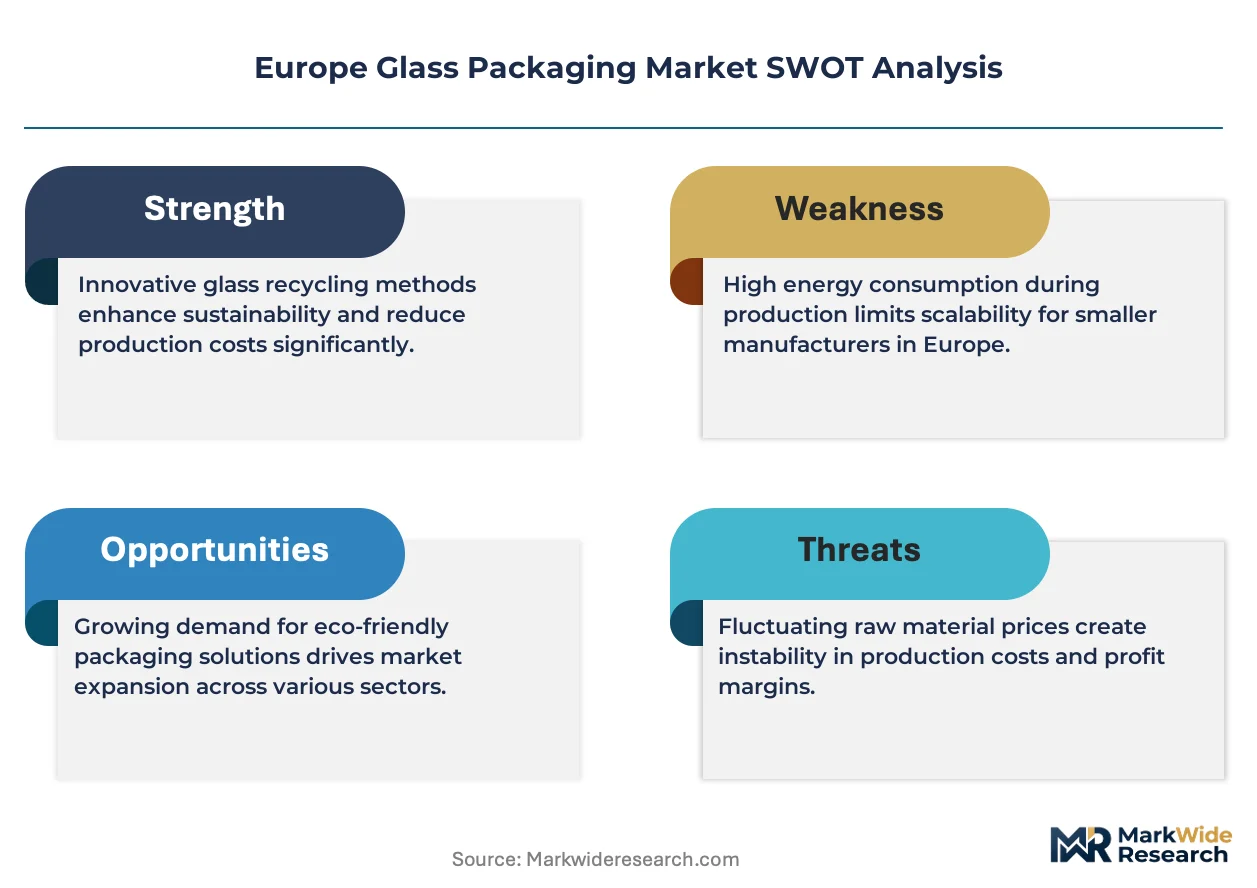
Lightweighting technology is reconfiguring how hollow glass articles achieve strength-to-weight ratios below 280 grams for standard wine bottles. Gerresheimer AG leverages pharmaceutical-grade borosilicate expertise to dominate parenteral and cosmetic vial segments across Central Europe. Stoelzle Oberglas anchors decorative and high-end spirits packaging through specialized mold capabilities and Austrian manufacturing heritage. Verallia S.A. competes on furnace scale, operating multiple oxy-fuel installations that reduce particulate emissions below conventional regenerative benchmarks.
Europe glass packaging denotes rigid containers formed from soda-lime silica batches melted at 1,500–1,600°C, with optional boron oxide additions for thermal shock resistance in pharmaceutical applications; these vessels provide inert, impermeable barriers for oxygen-sensitive and reactive contents. Bottles occupy the dominant value position across beverage and spirits applications, where premium embossing and punt depth drive margin stratification. Jars sustain growth in organic food segments, particularly across German and Nordic retail channels where deposit-return compatibility matters. Pharmaceutical vials and ampoules within the containers category command the highest unit margins, with SGD Pharma and Gerresheimer controlling most European conversion capacity for Type I borosilicate.
The EU Green Deal's packaging and packaging waste regulation revision tightens recycled content mandates, while REACH and ECHA scrutiny on heavy metal stabilizers shapes colorant formulation choices across member states. EMA guidelines on extractables and leachables further constrain pharmaceutical glass composition, favoring established converters with documented DMF histories. Stakeholders must monitor how the CSRD's scope 3 disclosure rules alter brand-owner sourcing calculus for virgin versus cullet-based feedstock.
Market Dynamics
The EU Green Deal's recycled content mandates are compressing virgin cullet ratios across converter furnaces, forcing batch formulation recalibration and supplier qualification overhauls throughout the value chain.
Growth Catalysts
- EU Packaging Waste Regulation:Mandatory recycled glass thresholds in beverage containers pull converters toward cullet-intensive batch designs. Member state enforcement timelines accelerate furnace upgrade cycles.
- Champagne-Ardenne cluster expansion:Bottling capacity additions in France's sparkling wine belt outpace regional hollow glass supply, creating procurement urgency among maisons de champagne.
- Oxy-fuel combustion:Furnace technology retrofits cut nitrogen oxide emissions below conventional regenerative benchmarks, aligning converter operations with CSRD disclosure requirements.
Market Restraints
- Natural gas price volatility:Melting energy constitutes 35-40% of production cost structure at European soda-lime furnaces, exposing margins to TTF hub fluctuations.
- Cullet supply concentration:Quality-sorted recycled glass availability clusters in Germany and Benelux collection systems, creating feedstock access disparities for Southern European converters.
- Aluminum bottle substitution:Lightweight metal formats capture share in mass-market beer and RTD spirits where shelf differentiation matters less than logistics cost.
Strategic Opportunities
- Nordic deposit-return expansion:Sweden and Finland are extending container deposit schemes to wine and spirits bottles, creating closed-loop cullet streams with 95%+ return rates.
- Pharmaceutical extractables testing:EMA guidelines on leachable profiling favor converters with documented DMF histories for Type I borosilicate vial supply.
- Lightweighting-embossing convergence:Thin-wall bottle designs with high-definition mold detailing address both carbon footprint targets and premium brand positioning requirements.
Industry Challenges
- Electrical furnace engineering talent:Oxy-fuel and hybrid electric melting installations require specialized refractory and combustion expertise scarce across Central European technical institutes.
- CSRD scope 3 data architecture:Brand-owner disclosure rules demand granular cullet provenance tracking from municipal collection through batch melting, forcing ERP system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Glass Packaging Market |
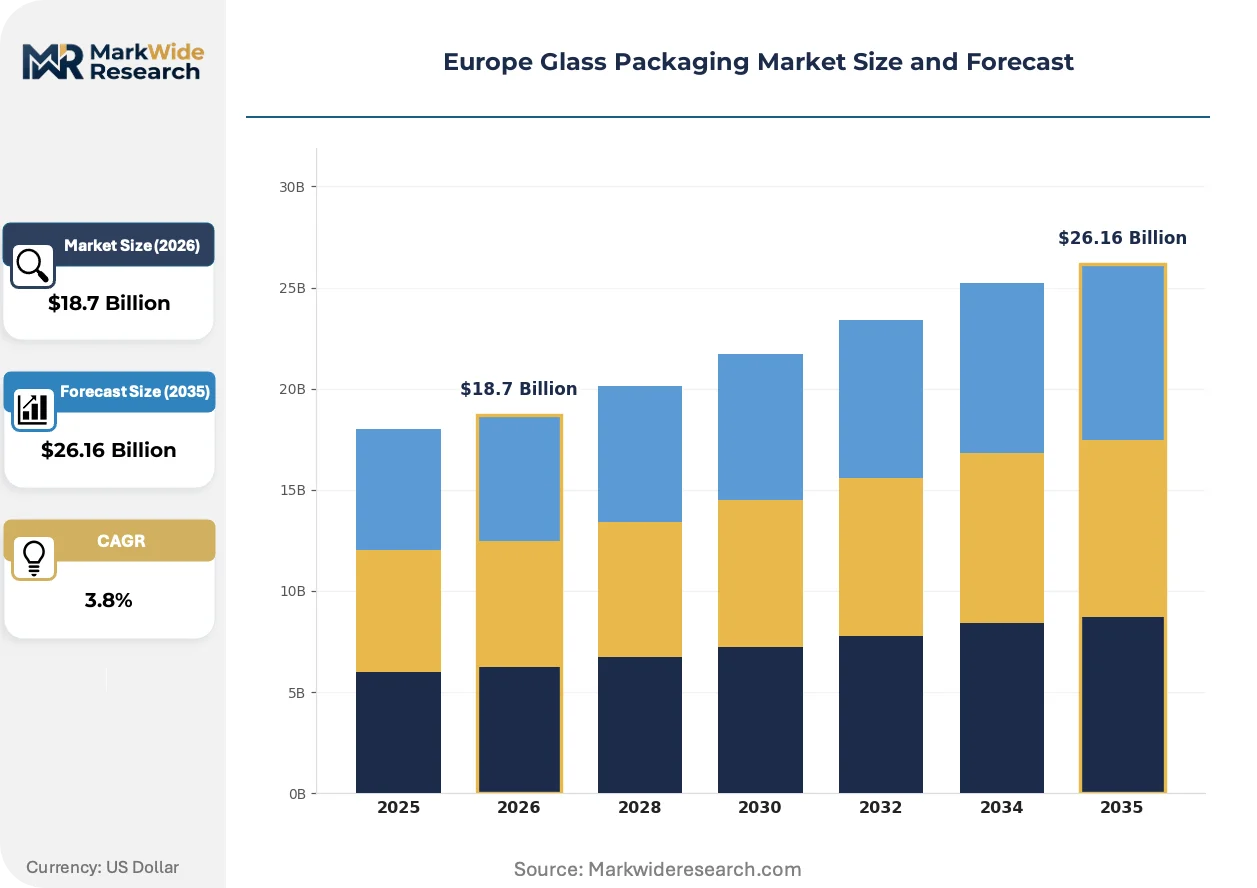
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Containers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Capacity: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Gerresheimer AG, Stoelzle Oberglas, Verallia S.A., SGD Pharma, Vetropack Group, O-I Glass, Vidrala, Berlin Packaging, Ardagh Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Glass Packaging Market Emerging Trajectories
Digital thread technologies are penetrating hollow glass production lines, linking mold design, furnace telemetry, and quality inspection into continuous feedback loops that compress defect detection latency from hours to seconds.
Machine vision inspection is digitizing surface defect classification across high-speed IS machine lines. Champagne houses and premium spirits bottlers in France are adopting 100% camera-based verification for embossing fidelity and wall thickness uniformity. This capability is digitizing quality assurance labor pools while enabling real-time mold maintenance scheduling that extends campaign durations.
REACH Annex XVII restrictions on cadmium and lead stabilizers in glass colorants are forcing reformulation of amber and UV-absorbing pharmaceutical vials. ECHA substance evaluation timelines are compressing R&D cycles for alternative sulfur and carbon-based coloration systems. Italian and German converters with in-house colorant laboratories are securing first-mover qualification status with EMA-inspected drug packaging buyers.
Brand-owner sustainability scorecards are restructuring supplier selection criteria across European beverage multinationals. Procurement teams in Germany and the Netherlands now weight verified cullet percentage above unit price in annual tender evaluations. This behavioral shift concentrates volume with converters operating dedicated post-consumer glass beneficiation plants rather than merchant cullet merchants.
Europe Glass Packaging Market Segmentation
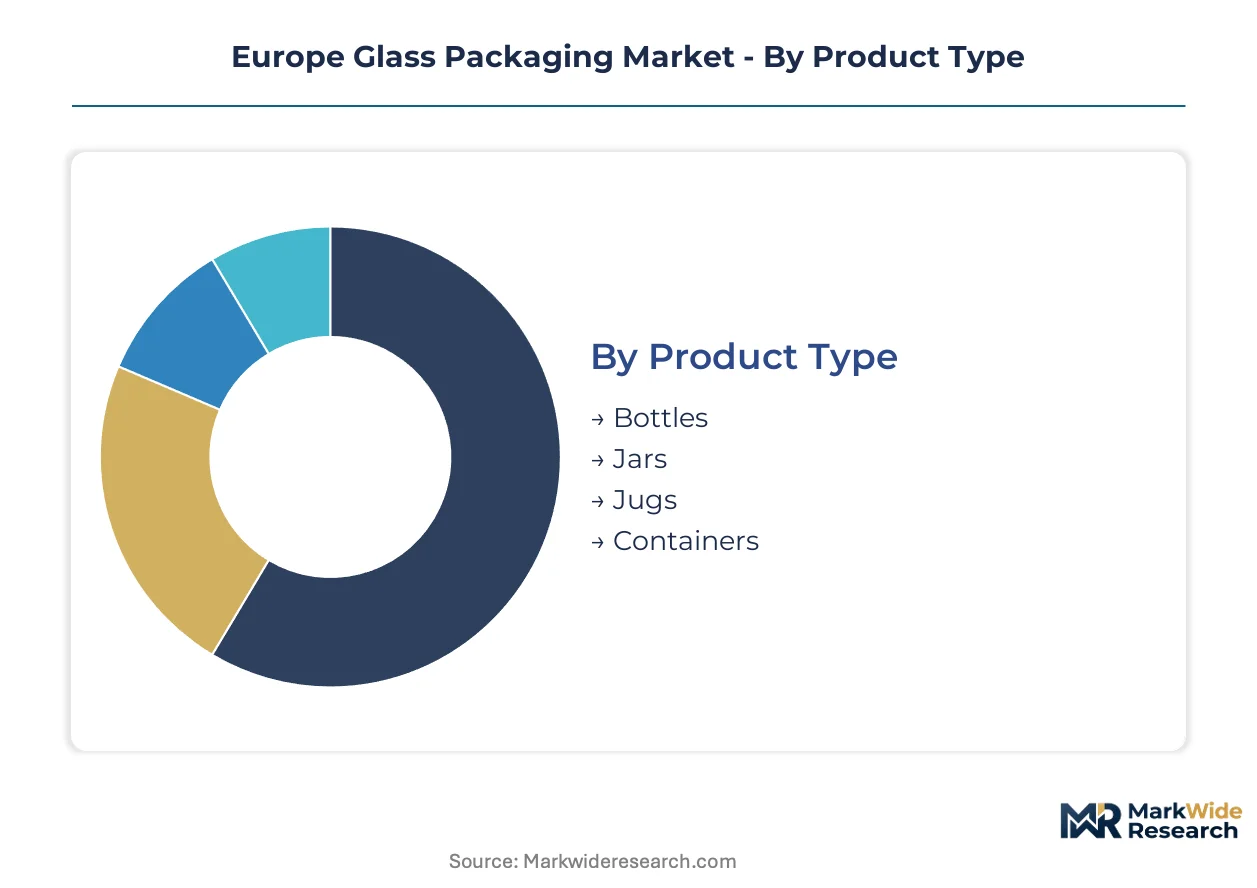
Glass packaging segmentation across Europe reflects divergent technical requirements between premium beverage branding and pharmaceutical barrier performance. Converter capacity allocation follows these fault lines, with furnace campaigns optimized for either decorative embossing or chemical inertness.
Product Type:
Mature formats dominate volume positions while emerging configurations capture sustainability-driven specification shifts.
- Bottles:Hollow glass vessels with standard finish specifications (BVS, GPI, or proprietary threads) dominate beverage and spirits applications. Champagne houses in France's Marne department and prosecco bottlers in Italy's Veneto region drive procurement for heavyweight punt-bottom designs with deep embossing.
- Jars:Wide-mouth containers with lug or continuous thread closures preserve organics and spreads across German and Nordic retail channels. Deposit-return compatibility in Sweden and Finland creates closed-loop cullet streams that favor jar format standardization.
- Jugs:Large-format handled containers serve bulk condiment and institutional food service segments with reduced surface-area-to-volume ratios for transport efficiency.
- Containers:Pharmaceutical vials and ampoules fabricated from Type I borosilicate or Type III soda-lime glass command premium unit margins through EMA extractables documentation requirements.
Bottles retain volume leadership; containers hold the steepest expansion curve.
End User:
Application-specific barrier requirements segment converter qualification pathways across regulated and non-regulated supply chains.
- Food & Beverage:Oxygen impermeability and UV protection specifications vary by product shelf-life requirements. Wine and spirits producers emphasize mold differentiation and lightweighting ratios.
- Pharmaceuticals:Parenteral packaging demands hydrolytic resistance per USP <660> and EP 3.2.1 classifications. EMA guidelines on leachable profiling favor converters with documented DMF histories for Type I borosilicate supply.
- Cosmetics:Premium fragrance and skincare brands specify heavy-wall bottles with metallized or lacquered surface treatments. Decorative capabilities anchor supplier selection above unit cost.
- Household:Standard soda-lime formats for cleaning agents and chemical storage prioritize cost efficiency over aesthetic differentiation.
Food & Beverage commands absolute volume; Pharmaceuticals is climbing the fastest on margin expansion.
Capacity:
Volume-to-weight economics and handling automation requirements stratify filling line compatibility across converter product ranges.
- Small:Pharmaceutical ampoules and cosmetic minis below 50ml require precision forming on dedicated IS machine sections with narrow neck-ring tooling.
- Medium:Standard wine bottles (750ml) and food jars (250-500ml) balance mold complexity with high-speed production economics across multi-gob furnace operations.
- Large:Spirits magnums and institutional food containers demand reinforced heel designs and specialized annealing lehr configurations.
- Extra Large:Bulk beverage and display formats exceed 3 liters, requiring custom mold engineering and reduced production speeds that compress margin structures.
Medium capacity retains volume leadership; Small holds the steepest expansion curve.
Distribution Channel:
Supply chain configuration determines order minimums, lead time flexibility, and technical service intensity across customer relationships.
- Online:E-commerce platforms for specialty and artisanal producers require fragmented SKU management and flexible minimum order quantities that challenge furnace campaign economics.
- Retail:Supermarket and hypermarket private label programs demand scale, consistent color matching, and rapid replenishment through regional distribution centers.
- Wholesale:Beverage distributors and co-packers aggregate volume across multiple brand owners, consolidating procurement power and standardizing specifications.
- Direct Sales:Champagne maisons and pharmaceutical multinationals contract directly with converters for dedicated furnace capacity and custom mold development.
Wholesale retains volume leadership; Direct Sales is gaining share fastest on premium contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium beverage brand-owners and pharmaceutical multinationals concentrate procurement power across Western European manufacturing clusters. Converter capacity allocation tracks these buyer footprints, with furnace investments clustering near Champagne-Ardenne, Emilia-Romagna, and the Rhine-Ruhr corridor.
Germany
Organic food retailers and deposit-return system operators drive jar format standardization across German retail channels. The country's national packaging regulator enforces strict recycled content verification under EU Green Deal implementation timelines. Converter operations concentrate in North Rhine-Westphalia, where cullet beneficiation plants supply furnace feedstock to Rhineland glassworks.
France
Champagne maisons and premium spirits bottlers sustain demand for heavyweight punt-bottom designs with deep embossing capabilities. ANSM pharmaceutical guidelines align with EMA extractables requirements for parenteral packaging qualification. The Marne department and broader Champagne-Ardenne cluster host dedicated furnace capacity serving sparkling wine houses with custom mold development programs.
Italy
Prosecco bottlers in Veneto and organic food producers across Emilia-Romagna pull container supply toward lightweighting-compatible formats. ECHA scrutiny on heavy metal stabilizers shapes amber glass colorant reformulation for pharmaceutical applications. Converter capacity expansion in the Emilia-Romagna wine belt outpaces regional hollow glass supply growth, tightening procurement timelines.
Spain
Mass-market beer producers and olive oil packagers prioritize cost efficiency in standard soda-lime formats for export-oriented production. The country's national environmental ministry enforces packaging waste reduction targets aligned with EU circular economy action plans. Catalonia and Valencia host container glass furnaces serving Mediterranean beverage distribution networks with regional distribution center proximity.
United Kingdom
Craft spirits distilleries and premium cosmetics brands specify heavy-wall bottles with metallized surface treatments for shelf differentiation. The UK's national standards body maintains alignment with REACH colorant restrictions post-regulatory transition. Converter operations in Yorkshire and the Midlands serve beverage co-packers with flexible campaign scheduling for fragmented SKU portfolios.
Europe Glass Packaging Market Vendor Landscape
Channel-controlling players compete with product-specialist players across furnace scale and mold capability vectors. The market structure tiers between multi-furnace operators with oxy-fuel installations and single-site decorators with specialized embossing expertise. Three archetypes dominate: scale-driven cullet processors, premium-spirits mold specialists, and pharmaceutical-grade borosilicate converters. Competitive moves concentrate on furnace technology retrofits and dedicated capacity contracting with brand-owner sustainability scorecards.
Among Germany-based fabricators, Gerresheimer AG represents pharmaceutical-grade borosilicate specialization through documented DMF histories. Stoelzle Oberglas and Verallia S.A. occupy positions at opposite ends of the capability spectrum—Austrian decorative heritage versus French furnace scale with oxy-fuel emissions profiles. These three exemplify how converter archetypes align with distinct buyer procurement criteria across beverage and pharmaceutical end-uses.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Stoelzle Oberglas |
| Verallia S.A. |
| SGD Pharma |
| Vetropack Group |
| O-I Glass |
| Vidrala |
| Berlin Packaging |
| Ardagh Group |
| Others |
Supply Flow & Price Mechanics
Rhine-Ruhr corridor freight rates for cullet-heavy inbound shipments compress margin structures at German hollow glassworks while simultaneously enabling price premiums for converters with integrated beneficiation assets. This logistics-cost asymmetry concentrates procurement power with Verallia and Gerresheimer operations adjacent to North Rhine-Westphalia collection systems, forcing Southern European competitors to absorb transport differentials or surrender volume in annual tender negotiations.
Pricing Analysis
Cost-plus contracts indexed to TTF natural gas benchmarks dominate furnace supply agreements between converters and beverage multinationals. Price differentiation rests on verified post-consumer cullet percentage and EMA DMF qualification status for pharmaceutical grades. Pricing pressure intensifies in mass-market beer segments where aluminum substitution threatens volume commitments. Private-label retailers exhibit highest price sensitivity; champagne maisons demonstrate lowest sensitivity due to mold-customization requirements.
Supply Chain Analysis
Converter capacity concentrates in Germany, France, and Italy, with Vetropack and Verallia operating multiple furnace installations across these markets. Batch formulation draws from soda-lime silica sand deposits in Germany and Benelux, boron oxide for pharmaceutical grades, and quality-sorted cullet from Nordic deposit-return systems. Single-source vulnerability exists for Type I borosilicate pharmaceutical vials where SGD Pharma and Gerresheimer control European conversion. Distribution runs through beverage co-packers and pharmaceutical contract manufacturers with regional distribution center proximity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story anchored in regulatory entrenchment. EMA extractables documentation requirements and EU Green Deal recycled content mandates create switching costs that cement incumbent positions.
For Market Incumbents: Build regulatory moats through accelerated DMF filing for Type I borosilicate expansions and captive cullet beneficiation investments in Germany. Aluminum bottle substitution in mass-market beer and electrical furnace engineering talent scarcity represent immediate threats. Capacity additions in Champagne-Ardenne and Emilia-Romagna clusters anchor volume defense against Southern European supply constraints. For New Entrants and Emerging Players: Build out lightweighting-embossing convergence capabilities for premium spirits bottlers in France and craft distilleries in the United Kingdom where mold differentiation commands price premiums. Nordic deposit-return expansion into wine and spirits segments offers the most penetrable white-space for closed-loop cullet sourcing. Direct sales contracting with sustainability-focused brand-owners bypasses wholesale consolidation barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parents with underoptimized glass packaging divisions lacking EMA qualification or oxy-fuel furnace retrofit progress. Long-term viability favors converters with documented pharmaceutical regulatory histories and integrated cullet processing rather than merchant feedstock dependence. Monitor CSRD scope 3 disclosure implementation timelines as inflection indicator for brand-owner sourcing calculus shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | Aligns converter emissions profiles with EU Green Deal benchmarks and CSRD disclosure requirements. |
| Captive Cullet Beneficiation | Secures quality-sorted recycled glass feedstock independent of Benelux collection system concentration. |
| Type I Borosilicate DMF Filing | Locks in pharmaceutical vial supply relationships through EMA extractables documentation barriers. |
| Lightweighting-Embossing Convergence | Addresses champagne house carbon targets while preserving premium mold differentiation capabilities. |
| Nordic Deposit-Return Integration | Captures 95%+ return rate cullet streams for closed-loop batch formulation in Swedish and Finnish markets. |
Methodological Framework
Initial hypotheses were tested against primary input from furnace operations managers, beverage procurement directors, pharmaceutical packaging engineers, and EMA regulatory consultants, then refined through secondary validation. Bottom-up triangulation incorporated trade data from Eurostat customs filings, EU ETS emissions disclosures, SEC 10-K filings for listed converters, and CSRD preparatory guidance documents. Top-down cross-checks applied macroeconomic indicators and EU packaging waste policy timelines.
Demand-supply balance modeling across the projection horizon segmented volume by product type, end-use application, capacity tier, and distribution channel, with additional stratification by furnace technology and cullet integration level. CAGRs were derived from regression analysis of historical production data against regulatory enforcement timelines and brand-owner sustainability procurement weightings. Forecast inputs included TTF natural gas price scenarios and aluminum substitution elasticity estimates for mass-market beverage segments.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian glass exporters or breakthrough electrical melting technologies would shift outcomes beyond modeled ranges. Quarterly review of EU Packaging Waste Regulation enforcement timelines, ECHA colorant restriction updates, and CSRD scope 3 disclosure implementation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
United Arab Emirates Glass Packaging Market
Glass Packaging
India Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Uzbekistan Container Glass Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Middle East and Africa Glass Packaging Market
Glass Packaging
Dominican Republic Container Glass Market
Glass Packaging
Cosmetic and Perfume Glass Packaging Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Slovakia Container Glass Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Saudi Arabia Glass Packaging Market