
 Main Battle Tank Market | 2026-2036
Main Battle Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Main Battle Tank Market Analysis
STANAG 4569 ballistic protection certification is bifurcating the competitive landscape into qualified incumbents and excluded aspirants. Krauss-Maffei Wegmann leverages its Leopard platform lineage to sustain German and export orders across NATO-aligned forces. Rheinmetall competes through vertical integration into turret systems and active protection technologies. Hyundai Rotem anchors Asia-Pacific positioning with the K2 Black Eagle and associated technology transfer agreements.
A main battle tank is a heavily armored, tracked combat vehicle mounting a large-caliber main gun in a rotating turret, typically weighing 40–70 tonnes and integrating composite or reactive armor arrays with digital fire-control systems. Its primary purpose is to deliver direct fire support, defeat armored threats, and seize contested terrain in combined-arms operations. Heavy tanks retain relevance in high-intensity peer-conflict scenarios where protection density outweighs mobility trade-offs, while diesel engine configurations dominate operational logistics due to fuel availability and thermal signature management. Military forces represent the core demand pool, with procurement cycles stretching across multi-year appropriations that insulate segment volume from short-term budget fluctuations.
The U.S. Department of Defense drives requirements through MIL-STD-810 environmental testing and NHTSA-equivalent safety protocols for transportability, while NATO STANAG frameworks harmonize ammunition and armor standards across allied fleets. Germany's KBA and BAAINBw enforce national military type certification that shapes Rheinmetall and Krauss-Maffei Wegmann product roadmaps. Stakeholders must monitor how EU defense procurement directives and national industrial base protections interact to determine accessible contract pools versus protected domestic competitions.
Market Dynamics
STANAG 4569 ballistic certification is decomposing the competitive landscape into qualified incumbents and excluded aspirants, forcing procurement decisions toward proven platforms with established NATO interoperability.
Growth Catalysts
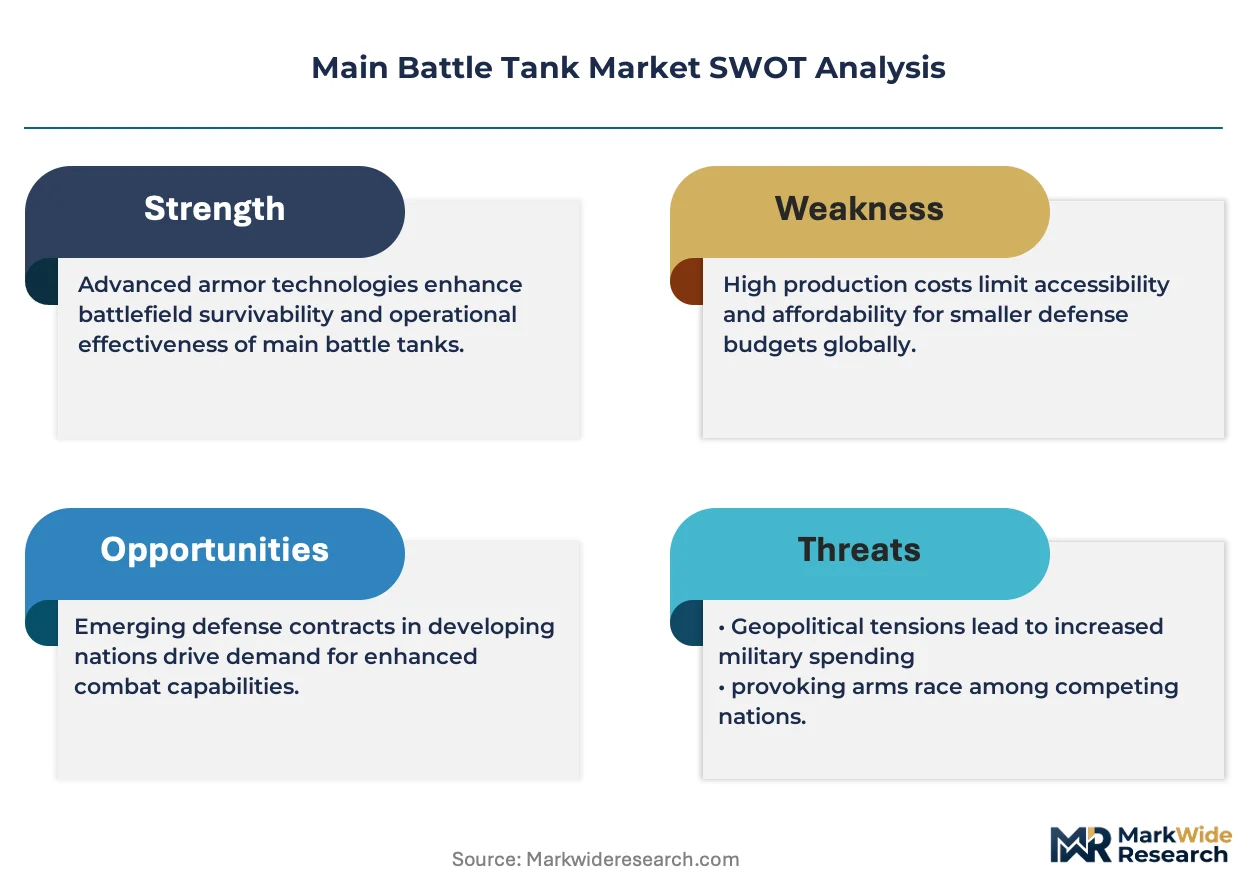
- Poland's Wilk Program:Warsaw's massive fleet replacement initiative is pulling orders for NATO-standard heavy armor across multiple allied vendors.
- REACH-compliant armor composites:European environmental frameworks are accelerating adoption of non-toxic ceramic matrix materials in hull protection systems.
- Active protection systems:Hard-kill and soft-kill defensive suites are reshaping survivability requirements in peer-conflict scenarios.
Market Restraints
- Specialized steel plate concentration:High-hardness rolled homogeneous armor production clusters in select European and Asian metallurgical centers.
- Powerpack thermal limitations:Gas turbine configurations face fuel consumption penalties that constrain operational range in extended deployments.
- Export control regimes:ITAR and national military end-use certification create multi-year approval timelines for cross-border transfers.
Strategic Opportunities
- Indigenous manufacturing partnerships:Technology transfer agreements in Central and Eastern European states are opening localized assembly pathways.
- Hybrid-electric propulsion convergence:Battery-diesel architectures promise thermal signature reduction alongside silent watch capabilities.
- EU defense procurement directives:PESCO framework incentives are creating preferential access for cross-border collaborative programs.
Industry Challenges
- Systems integration complexity:Digital fire-control networks must interoperate with legacy command infrastructure across multi-generation fleets.
- Specialized armor welding certification:Qualified technician pipelines for composite hull fabrication remain constrained in Western defense industrial bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Main Battle Tank Market |
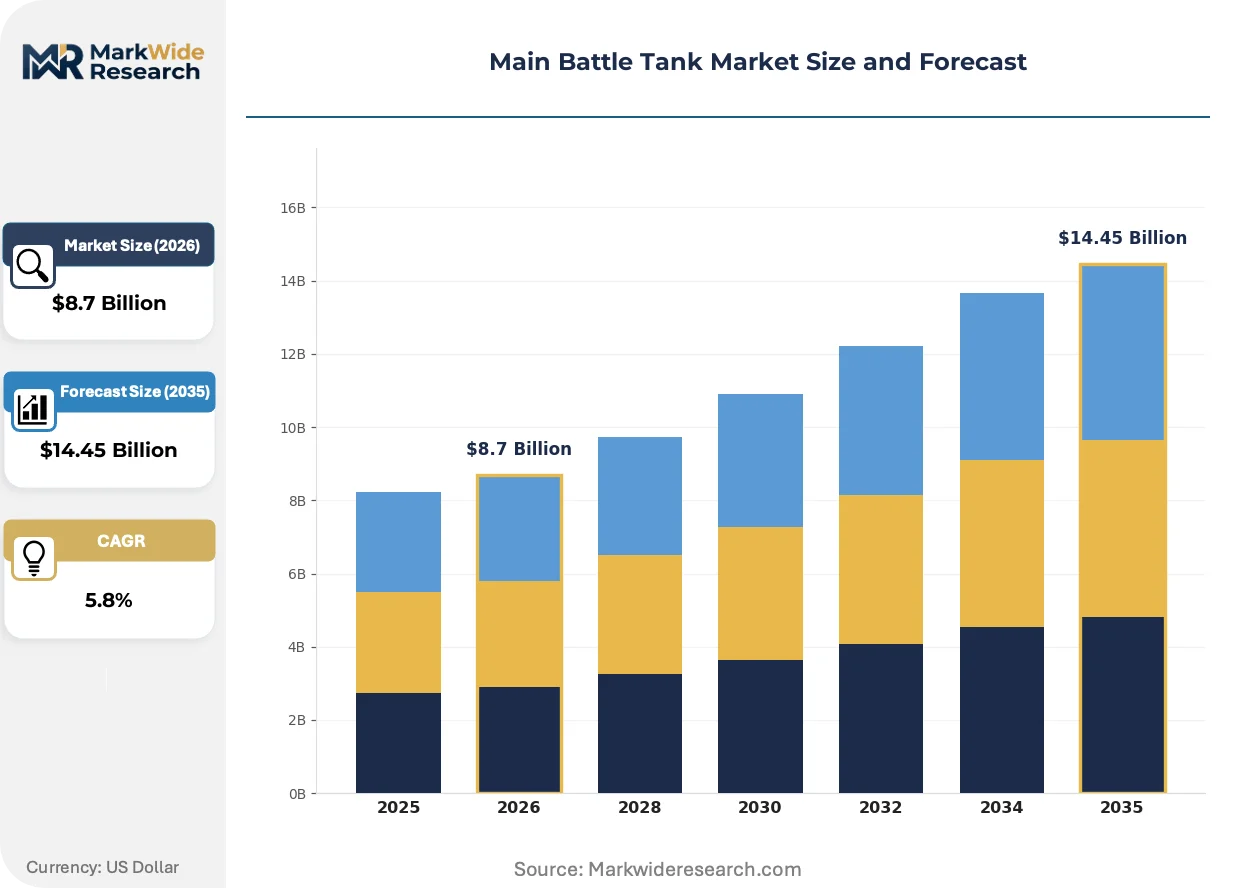
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Tanks, Medium Tanks, Heavy Tanks, Super Heavy Tanks Technology: Hybrid Propulsion, Turbine Engines, Diesel Engines, Electric Systems End User: Military Forces, Defense Contractors, Government Agencies, Private Security Firms Application: Combat Operations, Peacekeeping Missions, Training Exercises, Parades |
| Companies Covered | Hyundai Rotem Company, Uralvagonzavod, General Dynamics Land Systems, Israel Aerospace Industries, Krauss-Maffei Wegmann, KNDS, BAE Systems, Mitsubishi Heavy Industries, Rheinmetall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Main Battle Tank Market Emerging Trajectories
Autonomous turret architectures and artificial intelligence-assisted targeting are compressing crew requirements while elevating reaction speeds against saturation threats. These shifts are redrawing platform design priorities across NATO-aligned development programs.
Unmanned turret configurations are decomposing traditional three-person crew layouts into two-person or optionally-manned architectures. Rheinmetall and Krauss-Maffei Wegmann are fielding prototypes with reduced hull profiles and centralized situational awareness displays. This technology is decomposing the historical trade-off between protection density and internal volume allocation.
Germany's KBA and BAAINBw are tightening national military type certification timelines for active protection system integration, compressing development cycles for turret modernization kits. These requirements are forcing earlier subsystem validation in platform design phases. Polish and German procurement offices are now mandating STANAG-compliant interfaces as baseline evaluation criteria.
Life-cycle service contracting is replacing transactional spare-part purchasing among NATO defense ministries. Original equipment manufacturers are capturing decade-long sustainment commitments through availability-based agreements. This pattern concentrates most visibly in German and Polish fleet modernization frameworks, where total cost of ownership calculations now dominate source-selection evaluations.
Main Battle Tank Market Segmentation
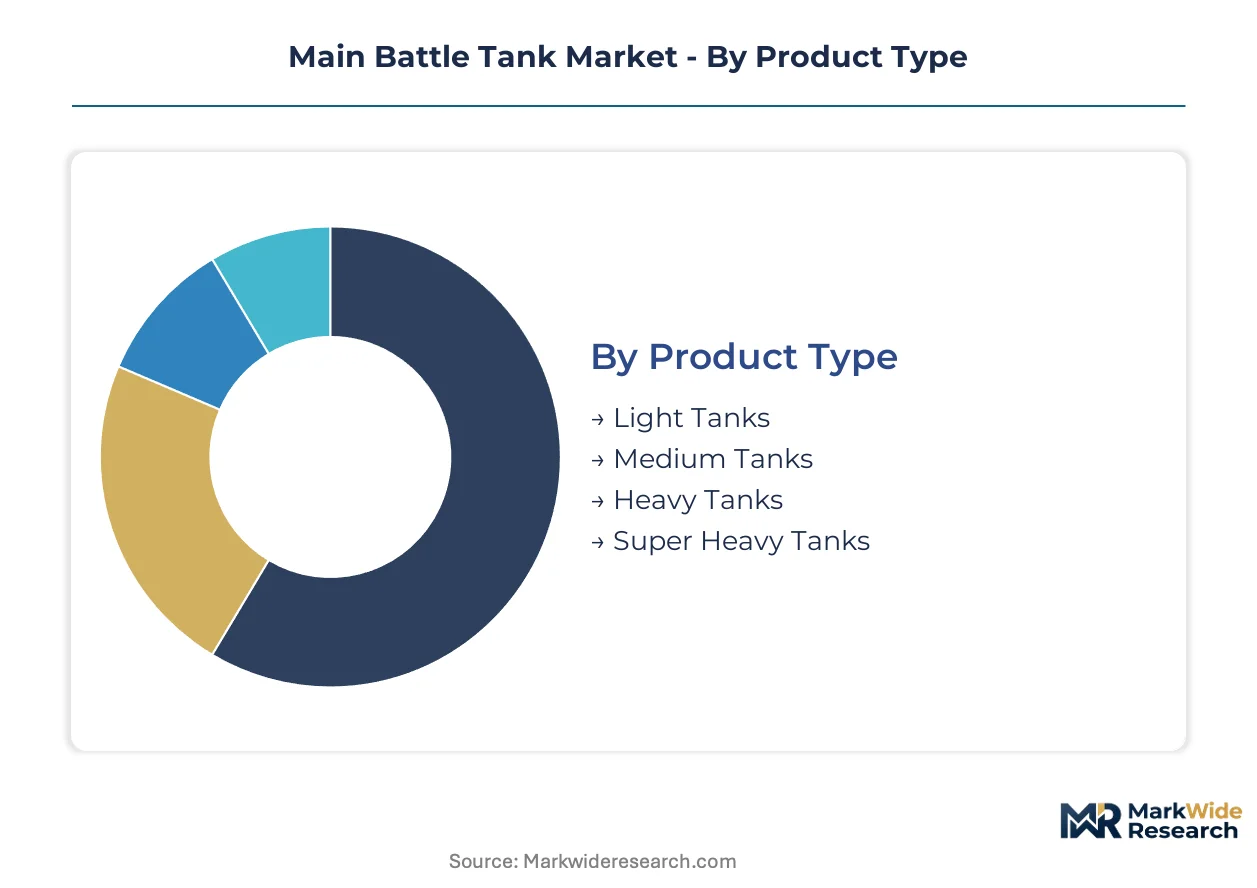
Segmentation in the main battle tank market reflects divergent operational doctrines, procurement budgets, and interoperability requirements across NATO and allied forces. Platform weight classes and propulsion architectures determine logistics compatibility, armor certification tiers, and strategic mobility profiles that shape contract awards.
Product Type:
Margin pools concentrate in heavy tank configurations where armor density and systems integration complexity sustain premium pricing across multi-year procurement cycles.
- Heavy Tanks:These platforms integrate composite and reactive armor arrays with 120mm or larger main gun systems, typically weighing 55–70 tonnes. Polish and German defense ministries are concentrating orders here under fleet modernization programs that prioritize STANAG 4569 ballistic certification and active protection system compatibility.
- Medium Tanks:Weighing 35–45 tonnes, these systems balance firepower and strategic deployability for expeditionary forces. South Korea's K2 Black Eagle and associated technology transfer agreements are driving demand concentration in Asia-Pacific partner nations seeking NATO-interoperable alternatives to legacy Soviet-era platforms.
- Light Tanks:Air-transportable platforms under 30 tonnes serve rapid reaction and airborne forces with reduced logistics footprints.
- Super Heavy Tanks:Experimental and historical categories exceeding 70 tonnes see limited procurement outside specialized engineering or museum restoration applications.
The dominant share belongs to Heavy Tanks, while Medium Tanks are closing the gap fastest.
Technology:
Volume leadership sits with mature propulsion architectures that defense ministries trust for operational availability and field repairability.
- Diesel Engines:Compression-ignition configurations dominate operational logistics due to fuel availability, thermal signature management, and established maintenance pipelines across NATO depots. Germany's KBA and BAAINBw certification requirements reinforce diesel's procurement advantage in European competitions.
- Turbine Engines:Gas turbine powerpacks deliver superior power-to-weight ratios and cold-start reliability in arctic conditions. The U.S. Department of Defense sustains demand through M1 Abrams fleet sustainment, though fuel consumption penalties constrain deployment range in extended theater operations.
- Hybrid Propulsion:Battery-diesel architectures promise silent watch capabilities and thermal signature reduction for reconnaissance and urban combat scenarios.
- Electric Systems:Fully electric propulsion remains developmental, constrained by energy density limitations and battlefield charging infrastructure gaps.
Diesel Engines retain procurement dominance, though Hybrid Propulsion is gaining share fastest among next-generation development programs.
End User:
Customer type determines contract structure, with availability-based service agreements replacing transactional purchasing among the largest accounts.
- Military Forces:National army procurement offices drive volume through multi-year appropriations insulated from short-term budget fluctuations. Life-cycle service contracting now dominates German and Polish fleet modernization frameworks, with original equipment manufacturers capturing decade-long sustainment commitments.
- Defense Contractors:Prime integrators and subsystem suppliers purchase platforms for technology evaluation, foreign military sales preparation, and demonstration leasing to prospective export customers.
- Government Agencies:Border security and internal defense ministries acquire reduced-capability configurations for territorial defense rather than combined-arms operations.
- Private Security Firms:Demilitarized or training-variant acquisitions support facility protection and contractor certification programs in conflict-adjacent jurisdictions.
Military Forces command the dominant procurement share, while Defense Contractors are expanding their platform holdings fastest through pre-positioning for third-country transfers.
Application:
Operational purpose shapes armor certification requirements and subsystem prioritization in platform specification.
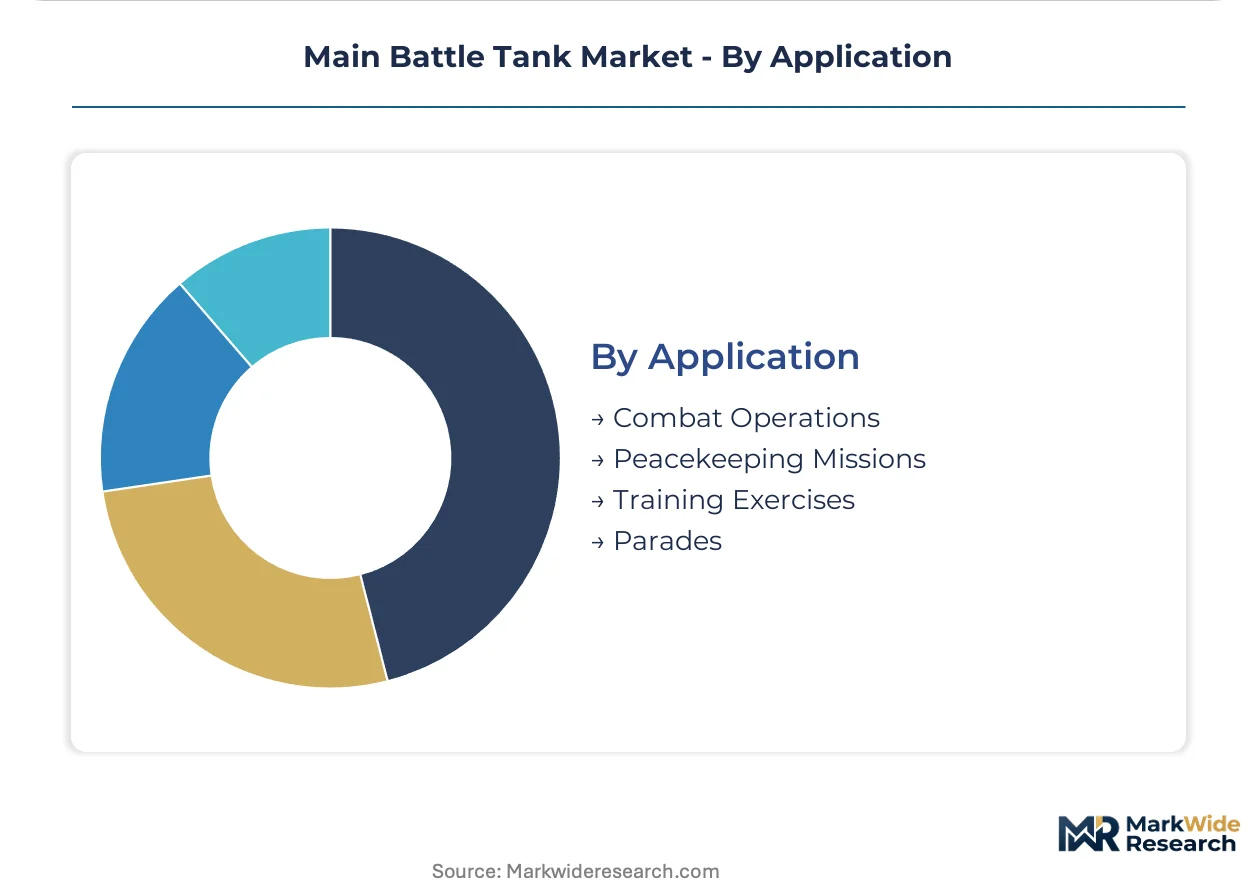
- Combat Operations:High-intensity peer-conflict scenarios demand maximum protection density, active protection systems, and digital fire-control networks interoperable with NATO command infrastructure. STANAG 4569 certification is mandatory for armor qualification in these procurement pools.
- Peacekeeping Missions:De-escalation-focused deployments prioritize situational awareness systems, non-lethal capability integration, and reduced collateral damage profiles in urban environments.
- Training Exercises:Simulator-linked platforms and instrumented range systems support crew certification and combined-arms coordination without ammunition expenditure.
- Parades:Ceremonial configurations emphasize aesthetic finish, historical accuracy for heritage units, and reduced maintenance requirements between infrequent deployments.
Combat Operations absorbs the dominant application share, while Peacekeeping Missions are climbing fastest as multinational stabilization commitments expand in Eastern European border regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NATO STANAG certification requirements are reshaping procurement patterns across allied defense ministries, with national industrial base protections creating divergent accessible contract pools. Fleet modernization timelines in Central and Eastern Europe are accelerating cross-border technology transfer negotiations. Environmental compliance frameworks in Western Europe are adding certification layers to armor composite specifications.
Poland
Warsaw's Wilk Program is pulling orders for NATO-standard heavy armor across multiple allied vendors, with defense spending commitments exceeding prior decade totals. The country's national military procurement office mandates STANAG 4569 ballistic protection certification as baseline evaluation criteria for all new platform acquisitions. Industrial partnerships in southwestern manufacturing corridors are opening localized assembly pathways for technology transfer agreements.
Germany
Krauss-Maffei Wegmann and Rheinmetall anchor sustained domestic and export orders through Leopard platform lineage and vertical integration into turret systems. KBA and BAAINBw enforce national military type certification that shapes product roadmaps and compresses development cycles for active protection system integration. Bavarian and Lower Saxon defense industrial clusters concentrate qualified technician pipelines for composite hull fabrication.
South Korea
Hyundai Rotem anchors Asia-Pacific positioning with the K2 Black Eagle platform and associated technology transfer agreements to partner nations. The country's national defense acquisition program administration aligns procurement with NATO-interoperable standards for export market access. Manufacturing concentration in Changwon and Sacheon supports scaled production for domestic fleet replacement and third-country deliveries.
United States
The Department of Defense drives requirements through MIL-STD-810 environmental testing and transportability protocols that shape platform design priorities. NHTSA-equivalent safety standards for road and rail movement create additional certification burdens for foreign system integration. Michigan and Ohio defense industrial corridors sustain M1 Abrams fleet sustainment through decade-long availability-based service agreements.
Israel
Israel Aerospace Industries competes through active protection technologies and unmanned turret architectures that reduce crew requirements. The country's national military certification authority mandates earlier subsystem validation in platform design phases for defensive suite integration. Tel Aviv-area engineering clusters concentrate artificial intelligence-assisted targeting development for export market positioning.
Main Battle Tank Market Vendor Landscape
Listed leaders compete with private specialists across certification-qualified platform categories, with public equity visibility providing capital access for multi-year development cycles. The vendor base organizes around NATO STANAG compliance tiers, with qualified incumbents capturing protected domestic competitions and excluded aspirants confined to non-aligned export markets. Three archetypes dominate: legacy platform stewards with upgrade roadmaps, subsystem integrators with turret and protection specialization, and technology transfer partners with localized assembly offerings. Competitive moves concentrate on strategic partnerships for indigenous manufacturing rights and portfolio diversification into life-cycle service contracting.
Within the legacy platform steward tier, Krauss-Maffei Wegmann and Rheinmetall exemplify European concentration around German engineering certification and NATO interoperability standards. Hyundai Rotem occupies a position bridging Asia-Pacific manufacturing scale with NATO-aligned export positioning. These three entities represent divergent geographic anchors for technology transfer negotiations in Central and Eastern European procurement competitions.
| Leading Market Players |
|---|
| Hyundai Rotem Company |
| Uralvagonzavod |
| General Dynamics Land Systems |
| Israel Aerospace Industries |
| Krauss-Maffei Wegmann |
| KNDS |
| BAE Systems |
| Mitsubishi Heavy Industries |
| Rheinmetall |
| Others |
Supply Flow & Price Mechanics
REACH-compliant ceramic matrix composites displacing legacy armor materials in European hull fabrication are simultaneously shifting procurement geography toward certified foundries in Germany and Poland while compressing margin structures for non-compliant suppliers locked out of NATO defense competitions.
Pricing Analysis
STANAG 4569 ballistic protection certification creates the primary spread between premium platform tiers and excluded alternatives. Three-tier pricing structure across STANAG-qualified, nationally certified, and non-aligned configurations governs contract awards. Cost compression in the non-certified tier is intensifying because export control delays strand inventory. Defense contractors demonstrate the highest price sensitivity due to thin margins on foreign military sales preparation, while national military procurement offices absorb premiums for lifecycle service bundling.
Supply Chain Analysis
Strait of Malacca transit risk for tungsten and rare earth shipments from China underwrites strategic stockpiling requirements across NATO armor programs. High-hardness rolled homogeneous armor production draws from Germany, Sweden, and Japan. Supply chain risk centers on single-source vulnerability in gas turbine powerpack castings from U.S. and Ukrainian facilities. Distribution runs through government-to-government foreign military sales channels with multi-year approval timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active protection system integration is compressing platform development cycles and opening acquisition windows for subsystem specialists with proven NATO certification trajectories.
For Market Incumbents: Shield core fleet modernization relationships through captive supply of turret systems and accelerated BAAINBw certification timelines for defensive suite integration. Threat: Korean and Polish technology transfer partnerships eroding German engineering premiums. Lever: backward integration into ceramic matrix armor foundries in Lower Saxony. For New Entrants and Emerging Players: Life-cycle service contracting gaps in Central European aftermarket support present the most penetrable entry vector. Target availability-based sustainment agreements for legacy Soviet-era platform operators in Romania and Bulgaria seeking NATO interoperability pathways. Go-to-market: joint ventures with established certification holders for STANAG interface validation. For Investors and Strategic Acquirers: The market sits at a platform refresh phase that favors subsystem integrators with active protection specialization over pure-play hull fabricators. Long-term viability hinges on PESCO framework access and cross-border collaborative program eligibility. Acquisition archetype: turret and fire-control specialists with existing KBA certification pipelines. Signal to watch: Polish Wilk Program award volumes as indicator of technology transfer appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Active Protection System Integration | BAAINBw certification timelines compress development cycles for Rheinmetall and Krauss-Maffei Wegmann modernization kits. |
| Technology Transfer Partnership | Hyundai Rotem's K2 agreements with Poland establish localized assembly pathways into NATO procurement pools. |
| Life-Cycle Service Contracting | Availability-based agreements in German and Polish frameworks capture decade-long sustainment revenue streams. |
| Hybrid-Electric Propulsion Development | Battery-diesel architectures address thermal signature requirements for reconnaissance and urban combat scenarios. |
| Indigenous Manufacturing Localization | Central European industrial partnerships open protected domestic competitions to qualified foreign subsystem suppliers. |
Methodological Framework
Cross-validation between procurement officer interviews and defense ministry budget documentation anchors the qualitative findings. Primary fieldwork engaged platform engineering directors at Krauss-Maffei Wegmann and Rheinmetall, Polish military procurement officials, BAAINBw certification engineers, and Hyundai Rotem export strategy leads. Secondary sources included NATO STANAG technical specifications, EU defense procurement directive filings, national military type certification records, and customs data for armor-grade steel trade flows. Bottom-up platform delivery tallies and top-down defense appropriation analysis were triangulated against industrial production capacity estimates.
Sensitivity analysis across propulsion architecture adoption rates and active protection system penetration scenarios shaped the forecast framework. Segmentation dimensions modeled include platform weight class, engine configuration, end-user contract structure, and application mission profile. CAGRs were derived from fitted growth curves against historical procurement cycles and projected fleet replacement timelines. Industry-specific inputs encompassed STANAG 4569 certification adoption curves and PESCO collaborative program funding allocations across the analysis window.
Forecasts assume regulatory continuity in EU defense procurement directives and NATO technical standard harmonization; material policy shifts would require re-modeling. Specific risks include REACH environmental framework expansion constraining armor material options and export control regime tightening extending cross-border transfer timelines. Practitioners should keep alternative scenarios live as Polish and German procurement volume commitments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Iran Defense Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Military Trucks Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Military Amphibious Vehicle Market
Military Vehicles
Infantry Fighting Vehicle (IFV) Market
Military Vehicles
Japan Defense Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Indonesia Defense Market
Military Vehicles
Military Ground Robots Market
Military Vehicles
Colombia Defense Market
Military Vehicles
Russia Defense Market