
 Destroyers Market | 2026-2036
Destroyers Market Size, Share, and Industry Trends Forecast 2026-2036
Destroyers Market Analysis
Buyer concentration among national navies is recalibrating procurement patterns across the destroyer sector. Huntington Ingalls Industries leverages its Ingalls Shipbuilding division to dominate large-deck surface combatant construction for the US Navy. BAE Systems sustains its position through integrated electric propulsion and naval gun system specialization for the Royal Navy and export customers. Fincantieri competes in the medium-destroyer segment with Franco-Italian FREMM-derived platforms serving European and Middle Eastern fleets.
Destroyers are heavily armed, fast-maneuvering warships typically displacing 7,000–15,000 tonnes, engineered for anti-air, anti-surface, anti-submarine, and strike warfare through layered sensor and weapon architectures. Their primary purpose centers on fleet air defense and power projection within carrier strike groups or independent surface action groups. Multi-role and guided-missile type categories anchor current procurement volumes as navies prioritize platform flexibility over single-mission specialization. AEGIS and integrated combat system technology segments command premium positioning due to software-defined upgrade paths and interoperability mandates with allied fleet networks.
The US Navy's shipbuilding requirements flow through Congressional defense authorization frameworks and Navy shipbuilding plans that set annual procurement floors. European procurement aligns with EU Permanent Structured Cooperation defense initiatives and NATO capability targets for integrated air and missile defense. Japan's Maritime Self-Defense Force destroyer programs operate under METI industrial base guidelines and US-Japan alliance technology transfer protocols. Stakeholders must monitor how classified technology release policies and domestic content requirements reshape competitive access to allied fleet modernization cycles.
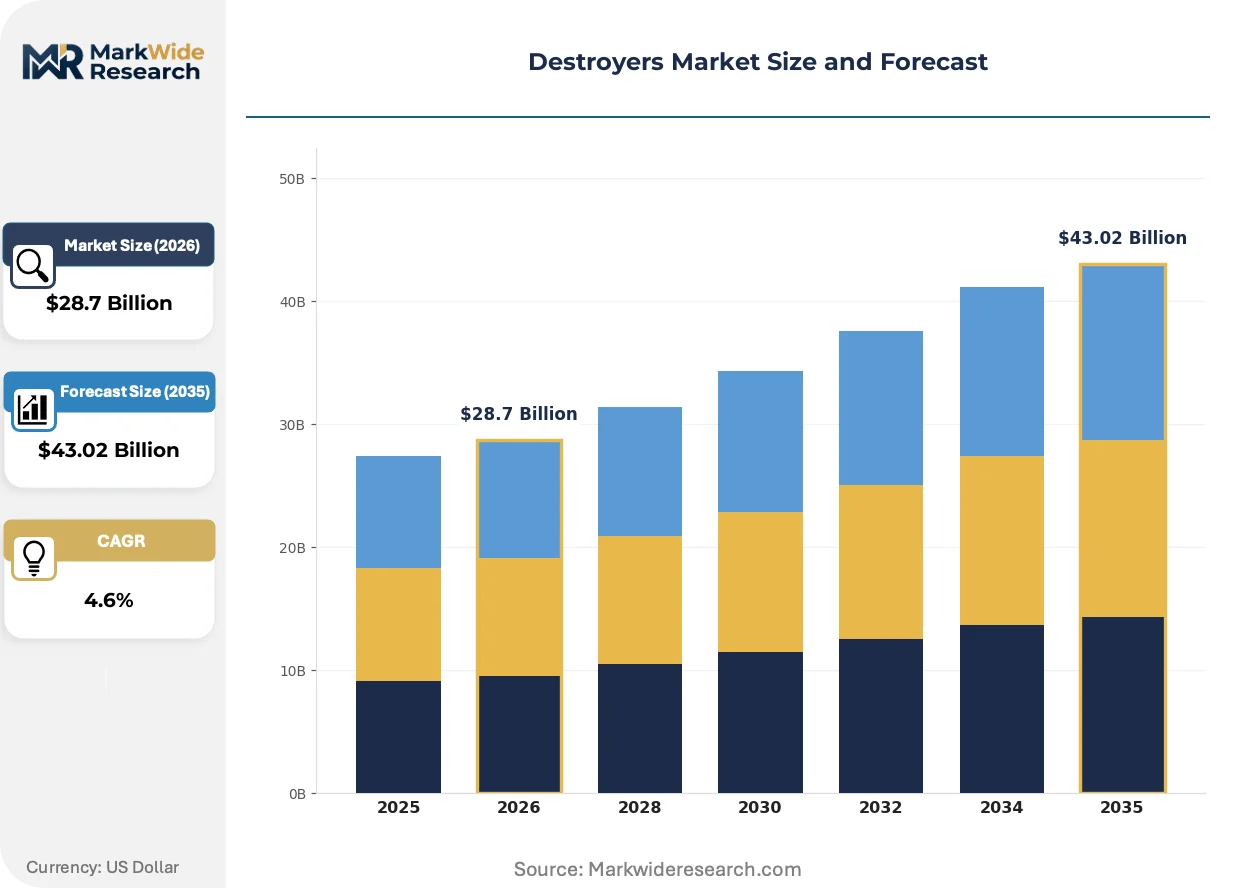
Market Dynamics
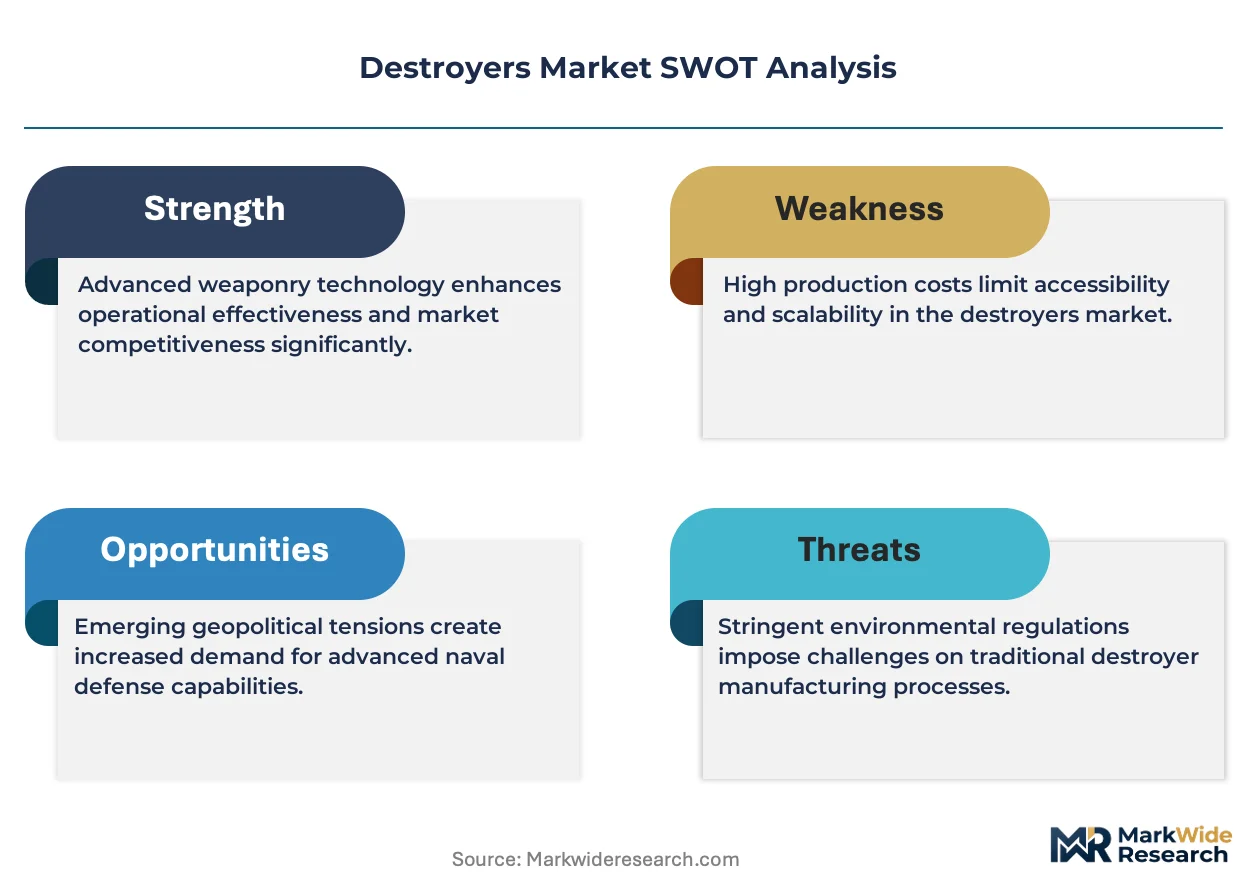
Naval modernization programs are compressing destroyer design cycles as NATO members and Asia-Pacific powers simultaneously pursue fleet recapitalization, creating procurement bottlenecks at specialized shipyards and forcing governments to accept extended delivery timelines for integrated combat systems.
Growth Catalysts
- US Navy Distributed Maritime Operations doctrine:This operational framework mandates additional large surface combatants to sustain dispersed fleet formations, directly expanding procurement authorizations within Congressional defense appropriations.
- EU Permanent Structured Cooperation (PESCO):European defense integration initiatives pool national procurement budgets for multi-role destroyer programs, enabling joint development of FREMM-derived platforms across Franco-Italian industrial partnerships.
- AEGIS-compatible indigenous construction:Japan's Maritime Self-Defense Force and South Korean shipbuilders are accelerating licensed production of integrated combat systems under US-Japan and US-Korea technology transfer protocols.
Market Restraints
- Specialized steel alloy supply concentration:High-tensile naval-grade steel production centers on a limited set of European and Japanese mills, exposing shipbuilders to input cost volatility and delivery uncertainty.
- Combat system integration complexity:Software-defined warfare architectures require sustained engineering talent pools that concentrate at prime contractors, constraining second-tier yard participation.
- Domestic content mandates:National industrial base preservation rules in the US, UK, and Japan restrict foreign subsystem sourcing, inflating unit costs and extending production timelines.
Strategic Opportunities
- Indigenous Middle Eastern programs:Saudi Arabia and the UAE are funding local shipyard capacity for medium-destroyer construction, creating export opportunities for European combat system integrators.
- Electrified propulsion convergence:Integrated full electric propulsion and energy storage integration enable directed-energy weapon hosting, opening new platform configuration categories.
- Australian continuous shipbuilding:The Hunter-class destroyer program under Australia's naval shipbuilding plan offers sustained production volume for combat system suppliers able to meet local content thresholds.
Industry Challenges
- Combat systems engineering talent scarcity:Software architecture and sensor fusion expertise concentrates at established primes, limiting workforce mobility and inflating compensation costs for emerging shipbuilders.
- Classification society certification timelines:Lloyd's Register and DNV naval vessel rules require extended validation cycles for novel integrated power and weapon systems, compressing available construction windows.
- Legacy fleet interoperability mandates:New destroyer programs must maintain backward compatibility with allied Link-16 and Cooperative Engagement Capability networks, constraining architectural innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Destroyers Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.02 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Multi-Role, Air-Defence, Guided-Missile, Conventional Technology: Stealth, AEGIS, Electric Propulsion, Integrated Combat Systems Size: Large, Medium, Small, Compact End User: Navy, Coast Guard, Private Security, Others |
| Companies Covered | Lockheed Martin, Northrop Grumman, General Dynamics Bath Iron Works, Raytheon, Fincantieri, Huntington Ingalls Industries, BAE Systems, Ingalls Shipbuilding, General Dynamics NASSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Destroyers Market Emerging Trajectories
Distributed lethality architectures are fragmenting traditional fleet formations and demanding new sensor-to-shooter network designs. Shipbuilders are responding with modular mission bay configurations and open combat system standards.
Artificial intelligence-enabled sensor fusion is decentralizing command-and-control functions across destroyer combat information centers. The US Navy's Project Overmatch and allied equivalents are accelerating adoption of edge-computing architectures. This compression of decision timelines is displacing legacy centralized processing models and enabling smaller crew complements.
EU CSRD sustainability disclosure requirements are extending to defense industrial base reporting, mandating carbon footprint transparency across shipyard supply chains. European naval procurement agencies are incorporating lifecycle emissions criteria into evaluation frameworks. Combat system suppliers with established environmental management systems under ISO 14001 are capturing preferential positioning in Franco-Italian and Nordic competitions.
Fleet buyers are consolidating procurement into multi-ship block buys with decade-long option structures. The US Navy's Flight III Arleigh Burke program and Japan's Maya-class follow-on orders demonstrate this commitment mechanism. This pattern compresses supplier pricing cycles and concentrates aftermarket service obligations at original equipment manufacturers.
Destroyers Market Segmentation
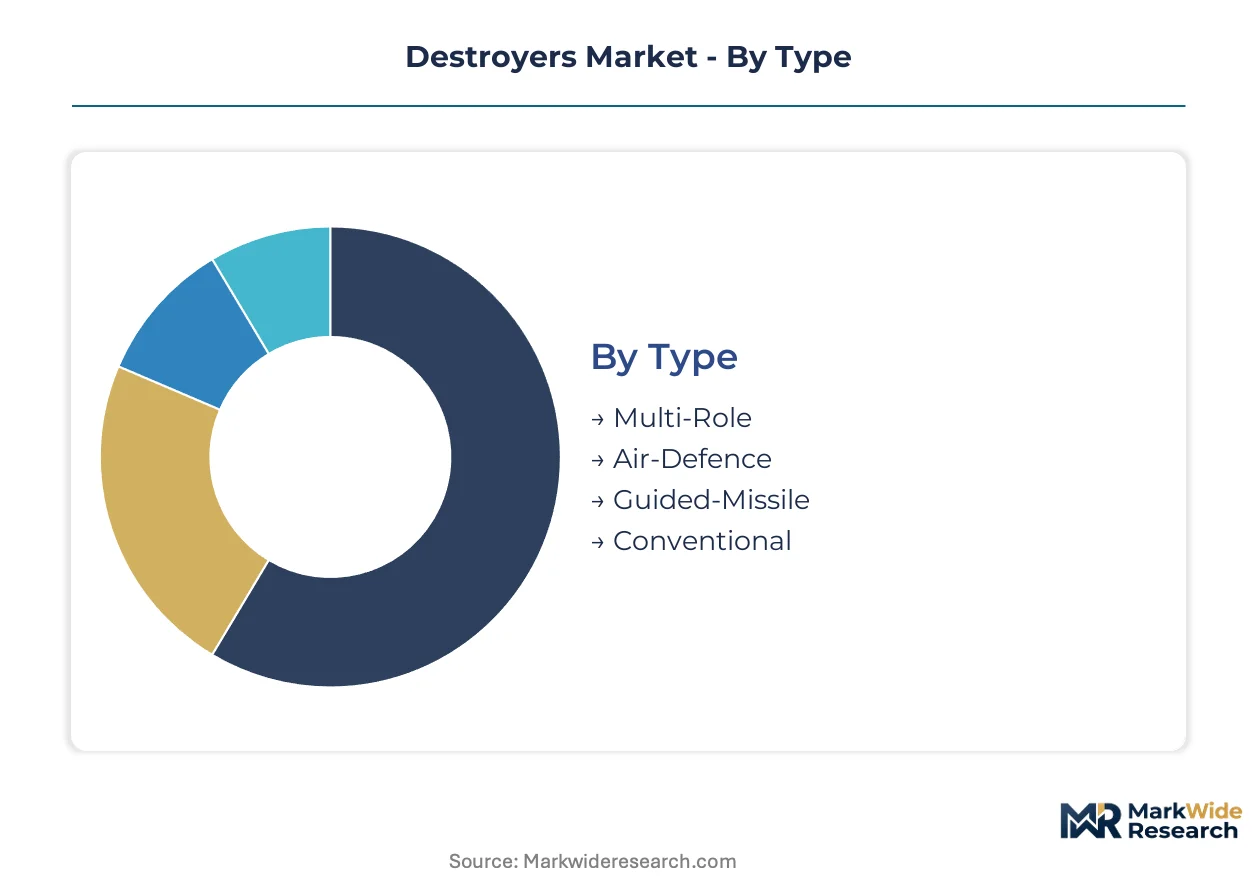
Destroyer procurement patterns fragment sharply across operational requirements and fleet modernization timelines. Commanders prioritize platform flexibility over single-mission specialization, driving segmentation by combat system integration depth and hull displacement categories.
Type:
Replacement cycles for Cold War-era hulls are compressing procurement windows as NATO and Asia-Pacific navies simultaneously recapitalize.
- Multi-Role:These hulls integrate layered anti-air, anti-surface, anti-submarine, and strike warfare capabilities through software-defined combat architectures. The US Navy's distributed maritime operations doctrine concentrates demand in this segment as fleet commanders seek maximum operational flexibility per hull.
- Guided-Missile:Vertical launch system density and long-range precision strike capacity define these platforms. Japan's Maritime Self-Defense Force and South Korean shipbuilders are accelerating indigenous production under US technology transfer protocols, expanding regional procurement volumes.
- Air-Defence:Specialized fleet protection platforms with enhanced radar aperture and interceptor magazine depth.
- Conventional:Legacy hull forms without integrated combat system backbones, now limited to secondary navies and training roles.
Multi-Role sits at the top of the volume ranking, with Guided-Missile climbing the fastest.
Technology:
Cost tiers separate combat system sophistication levels, with premium positioning commanding Congressional and parliamentary authorization thresholds.
- AEGIS:Lockheed Martin's integrated combat system anchors fleet air defense through AN/SPY radar and Mk 41 vertical launch system integration. US-Japan alliance technology transfer agreements license production to Mitsubishi Heavy Industries, creating dual-source supply security.
- Integrated Combat Systems:Open-architecture sensor and weapon fusion platforms enable incremental software upgrades without hull modifications. European navies under PESCO frameworks prioritize these systems for Franco-Italian FREMM-derived hulls.
- Stealth:Reduced radar cross-section hull forms and signature management coatings.
- Electric Propulsion:Integrated full electric drive architectures enabling directed-energy weapon hosting.
AEGIS commands the premium tier by authorization value, with Integrated Combat Systems gaining share fastest among European consortium builds.
Size:
Application requirements dictate displacement bands, with carrier strike group escort missions demanding maximum magazine capacity and endurance.
- Large:These hulls displace 10,000–15,000 tonnes with extensive aviation facilities and command-and-control suites. The US Navy's Flight III Arleigh Burke program and Japan's Maya-class follow-on orders demonstrate sustained procurement commitment to this band.
- Medium:7,000–10,000 tonne platforms balance capability with construction cost constraints. Fincantieri's FREMM-derived designs serve European and Middle Eastern fleets seeking multi-role capacity without large-hull overhead.
- Small:Reduced crew complement and maintenance burden for secondary fleet roles.
- Compact:Coastal defense and littoral warfare specialization with limited blue-water endurance.
Large hulls dominate authorization values, with Medium displacement expanding most quickly among NATO allies with constrained procurement budgets.
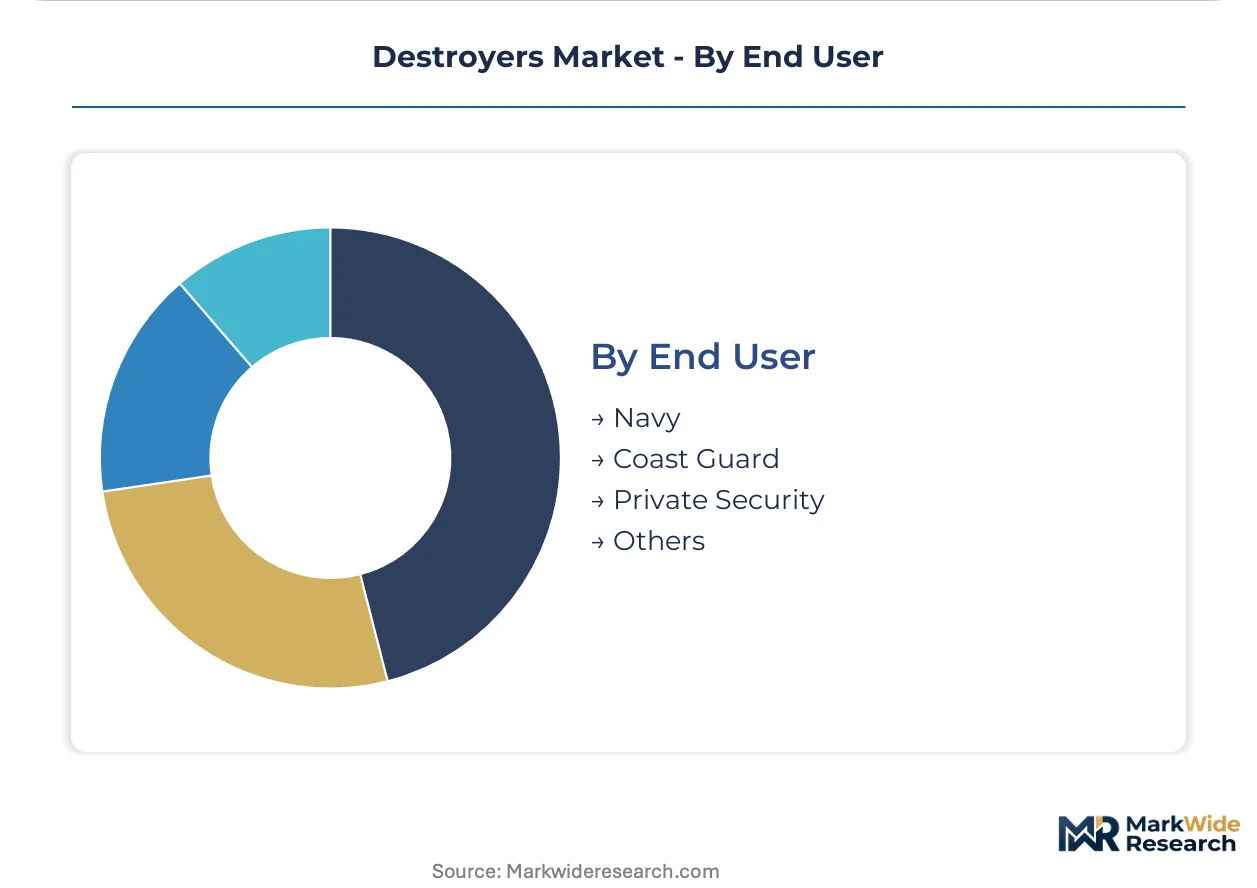
End User:
Customer type determines specification stringency, with national navies mandating classified technology integration and domestic construction requirements.
- Navy:National fleet commands specify integrated combat systems with Link-16 and Cooperative Engagement Capability interoperability. Congressional defense authorization frameworks in the US and EU PESCO initiatives in Europe channel procurement through multi-year block buy structures.
- Coast Guard:Maritime constabulary forces prioritize law enforcement adaptability over full-spectrum warfare integration. Hull specifications emphasize helicopter deck capacity and boat launch recovery systems for search and rescue missions.
- Private Security:Corporate maritime protection fleets with limited weapon system authorization.
- Others:Research vessels and training platforms with modified combat system suites.
Navy procurement anchors segment value, with Coast Guard demand climbing fastest as maritime security missions expand beyond traditional naval boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's indigenous destroyer construction outpaces South Korean output in integrated combat system depth, while both nations license AEGIS technology under separate US alliance protocols. Congressional authorization frameworks in the United States channel the largest procurement volumes through multi-year block buys.
United States
The US Navy's distributed maritime operations doctrine drives Flight III Arleigh Burke destroyer procurement through Congressional defense appropriations. Navy shipbuilding plans set annual procurement floors under authorization frameworks. Huntington Ingalls Industries and General Dynamics Bath Iron Works dominate construction at Pascagoula and Bath shipyard clusters.
Japan
Japan's Maritime Self-Defense Force accelerates Maya-class follow-on orders with AEGIS-compatible indigenous hulls. METI industrial base guidelines channel technology transfer protocols with US partners. Mitsubishi Heavy Industries anchors licensed production at Nagoya-area shipyards with integrated combat system assembly.
South Korea
South Korean shipbuilders expand KDX-III Sejong the Great-class construction with US-Korea technology transfer agreements. The central government defense procurement agency coordinates combat system integration mandates. Hyundai Heavy Industries and Daewoo Shipbuilding concentrate large-hull construction at Ulsan and Geoje shipyard complexes.
Italy
Italian naval procurement under EU PESCO frameworks prioritizes FREMM-derived multi-role destroyers for Franco-Italian fleet modernization. Fincantieri's integrated electric propulsion specialization serves European and Middle Eastern export customers. Riva Trigoso and Muggiano shipyards concentrate hull construction with combat system integration at Genoa-area facilities.
United Kingdom
The Royal Navy's Type 45 destroyer replacement programs sustain BAE Systems' naval gun system and integrated electric propulsion specialization. UK domestic content mandates restrict foreign subsystem sourcing under industrial base preservation rules. Glasgow-area shipyards on the River Clyde concentrate surface combatant construction with Govan and Scotstoun facilities.
Destroyers Market Vendor Landscape
United States producers anchor one tier; European specialists hold integrated electric propulsion and naval gun system positioning. The vendor base concentrates around prime contractors with sustained engineering talent pools for software-defined combat architectures. Two strategic archetypes dominate: full-service shipbuilders with captive combat system integration, and combat system specialists licensing technology to indigenous construction programs. Geographic expansion through technology transfer agreements and portfolio diversification into electrified propulsion configurations represent the dominant competitive moves.
Within the full-service shipbuilder tier, Huntington Ingalls Industries and General Dynamics exemplify integrated construction and combat system delivery models. Fincantieri occupies a position representing European consortium approaches to medium-destroyer platforms. Lockheed Martin anchors the combat system specialist archetype through AEGIS licensing arrangements with Japanese and South Korean shipbuilders.
| Leading Market Players |
|---|
| Lockheed Martin |
| Northrop Grumman |
| General Dynamics Bath Iron Works |
| Raytheon |
| Fincantieri |
| Huntington Ingalls Industries |
| BAE Systems |
| Ingalls Shipbuilding |
| General Dynamics NASSCO |
| Others |
Supply Flow & Price Mechanics
National navy procurement offices concentrate buying power through multi-year block buy authorizations, compressing supplier margins and locking combat system integrators into decade-long service obligations. Congressional defense appropriations frameworks and EU PESCO budget pooling mechanisms institutionalize this buyer dominance, forcing shipbuilders to absorb steel alloy volatility and engineering talent scarcity within fixed-price contract structures.
Pricing Analysis
Capacity additions in South Korean and Japanese shipyards are reshaping price floors for large guided-missile destroyers, intensifying competition for US technology transfer licenses. Contract-based long-term offtake dominates, with price differentiation anchored in AEGIS combat system integration depth and domestic content compliance thresholds. Cost compression in medium-displacement hulls is intensifying because European consortium builds under PESCO frameworks pool procurement volumes. Coast Guard maritime security programs exhibit highest price sensitivity, while nuclear-armed navy fleets demonstrate lowest sensitivity due to classified technology mandates.
Supply Chain Analysis
Dual-sourcing requirements in US Congressional authorization frameworks and UK industrial base preservation rules mandate qualified secondary suppliers for high-tensile naval-grade steel and integrated combat system components. Geographic supply concentration centers on Japan, South Korea, and specialized European mills for HY-80/100 steel alloys. Raw material dependencies include nickel-bearing superalloys for turbine components, rare earth elements for radar transmitters, and copper-intensive electric propulsion cabling. Single-source vulnerability pervades AN/SPY radar and Mk 41 vertical launch system supply. Distribution runs through prime contractor-led integration at Ingalls Shipbuilding, Bath Iron Works, and Mitsubishi Heavy Industries facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU CSRD sustainability disclosure mandates and NATO integrated air and missile defense capability targets accelerating procurement authorization cycles across member states.
For Market Incumbents: Anticipate compressed delivery timelines from classification society certification bottlenecks at Lloyd's Register and DNV by pre-qualifying integrated power system architectures before hull steel cutting. Lockheed Martin and Northrop Grumman should deepen backward integration into software-defined sensor fusion engineering pools to defend against emerging combat system specialists. Certification investment in ISO 14001 environmental management systems captures preferential positioning in Franco-Italian and Nordic competitions. For New Entrants and Emerging Players: Middle Eastern indigenous shipyard programs in Saudi Arabia and the UAE represent the most penetrable buyer archetype, with local construction mandates creating white-space for European combat system integrators lacking US technology transfer access. Australia's Hunter-class continuous shipbuilding plan offers second-tier entry for suppliers meeting local content thresholds. Go-to-market execution should anchor on electrified propulsion specialization, as integrated full electric drive architectures enable directed-energy weapon hosting configurations absent from legacy platforms. For Investors and Strategic Acquirers: Defense prime contractors with captive shipyard assets represent the most active acquirer category in this space, seeking software-defined warfare engineering talent concentrated at established combat system specialists. Long-term viability over the five-to-ten year horizon rests on AEGIS licensing portfolio depth and alliance technology transfer protocol access. Monitor US-Japan and US-Korea diplomatic friction as the signal to watch for license revocation risk that would shift competitive positioning materially.| Strategic Initiative | Industry Significance |
|---|---|
| AEGIS Technology Licensing Agreement | Lockheed Martin's combat system exports to Japan and South Korea under alliance protocols secure recurring revenue streams. |
| Integrated Full Electric Propulsion Investment | BAE Systems and Fincantieri capture premium positioning for directed-energy weapon hosting configurations. |
| Multi-Ship Block Buy Contracting | US Navy Flight III Arleigh Burke and Japan Maya-class follow-on orders compress supplier pricing cycles. |
| Indigenous Shipyard Joint Venture | European combat system integrators access Saudi and UAE local construction mandates through technology transfer partnerships. |
| ISO 14001 Environmental Certification | Combat system suppliers capture preferential EU procurement positioning under CSRD lifecycle emissions criteria. |
Methodological Framework
Direct dialogue with naval program executives, shipyard procurement directors, combat system integration engineers, and defense authorization legislative staff anchored qualitative grounding. Secondary validation drew from Congressional Research Service shipbuilding reports, EU PESCO capability target documentation, NATO integrated air and missile defense guidelines, and Lloyd's Register naval vessel rule publications. Bottom-up hull delivery tracking and top-down defense budget authorization analysis enabled triangulation across procurement volume estimates.
Bottom-up modeling segmented destroyer procurement by multi-role versus guided-missile type, AEGIS versus integrated combat system technology tier, and large versus medium displacement band across the analysis window. Top-down defense expenditure frameworks from US Congressional appropriations, EU PESCO pooled budgets, and Japan METI industrial guidelines provided authorization ceiling constraints. CAGRs derived from hull delivery schedules, technology transfer protocol renewals, and steel alloy input cost trajectories.
Underlying measurement precision varies by segment; AEGIS-equipped large hulls carry tighter precision than conventional technology compact platforms due to transparent Congressional authorization documentation. Forecasts reflect assumptions around US-Japan and US-Korea alliance stability, NATO capability target adherence, and naval-grade steel mill capacity expansion. Deviation in technology transfer protocol suspension or HY-80 steel alloy supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Japan Defense Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Military Amphibious Vehicle Market
Military Vehicles
Indonesia Defense Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Military Trucks Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Military Ground Robots Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Russia Defense Market