
 Amphibious Land Craft Market | 2026-2036
Amphibious Land Craft Market Size, Share, and Industry Trends Forecast 2026-2036
Amphibious Land Craft Market Analytics
Coastal defense modernization is repositioning procurement priorities across NATO and Indo-Pacific navies. BAE Systems leverages its combat-proven landing craft portfolio to anchor contracts with the UK Royal Marines and allied forces. CNIM sustains its position through specialized amphibious bridging and landing systems for French and export customers. Garden Reach Shipbuilders & Engineers competes on cost-optimized designs for India's expanding amphibious capabilities.
Amphibious land craft are vessels engineered for ship-to-shore cargo and personnel transport, typically featuring shallow drafts below 1.2 meters and aluminum or steel hulls rated for surf zones up to Sea State 3. These craft serve military assault logistics, humanitarian relief, and coastal resupply missions where conventional port infrastructure is absent. Military Vehicles dominate product-type revenue due to armored personnel carrier derivatives and landing craft utility programs, while Hybrid Systems within the technology dimension is gaining fastest as navies pursue reduced thermal and acoustic signatures. Emergency Services deployment channels show rising tender volumes for flood rescue craft, though Defense Forces end users still capture the bulk of margin pools through multi-year program-of-record structures.
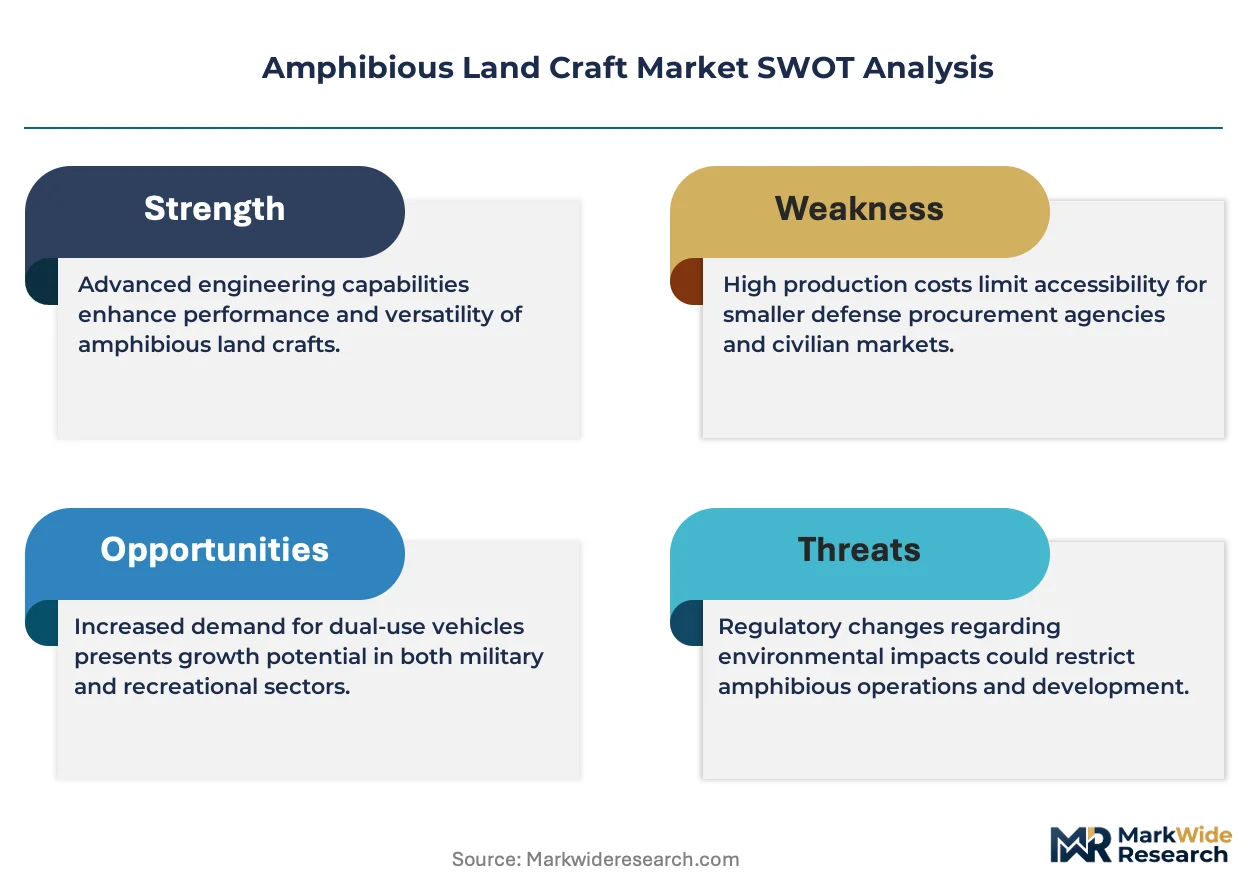
US Navy Naval Sea Systems Command sets hull, mechanical, and electrical standards that constrain foreign supplier access unless designs meet MIL-STD-810 shock requirements. NATO STANAG 4569 for ballistic protection and EU REACH chemical compliance for coatings and composites add parallel certification burdens for European suppliers. India's Ministry of Defence offsets policy mandates local content thresholds that shape joint-venture structures for Garden Reach Shipbuilders & Engineers and Goa Shipyard. Stakeholders must track how evolving anti-access area denial doctrines reshape payload and speed specifications before committing to next-generation platform development.
Market Dynamics
Naval modernization programs are compressing development cycles as marine corps and coast guard units demand landing craft with reduced thermal and acoustic signatures alongside hardened survivability against anti-access area denial threats.
Growth Catalysts
- NATO STANAG 4569 ballistic standards:Mandates for composite armor integration are pulling forward replacement demand across European marine units.
- Indo-Pacific coastal defense modernization:Marine corps procurement in Australia, Japan, and South Korea is accelerating multi-year program-of-record structures for amphibious utility craft.
- Hybrid electric propulsion systems:Reduced acoustic signature requirements from littoral warfare doctrines are driving technology refresh in existing landing craft fleets.
Market Restraints
- Aluminum hull plate price volatility:Input cost swings for marine-grade 5083 alloy constrain margin predictability for hull fabricators.
- MIL-STD-810 shock certification concentration:US Navy Naval Sea Systems Command standards limit foreign supplier qualification pathways.
- Composite armor supply bottleneck:Ceramic matrix production capacity concentrates among a handful of specialized foundries in the United States and Germany.
Strategic Opportunities
- Emergency Services flood rescue procurement:Coast guard and civil defense tenders for shallow-draft rescue craft are expanding addressable demand beyond military end users.
- India's Ministry of Defence offsets policy:Local content thresholds are creating joint-venture entry points for foreign hull designers with Garden Reach Shipbuilders & Engineers and Goa Shipyard.
- EU REACH chemical compliance:Coating and composite material standards are favoring European suppliers with established certification infrastructure.
Industry Challenges
- Surf zone hydrodynamics modeling expertise:Computational fluid dynamics talent scarcity constrains hull form optimization for Sea State 3 operations.
- Multi-standard certification timelines:Parallel NATO STANAG, MIL-STD, and national flag state approvals extend program entry by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amphibious Land Craft Market |
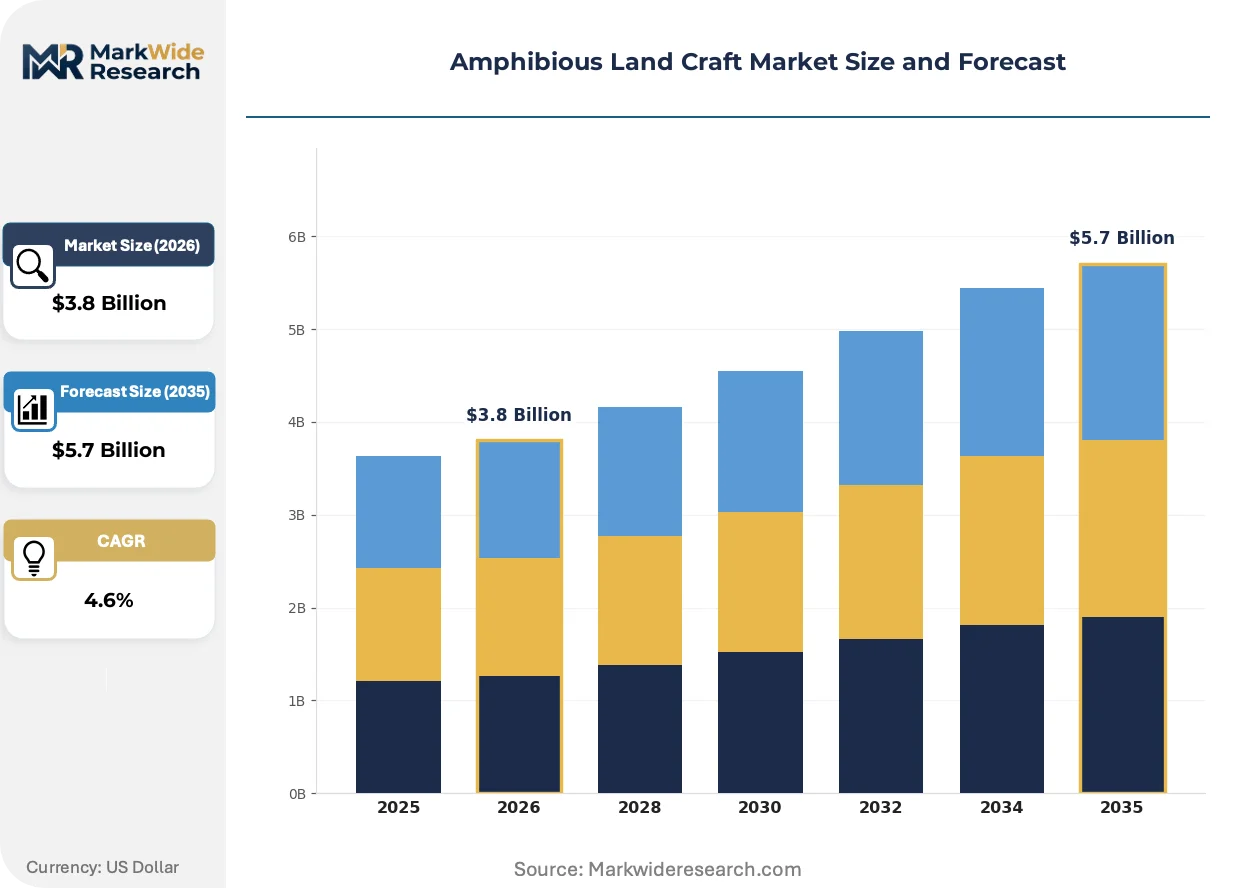
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Military Vehicles, Personal Watercraft, Utility Boats, Specialized Crafts End User: Defense Forces, Civilian Agencies, Recreational Users, Emergency Services Technology: Hydrostatic Drives, Ballistic Protections, GPS Navigation, Hybrid Systems Deployment: Coastal Operations, Disaster Relief, Search and Rescue, Training Exercises |
| Companies Covered | BAE Systems, Textron Marine and Land Systems, CNIM, Griffon Hoverwork, Fincantieri Marine Group, Garden Reach Shipbuilders & Engineers, Goa Shipyard, L3Harris Technologies, Marine Alutech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amphibious Land Craft Market Evolving Landscape
Propulsion architecture, survivability materials, and procurement contracting models are undergoing simultaneous transformation as operators balance signature reduction against payload preservation in contested littorals.
Plug-in hybrid diesel-electric drivetrains are modularizing landing craft powertrain architecture. Marine corps engineering divisions in the United States and United Kingdom are piloting swappable battery modules that enable silent final-approach modes. This is modularizing platform configurations so a single hull form can shift between high-speed transit and low-signature assault profiles without yard-time reconfiguration.
EU REACH chemical compliance for marine coatings and composite resins is tightening formulation requirements. Manufacturers must eliminate specific isocyanates and heavy-metal pigments from production lines. French and Italian shipyards are most affected, accelerating partnerships with specialty chemical suppliers to reformulate hull treatments before 2027 certification deadlines.
Multi-year availability contracting is displacing transactional vessel procurement. Royal Marines and Royal Australian Navy maintenance organizations now contract for fleet readiness rather than hull delivery. This concentrates vendor selection on through-life support capability, favoring BAE Systems and CNIM with established service networks in the United Kingdom and France.
Amphibious Land Craft Market Segmentation
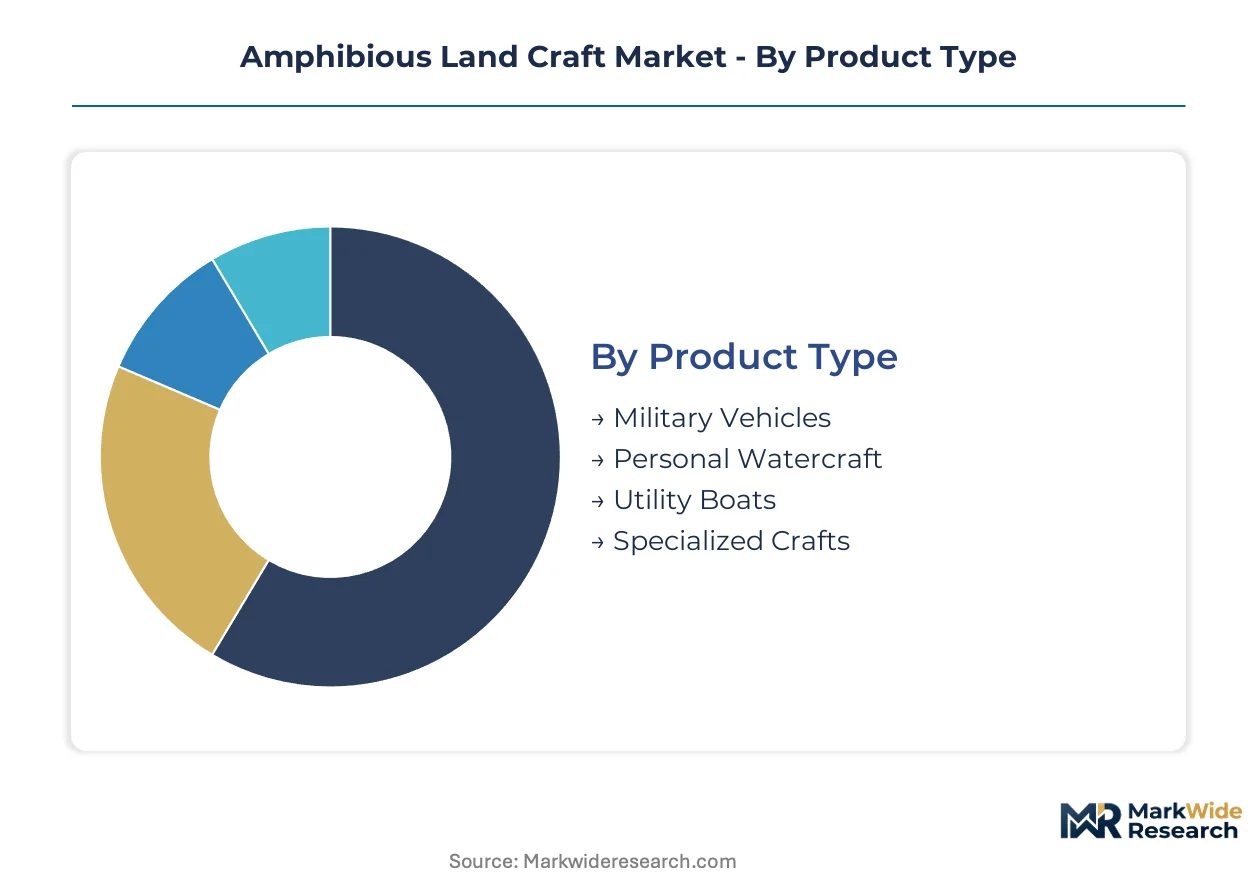
Segmentation in the amphibious land craft market reveals how payload requirements, signature reduction priorities, and mission profiles drive procurement decisions across defense and civilian channels. Understanding these divisions exposes where technology refresh concentrates and where long-term platform contracts anchor revenue stability.
Product Type:
Hull form and armor integration differentiate craft capabilities across surf zone assault, logistics transport, and shallow-water mobility missions.
- Military Vehicles:Armored personnel carrier derivatives and landing craft utility programs feature aluminum or steel hulls with STANAG 4569 ballistic protection. Demand concentrates in United States Marine Corps multi-year program-of-record structures, where hardened survivability against anti-access area denial threats drives replacement cycles.
- Utility Boats:Shallow-draft aluminum hulls rated for Sea State 3 operations support ship-to-shore cargo movement without port infrastructure. Procurement in Australia's coastal defense modernization and Japan's marine corps expansion favors modular payload configurations over fixed armament fits.
- Personal Watercraft:Compact reconnaissance and liaison platforms for special operations insertion.
- Specialized Crafts:Amphibious bridging systems and command variants for French and export customers.
Mature deployment sits with Military Vehicles. Newer deployment is concentrated in Utility Boats.
End User:
Customer type determines contract structure, certification burden, and through-life support expectations.
- Defense Forces:Marine corps and coast guard units drive multi-year availability contracting rather than transactional procurement. Royal Marines and Royal Australian Navy maintenance organizations now contract for fleet readiness, concentrating vendor selection on established service networks in the United Kingdom and France.
- Emergency Services:Flood rescue craft tenders from civil defense agencies are expanding addressable demand beyond military channels. Coast guard procurement for shallow-draft rescue platforms in flood-prone regions is climbing the fastest as climate adaptation budgets redirect toward amphibious capability.
- Civilian Agencies:Harbor patrol and environmental monitoring craft for non-military government operators.
- Recreational Users:Amphibious leisure craft for coastal property access and expedition tourism.
Defense Forces capture the bulk of margin pools through program-of-record structures. Emergency Services represent the steepest expansion trajectory for tender volumes.
Technology:
Propulsion and protection architectures determine platform competitiveness in contested littoral environments.
- Hybrid Systems:Plug-in hybrid diesel-electric drivetrains with swappable battery modules enable silent final-approach modes. United States and United Kingdom marine corps engineering divisions are piloting configurations that shift between high-speed transit and low-signature assault without yard-time reconfiguration.
- Ballistic Protections:Composite armor integration against ceramic matrix specifications. NATO STANAG 4569 mandates are pulling forward replacement demand, though production capacity concentrates among specialized foundries in the United States and Germany.
- Hydrostatic Drives:Variable displacement propulsion for precise maneuvering in surf zones.
- GPS Navigation:Precision positioning systems for contested electromagnetic environments.
Ballistic Protections anchor current fleet specifications. Hybrid Systems are gaining share fastest as navies pursue reduced thermal and acoustic signatures.
Deployment:
Mission profile dictates hull form optimization, payload flexibility, and support infrastructure requirements.
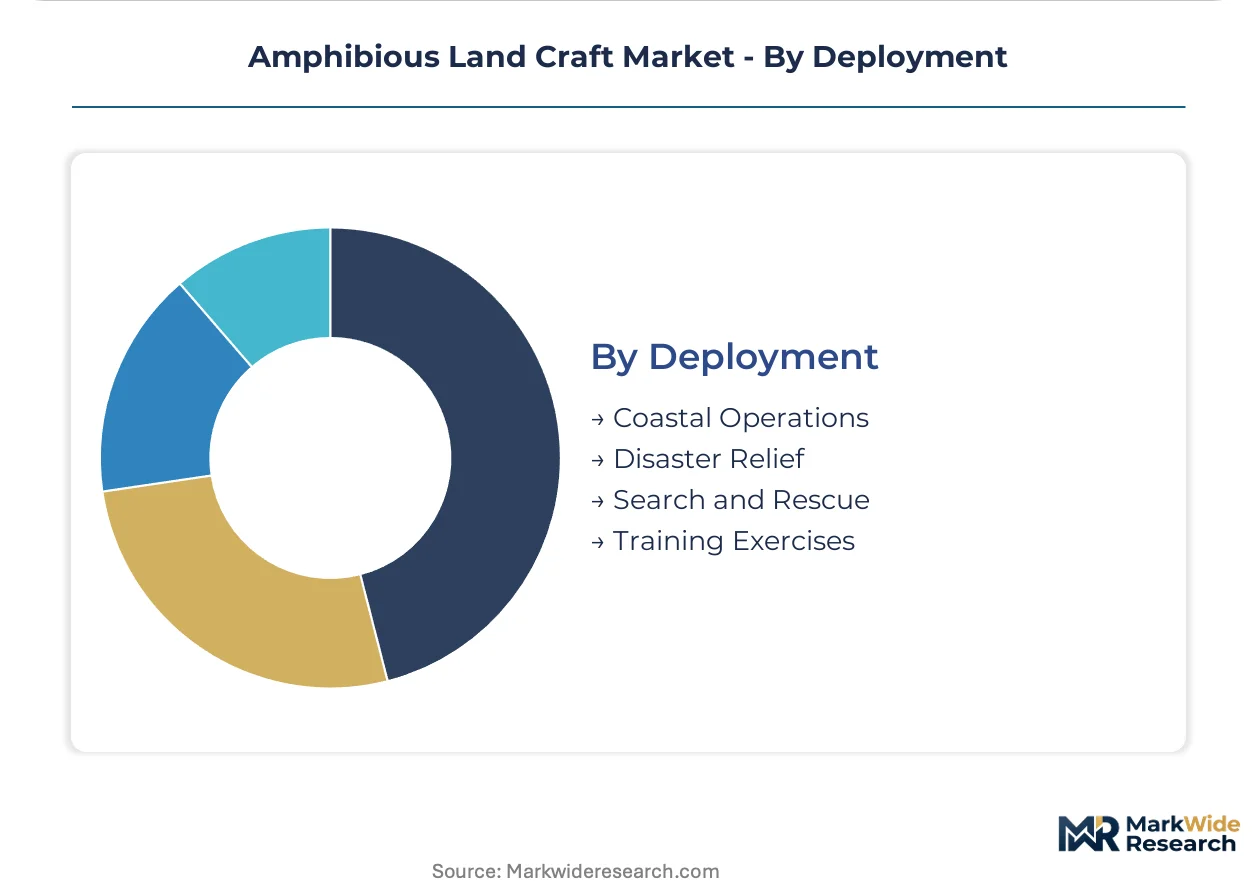
- Coastal Operations:Ship-to-shore assault and logistics missions where shallow draft below 1.2 meters enables beach access. United States Marine Corps maintains the largest fleet globally, with procurement prioritizing hardened survivability and modular payload preservation.
- Disaster Relief:Humanitarian resupply where conventional port infrastructure is absent. India's expanding amphibious capabilities through Garden Reach Shipbuilders & Engineers focus on cost-optimized designs for regional disaster response.
- Search and Rescue:Shallow-draft operations for coast guard and civil defense agencies.
- Training Exercises:Platform familiarization and crew certification programs.
Coastal Operations dominate capital expenditure allocation. Disaster Relief is expanding most quickly as climate adaptation redirects procurement priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in coastal manufacturing corridors concentrate amphibious craft fabrication. Tax incentives for defense industrial base expansion pull capacity toward littoral production clusters. Naval modernization programs across multiple jurisdictions reshape regional procurement patterns.
United States
Marine Corps multi-year program-of-record structures drive replacement demand for landing craft utility platforms. Naval Sea Systems Command MIL-STD-810 shock requirements constrain foreign supplier qualification pathways. Gulf Coast shipyards in Louisiana and Mississippi anchor fabrication capacity for shallow-draft assault craft.
United Kingdom
Royal Marines fleet readiness contracting prioritizes through-life support capability over transactional procurement. Ministry of Defence shipbuilding strategy directs investment toward amphibious bridging and landing systems. Clydebank and Portsmouth clusters specialize in composite armor integration for STANAG 4569 compliance.
France
Marine Nationale coastal defense modernization accelerates specialized amphibious system procurement. Direction Générale de l'Armement oversees certification timelines for EU REACH chemical compliance in marine coatings. Toulon and Lorient shipyards concentrate on hybrid electric propulsion integration for signature reduction.
India
Ministry of Defence offsets policy mandates local content thresholds for expanding amphibious capabilities. Garden Reach Shipbuilders & Engineers and Goa Shipyard leverage joint-venture structures for cost-optimized designs. Kolkata and Goa clusters focus on disaster relief platform configurations for regional response missions.
Australia
Royal Australian Navy maintenance organizations contract for fleet readiness rather than hull delivery. Department of Defence prioritizes shallow-draft rescue craft tenders for climate adaptation budgets. Henderson shipyard precinct in Western Australia develops modular payload configurations for Indo-Pacific littoral operations.
Amphibious Land Craft Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense program integrators capturing multi-year availability contracts while regional fabricators compete on cost-optimized designs. Market structure tilts toward consolidated prime contractor relationships in NATO markets and fragmented local production in offset-driven jurisdictions. Three archetypes dominate: systems integrators with established service networks, state-owned shipbuilders leveraging domestic procurement preferences, and specialized hull form designers with surf zone hydrodynamics expertise. Competitive moves center on joint-venture formations for market access and technology licensing for hybrid propulsion architectures.
Among UK-based defense primes, BAE Systems exemplifies the integrated service network archetype through its combat-proven portfolio positioning. French industrial group CNIM occupies a specialist position in amphibious bridging systems for marine corps and export customers. Indian state-owned enterprise Garden Reach Shipbuilders & Engineers represents the offset-leveraged domestic fabricator model, anchoring cost-competitive production for regional naval modernization.
| Leading Market Players |
|---|
| BAE Systems |
| Textron Marine and Land Systems |
| CNIM |
| Griffon Hoverwork |
| Fincantieri Marine Group |
| Garden Reach Shipbuilders & Engineers |
| Goa Shipyard |
| L3Harris Technologies |
| Marine Alutech |
| Others |
Value Network & Pricing Analysis
London Metal Exchange aluminum alloy 5083 pricing volatility cascades through hull fabrication tiers, compressing margins for European and Asian fabricators while concentrating pricing power among vertically integrated US Gulf Coast shipyards with captive metalworking capacity.
Pricing Analysis
Lead-time premiums command substantial markups for STANAG 4569-certified craft with sub-18-month delivery windows, while spot inventory of legacy utility hulls trades at discounted clearance levels. Three-tier pricing structure across premium, standard, and economy levels separates multi-year availability contracts with through-life support from transactional hull sales and refurbished surplus platforms. Price differentiation hinges on composite armor integration grade and MIL-STD-810 shock certification tier. Pricing pressure stems from aluminum hull plate cost compression in spot markets, tightening margins for independent fabricators without long-term alloy offtake agreements. Emergency Services buyers exhibit highest price sensitivity, prioritizing shallow-draft capability per dollar over survivability specifications.
Supply Chain Analysis
Single-source vulnerability sits with ceramic matrix composite armor foundries concentrated in the United States and Germany, constraining throughput for NATO STANAG 4569-compliant platforms. Hull fabrication draws from aluminum smelting capacity in the United States, Norway, and the United Arab Emirates, while marine-grade steel plate sources from South Korean and Japanese mills. Supply chain risk centers on tariff exposure for alloy imports into European Union shipyards under evolving trade remedy frameworks. Distribution runs through prime contractor direct sales for defense program-of-record structures, with offset-mandated joint ventures handling indigenous production in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic matrix foundry capacity constraints prop pricing premiums for survivability-integrated platforms, creating durable margin pools for suppliers with qualified armor supply chains.
For Market Incumbents: Anticipate margin compression from Indo-Pacific shipyard cost optimization by securing long-term ceramic matrix supply agreements and expanding hybrid propulsion R&D pipelines. Counter emerging French and Italian coating reformulation specialists through backward integration into REACH-compliant resin formulation. Prioritize multi-year availability contract renewals with Royal Marines and Royal Australian Navy maintenance organizations. For New Entrants and Emerging Players: Emergency Services channel partners represent the most penetrable entry vector, with flood rescue craft tenders climbing fastest as climate adaptation budgets redirect toward amphibious capability. Target shallow-draft utility configurations for coast guard civil defense agencies in flood-prone regions. Pursue technology licensing arrangements for plug-in hybrid diesel-electric drivetrains from established marine propulsion specialists. For Investors and Strategic Acquirers: Distressed-cycle entries favor surf zone hydrodynamics modeling boutiques with computational fluid dynamics expertise in the United Kingdom and Australia. Long-term viability across the analysis window rests on through-life support revenue streams rather than transactional hull margins. Monitor Royal Australian Navy fleet readiness contracting awards as inflection indicators for availability-based revenue model adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Armor Supply Agreement | Long-term ceramic matrix offtake with US or German foundries locks in STANAG 4569 certification capacity. |
| Hybrid Propulsion Pilot Program | Swappable battery module trials with US Marine Corps engineering divisions validate silent-approach architectures. |
| Joint Venture Formation | Offset-compliant partnerships with Garden Reach Shipbuilders & Engineers or Goa Shipyard secure Indian Ministry of Defence access. |
| REACH Compliance Certification | ECHA-aligned coating reformulation partnerships with French and Italian chemical suppliers eliminate isocyanate liabilities. |
| Availability Contract Conversion | Fleet readiness contracting with Royal Marines shifts revenue from hull delivery to through-life support annuities. |
Research Methodology
Independent corroboration across program-of-record documentation, shipyard production schedules, and defense procurement databases underwrites the qualitative findings in this study. Primary interviews with naval architects, marine corps engineering division procurement officers, shipyard program managers, and composite armor foundry technical directors combined with secondary validation from NATO STANAG certification registries, EU REACH chemical compliance filings, and customs trade data for marine-grade aluminum alloys. Bottom-up platform delivery tallies and top-down defense budget appropriation analysis triangulate market sizing.
Comparable-period anchoring to historical program-of-record award cycles and fleet replacement timelines structured the forecast window across the projection horizon. Segmentation modeling spanned hull form configuration, propulsion architecture, armor integration tier, end-user contract structure, and regional offset policy framework. CAGRs derived from weighted average of platform delivery trajectories and defense expenditure growth patterns. Industry-specific inputs included surf zone hydrodynamics performance specifications and thermal signature reduction technology adoption curves.
Caveats apply where ceramic matrix production capacity expansion, aluminum alloy tariff regime shifts, or anti-access area denial doctrine revisions could materially shift the outlook. Forecasts reflect assumptions about NATO STANAG 4569 compliance timelines and Indo-Pacific coastal defense modernization funding continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Destroyers Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Infantry Fighting Vehicle (IFV) Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Military Trucks Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Military Ground Vehicle Actuators Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Colombia Defense Market
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Combat Support Vehicle Market