
 Military Ground Robots Market | 2026-2036
Military Ground Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Military Ground Robots Market Insights
The defense robotics engineering workforce is rotating toward autonomy software and sensor fusion specializations, creating bottlenecks in traditional mechanical design roles. Lockheed Martin Corporation leverages its vertical integration across propulsion and command systems to sustain long-term program contracts. Northrop Grumman Corporation anchors its position through R&D intensity in artificial intelligence-enabled target recognition. Elbit Systems Ltd. competes on geographic dominance in Middle Eastern markets with field-proven logistics robot deployments.
Military ground robots are self-propelled, unmanned platforms operating on terrestrial surfaces, typically weighing between 5 kg portable units and 12-ton heavy combat vehicles, designed for missions in denied or hazardous environments without direct human presence. These systems execute reconnaissance, explosive ordnance disposal, and materiel transport functions that expose personnel to lethal risk. EOD robots command the largest installed base among type segments due to sustained counter-IED requirements in asymmetric conflict zones. Autonomous navigation technology represents the fastest-expanding capability dimension as militaries push beyond line-of-sight radio control toward GPS-denied terrain traversal. Sensor fusion applications concentrate margin pools where multi-spectral payloads integrate thermal, LiDAR, and acoustic inputs into single-operator interfaces.
The U.S. Department of Defense, NATO Standardization Office, and Israel's Ministry of Defense shape procurement through interoperability mandates and autonomous engagement protocols that restrict certain AI-driven firing decisions. These frameworks elevate compliance costs for vendors while creating preferred supplier status for entities with pre-cleared architectures. Stakeholders must monitor evolving rules of engagement for armed unmanned systems as coalition operations demand common command interfaces.
Market Dynamics
The U.S. Department of Defense's ethical AI guidelines for autonomous weapons systems are compressing vendor qualification timelines while elevating compliance architecture requirements across NATO procurement frameworks.
Growth Catalysts
- Counter-IED missions:Asymmetric conflict zones sustain demand for explosive ordnance disposal platforms with extended operational endurance.
- NATO Standardization Office interoperability mandates:Common command interfaces accelerate cross-border joint procurement programs among allied defense ministries.
- Israel's cross-border surveillance requirements:Persistent territorial tensions drive investment in unmanned perimeter security systems with autonomous patrol capabilities.
Market Restraints
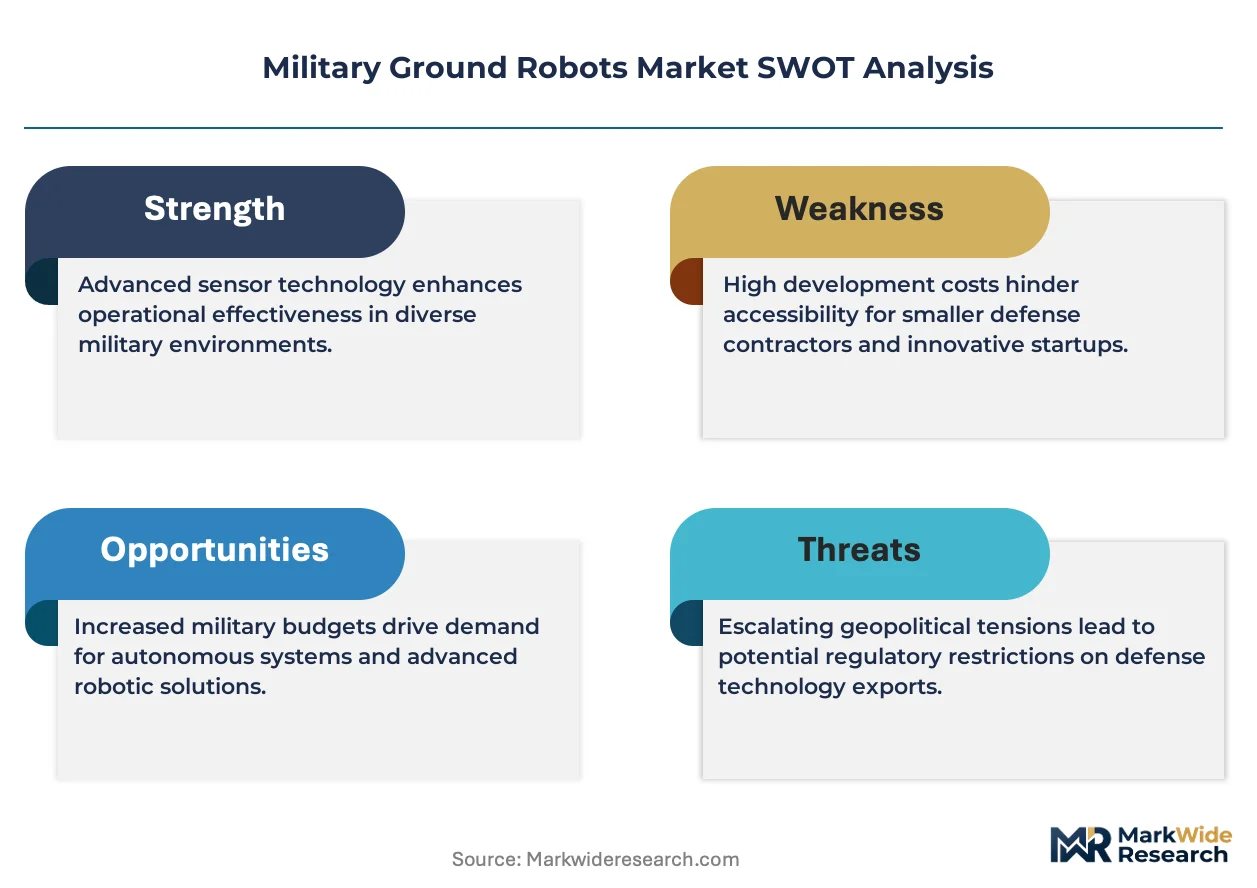
- Sensor payload cost volatility:Multi-spectral thermal and LiDAR component shortages inflate unit production costs for mid-tier vendors.
- Software talent concentration:Autonomy engineering expertise clusters in Israel and the United States, constraining development velocity elsewhere.
- U.S. DoD engagement protocol restrictions:Ethical AI constraints on autonomous firing decisions limit deployable capability sets for certain mission profiles.
Strategic Opportunities
- Urban warfare applications:Subterranean and dense-environment navigation capabilities open new mission profiles for reconnaissance and logistics transport.
- Swarming coordination protocols:Distributed multi-robot control architectures enable coordinated area denial and saturation reconnaissance tactics.
- Estonian and Polish border modernization:NATO eastern flank members accelerate unmanned ground system procurement for territorial defense infrastructure.
Industry Challenges
- Autonomy software certification timelines:Safety-critical algorithm validation for GPS-denied navigation extends program development cycles by 18-24 months.
- Legacy radio integration complexity:New autonomous platforms must maintain backward compatibility with existing command networks, constraining architecture optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Ground Robots Market |
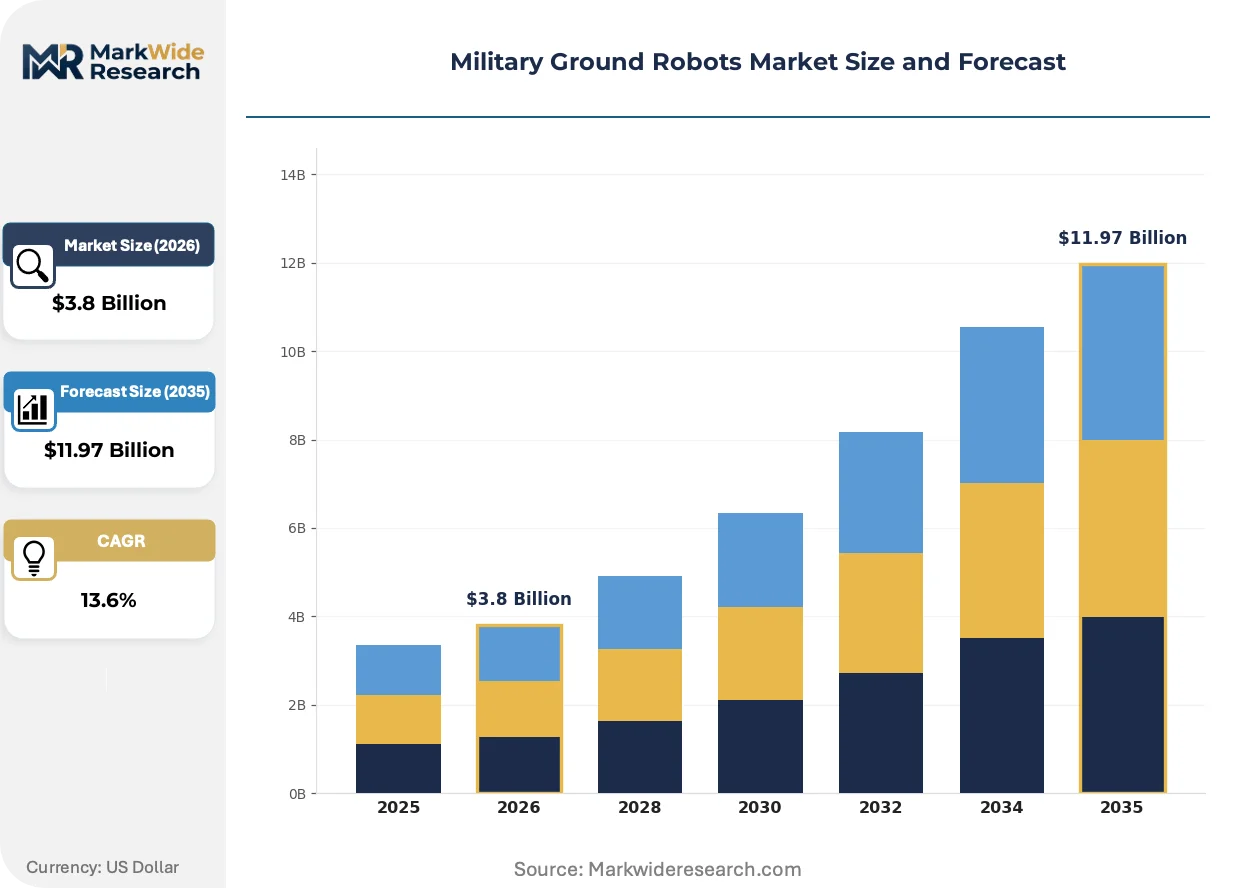
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Unmanned Combat Vehicles, Reconnaissance Robots, Logistics Robots, EOD Robots, Surveillance Robots Technology: Autonomous Navigation, Remote Operated Systems, Artificial Intelligence, Machine Learning, Sensor Fusion Application: Border Patrolling, Bomb Disposal, Target Acquisition, Supply Transport, Surveillance Missions End User: Defense Forces, Paramilitary Units, Counter-Terrorism Agencies, Peacekeeping Organizations |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, General Dynamics Corporation, BAE Systems, Elbit Systems Ltd., Israel Aerospace Industries Ltd., Teledyne Technologies Incorporated, L3Harris Technologies, Inc., Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Ground Robots Market Trends and Innovations
Active development in sensor fusion and edge computing architectures is compressing operator-to-robot ratios while expanding mission autonomy horizons beyond line-of-sight constraints.
Autonomous navigation stacks incorporating simultaneous localization and mapping (SLAM) with terrain-classification neural networks are displacing teleoperated control as the dominant operational mode for reconnaissance missions. U.S. Army combat teams are field-testing these capabilities in GPS-denied environments during joint readiness exercises. The shift is displacing traditional two-operator-per-robot staffing models in favor of single-operator multi-vehicle supervision architectures.
The EU AI Act's risk-classification framework for autonomous systems is imposing conformity assessment requirements on military ground robot exports to European defense ministries. Vendors must now document algorithmic decision transparency and human oversight protocols before platform deployment. Medium-weight combat vehicle segments face the steepest compliance burden, with several programs delaying fielding schedules to accommodate third-party audit requirements.
Bundled lifecycle service contracts are supplanting discrete hardware procurement as the dominant acquisition model among NATO member defense ministries. Contractors now retain platform maintenance and software update responsibilities for 10-15 year operational windows. This restructuring concentrates revenue streams with vertically integrated suppliers capable of sustaining long-term field support infrastructure across dispersed operational theaters.
Military Ground Robots Market Segmentation
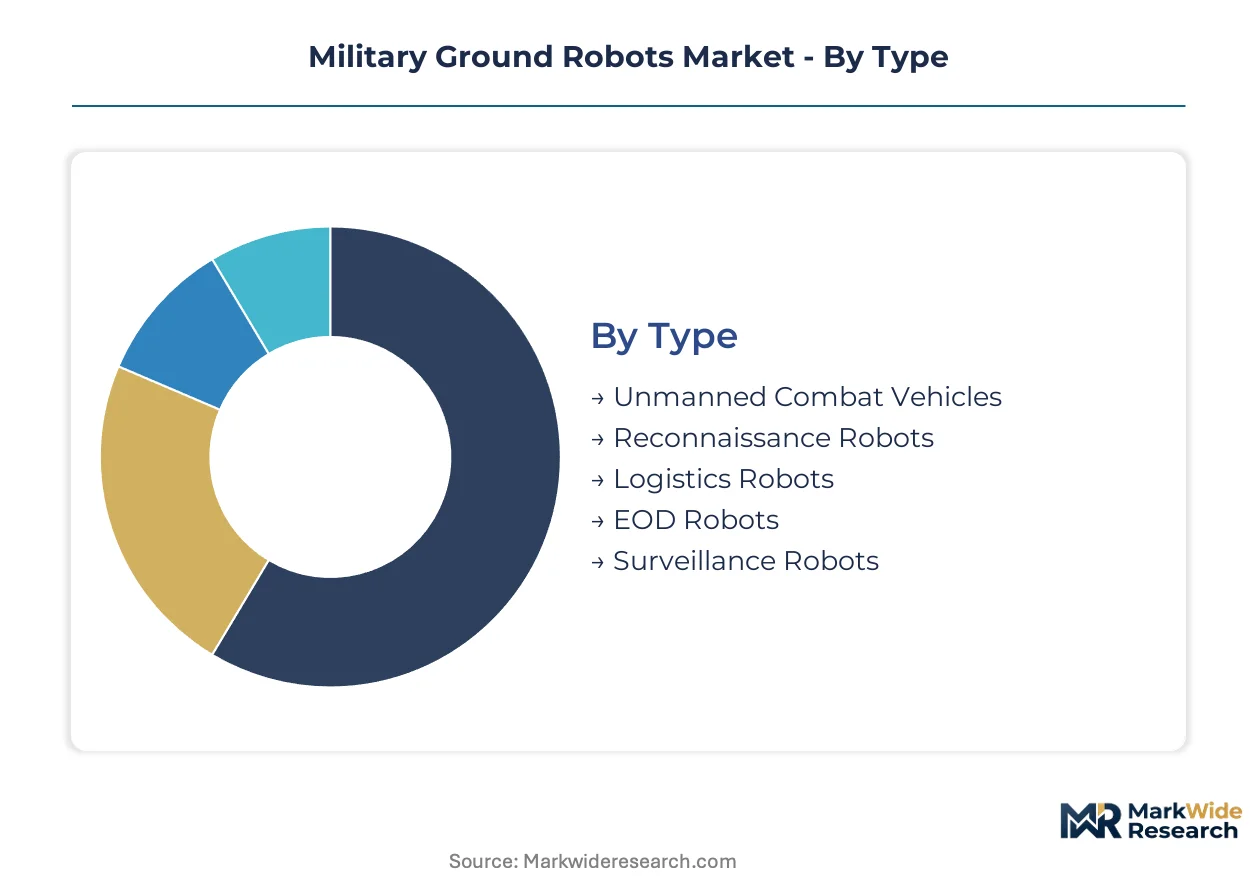
Military ground robot procurement channels diverge sharply by mission criticality and operational tempo. Defense ministries route high-risk applications through prime contractor direct sales, while lower-tier units leverage distributor networks for standardized platforms.
Type:
Channel configuration varies by platform weight class and mission profile, with heavy combat vehicles flowing through sole-source contracts and portable systems reaching operators via defense equipment distributors.
- EOD Robots:These platforms integrate manipulator arms with explosive disruption charges and chemical sensors for ordnance neutralization. Israeli Defense Forces and U.S. Army EOD teams sustain the largest installed base through sustained counter-IED procurement cycles driven by residual asymmetric threats.
- Logistics Robots:Autonomous resupply platforms navigate GPS-denied terrain to deliver ammunition and medical supplies. Estonian and Polish border defense modernization programs are accelerating unmanned ground vehicle adoption for territorial infrastructure support.
- Unmanned Combat Vehicles:Armed platforms mounting medium-caliber weapons with remote firing authorization.
- Reconnaissance Robots:Lightweight units with electro-optical and infrared payloads for forward observation.
- Surveillance Robots:Perimeter patrol systems with autonomous route planning and intruder detection algorithms.
By volume, EOD Robots lead. By growth pace, Logistics Robots are expanding most quickly.
Technology:
Cost tier stratification separates budget-constrained teleoperated systems from premium autonomous stacks requiring multi-year R&D investment.
- Autonomous Navigation:SLAM-based positioning with terrain-classification neural networks enables GPS-denied traversal. U.S. Army combat teams are field-testing these capabilities in contested electromagnetic environments, compressing operator-to-robot ratios from 2:1 toward 1:4 supervision architectures.
- Sensor Fusion:Multi-spectral integration of thermal, LiDAR, and acoustic inputs into unified operator interfaces commands premium pricing. NATO Standardization Office interoperability mandates are elevating compliance costs for vendors while creating preferred supplier status for pre-cleared architectures.
- Remote Operated Systems:Line-of-sight radio control with legacy backward compatibility requirements.
- Artificial Intelligence:Target recognition and decision-support algorithms subject to ethical engagement protocol restrictions.
- Machine Learning:Adaptive route optimization and threat pattern recognition trained on operational data.
Remote Operated Systems dominate current procurement volumes. Sensor Fusion is climbing the fastest as militaries prioritize reduced cognitive load on single operators.
Application:
Customer type determines specification intensity, with elite counter-terrorism units demanding hardened platforms and peacekeeping organizations prioritizing cost efficiency.
- Bomb Disposal:Platforms combining precision manipulation with blast containment for explosive ordnance neutralization. Cross-border tensions in Israel sustain concentrated investment in unmanned systems for counter-terrorism operations with autonomous patrol capabilities.
- Supply Transport:Autonomous convoy systems for ammunition, fuel, and medical resupply in denied environments. U.S. Department of Defense tightening ethical AI guidelines for autonomous weapons are reshaping vendor qualification requirements for logistics applications.
- Border Patrolling:Perimeter surveillance with intrusion detection and autonomous response protocols.
- Target Acquisition:Forward observation with laser designation and fire adjustment capabilities.
- Surveillance Missions:Persistent area monitoring with multi-spectral sensing and data relay.
Bomb Disposal holds the largest active fleet. Supply Transport is gaining share fastest as force protection priorities shift toward materiel movement.
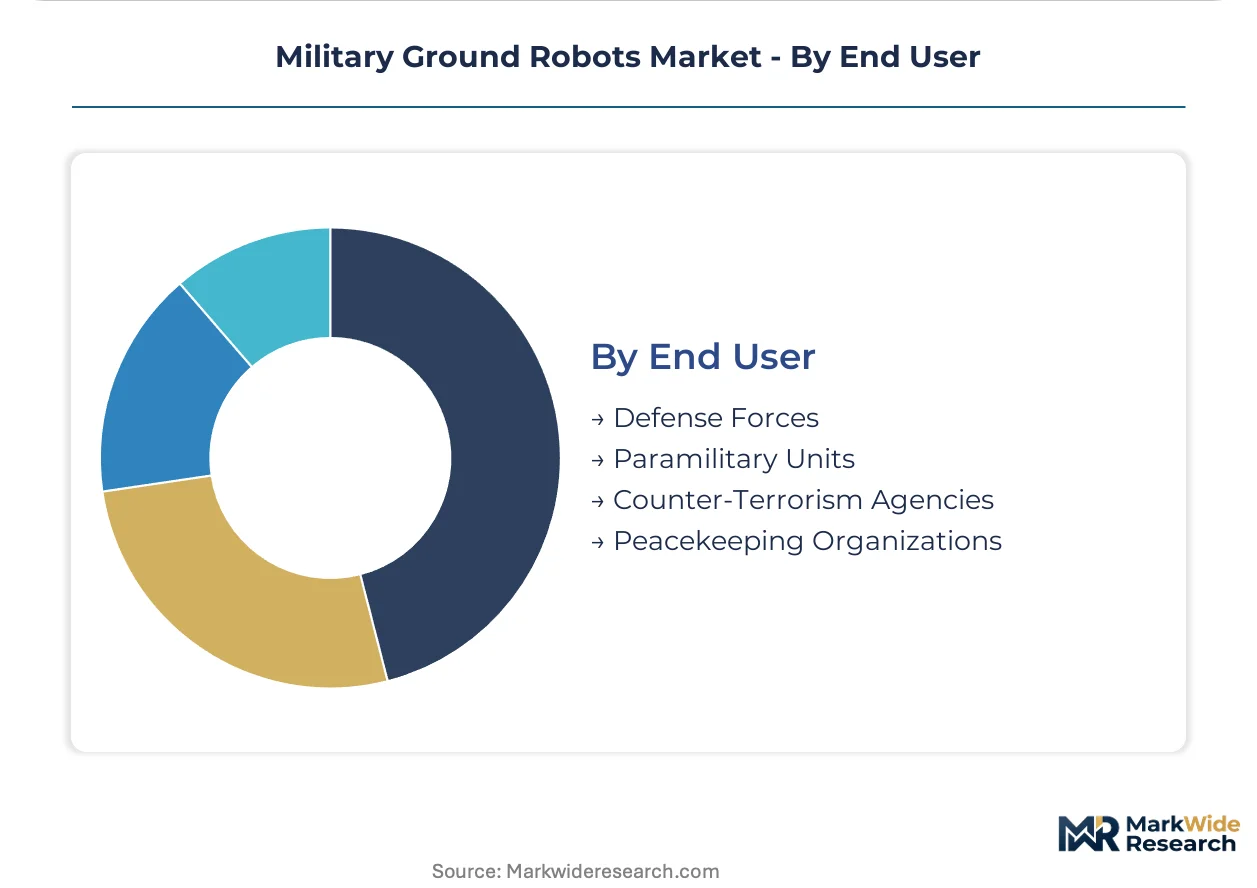
End User:
Maturity curves diverge by institutional sophistication, with established defense forces integrating autonomous systems and paramilitary units remaining dependent on teleoperated platforms.
- Defense Forces:National military services with formal acquisition programs and interoperability mandates. NATO member states are expanding procurement of autonomous systems for bomb disposal and perimeter security missions through joint framework agreements.
- Counter-Terrorism Agencies:Specialized units requiring rapid deployment and urban navigation capabilities. Israel's Ministry of Defense shapes procurement through autonomous engagement protocols that restrict certain AI-driven firing decisions.
- Paramilitary Units:Border guards and internal security forces with constrained budgets.
- Peacekeeping Organizations:Multinational deployments prioritizing standardization and supply chain simplicity.
Defense Forces account for the dominant procurement volume. Counter-Terrorism Agencies show the steepest expansion trajectory as asymmetric threats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense ministries in Israel and the United States prioritize autonomous perimeter patrol and counter-IED platforms, while European procurement concentrates on NATO interoperability certification and logistics modernization rather than armed unmanned systems.
United States
The U.S. Department of Defense drives procurement through ethical AI guidelines that reshape vendor qualification timelines for autonomous weapons. Army combat teams field-test GPS-denied navigation capabilities in contested electromagnetic environments during joint readiness exercises. Defense contractors cluster around Washington D.C.-area command centers and Boston robotics research corridors.
Israel
Cross-border territorial tensions sustain concentrated investment in unmanned ground systems for surveillance and counter-terrorism operations with autonomous patrol protocols. The Ministry of Defense shapes procurement through engagement restrictions on certain AI-driven firing decisions. Elbit Systems and Israel Aerospace Industries anchor industrial capacity in Haifa and Tel Aviv metropolitan engineering clusters.
Germany
Bundeswehr modernization programs prioritize NATO Standardization Office interoperability mandates for common command interfaces in joint operations. The EU AI Act imposes conformity assessment requirements on military ground robot exports to European defense ministries. Industrial robotics expertise concentrates in Bavaria's Munich-Stuttgart automation corridor.
Poland
NATO eastern flank border defense infrastructure accelerates unmanned ground system procurement for territorial security modernization. National defense ministry frameworks align with allied interoperability standards for cross-border joint procurement. Emerging robotics engineering capacity develops in Warsaw and Krakow technology parks.
Estonia
Frontline NATO positioning drives rapid adoption of autonomous logistics robots for ammunition and medical supply transport in denied environments. Defense innovation programs leverage digital government infrastructure for accelerated vendor testing. Tartu and Tallinn host concentrated cyber-physical systems research institutes.
Military Ground Robots Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with prime contractors commanding sole-source contracts for heavy combat vehicles while mid-tier vendors compete through distributor networks for portable EOD platforms. Defense robotics engineering workforce rotation toward autonomy software creates bottlenecks in traditional mechanical design roles. Two strategic archetypes dominate: vertically integrated primes with captive propulsion and command system production, and sensor fusion specialists with multi-spectral payload integration. Competitive moves concentrate on 10-15 year bundled lifecycle service contracts and backward integration into safety-critical algorithm validation capabilities.
Within the integrated prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify contrasting positioning strategies. Lockheed Martin leverages in-house production across propulsion and command systems to sustain long-term program contracts, while Northrop Grumman anchors its market position through R&D intensity in artificial intelligence-enabled target recognition. Elbit Systems Ltd. occupies a distinct geographic-specialist position, competing on field-proven logistics robot deployments concentrated in Middle Eastern operational theaters.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| BAE Systems |
| Elbit Systems Ltd. |
| Israel Aerospace Industries Ltd. |
| Teledyne Technologies Incorporated |
| L3Harris Technologies, Inc. |
| Saab AB |
| Others |
Pricing and Supply Chain Analysis
U.S. Department of Defense ethical AI certification gates both vendor qualification and price differentiation, compressing timelines for pre-cleared architectures while elevating compliance premiums for mid-tier suppliers unable to absorb validation costs.
Pricing Analysis
Long-term bundled lifecycle contracts dominate procurement, with 10-15 year service agreements supplanting discrete hardware transactions across NATO defense ministries. Price differentiation rests on autonomy software certification tier and sensor fusion payload integration, with field-proven platforms commanding substantial premiums over teleoperated alternatives. Cost compression in mid-weight combat vehicle segments intensifies as EU AI Act conformity assessments extend program schedules. Paramilitary units exhibit highest price sensitivity, while elite counter-terrorism agencies prioritize capability over unit economics.
Supply Chain Analysis
Strait of Hormuz transit risk underwrites concentrated sourcing of multi-spectral thermal and LiDAR components from Israel, the United States, and Germany. Critical inputs draw from gallium arsenide substrates, precision optics, and radiation-hardened semiconductors. Single-source vulnerability in autonomy software engineering clusters constrains development velocity outside Israeli and U.S. technology corridors. Distribution runs through prime contractor direct sales for heavy combat platforms and defense equipment distributors for portable EOD systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cycles exhibit cyclical recovery characteristics as NATO eastern flank modernization programs and sustained counter-IED requirements replenish order backlogs depleted during budget austerity periods.
For Market Incumbents: Fortify algorithm validation capabilities through backward integration into safety-critical SLAM and terrain-classification software stacks. Lockheed Martin's captive propulsion production and Northrop Grumman's R&D intensity in AI-enabled target recognition demonstrate viable defensive postures against emerging sensor fusion specialists threatening margin pools in multi-spectral payload integration.
For New Entrants and Emerging Players: NATO Standardization Office interoperability fast-tracks offer accelerated qualification pathways for vendors with pre-cleared command interface architectures. Estonian and Polish border defense modernization presents the most penetrable geographic entry point, with autonomous logistics robots for ammunition transport commanding unmet demand. Channel partnership with established defense equipment distributors reduces customer acquisition friction in portable EOD platform segments.
For Investors and Strategic Acquirers: U.S. DoD ethical AI guideline implementation reshapes the acquisition landscape toward vertically integrated primes with sustained field support infrastructure across dispersed operational theaters. Five-to-ten year viability favors entities combining autonomous navigation software development with multi-spectral payload manufacturing. Monitor EU AI Act third-party audit completion rates as inflection indicator for European defense ministry contract accessibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Bundled Lifecycle Service Contract Conversion | Captures recurring revenue streams across 10-15 year operational windows for NATO defense ministries. |
| Autonomy Software Certification Investment | Accelerates vendor qualification timelines under tightening U.S. DoD ethical AI engagement protocols. |
| Sensor Fusion Capability Integration | Commands premium pricing through multi-spectral thermal, LiDAR, and acoustic payload unification. |
| NATO Interoperability Architecture Alignment | Unlocks joint procurement frameworks across allied defense ministries in Estonia and Poland. |
| Urban Warfare Navigation Stack Development | Opens subterranean and dense-environment mission profiles beyond traditional line-of-sight constraints. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with defense procurement officers, autonomy software engineers, EOD team commanders, and prime contractor program managers; and secondary validation through NATO Standardization Office procurement databases, U.S. DoD budget justification documents, Israeli Ministry of Defense tender filings, and customs trade records for robotics component flows. Bottom-up platform deployment estimates triangulated against top-down defense ministry expenditure allocations.
Across the projection horizon, the analytical framework modeled volume and value trajectories by platform type, technology tier, mission application, and end-user institutional sophistication. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion bounds. Industry-specific forecast inputs incorporated GPS-denied navigation field-test schedules, EU AI Act implementation timelines, and NATO eastern flank border infrastructure investment commitments.
Decision-makers should treat outputs as directional under sustained asymmetric conflict conditions and stable defense budget trajectories; material deviation in territorial tension intensity or alliance spending cohesion would warrant model refresh. Practitioners should keep alternative scenarios live as ethical AI engagement protocol interpretations and swarming coordination protocol standardization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Japan Defense Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Colombia Defense Market
Military Vehicles
Iran Defense Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Military Amphibious Vehicle Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Infantry Fighting Vehicle (IFV) Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Taiwan Defense Market