
 Middle East Military Vehicles Market | 2026-2036
Middle East Military Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Military Vehicles Market Foresight
Border patrol and counter-insurgency operations is shifting toward heavier protected mobility across Middle Eastern armies. General Dynamics sustains its position through long-running MRAP and Stryker supply relationships with Gulf Cooperation Council members. Rheinmetall AG anchors German engineering credibility in the region via armored vehicle joint ventures and local production partnerships. BMC Otomotiv Sanayi ve Ticaret A.Ş. leverages Turkish geographic proximity and competitive pricing to compete for infantry fighting vehicle contracts in Iraq and Qatar.
Middle East military vehicles encompass wheeled and tracked platforms engineered to ballistic protection standards STANAG 4569 Level 3 or above, integrating composite armor, remote weapon stations, and diesel-hybrid propulsion for desert operational endurance. These platforms serve force projection, territorial defense, and internal security missions across arid and urban theaters. Armored Personnel Carriers lead procurement volume as militaries prioritize troop survivability against improvised explosive devices and anti-tank guided missiles. Electronics & Communication technology captures expanding budget share as networked battlefield management and counter-drone systems become mandatory. Army end users dominate absolute demand, though Paramilitary Forces represent the fastest-growing buyer segment for light tactical vehicles used in border surveillance.
Saudi Arabia's General Authority for Military Industries enforces local content requirements that reshape foreign OEM market access and compel joint ventures with SAMI. Turkey's Ministry of National Defense procurement standards and the UAE's Tawazun offset framework similarly condition technology transfer and in-country assembly obligations. Stakeholders must monitor how Gulf states balance NATO interoperability requirements against emerging Chinese and Russian platform alternatives in upcoming replacement cycles.
Market Dynamics
Gulf localization mandates are restructuring military vehicle procurement by forcing foreign OEMs into joint ventures with national champions, fundamentally altering how technology transfers and assembly rights are negotiated across Saudi Arabia, the UAE, and Qatar.
Growth Catalysts
- Saudi Vision 2030 localization thresholds:The General Authority for Military Industries mandates minimum local content ratios for armored vehicle contracts, compelling foreign suppliers to establish in-country production facilities and transfer welding, armor fabrication, and electronics integration capabilities to SAMI-aligned partners.
- Counter-drone integration requirements:Army end users across the Gulf now specify hard-kill active protection systems and electronic countermeasures as standard equipment on new armored personnel carriers, expanding platform electronics budgets and opening subsystem supplier opportunities.
- Legacy fleet age-out cycles:Mechanized brigades in Qatar and Kuwait face simultaneous replacement of 1980s-era wheeled and tracked platforms, concentrating demand for STANAG 4569 Level 4+ protected mobility solutions within a compressed procurement window.
Market Restraints
- Specialized armor steel supply concentration:High-hardness rolled homogeneous armor plate production concentrates among a limited set of European and South Korean mills, exposing vehicle integrators to price volatility and extended lead times for ballistic-grade material.
- Remote weapon station export licensing:German KBA and US State Department ITAR controls restrict transfer of stabilized turret and fire-control technologies to specific Middle Eastern end users, complicating platform configuration standardization across national fleets.
- Skilled welder and armorer scarcity:Local workforce development in Saudi Arabia and the UAE lags behind in-country assembly capacity expansion, constraining joint venture production ramp rates and forcing reliance on expatriate technical labor.
Strategic Opportunities
- Iraqi security force modernization:Baghdad's delayed mechanized infantry equipment programs represent underpenetrated demand for cost-optimized wheeled armored vehicles, with Turkish and South Korean suppliers positioned to capture volume through competitive pricing and faster delivery timelines.
- Diesel-hybrid propulsion adoption:Convergence of commercial automotive battery density improvements and military silent-watch requirements is creating specification space for hybrid-electric drivelines in next-generation reconnaissance and command vehicles.
- Paramilitary border surveillance expansion:Saudi Border Guard and UAE Federal Customs Authority procurement of light tactical vehicles for desert patrol missions opens a faster-growing buyer segment distinct from conventional army acquisition cycles.
Industry Challenges
- STANAG 4569 live-fire certification timelines:Ballistic and blast testing protocols for Level 3+ protection ratings require 18-24 month validation cycles at approved European facilities, compressing platform development schedules and delaying contract milestone payments.
- Legacy fleet interoperability integration:New armored vehicles must maintain communications and logistics compatibility with existing NATO-sourced and Eastern-origin platforms in service, complicating electronics architecture decisions and increasing subsystem qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Military Vehicles Market |
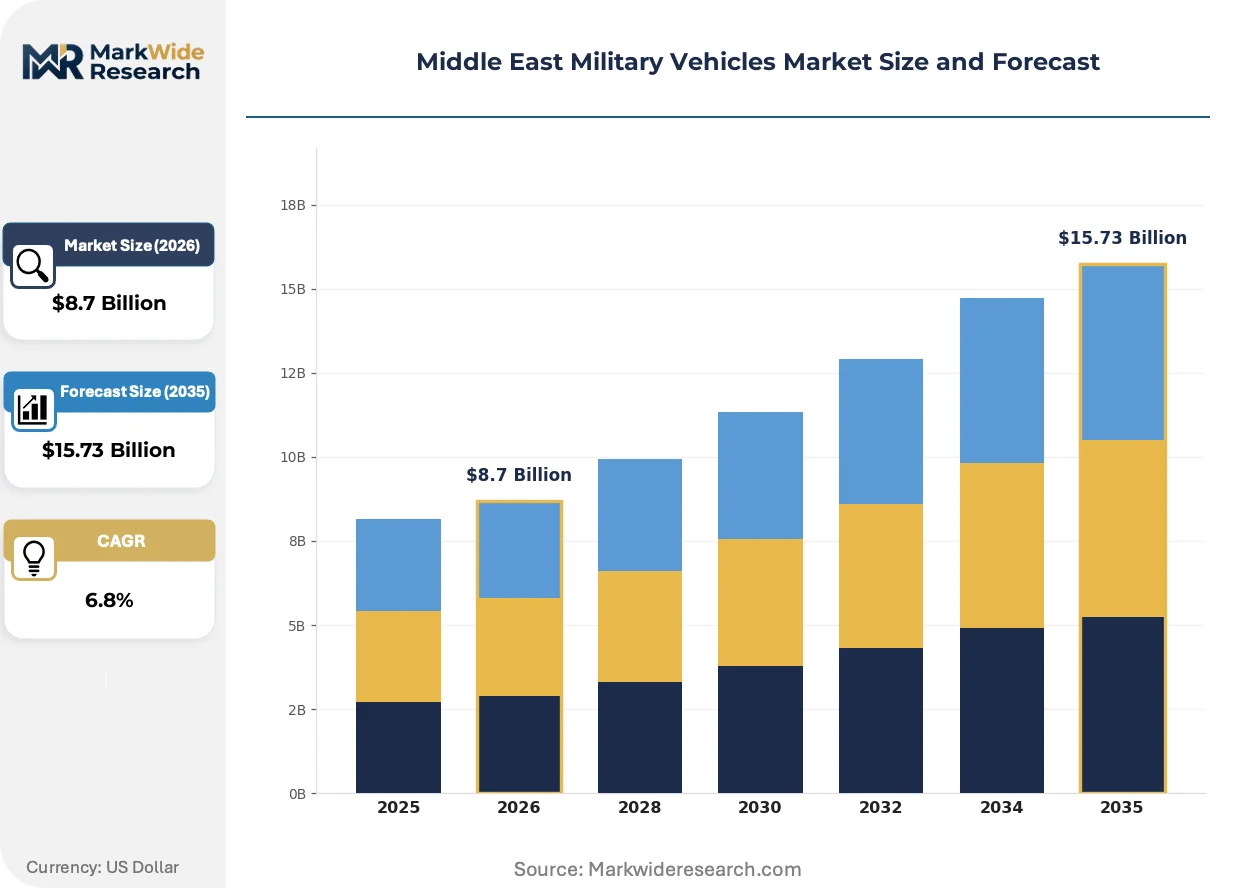
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Tanks, Armored Personnel Carriers, Combat Support Vehicles, Light Utility Vehicles Technology: Electronics & Communication, Weapon Systems, Propulsion Systems, Navigation Systems End User: Army, Navy, Air Force, Paramilitary Forces Deployment: Onshore, Offshore, Military Bases, Conflict Zones |
| Companies Covered | Saudi Arabian Military Industries (SAMI), General Dynamics, Rostec, Oshkosh Defense, Rheinmetall AG, Lockheed Martin Corporation, BMC Otomotiv Sanayi ve Ticaret A.Ş., Leonardo S.p.A., BAE Systems, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Military Vehicles Market Shifts & Advancements
Active protection systems and unmanned turret architectures are displacing conventional manned-gunner configurations across Gulf armored vehicle specifications, redefining platform crew layouts and survivability engineering priorities.
Composite armor packages incorporating ceramic tiles and ultra-high-molecular-weight polyethylene backing layers are modularizing vehicle protection schemes. Saudi and Emirati army technical teams now specify field-replaceable armor modules rather than integrated hull designs, enabling rapid battle-damage repair and threat-specific configuration changes. This modularity is compressing platform life-cycle costs and accelerating upgrade cycles.
The UAE's Tawazun offset framework and Saudi GAMI local content regulations are restructuring foreign OEM market access. Suppliers must now commit to technology transfer thresholds and in-country assembly volumes before contract award consideration, shifting competitive advantage toward partners with established regional joint ventures. Armored vehicle electronics and communication subsystems face the most stringent localization requirements.
Direct commercial sales channels are displacing traditional foreign military sale routes for wheeled protected mobility platforms. Qatari and Kuwaiti procurement offices now favor government-to-government negotiations with OEMs over US Defense Security Cooperation Agency intermediation, shortening decision timelines but requiring suppliers to navigate bilateral financing and warranty arrangements. This pattern is most visible in light tactical vehicle categories where NATO interoperability certification carries less weight.
Middle East Military Vehicles Market Segmentation
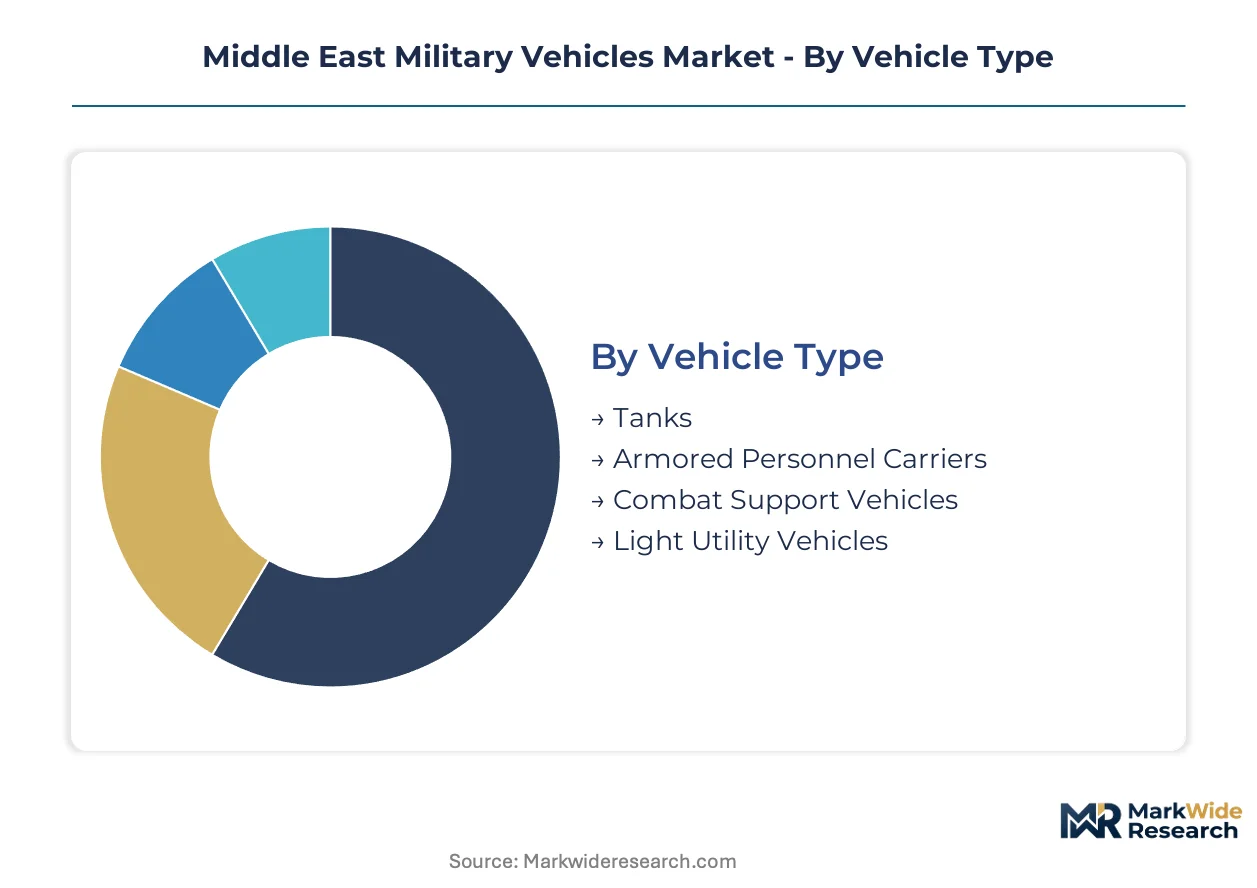
Segmentation in the Middle East military vehicles market reveals how procurement budgets allocate across platform types, technology tiers, and operational environments. Understanding these divisions exposes where localization mandates and interoperability requirements create divergent supplier strategies across Saudi Arabia, the UAE, and Qatar.
Vehicle Type:
Capital intensity varies sharply across vehicle categories, with tracked platforms demanding 3-4x the upfront investment of wheeled alternatives due to powertrain complexity and armor integration requirements.
- Armored Personnel Carriers:These platforms integrate STANAG 4569 Level 3+ ballistic hulls with modular composite armor packages and remote weapon stations. Saudi Arabian and Qatari army mechanized brigades concentrate procurement here as legacy fleet replacements accelerate. GAMI localization thresholds compel foreign OEMs to transfer welding and electronics integration capabilities to SAMI-aligned joint ventures.
- Tanks:Main battle tanks incorporate 120mm smoothbore cannons, heavy composite armor arrays, and diesel-hybrid powerpacks engineered for desert endurance. The UAE and Saudi Arabia prioritize these for force projection capabilities, though procurement volumes trail armored personnel carriers due to higher unit costs and extended development timelines.
- Combat Support Vehicles:Recovery, engineering, and bridging variants extend mechanized unit operational reach. These platforms absorb specialized subsystem integration costs.
- Light Utility Vehicles:Wheeled tactical transports for reconnaissance and command functions carry lower armor ratings but faster procurement cycles. Saudi Border Guard and UAE Federal Customs Authority demand concentrates in paramilitary configurations.
Armored personnel carriers absorb the bulk of installed capacity; light utility vehicles are expanding most quickly.
Technology:
Technology segmentation tracks where electronics budgets concentrate as platform digitization redefines combat effectiveness standards across Gulf armies.
- Electronics & Communication:Battlefield management systems, secure tactical radios, and counter-drone electronic warfare suites now capture expanding budget share. Saudi and Emirati specifications mandate hard-kill active protection integration, with Tawazun and GAMI frameworks imposing the strictest localization requirements on this category. Army end users drive volume as networked warfare capabilities become non-negotiable.
- Weapon Systems:Stabilized turrets, fire-control computers, and remote weapon stations determine platform lethality. German KBA and US State Department ITAR licensing restrictions complicate standardization across national fleets.
- Propulsion Systems:Diesel-hybrid drivelines are gaining specification traction for silent-watch reconnaissance missions. Commercial battery density improvements enable military adoption.
- Navigation Systems:GPS-denied positioning and inertial guidance packages support operations in contested electromagnetic environments. These subsystems face fewer localization mandates than electronics.
Electronics & communication commands the largest technology budget allocation; propulsion systems are climbing the fastest as hybrid specifications proliferate.
End User:
Customer type segmentation exposes divergent procurement timelines, with conventional military branches operating on multi-year capital cycles while paramilitary forces accelerate tactical vehicle acquisitions.
- Army:Mechanized infantry and armored divisions dominate absolute demand volume across Saudi Arabia, the UAE, and Qatar. These end users specify STANAG 4569 Level 4+ protection and NATO interoperability as baseline requirements. Legacy fleet age-out cycles in Qatari and Kuwaiti brigades compress procurement windows.
- Paramilitary Forces:Saudi Border Guard and UAE Federal Customs Authority procurement operates on faster acquisition timelines with lighter protection requirements. Desert patrol and border surveillance missions drive wheeled tactical vehicle demand distinct from conventional army cycles.
- Navy:Marine expeditionary units and coastal defense formations require amphibious-capable platforms with corrosion-resistant hull treatments. Procurement volumes trail army demand significantly.
- Air Force:Base security and airfield defense units prioritize rapid-response light vehicles over heavy armor. These requirements align more closely with paramilitary specifications than army mechanized standards.
Army end users absorb the bulk of installed capacity; paramilitary forces are gaining share fastest as border security budgets expand.
Deployment:
Operational environment segmentation determines platform engineering priorities, with desert theater requirements dominating Gulf procurement specifications.
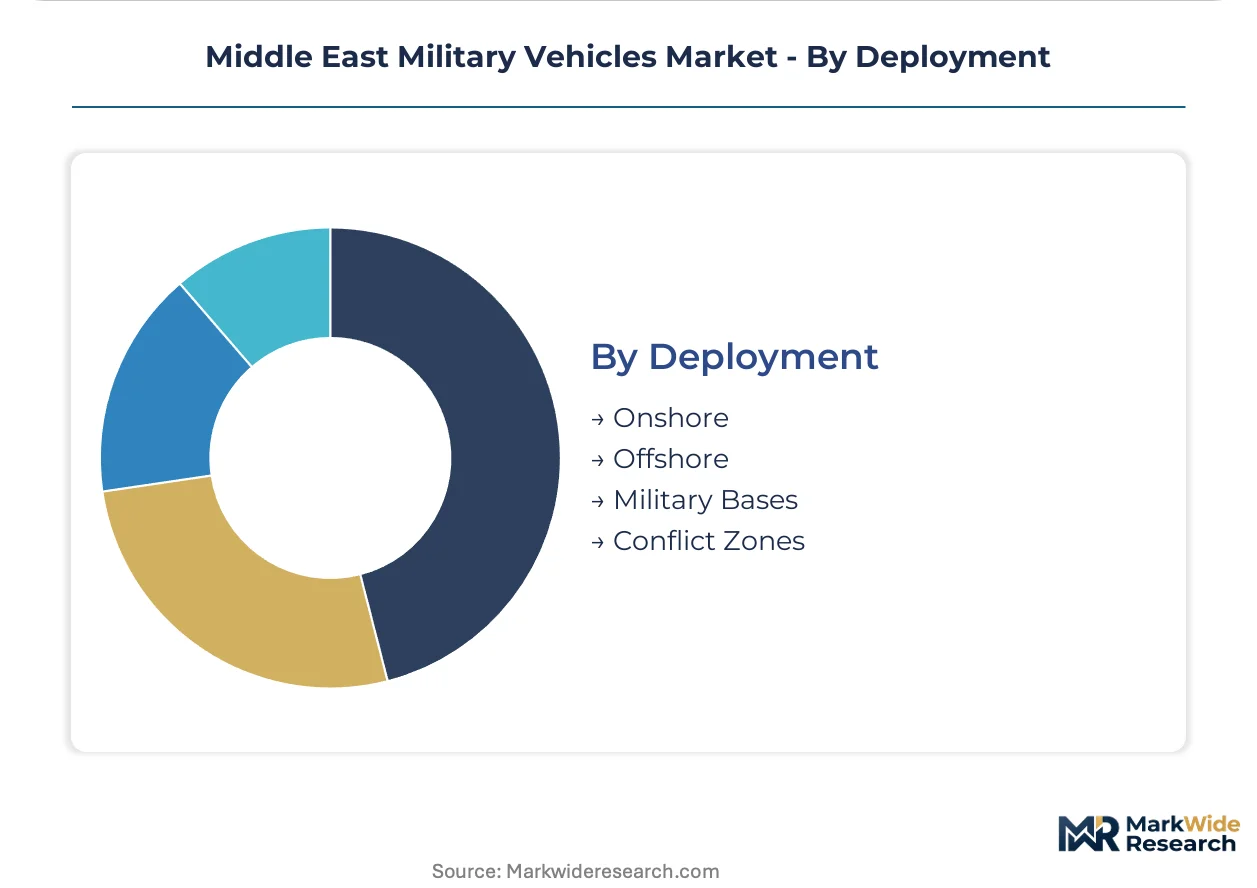
- Onshore:Desert patrol and territorial defense missions across Saudi Arabia's northern border and UAE's Rub' al Khali drive dust filtration, cooling system, and sand-resistant seal specifications. These operational demands are reshaping vehicle engineering priorities for all suppliers.
- Military Bases:Internal security and force protection roles require urban-optimized platforms with maneuverability in confined spaces. Base defense procurement concentrates in Qatar and Kuwait.
- Conflict Zones:Active theater deployment demands hardened electronic countermeasures and improvised explosive device protection packages. Iraqi security force modernization programs represent emerging demand.
- Offshore:Maritime prepositioning and island defense requirements affect a limited subset of UAE and Qatari procurement. These deployments impose saltwater corrosion standards on platform materials.
Onshore deployment specifications absorb the bulk of engineering resources; military base applications are expanding most quickly as internal security priorities shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Turkey and Saudi Arabia, while consumption demand clusters in the Gulf Cooperation Council states. Localization mandates are redrawing traditional supply routes as foreign OEMs establish joint ventures with national champions.
Saudi Arabia
Vision 2030 mechanization programs and legacy M113 fleet replacements drive armored personnel carrier procurement. The General Authority for Military Industries enforces minimum local content ratios through SAMI joint ventures. Riyadh's Military Industrial Complex hosts welding and electronics integration facilities transferring capabilities from Rheinmetall AG and Lockheed Martin Corporation partnerships.
United Arab Emirates
Force projection requirements and border surveillance modernization sustain demand for wheeled protected mobility. The Tawazun offset framework conditions contract awards on technology transfer and in-country assembly volumes. Abu Dhabi's Tawazun Services Center coordinates armored vehicle subsystem localization with European and Turkish suppliers.
Qatar
Mechanized brigade expansion and 1980s-era platform age-outs compress procurement timelines for STANAG 4569 Level 4+ vehicles. Qatar Armed Forces procurement offices favor direct commercial sales over foreign military sale intermediation. Doha's Barzan Holdings negotiates government-to-government agreements with OEMs for rapid delivery schedules.
Turkey
BMC Otomotiv Sanayi ve Ticaret A.Ş. leverages geographic proximity and competitive pricing to supply Iraqi and Qatari infantry fighting vehicle contracts. The Ministry of National Defense procurement standards emphasize NATO interoperability with regional cost optimization. Sakarya's vehicle production facilities anchor Anatolia's armored platform manufacturing cluster.
Iraq
Delayed security force modernization programs create underpenetrated demand for cost-optimized wheeled armored vehicles. Baghdad's defense procurement operates outside strict Gulf localization frameworks, enabling faster Turkish and South Korean supplier access. Basra's logistics corridors facilitate regional distribution of tactical platforms to Iraqi mechanized units.
Middle East Military Vehicles Market Competitive Landscape
Top-tier vendors anchor long-running Gulf supply relationships, while mid-tier regional specialists compete on localization compliance and delivery speed. The vendor base stratifies across NATO-aligned system integrators, Turkish cost-optimized producers, and emerging national champions. Three archetypes dominate: legacy relationship holders with established maintenance networks, joint venture partners with in-country assembly rights, and modular subsystem suppliers capturing electronics localization mandates. Competitive moves concentrate on strategic partnerships with SAMI and Tawazun entities, plus capacity expansion into Saudi and Emirati industrial zones.
Among the established relationship holders, General Dynamics exemplifies the legacy Gulf supplier archetype through sustained MRAP and Stryker program presence. Rheinmetall AG occupies a position representing German engineering credibility via regional armored vehicle joint ventures. BMC Otomotiv Sanayi ve Ticaret A.Ş. sits within the geographic-proximity specialist tier, competing for contracts in Iraq and Qatar through competitive positioning and faster fulfillment timelines.
| Leading Market Players |
|---|
| Saudi Arabian Military Industries (SAMI) |
| General Dynamics |
| Rostec |
| Oshkosh Defense |
| Rheinmetall AG |
| Lockheed Martin Corporation |
| BMC Otomotiv Sanayi ve Ticaret A.Ş. |
| Leonardo S.p.A. |
| BAE Systems |
| Others |
Supply & Pricing Matrix
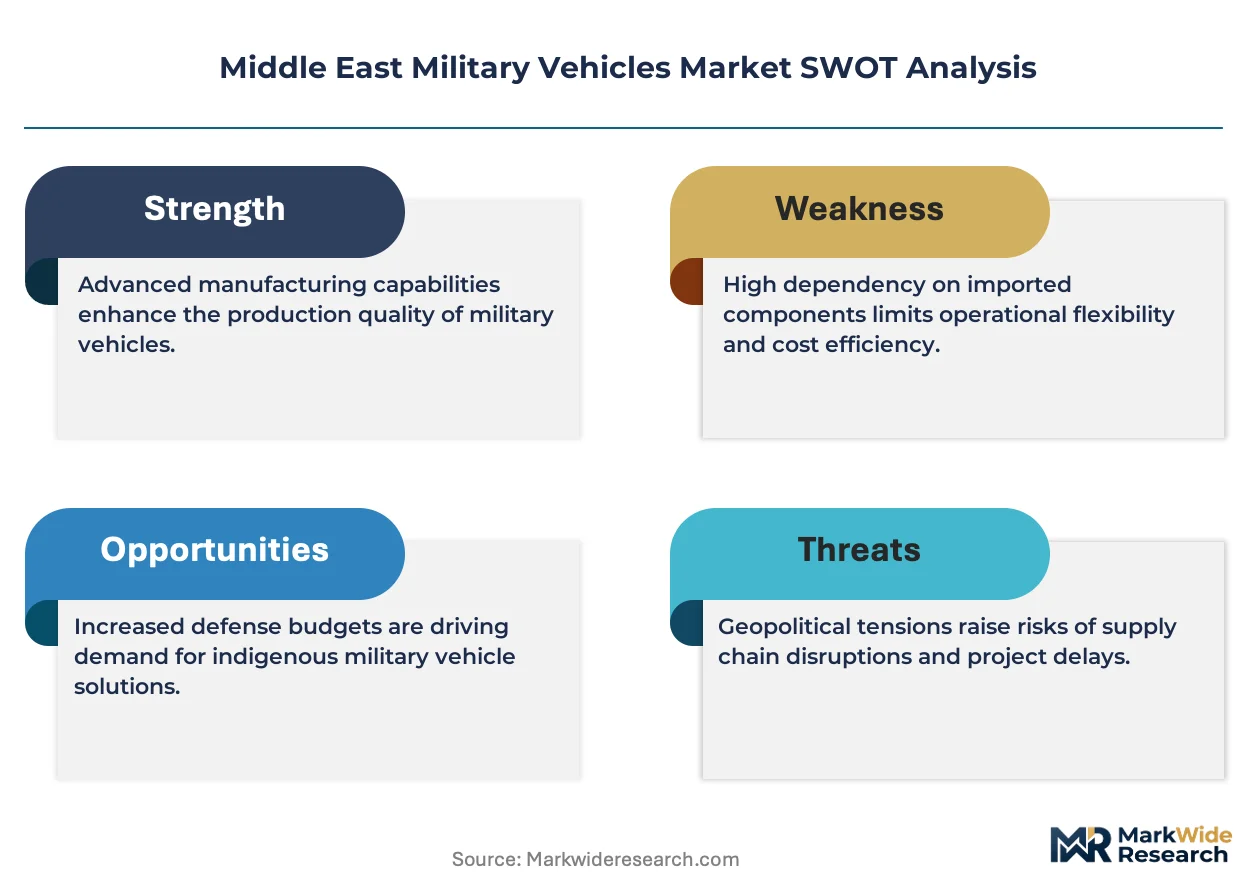
High-hardness rolled homogeneous armor plate indices cascade through Middle Eastern military vehicle supply chains, compressing margins for integrators while amplifying price premiums for STANAG 4569 Level 4+ certified platforms with modular composite armor packages.
Pricing Analysis
Cost-down pressure on wheeled armored vehicle tiers accelerates because Turkish and South Korean suppliers undercut NATO-aligned OEMs on delivery timelines. Three-tier pricing structure across premium, standard, and economy levels separates Rheinmetall AG and General Dynamics from BMC Otomotiv and emerging regional assemblers. Certification grade and volume scale drive price differentiation, with GAMI-mandated local content ratios adding assembly cost premiums. Paramilitary border surveillance buyers exhibit highest price sensitivity; Saudi mechanized brigades prioritize protection ratings over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle Gulf defense procurement demand, with government-to-government negotiations displacing traditional foreign military sale intermediation. High-hardness armor plate production concentrates in Germany, South Korea, and selected European mills, while electronics integration capabilities cluster in Turkey and Saudi Arabia's emerging industrial zones. Vehicle integrators draw from ceramic tile suppliers, ultra-high-molecular-weight polyethylene backing producers, and diesel-hybrid battery providers. Single-source vulnerability in specialized armor steel exposes integrators to extended lead times. Distribution runs through national champions SAMI and Tawazun-aligned joint ventures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active protection systems and unmanned turret architectures are displacing manned-gunner configurations across Gulf armored vehicle specifications, forcing stakeholders to recalibrate around electronics integration capabilities and hard-kill subsystem sourcing.
For Market Incumbents: Cement long-running maintenance network advantages by embedding technical training within SAMI and Tawazun joint venture facilities. Deepen backward integration into armor fabrication to offset European mill price volatility. Counter Turkish cost-optimized entrants through accelerated STANAG 4569 certification timelines and pre-positioned spare parts inventories. For New Entrants and Emerging Players: GAMI localization mandates in Saudi Arabia open a window for modular subsystem suppliers specializing in battlefield management electronics and counter-drone integration. Target Iraqi security force modernization programs where procurement operates outside strict Gulf content frameworks. Penetrate through direct commercial sales channels favored by Qatari procurement offices for rapid contract execution. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed European armor component specialists with transferable welding certifications and existing KBA export licensing. Long-term viability hinges on positioning within Saudi and Emirati industrial zone expansions. Monitor German KBA and US State Department ITAR control relaxation as inflection signal for stabilized turret technology transfer opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Localization | GAMI and Tawazun frameworks compel foreign OEMs to transfer welding and electronics capabilities to SAMI-aligned partners. |
| Active Protection System Integration | Hard-kill and electronic countermeasure subsystems capture expanding platform budgets as Gulf armies specify counter-drone mandates. |
| Diesel-Hybrid Propulsion Development | Commercial battery density improvements enable silent-watch specifications for next-generation reconnaissance and command vehicles. |
| Direct Commercial Sales Channel | Qatari and Kuwaiti procurement offices favor government-to-government OEM negotiations over DSCA intermediation. |
| Modular Armor Package Standardization | Field-replaceable ceramic tile and polyethylene configurations reduce life-cycle costs and accelerate battle-damage repair. |
Research Methodology
Independent corroboration across primary interviews with defense procurement officers, joint venture production managers, and subsystem engineering directors, combined with secondary validation through customs import records, national defense budget disclosures, and STANAG certification registries, underwrites the qualitative findings. Bottom-up platform delivery estimates triangulate against top-down military expenditure allocations across Saudi Arabia, the UAE, Qatar, and Turkey.
Comparable-period anchoring to legacy fleet age-out cycles and mechanized brigade expansion timelines structures the projection horizon. The analytical framework models vehicle type, technology tier, end-user classification, and deployment environment segmentation throughout the forecast period. CAGRs derive from fitted trend extrapolation against documented contract award volumes and announced localization capacity buildouts. Diesel-hybrid propulsion adoption curves and counter-drone subsystem penetration rates constitute industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for unmanned turret architectures and active protection system standardization would alter the outlook. Forecasts reflect documented contract milestones, localization compliance timelines, and export licensing approval assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Taiwan Defense Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Indonesia Defense Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Japan Defense Market
Military Vehicles
Destroyers Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Russia Defense Market
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Military Ground Vehicle Actuators Market