
 Military Amphibious Vehicle Market | 2026-2036
Military Amphibious Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Military Amphibious Vehicle Market Foresight
REACH compliance is decoupling European suppliers from legacy material streams and forcing reformulation of hull coatings and sealing compounds. BAE Systems plc leverages its shipyard integration to sustain full-lifecycle contracts across British and Commonwealth fleets. Rheinmetall AG anchors Central European supply through its amphibious bridging and armored swimmer programs. General Dynamics Corporation competes on scale, dominating US Navy Expeditionary Fighting Vehicle replacements with integrated digital architecture.
Military amphibious vehicles combine watertight hull geometry with tracked or wheeled propulsion, typically achieving water speeds of 8-12 knots while carrying 10-25 personnel or equivalent payload across surf zones and inland waterways. Personnel carriers occupy the largest installed base, though reconnaissance vehicles represent the fastest-growing segment as unmanned turret integration and sensor fusion expand mission versatility. Diesel propulsion retains dominance in operational use, yet electric fuel types are gaining structural share in coastal patrol and special operations variants where acoustic signature reduction determines mission success.
The US Marine Corps Force Design 2030, the EU Green Deal defense procurement guidelines, and NATO standardization agreements (STANAG) collectively shape platform requirements, export eligibility, and interoperability mandates. The US Department of Defense and European Defence Agency coordinate certification protocols that determine which manufacturers qualify for cross-border tendering. Stakeholders must monitor how battery-electric range specifications and littoral connectivity standards rewrite qualification thresholds before next-generation procurement cycles lock in supplier rosters.
Market Dynamics
Force Design 2030 is compressing platform weight ceilings while expanding water-speed requirements, forcing manufacturers to reconcile contradictory engineering constraints through novel hull geometries and power-dense propulsion architectures.
Growth Catalysts
- EU Green Deal defense procurement guidelines:Carbon-emission thresholds for naval auxiliary fleets are accelerating electric-hybrid development programs across NATO littoral commands.
- Marine expeditionary units:Island-chain contingency planning in the Indo-Pacific theater is generating expeditionary readiness investments from Australia, Japan, and the Philippines.
- Advanced composite armor:Ceramic-matrix panels are replacing steel appliqué, yielding 15-20% hull-weight reductions without sacrificing ballistic protection levels.
Market Restraints
- High-grade aluminum alloy supply:5083-H116 plate availability concentrates in Norwegian and Russian smelter networks, creating input-cost volatility for hull fabricators.
- Waterproof sealing compound chemistry:REACH authorization restrictions on isocyanate-based formulations are forcing multi-year reformulation cycles without proven marine-equivalent substitutes.
- Tracked propulsion maintenance:Salt-water immersion intervals below 72 hours demand specialized corrosion-prevention protocols that extend turnaround times versus wheeled alternatives.
Strategic Opportunities
- Indonesia's maritime security expansion:Archipelagic geography and coastal patrol modernization programs create demand for shallow-draft, high-payload platforms with indigenous assembly provisions.
- Unmanned turret integration:Remote weapon stations with AI-assisted target tracking are opening reconnaissance-vehicle segments previously served by manned scout formations.
- NATO STANAG 4569 harmonization:Ballistic and blast-protection certification alignment is reducing re-engineering costs for cross-border tender participation.
Industry Challenges
- Marine electrical systems integration:Salt-water ingress protection for high-voltage battery architectures demands IP67+ sealing expertise scarce in legacy armored-vehicle engineering teams.
- Multi-domain certification timelines:Concurrent naval seaworthiness and land-mobility qualification protocols extend development schedules by 18-24 months versus single-domain platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Amphibious Vehicle Market |
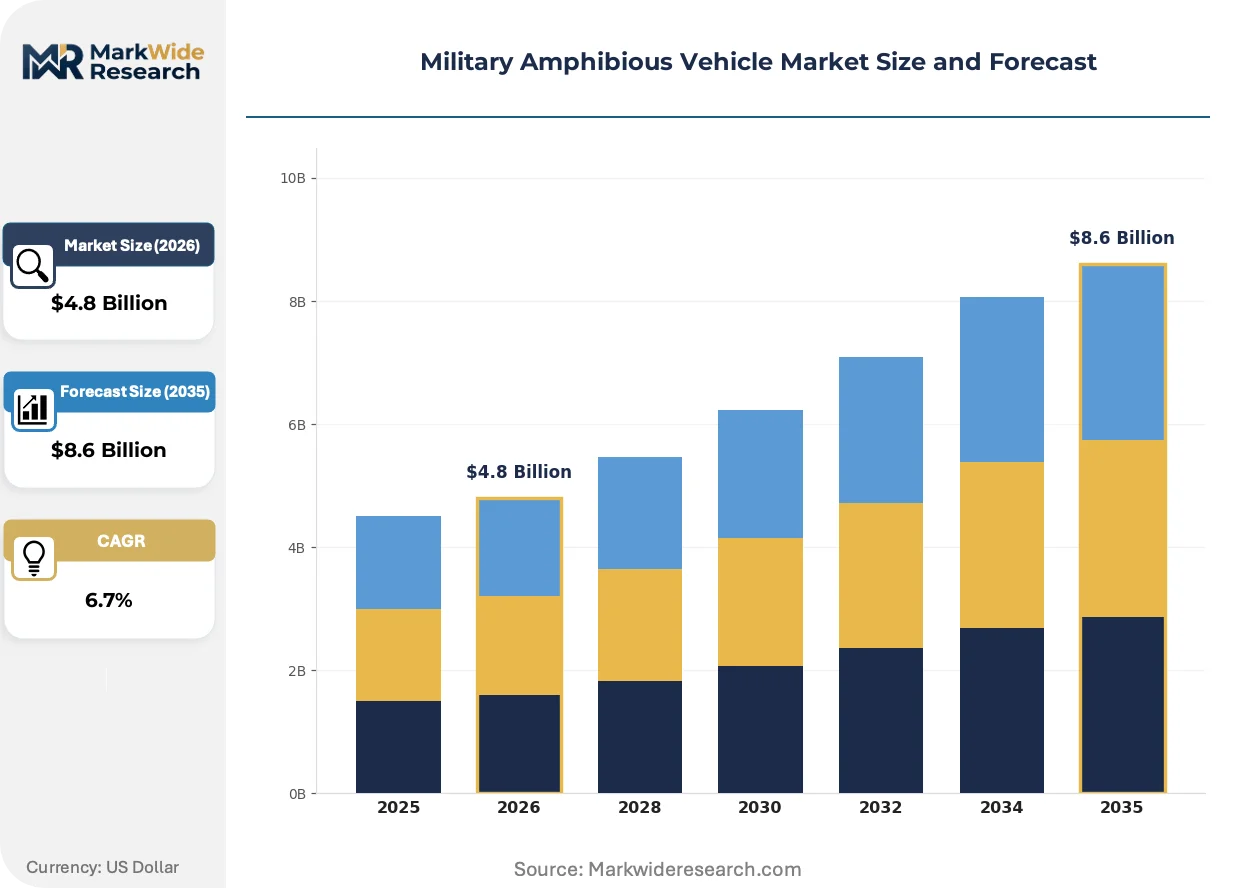
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Landing Craft, Payload Carrier, Reconnaissance Vehicle, Personnel Carrier Operational Use: Amphibious Assault, Logistics Support, Search and Rescue, Reconnaissance Missions End User: Military Forces, Special Operations, Coast Guard, Defense Contractors Fuel Type: Diesel, Jet Fuel, Biodiesel, Electric |
| Companies Covered | BAE Systems plc, General Dynamics Corporation, Rheinmetall AG, Textron Systems Corporation, Griffon Hoverwork Ltd, Lockheed Martin Corporation, Iveco Defence Vehicles, Hanwha Aerospace, Oshkosh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Amphibious Vehicle Market Shifts & Advancements
Platform architecture is converging around modular mission packages, where hull structures accommodate interchangeable sensor, weapon, and propulsion modules rather than fixed configurations.
Integrated digital backbone architectures are unifying power management, navigation, and situational awareness systems onto single Ethernet-based networks. Marine expeditionary units are mandating these open-standard interfaces for fleet-commonality. This convergence is unifying previously siloed subsystem suppliers into integrated prime-contractor teams.
REACH compliance deadlines for hull-coating biocides are forcing reformulation of anti-fouling compounds across European supplier bases. ECHA substance-of-very-high-concern listings are eliminating copper-based alternatives faster than replacement chemistries mature. Coastal patrol variants operating in EU territorial waters face accelerated dry-dock intervals until compliant coatings achieve operational parity.
Acquisition authorities are consolidating platform decisions under joint-program offices spanning multiple service branches. Traditional single-service procurement channels are ceding authority to cross-functional evaluation boards in the US Department of Defense and equivalent structures in Australia and the United Kingdom. This institutional concentration is compressing vendor access points and elevating full-lifecycle cost models over unit-acquisition pricing in source-selection criteria.
Military Amphibious Vehicle Market Segmentation
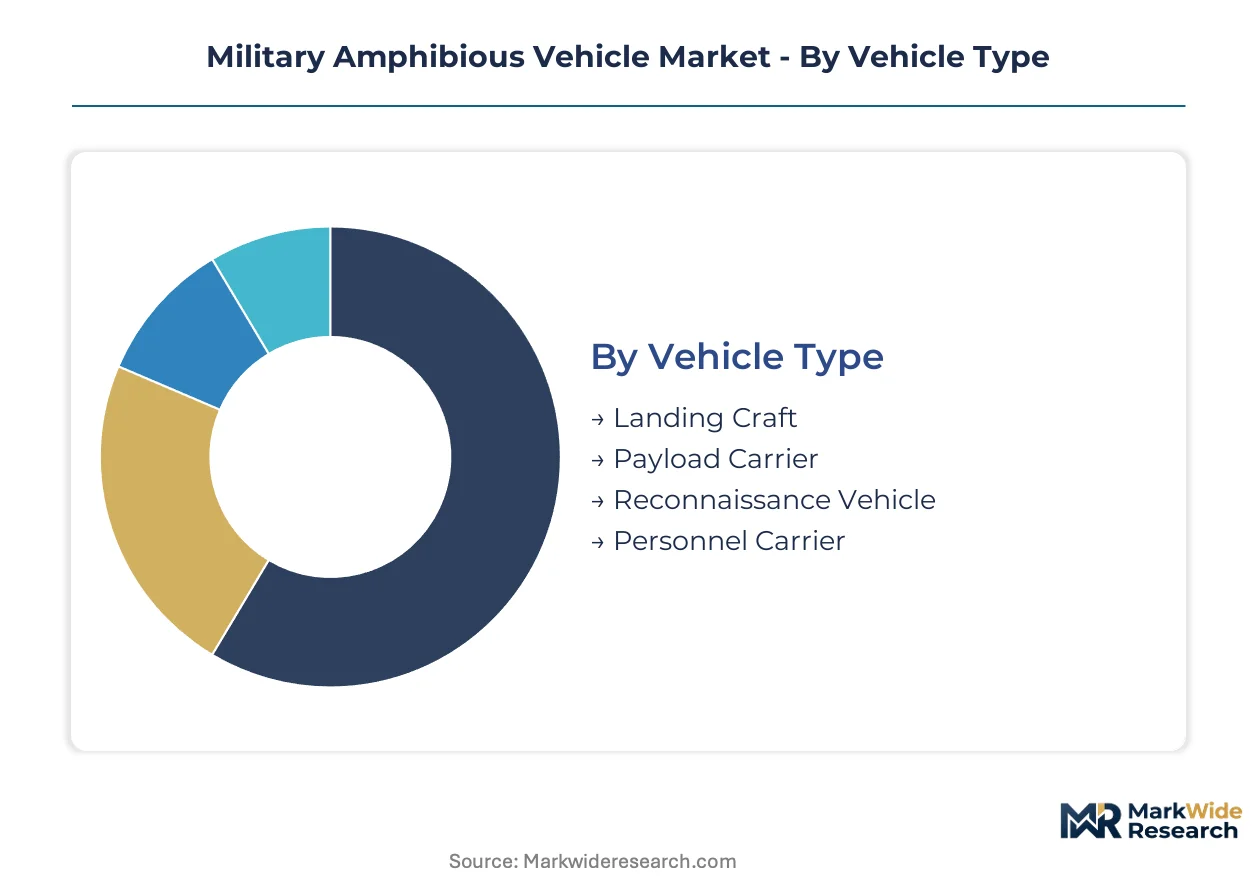
Platform specialization in military amphibious vehicles reflects divergent mission profiles across littoral warfare, expeditionary logistics, and coastal security operations. Procurement authorities segment requirements by payload capacity, water-speed thresholds, and deployability constraints rather than pursuing universal platforms.
Vehicle Type:
Standardized hull geometries dominate high-volume procurement, while mission-specific variants command premium pricing through specialized sensor and propulsion packages.
- Personnel Carrier:Watertight hulls with 10-25 troop capacity and 8-12 knot water speeds form the backbone of marine expeditionary unit equipment. US Marine Corps Force Design 2030 weight ceilings are compressing procurement toward lighter tracked configurations with reduced air-transport footprint.
- Reconnaissance Vehicle:Unmanned turret integration and sensor fusion architectures are expanding mission versatility for scout formations. Demand concentrates in Indo-Pacific theater investments where island-chain contingencies require low-signature coastal surveillance.
- Landing Craft:Shallow-draft hulls with high-volume payload bays support ship-to-shore logistics at scale.
- Payload Carrier:Modular deck configurations accommodate containerized equipment and vehicle transport across surf zones.
Most installed capacity flows through Personnel Carrier configurations. Expansion is steepest in Reconnaissance Vehicle segments.
Operational Use:
Cost tiers separate kinetic operations from support functions, with assault missions commanding integrated armor and weapons systems while logistics variants optimize for fuel efficiency and maintenance intervals.
- Amphibious Assault:Combined arms operations require ballistic protection, stabilized weapon stations, and networked command systems. NATO STANAG 4569 certification alignment is reducing re-engineering costs for cross-border tender participation in assault platform procurement.
- Logistics Support:Cargo-configured hulls with reduced armor weight maximize payload-to-displacement ratios for sustainment operations. EU Green Deal defense procurement guidelines are accelerating electric-hybrid development programs for coastal auxiliary fleets in this segment.
- Search and Rescue:Open-deck configurations with medical evacuation capabilities serve humanitarian and disaster response missions.
- Reconnaissance Missions:Low-acoustic signature propulsion and reduced radar cross-section prioritize stealth over protection.
Amphibious Assault absorbs the largest procurement budgets. Logistics Support is gaining share fastest as expeditionary readiness investments expand sustainment fleet modernization.
End User:
Customer type determines specification stringency, with frontline military forces mandating full-spectrum survivability while coast guard and contractor fleets accept reduced protection for cost and availability.
- Military Forces:Marine expeditionary units and army amphibious brigades require multi-domain certification for naval seaworthiness and land-mobility protocols. Indonesia's maritime security expansion is creating demand for shallow-draft, high-payload platforms with indigenous assembly provisions.
- Special Operations:Acoustic signature reduction and reduced visual/IR signatures determine mission success for coastal infiltration. Electric fuel types are gaining structural share in this segment where stealth characteristics override range limitations.
- Coast Guard:Patrol-configured platforms prioritize endurance and search-and-rescue equipment over armor.
- Defense Contractors:Lease and service-based procurement models emphasize availability guarantees and lifecycle cost predictability.
Military Forces maintain dominant procurement volume. Special Operations represents the fastest-climbing segment as unmanned systems integration expands mission sets.
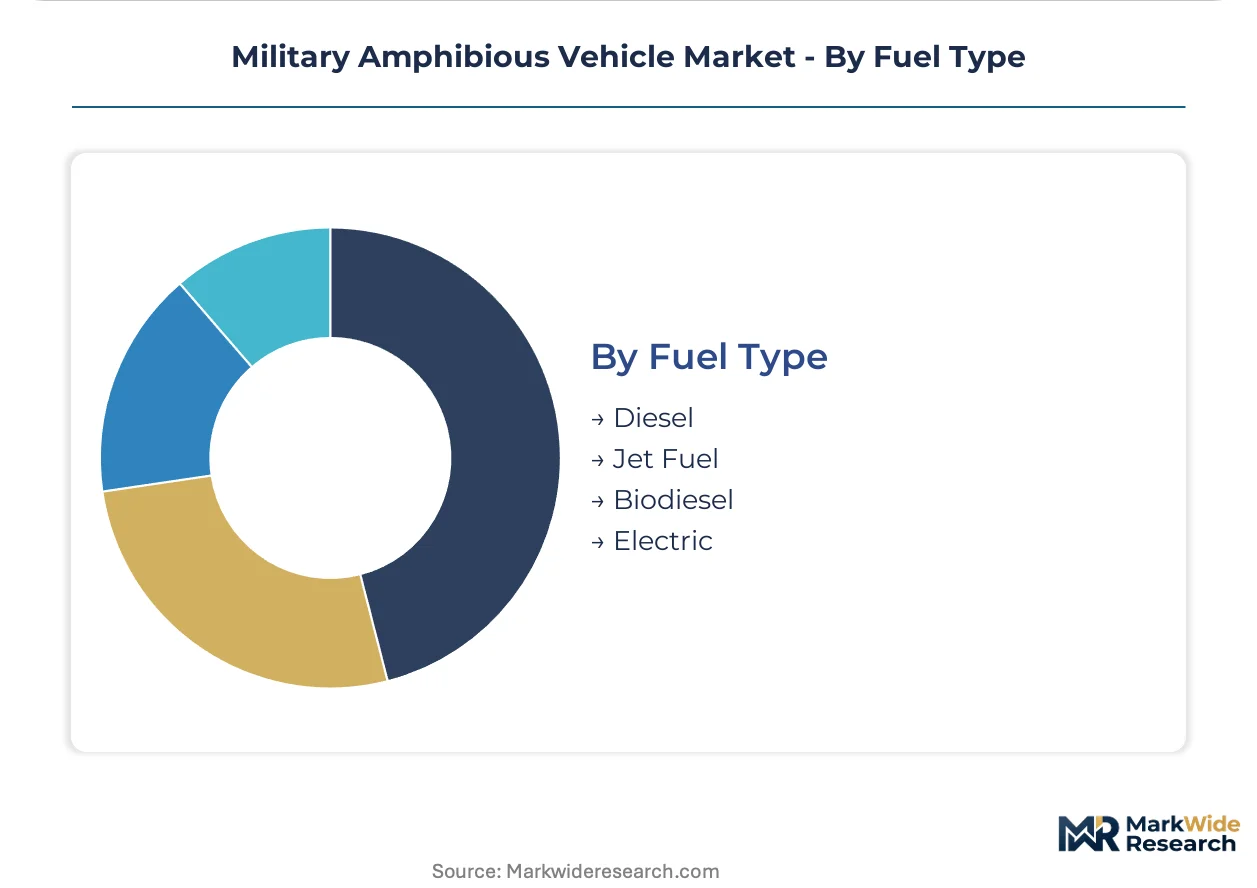
Fuel Type:
Maturity curves separate proven diesel architectures from emerging electric alternatives, with transition timelines determined by battery energy density improvements and charging infrastructure in expeditionary settings.
- Diesel:Compression-ignition engines with marine-grade cooling and sealing systems retain operational dominance across NATO and allied fleets. High-grade aluminum alloy supply constraints in 5083-H116 plate are creating input-cost volatility for hull fabricators serving diesel-powered platforms.
- Electric:High-voltage battery architectures with IP67+ sealing expertise are penetrating coastal patrol and special operations variants. REACH compliance deadlines for hull-coating biocides are forcing parallel reformulation of electrical system corrosion protection across European supplier bases.
- Jet Fuel:Turbine propulsion enables higher water speeds for rapid ship-to-shore transit.
- Biodiesel:Drop-in renewable alternatives are piloting in garrison training fleets with established fuel logistics.
Diesel propulsion carries the largest installed base. Electric configurations are expanding most quickly as acoustic signature requirements tighten in reconnaissance and special operations roles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amphibious warfare doctrine crystallized during Pacific theater operations in the 1940s, with the United States Marine Corps establishing the foundational requirements for ship-to-shore maneuver that persist in contemporary platform specifications.
United States
Marine expeditionary units drive procurement under Force Design 2030 modernization, compressing weight ceilings while expanding water-speed thresholds. The Department of Defense coordinates certification protocols through joint-program offices spanning multiple service branches. Industrial activity concentrates in Michigan and Virginia, where prime contractors integrate digital backbone architectures for next-generation expeditionary platforms.
United Kingdom
Commonwealth fleet sustainment and littoral readiness investments sustain demand for full-lifecycle contracts. BAE Systems plc leverages shipyard integration capabilities across British and allied naval programs. Manufacturing clusters in Barrow-in-Furness and Glasgow anchor hull fabrication and systems integration for amphibious bridging and armored swimmer variants.
Germany
Central European supply chains for amphibious bridging equipment anchor Rheinmetall AG's market position. REACH compliance deadlines for hull-coating biocides force reformulation of anti-fouling compounds across supplier bases. Engineering expertise concentrates in Düsseldorf and Kassel, where armored vehicle specialists develop ceramic-matrix composite armor for weight reduction.
Japan
Island-chain contingency planning accelerates expeditionary readiness investments alongside allied Indo-Pacific initiatives. METI coordinates dual-use technology transfer guidelines affecting amphibious platform development. Industrial capacity clusters in Kobe and Yokohama, where shipbuilders collaborate with land-systems engineers on shallow-draft hull geometries.
Australia
Coastal patrol modernization and regional security partnerships generate demand for deployable littoral platforms. The Department of Defence aligns procurement with NATO STANAG interoperability standards for cross-border tender eligibility. Manufacturing activity concentrates in Melbourne and Adelaide, where domestic assembly provisions support regional fleet expansion.
Military Amphibious Vehicle Market Competitive Landscape
The competitive structure tilts toward integrated prime contractors with full-lifecycle service capabilities. Shipyard-aligned conglomerates and land-systems specialists divide the vendor base between naval integration expertise and armored vehicle engineering. Three archetypes dominate: full-lifecycle integrators with shipyard assets, modular platform specialists, and subsystem component suppliers. Consolidation pressures favor acquisition of digital architecture capabilities, while cross-border partnerships address multi-domain certification requirements.
Among British and American integrated defense conglomerates, BAE Systems plc and General Dynamics Corporation exemplify the full-lifecycle archetype through shipyard-aligned production networks. Rheinmetall AG anchors Central European positioning with amphibious bridging specialization. These three occupy positions defined by geographic defense procurement alignment rather than interchangeable product competition.
| Leading Market Players |
|---|
| BAE Systems plc |
| General Dynamics Corporation |
| Rheinmetall AG |
| Textron Systems Corporation |
| Griffon Hoverwork Ltd |
| Lockheed Martin Corporation |
| Iveco Defence Vehicles |
| Hanwha Aerospace |
| Oshkosh Corporation |
| Others |
Supply & Pricing Matrix
Marine expeditionary units operating under Force Design 2030 procurement mandates concentrate buying power around full-lifecycle contracting models that bundle platform acquisition with decades of sustainment support. This buyer concentration favors prime contractors with shipyard-aligned service networks and compresses margins for component specialists lacking integrated logistics capabilities.
Pricing Analysis
Three-tier pricing structure across expeditionary-grade, allied-export, and coastal-patrol levels dominates platform transactions, with NATO STANAG 4569 certification tier and indigenous assembly provisions driving price differentiation. Cost compression in allied-export configurations is intensifying because Australian and Japanese procurement offices now mandate domestic-content floors that force foreign primes to absorb local-partner margins. Coast guard fleets exhibit highest price sensitivity due to budget cycles tied to civilian appropriations, while special operations commands prioritize acoustic-signature performance over unit cost.
Supply Chain Analysis
Domestic-content mandates in Indonesia, Australia, and Japan are reshaping sourcing patterns away from centralized European fabrication toward distributed regional assembly nodes. Hull-grade aluminum draws from Norwegian smelter networks and Russian 5083-H116 plate streams, while ceramic-matrix armor panels and IP67+ electrical sealing compounds rest on German and Japanese specialty-chemical supply chains. Single-source vulnerability concentrates in high-grade aluminum alloy availability, with tariff exposure running through Norwegian-Russian supply corridors. Distribution runs through national armaments directors coordinating joint-program office tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in military amphibious vehicles hinges on ceramic-matrix composite substitution cycles that yield 15-20% hull-weight reductions without ballistic protection degradation, enabling premium pricing for lighter expeditionary configurations.
For Market Incumbents: Hedge against REACH-compliant material disruption by securing alternative biocide supply agreements before ECHA authorization deadlines eliminate copper-based hull coatings. Incumbent primes should deepen backward integration into ceramic-matrix armor production to capture weight-reduction premiums and defend against modular-platform specialists encroaching on reconnaissance-vehicle segments. For New Entrants and Emerging Players: Launch via unmanned turret integration partnerships targeting the reconnaissance-vehicle segment where AI-assisted target tracking opens white space previously served by manned scout formations. Indonesia's shallow-draft coastal patrol modernization offers the most penetrable geography, with indigenous assembly provisions allowing foreign technology transfer through local joint ventures rather than direct platform export. For Investors and Strategic Acquirers: Defense conglomerates with shipyard assets are the most active acquirers in this space, consolidating digital backbone architecture capabilities to meet Marine expeditionary unit mandates for open-standard Ethernet networks. Acquisition targets should display IP67+ marine electrical sealing expertise scarce in legacy armored-vehicle engineering teams. The signal to monitor is battery-electric range specification thresholds in next-generation procurement cycles, which will determine which supplier rosters survive qualification lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Matrix Armor Integration | BAE Systems and Rheinmetall leverage composite substitution to meet Force Design 2030 weight ceilings. |
| Unmanned Turret Development | Remote weapon stations with AI tracking expand reconnaissance-vehicle addressable market for modular specialists. |
| Indigenous Assembly Partnerships | Indonesian and Australian domestic-content mandates force foreign primes into local joint-venture structures. |
| Electric-Hybrid Propulsion Investment | EU Green Deal carbon thresholds accelerate battery-electric development for coastal auxiliary fleets. |
| REACH-Compliant Coating Reformulation | ECHA biocide restrictions eliminate copper-based alternatives faster than replacement chemistries mature. |
Research Methodology
Bottom-up marine expeditionary unit equipment modeling reconciled against top-down prime-contractor production tracking forms the analytical core of this study. Primary interviews with program managers at joint-program offices, procurement leads at national armaments directors, hull fabrication engineers at shipyard-integrated facilities, and sustainment directors at Commonwealth fleet commands combined with secondary validation from NATO STANAG certification databases, EU Green Deal defense procurement guideline filings, and Department of Defense budget justification documents.
Historical trendline analysis across platform weight, water-speed, and payload capacity dimensions established baseline trajectories for projection modeling. Segmentation by vehicle type, operational use, end user, and fuel type structured volume and value outputs across the analysis window, with CAGRs derived from fitted growth curves calibrated to Force Design 2030 modernization timelines and Indo-Pacific theater investment patterns. Battery energy density improvement curves and littoral connectivity standard adoption rates informed electric-hybrid transition assumptions.
Several conditions sit outside the modeled scope, including classified special operations requirements, rapid-response humanitarian deployment scenarios, and potential NATO STANAG revision cycles. Forecasts reflect documented assumptions regarding aluminum alloy supply stability and REACH authorization timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Colombia Defense Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Indonesia Defense Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Destroyers Market
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Infantry Fighting Vehicle (IFV) Market
Military Vehicles
Iran Defense Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Southeast Asia Defense Market