
 Global Power to Gas Market | 2026-2036
Global Power to Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power to Gas Market Intelligence
European project development for green hydrogen production is realigning the competitive positioning of electrolyzer manufacturers. Siemens leverages its extensive industrial automation and energy portfolio to offer integrated P2G solutions. ITM Power specializes in proton exchange membrane (PEM) electrolyzer technology for rapid response applications. ThyssenKrupp competes with its large-scale alkaline electrolysis technology for industrial clients.
Power to Gas is a technology pathway that converts surplus electrical energy, primarily from renewable sources, into a gaseous energy carrier like hydrogen. The process most commonly uses electrolysis to split water into hydrogen and oxygen, with the resulting hydrogen being stored, used as a fuel, or converted into synthetic methane. The electrolysis technology segment, including both alkaline and PEM systems, commands the majority of investment. Within applications, energy storage for grid stabilization and use as an industrial feedstock for chemical manufacturers represent the largest current demand centers.
Regulatory frameworks are critical to project financial viability and market expansion. The EU Green Deal and the US Inflation Reduction Act (IRA) offer substantial subsidies and tax credits that directly support green hydrogen production. Concurrently, China's dual carbon goals are creating state-led investment in hydrogen infrastructure. Future success for operators depends on navigating divergent regional incentive structures and securing supply chains for critical electrolyzer components.
Market Dynamics
The imperative to decarbonize energy systems while managing the intermittency of renewable power sources is the central force shaping the Power to Gas market. This creates a structural need for long-duration energy storage, positioning hydrogen as a key vector for balancing electrical grids and linking power generation with industrial consumption.
Growth Catalysts
- Supportive Regulatory Frameworks:The US Inflation Reduction Act provides substantial production tax credits for clean hydrogen, directly improving the financial viability of new P2G projects and stimulating domestic investment in electrolyzer manufacturing capacity.
- Industrial Decarbonization Mandates:Demand from hard-to-abate sectors, particularly chemical producers and steel manufacturers in industrial clusters within Germany, provides a concentrated and high-volume offtake market for green hydrogen as a feedstock.
- Electrolyzer Technology Advancement:Continuous improvements in the efficiency, durability, and cost-effectiveness of both PEM and alkaline electrolysis systems are lowering the levelized cost of hydrogen, making P2G a more competitive pathway against fossil-fuel alternatives.
Market Restraints
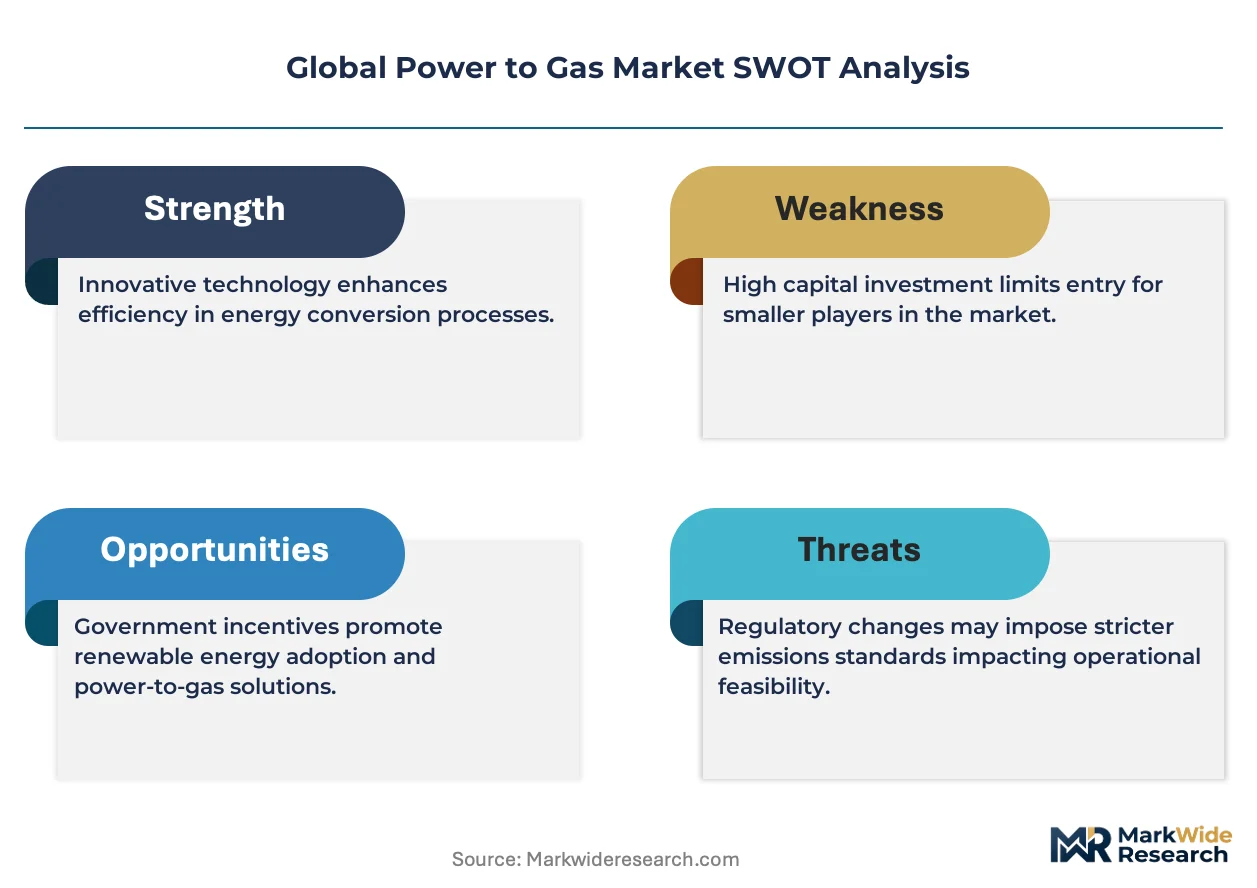
- High Capital Expenditure:The significant upfront investment required for multi-megawatt or gigawatt-scale electrolyzer plants and associated compression and storage infrastructure presents a major financial barrier for project developers.
- Critical Material Dependencies:PEM electrolyzer production relies on scarce platinum group metals like iridium and platinum, creating supply chain vulnerabilities and exposure to price volatility tied to mining output in specific geographies.
- Infrastructure Deficits:A widespread lack of dedicated pipelines for hydrogen transport and large-scale geological storage facilities limits the ability to move green hydrogen from production centers to distant demand hubs efficiently.
Strategic Opportunities
- Export-Oriented Production Hubs:Coastal regions in Australia with abundant solar and wind resources offer significant potential for developing large-scale P2G facilities dedicated to producing green hydrogen or ammonia for export to markets in Asia.
- Mobility and Transport Fuel:The application of green hydrogen as a fuel for heavy-duty trucking, maritime shipping, and aviation represents a vast, emerging demand sector that is currently underserved by battery-electric solutions.
- E-Fuel Synthesis:Integrating P2G systems with captured carbon dioxide sources enables the production of synthetic methane (e-methane) or other e-fuels, which can be used directly in existing natural gas infrastructure and applications.
Industry Challenges
- Lack of Global Standardization:The absence of internationally harmonized standards for hydrogen purity grades, refueling protocols, and safety certifications creates operational friction and complicates cross-border trade and equipment interoperability.
- Grid Integration Complexity:Managing the dynamic operation of electrolyzers to match the fluctuating output of renewable energy sources requires sophisticated control systems and close coordination with grid operators to avoid system instability.
- Specialized Talent Scarcity:A shortage of engineers and technicians with expertise in high-pressure hydrogen systems, electrolysis plant operation, and safety management hinders project execution and operational readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power to Gas Market |
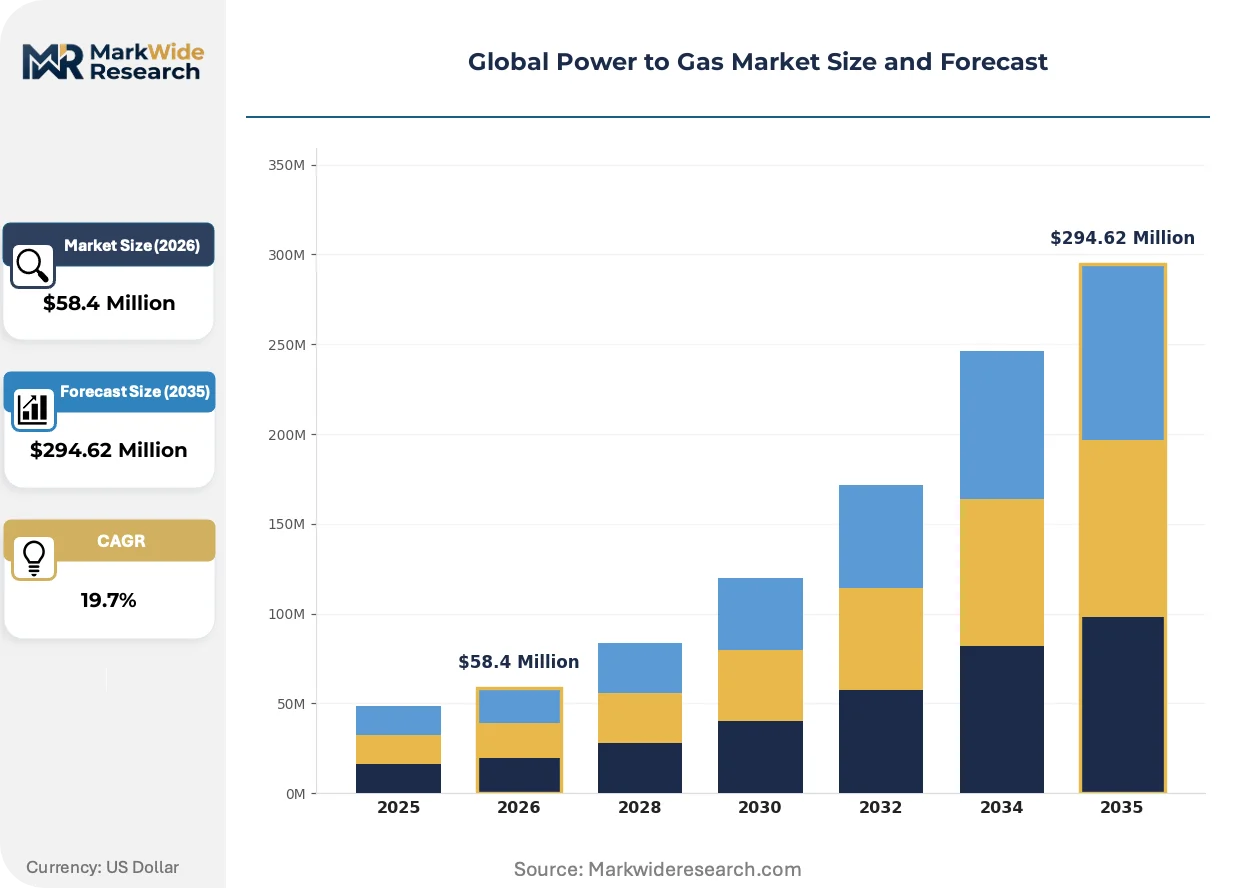
| Market Size in 2026 | $58.4 Million |
| Market Size in 2035 | $294.62 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrolysis, Steam Methane Reforming, Biomass Gasification, Methanation Application: Energy Storage, Industrial Applications, Transportation Fuel, Power Generation End User: Utilities, Chemical Manufacturers, Oil & Gas Industry, Transportation Providers Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Siemens, ITM Power, Hydrogenics, McPhy Energy, Nel Hydrogen, ThyssenKrupp, Electrochaea, MAN Energy Solutions, ENGIE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power to Gas Market Strategic Shifts & Innovations
The market is transitioning from demonstration-scale projects to commercially viable, industrial-sized installations. This evolution is driven by maturing electrolysis technologies, concrete policy incentives that de-risk investment, and a fundamental change in how large energy consumers secure their long-term fuel supply.
Proton Exchange Membrane (PEM) electrolysis is a technology utilizing a solid polymer electrolyte for rapid start-up and dynamic operation. Grid operators and utilities are adopting PEM systems specifically to absorb surplus power and provide fast-frequency response services. For grid-balancing applications requiring immediate ramp-up and ramp-down capabilities to stabilize intermittent renewables, PEM technology is overtaking traditional alkaline electrolysis.
The European Union's Green Deal provides a powerful regulatory tailwind, establishing clear targets for green hydrogen production and use. This policy framework is forcing investment into dedicated hydrogen infrastructure, including pipelines and import terminals. The industrial feedstock segment in nations like Germany and the Netherlands is most affected, with refineries and chemical plants accelerating plans to integrate green hydrogen to meet emissions reduction mandates.
A definitive shift toward long-term hydrogen offtake agreements now underpins project bankability. This model replaces speculative production with guaranteed, contract-backed demand, providing the revenue certainty needed to secure financing for capital-intensive P2G facilities. This procurement behavior is most advanced in industrial ecosystems within the United States and Australia, where large manufacturing and chemical companies sign multi-year deals to lock in green hydrogen supply.
Global Power to Gas Market Segmentation
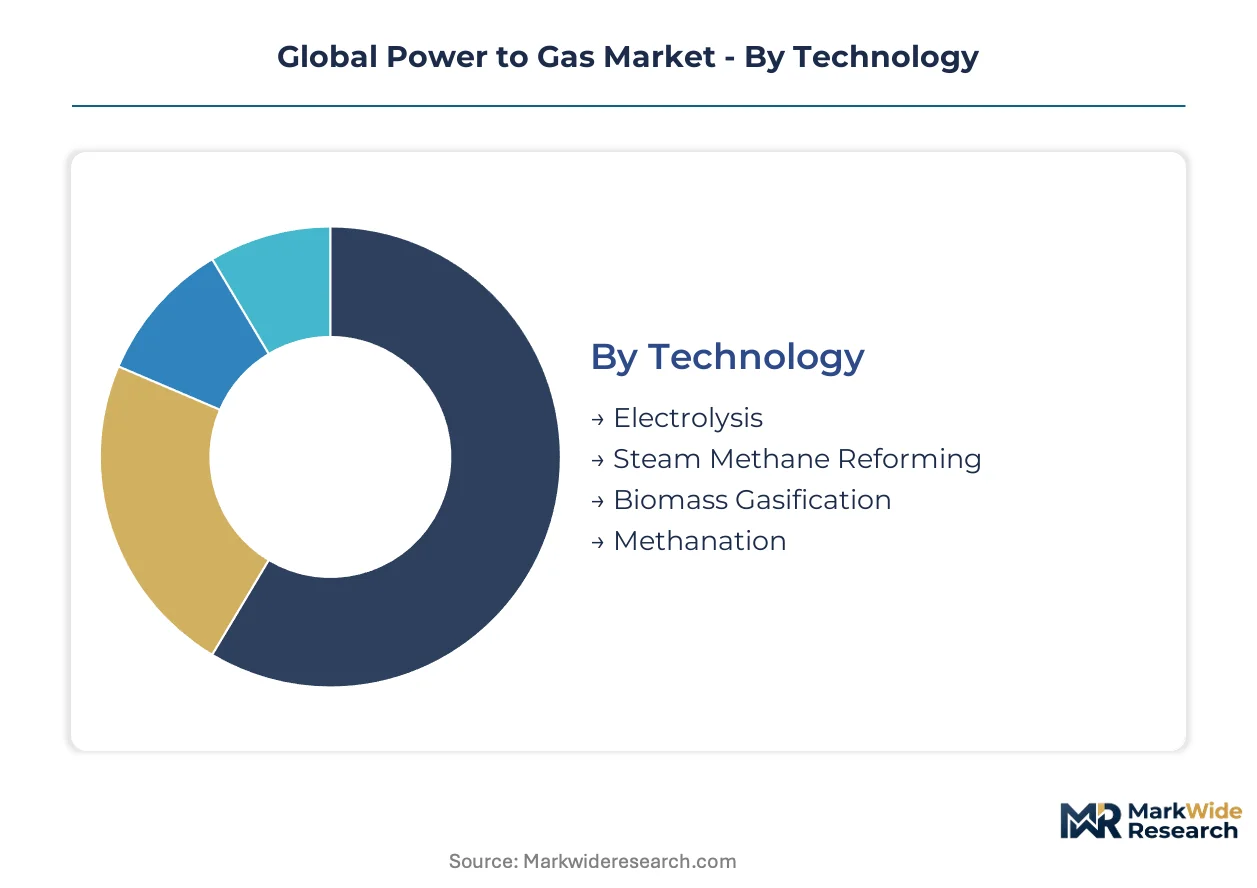
Understanding the segmentation of the Power to Gas market is essential for stakeholders to identify specific value pools and tailor investment strategies. This market's diverse technological pathways and varied end-use applications require a granular approach to project development and market entry. Segmentation highlights the distinct requirements of different customer groups and operational contexts.
Technology:
Buyers in this category differentiate based on their energy source, hydrogen purity requirements, and carbon intensity goals, influencing the choice of conversion pathway.
- Electrolysis:This process splits water into hydrogen and oxygen using electrical energy, predominantly from renewable sources, yielding green hydrogen. Demand concentrates in grid balancing applications and as a clean industrial feedstock for chemical manufacturers in Germany.
- Methanation:This technology converts hydrogen and carbon dioxide into synthetic methane, which is fully compatible with existing natural gas infrastructure. Demand is emerging for e-fuel synthesis and long-duration energy storage solutions in European markets.
- Steam Methane Reforming:This established method produces hydrogen from natural gas, often with carbon capture, to create blue hydrogen. Industrial users in the Oil & Gas sector continue to rely on this technology for large-scale hydrogen production.
- Biomass Gasification:This process converts organic matter into syngas, which can then be further processed to yield hydrogen. Decentralized energy systems and waste-to-energy initiatives in regions like Australia explore this method.
Electrolysis leads volumes today; Methanation is gaining share fastest.
Application:
The primary function or problem solved by the Power to Gas solution drives the selection of specific applications within the market.
- Energy Storage:This application utilizes hydrogen to store surplus electrical energy from intermittent renewable sources, providing grid stability and long-duration storage. Utilities in the United States increasingly deploy P2G systems for grid balancing services.
- Industrial Applications:Green hydrogen serves as a vital feedstock for various industrial processes, replacing fossil-derived hydrogen in hard-to-abate sectors. Chemical producers and steel manufacturers in Germany are significant demand centers.
- Transportation Fuel:Hydrogen powers fuel cell electric vehicles, including heavy-duty trucks, maritime vessels, and potentially aircraft, offering a zero-emission alternative to fossil fuels. Australia is developing export-oriented production hubs for green hydrogen and ammonia to serve this sector.
- Power Generation:Hydrogen can be combusted in turbines or used in fuel cells to generate electricity, offering flexible power solutions. Remote communities and peak power plants are considering hydrogen for reliable energy supply.
The market's expansion is primarily driven by Energy Storage, while Transportation Fuel offers significant future growth potential.
End User:
The operational imperatives and infrastructure capabilities of different end-user groups shape their Power to Gas adoption and project requirements.
- Chemical Manufacturers:These companies require significant volumes of hydrogen as a feedstock for producing ammonia, methanol, and other chemicals. Decarbonization mandates and the need for secure, green supply chains are driving adoption among European chemical giants.
- Utilities:Electrical utilities integrate P2G systems to manage the intermittency of renewable energy sources and enhance grid flexibility. Grid operators in the United States leverage P2G for frequency regulation and long-term energy storage.
- Oil & Gas Industry:This sector explores P2G for decarbonizing existing hydrogen production, producing synthetic fuels, and leveraging existing infrastructure for hydrogen transport. Companies in the Middle East are investing in blue and green hydrogen projects.
- Transportation Providers:Logistics companies and public transport operators are adopting hydrogen fuel cell technology for their fleets to meet emissions reduction targets. Heavy-duty trucking firms are piloting hydrogen solutions across Europe.
Demand from Chemical Manufacturers provides foundational volume, as Transportation Providers explore new P2G integration models.
Distribution Channel:
The scale and complexity of Power to Gas projects dictate the preferred procurement pathways for equipment, technology, and associated services.
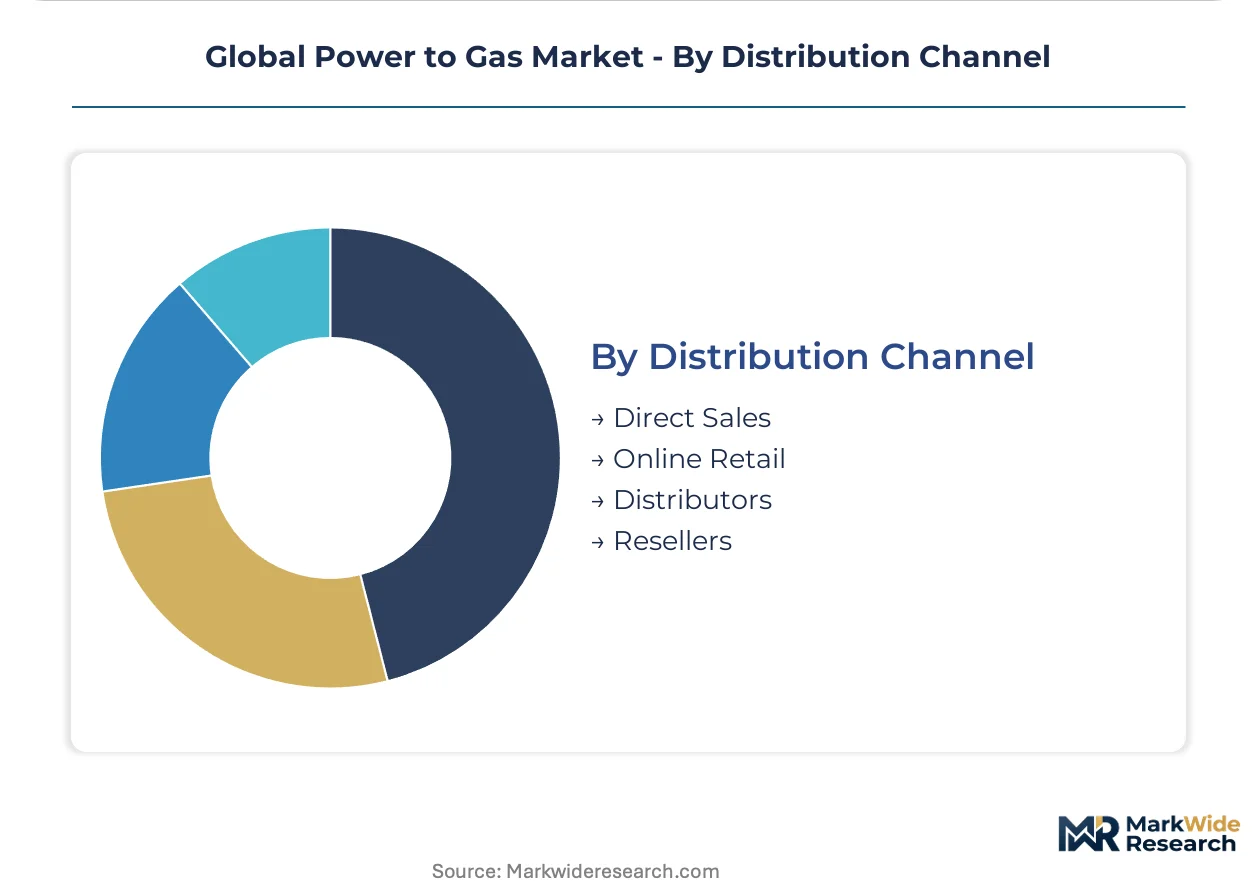
- Direct Sales:Manufacturers engage directly with large industrial clients and project developers for multi-megawatt electrolyzer installations and integrated P2G solutions. Siemens and ThyssenKrupp often utilize this channel for major projects in Germany.
- Distributors:These intermediaries provide regional market access, technical support, and localized inventory for smaller-scale P2G components and systems. Distributors serve a broader base of engineering firms and specialized contractors in the United States.
- Online Retail:E-commerce platforms facilitate the sale of standardized components, spare parts, and smaller laboratory-scale electrolysis units. Research institutions and niche developers often procure through these channels.
- Resellers:Value-added resellers integrate P2G technologies into broader energy solutions, offering complete turnkey systems to end-users. These partners often focus on specific industrial clusters or regional markets.
Large-scale projects predominantly utilize Direct Sales, while Distributors support market penetration for standardized offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks globally create distinct arbitrage opportunities, influencing where Power to Gas production facilities are established. Differing incentives and decarbonization mandates position specific nations as attractive hubs for P2G development and deployment. These varied policy landscapes drive investment towards regions offering the most favorable economic conditions for green hydrogen production.
Germany
Germany's industrial sectors generate significant demand for green hydrogen as a feedstock. The EU Green Deal provides substantial subsidies, accelerating the transition to cleaner industrial processes. Chemical producers and steel manufacturers in the Ruhr area are actively integrating green hydrogen to meet stringent emissions reduction targets.
United States
The United States prioritizes energy storage applications for grid stability through Power to Gas systems. The US Inflation Reduction Act (IRA) offers production tax credits that significantly improve project viability. Utilities across the Southwestern states are deploying P2G solutions for balancing intermittent renewable energy sources.
Australia
Australia's abundant solar and wind resources drive the development of export-oriented P2G facilities. Government initiatives support large-scale green hydrogen and ammonia production for international markets. Coastal regions in Western Australia are emerging as major hubs for energy exports to Asia.
China
China's dual carbon goals necessitate substantial investment in hydrogen infrastructure. State-led initiatives support the expansion of green hydrogen production and utilization across key industrial zones. Major energy companies in regions like Inner Mongolia are developing large-scale electrolysis projects.
Netherlands
The Netherlands focuses on industrial feedstock applications for green hydrogen within its chemical industry. The EU Green Deal incentivizes decarbonization efforts among chemical manufacturers. Port areas like Rotterdam are developing integrated hydrogen ecosystems to supply local industries.
Global Power to Gas Market Key Industry Players
European producers anchor one tier of the Power to Gas market, focusing on integrated solutions; Asian and North American specialists hold another, often emphasizing specific electrolyzer technologies. The market structure exhibits a tiered consolidation, with established industrial giants alongside agile technology developers. Strategic archetypes include integrated P2G solution providers, specialized electrolyzer manufacturers, and project developers. Capacity expansion and strategic partnerships represent dominant competitive moves, alongside portfolio diversification into e-fuels.
Leading integrated solution providers like Siemens AG, a German company, occupy a position leveraging extensive industrial automation and energy portfolios to deliver comprehensive P2G systems. ITM Power Plc, a UK-based specialist, exemplifies expertise in proton exchange membrane (PEM) electrolyzer technology, particularly for rapid response and dynamic grid applications. ThyssenKrupp AG, another German industrial conglomerate, anchors the large-scale alkaline electrolysis segment, catering specifically to heavy industrial clients requiring significant hydrogen volumes.
| Leading Market Players |
|---|
| Siemens |
| ITM Power |
| Hydrogenics |
| McPhy Energy |
| Nel Hydrogen |
| ThyssenKrupp |
| Electrochaea |
| MAN Energy Solutions |
| ENGIE |
| Others |
Cost & Logistics Intelligence
Industrial decarbonization mandates from chemical producers in Germany, coupled with US Inflation Reduction Act incentives, drive demand for green hydrogen. This demand forces a responsive supply chain for electrolyzer components, influencing overall project pricing.
Pricing Analysis
Direct sales channels often incorporate significant project development and integration margins. The dominant pricing model involves contract-based long-term offtake agreements, providing revenue certainty for developers. Price differentiation stems from the volume scale of green hydrogen supply and the certification level of hydrogen purity. Pricing softness reflects high upfront capital expenditure and competition from established fossil fuel alternatives. Utilities exhibit high price sensitivity for grid balancing applications, whereas chemical manufacturers prioritize long-term supply security.
Supply Chain Analysis
Platinum group metals, particularly iridium and platinum, represent a critical input dependency for PEM electrolyzer production. Supply concentration for these specialized components is in specific mining regions and processing centers, impacting global availability. A structural risk involves single-source vulnerability for these critical materials, creating exposure to price volatility. The distribution model for large-scale electrolyzer systems primarily utilizes direct sales from manufacturers like Siemens and ThyssenKrupp to project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Power to Gas market offers significant geographic arbitrage opportunities, with US Inflation Reduction Act production tax credits creating a distinct financial advantage compared to European project financing structures. This regulatory differential influences investment flows and project viability.
For Market Incumbents: Deploy strategic partnerships with critical material suppliers to mitigate supply chain vulnerabilities for platinum group metals. Incumbents should secure long-term green hydrogen offtake agreements with industrial clients in Germany to counter competition from fossil-derived hydrogen. Diversifying electrolyzer component sourcing across multiple geographies reduces exposure to geopolitical risks. Investing in R&D for non-PGM catalysts can provide a long-term cost advantage.
For New Entrants and Emerging Players: Begin with targeting underserved niche applications like e-fuel synthesis, leveraging existing natural gas infrastructure for synthetic methane. The most penetrable segment is likely small to mid-scale industrial users in regions with strong decarbonization mandates, such as the Netherlands. Offer turnkey Power to Gas solutions for specific industrial clusters, bundling electrolyzer technology with integration services. Focus on modular, rapidly deployable systems to reduce upfront capital expenditure for clients.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized electrolyzer manufacturers possessing proprietary technology or strong regional market penetration. The long-term viability of green hydrogen projects, driven by global decarbonization and energy independence imperatives, remains compelling. Target companies with established supply chains for critical components or those developing advanced non-PGM electrolysis systems. A key signal to watch is the adoption rate of global standardization for hydrogen purity and transport protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Building large-scale electrolyzer plants increases green hydrogen production volume for industrial clients. |
| Backward Integration | Securing captive supply of critical platinum group metals reduces supply chain risk and cost volatility. |
| Green Manufacturing Transition | Utilizing renewable energy for electrolyzer production enhances the overall carbon footprint of P2G systems. |
| Long-term Supply Agreement | Establishing multi-year green hydrogen offtake contracts provides revenue certainty for project financing. |
| Joint Venture | Partnering with energy companies or infrastructure developers accelerates deployment of hydrogen pipelines and storage. |
Research Approach
Bottom-up energy storage application modeling reconciled against top-down electrolyzer manufacturing tracking forms the analytical core of this study. Primary interviews with electrolyzer manufacturers, project developers, industrial end-users, and utility grid operators provided qualitative insights. Secondary validation drew from IEA reports, national energy agency data, company financial filings, and academic literature on electrolysis technologies. This approach ensures robust data triangulation.
Historical trendline analysis, combined with forward-looking projections, established the market's trajectory across the analysis window. The analytical framework modeled key segmentation dimensions including technology type, application, end-user segment, and regional regulatory frameworks. Compound Annual Growth Rates were derived from an assessment of market drivers and restraints. Key forecast inputs included renewable energy deployment rates and clean hydrogen production tax credits.
Caveats apply where significant shifts in regulatory policy or critical material price volatility could materially shift the outlook. Forecasts reflect assumptions regarding continued decarbonization mandates and technological advancements. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Variable Speed Generator Market
Power Generation
Japan Combined Heat and Power Market
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Captive Power Generation Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
Global Power Generation Market
Power Generation
India Gensets Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Hydrogenerators Market
Power Generation
Power Sector North America Gas Turbine MRO Market
Power Generation
Cogeneration System Market
Power Generation
Asia-Pacific Distributed Power Generation Market