
 Zinc-Ion Battery Cells Market | 2026-2036
Zinc-Ion Battery Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc-Ion Battery Cells Market Insights
Project finance structures tied to long-duration energy storage contracts are reshaping competitive entry in the zinc-ion battery cells space. Eos Energy Enterprises leverages its utility-scale project pipeline to anchor manufacturing commitments. Salient Energy competes through architectural control over electrode design. ZincFive Inc specializes in high-power discharge configurations for data center backup.
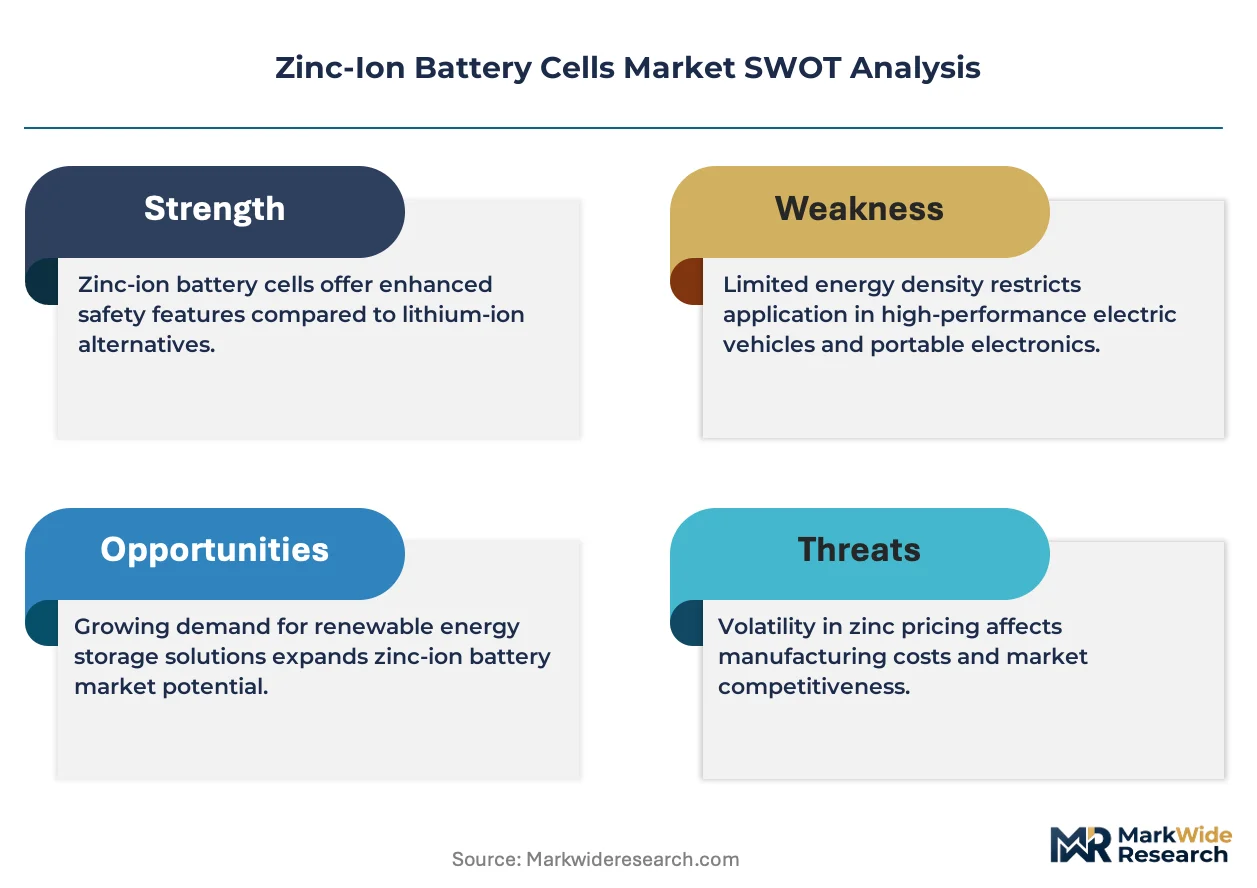
Zinc-ion battery cells store electrical energy through reversible zinc plating in mildly acidic or neutral aqueous electrolytes, achieving energy densities of 70-100 Wh/kg with inherent thermal stability that eliminates flammability risks. Rechargeable cells dominate current shipment volumes while solid-state technology represents the fastest-growing R&D category due to its potential for higher voltage windows. Stationary batteries command the deepest margin pools because utility buyers prioritize cycle life over gravimetric density.
FERC Order 841 in the United States mandates market access for storage resources, while the EU Green Deal and REACH frameworks govern chemical substance registration for European cell imports. China's MIIT enforces GB standards for battery safety testing that aqueous zinc-ion designs satisfy without costly thermal management systems. Stakeholders must monitor how evolving national mineral security strategies alter qualification criteria for non-lithium chemistries in public procurement programs.
Market Dynamics
Grid-scale renewable energy storage operators are expanding procurement of zinc-ion systems as lithium supply constraints persist and aqueous chemistry costs compress below nickel-manganese-cobalt alternatives.
Growth Catalysts
- China's dual carbon goals:Updated GB standards for non-lithium electrochemistry accelerate domestic manufacturing investment in aqueous zinc-ion cell production.
- FERC Order 841:Mandated market access for storage resources in the United States creates interconnection pathways for utility-scale zinc-ion installations.
- Mineral security policies:Germany, India, and the United States favor aqueous chemistries in public procurement, directing capital toward zinc-ion qualification programs.
Market Restraints
- Input cost volatility:Zinc metal price swings on the London Metal Exchange compress cell margin predictability for manufacturers without captive smelter relationships.
- Technical limitation:Zinc dendrite formation during high-rate cycling constrains power density in configurations targeting data center backup applications.
- Regulatory friction:EU REACH frameworks impose extended chemical substance registration timelines for European cell imports, delaying market entry.
Strategic Opportunities
- Emerging application:Maritime vessel electrification creates demand for non-flammable aqueous storage in port operations and short-route shipping.
- Regulatory tailwind:India's PLI scheme for advanced chemistry cell manufacturing includes zinc-ion eligibility, attracting module assembly investment.
- Technology convergence:Integration with solid-state electrolyte research programs opens voltage window expansion beyond aqueous thermodynamic limits.
Industry Challenges
- Skill gap:Electrochemical engineers with aqueous metal plating expertise remain concentrated in lead-acid and nickel-zinc legacy operations, constraining R&D team scaling.
- Certification timeline:UL 9540A thermal runaway testing protocols require adaptation for zinc-ion thermal profiles, extending safety validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc-Ion Battery Cells Market |
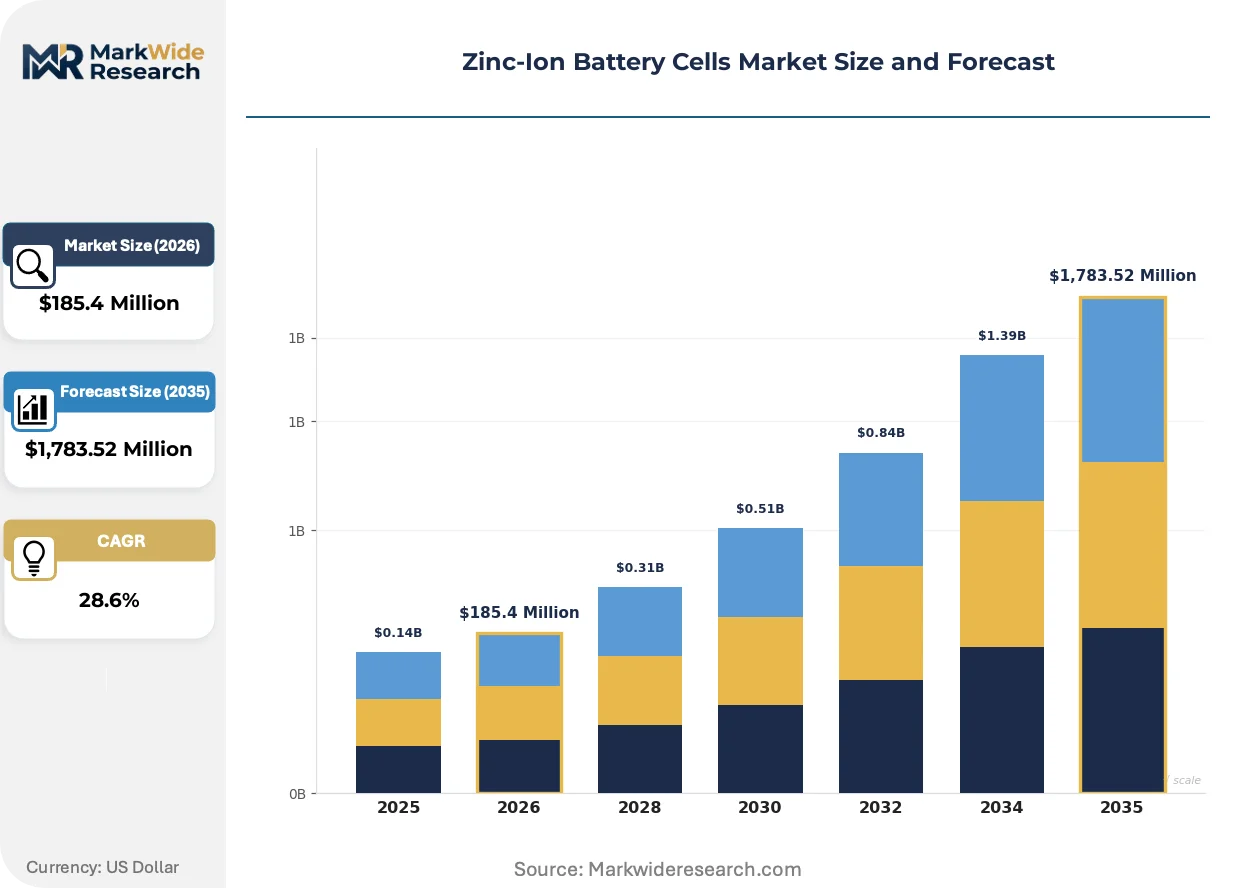
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $1,783.52 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable Cells, Primary Cells, Portable Batteries, Stationary Batteries Technology: Conventional Zinc-Ion, Advanced Zinc-Ion, Hybrid Designs, Solid-State Technology Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Backup Power Systems End User: Manufacturers, Energy Providers, Consumers, Research Institutions |
| Companies Covered | ZincFive Inc, Salient Energy, Enerpoly AB, Eastman Kodak Company, Panasonic Energy Co., Ltd., Eos Energy Enterprises, Phinergy, Primus Power, ENZINC, INC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc-Ion Battery Cells Market Trends and Innovations
Electrode architecture and electrolyte formulation advances are compressing performance gaps with lithium-ion while preserving the intrinsic safety profile that distinguishes aqueous chemistry.
Electrolyte composition is migrating from mildly acidic sulfate solutions toward neutral chloride and acetate systems that suppress hydrogen evolution and extend cycle life. Stationary storage developers in Germany are piloting these formulations for multi-hour duration applications. The shift is migrating from laboratory validation to utility-scale procurement specifications.
China's MIIT enforcement of GB/T 36276 safety testing standards for electrochemical energy storage systems exempts aqueous zinc-ion designs from costly thermal management system requirements. Battery integrators are redesigning container architectures to eliminate HVAC and suppression hardware. Utility buyers in Shandong and Jiangsu provinces are incorporating these cost savings into levelized cost of storage calculations.
Long-term service agreements are displacing equipment-only transactions in utility procurement. Independent power producers in the United States are bundling zinc-ion cells with 20-year performance guarantees and degradation warranties. Arizona and Texas markets exhibit the fastest contract restructuring as offtakers assume operational risk transfer.
Zinc-Ion Battery Cells Market Segmentation
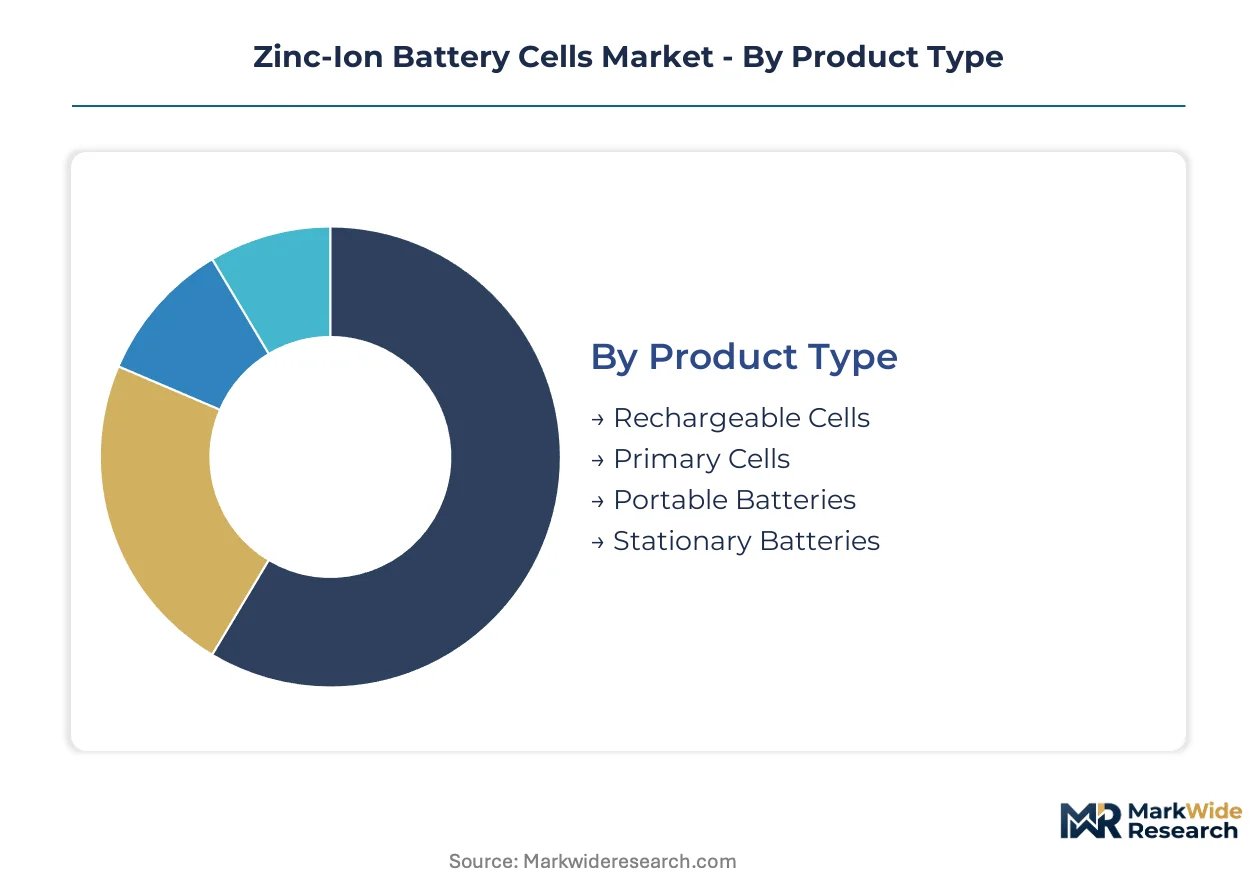
Zinc-ion battery cells serve divergent performance requirements across stationary and mobile applications. Segmentation reveals how aqueous chemistry trade-offs between energy density, cycle life, and safety profile map to distinct customer willingness-to-pay.
Product Type:
Use-case spectrum spans grid-scale installations requiring decade-long service life to single-use medical devices where rechargeability adds cost without utility.
- Stationary Batteries:Containerized systems engineered for 6-12 hour discharge duration dominate utility procurement in Germany and India. Buyers prioritize cycle stability over gravimetric density, accepting 70-80 Wh/kg in exchange for inherent thermal stability that eliminates NFPA 855 fire suppression requirements.
- Rechargeable Cells:Secondary electrochemistry with zinc metal anodes and manganese oxide or vanadium oxide cathodes enables 2000+ cycles in mildly acidic electrolyte. Grid operators in Texas and Arizona are bundling these cells with long-term service agreements that transfer operational risk to integrators.
- Primary Cells:Single-discharge zinc-air or zinc-carbon configurations retain niche demand in remote sensor networks where battery replacement costs exceed cell value.
- Portable Batteries:Compact aqueous cells target camping equipment and marine electronics in Europe, where REACH registration burdens favor domestic assembly over Asian imports.
Established volume favors stationary systems; emerging adoption favors portable configurations in safety-critical outdoor applications.
Technology:
Cost tier separation reflects R&D intensity and manufacturing maturity, with aqueous systems commanding price premiums over legacy alkaline while trailing solid-state laboratory performance.
- Conventional Zinc-Ion:Sulfate-based electrolyte systems with manganese dioxide cathodes achieve manufacturing scale in Chinese facilities serving Shandong and Jiangsu provincial storage tenders. MIIT GB/T 36276 compliance without thermal management hardware compresses balance-of-system costs below lithium-ion alternatives.
- Solid-State Technology:Polymer and ceramic electrolyte research programs at national laboratories in the United States and Germany are expanding voltage windows beyond aqueous thermodynamic limits. Technical barriers around zinc dendrite suppression in dry environments constrain commercial timelines.
- Advanced Zinc-Ion:Electrolyte additives and structured electrode architectures improve coulombic efficiency in chloride and acetate formulations.
- Hybrid Designs:Capacitive buffering layers paired with zinc metal anodes target high-power data center backup where discharge rates exceed pure battery capability.
Production scale concentrates in conventional aqueous platforms; patent filing velocity climbs fastest in solid-state electrolyte composites.
Application:
Customer type determines specification priority, with industrial buyers accepting lower energy density for fire safety certification while automotive developers demand gravimetric performance aqueous chemistry cannot yet deliver.
- Renewable Energy Storage:Multi-hour duration systems paired with solar and wind assets in India and the United States absorb generation intermittency. India's PLI scheme for advanced chemistry cell manufacturing includes zinc-ion eligibility, attracting module assembly joint ventures.
- Backup Power Systems:Uninterruptible power supply configurations for data centers and telecommunications exploit zinc-ion thermal stability to eliminate cooling infrastructure. ZincFive Inc specializes in high-rate discharge architectures for this segment.
- Consumer Electronics:Low energy density relative to lithium-ion limits penetration in smartphones and laptops, with niche adoption in hearing aids and medical wearables where aqueous safety profiles satisfy FDA biocompatibility pathways.
- Electric Vehicles:Gravimetric energy density constraints exclude zinc-ion from passenger car traction batteries, though port equipment and short-route maritime vessels are piloting non-flammable storage for electrified harbor operations.
Procurement volume concentrates in renewable energy storage; qualification activity is expanding most quickly in maritime electrification applications.
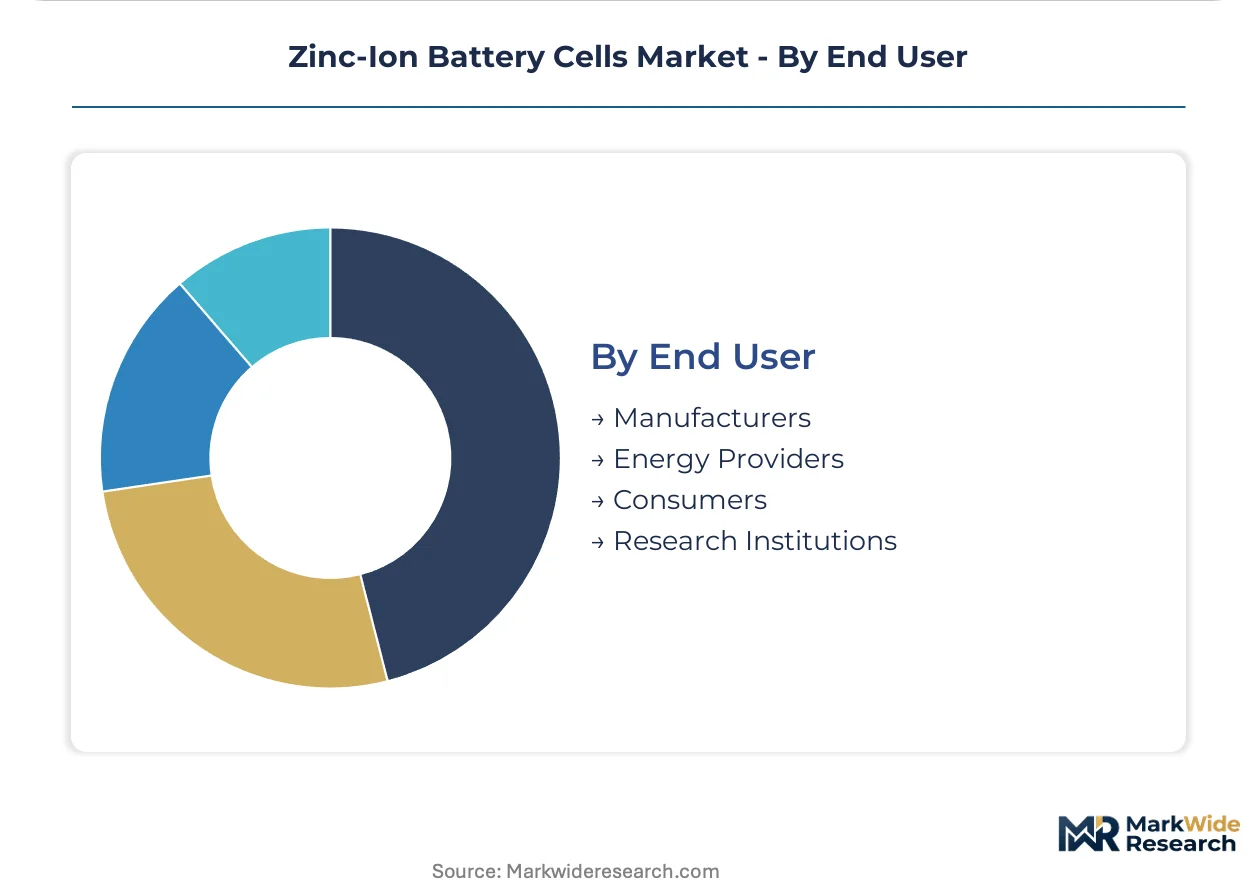
End User:
Volume distribution reflects capital intensity and technical sophistication, with institutional buyers driving standardization while research funding shapes next-generation specifications.
- Energy Providers:Independent power producers and electric utilities in Germany, India, and the United States specify zinc-ion cells in requests for proposals that prioritize mineral security and supply chain localization over energy density metrics.
- Research Institutions:National laboratories and university consortia in China and the United States control solid-state electrolyte patent landscapes, licensing electrode architectures to commercial manufacturers.
- Manufacturers:Cell producers and battery integrators in Jiangsu and Shandong provinces are scaling aqueous production lines to serve domestic storage procurement.
- Consumers:Direct retail demand remains negligible outside emergency preparedness and recreational marine segments where safety messaging resonates.
Contract value concentrates with energy providers; technology licensing revenue flows fastest through research institution partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in zinc-ion battery cells tilt toward net-importing markets in Europe and North America, while China consolidates as the dominant manufacturing source for aqueous cell components.
United States
Utility-scale storage procurement in Texas and Arizona absorbs imported zinc-ion cell modules for multi-hour duration applications. FERC Order 841 mandates grid interconnection access for non-lithium storage resources, lowering regulatory barriers for aqueous chemistry deployment. Manufacturing activity clusters in Arizona, where project developers bundle cells with long-term service agreements that transfer operational risk to integrators.
Germany
Grid operators specify zinc-ion systems in renewable energy storage tenders prioritizing mineral security over energy density metrics. EU REACH frameworks govern chemical substance registration for cell imports, extending qualification timelines for Asian manufacturers. Industrial deployment concentrates in North Rhine-Westphalia, where containerized systems eliminate NFPA 855 fire suppression requirements through inherent thermal stability.
China
Domestic manufacturing investment accelerates under dual carbon goals and updated GB standards for non-lithium electrochemistry. MIIT enforcement of GB/T 36276 safety testing exempts aqueous designs from thermal management hardware, compressing balance-of-system costs. Production gravity centers on Shandong and Jiangsu provinces, where integrators redesign container architectures to eliminate HVAC systems for utility buyers.
India
Central and state electricity utilities expand procurement of zinc-ion cells for solar-wind hybrid storage under mineral security policies favoring aqueous chemistries. The PLI scheme for advanced chemistry cell manufacturing includes zinc-ion eligibility, attracting module assembly joint ventures. Deployment activity concentrates in Gujarat and Rajasthan, where state tenders prioritize supply chain localization.
Zinc-Ion Battery Cells Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with electrode and electrolyte IP. The vendor base spans three tiers: utility-scale project developers with captive manufacturing pipelines, technology licensors controlling solid-state electrolyte patents, and specialty chemical suppliers feeding formulated electrolyte blends. Competitive moves concentrate on backward integration into zinc refining and strategic partnerships with independent power producers seeking long-term service agreements.
Among North American platform developers, Eos Energy Enterprises and ZincFive Inc occupy distinct positioning archetypes—one anchored to utility-scale project pipelines, the other specialized in high-rate discharge configurations. Salient Energy represents the architectural control archetype, with electrode design IP licensing to commercial manufacturers. These three exemplify how competitive differentiation fragments across system integration, power density specialization, and materials science control.
| Leading Market Players |
|---|
| ZincFive Inc |
| Salient Energy |
| Enerpoly AB |
| Eastman Kodak Company |
| Panasonic Energy Co., Ltd. |
| Eos Energy Enterprises |
| Phinergy |
| Primus Power |
| ENZINC, INC |
| Others |
Pricing and Supply Chain Analysis
Shandong and Jiangsu province manufacturing clusters concentrate aqueous cell production capacity, anchoring margin pools in utility-scale project developers who bundle long-term service agreements with hardware sales. Zinc metal feedstock contracts on the London Metal Exchange transmit volatility directly into cell manufacturer cost structures, compressing predictability for producers without captive smelter relationships.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate utility procurement. Price differentiation rests on GB/T 36276 certification tier and volume scale, with Shandong province integrators commanding premiums for thermal-management-exempt container architectures. Cost compression in chloride electrolyte formulations is intensifying because Jiangsu manufacturers are scaling neutral pH production lines. Data center operators exhibit least price sensitivity due to fire-safety-driven specification lock-in, while portable battery distributors face greatest pressure from REACH registration cost pass-through.
Supply Chain Analysis
Extended payment terms from Chinese state-backed project developers are reshaping working capital requirements for electrolyte additive suppliers. Geographic supply concentration centers on China, Australia, and Peru for zinc concentrate feedstock. Raw material dependencies draw from manganese dioxide cathode materials, sulfate and chloride electrolyte salts, and polymer separator membranes. Single-source vulnerability around Australian zinc concentrate exposes margins to export license restrictions. Distribution runs through utility EPC contractors and independent power producer procurement teams rather than wholesale component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology fragmentation across aqueous and solid-state electrolyte platforms creates niche specialization opportunities as utility buyers diverge between cost-optimized stationary systems and performance-driven maritime applications.
For Market Incumbents: Pre-empt solid-state patent encroachment by accelerating licensing partnerships with U.S. national laboratories controlling polymer-ceramic composite IP. Lock in backward integration into zinc refining through offtake agreements with Australian concentrate producers before supply competition intensifies. Defend against emerging electrode architecture specialists by acquiring structured anode design capabilities.
For New Entrants and Emerging Players: India's Gujarat and Rajasthan state utility tenders offer the most penetrable procurement channels under PLI scheme eligibility for zinc-ion module assembly. Maritime vessel electrification in European port operations presents uncaptured white-space demand for non-flammable aqueous storage. Target qualification partnerships with classification societies as the critical go-to-market angle for marine certification.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed utility-scale developers in Arizona and Texas holding contracted project pipelines but constrained manufacturing scale. Long-term viability hinges on electrolyte formulation IP durability against solid-state voltage window expansion. Watch FERC interconnection queue data for utility-scale storage as the inflection signal for demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Formulation Scale-Up | Neutral chloride and acetate systems from Jiangsu labs are migrating into Shandong procurement specifications. |
| GB/T 36276 Certification Investment | MIIT compliance exempts aqueous designs from HVAC hardware, compressing balance-of-system costs below lithium-ion. |
| Long-Term Service Agreement Bundling | Arizona IPPs are transferring operational risk to integrators through 20-year performance guarantees. |
| Zinc Concentrate Backward Integration | Captive smelter relationships insulate margins from London Metal Exchange price volatility transmission. |
| Solid-State Electrolyte Licensing | U.S. national laboratory patent landscapes control voltage window expansion beyond aqueous thermodynamic limits. |
Research Methodology
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base. Primary interviews combined with secondary validation from EIA storage deployment data, FERC interconnection filings, IEA long-duration storage reports, and MIIT GB standard documentation. Bottom-up cell shipment estimates triangulated against top-down utility procurement contract values across the analysis window.
Scenario-bracketing framed demand projections across product type, technology tier, application segment, and end-user category dimensions. CAGRs derived from fitted growth curves applied to segment-level baseline estimates. Zinc metal price trajectory assumptions and electrolyte formulation cost curves served as industry-specific forecast inputs throughout the modeling period.
Practitioners should monitor FERC Order 841 implementation pace, EU REACH registration timeline extensions, and solid-state electrolyte patent licensing velocity for early signals. Forecasts reflect documented assumptions around mineral security policy continuity and aqueous chemistry cost compression trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Alkaline Secondary Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Myanmar Battery Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
Lithium Marine Battery Market
Batteries
East Europe Battery Market
Batteries
India SLI Battery Market
Batteries
France Rechargeable Battery Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Second-Life EV Battery Module Qualification Test Systems Market
Batteries
Battery Swapping Market
Batteries
Alkaline Battery Market
Batteries
South Africa Battery Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
Stretchable Battery Market