
 Power-Sports Batteries Market | 2026-2036
Power-Sports Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Power-Sports Batteries Market Analytics
Lithium iron phosphate is pivoting into power-sports starting applications as riders seek weight reduction and cold-cranking reliability. Exide Technologies leverages its North American distribution network to sustain fleet and dealer-channel presence. GS Yuasa Corporation anchors Japanese OEM supply relationships with absorbed glass mat expertise. Clarios differentiates through maintenance-free lead-acid platforms that compete on price against emerging lithium alternatives.
Power-sports batteries are electrochemical storage devices engineered to deliver high burst current for engine starting, with nominal voltages typically at 12V and capacity ranges from 4Ah to 30Ah depending on vehicle displacement; they must withstand vibration, temperature swing, and prolonged standby in seasonal-use machines. The lithium-ion product type captures the fastest expansion as energy density advantages reshape motorcycle and watercraft fitments. Among end users, ATVs and side-by-sides concentrate margin pools through commercial farm and ranch procurement channels that prioritize durability over upfront cost. Maintenance-free technology leads unit volume while smart-battery platforms with Bluetooth state-of-charge monitoring represent the emerging premium tier.
EPA certification requirements for off-highway engines indirectly govern battery specifications through cranking-performance mandates, while NHTSA lighting standards shape ignition-system electrical loads in street-legal motorcycles. ISO 6469 and IEC 62660 frameworks increasingly influence lithium-ion pack design as cell-level safety protocols migrate from automotive into power-sports applications. Stakeholders must monitor how solid-state prototyping timelines and OEM electrification roadmaps recalibrate the lead-acid versus lithium investment horizon.
Market Dynamics
Off-highway electrification is compressing the lead-acid replacement cycle while lithium-ion chemistry penetrates starting applications previously dominated by absorbed glass mat designs. EPA emissions thresholds and cold-cranking performance mandates are forcing battery specification upgrades across motorcycle and ATV OEM supply chains.
Growth Catalysts
- Lithium Iron Phosphate Chemistry:Energy density advantages are pulling this chemistry into motorcycle fitments where weight reduction directly improves power-to-weight ratios and handling dynamics.
- California Air Resources Board Standards:Tightening cranking-performance requirements for internal-combustion powertrains indirectly expand battery capacity specifications across 50-state vehicle platforms.
- Trail-Access Permit Systems:Seasonal registration requirements in United States recreational jurisdictions sustain replacement-cycle frequency through mandatory safety inspections.
Market Restraints
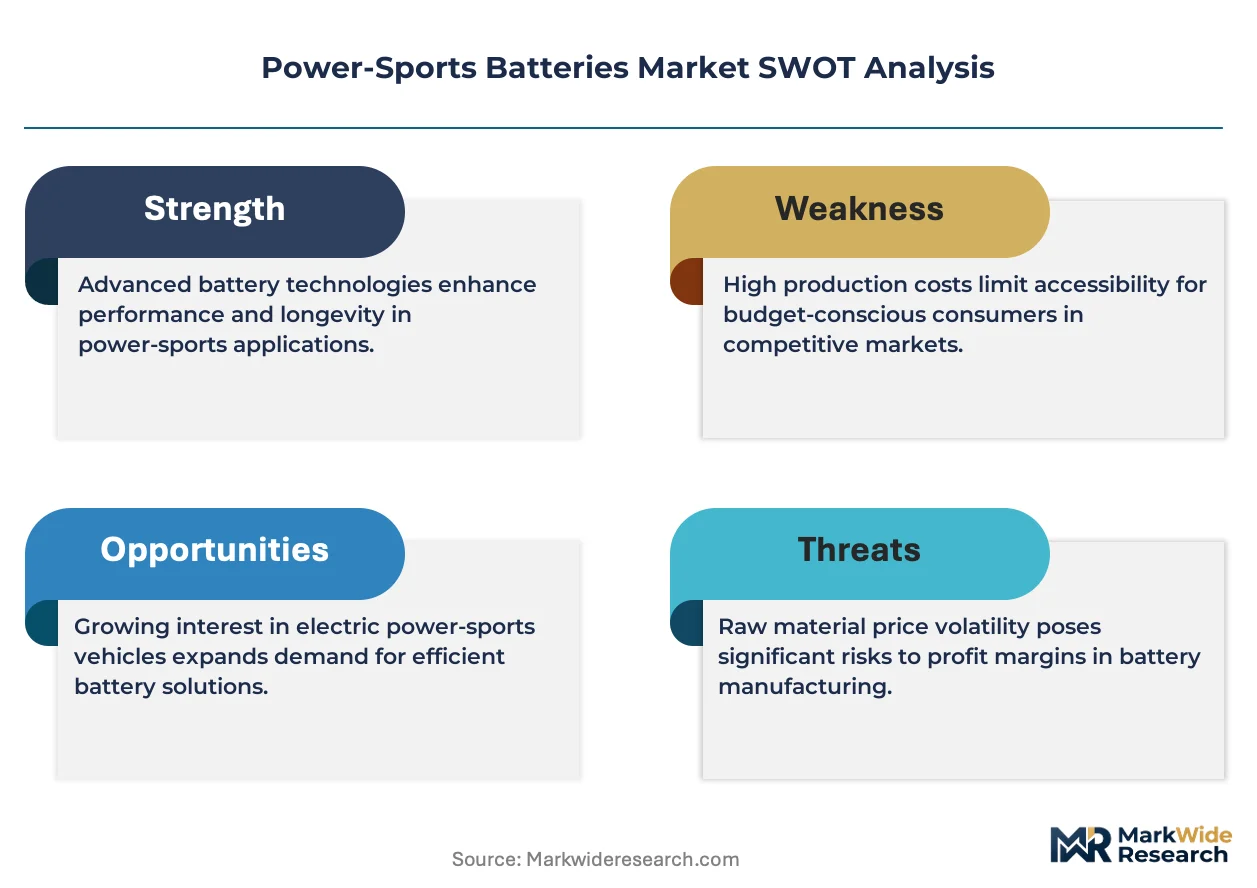
- Lithium Carbonate Price Volatility:Raw material input costs for cathode active materials create margin compression for pack assemblers without long-term offtake agreements.
- East Asian Cell Concentration:Cylindrical and prismatic cell supply concentrates in China, Japan, and South Korea, exposing power-sports brands to shipping disruption and tariff exposure.
- Lead-Acid Infrastructure Lock-In:Dealer service bays, charging equipment, and technician training represent sunk costs that slow lithium conversion in independent repair channels.
Strategic Opportunities
- Bluetooth State-of-Charge Monitoring:Smart-battery platforms with smartphone integration command premium pricing in touring motorcycle and high-performance watercraft segments.
- Commercial Farm and Ranch Procurement:Side-by-side utility vehicles in United States agricultural counties present fleet replacement contracts with multi-year volume commitments.
- ISO 6469 Safety Migration:Automotive cell-level safety protocols migrating into power-sports applications create certification-based differentiation for early adopters.
Industry Challenges
- Battery Management System Integration:Legacy wiring harness architectures in established motorcycle platforms require costly redesign to accommodate lithium-specific charge protocols and thermal monitoring.
- Seasonal Demand Concentration:Spring surge patterns in North American and European markets strain finished goods inventory positioning and working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power-Sports Batteries Market |
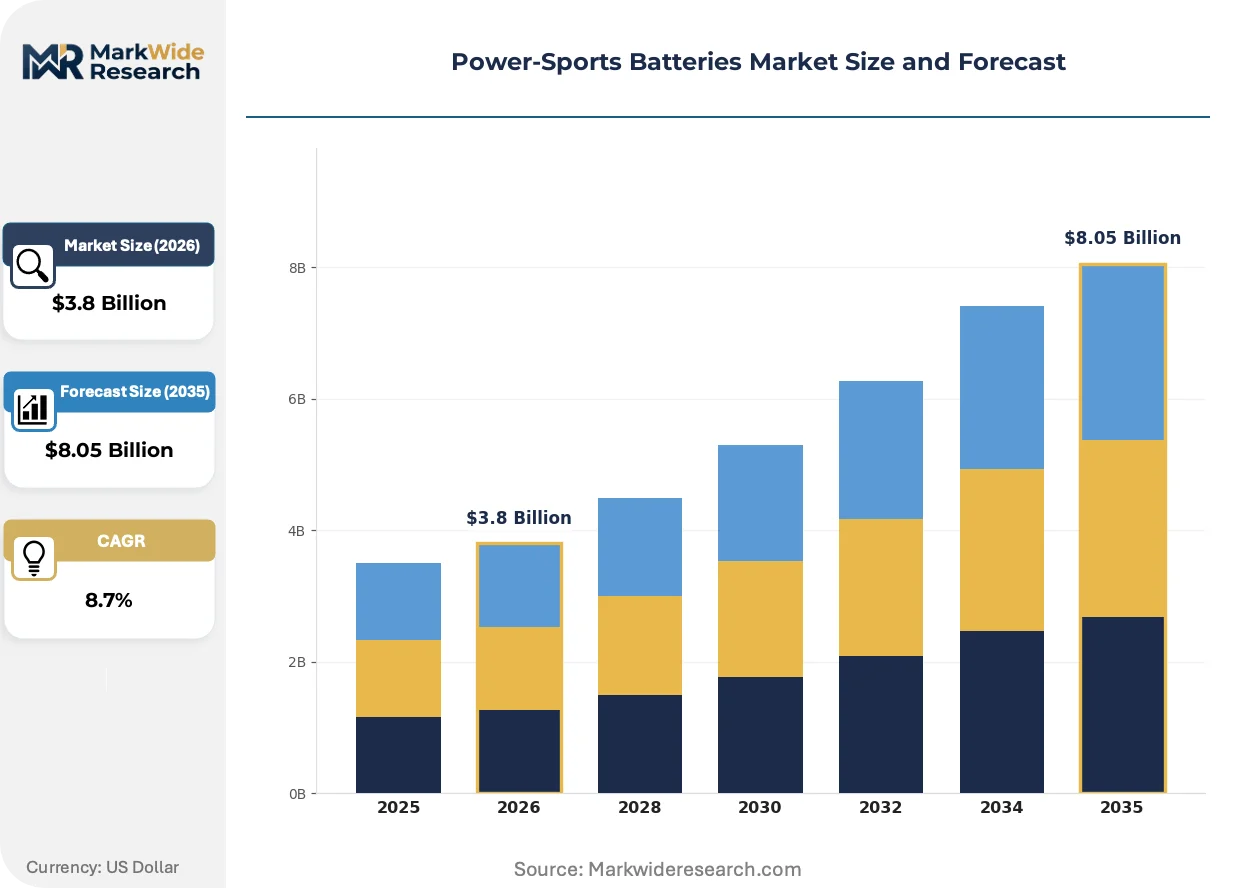
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AGM, Lithium-ion, Lead Acid, Gel End User: Motorcycles, ATVs, Snowmobiles, Watercrafts Application: Starting, Lighting, Ignition, Backup Technology: Conventional, Maintenance-Free, Smart, Fast-Charging |
| Companies Covered | Exide Technologies, GS Yuasa Corporation, Clarios, Johnson Controls, EnerSys, East Penn Manufacturing Company, Power-Sonic Corporation, Fullriver Battery, Discover Battery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power-Sports Batteries Market Evolving Landscape
Battery pack architecture is fragmenting across chemistry types while intelligence layers migrate from vehicle controllers into the storage device itself. Electrification roadmaps from major powersports OEMs are recalibrating supplier investment horizons.
Lithium iron phosphate cell technology is modularizing into standardized 12V form factors that replicate legacy lead-acid case dimensions and terminal positions. Adventure touring and dual-sport motorcycle buyers are adopting these drop-in replacements at accelerating rates. This chemistry is modularizing service procedures across dealer networks previously trained exclusively on flooded and AGM maintenance protocols.
EPA certification requirements for off-highway engines are tightening cranking-performance mandates that indirectly govern battery specifications. Cold-start emissions testing protocols now require sustained voltage delivery under sub-zero conditions. Street-legal motorcycle segments face the most stringent thresholds, driving absorbed glass mat and lithium-ion specification upgrades in 250cc-plus displacement categories.
Rider behavior is compressing replacement cycles through smartphone-enabled diagnostic expectations. Weekend enthusiasts in United States mountain and desert trail regions now expect real-time state-of-health data. This pattern is most visible in premium ATV and side-by-side segments where Bluetooth-equipped batteries command shelf space at powersports retailers.
Power-Sports Batteries Market Segmentation
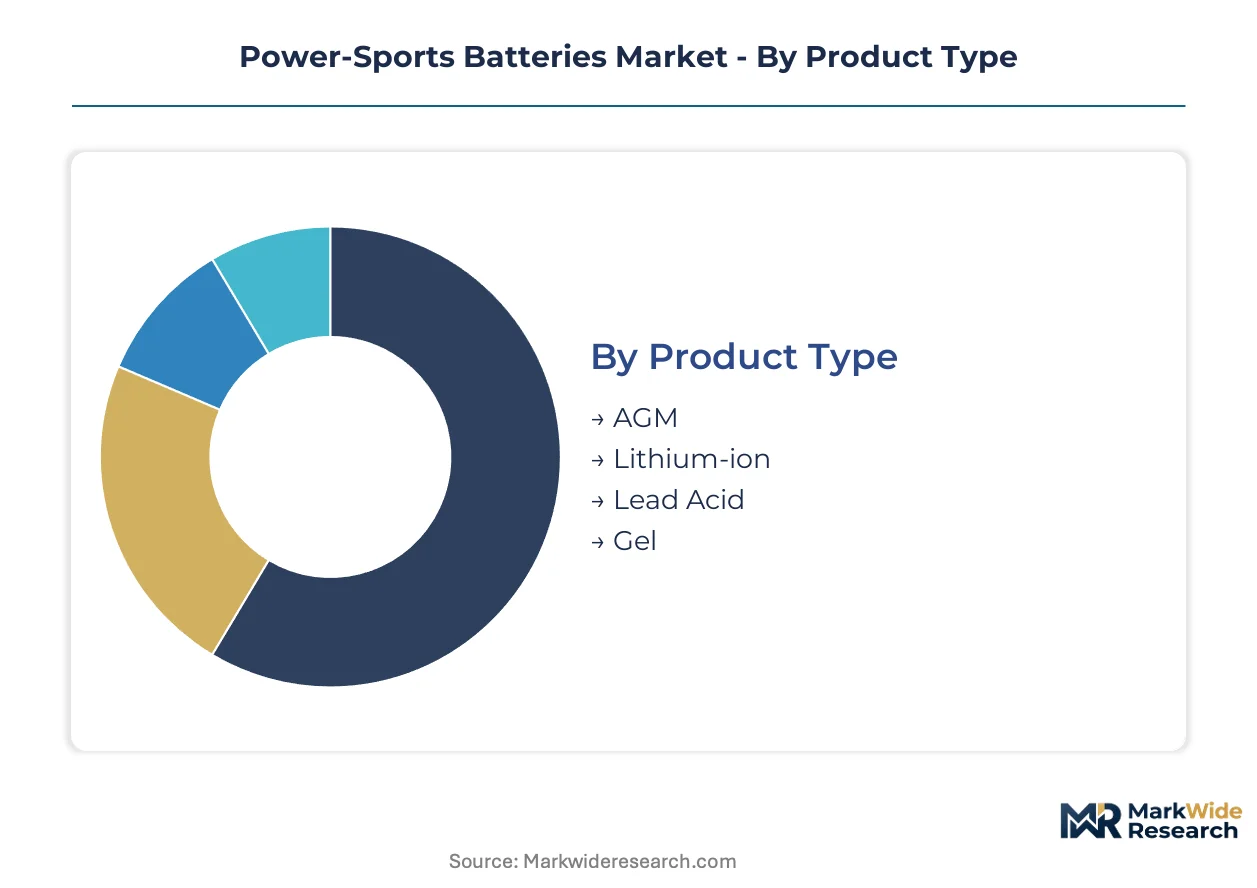
Power-sports batteries fragment across chemistry types, vehicle platforms, electrical functions, and intelligence layers. Each segmentation axis reveals distinct margin structures, replacement-cycle dynamics, and supplier positioning requirements.
Product Type:
Integration depth varies sharply — standalone starting batteries dominate unit volume while embedded lithium packs penetrate electrified powertrains.
- Lithium-ion:Lithium iron phosphate cells deliver energy density above 100 Wh/kg with flat discharge curves critical for cold-cranking reliability. Demand clusters in United States adventure touring motorcycles where riders prioritize weight reduction for off-pavement handling. EPA cold-start emissions testing is compressing specification timelines for this chemistry.
- AGM:Absorbed glass mat construction suspends electrolyte in fiberglass separators, enabling vibration resistance exceeding 10G sustained load. Japanese OEM supply chains anchor volume placements for this technology in 400cc-plus street motorcycles. CARB cranking-performance mandates are forcing capacity upgrades across 50-state platforms.
- Lead Acid:Flooded-cell designs with antimony-alloy grids remain the default for price-sensitive farm utility vehicles in Midwestern United States counties. Independent repair channels resist conversion due to sunk costs in charging equipment and technician training.
- Gel:Silica-thickened electrolyte eliminates stratification in deep-cycle applications, serving marine trolling motor backup functions in Great Lakes watercraft. Niche positioning limits volume penetration relative to AGM alternatives.
Volume placements concentrate in AGM; the faster expansion belongs to Lithium-ion.
End User:
Vehicle platform segmentation maps directly to use-intensity patterns and procurement channel structures.
- Motorcycles:Street-legal displacement categories above 250cc drive absorbed glass mat and lithium-ion upgrades under NHTSA lighting-system electrical loads. United States touring segments command premium pricing for Bluetooth-enabled state-of-charge monitoring.
- ATVs:All-terrain vehicles concentrate commercial procurement through farm and ranch fleet contracts with multi-year volume commitments. Side-by-side utility variants prioritize durability over upfront cost in agricultural counties.
- Snowmobiles:Seasonal standby requirements in sub-zero conditions favor maintenance-free AGM configurations for reliable spring starting. Trail-access permit systems in mountain states sustain replacement-cycle frequency.
- Watercraft:Personal watercraft and jet boats expose batteries to salt spray and vibration profiles distinct from land vehicles. Marine retailers stock dual-purpose starting/deep-cycle hybrids for fishing boat auxiliary power.
Motorcycles generate the highest unit margins; ATVs present the steepest fleet-contract expansion trajectory.
Application:
Electrical function segmentation determines current-draw profiles and duty-cycle engineering requirements.
- Starting:High burst current delivery — 100-400 amps for 5-10 seconds — defines this core function across all power-sports categories. Lithium iron phosphate chemistry is displacing lead-acid in premium motorcycle fitments where weight reduction improves power-to-weight ratios.
- Lighting:Sustained moderate discharge for headlamp and auxiliary illumination loads shapes battery capacity sizing in street-legal segments. NHTSA standards govern minimum electrical reserves for brake-light visibility.
- Ignition:Fuel-injection system power demands have elevated baseline electrical requirements above carbureted-era specifications. EFI-equipped ATVs and side-by-sides require voltage stability under cranking load.
- Backup:Deep-cycle reserve capacity serves winch operation, GPS units, and communication equipment in expedition touring motorcycles. Dual-sport riders in desert trail regions drive demand for auxiliary power segregation.
Starting commands absolute unit volume; backup functions are climbing the fastest as accessory electrical loads multiply.
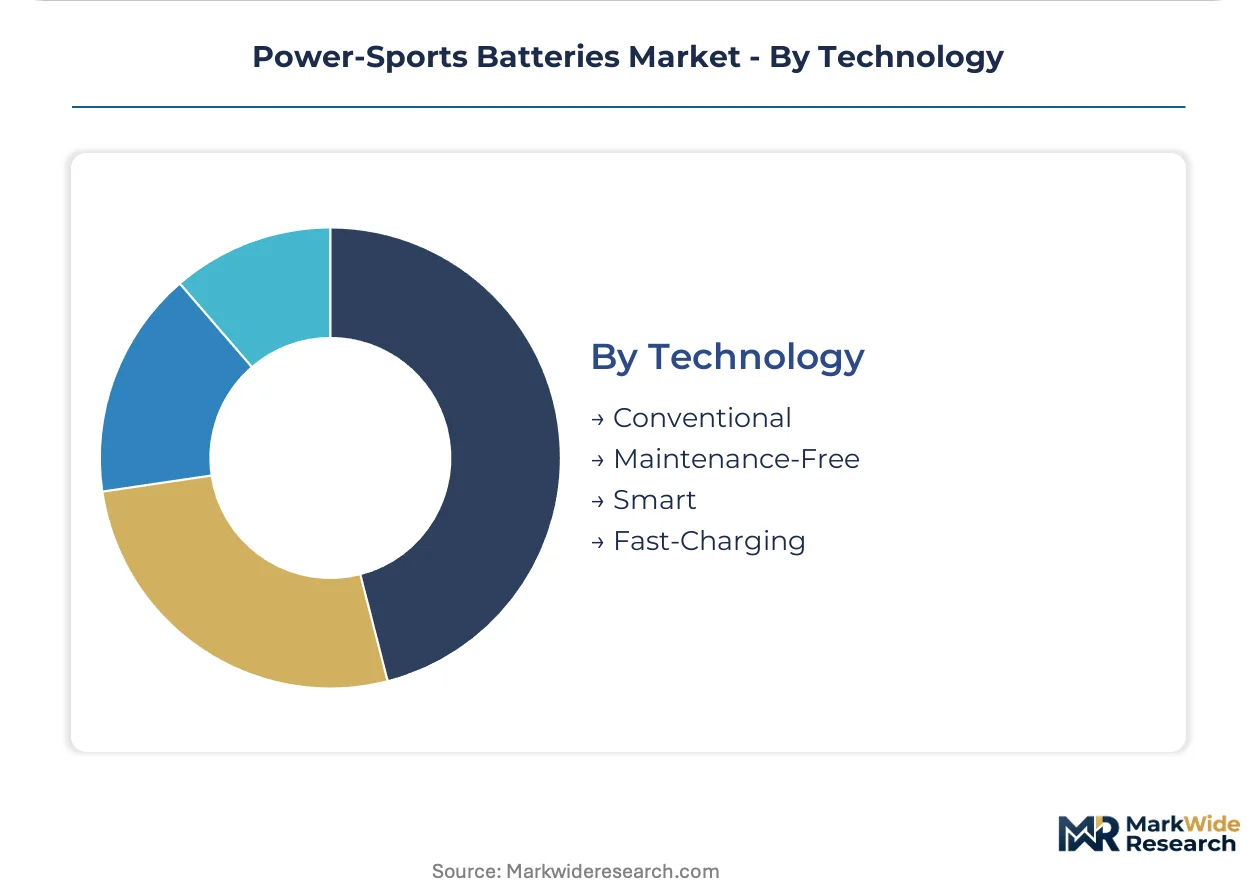
Technology:
Intelligence and maintenance characteristics segment the market across customer sophistication tiers and service-channel capabilities.
- Maintenance-Free:Sealed AGM and gel constructions eliminate electrolyte topping, dominating dealer service bay throughput. This technology leads unit volume through replacement-cycle convenience.
- Smart:Bluetooth-enabled battery management systems with smartphone state-of-charge readouts command premium shelf space at powersports retailers. Weekend enthusiasts in United States mountain regions now expect real-time diagnostic data.
- Conventional:Flooded lead-acid with removable caps persists in price-driven farm equipment channels and developing-market motorcycle segments. Removable caps enable specific gravity testing in legacy service procedures.
- Fast-Charging:Enhanced acceptance rates above 0.5C enable rapid turnaround for rental fleet and commercial utility applications. Lithium-ion cell chemistry enables this capability without thermal runaway risk.
Maintenance-Free technology holds dominant share; Smart platforms are gaining share fastest through premium tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Mexico's Bajío region and Vietnam's industrial parks are pulling assembly capacity away from traditional manufacturing clusters. Battery pack operations concentrate where OEM electrification roadmaps intersect with tariff-advantaged export corridors.
United States
Trail-access permit systems in Colorado and Utah sustain replacement-cycle frequency through mandatory safety inspections. EPA cold-start emissions testing tightens cranking-performance thresholds for 250cc-plus motorcycles. Milwaukee anchors OEM supply relationships where dealer-channel density shapes aftermarket battery distribution.
Germany
KBA certification requirements for street-legal motorcycles elevate absorbed glass mat specifications above baseline EU thresholds. Bavaria's automotive supplier ecosystem migrates cell-level safety protocols from passenger vehicles into powersports applications. Munich-based engineering consultancies advise OEMs on ISO 6469 compliance for lithium-ion pack architectures.
Japan
METI battery recycling mandates compress end-of-life collection timelines for lead-acid replacements. Tokyo-Osaka OEM supply chains anchor absorbed glass mat volume placements in 400cc-plus displacement categories. Yokohama industrial corridors concentrate cell testing facilities for motorcycle starting applications.
China
MIIT new-energy vehicle subsidies indirectly accelerate lithium iron phosphate cost curves for adjacent powersports applications. Shenzhen and Dongguan manufacturing clusters dominate cylindrical cell output for export-oriented battery pack assemblers. GB standards for lithium-ion safety increasingly influence pack design for Western OEM sourcing.
India
BIS certification requirements for automotive batteries extend testing protocols to motorcycle starting applications. Tamil Nadu and Gujarat industrial corridors attract AGM assembly investments serving domestic two-wheeler OEMs. PLI scheme incentives for advanced chemistry cell manufacturing reshape long-term supplier investment horizons.
Power-Sports Batteries Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with maintenance-free lead-acid platforms dominating dealer throughput while lithium-ion specialists capture premium shelf space. The vendor base organizes around three archetypes: diversified electrochemical conglomerates with North American distribution networks, Japanese OEM-anchored absorbed glass mat specialists, and emerging lithium pack assemblers leveraging automotive cell supply. Consolidation pressures concentrate in the middle tier where regional battery brands lack scale for long-term offtake agreements. Competitive moves center on backward integration into cell sourcing and certification-based differentiation through ISO 6469 safety migration.
Within the diversified conglomerate tier, Exide Technologies and Clarios occupy positions shaped by legacy lead-acid infrastructure and dealer-channel presence. GS Yuasa Corporation exemplifies the OEM-anchored specialist archetype, with its corporate structure reflecting deep integration into Japanese motorcycle supply chains. These three entities represent distinct strategic postures: Exide Technologies leverages North American distribution density, Clarios competes on maintenance-free platform pricing, and GS Yuasa Corporation sustains volume through absorbed glass mat expertise in displacement-heavy segments.
| Leading Market Players |
|---|
| Exide Technologies |
| GS Yuasa Corporation |
| Clarios |
| Johnson Controls |
| EnerSys |
| East Penn Manufacturing Company |
| Power-Sonic Corporation |
| Fullriver Battery |
| Discover Battery |
| Others |
Value Network & Pricing Analysis
Electrochemical engineer concentrations in Michigan and Ohio battery corridors feed labor-cost differentials that widen pricing-tier spreads between premium lithium-ion packs and commodity lead-acid replacements. Dealer service bay wages in these Midwestern clusters compress margins on maintenance-free AGM platforms while supporting premium positioning for Bluetooth-enabled smart batteries.
Pricing Analysis
Volume placements concentrate in standard-grade absorbed glass mat batteries where per-unit margins compress under raw material volatility; premium-tier lithium iron phosphate commands three-tier pricing structure across premium, standard, and economy levels driven by certification grade and Bluetooth integration depth. CARB cranking-performance mandates are forcing specification upgrades that narrow price gaps between mid-tier AGM and entry lithium alternatives. Commercial farm and ranch fleet buyers exhibit highest price sensitivity, while adventure touring motorcycle enthusiasts show least sensitivity given weight-reduction priorities.
Supply Chain Analysis
Regional distribution centers in Milwaukee and Memphis anchor hub-and-spoke patterns that position finished goods ahead of spring demand surges in mountain and desert trail jurisdictions. Cell supply concentrates in China, Japan, and South Korea, with cylindrical lithium iron phosphate output feeding pack assembly operations in Mexico's Bajío free-trade zones. Raw material dependencies on lithium carbonate, cobalt sulfate, and electrolyte salts expose assemblers to commodity price volatility. Distribution runs through OEM captive networks and independent dealer channels with diverging service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive cell supply and backward integration into cathode active materials represent the decisive upstream lever separating sustainable margin structures from commodity trap exposure.
For Market Incumbents: Anticipate lithium-ion conversion timelines by securing long-term offtake agreements with East Asian cell producers before tariff exposure hardens. Reinforce dealer channel control through technician certification programs that embed proprietary diagnostic tools. Defend against emerging lithium pack assemblers by accelerating maintenance-free AGM capacity upgrades that satisfy interim CARB mandates. For New Entrants and Emerging Players: Enter via side-by-side utility fleet contracts in United States agricultural counties where durability specifications favor challenger brands with aggressive warranty terms. Target watercraft segments where salt-spray corrosion resistance creates white-space opportunities absent established incumbents. Pursue direct-to-farm distribution partnerships that bypass legacy dealer infrastructure locked into lead-acid service protocols. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier pack assemblers possessing ISO 6469 certification progress and automotive cell supply relationships given OEM electrification roadmap acceleration. Long-term viability over the next decade hinges on lithium chemistry conversion speed versus stranded lead-acid asset exposure. Monitor solid-state prototyping announcements from Japanese OEMs as the critical inflection signal for chemistry transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cell Supply Agreement | Long-term offtake with cylindrical cell producers in South Korea secures lithium iron phosphate cost curves. |
| Dealer Certification Program | Technician training on lithium-specific charge protocols accelerates conversion in independent repair channels. |
| Bluetooth Platform Launch | Smartphone state-of-charge integration commands premium shelf space at powersports retailers in Colorado. |
| Backward Integration | In-house cathode active material production reduces lithium carbonate price volatility exposure for pack assemblers. |
| Fleet Contract Expansion | Multi-year volume commitments with Midwestern farm cooperatives lock in replacement-cycle revenue streams. |
Research Methodology
Trade databases, EPA certification filings, and OEM electrification roadmaps formed the secondary backbone, supplemented by customs records tracking lithium cell import volumes into Mexico and Vietnam assembly corridors. Primary fieldwork engaged battery pack engineering directors, powersports dealer operations managers, and agricultural fleet procurement officers across United States Midwestern counties. Bottom-up and top-down triangulation validated unit shipment estimates against production capacity disclosures and channel inventory positioning.
Bottom-up modeling anchored the analytical lens, with top-down macroeconomic cross-checks ensuring consistency across the projection horizon. Segmentation dimensions span chemistry type, vehicle platform displacement category, electrical function, and intelligence tier. CAGRs derived from fitted growth curves incorporating OEM platform electrification timelines, CARB regulatory phase-in schedules, and seasonal demand concentration patterns in North American trail-access jurisdictions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium carbonate price spike scenarios or accelerated solid-state commercialization. Outputs reflect assumptions on cell cost decline trajectories and dealer conversion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Europe Battery Market
Batteries
Rechargeable Coin Cell Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Second-Life Automotive Battery Module Systems Market
Batteries
Wood-Based Batteries Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Deep Cycle Battery Market
Batteries
Battery Diagnostics and Repair Market
Batteries
Potassium-Ion Battery Market
Batteries
Battery-Powered Riveter Market
Batteries
Automotive Starting Battery Market
Batteries
Global Industrial Battery Market
Batteries
Yacht Battery Market
Batteries
Automotive AGM Battery Market
Batteries
Residential Battery Market