
 Denmark Rechargeable Battery Market | 2026-2036
Denmark Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Rechargeable Battery Market Insights
Modular battery pack architecture is broadening buyer choice across Danish industrial and automotive segments. Xolta A/S leverages its domestic assembly footprint to serve Nordic energy storage contracts. Viridus Manufacturing A/S anchors its position through specialized lithium-ion module production for marine and stationary applications. LG Energy Solution, Ltd. competes via high-volume cell supply relationships with European OEMs serving Denmark.
A rechargeable battery electrochemically stores and releases energy through reversible redox reactions, with lithium-ion variants employing graphite anodes and metal oxide cathodes to achieve energy densities exceeding 250 Wh/kg for electric traction and grid-scale buffering. Lithium-ion chemistry dominates Danish procurement volumes due to its maturity in electric vehicle and renewable energy storage applications, where cycle life and charge efficiency determine total cost of ownership. Nickel-metal hydride retains a niche in power tools and hybrid vehicle auxiliary systems, while lead-acid continues in backup power roles where capital cost sensitivity outweighs energy density requirements.
Danish regulation operates under the EU Battery Regulation framework, with national alignment through the Danish Environmental Protection Agency enforcing extended producer responsibility and recycling content mandates. The Danish Energy Agency's grid interconnection standards shape battery system certification for behind-the-meter storage paired with wind assets. Stakeholders must monitor forthcoming EU critical raw material sourcing disclosure rules and their impact on cell supply contract renegotiations.
Market Dynamics
Denmark's rechargeable battery market pivots on the 2030 fossil-fuel vehicle sales ban, which is compressing procurement cycles for lithium-ion traction systems and concentrating demand around Copenhagen's urban electrification corridors.
Growth Catalysts
- EU Battery Regulation alignment:Extended producer responsibility mandates are accelerating Danish fleet operators' replacement schedules for commercial vehicle batteries.
- Offshore wind buffering demand:North Sea wind interconnectors require grid-scale storage, pulling battery procurement toward Bornholm and Esbjerg port clusters.
- Solid-state electrolyte research:DTU Energy and Copenhagen University partnerships are shortening commercialization timelines for next-generation Danish cell production.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress Danish assembler margins on fixed-price Nordic energy storage contracts.
- Asian cell supply concentration:Korean and Chinese cathode precursor dominance creates procurement bottlenecks for Danish pack integrators.
- EU critical raw material disclosure rules:Forthcoming supply chain transparency mandates are forcing contract renegotiations before full regulatory clarity exists.
Strategic Opportunities
- Jutland industrial corridor:Underpenetrated heavy machinery electrification offers white space for lithium-ion traction systems in agricultural and construction equipment.
- District heating convergence:Copenhagen's thermal-to-electric hybrid pilots create novel application demand for behind-the-meter storage.
- Marine electrification tailwind:Danish ferry route decarbonization mandates under the EU Green Deal are opening specialized battery system procurement channels.
Industry Challenges
- Electrochemical engineering talent scarcity:Solid-state R&D programs compete for limited Danish PhD-level specialists against German and Dutch battery clusters.
- Grid interconnection certification timelines:Danish Energy Agency behind-the-meter standards create 12-18 month approval delays for wind-coupled storage projects.
- Legacy lead-acid replacement complexity:Industrial buyers face integration friction retrofitting existing forklift and backup power infrastructure for lithium-ion chemistry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Rechargeable Battery Market |
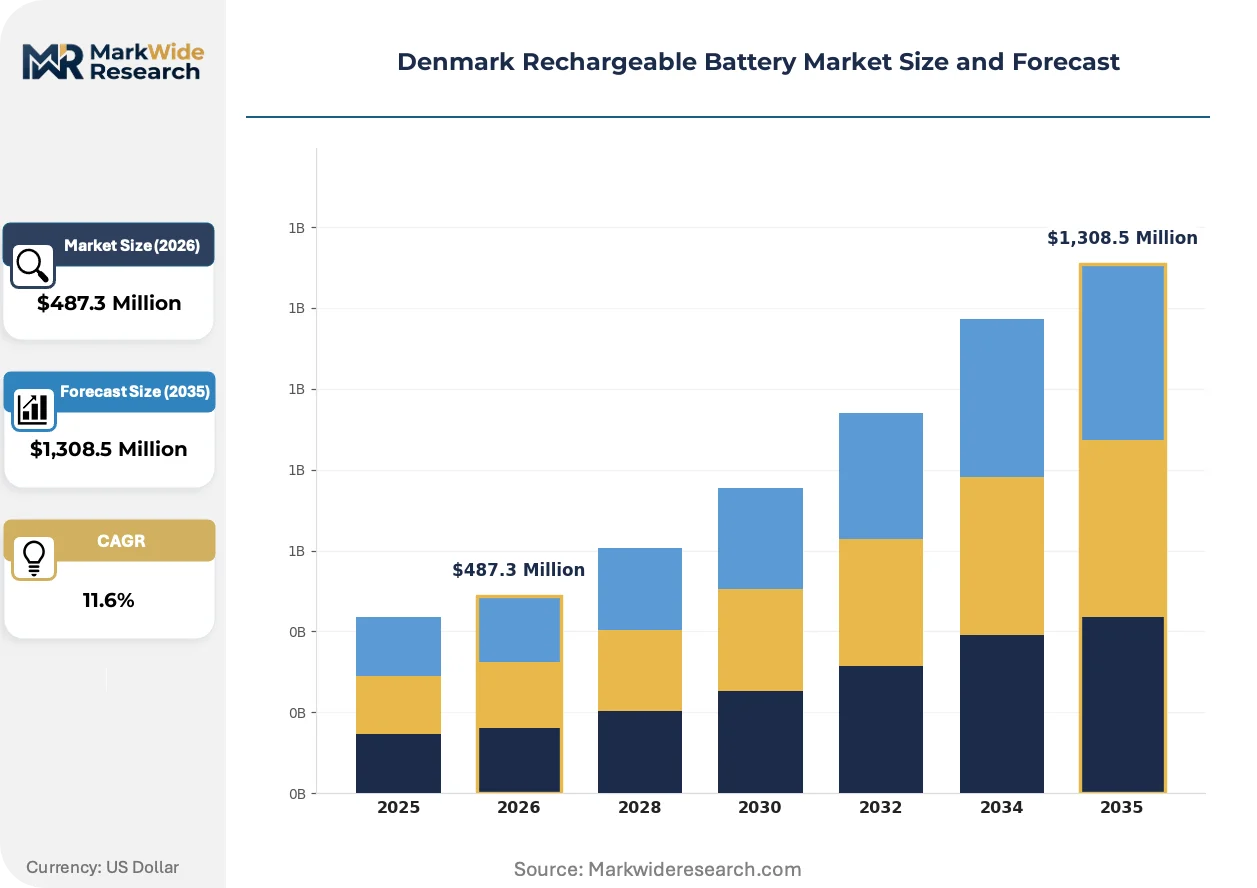
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Lithium Polymer Application: Consumer Electronics, Electric Vehicles, Power Tools, Renewable Energy Storage End User: Retail Customers, Industrial Users, Automotive Manufacturers, Energy Providers Technology: Fast Charging, Wireless Charging, Smart Battery Management, Energy Density |
| Companies Covered | Xolta A/S, Viridus Manufacturing A/S, WS Technicals A/S, MILA Nordic A/S, EPTechnologies, ACTEC A/S, Lithium Balance, Contemporary Amperex Technology Co. Limited (CATL), LG Energy Solution, Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Rechargeable Battery Market Trends and Innovations
Pack architecture standardization and solid-state chemistry maturation are restructuring how Danish buyers specify battery systems across automotive and stationary applications.
Solid-state battery technology replaces flammable liquid electrolytes with ceramic or polymer alternatives to achieve higher energy density and thermal stability. Danish marine operators and fleet managers are piloting early prototypes for ferry and heavy-duty truck routes. This chemistry shift is modularizing how system integrators design thermal management and safety enclosures around standardized cell formats.
The EU Battery Regulation's carbon footprint declaration requirements take full effect for electric vehicle batteries in 2025. Danish assemblers must now document lifecycle emissions from mining through recycling, reshaping supplier qualification criteria. Industrial and automotive segments are responding by consolidating procurement around certified European cell sources with verified supply chain data.
Danish fleet operators are compressing replacement cycles from seven years to four years as residual value guarantees and second-life grid storage options mature. Leasing structures and battery-as-a-service contracts are displacing outright purchase in municipal bus and commercial van segments. This financing rotation is most visible in Copenhagen and Aarhus metropolitan procurement, where total-cost-of-ownership calculations now dominate specification decisions.
Denmark Rechargeable Battery Market Segmentation
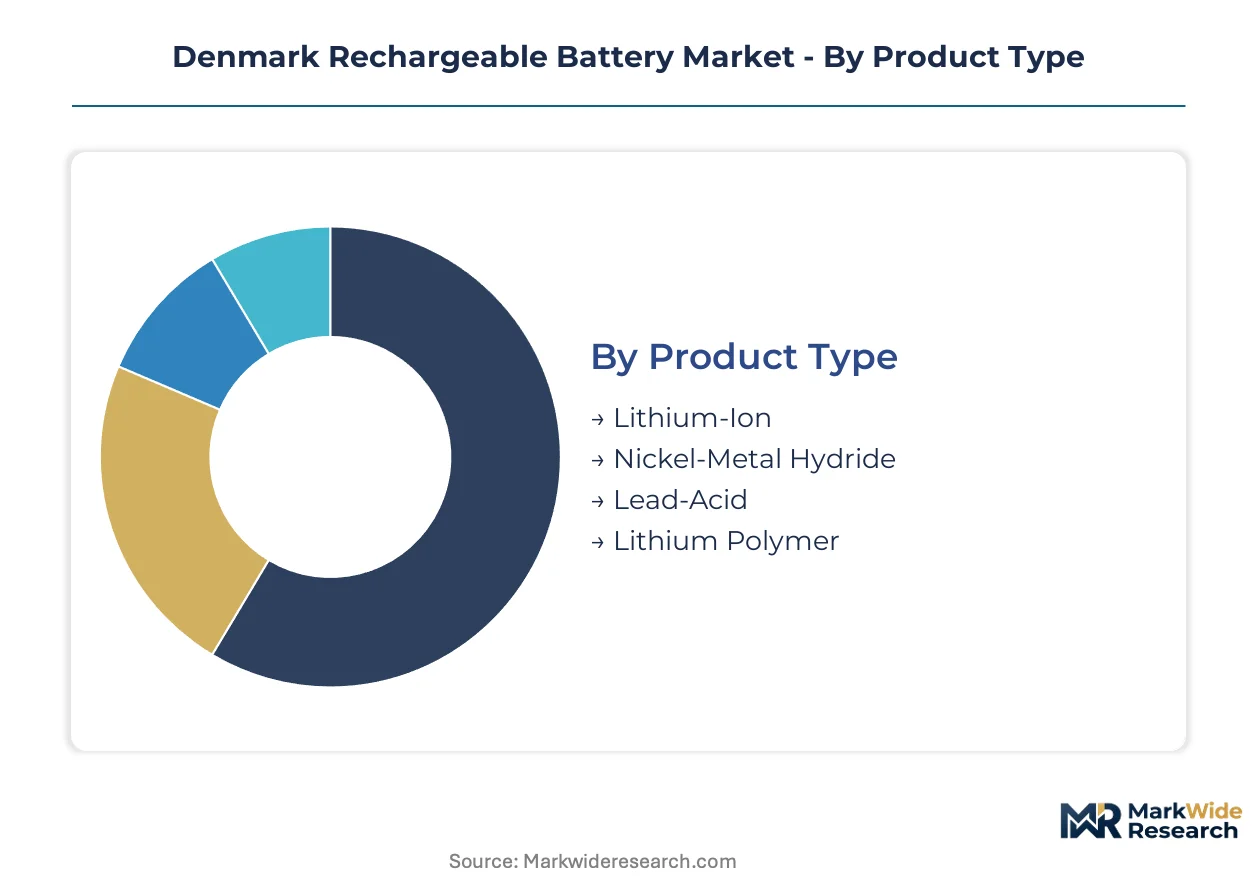
Segmentation in the Danish rechargeable battery market reveals how certification requirements, application-specific performance thresholds, and end-user procurement power concentrate demand around distinct product configurations. Understanding these divides clarifies where pack integrators must align with Danish Energy Agency grid standards versus EU Battery Regulation carbon footprint mandates.
Product Type:
Danish Energy Agency behind-the-meter certification applies differentially across chemistries, with lithium-ion facing the most stringent cycle-life verification for wind-coupled installations while lead-acid operates under simplified backup-power exemptions.
- Lithium-Ion:Graphite anode and metal oxide cathode architecture delivers energy densities above 250 Wh/kg. Procurement concentrates in Copenhagen's electric bus fleet and Bornholm offshore wind buffering projects, where Danish fleet operators compress replacement cycles from seven years to four years under total-cost-of-ownership pressures.
- Lead-Acid:Mature flooded and valve-regulated designs persist where capital cost sensitivity outweighs energy density requirements. Industrial buyers in Jutland's agricultural equipment sector face integration friction retrofitting existing forklift infrastructure, slowing chemistry migration despite lifecycle cost advantages.
- Nickel-Metal Hydride:Rare earth hydride anode chemistry retains niche positioning in hybrid vehicle auxiliary systems and premium power tools where temperature tolerance matters.
- Lithium Polymer:Pouch cell format with gel electrolyte enables flexible form factors for wearable electronics and drone applications, though Danish volume remains constrained by Asian cell supply concentration.
Lithium-ion sits at the top of the volume ranking, with lithium polymer climbing the fastest as marine electrification mandates under the EU Green Deal open specialized procurement channels.
Application:
Cost tier differentiation separates mass-market consumer electronics from capital-intensive grid storage, with the latter requiring 12-18 month Danish Energy Agency approval timelines that reshape project finance structures.
- Electric Vehicles:Traction battery systems face the full EU Battery Regulation carbon footprint declaration requirements. Copenhagen and Aarhus metropolitan procurement dominates, where battery-as-a-service contracts displace outright purchase in municipal bus and commercial van segments.
- Renewable Energy Storage:Grid-scale and behind-the-meter configurations buffer North Sea wind interconnectors. Demand concentrates around Esbjerg port clusters and Bornholm, where district heating-to-battery hybrid pilots create novel thermal-electric integration requirements.
- Consumer Electronics:Smartphone, laptop, and portable device batteries operate under less stringent certification, with retail channel pricing exposed to lithium carbonate volatility.
- Power Tools:Professional-grade cordless equipment favors nickel-metal hydride and lithium-ion packs, with construction sector procurement sensitive to fast-charge capabilities.
Electric vehicles holds the dominant volume position, while renewable energy storage gains share fastest as offshore wind capacity expansion accelerates.
End User:
Customer type determines contract structure, with energy providers and automotive manufacturers locking in multi-year supply agreements while retail channels absorb spot market price swings.
- Automotive Manufacturers:European OEMs serving Denmark negotiate high-volume cell supply relationships with Korean and Chinese producers, then source domestic pack assembly from Xolta A/S and specialized integrators.
- Energy Providers:Orsted and regional utilities drive grid-scale procurement, with Danish Energy Agency interconnection standards forcing 12-18 month certification delays that compress project development timelines.
- Industrial Users:Warehouse operators and manufacturing facilities balance lead-acid replacement complexity against lithium-ion lifecycle gains, with forklift fleet retrofits representing underpenetrated conversion potential.
- Retail Customers:Individual consumers purchase replacement batteries through electronics retailers and automotive service channels, with minimal brand loyalty and high price elasticity.
Automotive manufacturers command the largest procurement volumes, though energy providers are expanding most quickly as wind buffering mandates harden.
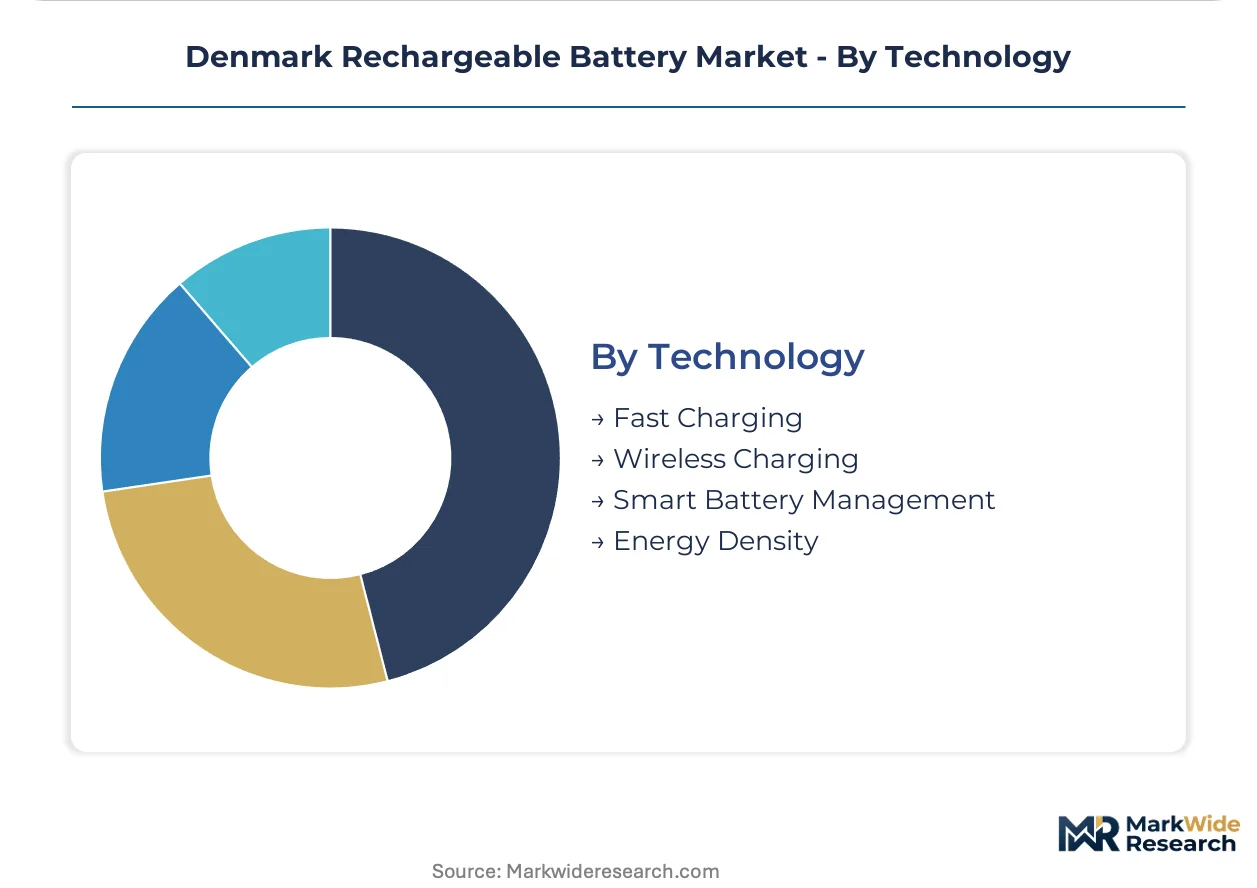
Technology:
Maturity gradients separate commercialized fast-charging infrastructure from emerging solid-state electrolyte research at DTU Energy and Copenhagen University.
- Smart Battery Management:Cell balancing, thermal monitoring, and state-of-charge algorithms extend cycle life and enable second-life grid storage applications. Danish fleet operators leverage residual value guarantees to compress replacement schedules.
- Fast Charging:High-current protocols reduce electric vehicle downtime, with Copenhagen's urban electrification corridors requiring compatible infrastructure investment alongside battery procurement.
- Energy Density:Wh/kg optimization drives material science investment, with solid-state electrolyte research promising step-change improvements in thermal stability and pack-level safety.
- Wireless Charging:Inductive power transfer remains niche in Denmark, limited to premium consumer electronics and pilot autonomous vehicle applications.
Smart battery management leads on installed base, while energy density R&D shows the steepest expansion trajectory as solid-state commercialization timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery manufacturing in Denmark traces its modern lineage to Nordic energy storage pilots in the early 2010s, when wind-rich economies first tested electrochemical buffering for grid stabilization.
Capital Region
Copenhagen's metropolitan corridor concentrates Denmark's highest battery procurement intensity, driven by municipal bus electrification and district heating-to-storage hybrid pilots. The Danish Energy Agency enforces 12-18 month grid interconnection certification timelines that reshape project finance structures. DTU Energy's solid-state research facilities in Lyngby anchor the region's R&D concentration alongside commercial pack assembly operations.
North Denmark Region
Aalborg's industrial base supports marine battery system integration for ferry route decarbonization under EU Green Deal mandates. The Danish Maritime Authority coordinates with regional ports on electrification standards. Esbjerg's offshore wind servicing clusters pull grid-scale storage demand toward western Jutland, where North Sea interconnector projects require buffering capacity.
Central Denmark Region
Aarhus metropolitan procurement mirrors Copenhagen's battery-as-a-service adoption in municipal transport, though at smaller fleet scale. Regional industrial users in Randers and Silkeborg face lead-acid replacement complexity in warehouse forklift fleets. The Danish Environmental Protection Agency's extended producer responsibility rules accelerate commercial vehicle battery replacement schedules across Jutland's logistics corridors.
Southern Denmark Region
Odense's robotics and automation sector generates specialized demand for compact lithium-ion packs in industrial equipment. The region's agricultural machinery electrification remains underpenetrated, offering white space for traction system suppliers. Danish ferry operators serving Bornholm route through southern ports, creating maintenance and retrofit demand for marine-certified battery systems.
Denmark Rechargeable Battery Market Competitive Landscape
The competitive structure tilts toward domestic pack integrators serving Nordic energy storage contracts. Danish assemblers occupy mid-tier positions between Asian cell suppliers and European OEM qualification requirements. Three archetypes dominate: domestic system integrators with regional assembly footprints, international cell producers supplying high-volume cathode materials, and specialized marine/industrial module fabricators. Capacity expansion and strategic partnerships with wind developers constitute the dominant competitive moves.
Among Denmark-based integrators, Xolta A/S and Viridus Manufacturing A/S occupy positions within the domestic assembly tier, while LG Energy Solution, Ltd. represents the international cell supply archetype serving European OEM channels into Denmark.
| Leading Market Players |
|---|
| Xolta A/S |
| Viridus Manufacturing A/S |
| WS Technicals A/S |
| MILA Nordic A/S |
| EPTechnologies |
| ACTEC A/S |
| Lithium Balance |
| Contemporary Amperex Technology Co. Limited (CATL) |
| LG Energy Solution, Ltd. |
| Others |
Pricing and Supply Chain Analysis
Danish fleet operators' compressed replacement cycles—dropping from seven years to four years under total-cost-of-ownership pressures—are forcing pack integrators to absorb lithium carbonate volatility into fixed-price Nordic energy storage contracts. This demand-side compression reshapes how assemblers negotiate cathode precursor supply and where they source cells to defend margins.
Pricing Analysis
Project-based long-term offtake agreements dominate Danish procurement, with pricing stratifying across EU Battery Regulation carbon footprint certification tiers, volume scale commitments, and after-sales service bundling. Cost compression in standard-grade lithium-ion packs is intensifying because Korean and Chinese cell suppliers wield pricing power over Danish assemblers. Municipal bus fleet operators exhibit the highest price sensitivity due to public budget constraints, while offshore wind developers prioritize certification compliance over unit cost.
Supply Chain Analysis
EU Battery Regulation carbon footprint declaration requirements act as qualification gates that filter qualified cell sources for Danish pack integrators. Supply concentrates in China, South Korea, and Japan for cathode precursors and finished cells, while graphite anode material draws from Chinese processing facilities. Single-source vulnerability around lithium carbonate refining creates procurement bottlenecks when spot prices spike. Distribution runs through Esbjerg port clusters for grid-scale projects and Copenhagen metropolitan logistics corridors for urban electrification fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
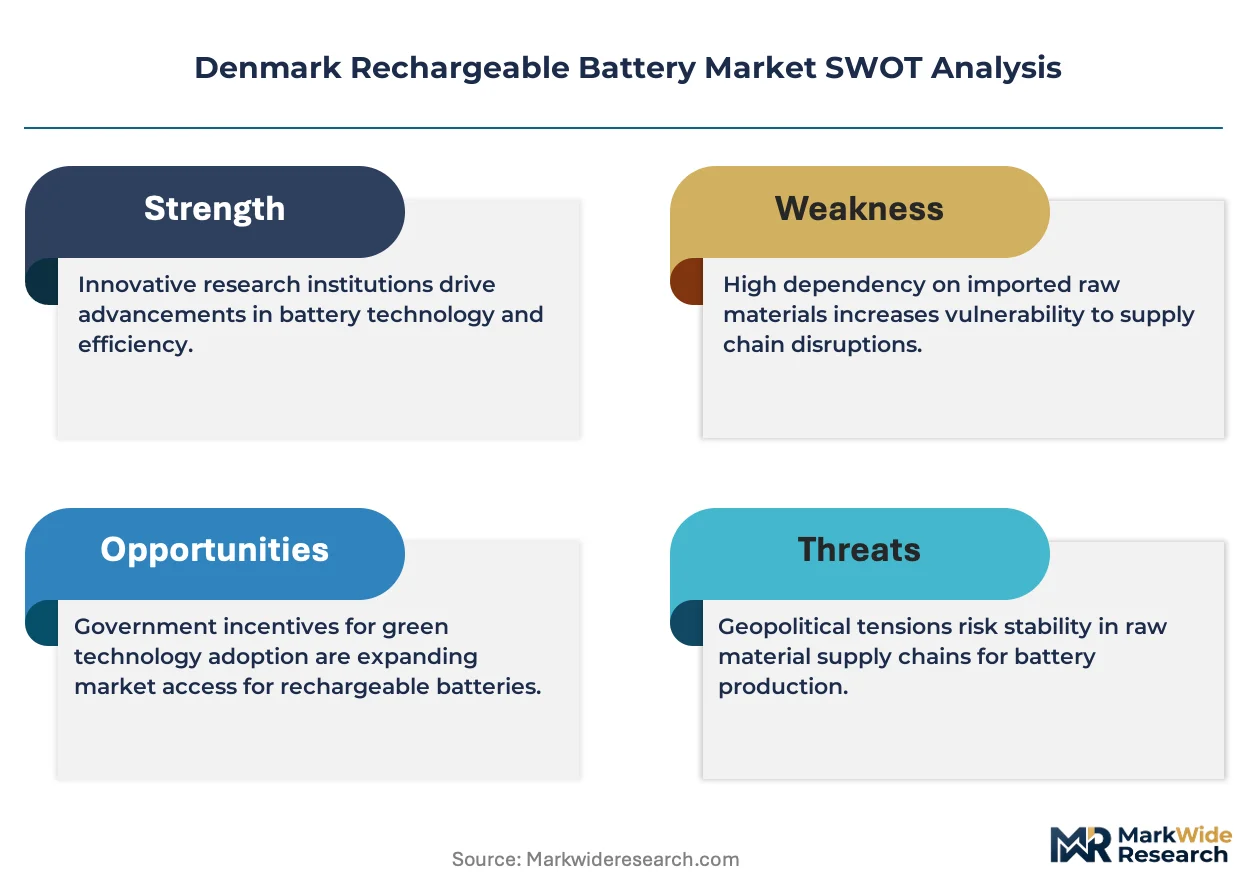
Denmark's rechargeable battery market functions as a geographic-arbitrage play where EU regulatory stringency—particularly the Battery Regulation's extended producer responsibility—creates cost and compliance premiums that domestic assemblers can capture against less-regulated import competition.
For Market Incumbents: Anchor domestic assembly capacity in Jutland to serve underpenetrated agricultural equipment electrification before Asian cell suppliers establish direct pack integration. Invest in Danish Energy Agency grid interconnection certification capabilities to compress 12-18 month approval timelines that currently delay wind-coupled storage projects. Deepen backward integration into battery management system software to differentiate against commodity cell suppliers.
For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer the lowest-friction entry path for specialized marine battery systems serving Bornholm ferry route decarbonization mandates. Target the Southern Denmark Region's agricultural machinery segment where lithium-ion traction penetration remains minimal and incumbent presence is thin. Lead with battery-as-a-service financing structures that match Copenhagen municipal procurement preferences.
For Investors and Strategic Acquirers: Asymmetric upside sits with solid-state electrolyte R&D ventures spun out from DTU Energy and Copenhagen University partnerships, where commercialization timeline compression could unlock premium positioning. The five-to-ten year viability window favors acquisition of Danish pack integrators with proven Danish Energy Agency certification track records and existing Nordic energy storage contract backlogs. Watch for EU critical raw material sourcing disclosure rule finalization as the inflection signal for supply contract renegotiation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Supply | Reduces Korean and Chinese supplier pricing power over Danish assemblers. |
| Danish Energy Agency Certification Pre-Approval | Compresses 12-18 month grid interconnection timelines for wind-coupled storage. |
| Battery-as-a-Service Platform Launch | Matches Copenhagen and Aarhus municipal fleet procurement financing preferences. |
| Marine Electrification System Specialization | Captures EU Green Deal ferry decarbonization mandates through Bornholm routes. |
| Solid-State Electrolyte R&D Partnership | Accelerates DTU Energy commercialization timelines for next-generation cell production. |
Research Methodology
Direct dialogue with battery pack integration engineers, Danish Energy Agency certification officers, offshore wind project developers, and municipal fleet procurement managers grounded the qualitative foundation. Secondary validation drew from EU Battery Regulation implementation guidance, Danish Environmental Protection Agency enforcement records, North Sea wind interconnector development databases, and customs trade data on lithium-ion cell imports. Bottom-up project pipeline analysis and top-down regulatory impact assessment were triangulated to cross-verify market sizing.
Installed base estimates and value projections across the analysis window reflect segment-level modeling of lithium-ion, lead-acid, nickel-metal hydride, and lithium polymer chemistries by application—electric vehicles, renewable energy storage, consumer electronics, and power tools—and end user type. CAGRs were derived from regression against historical procurement patterns and policy-mandated replacement schedules. Key forecast inputs included Danish fossil-fuel vehicle sales ban compliance timelines and offshore wind capacity expansion trajectories.
Lithium carbonate price volatility, EU critical raw material disclosure rule finalization delays, and solid-state electrolyte commercialization setbacks are the dominant revision risks to the forecast framework. A model refresh is warranted upon material change in Danish Energy Agency grid interconnection certification processing speeds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Global Solar Battery Charger Market
Batteries
West Europe Battery Market
Batteries
Low Temperature Battery Market
Batteries
Micro Battery Market
Batteries
High Temperature NiMH Battery Market
Batteries
North Africa Battery Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Lithium-Based Battery Charger Market
Batteries
Smart Battery Market
Batteries
Zinc Carbon Battery Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
North Europe Battery Market
Batteries
Lead Acid Battery Market
Batteries
India SLI Battery Market
Batteries
SLI Battery Market
Batteries
Power-Sports Batteries Market