
 Middle East and Africa Automotive Aftermarket Glass Market | 2026-2036
Middle East and Africa Automotive Aftermarket Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Automotive Aftermarket Glass Market Foresight
Modular windshield-and-adhesive bundling is consolidating buyer choice across the Middle East and Africa Automotive Aftermarket Glass Market, pushing independent repair shops toward pre-assembled kits. Saint-Gobain leverages its regional manufacturing footprint to supply laminated glass assemblies to wholesale distributors. AGC Inc. anchors premium windshield demand through specialized acoustic and solar-control product lines. Sisecam competes aggressively on tempered side-window volumes for the fleet operator segment.
The Middle East and Africa Automotive Aftermarket Glass comprises replacement glazing components manufactured from soda-lime silica formulations, with laminated windshields incorporating polyvinyl butyral interlayers for structural integrity and tempered side and rear windows undergoing controlled thermal treatment to achieve fragmentation patterns that reduce occupant injury. Windshields command the dominant value share due to complexity of installation and regulatory mandates for laminated construction, while sunroofs represent the fastest-expanding product category as OEM sunroof penetration rises in vehicles now entering their replacement cycle. Tempered glass sustains volume leadership in side and rear applications, though polycarbonate alternatives are gaining traction in commercial vehicle segments where weight reduction delivers fuel economy benefits.
South Africa's NRCS compulsory specification, Saudi Arabia's SASO quality mark requirements, and the UAE's ESMA conformity schemes collectively shape product standards and market access across the region, with compliance costs favoring suppliers with established certification infrastructure. Fleet operators and repair shops must monitor evolving national standards that increasingly reference ECE R43 and ANSI Z26.1 test protocols. Stakeholders should evaluate certification breadth as a primary filter for supplier selection, since regulatory divergence between Gulf Cooperation Council members and sub-Saharan African markets continues to fragment distribution requirements.
Market Dynamics
Fleet operators across the Middle East and Africa are intensifying glass replacement cycles as road infrastructure expansion accelerates vehicle wear rates. This demand compression is reshaping supplier-distributor relationships around pre-assembled modular kits.
Growth Catalysts
- Road Infrastructure Expansion:Saudi Arabia's giga-project construction and UAE logistics corridor development are elevating commercial vehicle utilization rates. Glass damage incidents rise proportionally with aggregate vehicle-kilometers.
- ESMA Conformity Schemes:The UAE's Emirates Authority for Standardization and Metrology mandates laminated windshield certification for all replacement installations. Compliance requirements filter substandard imports and elevate certified supplier margins.
- Sunroof Penetration Legacy:OEM sunroof installation rates in premium vehicles from the 2018-2022 production wave are now triggering replacement demand. This application category commands 40-60% value premiums over standard windshields.
Market Restraints
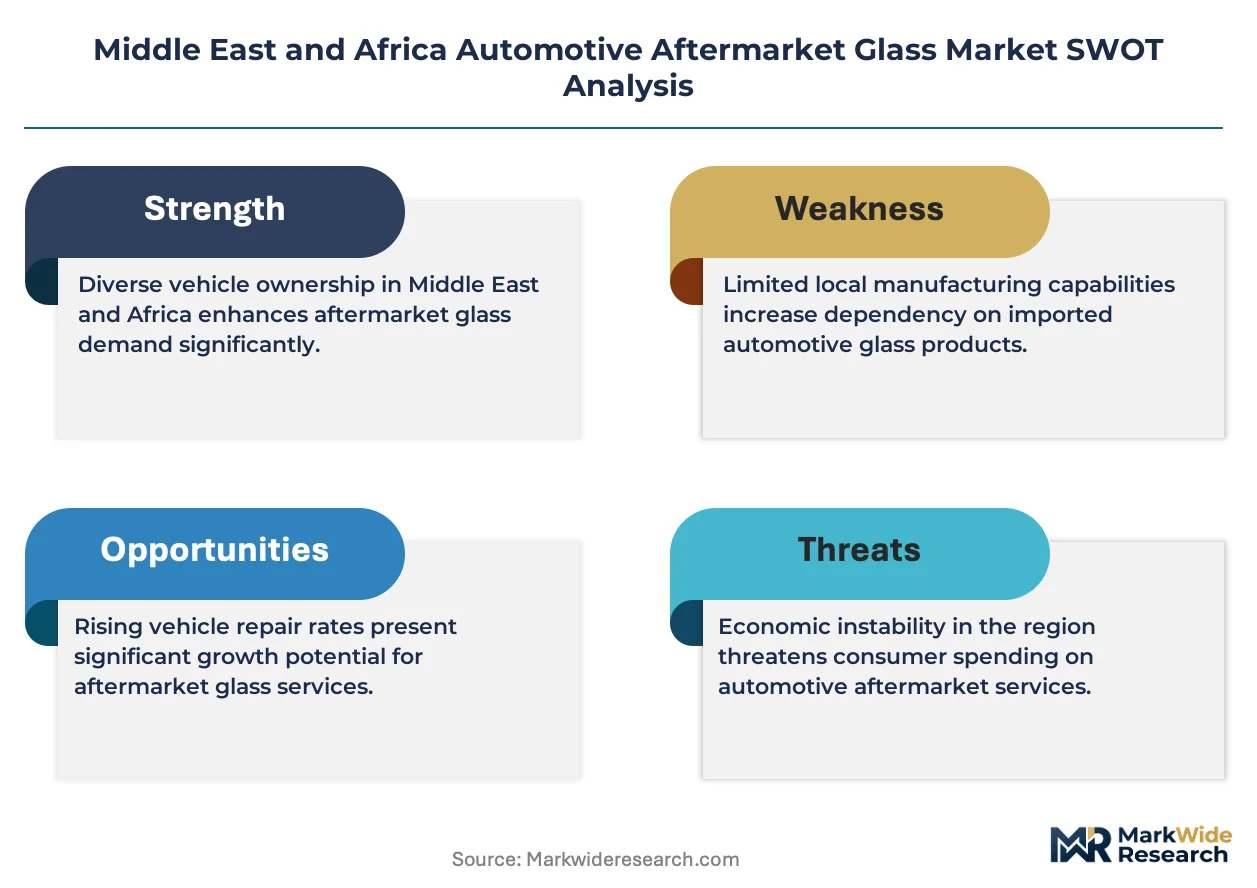
- PVB Interlayer Cost Volatility:Polyvinyl butyral resin prices track petrochemical feedstock fluctuations. Laminated windshield manufacturers absorb margin compression when crude derivatives spike.
- Import Concentration Risk:Sub-Saharan African markets depend on containerized shipments from Turkish and Egyptian production hubs. Port congestion at Mombasa and Lagos extends inventory cycles by 3-6 weeks.
- Polycarbonate Substitution:Commercial vehicle operators in South Africa and Nigeria are piloting polycarbonate side-window panels. Weight reduction delivers measurable fuel economy gains on long-haul routes.
Strategic Opportunities
- Kenya's Underpenetrated Fleet Segment:Nairobi's matatu operator cooperatives maintain 15,000+ vehicles with minimal formal glass supply relationships. Structured fleet contracts could consolidate this dispersed demand.
- Acoustic Windshield Convergence:Laminated glass with embedded acoustic interlayers is penetrating premium SUV replacement channels. This technology merges noise reduction with structural safety functions.
- SASO Quality Mark Acceleration:Saudi Arabia's Saudi Standards, Metrology and Quality Organization is expanding mandatory certification to tempered side windows. Early certifiers gain preferential distributor placement.
Industry Challenges
- ADAS Calibration Skill Gap:Windshield replacement now requires camera and sensor recalibration. Technician training lags behind vehicle technology penetration in regional repair shops.
- Multi-Jurisdiction Certification Timelines:Suppliers serving both GCC and sub-Saharan markets must maintain parallel compliance documentation. NRCS, SASO, and ESMA testing protocols diverge on impact resistance thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Automotive Aftermarket Glass Market |
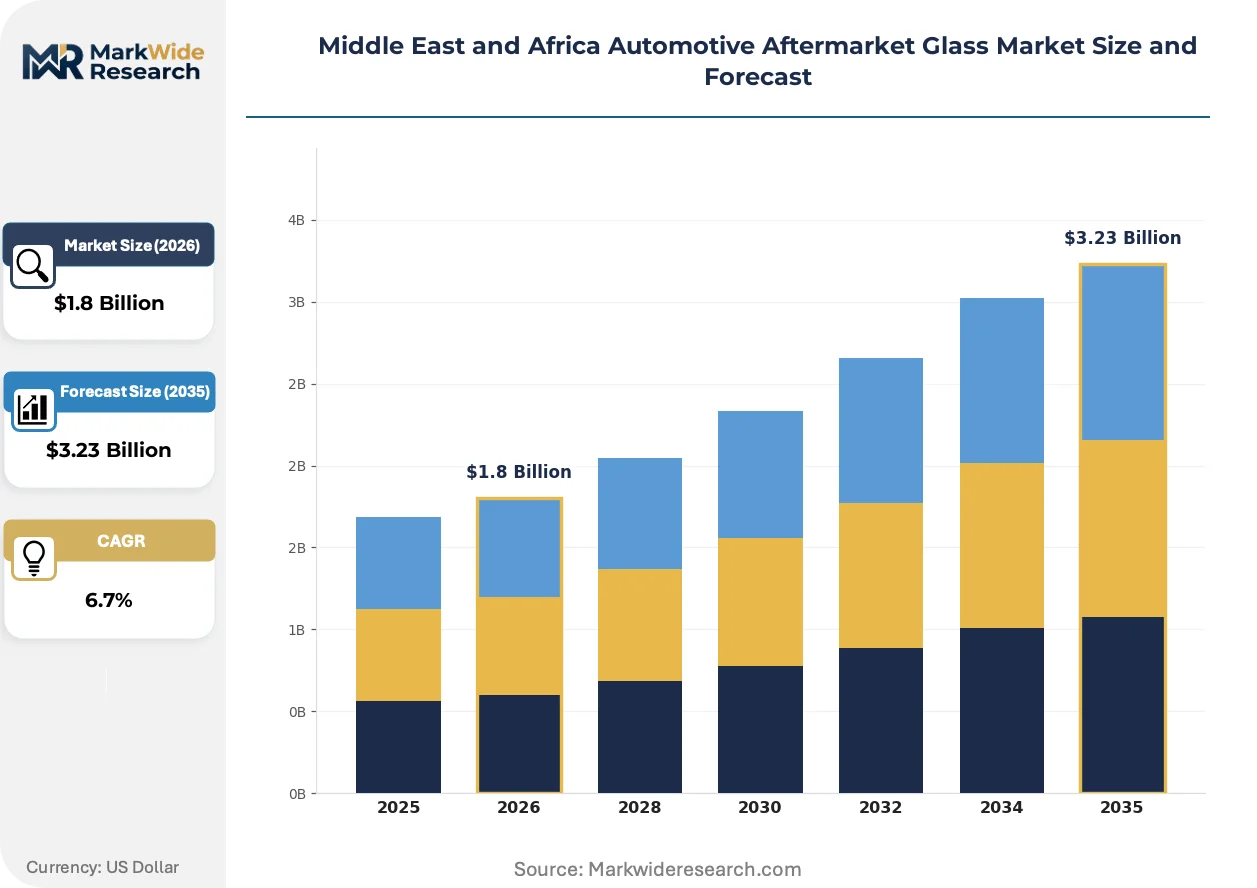
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windshields, Side Windows, Rear Windows, Sunroofs End User: Retail Customers, Automotive Repair Shops, OEMs, Fleet Operators Distribution Channel: Online Retail, Offline Retail, Wholesale Distributors, Direct Sales Material: Tempered Glass, Laminated Glass, Polycarbonate, Others |
| Companies Covered | Saint-Gobain, AGC Inc., Fuyao Glass Industry Group, NSG Group, Xinyi Glass, Sisecam, Cleopatra Glass, Shatterprufe, Olimpia Auto Glass, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Automotive Aftermarket Glass Market Shifts & Advancements
Technological layering and regulatory harmonization pressures are converging to transform product specifications and distribution architectures across Middle East and Africa glass replacement channels.
Embedded sensor-compatible windshield designs are expanding into the premium vehicle replacement segment. These laminates incorporate dedicated mounting zones for rain sensors, lane-departure cameras, and heads-up display projectors. High-end repair shops in Dubai and Riyadh are retrofitting calibration equipment to capture this installation complexity premium.
South Africa's NRCS compulsory specification for automotive safety glass is tightening fragmentation pattern requirements for tempered products. The regulation now references ECE R43 test protocols for optical clarity and mechanical strength. Domestic distributors are rationalizing supplier bases to exclude uncertified Asian imports that dominated price-sensitive channels.
Commercial fleet managers are consolidating procurement through authorized dealer networks rather than independent glass shops. This channel migration compresses price transparency and locks volume commitments into annual framework agreements. The shift is most visible in UAE logistics hubs where Jebel Ali-based operators negotiate direct with Saint-Gobain and AGC distribution arms.
Middle East and Africa Automotive Aftermarket Glass Market Segmentation
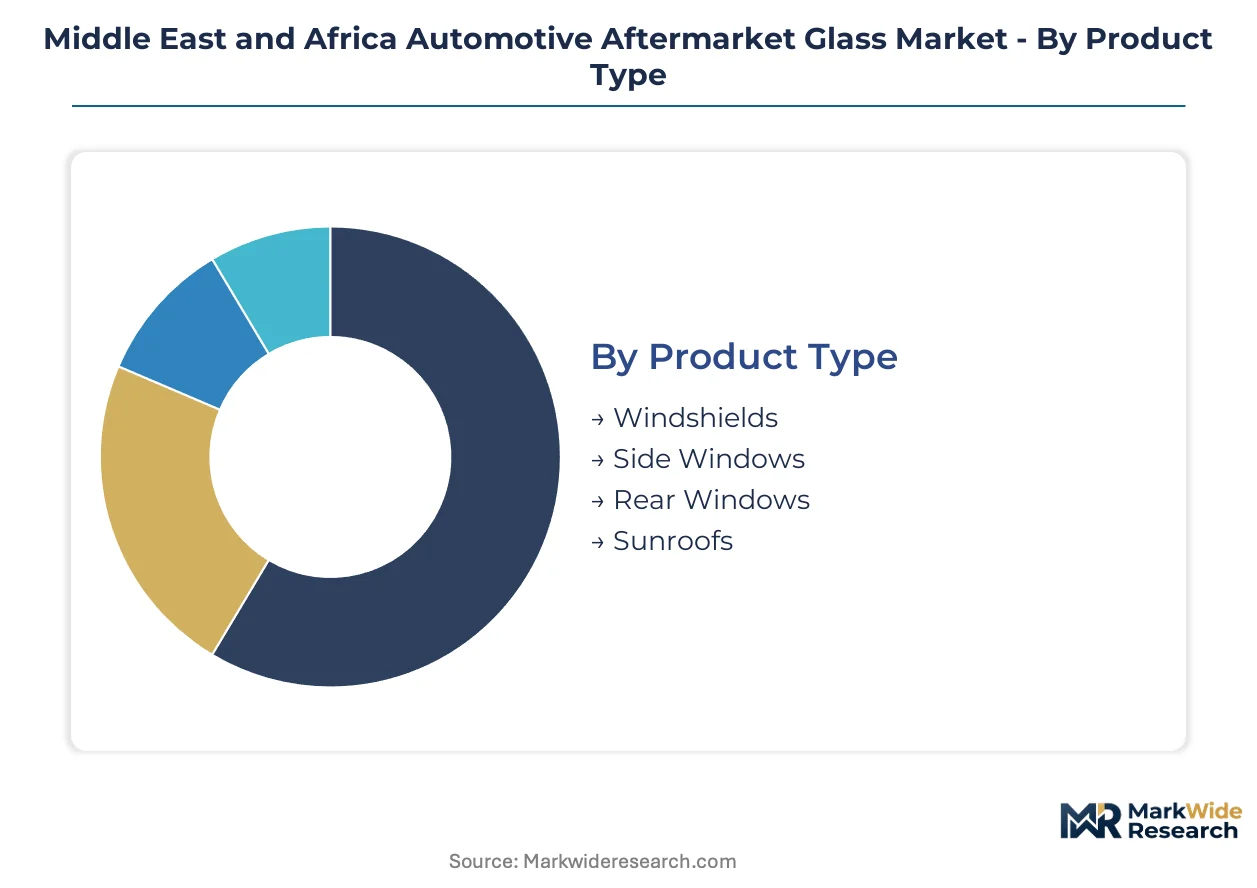
Segmentation in the Middle East and Africa Automotive Aftermarket Glass Market reveals how supply-side capabilities align with distinct demand profiles. Each category exposes structural mismatches between certified manufacturing capacity and localized replacement needs.
Product Type:
Supply concentration for complex laminated assemblies shapes competitive positioning across replacement channels.
- Windshields:Laminated glass incorporating polyvinyl butyral interlayers dominates value capture. Dubai's commercial vehicle hub and Riyadh's fleet corridors concentrate demand where ESMA and SASO certification filters substandard imports.
- Sunroofs:OEM sunroof penetration in premium vehicles from recent production waves now triggers replacement cycles. South Africa's NRCS fragmentation requirements and acoustic interlayer adoption in UAE premium channels drive specification complexity.
- Side Windows:Tempered glass volumes sustain fleet operator procurement across Nigerian and Kenyan long-haul corridors.
- Rear Windows:Standard tempered formulations serve price-sensitive replacement demand in informal repair networks.
Windshields absorb the bulk of installed capacity; sunroofs are expanding most quickly.
End User:
Customer type determines procurement scale and certification tolerance, with fleet consolidation rewriting distributor relationships.
- Fleet Operators:Annual framework agreements with authorized dealer networks compress price transparency. Jebel Ali-based logistics operators negotiate direct volume commitments with certified suppliers, bypassing traditional wholesale channels.
- Automotive Repair Shops:Modular windshield-and-adhesive bundling consolidates buyer choice toward pre-assembled kits. Technician training lags on ADAS calibration requirements, creating installation complexity premiums for equipped facilities.
- Retail Customers:Individual vehicle owners in fragmented sub-Saharan markets depend on informal glass shops with limited certified product access.
- OEMs:Authorized service networks maintain captive supply relationships for warranty-period replacements.
Fleet operators command the deepest volume commitments; automotive repair shops face the steepest capability upgrade pressures.
Distribution Channel:
Channel structure reflects certification infrastructure proximity and inventory cycle tolerance across divergent regulatory zones.
- Wholesale Distributors:Saint-Gobain and AGC distribution arms anchor certified product flows to UAE and Saudi Arabia. Mombasa and Lagos port congestion extends inventory cycles by weeks, favoring distributors with bonded warehousing.
- Direct Sales:Fleet procurement consolidation bypasses intermediaries in commercial vehicle hubs. Annual framework agreements lock volume commitments and compress spot-market participation.
- Offline Retail:Independent glass shops in South Africa and Nigeria maintain price-sensitive channel positions with mixed certification compliance.
- Online Retail:Digital penetration remains limited by installation service requirements and ADAS calibration complexity.
Wholesale distributors retain structural dominance in certified product flows; direct sales channels are climbing the fastest as fleet consolidation accelerates.
Material:
Material selection tracks application-specific safety mandates and weight-driven fuel economy calculations in commercial segments.
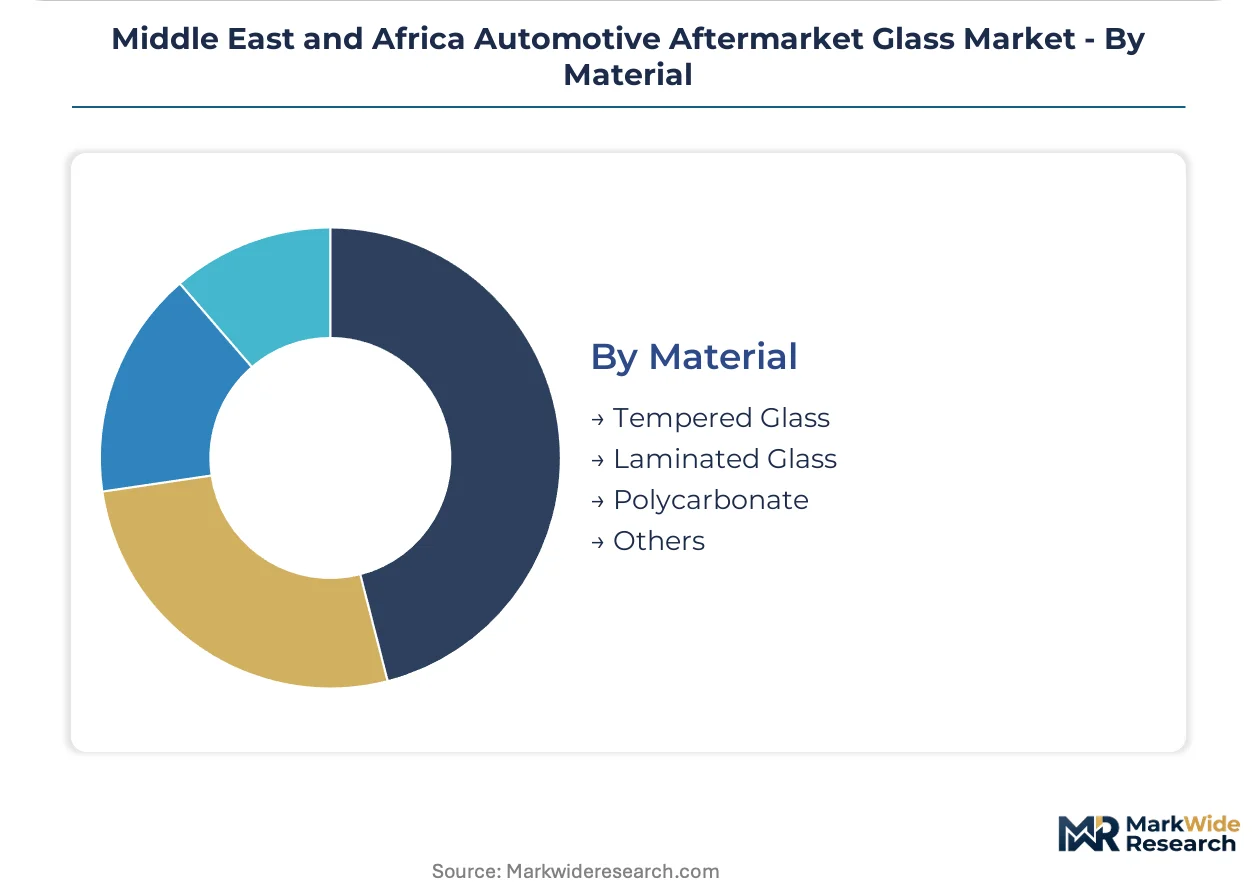
- Laminated Glass:Windshield mandates under ESMA, SASO, and South Africa's NRCS compulsory specification enforce polyvinyl butyral interlayer construction. PVB resin cost volatility tracks petrochemical feedstock fluctuations, compressing margins during crude derivative spikes.
- Tempered Glass:Controlled thermal treatment achieves fragmentation patterns reducing occupant injury in side and rear applications. Volume leadership persists where regulatory enforcement remains uneven.
- Polycarbonate:Commercial vehicle operators in South Africa and Nigeria pilot side-window panels where weight reduction delivers measurable fuel economy gains on long-haul routes.
- Others:Emerging formulations including acoustic interlayers and solar-control coatings penetrate premium replacement channels in Dubai and Riyadh.
Laminated glass captures the dominant value share; polycarbonate alternatives are gaining share fastest in weight-sensitive commercial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Turkey and Egypt while consumption concentrates in Gulf logistics corridors and South African fleet networks. This geographic mismatch shapes inventory cycles and certification requirements across replacement channels.
United Arab Emirates
Commercial vehicle utilization at Jebel Ali and Dubai South logistics hubs drives windshield replacement volumes. ESMA conformity schemes mandate laminated glass certification, filtering uncertified imports from wholesale channels. Dubai's authorized dealer networks negotiate direct procurement contracts with certified suppliers.
Saudi Arabia
Giga-project construction fleets and Riyadh logistics corridors elevate tempered side-window demand for heavy-duty trucks. SASO quality mark requirements are expanding to cover side-window categories beyond windshields. Jeddah's bonded warehousing infrastructure shortens inventory cycles for Turkish-manufactured laminated assemblies.
South Africa
Long-haul fleet operators on the N3 corridor between Johannesburg and Durban sustain tempered glass volumes. NRCS compulsory specifications now reference ECE R43 fragmentation protocols for optical clarity. Port Elizabeth's automotive supplier zone hosts distributors rationalizing supplier bases to exclude non-compliant Asian imports.
Nigeria
Informal transport cooperatives in Lagos and Abuja maintain fragmented procurement patterns with limited certified product access. The country's national standards body enforces evolving safety glass specifications without unified federal inspection infrastructure. Apapa port congestion extends inventory cycles by 4-6 weeks for Egyptian-sourced container shipments.
Kenya
Matatu operator cooperatives in Nairobi manage 15,000+ vehicles with minimal formal glass supply relationships. Kenya Bureau of Standards maintains automotive glass specifications that diverge from GCC certification protocols. Mombasa port delays favor distributors with inland bonded warehousing at Athi River industrial zone.
Middle East and Africa Automotive Aftermarket Glass Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers and distribution channels. The vendor base separates into three strategic archetypes: integrated materials conglomerates with regional manufacturing footprints, specialized automotive glass fabricators, and regional distributors with bonded warehousing capabilities. Consolidation pressures favor suppliers with parallel NRCS, SASO, and ESMA certification infrastructure. Capacity expansion and strategic distributor partnerships constitute the dominant competitive moves as fleet procurement consolidates.
Within the integrated conglomerate tier, Saint-Gobain and AGC Inc. exemplify scale-driven positioning through regional distribution arms and certified manufacturing proximity. Sisecam occupies a focused specialist position, anchoring tempered glass volumes for fleet operator segments. These three entities represent the certification-breadth archetype that procurement managers filter for when navigating multi-jurisdiction compliance requirements across GCC and sub-Saharan markets.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| Fuyao Glass Industry Group |
| NSG Group |
| Xinyi Glass |
| Sisecam |
| Cleopatra Glass |
| Shatterprufe |
| Olimpia Auto Glass |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap distributors across Turkey and Egypt anchor regional supply flows, translating bonded warehousing investments into pricing discipline that resists spot-market volatility. Their concentrated ownership structures enable long-term contracting with fleet operators that locks out price-sensitive informal channels.
Pricing Analysis
Margin tightening in certified laminated windshields reflects PVB resin cost volatility tracking petrochemical feedstock movements. Three-tier pricing structure across ESMA-certified premium, SASO-compliant standard, and uncertified economy levels separates fleet procurement from retail replacement demand. Cost-down pressure on tempered side windows accelerates because polycarbonate substitution trials in South African long-haul fleets threaten volume commitments. Fleet operators exhibit lowest price sensitivity due to annual framework agreements, while Nairobi matatu cooperatives remain most exposed to spot-market fluctuations.
Supply Chain Analysis
Direct-to-fleet channels handle consolidated procurement from Jebel Ali and Riyadh logistics hubs, bypassing traditional wholesale intermediaries. Manufacturing concentrates in Turkish coastal plants, Egyptian glassworks near Alexandria, and domestic South African fabricators serving NRCS-mandated demand. Raw material dependencies center on soda-ash shipments from Solvay's European operations, PVB resin from Eastman and Kuraray, and silica sand from regional desert quarries. Single-source vulnerability in PVB interlayer supply creates margin compression risk during crude derivative spikes. Distribution runs through bonded warehousing at Jeddah, Dubai, and Athi River to circumvent Mombasa and Lagos port congestion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified manufacturing capacity scarcity props pricing power across replacement channels, as ESMA and SASO compliance timelines extend 6-12 months for new entrants. This bottleneck sustains incumbent margins despite input cost volatility.
For Market Incumbents: Anchor certification breadth across NRCS, SASO, and ESMA protocols to lock out Asian import competition in South Africa. Deepen backward integration into PVB interlayer supply or captive silica processing to defend against petrochemical feedstock spikes. Prioritize ADAS calibration training partnerships with Dubai and Riyadh dealer networks to capture installation complexity premiums. For New Entrants and Emerging Players: Enter via Kenya's matatu operator cooperatives, where 15,000+ vehicles lack formal glass supply relationships and certification enforcement remains uneven. Target acoustic windshield retrofit demand in UAE premium SUV channels where specification complexity filters low-cost competition. Pursue direct fleet contracting with Nairobi-based logistics operators to bypass congested Mombasa wholesale channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor Turkish manufacturing assets with established GCC certification infrastructure and Egyptian exporters serving sub-Saharan markets. Long-term viability hinges on parallel compliance capability across fragmentation standards that diverge between Gulf Cooperation Council and East African Community regulatory zones. Watch for SASO expansion of mandatory certification to tempered side windows as an inflection signal for margin compression in that tier.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Expansion | Parallel NRCS, SASO, and ESMA accreditation locks out uncertified Asian imports from South African and Gulf markets. |
| Backward Integration into PVB Supply | In-house polyvinyl butyral resin sourcing insulates laminated windshield margins from petrochemical feedstock volatility. |
| ADAS Calibration Capability Buildout | Technician training partnerships with Dubai dealer networks capture installation complexity premiums on sensor-compatible windshields. |
| Bonded Warehousing Network Expansion | Inland storage at Athi River and Jeddah shortens inventory cycles threatened by Mombasa and Apapa port congestion. |
| Direct Fleet Procurement Contracts | Annual framework agreements with Jebel Ali logistics operators bypass wholesale intermediaries and compress spot-market exposure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fleet procurement managers, automotive glass distributors, NRCS certification auditors, and ADAS calibration technicians combined with secondary validation from SASO quality mark registries, ESMA conformity databases, and Turkish Exporters Assembly shipment records. Bottom-up triangulation across vehicle parc estimates and replacement frequency assumptions reconciled with top-down market sizing from regional production capacity disclosures.
Data-stream reconciliation across volume and value outputs employed segmentation modeling by product type, end-user archetype, distribution channel, and material formulation. CAGRs derived from regression analysis of historical replacement cycles against fleet expansion trajectories and road infrastructure investment pipelines. Industry-specific forecast inputs incorporated OEM sunroof penetration legacy effects and polycarbonate substitution elasticity in commercial vehicle segments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios between Gulf Cooperation Council harmonization and East African Community fragmentation. Periodic stress-testing of base assumptions is recommended, particularly regarding PVB resin price volatility and port congestion duration at Mombasa and Lagos.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Global Fleet Maintenance Software Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Car Care Cosmetics Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Silicone in Car Care Products Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market