
 Premium Electric Motorcycle Market | 2026-2036
Premium Electric Motorcycle Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Electric Motorcycle Market Analysis
Urban commuters are redrawing the premium electric motorcycle demand map as city dwellers with disposable income trade combustion convenience for zero-emission access privileges. Zero Motorcycles leverages its early-mover platform architecture to dominate North American urban corridors. BMW Motorrad anchors European credibility through its Munich-engineered battery thermal management and established dealer infrastructure. Lightning Motorcycles specializes in extreme-performance sub-segments where drag-strip acceleration metrics command price premiums.
A premium electric motorcycle integrates high-voltage battery packs exceeding 15 kWh with liquid-cooled permanent magnet motors delivering 100-plus horsepower, wrapped in chassis architectures that satisfy both track-day dynamics and daily rideability. Sport configurations currently capture the largest margin pools due to performance-tuned suspension and aerodynamic bodywork that justify top-tier pricing. Solid-state battery technology is attracting the fastest development investment as cell manufacturers promise energy density gains that would extend highway range beyond current lithium-ion ceilings. Urban commuters and luxury buyers represent the most structurally advantaged target audience segments because municipal congestion policies and discretionary spending resilience create dual demand buffers.
The US EPA tailpipe standards and the EU Green Deal's 2035 combustion sales ban are forcing powertrain electrification timelines that compress manufacturer R&D cycles. The EU AI Act and ISO 26262 functional safety standards are reshaping product liability frameworks for connected rider-assistance systems. Stakeholders must monitor how battery passport traceability mandates alter supply chain qualification costs and sourcing flexibility across European and North American markets.
Market Dynamics
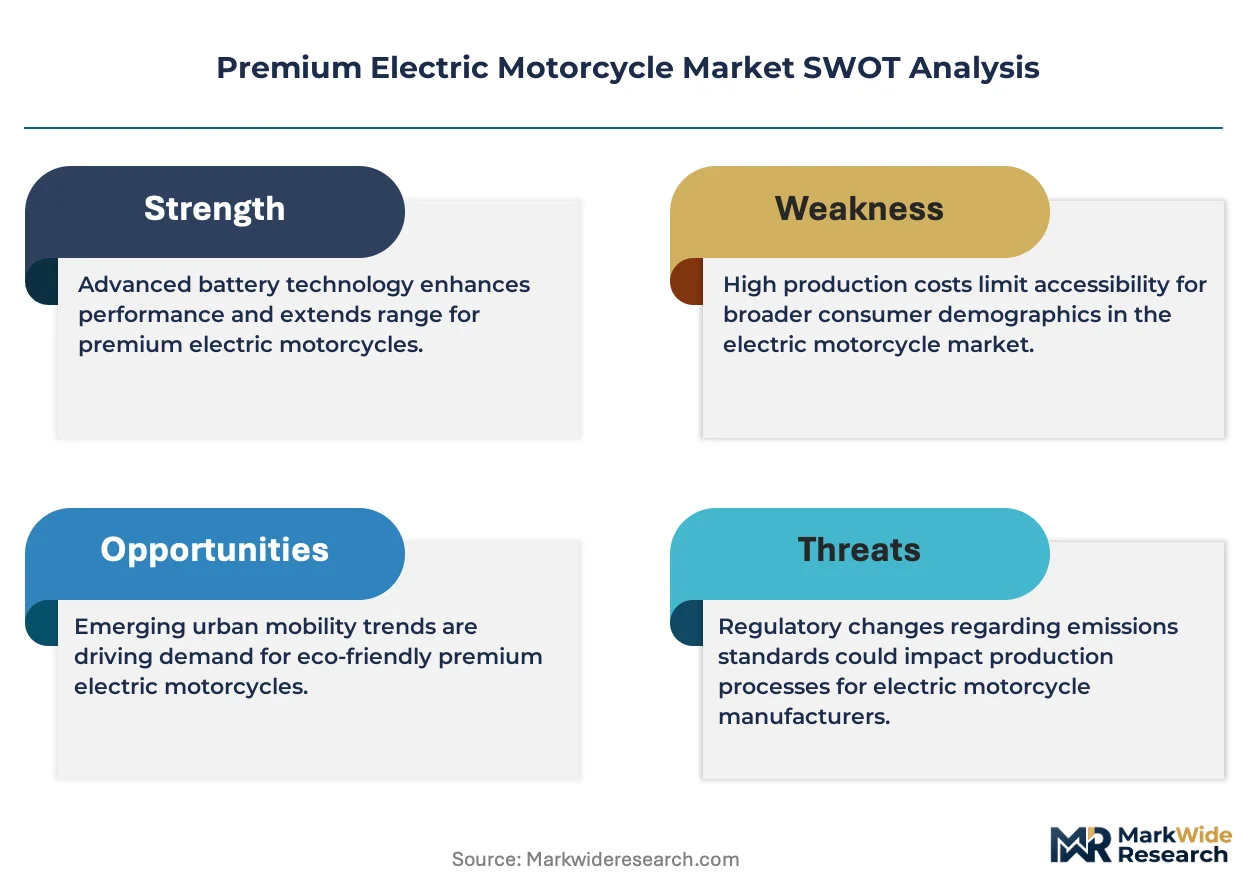
Solid-state battery chemistry transitions are compressing charge cycles while extending thermal stability envelopes, forcing incumbent lithium-ion pack architectures toward obsolescence risk and reshaping supplier qualification timelines across the premium two-wheeler value chain.
Growth Catalysts
- Battery passport mandates:EU battery passport traceability requirements under the EU Green Deal are accelerating supply chain transparency investments, creating competitive moats for early-compliant manufacturers.
- Congestion pricing expansion:Metropolitan mobility pricing schemes in London, Singapore, and Stockholm are privileging zero-emission vehicle access, redirecting affluent commuter spending toward premium electric motorcycles.
- Silicon-anode integration:Advanced anode material adoption is lifting energy density thresholds without full solid-state transitions, enabling interim range extensions that satisfy autobahn-performance specifications.
Market Restraints
- Raw material concentration:Cobalt and lithium refining capacity concentrates in the Democratic Republic of Congo and Chile, exposing cell manufacturers to geopolitical supply interruptions and price volatility.
- Thermal runaway physics:Current-generation lithium-ion packs face inherent energy density ceilings where safety margins constrain pack architecture flexibility, limiting power-to-weight ratios.
- Charging infrastructure asymmetry:Fast-charging network deployment lags vehicle capability in rural Germany and secondary US corridors, creating range anxiety that suppresses non-urban demand.
Strategic Opportunities
- Battery subscription unbundling:Separating cell ownership from vehicle purchase is emerging in Nordic markets, lowering entry price points while securing recurring revenue streams for manufacturers.
- Track-day experience bundling:Premium sport configurations can integrate circuit access and rider coaching, monetizing performance credibility beyond hardware margins.
- India PLI scheme alignment:India's production-linked incentive scheme for advanced chemistry cell manufacturing offers cost-competitive sourcing pivots for brands seeking geographic diversification.
Industry Challenges
- ISO 26262 functional safety certification:Connected rider-assistance systems require ASIL-rated validation cycles that extend development timelines and strain embedded software engineering capacity.
- Dealer technical retraining:Legacy motorcycle service networks lack high-voltage certification infrastructure, forcing manufacturers to build parallel training ecosystems or vertically integrate service operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Electric Motorcycle Market |
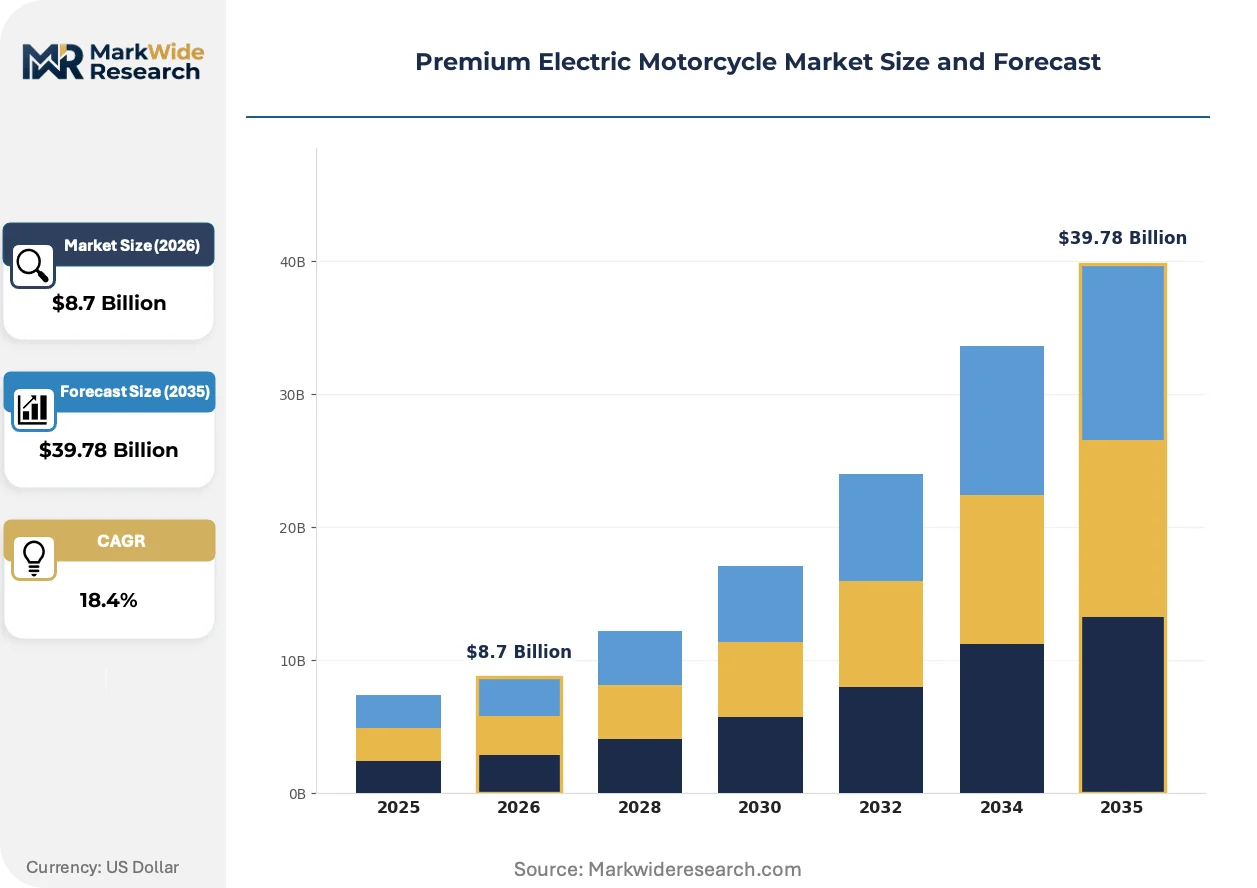
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sport, Cruiser, Touring, Off-Road Battery Technology: Lithium-ion, Solid State, Lead Acid, Nickel-Metal Hydride Target Audience: Urban Commuters, Enthusiasts, Eco-conscious Consumers, Luxury Buyers Distribution Channel: Dealerships, Online Retail, Specialty Stores, Direct Sales |
| Companies Covered | Damon Motorcycles, BMW Motorrad, Zero Motorcycles, LiveWire, REZON, Lightning Motorcycles, Verge Motorcycles, Stark Future, Harley-Davidson LiveWire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Electric Motorcycle Market Emerging Trajectories
Powertrain architecture decisions are splitting along thermal management philosophy lines, with air-cooled simplicity competing against liquid-cooled performance density for segment dominance and manufacturing capital allocation.
Silicon-carbide inverter topology is bifurcating motor control strategies between efficiency-optimized commuter platforms and performance-tuned sport configurations. Urban delivery fleets and daily commuters favor the former for range preservation. The technology is bifurcating supplier ecosystems into automotive-scale semiconductor houses and specialized motorcycle electronics vendors with incompatible volume expectations.
EU AI Act liability frameworks are reclassifying adaptive cruise control and collision avoidance systems as high-risk AI applications, triggering mandatory conformity assessment procedures. Motorcycle OEMs must now document algorithmic decision transparency and human oversight protocols. Sport and touring segments with extensive rider-assistance suites face the steepest compliance cost escalations.
Direct-to-consumer configuration platforms are displacing traditional dealer inventory models in metropolitan markets. Younger buyers in Germany and California expect online specification tools with factory delivery scheduling. Urban commuter segments show the highest digital purchase completion rates, while sport buyers still demand physical test-ride validation before transaction commitment.
Premium Electric Motorcycle Market Segmentation
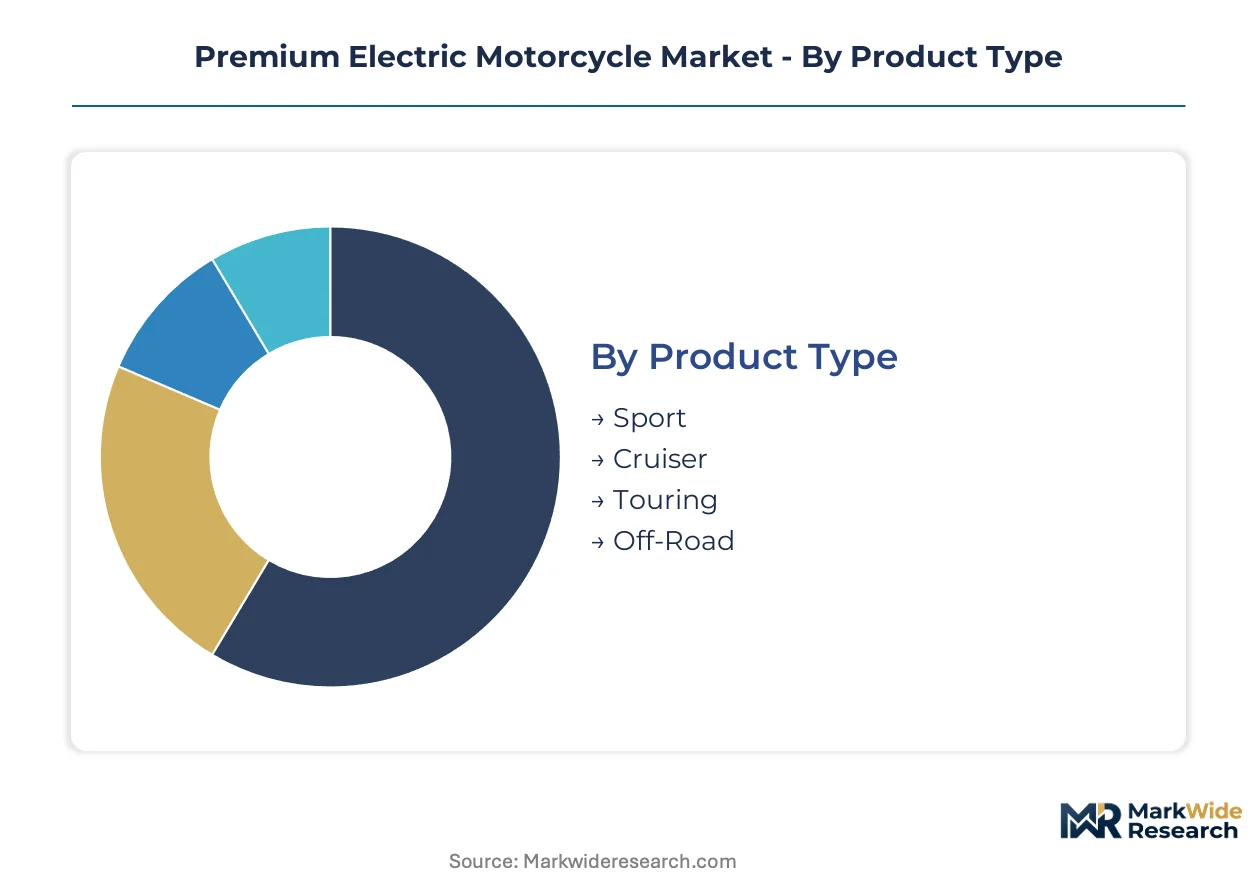
Premium electric motorcycle segmentation reveals how regulatory frameworks and infrastructure maturity create divergent growth trajectories across product configurations and buyer archetypes. Manufacturers must align battery chemistry roadmaps and distribution investments with geographically clustered demand patterns to capture margin pools.
Product Type:
EU Green Deal vehicle classification standards and national type-approval procedures create divergent compliance burdens across riding disciplines, concentrating R&D investment where certification pathways are clearest.
- Sport:Track-tuned suspension geometry and aerodynamic fairings deliver autobahn-capable top speeds exceeding 200 km/h. German and California buyers dominate this segment as congestion pricing exemptions reward high-performance urban mobility.
- Cruiser:Relaxed ergonomics and low-slung battery placement prioritize stylistic presence over outright velocity. Demand clusters in US secondary cities where charging infrastructure gaps favor shorter-range, style-forward configurations.
- Touring:Integrated panniers, adjustable windscreens, and 20-plus-kilowatt-hour packs support multi-day highway travel. European long-distance riders drive adoption where fast-charging corridor density permits.
- Off-Road:Lightweight chassis and ruggedized battery enclosures serve closed-course recreation and emerging electric motocross competition formats. Trail access restrictions in Alpine regions constrain volume.
Established volume favors Sport; emerging adoption favors Touring.
Battery Technology:
Cost tier stratification separates incumbent chemistries from next-generation architectures, with cell ownership models and thermal management requirements driving distinct customer value propositions.
- Lithium-ion:NMC and LFP cell formats dominate current production through proven manufacturing scale and established recycling pathways. Supply concentrates in cylindrical and prismatic formats from South Korean and Chinese cell houses.
- Solid State:Sulfide and oxide electrolyte architectures promise energy density gains above 400 Wh/kg with enhanced thermal stability. Japanese automotive consortiums and European pilot lines are accelerating qualification timelines for premium motorcycle integration.
- Lead Acid:Legacy chemistry persists in limited regional markets where import tariffs and low-speed vehicle regulations accommodate cost-minimized powertrains. Southeast Asian and African fringe applications sustain residual demand.
- Nickel-Metal Hydride:Mature chemistry retains niche utility in mild-hybrid auxiliary systems and temperature-extreme operating environments. Toyota-affiliated supply chains maintain limited motorcycle-scale production.
Current revenue concentrates in Lithium-ion; technology transition favors Solid State.
Target Audience:
Customer type determines pricing tolerance, feature prioritization, and channel preferences, with municipal policy exposure creating structural demand buffers for specific archetypes.
- Urban Commuters:Metropolitan professionals with disposable income trade combustion convenience for zero-emission access privileges in London, Singapore, and Stockholm congestion zones. Daily rideability and parking efficiency outweigh top-speed specifications.
- Enthusiasts:Performance-oriented riders seek track-day credibility and aftermarket modification ecosystems. This segment shows highest willingness to pay for carbon-fiber components and telemetry-enabled suspension.
- Eco-conscious Consumers:Sustainability-motivated buyers prioritize supply chain transparency and end-of-life battery stewardship. EU battery passport mandates align purchasing criteria with manufacturer disclosure capabilities.
- Luxury Buyers:Discretionary spending resilience insulates this segment from macroeconomic cyclicality. Bespoke colorways, concierge delivery, and exclusive ownership experiences command substantial price premiums.
Volume leadership sits with Urban Commuters; margin expansion favors Luxury Buyers.
Distribution Channel:
Geography shapes channel viability, with metropolitan density enabling direct-to-consumer models while rural markets require physical presence for test-ride validation and service support.
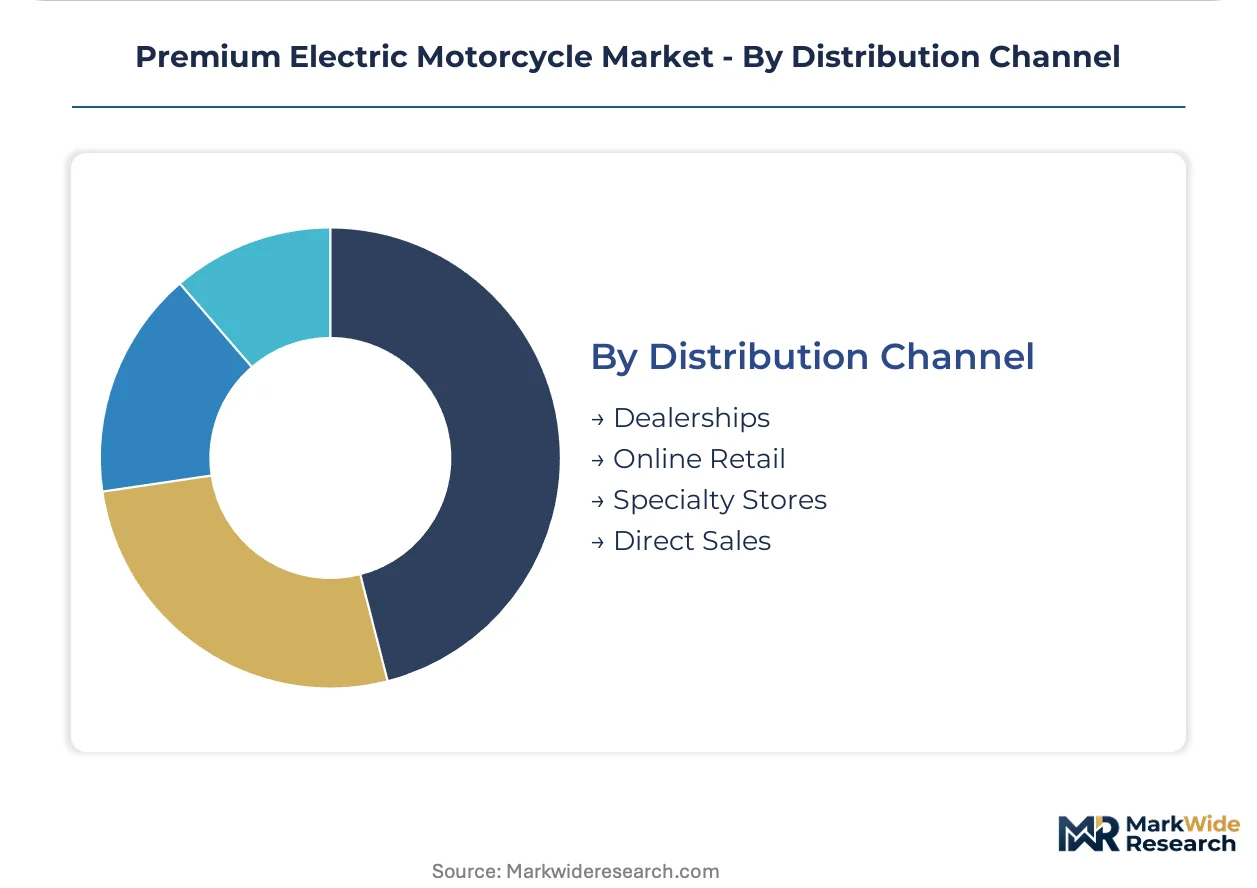
- Dealerships:Authorized retail networks provide test-ride infrastructure, financing arrangements, and warranty service execution. German KBA type-approval requirements and US state dealer franchise laws entrench this channel for premium transactions.
- Online Retail:Configuration platforms with factory delivery scheduling attract digitally native buyers in Berlin, Munich, and California metropolitan corridors. Urban Commuter segments show highest digital purchase completion rates.
- Specialty Stores:Curated showrooms in lifestyle retail districts emphasize brand experience over inventory depth. Limited locations in Milan, Paris, and Tokyo serve as brand temples for enthusiast engagement.
- Direct Sales:Manufacturer-owned stores and mobile delivery units bypass traditional margin structures. Regulatory friction varies by US state franchise legislation and EU selective distribution exemptions.
Transaction volume flows through Dealerships; customer acquisition cost optimization favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering exports dominate European premium electric motorcycle supply chains while California and Shanghai serve as the primary demand absorption centers for high-performance zero-emission two-wheelers.
Germany
Autobahn-capable performance specifications and federal purchase incentives align with premium positioning. KBA type-approval requirements enforce stringent safety validation for connected rider-assistance systems. Munich anchors battery thermal management R&D clusters where established dealer infrastructure supports high-margin sport configurations.
United States
EPA tailpipe standards compress manufacturer electrification timelines while state-level ZEV mandates accelerate adoption curves. Congestion pricing expansion in Manhattan and San Francisco privileges zero-emission vehicle access. California's metropolitan corridors concentrate early-mover platform deployments and direct-to-consumer configuration platform adoption.
China
Dual carbon goals and MIIT new energy vehicle directives reshape domestic manufacturing priorities. GB standards for electric two-wheelers create compliance baselines for export-oriented production. Yangtze River Delta cell manufacturing clusters supply cylindrical and prismatic formats to premium motorcycle integrators.
India
PLI scheme alignment for advanced chemistry cell manufacturing offers cost-competitive sourcing pivots. FAME-II subsidy extensions and state-level EV policies accelerate metropolitan adoption. Tamil Nadu and Gujarat host emerging battery pack assembly operations serving domestic and export demand.
United Kingdom
London congestion charging and ULEZ expansion redirect affluent commuter spending toward premium electric motorcycles. DVSA type-approval harmonization with EU frameworks maintains certification pathway continuity. Southeast England technology corridors concentrate silicon-carbide inverter and motor control engineering talent.
Premium Electric Motorcycle Market Vendor Landscape
Listed leaders compete with private specialists across capitalization structures and R&D funding models. The vendor base splits between automotive-scale conglomerates with captive battery supply and venture-backed pure-plays pursuing platform architecture dominance. Three archetypes predominate: legacy motorcycle OEMs with electrified sub-brands, electric-native specialists with clean-sheet powertrain designs, and component suppliers forward-integrating into finished vehicle production. Capacity expansion and strategic technology licensing constitute the dominant competitive moves reshaping supplier qualification timelines.
Within the legacy electrification tier, BMW Motorrad and Harley-Davidson LiveWire exemplify established manufacturer strategies leveraging dealer infrastructure and brand heritage. Among electric-native specialists, Zero Motorcycles and Lightning Motorcycles occupy positions defined by early-mover platform maturity and extreme-performance sub-segment focus respectively. These four anchors illustrate how capital access and thermal management philosophy split competitive positioning across liquid-cooled performance density and air-cooled simplicity vectors.
| Leading Market Players |
|---|
| Damon Motorcycles |
| BMW Motorrad |
| Zero Motorcycles |
| LiveWire |
| REZON |
| Lightning Motorcycles |
| Verge Motorcycles |
| Stark Future |
| Harley-Davidson LiveWire |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German OEMs and South Korean cell houses lock in lithium-ion supply visibility while anchoring pack cost predictability across the premium motorcycle production cycle. These arrangements insulate manufacturers from cobalt price volatility while constraining flexibility to pivot toward solid-state chemistry transitions.
Pricing Analysis
Current-generation lithium-ion configurations command substantial premiums over prior-generation lead-acid alternatives, while next-generation solid-state architectures threaten to reset pricing baselines entirely. Three-tier pricing structure across premium sport, standard urban commuter, and economy entry-level segments stratifies by battery capacity and thermal management sophistication. Pricing pressure stems from silicon-anode integration costs as manufacturers race interim range extensions without full solid-state transitions. Urban commuters exhibit highest price sensitivity due to total-cost-of-ownership calculations against public transit, while luxury buyers tolerate substantial premiums for bespoke configuration and concierge delivery.
Supply Chain Analysis
Cobalt concentrate refining in the Democratic Republic of Congo and lithium carbonate processing in Chile's Atacama salt flats constitute critical chokepoints that tether premium motorcycle cell production to geopolitical risk exposure. South Korean cylindrical cell manufacturing and Chinese prismatic pack assembly feed tier-one supply tiers, while Japanese automotive consortiums pilot solid-state electrolyte qualification. Single-source vulnerability concentrates in cathode active material precursors where Indonesian nickel processing expansion remains incomplete. Distribution runs through authorized dealer networks in Germany and California metropolitan corridors, with direct-to-consumer platforms capturing growing share among digitally native urban buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Premium electric motorcycle incumbents face substitution defense imperatives as electric micro-mobility scooters and urban transit investments threaten to capture commuter mobility spend. The analysis frames strategic positioning around preserving performance credibility while expanding daily-use accessibility.
For Market Incumbents: Shield core sport segment margins by accelerating silicon-carbide inverter in-sourcing that locks in thermal management differentiation against electric-native challengers. Prioritize captive battery supply through joint venture structures with South Korean cell houses before solid-state qualification timelines compress incumbent lithium-ion advantages. Defend dealer network exclusivity against direct-to-consumer regulatory arbitrage in California and German metropolitan corridors.
For New Entrants and Emerging Players: Battery subscription service gaps in Nordic markets expose incumbents wedded to traditional ownership models, creating white-space for unbundled cell-as-a-service propositions that lower entry price points. Target India's metropolitan commuter segment where FAME-II subsidies and PLI scheme alignment compress effective customer acquisition costs versus saturated European corridors. Pursue track-day experience bundling as differentiated go-to-market positioning that monetizes performance credibility beyond hardware margins.
For Investors and Strategic Acquirers: Capital is best deployed toward electric-native specialists with clean-sheet thermal management architectures and established platform scalability rather than legacy OEM electrification sub-brands burdened by combustion transition costs. Long-term viability favors ventures with demonstrated silicon-anode integration pathways and ISO 26262 functional safety certification progress. Monitor EU battery passport compliance timelines as inflection indicator for supply chain qualification cost escalations that will favor early-compliant manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Partnership | Japanese automotive consortiums accelerate sulfide electrolyte qualification for premium motorcycle energy density gains. |
| Silicon-Carbide Inverter Integration | Automotive-scale semiconductor houses displace specialized motorcycle electronics vendors in motor control strategies. |
| Battery Subscription Unbundling | Nordic market pilots separate cell ownership from vehicle purchase, securing recurring revenue streams. |
| Direct-to-Consumer Platform Launch | Berlin and California metropolitan buyers complete digital transactions without dealer inventory intermediation. |
| India PLI Scheme Manufacturing Alignment | Tamil Nadu and Gujarat pack assembly operations serve cost-competitive sourcing for export demand. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 battery pack procurement leads, dealership operations managers, and connected rider-assistance system software architects, then refined through secondary validation. SEC filings from listed motorcycle manufacturers, EPA tailpipe standard dockets, EU Green Deal regulatory texts, and IHS Markit vehicle registration databases anchored quantitative baselines. Bottom-up cell chemistry adoption curves and top-down metropolitan congestion policy impact assessments were triangulated to constrain forecast variance.
Variance decomposition across product type, battery technology generation, target audience archetype, and distribution channel configuration structured the analytical framework over the projection horizon. CAGRs were derived from segment-level volume build-ups validated against regional regulatory adoption curves and infrastructure deployment timelines. Silicon-anode integration roadmaps and solid-state pilot production announcements informed technology transition assumptions.
Material uncertainties — solid-state chemistry commercialization delays, EU AI Act liability framework enforcement intensity, and cobalt supply disruption events — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as battery passport traceability mandate implementation timelines and congestion pricing expansion patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Germany Solar E-Bike Market
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
France E-Bike Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
India Electric Car Market
Electric Vehicles
Electric Vehicle E-Axle Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market