
 Water Proof E-Scooter Market | 2026-2036
Water Proof E-Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Water Proof E-Scooter Market Analytics
Subscription-based battery-swapping networks is expanding the addressable market beyond hardware ownership. NIU leverages its captive charging infrastructure to lock in recurring revenue from fleet clients. Segway-Ninebot anchors its position through software-defined speed governors that adapt to local regulations. Gogoro Inc controls the swap-station density advantage in Taipei and now extends that model toward Southeast Asian partnerships.
A water proof e-scooter is a personal electric vehicle engineered with sealed enclosures, gaskets, and corrosion-resistant materials to maintain operational integrity when exposed to rain, puddles, or humidity, typically achieving IPX4 or higher ingress protection ratings against water intrusion. Its primary commercial purpose is to eliminate weather-related downtime for daily commuters and delivery riders in climates with frequent precipitation. The foldable product type dominates urban commuter channels where storage constraints dictate purchase decisions, while high-speed variants command the strongest margin pools among enthusiast and commercial buyers. Lithium-ion battery configurations lead unit economics through superior energy density and cycle life, though lithium-polymer alternatives are gaining traction in premium tiers seeking reduced weight.
The EU Machinery Directive and CE marking requirements enforce minimum safety and environmental standards for e-scooters sold across member states, while the F-Gas Regulation indirectly shapes thermal management material choices in sealed battery packs. In the United States, the Consumer Product Safety Commission and state-level DMV classifications determine where these vehicles may legally operate and what labeling they must carry. Stakeholders must monitor how evolving municipal micro-mobility permits and insurance mandates reshape the total cost of ownership equation for both consumer and fleet purchasers.
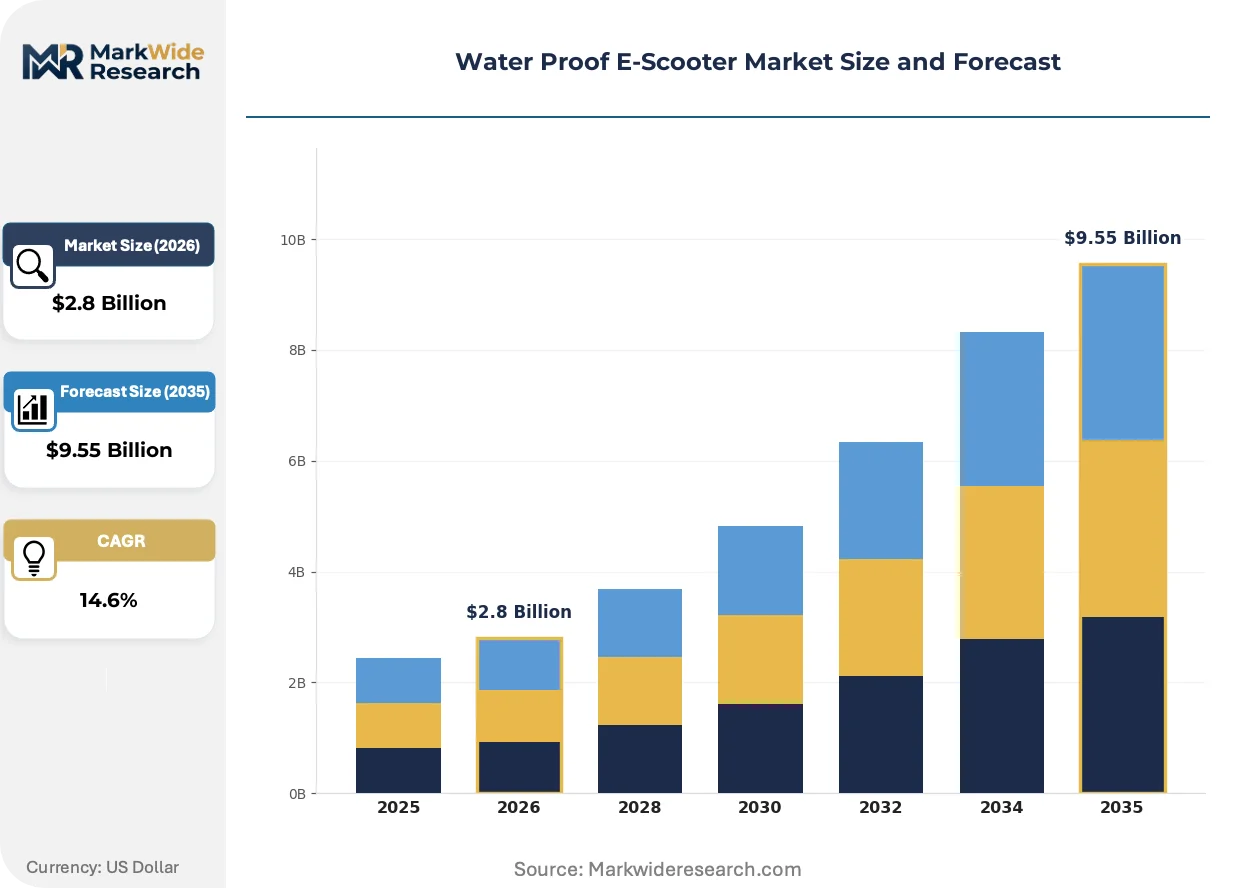
Market Dynamics
Fleet electrification mandates and ingress protection standardization are compressing product development cycles while concentrating procurement authority among logistics operators with multi-thousand-unit deployment requirements.
Growth Catalysts
- IPX7 Sealing Standards:Municipal fleet tenders in Germany now require submersion-rated enclosures, forcing component suppliers to retool gasket and housing specifications.
- Last-Mile Delivery Electrification:Food and parcel logistics operators face diesel van bans in Paris, Amsterdam, and Barcelona, redirecting capital toward weather-resistant micromobility assets.
- Dongguan Supplier Cluster:Concentrated die-casting and motor-winding capacity enables rapid prototyping of sealed drivetrain architectures for export markets.
Market Restraints
- Lithium Price Volatility:Cathode material cost swings compress margin visibility for battery pack assemblers serving price-sensitive commuter segments.
- Single-Source Magnet Supply:Rare-earth permanent magnet dependency on Chinese processing facilities creates exposure to export licensing disruptions.
- CE Marking Complexity:Machinery Directive conformity assessment timelines extend 4-8 months for novel enclosure designs, delaying EU market entry.
Strategic Opportunities
- Indonesia Micromobility Expansion:Jakarta's odd-even vehicle restrictions and monsoon rainfall patterns create unmet demand for flood-resistant fleet vehicles.
- Battery-as-a-Service Convergence:Swappable pack architectures decouple hardware from energy costs, unlocking subscription revenue from delivery cooperatives.
- US IRA Commercial Credits:Section 45W clean vehicle incentives apply to commercial light-duty electrification, improving total cost of ownership calculations for domestic fleet operators.
Industry Challenges
- IP Certification Bottlenecks:Third-party testing laboratory capacity constraints in Shenzhen and Rotterdam extend validation queues to 12-16 weeks.
- Embedded Software Talent Scarcity:Firmware engineers capable of integrating motor controllers with CAN-based fleet management systems command premium compensation in Taiwan and South Korea.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Proof E-Scooter Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable, Unfoldable, High-Speed, Mini Power Rating: 250W, 500W, 750W, 1000W Battery Type: Lithium-Ion, Lead-Acid, Lithium-Polymer, NiMH Weight Capacity: 100 kg, 120 kg, 150 kg, 200 kg |
| Companies Covered | Xiaomi Corporation, Segway-Ninebot, Voro Motors, Apollo Scooters, GOTRAX, Kaabo, NIU, Razor USA, Gogoro Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Proof E-Scooter Market Evolving Landscape
Sealed thermal management architectures and software-defined vehicle platforms are displacing modular hardware approaches, while procurement centralization among fleet operators compresses supplier negotiation leverage.
Solid-state potting compounds with silicone-urethane hybrid chemistry are rewriting how battery enclosures achieve IPX7 ratings without sacrificing serviceability. Tier-1 pack assemblers in South Korea and Japan are adopting these materials for high-cycle fleet contracts. The shift is compressing warranty reserve requirements while extending operational duty cycles in tropical humidity conditions.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in active cooling systems for high-performance battery packs. Manufacturers are pivoting toward phase-change materials and liquid-cooled cold plates with lower global warming potential. This transition most affects premium high-speed variants targeting German and Dutch enthusiast markets, where thermal runaway protection is a purchase determinant.
Centralized procurement desks at logistics platforms now specify fleet-wide telematics integration and unified charging protocols as table stakes. Traditional distributor networks lose share to direct manufacturer relationships with volume guarantees. This consolidation is most advanced in the United Kingdom, where Deliveroo and Uber Eats have standardized on interchangeable battery formats across supplier bases.
Water Proof E-Scooter Market Segmentation
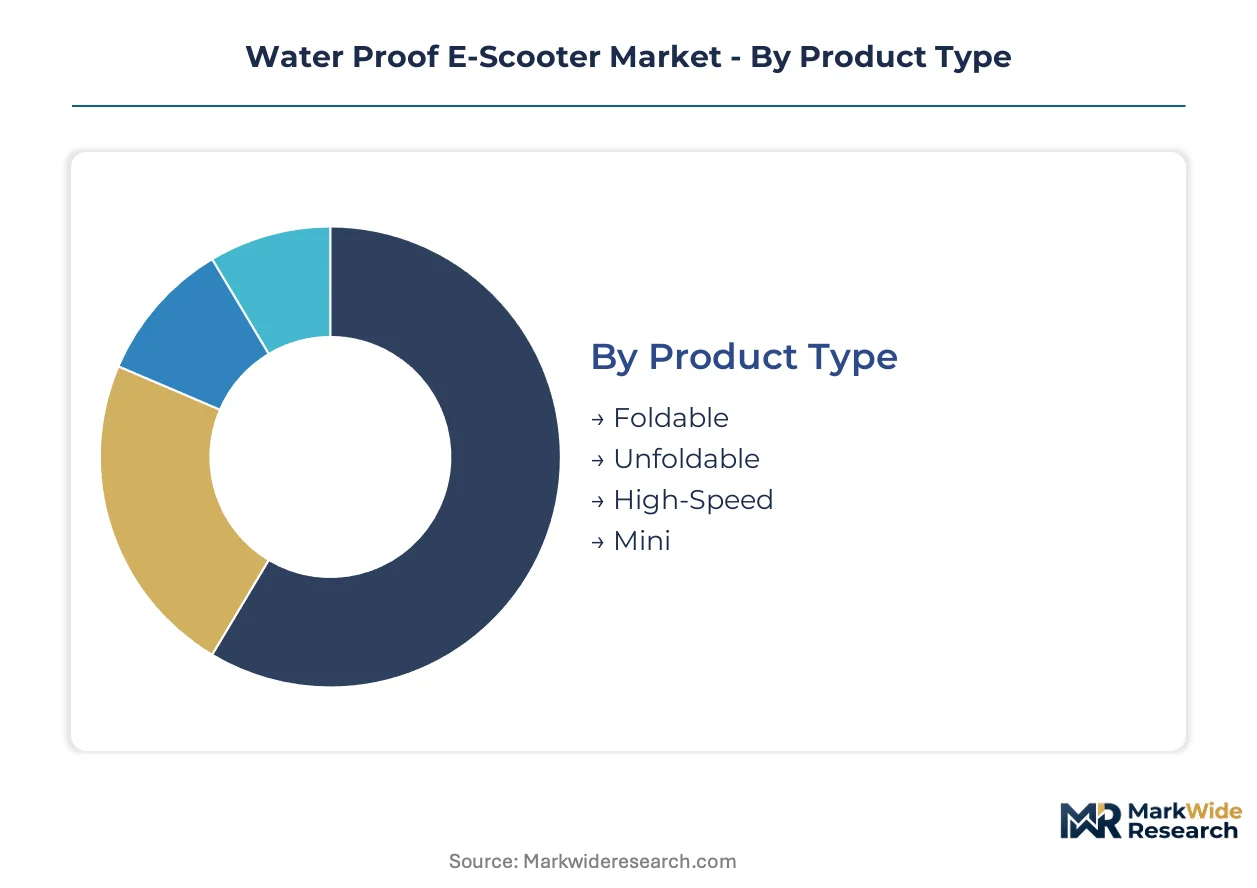
Water proof e-scooter procurement decisions split sharply between urban commuters prioritizing portability and fleet operators demanding load-bearing durability. Segmentation reveals how ingress protection requirements vary dramatically across use cases, from IPX4-rated foldable units for occasional rain exposure to IPX7-sealed high-speed variants for all-weather commercial duty.
Product Type:
Volume concentrates in commuter-optimized formats where storage constraints override speed specifications, while premium margins accumulate in performance-tier commercial variants.
- Foldable:Hinged stem and deck mechanisms enable trunk storage and office stowage, with sealed hinge gaskets representing the critical failure point for water ingress. Demand clusters in Tokyo, Amsterdam, and Singapore where multi-modal transit integration drives purchase decisions. IPX5-rated units dominate this tier as sufficient protection against road spray without the cost burden of submersion sealing.
- High-Speed:Dual-motor configurations exceeding 45 km/h require reinforced motor housings and liquid-cooled battery architectures to maintain thermal equilibrium in sealed enclosures. Fleet operators in Paris and Barcelona specify these variants for suburban delivery routes where velocity compensates for longer distances. Margins here exceed commuter tiers by factor of two through enthusiast and commercial pricing power.
- Unfoldable:Fixed-frame construction sacrifices portability for structural rigidity and simplified sealing geometry.
- Mini:Sub-12 kg ultraportables target last-mile transit connections with reduced range and motor power.
Today's leader: Foldable. Tomorrow's challenger: High-Speed.
Power Rating:
Municipal regulations cap permissible wattage, creating geographic fragmentation where 250W dominates European streets and 750W-1000W variants serve unregulated private campuses.
- 250W:Single-hub motors meeting EU Machinery Directive limits for unlicensed operation, with sealed stator windings protecting against puddle immersion. German KBA classification rules entrench this tier across Berlin, Munich, and Hamburg commuter markets. CE marking requirements for electromagnetic compatibility add compliance cost that smaller manufacturers avoid through 250W ceiling adherence.
- 1000W:Dual-motor peak outputs enabling 50+ km/h speeds and 20-degree hill climbs, requiring active thermal management in sealed battery compartments. Indonesian delivery cooperatives in Jakarta specify this tier to overcome monsoon-flooded streets and bridge approaches. The power-density demands force lithium-polymer adoption despite cost premiums.
- 500W:Mid-tier balance of acceleration and regulatory compliance for mixed-use operators.
- 750W:Threshold specification for US commercial fleet tenders where state DMV classifications permit higher wattage with registration.
Regulatory ceilings anchor 250W volume. Commercial torque requirements push 1000W expansion fastest.
Battery Type:
Energy density versus serviceability tradeoffs determine chemistry selection, with sealed enclosure requirements complicating traditional maintenance models.
- Lithium-Ion:NMC and LFP cylindrical cell configurations deliver 250-300 Wh/kg density with established recycling infrastructure. Dongguan pack assemblers dominate supply through vertical control of cell sourcing, BMS firmware, and potting compound integration. Cycle life exceeding 800 charges supports fleet utilization rates above 200 km daily.
- Lithium-Polymer:Pouch cell form factors enable custom pack geometries that maximize volumetric efficiency in compact deck enclosures. Premium commuter brands in South Korea and Japan specify these for weight reduction below 15 kg total vehicle mass. Thermal runaway risks demand more sophisticated BMS integration, concentrating procurement among Tier-1 suppliers.
- Lead-Acid:Legacy chemistry persisting in price-sensitive Indian and Southeast Asian markets where recycling networks offset density disadvantages.
- NiMH:Niche chemistry retained in cold-climate deployments where lithium performance degradation exceeds acceptable thresholds.
Lithium-Ion commands installed base. Lithium-Polymer gains share in premium tiers.
Weight Capacity:
Structural reinforcement for payload tolerance directly conflicts with portability targets, bifurcating design philosophies between individual and commercial use cases.
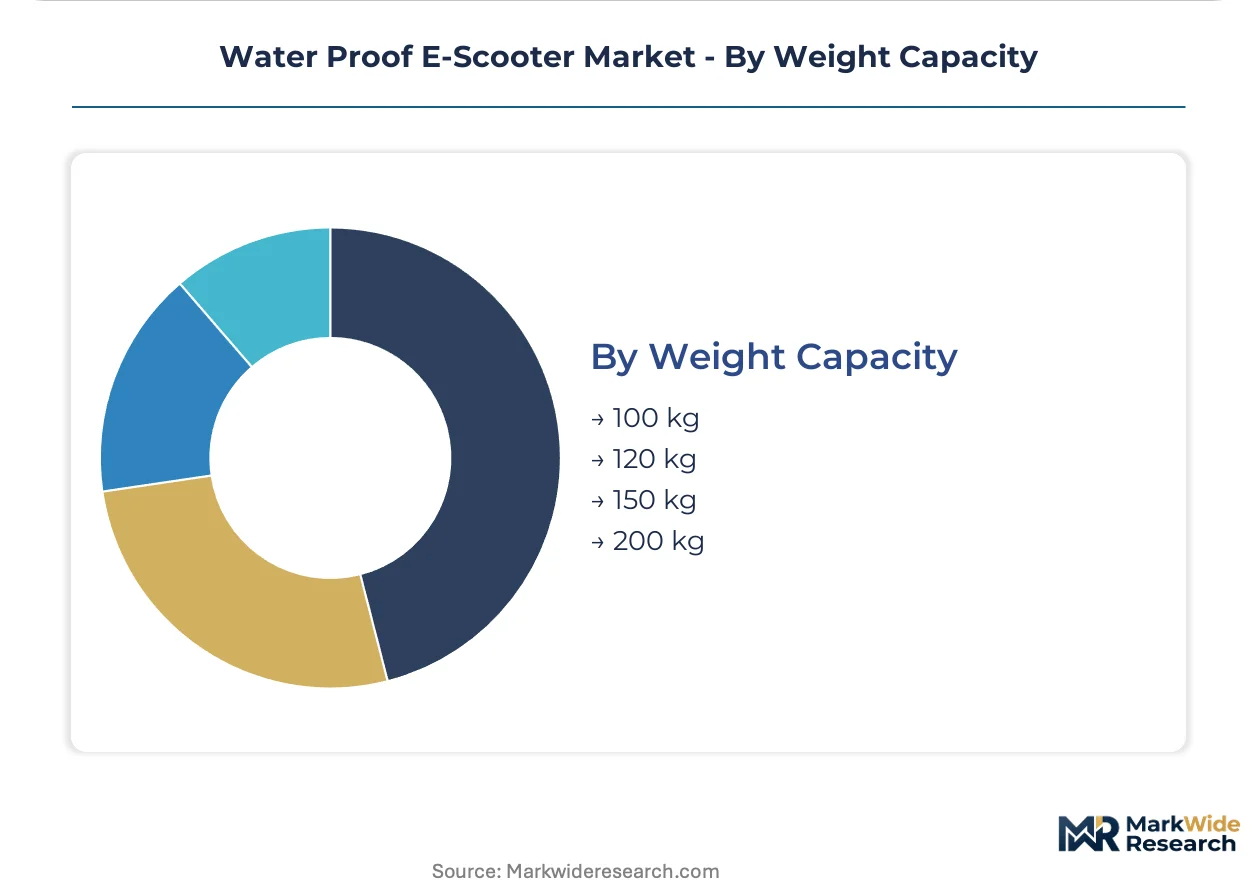
- 120 kg:Reinforced deck extrusions and dual-suspension configurations accommodate average adult riders with cargo loads, representing the specification sweet spot for European fleet tenders. Deliveroo and Uber Eats standardized procurement around this threshold to accommodate insulated delivery bags without exceeding structural safety margins. IP sealing complexity increases with suspension travel requirements.
- 200 kg:Heavy-duty frame geometries and 11-inch pneumatic tires for dual-rider or substantial cargo applications, specified by Indonesian logistics platforms for bulk commodity delivery. Frame welding and gusseting requirements concentrate production with Dongguan die-casting specialists capable of structural validation documentation.
- 100 kg:Minimal specification for Asian commuter markets where average rider mass permits material cost reduction.
- 150 kg:Intermediate tier capturing North American rider demographics and light commercial loads.
120 kg defines fleet procurement standards. 200 kg emerges for cargo specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces the strictest ingress protection mandates among major markets, while Indonesia's monsoon climate drives demand for flood-resistant fleet vehicles without equivalent regulatory pressure.
China
Shenzhen and Dongguan host the densest supplier ecosystems for sealed motor housings and battery enclosures. MIIT certification requirements for electric two-wheelers mandate minimum IPX4 ratings, accelerating factory retooling. Dongguan die-casting specialists now prototype IPX7-rated drivetrain architectures for export to European fleet operators within 6-week development cycles.
Germany
KBA classification rules entrench 250W commuter tiers across Berlin, Munich, and Hamburg, while municipal fleet tenders in Stuttgart and Frankfurt now require IPX7 submersion ratings. The EU Machinery Directive and CE marking extend conformity assessment timelines to 4-8 months for novel enclosure designs. Bavaria-based logistics platforms standardize procurement around 120 kg payload thresholds with unified telematics integration.
United States
State-level DMV classifications fragment permissible wattage between 250W and 750W thresholds, creating compliance complexity for national fleet rollouts. Section 45W clean vehicle incentives under the IRA improve total cost of ownership calculations for commercial operators. California's municipal micro-mobility permits now require IPX5 minimum ratings for shared fleet deployments in San Francisco and Los Angeles.
Indonesia
Jakarta's odd-even vehicle restrictions and monsoon rainfall patterns generate unmet demand for flood-resistant delivery vehicles. The national government's battery swap infrastructure investments support Gogoro's station density expansion into Surabaya and Bandung. Local logistics cooperatives specify 1000W dual-motor configurations to overcome flooded bridge approaches during tropical storm seasons.
United Kingdom
Deliveroo and Uber Eats procurement desks have standardized interchangeable battery formats across supplier bases, compressing distributor margins. The Department for Transport's micromobility trials mandate minimum IPX4 ratings for legal street operation. London's congestion charging zone expansion redirects last-mile logistics capital toward weather-resistant e-scooter fleets.
Water Proof E-Scooter Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fleet procurement centralization favoring direct manufacturer relationships over traditional distribution. The vendor base organizes into three tiers: vertically integrated platform operators controlling captive charging infrastructure, component-specialist assemblers serving white-label contracts, and regional distributors losing ground to volume guarantees. Consolidation pressures concentrate among logistics operators with multi-thousand-unit deployment requirements, while capacity expansion and strategic partnerships represent the dominant competitive moves.
Among platform-integrated operators, NIU and Gogoro exemplify the battery-as-a-service archetype through captive charging and swap-station networks. Segway-Ninebot occupies a position bridging consumer brand recognition with fleet-grade telematics integration. These three companies represent divergent strategic postures: NIU anchors recurring revenue through infrastructure lock-in, Gogoro extends geographic density advantages into partnership markets, and Segway-Ninebot leverages software-defined vehicle platforms to adapt across regulatory environments.
| Leading Market Players |
|---|
| Xiaomi Corporation |
| Segway-Ninebot |
| Voro Motors |
| Apollo Scooters |
| GOTRAX |
| Kaabo |
| NIU |
| Razor USA |
| Gogoro Inc |
| Others |
Value Network & Pricing Analysis
Family-owned die-casting specialists in Dongguan anchor component supply for sealed motor housings, translating concentrated manufacturing capacity into asymmetric pricing power over battery pack assemblers in South Korea and Japan. Their captive control of gasket prototyping and thermal potting compound integration lets them dictate minimum order quantities that reshape procurement economics for European fleet operators.
Pricing Analysis
Capacity additions in Shenzhen and Dongguan are reshaping price floors for IPX7-rated enclosures as die-casting specialists absorb volume from Taiwanese competitors. Three-tier pricing structure across premium, standard, and economy levels separates fleet-grade telematics-integrated units from commuter-tier foldables and white-label mini variants. Cost compression in the commuter tier intensifies because lithium-polymer alternatives from South Korean cell suppliers command material premiums. Food delivery cooperatives in Indonesia exhibit highest price sensitivity, while German municipal fleet tenders show lowest sensitivity due to total-cost-of-ownership mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Deliveroo and Uber Eats procurement desks, bypassing traditional distributor networks entirely. Manufacturing gravity centers on China, South Korea, and Vietnam, with rare-earth permanent magnet processing tethered to Chinese facilities. The supply chain draws from lithium carbonate, neodymium-iron-boron magnets, and silicone-urethane potting compounds as critical inputs. Single-source magnet dependency creates exposure to export licensing disruptions. Distribution runs through manufacturer-direct relationships with volume guarantees rather than regional wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The waterproof e-scooter market functions as a geographic-arbitrage play where Jakarta's monsoon-driven fleet demand meets Dongguan's manufacturing cost base, exploiting regulatory gaps between Indonesia's absent IP mandates and Germany's strict CE marking requirements.
For Market Incumbents: Anticipate margin compression from Chinese contract manufacturers backward-integrating into battery management firmware. Defend position by deepening captive charging infrastructure lock-in with fleet clients and accelerating IPX7 certification investment ahead of EU Machinery Directive expansions. Vertical integration into swap-station hardware production represents the critical lever for recurring revenue protection against white-label entrants. For New Entrants and Emerging Players: Launch via battery-as-a-service partnerships with Indonesian logistics cooperatives, bypassing hardware ownership models entirely. Target the 1000W dual-motor segment for Jakarta's flooded bridge approaches, where incumbent coverage remains thin. Exploit white-space in cold-climate NiMH deployments for Nordic commuter markets where lithium degradation creates performance gaps. For Investors and Strategic Acquirers: Valuations sit cheapest among component-specialist assemblers lacking captive charging infrastructure. Long-term viability hinges on swap-station density economics and software-defined vehicle platform control rather than hardware margins alone. Monitor Gogoro's Southeast Asian partnership expansion as the signal for battery-as-a-service model validation outside Taipei.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swap Infrastructure Partnership | Gogoro's station density in Taipei validates subscription revenue models for tropical fleet markets. |
| IPX7 Certification Investment | German KBA and municipal tender requirements force retooling timelines that advantage early certifiers. |
| Software-Defined Vehicle Platform | Segway-Ninebot's adaptive speed governors enable single-SKU regulatory compliance across fragmented DMV classifications. |
| Backward Integration into Cell Sourcing | NIU's captive battery production insulates fleet pricing from lithium carbonate volatility. |
| Direct Fleet Procurement Relationship | Deliveroo's standardized battery formats compress distributor margins and lock in volume guarantees. |
Research Methodology
Coverage spans China, Germany, Indonesia, the United Kingdom, and the United States, with primary inputs from each market. Triangulation combined interviews with fleet procurement managers at logistics platforms, battery pack engineering leads at Dongguan assemblers, regulatory affairs specialists navigating CE marking, and telematics integration engineers at Tier-1 suppliers. Secondary validation drew from MIIT certification databases, EU Machinery Directive conformity assessment records, FERC filings on IRA Section 45W implementation, and customs trade data on lithium-ion cell imports. Bottom-up unit shipment estimates and top-down addressable market sizing were reconciled through iterative stakeholder feedback.
Granularity-level modeling deployed separate projections for foldable versus high-speed product architectures, 250W versus 1000W power rating tiers, and lithium-ion versus lithium-polymer chemistry splits. CAGRs were derived from regression analysis of historical fleet deployment curves and forward elasticity estimates around battery swap adoption. Industry-specific inputs included Jakarta odd-even restriction enforcement timelines, German municipal tender IPX7 mandate adoption rates, and Section 45W credit utilization patterns among US commercial operators across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium price spike scenarios or rare-earth export licensing disruptions. Periodic stress-testing of base assumptions is recommended, particularly around fleet electrification mandate acceleration in EU member states and monsoon severity patterns affecting Indonesian utilization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Solar Car Market
Electric Vehicles
South America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Car Battery Chargers Market
Electric Vehicles
Foldable Electric Vehicle Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Electric Vehicle Heating System Market
Electric Vehicles
UK Electric Vehicle Market
Electric Vehicles
Electric Van Market