
 Child-Resistant Foil Packaging Market | 2026-2036
Child-Resistant Foil Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Child-Resistant Foil Packaging Market Analysis
Specialized tooling engineering talent is reorganizing competitive dynamics as converter investments in press-to-close zipper dies outpace available workforce supply. Amcor Limited leverages captive film extrusion capacity across European pharmaceutical corridors to sustain margin control. Berry Global Inc. anchors North American supply through multi-layer coextrusion lines purpose-built for opioid pouch specifications. Huhtamaki Oyj competes via lidding film specialization that meets both FDA 16 CFR 1700 and EMA child-resistance protocols.
Child-resistant foil packaging denotes multi-layer laminates incorporating aluminium or composite barrier substrates with engineered closure systems requiring adult-dexterity manipulation sequences to access contents, typically achieving ASTM D3475 compliance through press-to-close, peel-and-reseal, or slider zip mechanisms. These structures employ heat-seal coatings and precisely calibrated tear-initiation forces to prevent pediatric opening while maintaining senior accessibility. Blister packs dominate pharmaceutical applications where unit-dose compliance and moisture barrier performance command premium positioning. Stand-up pouches represent the fastest-growing configuration as cannabis and nutraceutical brands adopt flexible formats with compliant closures. Rollstock maintains mature volume positions in automated pharmaceutical lines where line-speed compatibility and gauge consistency outweigh format innovation.
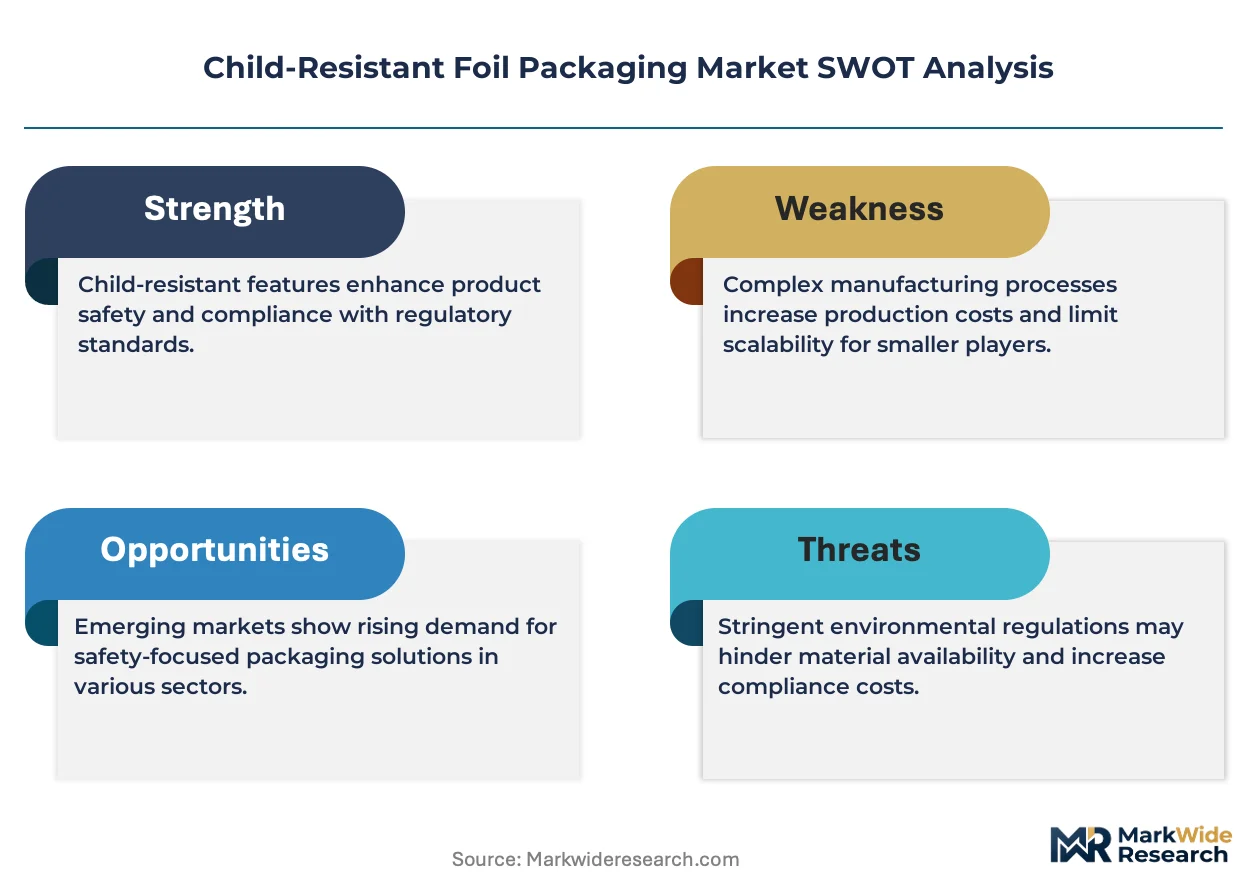
FDA 16 CFR 1700 and EMA MDR frameworks mandate protocol-tested child-resistance certification as a precondition for pharmaceutical and hazardous household product market access, directly determining converter qualification status. ISO 8317 and ASTM D3475 testing standards define the mechanical performance thresholds that closure systems must satisfy, creating technical barriers that favor converters with in-house certification laboratories. Stakeholders must monitor evolving state-level cannabis packaging regulations across the United States, where patchwork requirements between jurisdictions create compliance complexity that rewards modular closure platform investments.
Market Dynamics
Pharmaceutical contract packaging clusters in Germany are reorganizing converter qualification hierarchies as FDA 16 CFR 1700 certification becomes a non-negotiable entry ticket for opioid and cannabis pouch supply.
Growth Catalysts
- EMA MDR child-safety mandates:European pharmaceutical packaging must demonstrate protocol-tested resistance, forcing brand owners to source only certified converters.
- Stand-up pouch adoption:Cannabis and nutraceutical brands in North America are migrating from rigid containers to flexible formats with press-to-close zipper mechanisms.
- Heidelberg-Frankfurt corridor concentration:German pharmaceutical contract packaging hubs generate specialized foil demand that rewards localized converter investment.
Market Restraints
- Aluminium price volatility:Multi-layer laminate input costs fluctuate with commodity metal markets, compressing converter margins on fixed-price pharmaceutical contracts.
- Tooling engineer scarcity:Press-to-close zipper die design expertise concentrates among a handful of European specialists, creating qualification bottlenecks.
- ISO 8317 testing backlog:Certification laboratory capacity constraints delay product launches by six to eighteen months for new market entrants.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO alignment with FDA protocols creates a compliance pathway for converters serving US-bound generic drug shipments.
- Senior-accessibility dual certification:Closure systems achieving both ASTM D3475 child-resistance and senior-friendly F=1 accessibility ratings command premium positioning.
- Modular closure platforms:Reconfigurable zipper and peel-and-reseal mechanisms allow converters to serve fragmented US state-level cannabis regulations without SKU proliferation.
Industry Challenges
- Heat-seal coating formulation expertise:Precise tear-initiation force calibration requires polymer science talent that competes with broader flexible packaging sectors.
- Legacy line-speed compatibility:Automated pharmaceutical blister lines demand gauge consistency that conflicts with experimental laminate structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child-Resistant Foil Packaging Market |
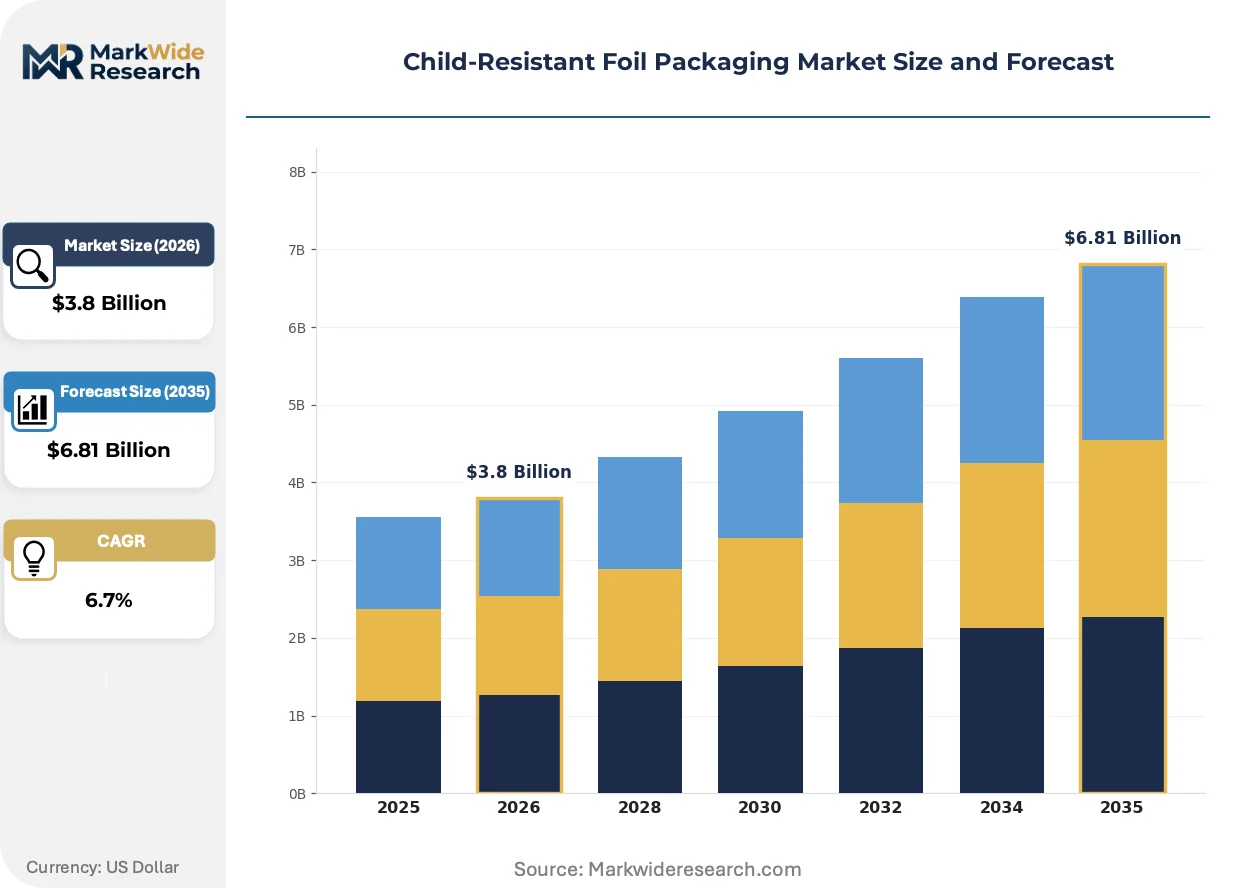
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Blister Packs, Rollstock, Lidding Films Closure Type: Press-to-Close, Peel-and-Reseal, Screw Cap, Slider Zip End User: Pharmaceuticals, Food & Beverage, Consumer Goods, Personal Care Material: Aluminium, Composite Foils, Polyester, Paperboard |
| Companies Covered | Constantia Flexibles, Huhtamaki Oyj, Amcor Limited, Sealed Air Corporation, Coveris Holdings S.A., Berry Global Inc., Winpak Ltd, Clondalkin Group, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child-Resistant Foil Packaging Market Emerging Trajectories
Closure engineering is fragmenting into specialized sub-disciplines as pharmaceutical, cannabis, and nutraceutical end-uses diverge in performance requirements and regulatory pathways.
Peel-and-reseal lidding films with integrated tear-initiation zones are decomposing the traditional separation between child-resistant and senior-accessible performance tiers. Blister pack manufacturers serving chronic disease medication markets are adopting these structures fastest, collapsing the historical trade-off between safety compliance and user convenience into a single laminate specification.
REACH substance restrictions on certain adhesive chemistries are forcing European converters to reformulate heat-seal coatings ahead of sunset dates. The industrial consequence is a qualification race among lidding film suppliers to secure ECHA-compliant alternatives without sacrificing ASTM D3475 mechanical performance. German pharmaceutical packaging lines are most affected, with Heidelberg-area converters accelerating supplier audits to preempt supply disruption.
Brand owners are consolidating supplier relationships around converters with captive certification laboratories, displacing arms-length testing arrangements that previously fragmented accountability. This concentration is most visible in North American cannabis packaging, where multi-state operators now mandate in-house ASTM D3475 protocol execution as a condition of contract award, compressing the vendor base toward integrated quality-control capabilities.
Child-Resistant Foil Packaging Market Segmentation
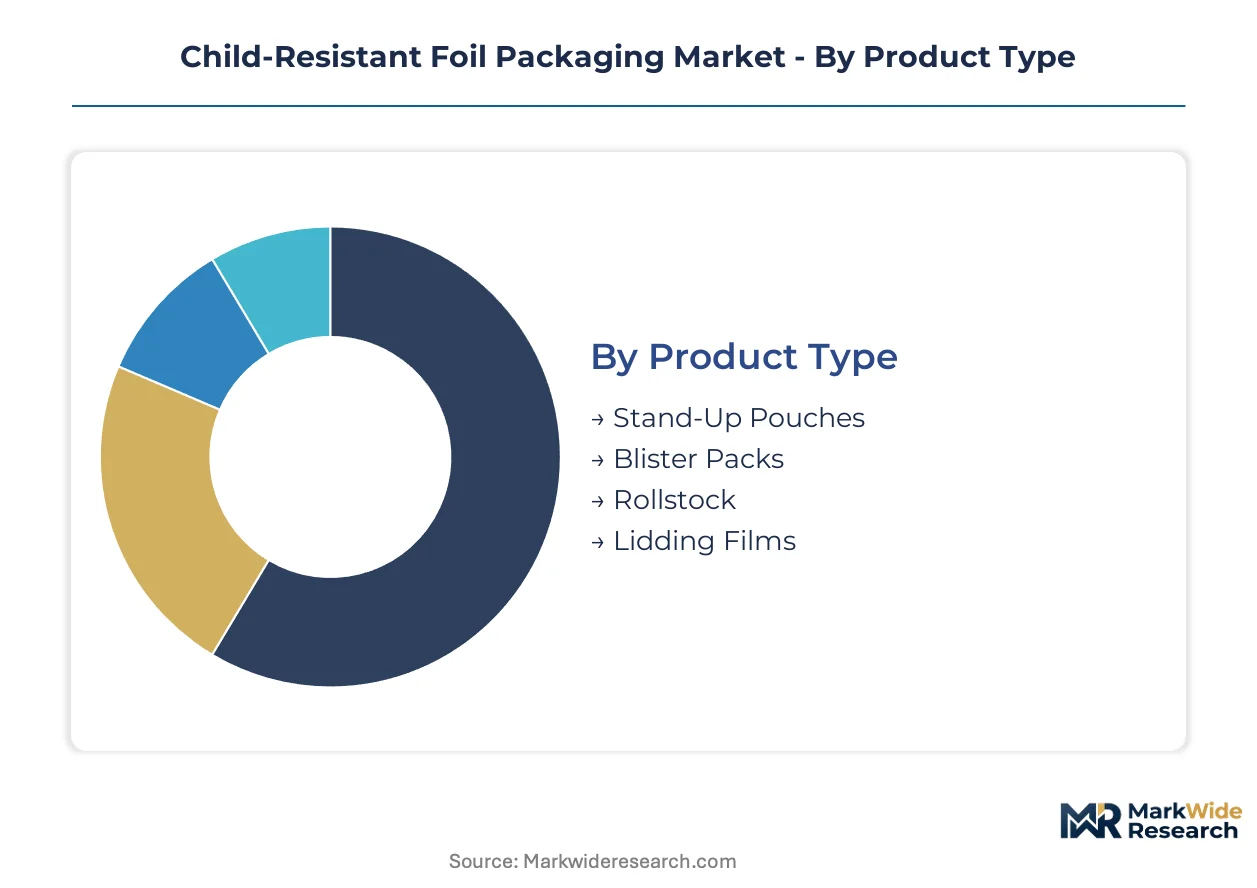
Converter qualification hierarchies in child-resistant foil packaging hinge on segment-specific certification requirements. Closure complexity and barrier performance specifications create divergent sourcing patterns across pharmaceutical, cannabis, and nutraceutical end-uses.
Product Type:
Domestic pharmaceutical lines in Germany and the United States favor blister packs and rollstock for regulatory familiarity, while export-oriented cannabis packaging in Canada and the Netherlands drives stand-up pouch demand.
- Blister Packs:Unit-dose aluminium-PVC laminates with cold-form or thermoform cavities dominate chronic disease medication compliance packaging. Demand concentrates in Heidelberg-area contract packaging facilities serving FDA 16 CFR 1700 mandates for opioid unit-dose distribution.
- Stand-Up Pouches:Multi-layer flexible structures with press-to-close zipper mechanisms represent the steepest expansion trajectory as North American cannabis brands abandon rigid containers for compliant flexible formats with senior-accessible opening sequences.
- Rollstock:Continuous web formats maintain volume positions in automated pharmaceutical filling lines where gauge consistency and heat-seal calibration stability outweigh format innovation.
- Lidding Films:Peel-and-reseal structures with integrated tear-initiation zones serve blister pack sealing applications requiring both child-resistance and senior-friendly accessibility ratings.
Blister packs hold the largest share; momentum sits with stand-up pouches.
Closure Type:
Cost tier differentiation separates premium press-to-close engineering from commodity screw cap alternatives, with certification complexity driving converter margin stratification.
- Press-to-Close:Dual-action zipper mechanisms requiring finger pressure and lateral sliding motion achieve ASTM D3475 compliance through precise die engineering. Tooling expertise concentrates among German and Italian specialists serving pharmaceutical and cannabis pouch specifications.
- Peel-and-Reseal:Lidding film structures with calibrated tear-initiation forces collapse the historical safety-accessibility trade-off into single-laminate specifications. Adoption accelerates in European chronic disease packaging where EMA MDR mandates tighten.
- Slider Zip:Track-based closure systems offer reseal convenience but face certification complexity for child-resistance protocols, limiting penetration to nutraceutical applications with less stringent testing requirements.
- Screw Cap:Rigid-container legacy closures maintain positions in pharmaceutical bottle formats but lose flexible packaging share to zipper mechanisms offering superior senior accessibility.
Press-to-close commands premium positioning; peel-and-reseal gains share fastest.
End User:
Application maturity separates established pharmaceutical certification pathways from emerging cannabis compliance complexity, with customer type determining converter qualification depth.
- Pharmaceuticals:Opioid, pediatric, and geriatric medication packaging drives the strictest ASTM D3475 and ISO 8317 certification requirements. German contract packaging clusters around Frankfurt and Heidelberg generate concentrated foil demand with non-negotiable FDA and EMA protocol compliance.
- Food & Beverage:Hazardous household product applications including concentrated detergent pods adopt child-resistant formats under EPA and state-level poisoning prevention mandates, though certification depth remains below pharmaceutical tiers.
- Consumer Goods:Cannabis flower, concentrate, and edible packaging in fragmented US state markets rewards modular closure platforms capable of reconfiguration across jurisdictional requirements without SKU proliferation.
- Personal Care:Nicotine replacement therapy and topical pharmaceutical-adjacent products occupy intermediate regulatory territory with emerging child-resistance expectations but less standardized testing protocols.
Pharmaceuticals anchor volume; consumer goods expands most quickly.
Material:
Supply concentration in aluminium smelting and European film extrusion shapes regional sourcing patterns, with composite development efforts targeting performance gaps.
- Aluminium:High-barrier dead-soft foil in 20-30 micron gauges provides moisture, oxygen, and light protection for pharmaceutical stability requirements. Price volatility in London Metal Exchange markets compresses converter margins on fixed-price multi-year contracts.
- Composite Foils:Aluminium-polyester-polyethylene laminates balance barrier performance with seal integrity, dominating flexible pouch specifications where puncture resistance and heat-seal calibration precision converge.
- Polyester:PET film layers contribute mechanical strength and printability to multi-layer structures, with biaxially oriented grades preferred for lidding film dimensional stability.
- Paperboard:Structural substrates in rigid-child-resistant formats and outer packaging applications provide graphic surface area but limited barrier function without foil lamination.
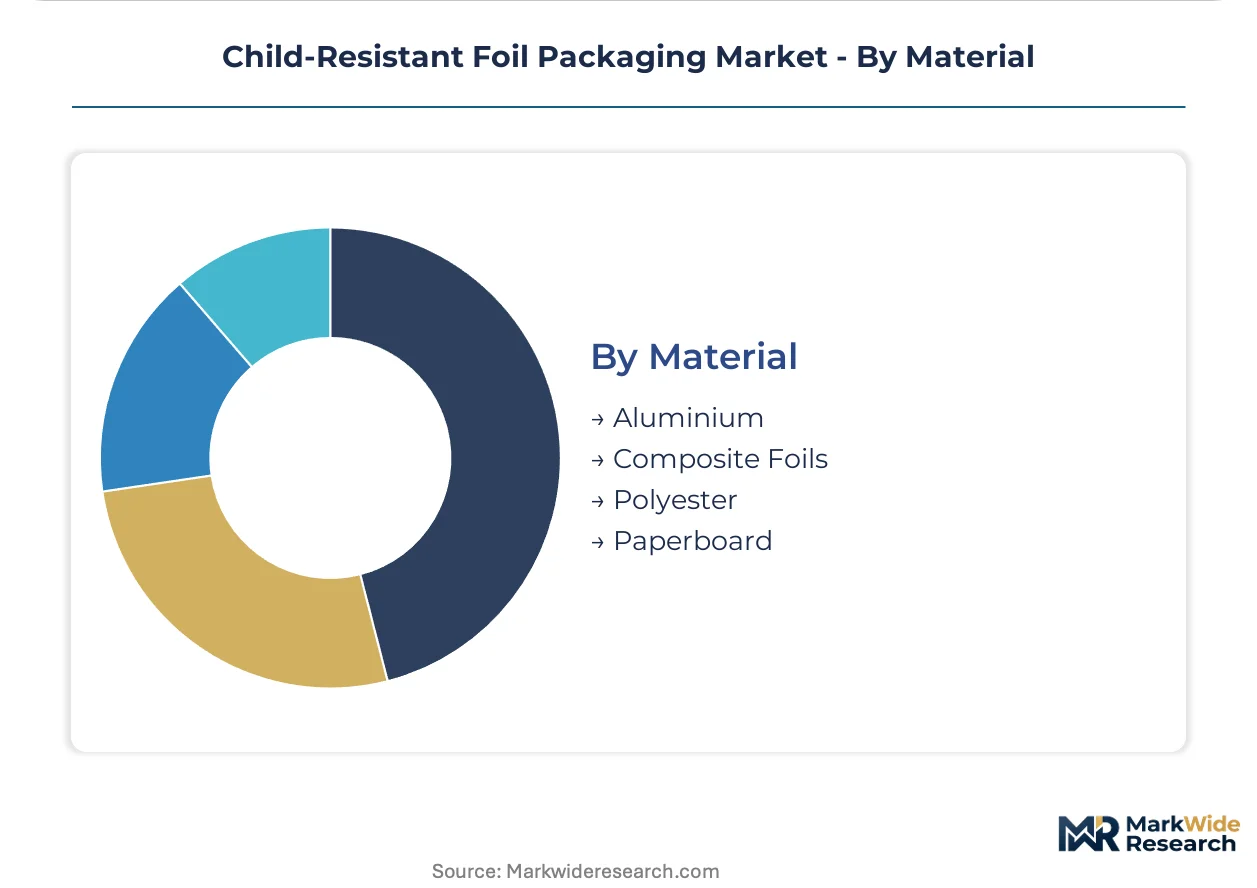
Aluminium retains dominant share; composite foils climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 16 CFR 1700 certification requirements anchor United States demand, while EMA MDR protocols reshape European sourcing patterns. German pharmaceutical contract packaging clusters generate concentrated foil demand with non-negotiable compliance standards. Indian pharmaceutical exports and Canadian cannabis packaging emerge as secondary growth vectors with distinct regulatory pathways.
United States
Opioid packaging mandates and multi-state cannabis regulations drive ASTM D3475 certification demand across pharmaceutical and consumer goods segments. FDA protocol enforcement intensifies as state-level cannabis rules fragment, rewarding modular closure platforms. California and Colorado cannabis packaging operations concentrate procurement with converters holding captive testing laboratories.
Germany
Heidelberg-Frankfurt pharmaceutical contract packaging corridors generate specialized foil demand for chronic disease medication compliance packs. EMA MDR child-safety mandates tighten closure-performance standards, disqualifying uncertified converters from European supply chains. Baden-Württemberg extrusion facilities anchor regional laminate production serving both domestic and export pharmaceutical clients.
Canada
Cannabis legalization frameworks drive stand-up pouch adoption as brands migrate from rigid containers to flexible formats with press-to-close mechanisms. Health Canada packaging regulations align with ASTM protocols, creating certification overlap with US-bound suppliers. Ontario and British Columbia processing facilities concentrate demand for senior-accessible child-resistant closures.
India
CDSCO alignment with FDA protocols creates compliance pathways for converters serving US-bound generic drug shipments. Pharmaceutical export packaging investments accelerate in Gujarat and Maharashtra as contract manufacturers expand FDA-certified production lines. Mumbai-Pune pharmaceutical corridors generate foil demand calibrated to international child-resistance standards.
Switzerland
Swissmedic pharmaceutical packaging requirements sustain premium positioning for dual-certified closure systems achieving both child-resistance and senior-accessibility ratings. Basel-area pharmaceutical headquarters drive specialized sourcing for high-barrier unit-dose applications. Domestic converter investments focus on lidding film precision for temperature-sensitive biologic medications.
Child-Resistant Foil Packaging Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with qualification depth separating contract-eligible converters from commodity suppliers. Market structure rewards players with captive certification laboratories and in-house film extrusion capacity. Three archetypes dominate: integrated multinational converters with pharmaceutical corridor presence, regional specialists in lidding film engineering, and modular closure platform developers serving fragmented regulatory environments. Competitive moves concentrate on M&A to secure certification assets and capacity expansion near German pharmaceutical clusters.
Among European integrated leaders, Constantia Flexibles and Huhtamaki Oyj occupy positions shaped by lidding film specialization and regulatory protocol mastery. Amcor Limited represents the scale-driven archetype with extrusion capacity positioned across pharmaceutical manufacturing corridors. These three entities exemplify how converter qualification hierarchies reorganize around FDA and EMA certification depth rather than unit volume alone.
| Leading Market Players |
|---|
| Constantia Flexibles |
| Huhtamaki Oyj |
| Amcor Limited |
| Sealed Air Corporation |
| Coveris Holdings S.A. |
| Berry Global Inc. |
| Winpak Ltd |
| Clondalkin Group |
| Sonoco Products Company |
| Others |
Supply Flow & Price Mechanics
Composite foil substitution for pure aluminium laminates redraws supply geography toward European extrusion hubs while compressing margin structures on legacy fixed-price pharmaceutical contracts. German converters near Heidelberg and Frankfurt exploit captive multi-layer coextrusion capacity to capture premium positioning, while North American suppliers absorb London Metal Exchange volatility through contract renegotiation clauses.
Pricing Analysis
Price spreads between German pharmaceutical corridor converters and Asian export-oriented suppliers reflect certification depth rather than input cost alone. Three-tier pricing structure across FDA-certified premium, EMA-compliant standard, and uncertified economy levels stratifies the vendor base. Cost compression in the economy tier intensifies because aluminium price volatility outpaces contract adjustment cycles. Generic drug contract manufacturers in India exhibit highest price sensitivity; Swiss biologic brands show least.
Supply Chain Analysis
Inventory lead times for press-to-close zipper dies extend eighteen to twenty-four months due to tooling engineer scarcity concentrated in Italy and Germany. Raw material flows draw from German aluminium rolling mills, Chinese polyester film extruders, and Belgian adhesive formulators. Single-source vulnerability concentrates in European die engineering shops serving ASTM D3475 certification requirements. Distribution runs through pharmaceutical contract packaging clusters rather than direct brand-owner procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified converter capacity trails demand acceleration, with in-house certification laboratory scarcity now determining contract eligibility more than unit cost. The bottleneck sits in polymer science talent capable of calibrating tear-initiation forces within narrow ASTM D3475 tolerance bands.
For Market Incumbents: Compound certification asset advantages by acquiring European tooling engineering boutiques before competitor consolidation. Expand captive testing laboratory capacity in the Heidelberg-Frankfurt corridor to preempt ISO 8317 backlog delays. Defend margin structures through backward integration into heat-seal coating formulation rather than commodity aluminium sourcing. For New Entrants and Emerging Players: Differentiate on modular closure platforms reconfigurable across fragmented US state-level cannabis regulations without SKU proliferation. Target Indian pharmaceutical export packaging corridors where CDSCO-FDA alignment creates compliance pathways absent entrenched converter relationships. Pursue senior-accessibility dual certification as the primary go-to-market wedge against established suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap European converters with captive extrusion lines and EMA MDR certification depth rather than volume-scale commodity players. Long-term viability hinges on regulatory protocol mastery rather than geographic expansion alone. Watch ASTM D3475 testing laboratory capacity utilization as the inflection signal for qualification bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Laboratory Acquisition | In-house ASTM D3475 testing capability compresses product launch timelines by eliminating third-party queue delays. |
| Modular Closure Platform Development | Reconfigurable press-to-close mechanisms address patchwork US state cannabis regulations without SKU proliferation costs. |
| Heat-Seal Coating Formulation Investment | REACH-compliant adhesive alternatives secure EMA market access ahead of sunset date enforcement. |
| Tooling Engineering Talent Recruitment | Press-to-close zipper die expertise concentrates among Italian and German specialists, creating hiring scarcity. |
| Pharmaceutical Corridor Capacity Expansion | Proximity to Heidelberg-Frankfurt contract packaging clusters reduces logistics costs for FDA 16 CFR 1700 compliance. |
Methodological Framework
Operator-level perspectives from foil converter plant managers, pharmaceutical packaging procurement leads, certification laboratory technical directors, and cannabis brand supply chain heads anchored the qualitative base. Secondary validation drew from FDA 16 CFR 1700 protocol documentation, EMA MDR submission databases, German pharmaceutical industry association reports, and London Metal Exchange aluminium pricing records. Bottom-up volume estimates triangulated against top-down market sizing across closure type and end-use segments.
Sensitivity analysis tested forecast robustness across aluminium price volatility scenarios and certification timeline compression assumptions. Segmentation modeling incorporated product type, closure mechanism, end-use application, material composition, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate aggregation weighted by baseline volume shares. Industry-specific inputs included ISO 8317 laboratory capacity constraints and REACH substance restriction implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EMA enforcement intensity would require recalibration. Forecasts reflect assumptions regarding certification backlog duration and tooling engineer supply elasticity. Revision becomes warranted when aluminium price volatility crosses thresholds that trigger contract renegotiation cascades.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
Copper Coated Films Market
Packaging Barrier Films
Transport Protection Film Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Global Peelable Lidding Films Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
Barrier Shrink Films Market
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Biodegradable Plastic Films Market
Packaging Barrier Films
Saudi Arabia Plastic Packaging Films Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Perforated Packaging Market