
 Commonwealth of Independent States (CIS) Underground Mining Equipment Market | 2026-2036
Commonwealth of Independent States (CIS) Underground Mining Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Commonwealth of Independent States (CIS) Underground Mining Equipment Market Outlook
Coal mining is shifting toward deeper, mechanized extraction across the CIS, displacing labor-intensive methods in aging Siberian pits. Sandvik AB leverages its automation portfolio to capture premium contracts in Russia's Kuzbass basin. BELAZ anchors domestic supply chains through heavy-duty shuttle car production at its Zhodino complex. Caterpillar competes via established dealer networks spanning Kazakhstan and Uzbekistan.
Underground mining equipment encompasses specialized machinery engineered to operate below surface level in confined, high-stress environments, typically featuring explosion-proof electrical systems, reinforced structural frames, and ventilation-integrated designs rated for methane-rich atmospheres. These systems perform drilling, cutting, hauling, and ground support functions essential to accessing ore bodies unreachable through surface methods. Longwall equipment commands substantial capital allocation where retreat mining dominates thick seams, while automation technology is capturing disproportionate investment as labor costs rise and safety thresholds tighten. Roof support equipment retains stable replacement demand given its consumable-like wear profile in geologically disturbed zones.
Russia's Federal Service for Environmental, Technological and Nuclear Supervision (Rostekhnadzor) enforces mandatory certification for machinery deployed in gassy mines, directly filtering import eligibility and retrofit requirements. Kazakhstan's Committee for Industrial Development aligns equipment subsidies with local content thresholds, shaping vendor selection for state-owned mine operators. Stakeholders must monitor how Belarusian and Chinese manufacturers navigate evolving Eurasian Economic Union technical regulations to preserve market access.
Market Dynamics
Automation-capable longwall systems are displacing conventional mechanized extraction across Siberian and Kazakh coal basins as seam depths exceed economically viable open-pit thresholds and labor availability tightens.
Growth Catalysts
- Seam deepening economics:Coal operations in Kazakhstan's Karaganda region now require longwall systems where surface stripping ratios became uneconomic. State-backed modernization programs sustain replacement cycles for state-owned mine operators.
- Rostekhnadzor safety mandates:Russia's updated industrial safety regulations for hazardous underground workplaces compel fleet upgrades toward remote-operated and automation-capable platforms in gassy mine environments.
- Local content subsidies:Kazakhstan's Committee for Industrial Development ties equipment subsidies to domestic assembly thresholds, steering procurement toward vendors with regional manufacturing presence.
Market Restraints
- Import certification friction:Rostekhnadzor's mandatory machinery certification for gassy mines creates extended validation timelines for non-Eurasian Economic Union suppliers, filtering market access.
- Capital intensity barriers:Longwall system procurement requires multi-year capital allocation cycles that strain privately held mining operators without state-backed financing guarantees.
- Geographic supply concentration:Critical subsystems including explosion-proof electrical components concentrate in Belarusian and Russian manufacturing clusters, exposing buyers to cross-border logistics volatility.
Strategic Opportunities
- Uzbekistan mine mechanization:Underpenetrated underground coal and gold extraction in the Navoi and Angren basins offers first-mover positioning for automation-integrated system vendors.
- Remote operation convergence:Integration of 5G-enabled telemetry with autonomous cutting heads creates service-layer revenue potential beyond equipment sales in Russia's Kuzbass basin.
- Eurasian Economic Union harmonization:Unified technical regulations across member states reduce duplicate certification burdens for vendors establishing regional assembly capacity.
Industry Challenges
- Automation engineering scarcity:Mine operators in Siberian coal basins face acute shortages of technicians capable of maintaining integrated longwall automation systems, forcing reliance on vendor field service.
- Legacy fleet integration complexity:Retrofitting automation-capable controls onto Soviet-era continuous miners requires custom engineering that extends deployment timelines and inflates project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commonwealth of Independent States (CIS) Underground Mining Equipment Market |
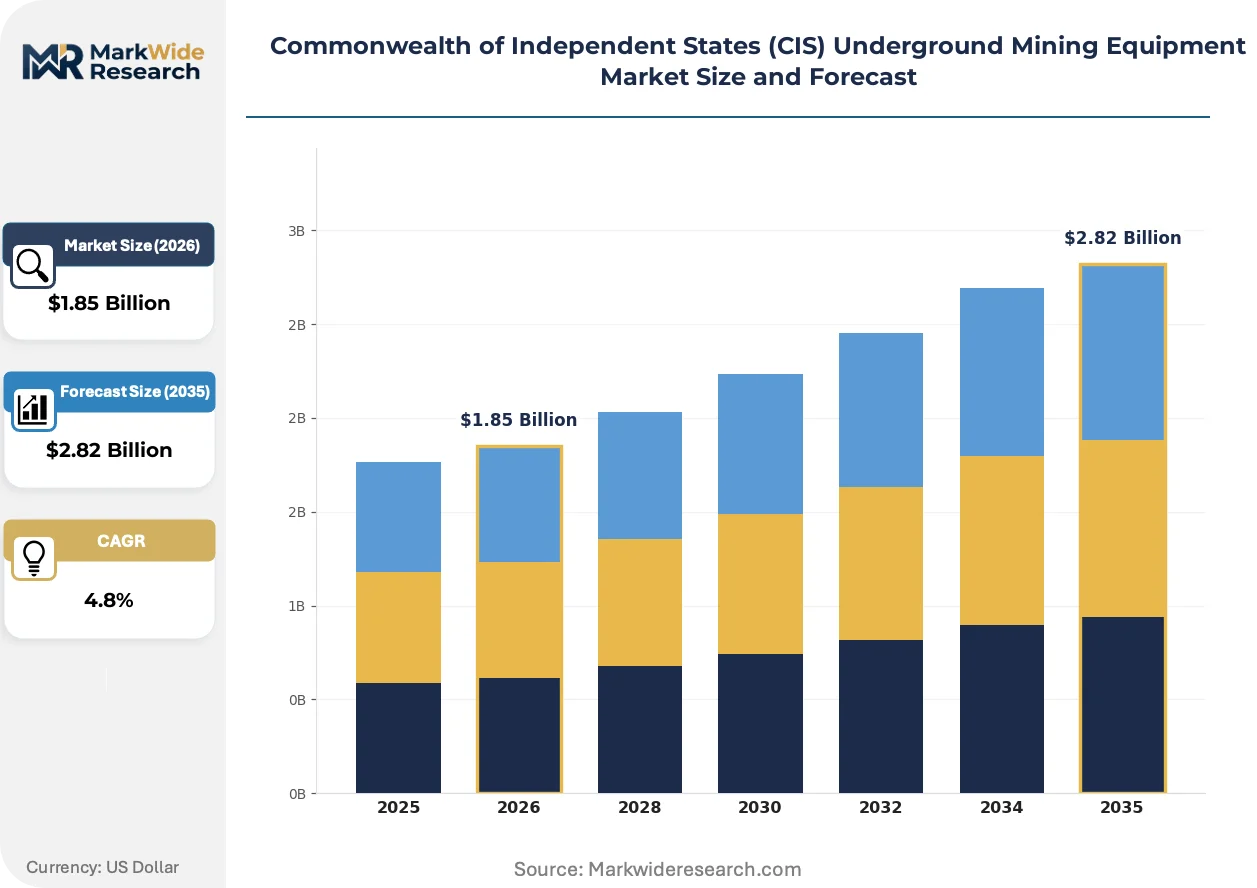
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Miners, Longwall Equipment, Roof Support Equipment, Shuttle Cars Technology: Automation, Remote Control, Hybrid Systems, Electric Drives End User: Coal Mining, Metal Mining, Mineral Mining, Non-Metallic Mining Application: Drilling, Excavation, Transportation, Support |
| Companies Covered | Sandvik AB, Liebherr-International Deutschland GmbH, BELAZ, SANY Group, Metso, Caterpillar, Komatsu Mining Corp, Hyundai Doosan Infracore, Epiroc AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commonwealth of Independent States (CIS) Underground Mining Equipment Market Strategic Shifts
Remote-operated and autonomous mining platforms are compressing labor requirements while elevating safety thresholds across methane-rich extraction environments in the CIS region.
Autonomous longwall shearers equipped with real-time seam boundary detection and adaptive cutting algorithms are rewriting operational economics in Russia's Kuzbass basin. SUEK and other major coal operators are deploying these systems at pace in seams exceeding 400 meters depth. The technology is compressing labor headcount requirements by half while extending productive cutting hours beyond shift-based limitations.
Rostekhnadzor's 2024 amendments to industrial safety regulations mandate remote operation capabilities for all new longwall installations in gassy mines. The policy forces immediate capital redirection toward automation-ready platforms and disqualifies conventional manned equipment from new procurement. Kazakh state-owned operators are accelerating compliance timelines to align with concurrent subsidy eligibility windows.
Buyer consolidation around integrated system procurement is displacing component-level equipment sourcing across major CIS coal basins. Mine operators now specify single-vendor accountability for longwall cutting, roof support, and armored face conveyor subsystems. Kazakhstan's state mining holdings are pioneering this bundled approach in the Karaganda region, compressing vendor negotiation cycles and elevating aftermarket service contract values.
Commonwealth of Independent States (CIS) Underground Mining Equipment Market Segmentation
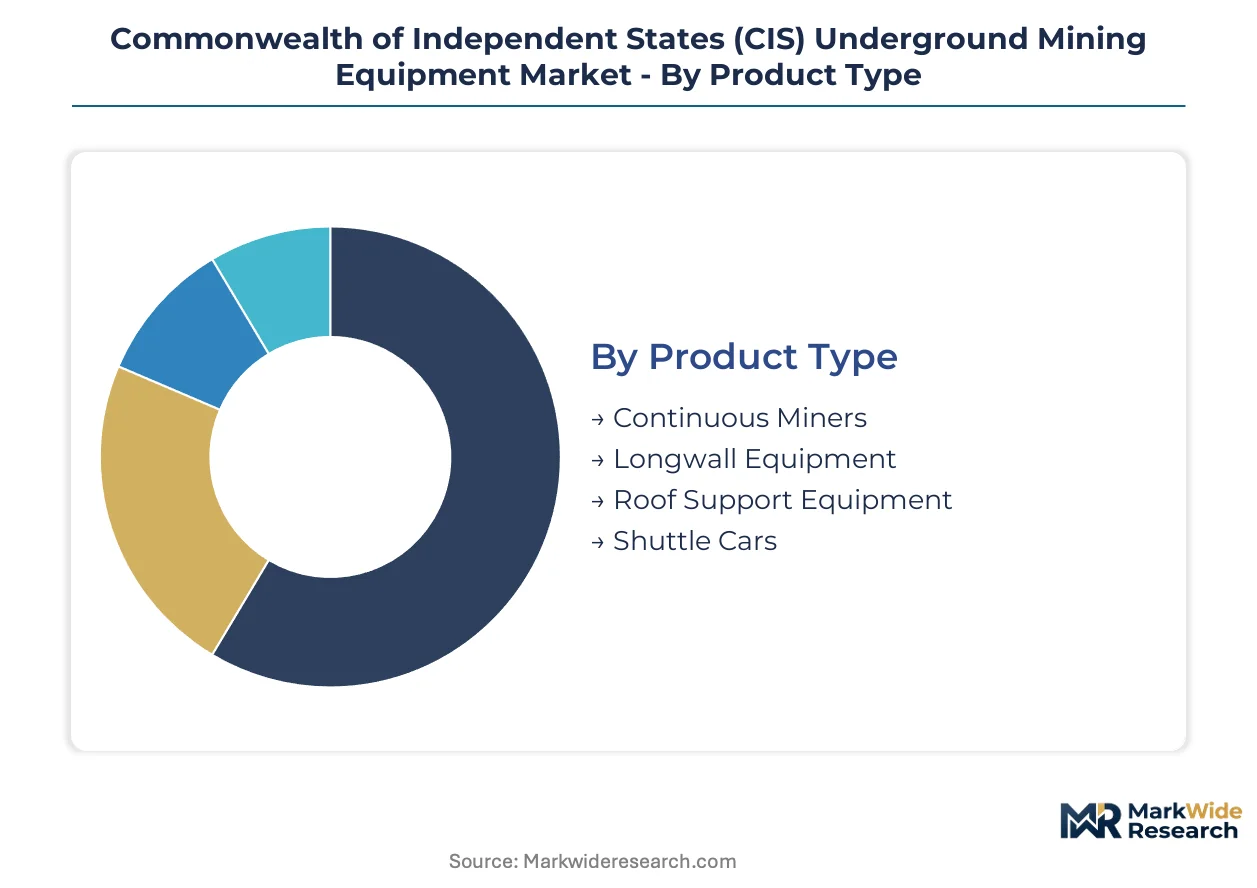
Equipment specification choices in the CIS underground mining sector hinge on seam depth, methane classification, and the availability of skilled maintenance labor. Procurement committees weight automation compatibility against retrofit feasibility and local content compliance thresholds.
Product Type:
Capital allocation cycles favor integrated systems over component-level purchasing as state-owned operators consolidate vendor accountability.
- Continuous Miners:These drum-cutting machines integrate gathering arms and loading mechanisms for room-and-pillar extraction in medium-thickness seams. Demand clusters in Kuzbass basin operations where gassy conditions mandate explosion-proof electrical enclosures. Kazakh procurement offices prioritize models with modular cutting heads to reduce parts inventory.
- Longwall Equipment:Shearers paired with armored face conveyors and hydraulic roof supports enable full-seam retreat mining in thick deposits exceeding 400 meters depth. SUEK and other Russian operators are replacing Soviet-era mechanized faces with automation-capable platforms. The Karaganda region drives replacement demand as surface stripping ratios deteriorate.
- Roof Support Equipment:Hydraulic shield supports and individual props manage ground pressure in geologically disturbed zones. These systems exhibit consumable-like replacement cycles.
- Shuttle Cars:Articulated haulers transfer coal from continuous miner faces to feeder breakers. BELAZ manufactures heavy-duty variants at its Zhodino complex.
Volume sits with Longwall Equipment; growth tilts toward Continuous Miners.
Technology:
Regulatory mandates from Rostekhnadzor are filtering procurement toward platforms with proven telemetry architectures.
- Automation:Autonomous shearers with real-time seam boundary detection compress labor headcount by half while extending productive cutting hours. Deployment concentrates in Kuzbass gassy mines where remote operation is now mandatory for new installations.
- Remote Control:Line-of-sight and teleoperated systems enable operator positioning in fresh air while machinery works in hazardous zones. These platforms dominate retrofit applications where full automation integration proves cost-prohibitive.
- Hybrid Systems:Diesel-electric powertrains bridge gaps in underground electrical infrastructure.
- Electric Drives:Explosion-proof AC motors eliminate diesel particulate exposure and reduce ventilation loads.
Adoption concentrates in Automation; expansion runs fastest through Electric Drives.
End User:
Deposit geology and state ownership structure shape equipment specification priorities across extraction sectors.
- Coal Mining:Bituminous and anthracite operations in Siberian and Kazakh basins command the dominant equipment procurement volume. Seam deepening economics and safety mandates are accelerating fleet turnover toward automation-capable platforms.
- Metal Mining:Copper-nickel and polymetallic operations in the Norilsk region and Ural Mountains deploy specialized ground support and haulage equipment. Harsh thermal conditions stress hydraulic systems.
- Mineral Mining:Potash and salt extraction in Belarus and Russia's Volga region utilizes continuous mining techniques with corrosion-resistant materials.
- Non-Metallic Mining:Limestone and gypsum operations employ lighter-duty equipment given lower ground stress and non-gassy conditions.
Equipment fleet scale favors Coal Mining; contract velocity is climbing fastest in Metal Mining.
Application:
Operational phase sequencing determines subsystem interdependence and vendor bundling strategies.
- Drilling:Roof bolters and long-hole drills establish ground support and blast patterns. Demand concentrates in development headings where mechanized bolting advances cycle times.
- Excavation:Shearers and continuous miners perform the primary coal or ore extraction function. This application captures the largest capital allocation per production face.
- Transportation:Armored face conveyors, shuttle cars, and stage loaders move material from extraction point to surface.
- Support:Ventilation, pumping, and auxiliary systems maintain safe working environments.
Capital intensity peaks in Excavation; modernization urgency is strongest in Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kazakhstan's Karaganda Special Economic Zone concentrates longwall system demand as seam depths exceed surface stripping economics across state-owned mining holdings.
Russia
Kuzbass basin coal operators deploy automation-capable shearers as seam depths surpass 400 meters. Rostekhnadzor mandates remote operation for all new longwall installations in gassy mines from 2024. Novokuznetsk industrial cluster anchors domestic manufacturing of explosion-proof electrical subsystems.
Kazakhstan
Karaganda region drives procurement of integrated longwall systems where open-pit ratios turned uneconomic. The Committee for Industrial Development ties equipment subsidies to local assembly thresholds exceeding 50 percent. Temirtau mining complex sustains replacement cycles through state-backed modernization programs.
Belarus
Zhodino manufacturing complex anchors regional supply chains for heavy-duty shuttle cars and haulage equipment. The Eurasian Economic Union technical regulations harmonize certification standards across member states. Soligorsk potash operations utilize continuous mining techniques with corrosion-resistant materials.
Uzbekistan
Navoi and Angren basins present underpenetrated opportunities for mechanized underground coal and gold extraction. The national industrial development strategy prioritizes foreign equipment partnerships with technology transfer requirements. Almalyk mining cluster advances pilot automation programs in polymetallic operations.
Ukraine
Donetsk basin operations maintain demand for roof support equipment and continuous miners amid constrained capital cycles. The State Service of Mining Supervision enforces industrial safety standards for hazardous underground workplaces. Dnipro industrial region concentrates maintenance capabilities for Soviet-era fleet retrofits.
Commonwealth of Independent States (CIS) Underground Mining Equipment Market Competitive Environment
Top-tier vendors anchor premium automation contracts, while mid-tier fabricators compete on local content compliance and retrofit compatibility. The market structures around three tiers: integrated system providers, regional assembly specialists, and component subsystem suppliers. Strategic archetypes include automation-technology licensors, Eurasian Economic Union manufacturing anchors, and state-backed domestic champions. Competitive moves concentrate on establishing regional assembly capacity and securing aftermarket service contracts.
Among European-integrated mining technology groups, Sandvik AB and Epiroc AB represent the automation-capable tier, while BELAZ anchors the Eurasian Economic Union manufacturing vector. Caterpillar occupies a position bridging established dealer networks with state procurement frameworks. These three exemplify distinct competitive archetypes: technology-led system integration, regional supply chain anchoring, and global distribution leverage.
| Leading Market Players |
|---|
| Sandvik AB |
| Liebherr-International Deutschland GmbH |
| BELAZ |
| SANY Group |
| Metso |
| Caterpillar |
| Komatsu Mining Corp |
| Hyundai Doosan Infracore |
| Epiroc AB |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between Rostekhnadzor-approved automation platforms and legacy mechanized equipment manifests in procurement premiums for certified longwall systems and fragmented supplier qualification across the Eurasian Economic Union. State-owned mine operators in Kazakhstan and Russia absorb extended lead times for certified subsystems while private operators face spot-market pricing for non-compliant inventory.
Pricing Analysis
Short lead-time premiums dominate pricing for explosion-proof electrical components and hydraulic roof supports as Rostekhnadzor certification queues extend validation timelines. Contract-based long-term offtake agreements anchor volume procurement for state-backed operators, while spot-market transactions serve capital-constrained private mines. Price differentiation hinges on automation certification tier and local content compliance thresholds. Cost compression in standard mechanized equipment intensifies as Belarusian and Chinese manufacturers expand regional assembly capacity. State-owned operators exhibit lowest price sensitivity given subsidy-backed financing, while privately held Siberian coal ventures face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements for critical explosion-proof electrical subsystems compel mine operators to qualify both Belarusian and Russian component suppliers despite geographic concentration. Manufacturing clusters in Belarus, Russia, and Kazakhstan supply heavy-duty shuttle cars, hydraulic shield supports, and armored face conveyors. Raw material dependencies include high-grade steel plate, specialized hydraulic fluids, and flame-resistant cabling. Single-source vulnerability concentrates in proprietary automation control systems sourced from European technology licensors. Distribution runs through authorized dealer networks anchored in Novokuznetsk, Zhodino, and Karaganda industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained conditions in certified automation subsystems prop pricing premiums as Rostekhnadzor validation capacity fails to match procurement velocity across state modernization programs.
For Market Incumbents: To counter Belarusian and Chinese manufacturers expanding local assembly capacity, Sandvik AB and Epiroc AB should anchor regional service centers in Kuzbass and Karaganda to compress response times for automation system failures. Certification investment in Eurasian Economic Union technical regulations preserves import eligibility against evolving safety mandates. Capacity addition in regional explosion-proof electrical component manufacturing reduces cross-border logistics exposure. For New Entrants and Emerging Players: Enter via Uzbekistan's Navoi and Angren basins where mechanization rates lag regional benchmarks and foreign equipment partnerships carry technology transfer incentives. The underpenetrated gold and coal extraction segment offers lowest competitive density for automation-integrated system vendors. A go-to-market angle emphasizing remote-operation retrofit compatibility with Soviet-era continuous miners addresses legacy fleet integration complexity. For Investors and Strategic Acquirers: Re-rating potential sits with regional assembly specialists given Eurasian Economic Union harmonization reducing duplicate certification burdens across member states. Long-term viability over a multi-year horizon favors vendors with captive supply of hydraulic subsystems and established aftermarket service contracts. The signal to watch is Rostekhnadzor staffing expansion indicating validation capacity relief and pricing normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Assembly Capacity Expansion | Local content thresholds in Kazakhstan steer procurement toward Zhodino and Karaganda manufacturing clusters. |
| Automation Certification Investment | Rostekhnadzor mandates filter import eligibility and elevate aftermarket service contract values. |
| Remote Operation Technology Licensing | 5G-enabled telemetry integration creates recurring revenue beyond equipment sales in Kuzbass. |
| Aftermarket Service Network Buildout | Automation engineering scarcity forces mine operators toward vendor-dependent field service arrangements. |
| Joint Venture with State Mining Holdings | Kazakhstan's Committee for Industrial Development ties subsidies to domestic partnership structures. |
Study Parameters
Document review covered equipment procurement databases, Rostekhnadzor certification registries, and Eurasian Economic Union technical regulation filings, complemented by interviews with maintenance directors at Siberian coal operations, procurement leads at Kazakh state mining holdings, aftermarket service heads at regional dealer networks, and plant engineers at Belarusian manufacturing complexes. Secondary validation drew from customs trade data, industrial safety regulatory amendments, and state modernization program disclosures. Bottom-up equipment shipment tracking and top-down mining sector capital expenditure analysis enabled triangulation.
Cross-reference between historical procurement patterns and expert panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment type, automation technology tier, end-use sector, and regional regulatory cluster. CAGRs were derived from weighted average of trend-line extrapolation and scenario-adjusted growth assumptions. Industry-specific forecast inputs incorporated seam depth economics and labor availability projections for Siberian and Kazakh basins.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Rostekhnadzor staffing constraints or Eurasian Economic Union technical regulation amendments. Forecasts reflect documented assumptions regarding state subsidy continuity and certification timeline stability. A model refresh is warranted upon material change in Kazakhstan's local content threshold requirements or Kuzbass basin labor migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Surface Mining Machinery Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Underground Mining Diamond Drilling Market
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Underground Mining Automation Market
Mining Equipment
Mining Locomotive Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Geology and Mine Planning Solution Market