
 Underground Mining Diamond Drilling Market | 2026-2036
Underground Mining Diamond Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Mining Diamond Drilling Market Intelligence
Australian drill rig manufacturers is hardening supply chains for underground diamond drilling equipment after prolonged lead times for high-pressure hydraulic components. Boart Longyear leverages its integrated drill string manufacturing to secure captive supply of wireline core barrels across multiple continents. Sandvik Mining and Rock Technology anchors its position through automated drilling platforms that reduce operator exposure in deep ore bodies. Epiroc competes aggressively on electric-hydraulic hybrid architectures that cut ventilation burdens in confined raises.
Underground mining diamond drilling employs impregnated or surface-set diamond bits bonded to steel core barrels to extract intact rock cylinders from depths exceeding two kilometers, with typical core diameters ranging from 36 millimetres (BQ) to 146 millimetres (PQ). The method serves primarily to delineate ore boundaries, verify mineral grades, and guide stope planning in metalliferous operations where visual ore recognition fails. Diamond core drills dominate capital allocation among product categories because every greenfield and brownfield feasibility study depends on continuous core recovery for resource estimation. Automated drilling systems within the technology dimension command outsized attention from major mining houses seeking to remove operators from unsupported ground, though pneumatic units retain share in narrow-vein mechanization where power infrastructure remains absent.
Canada's provincial mining regulators, Australia's state-based workplace safety authorities, and South Africa's Department of Mineral Resources and Energy each enforce distinct ground support and ventilation standards that dictate drill rig specifications and operator certification requirements. ISO 18758 and national variants for rock drilling machinery further constrain equipment design, particularly for noise emissions and hydraulic fluid containment in environmentally sensitive catchments. Stakeholders must monitor how automated drilling interoperability standards evolve across jurisdictions, as fragmented certification pathways threaten to fragment fleet procurement decisions and strand development investments.
Market Dynamics
Automated drilling platforms are compressing operator exposure timelines while regulators in Canada, Australia, and South Africa harden ground stability mandates that force fleet replacement cycles. Equipment procurement decisions now hinge on interoperability certification rather than standalone performance metrics.
Growth Catalysts
- Deep-level ore delineation:Gold and copper operators in South Africa's Witwatersrand Basin are expanding core recovery programs to verify mineral grades beyond two-kilometer depths where visual recognition fails.
- ISO 18758 compliance mandates:National variants for rock drilling machinery in Canada and Australia now require noise emission controls and hydraulic fluid containment systems that drive equipment upgrade cycles.
- Wireline core barrel standardization:Impregnated diamond bit bonding techniques have improved core recovery rates in narrow-vein mechanization, sustaining capital allocation toward diamond drilling over pneumatic alternatives.
Market Restraints
- High-pressure hydraulic component scarcity:Prolonged lead times for specialized valves and pumps constrain rig manufacturing output and extend delivery timelines for underground fleets.
- Substitution by reverse circulation drilling:Exploration programs in shallow, unconsolidated formations increasingly deploy RC rigs that sacrifice core integrity for speed and lower per-meter costs.
- Regulatory fragmentation:Canada's provincial mining regulators, Australia's state-based workplace safety authorities, and South Africa's Department of Mineral Resources and Energy enforce non-aligned certification pathways that complicate multinational fleet standardization.
Strategic Opportunities
- Electric-hydraulic hybrid architectures:Mining houses in Canada's Abitibi greenstone belt are piloting battery-tethered rigs that reduce ventilation infrastructure burdens in confined raises and drifts.
- Automated drilling interoperability standards:Emerging cross-jurisdiction protocols for remote-operated rig communication create white space for control system vendors to capture recurring software revenue.
- Exploration budget rotation:Underground target allocations in Australia's Yilgarn Craton are rising as surface discoveries deplete, shifting demand toward compact, highly mobile diamond drill rigs.
Industry Challenges
- Certification timeline compression:Mining operators face extended validation periods for automated drilling platforms as regulators in multiple jurisdictions develop divergent safety case requirements for unmanned ground support.
- Legacy fleet integration friction:Brownfield operations struggle to retrofit existing drill string inventories with automated rod handling systems without complete string replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Mining Diamond Drilling Market |
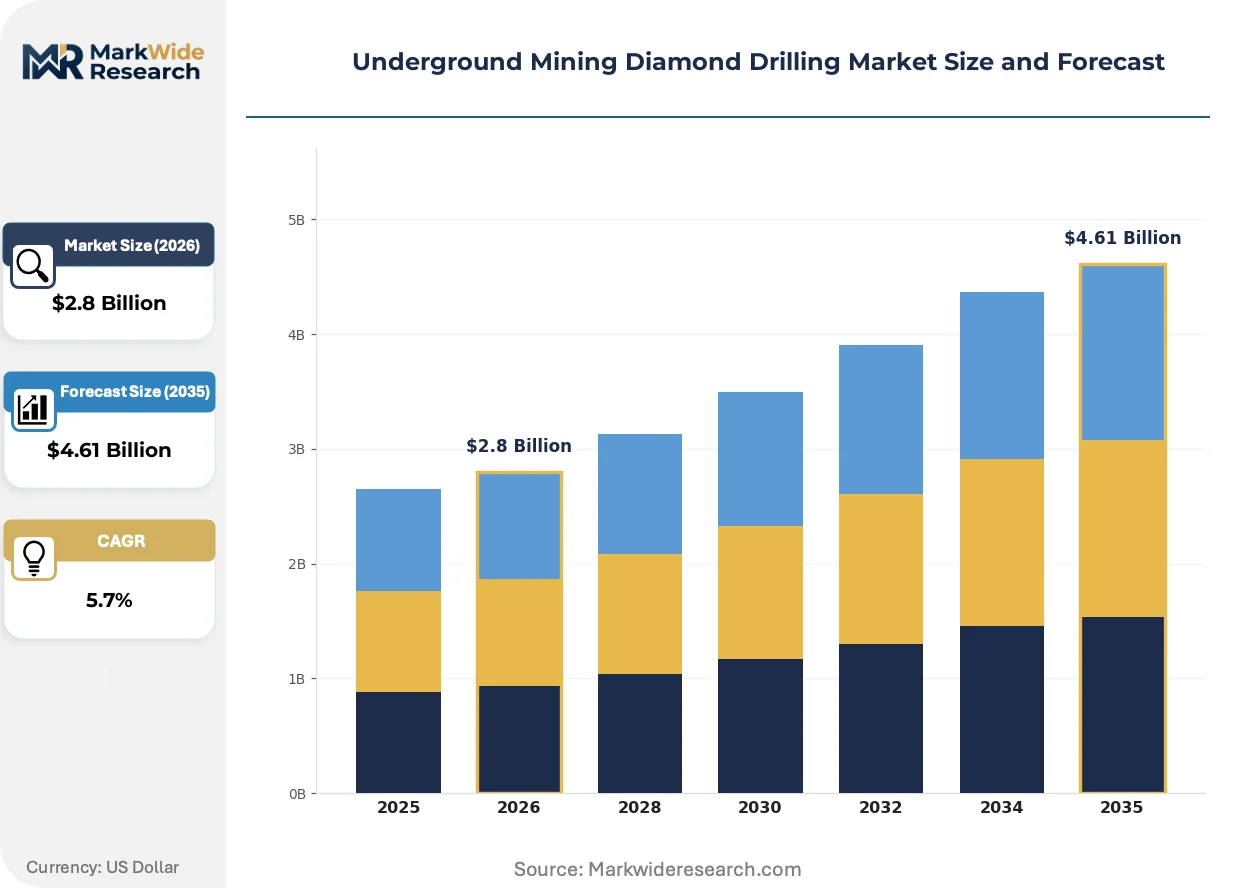
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diamond Core Drills, Percussion Drills, Down-the-Hole Drills, Rotary Drills, Wireline Drills Technology: Hydraulic Drilling, Pneumatic Drilling, Electric Drilling, Automated Drilling, Remote-Controlled Drilling Application: Ore Sampling, Geological Exploration, Tunnel Construction, Ground Support, Ventilation Shaft Drilling End User: Mining Operators, Geological Survey Firms, Construction Contractors, Equipment Leasing Companies |
| Companies Covered | Boart Longyear, Atlas Copco, Sandvik Mining and Rock Technology, Epiroc, Fordia, VersaDrill Canada, Geomachine Oy, Wuxi Geological Drilling Equipment Co., Ltd., Zinex Mining Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Mining Diamond Drilling Market Strategic Shifts & Innovations
Drill rig architecture is fragmenting into configurable subsystems that let operators swap power modules, mast configurations, and control interfaces without platform replacement. This modularity is compressing capital deployment cycles and enabling faster adaptation to ore body geometry changes.
Drill string telemetry systems are modularizing around standardized digital buses that transmit real-time vibration, torque, and penetration rate data to surface control cabins. Major mining houses in Canada's Abitibi belt and Australia's Kalgoorlie region are specifying these interfaces in procurement tenders. The technology is modularizing maintenance scheduling by enabling predictive component replacement rather than interval-based overhauls.
REACH and national variants for hydraulic fluid containment in the European Union and Australia now mandate biodegradable lubricant formulations and double-walled hose assemblies for environmentally sensitive catchments. Equipment manufacturers must redesign fluid power circuits to meet these specifications or face market exclusion. Underground contractors in Western Australia's Pilbara region are absorbing compliance costs through longer equipment financing terms.
After-sales service unbundling is disrupting traditional bundled maintenance contracts as mining houses develop in-house diagnostic capabilities through telemetry data ownership. Independent service providers in South Africa's platinum belt now compete for component-level repair work that OEMs previously captured. This shift is most visible in Canada's Sudbury Basin, where major nickel producers have established captive rebuild facilities for wireline core barrel refurbishment.
Underground Mining Diamond Drilling Market Segmentation
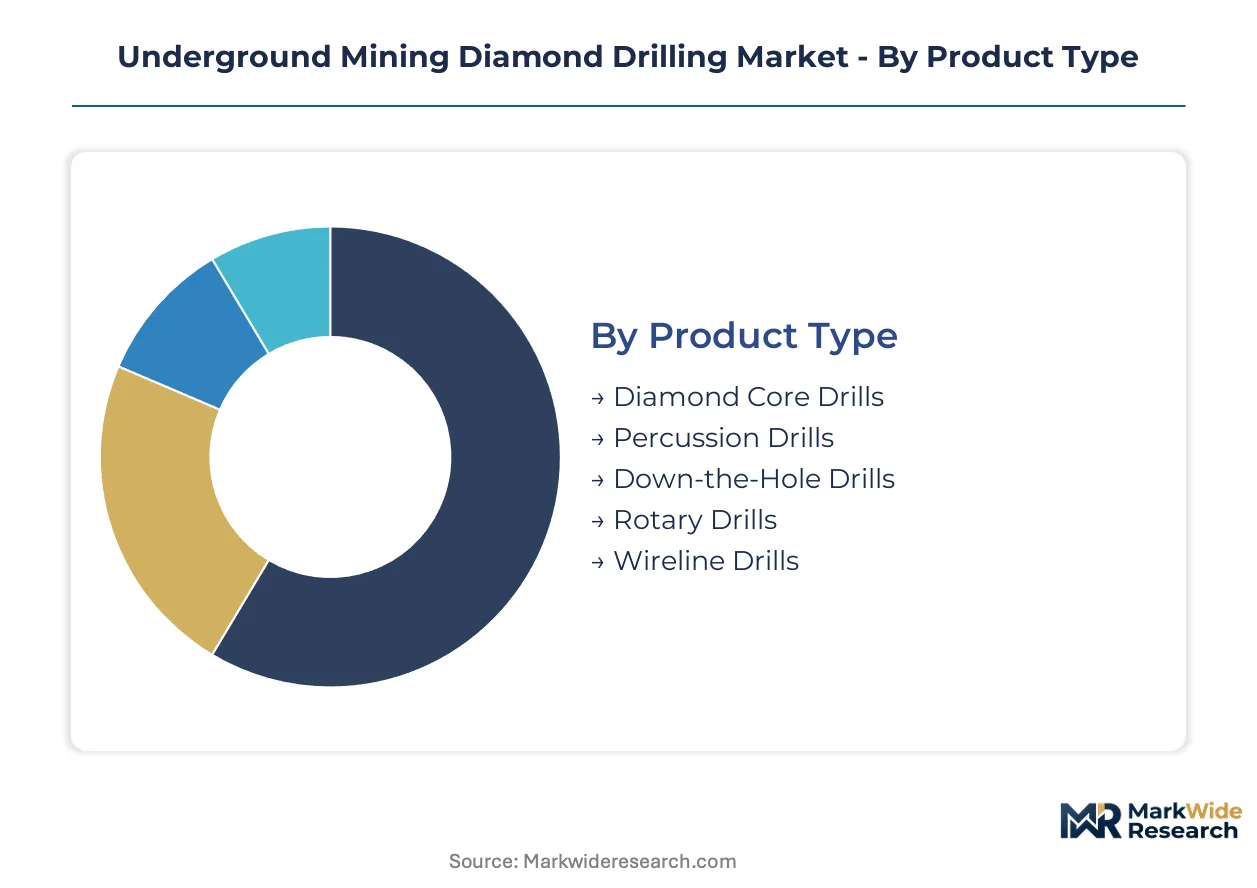
Segmentation in underground mining diamond drilling reveals how capital allocation splits across rig architectures and operational contexts. Equipment procurement decisions track ore body depth, ground stability mandates, and ventilation constraints that vary sharply by application and jurisdiction.
Product Type:
Replacement cycles in underground fleets are compressing as automated platforms displace legacy mechanical systems, forcing operators to reassess core recovery specifications against total cost of ownership.
- Diamond Core Drills:Impregnated or surface-set diamond bits bonded to steel core barrels extract intact rock cylinders from depths exceeding two kilometers. South Africa's Witwatersrand Basin operators deploy these for grade verification where visual ore recognition fails, driving sustained capital allocation despite higher per-meter costs than alternative methods.
- Wireline Drills:Rod retrieval without pulling the entire drill string cuts round-trip times in deep holes. Canada's Abitibi greenstone belt mining houses specify wireline configurations for narrow-vein targets where rapid core recovery directly impacts stope planning timelines and resource estimation confidence.
- Percussion Drills:Pneumatic hammer mechanisms suit blasthole drilling in ground support applications rather than core recovery.
- Down-the-Hole Drills:Hammer positioned at the bit bottom transmits energy efficiently through fractured formations.
- Rotary Drills:Tricone or drag bit configurations dominate large-diameter ventilation shaft development where core integrity matters less than penetration rate.
Volume placements concentrate in Diamond Core Drills; the faster expansion belongs to Wireline Drills.
Technology:
Power source selection in underground environments hinges on ventilation infrastructure availability and regulatory emissions thresholds that differ across Canada's provincial mining jurisdictions and Australia's state-based safety authorities.
- Automated Drilling:Remote-operated platforms remove operators from unsupported ground in deep ore bodies. Australia's Kalgoorlie region nickel producers are specifying these systems in procurement tenders to satisfy Western Australia's workplace safety authority mandates for minimizing exposure in seismically active ground.
- Electric Drilling:Battery-tethered or cable-electric architectures eliminate diesel particulate burdens in confined raises. Canada's Sudbury Basin copper-nickel operations are piloting electric-hydraulic hybrids to reduce ventilation infrastructure capital in brownfield expansions where shaft capacity is constrained.
- Hydraulic Drilling:High-pressure fluid power dominates precision core recovery with superior torque control.
- Pneumatic Drilling:Compressed air systems retain share in narrow-vein mechanization where electrical infrastructure is absent.
- Remote-Controlled Drilling:Line-of-sight or telerobotic operation provides intermediate automation for semi-mechanized operations.
Procurement volumes favor Hydraulic Drilling; Electric Drilling is climbing the fastest as ventilation regulations tighten.
Application:
Application selection tracks the mineral exploration lifecycle, with early-stage programs prioritizing speed and feasibility-stage operations demanding continuous core recovery for resource estimation compliance.
- Ore Sampling:Systematic core extraction defines mineral grade boundaries for reserve calculations. South Africa's platinum belt operators maintain dedicated sampling fleets to satisfy the Department of Mineral Resources and Energy reporting codes that govern public disclosure of mineral resources.
- Geological Exploration:Greenfield and brownfield target testing requires mobile, rapid-deployment rigs. Australia's Yilgarn Craton exploration budgets are rotating toward underground targets as surface discoveries deplete, shifting demand toward compact diamond drill rigs with modular mast configurations.
- Tunnel Construction:Pilot hole drilling and probe drilling ahead of excavation faces characterize civil mining applications.
- Ground Support:Rock bolting and cable bolt hole drilling supports excavation stability in permanent openings.
- Ventilation Shaft Drilling:Large-diameter raise boring and blind boring creates critical infrastructure for deep operations.
Equipment deployment concentrates in Ore Sampling; Geological Exploration is gaining share fastest as exploration budgets rotate underground.
End User:
Customer type determines financing structures and service relationships, with mining houses developing in-house diagnostic capabilities while contractors absorb compliance costs through extended equipment financing terms.
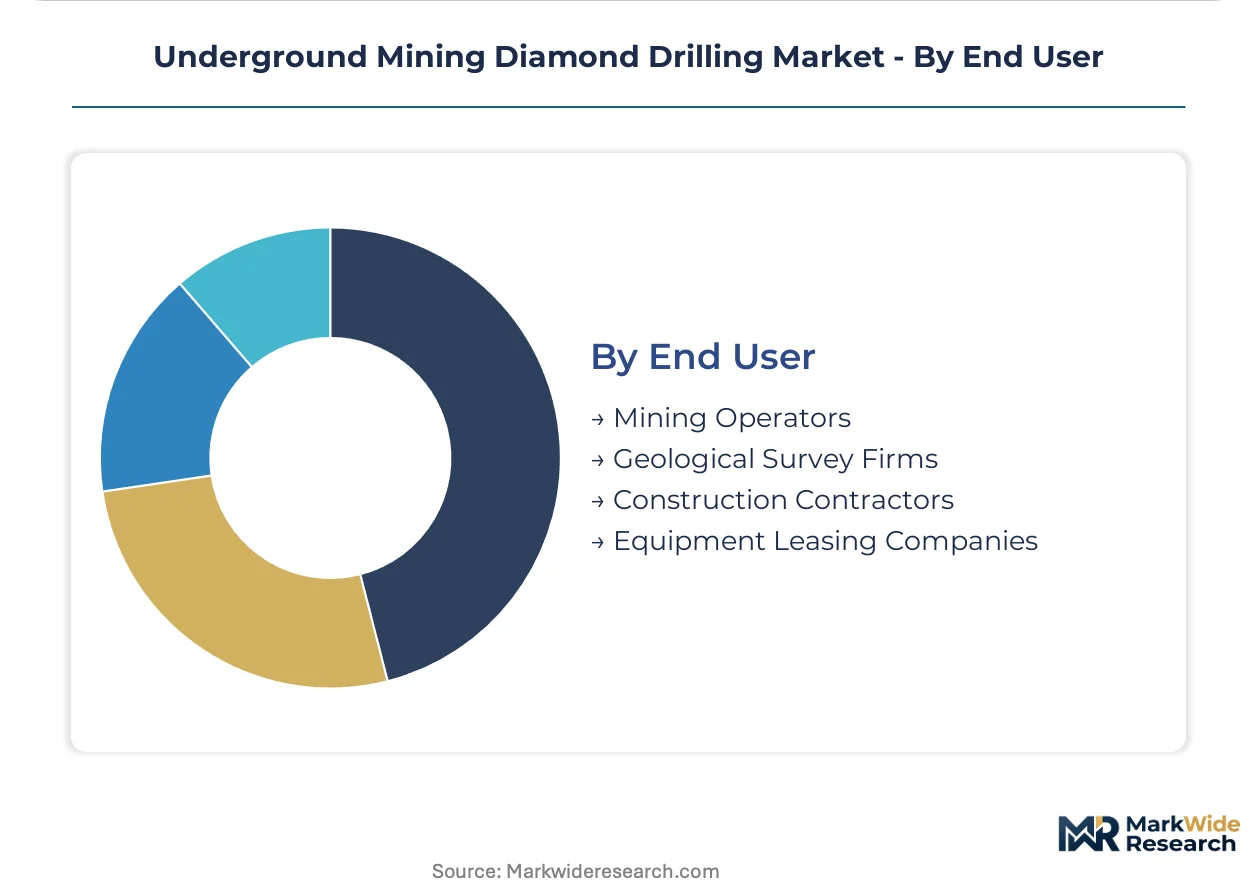
- Mining Operators:Integrated producers with captive geology departments specify automated platforms and retain telemetry data ownership. Canada's major nickel producers in the Sudbury Basin have established captive rebuild facilities for wireline core barrel refurbishment, unbundling after-sales service from OEM maintenance contracts.
- Geological Survey Firms:Independent contractors serving junior explorers prioritize rig mobility and rapid mobilization between projects. Western Australia's Pilbara region contractors are absorbing REACH-compliant hydraulic fluid containment costs through longer equipment financing terms arranged with leasing providers.
- Construction Contractors:Civil tunneling specialists deploy modified mining rigs for infrastructure projects.
- Equipment Leasing Companies:Fleet owners finance rig acquisitions for rental to operators seeking operational flexibility without capital commitment.
Capital deployment concentrates with Mining Operators; Geological Survey Firms are expanding fleet ownership fastest as exploration services unbundle from integrated producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Pilbara iron ore deposits and Canada's Abitibi greenstone belt anchor underground diamond drilling demand, with South Africa's Witwatersrand Basin and Chile's copper corridors completing the core geography.
Australia
Western Australia's Yilgarn Craton drives exploration budget rotation toward underground targets as surface discoveries deplete. TGA-aligned workplace safety authorities mandate automated drilling platforms to minimize operator exposure in seismically active ground. Kalgoorlie region nickel producers specify remote-operated rigs in procurement tenders to satisfy these requirements.
Canada
Ontario's Sudbury Basin and Quebec's Abitibi belt concentrate capital allocation for deep ore delineation in copper-nickel operations. Provincial mining regulators enforce ISO 18758 noise emission controls and hydraulic fluid containment standards that force equipment upgrade cycles. Sudbury nickel producers have established captive rebuild facilities for wireline core barrel refurbishment.
South Africa
The Witwatersrand Basin sustains core recovery programs beyond two-kilometer depths where visual ore recognition fails. The Department of Mineral Resources and Energy governs public disclosure codes for mineral resource reporting that dictate dedicated sampling fleet maintenance. Platinum belt operators absorb compliance costs through extended equipment financing terms.
Chile
Copper corridors in the Atacama and Coquimbo regions deploy diamond drilling for ore body delineation in porphyry deposits. National mining regulator SERNAGEOMIN enforces ground stability standards that align with international certification pathways. Northern desert operations prioritize electric-hydraulic hybrid architectures to reduce ventilation infrastructure burdens.
China
Shandong and Jiangxi provinces concentrate domestic rig manufacturing capacity for regional supply. GB standards for rock drilling machinery constrain equipment design alongside MIIT industrial policy directives. Wuxi-based fabricators serve captive demand from state-owned mining conglomerates expanding underground base metal operations.
Underground Mining Diamond Drilling Market Key Industry Players
Global majors compete with regional champions across automated platform certification and aftermarket service reach. The vendor base separates into three tiers: integrated drilling technology conglomerates with captive drill string manufacturing, specialized wireline equipment fabricators with modular subsystem expertise, and regional rig builders serving price-sensitive contractors. Consolidation pressure intensifies as interoperability standards fragment procurement decisions. Dominant competitive moves include backward integration into high-pressure hydraulic component supply and geographic expansion through leasing partnerships.
Among integrated technology providers, Boart Longyear and Sandvik Mining and Rock Technology exemplify the premium-tier archetype through captive supply chain control. Epiroc occupies a position within the electric-hydraulic hybrid specialization. Wuxi Geological Drilling Equipment Co., Ltd. represents the regional-scale fabricator tier serving domestic Chinese mining houses. VersaDrill Canada and Geomachine Oy sit within the narrow-vein mechanization specialist category with compact rig configurations.
| Leading Market Players |
|---|
| Boart Longyear |
| Atlas Copco |
| Sandvik Mining and Rock Technology |
| Epiroc |
| Fordia |
| VersaDrill Canada |
| Geomachine Oy |
| Wuxi Geological Drilling Equipment Co., Ltd. |
| Zinex Mining Corp |
| Others |
Cost & Logistics Intelligence
Electric-hydraulic hybrid rig adoption in Canada's Sudbury Basin and Australia's Kalgoorlie region is simultaneously compressing ventilation infrastructure costs and concentrating procurement power among integrated technology providers with captive component supply. This technology transition tightens price competition in the hydraulic drilling tier while elevating premium capture for automated platforms certified under ISO 18758 and TGA-aligned safety mandates.
Pricing Analysis
After-sales service unbundling now dominates contract structures, with mining houses in South Africa's platinum belt and Canada's Abitibi greenstone belt separating telemetry data ownership from OEM maintenance agreements. Three-tier pricing structure across premium automated platforms, standard hydraulic rigs, and economy pneumatic units reflects certification grade and interoperability compliance rather than raw performance metrics. Cost compression in the hydraulic tier is intensifying because high-pressure component scarcity extends delivery timelines and forces contractors to absorb financing carry costs. Junior exploration contractors serving Australia's Yilgarn Craton exhibit highest price sensitivity, while integrated nickel producers in Sudbury prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
High-pressure hydraulic component supply rests on German precision valve manufacturers, Japanese specialty pump fabricators, and Chinese steel forging operations for core barrel production. Impregnated diamond bit manufacturing draws from synthetic diamond synthesis facilities in China and abrasive bonding specialists in Europe. Supply chain risk centers on single-source vulnerability for specialized wireline retrieval systems, where Boart Longyear's integrated drill string manufacturing creates captive supply advantages. Distribution runs through OEM direct sales for automated platforms, regional leasing partnerships for mid-tier hydraulic rigs, and independent distributors serving price-sensitive contractors in narrow-vein mechanization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
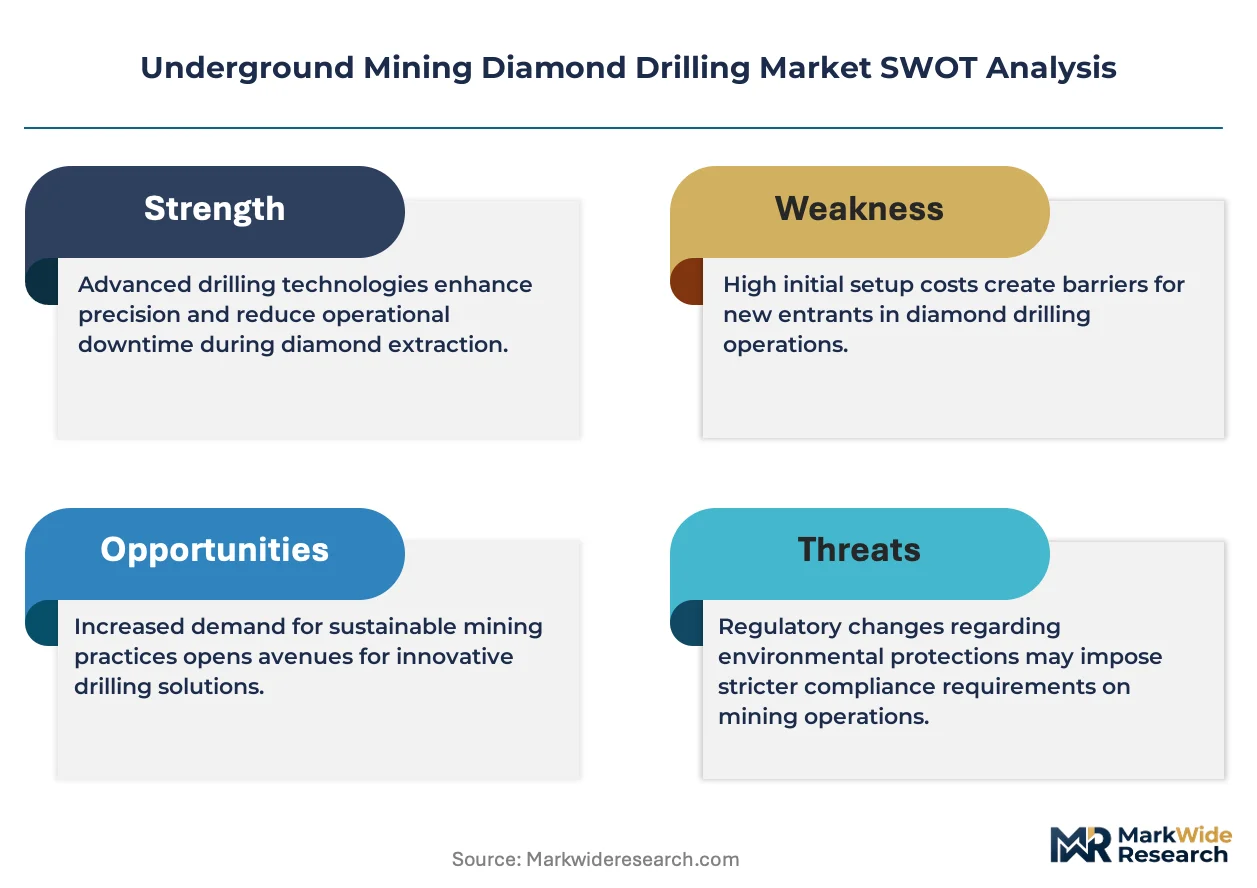
ISO 18758 compliance mandates and national variants for rock drilling machinery construct a formidable barrier-to-entry moat, elevating capital requirements for certification investment and fragmenting procurement decisions across Canada's provincial regulators, Australia's state-based authorities, and South Africa's Department of Mineral Resources and Energy.
For Market Incumbents: Deepen backward integration into high-pressure hydraulic component supply to secure captive manufacturing capacity against prolonged lead times that constrain rig output. Anchor market position through automated drilling interoperability certification investments that preempt regulatory fragmentation across jurisdictions, while developing predictive maintenance software revenue streams from telemetry data architectures specified in Kalgoorlie and Abitibi procurement tenders. For New Entrants and Emerging Players: The price-point gap between premium automated platforms and economy pneumatic rigs creates white-space opportunity for electric-hydraulic hybrid architectures targeting ventilation-constrained brownfield expansions. Australia's Yilgarn Craton exploration contractors and Chile's Atacama copper corridors represent most penetrable segments, with go-to-market traction coming through leasing partnerships that absorb REACH-compliant hydraulic fluid containment costs through extended financing terms. For Investors and Strategic Acquirers: Re-rating potential sits with wireline equipment fabricators possessing modular subsystem expertise given exploration budget rotation toward underground targets in depleting surface discovery environments. Acquisition focus should target narrow-vein mechanization specialists with compact rig configurations and established certification pathways across multiple jurisdictions. The signal to watch is convergence in automated drilling interoperability standards, which would trigger consolidation premiums for control system vendors with cross-platform software capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Components | Secures captive supply of high-pressure valves and pumps against manufacturing bottlenecks extending rig delivery timelines. |
| Automated Platform Certification Investment | Preempts fragmented procurement decisions across Canada's provincial regulators and Australia's TGA-aligned safety authorities. |
| Electric-Hydraulic Hybrid Architecture Development | Reduces ventilation infrastructure burdens in Chile's Atacama copper corridors and Canada's Sudbury Basin brownfield expansions. |
| Telemetry Data Ownership Models | Enables predictive maintenance revenue streams from Sudbury nickel producers establishing captive rebuild facilities. |
| Leasing Partnership Expansion | Absorbs REACH-compliant hydraulic fluid containment costs for Western Australian contractors facing extended financing terms. |
Research Approach
Independent corroboration across drill rig OEM technical specifications, mining operator procurement tender documentation, and regulatory filing databases underwrites the qualitative findings in this analysis. Primary interviews with maintenance directors at deep-level gold and copper operations, aftermarket service heads at platinum belt contractors, and OEM procurement teams at integrated technology providers combined with secondary validation from ISO 18758 machinery standards, TGA workplace safety guidance documents, and Department of Mineral Resources and Energy disclosure codes. Bottom-up rig deployment tallies across Canada's Abitibi belt, Australia's Yilgarn Craton, and South Africa's Witwatersrand Basin triangulate against top-down exploration budget allocations from public mining house disclosures.
Historical reference periods spanning pre-automation fleet compositions through current electric-hydraulic hybrid pilot programs anchor the forecast window to observable technology substitution patterns. Segmentation dimensions modeled include rig architecture by product type, power source technology, application lifecycle stage, and end-user financing structure, with regional regulatory cluster effects captured through jurisdiction-specific compliance cost overlays. CAGRs derive from equipment replacement cycle compression rates observed as ground stability mandates harden, with forecast inputs incorporating wireline core barrel standardization trends and exploration budget rotation toward underground targets.
Underlying measurement precision varies by segment; automated drilling platforms and electric-hydraulic hybrids carry tighter precision than legacy pneumatic units given concentrated procurement documentation from major mining houses. Forecasts reflect assumptions regarding regulatory alignment timelines across Canada's provincial regulators, Australia's state-based authorities, and South Africa's national department, with revision triggers including interoperability standard convergence, high-pressure component supply normalization, and exploration budget volatility in base metal price cycles. A small set of regulatory harmonization signals, component supply lead time inflections, and major mining house fleet standardization decisions warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Crawler Drilling Machine Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Logging Cable Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Underground Mining Automation Market
Mining Equipment
Drilling Rigs Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Mine Hoisting Systems Market
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Borehole Equipment Market
Mining Equipment
North America Underground Mining Equipment Market