
 Asia-Pacific Drill Pipe Market | 2026-2036
Asia-Pacific Drill Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Drill Pipe Market Insights
Market Context with Strategic Players
Australia's capacity build-out in Newcastle and Perth steel fabrication corridors is reshaping regional supply availability for premium drill pipe grades. Hilong Group of Companies leverages integrated threading and heat-treatment facilities to serve CNPC and Sinopec contracts across the Sichuan shale belt. NOV Inc. anchors its Asia-Pacific position through Singapore distribution hubs that stock API-specification heavyweights for offshore rig operators. Tenaris S.A. competes on alloy steel product lines certified to NACE MR0175 sour service standards, which dominate Australian Cooper Basin workovers.
Technical Definition and Structural Segments
Asia-Pacific drill pipe comprises hollow steel tubulars typically manufactured from AISI 4145H modified alloy steel with API-specified wall thicknesses of 0.362 to 0.688 inches, engineered to transmit rotational torque and convey drilling fluid in vertical and directional boreholes. Premium drill pipe commands margin concentration due to hardbanding overlays and internal plastic coating requirements that extend fatigue life in corrosive formations. Standard drill pipe occupies volume leadership across India's onshore Cambay Basin campaigns where cost sensitivity overrides specification premiums. Offshore drilling applications drive fastest-growing demand as subsea tiebacks in Malaysia and Vietnam require sour-service-qualified heavyweight drill pipe with enhanced tensile ratings above 135 ksi yield strength.
Regulatory Frame and Forward-Looking Close
China's SAMR enforces GB/T 19830 national standards that align with API 5DP specifications, while Australia's NOPSEMA mandates well integrity management systems that prescribe material traceability for subsea drill strings. Japan's METI administers JIS G 3441 alloy steel tube standards that constrain import eligibility for Indonesian and Thai rig contractors. India's CEA technical regulations on offshore electrical safety indirectly shape drill pipe inspection intervals through integrated rig certification requirements. Stakeholders must monitor how Australia's proposed domestic content thresholds for offshore decommissioning projects redirect procurement toward locally threaded premium grades rather than imported finished goods.
Market Dynamics
China's MIIT mandates on high-strength alloy standards are forcing domestic mills to abandon legacy production lines and retool for API-compliant premium grades, compressing supply timelines for regional offshore operators.
Growth Catalysts
- Deepwater exploration mandates:Southeast Asian offshore operators in Malaysia and Vietnam are expanding procurement for sour-service-qualified heavyweight drill pipe to support subsea tieback projects.
- GB/T 19830 alignment:China's SAMR enforcement of national standards matching API 5DP specifications is accelerating domestic certification velocity and reducing import dependency for Sichuan shale operators.
- Coal seam gas basins:Australia's onshore drilling intensity in Newcastle and Perth corridors is sustaining volume demand for standard-grade tubulars with established supply chains.
Market Restraints
- Alloy steel input volatility:AISI 4145H modified alloy pricing fluctuations constrain margin predictability for mills serving premium hardbanding overlay specifications.
- Supply concentration risk:Heavyweight drill pipe production clusters in China's Sichuan and Hebei provinces create geographic vulnerability for Australian and Indian rig contractors.
- JIS G 3441 import barriers:Japan's METI administration of alloy steel tube standards restricts Indonesian and Thai contractors from accessing lower-cost regional supply.
Strategic Opportunities
- India KG-D offshore blocks:Underpenetrated deepwater acreage off Andhra Pradesh offers white-space demand for 135 ksi yield-strength premium connections with enhanced fatigue ratings.
- Australia domestic content thresholds:Proposed NOPSEMA-aligned local sourcing rules for decommissioning projects redirect procurement toward Perth-threaded premium grades versus imported finished goods.
- Internal plastic coating convergence:Fusion-bonded epoxy and phenolic liner technologies are extending corrosion resistance in Cooper Basin sour service, differentiating regional fabricators.
Industry Challenges
- API 5DP recertification timelines:Extended audit cycles for heat-treatment and threading facilities delay contract eligibility for mid-tier mills upgrading from standard to premium grades.
- Hardbanding technician scarcity:Specialized welding expertise for tungsten carbide matrix overlays remains concentrated among Singapore and Perth service centers, constraining regional capacity scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Drill Pipe Market |
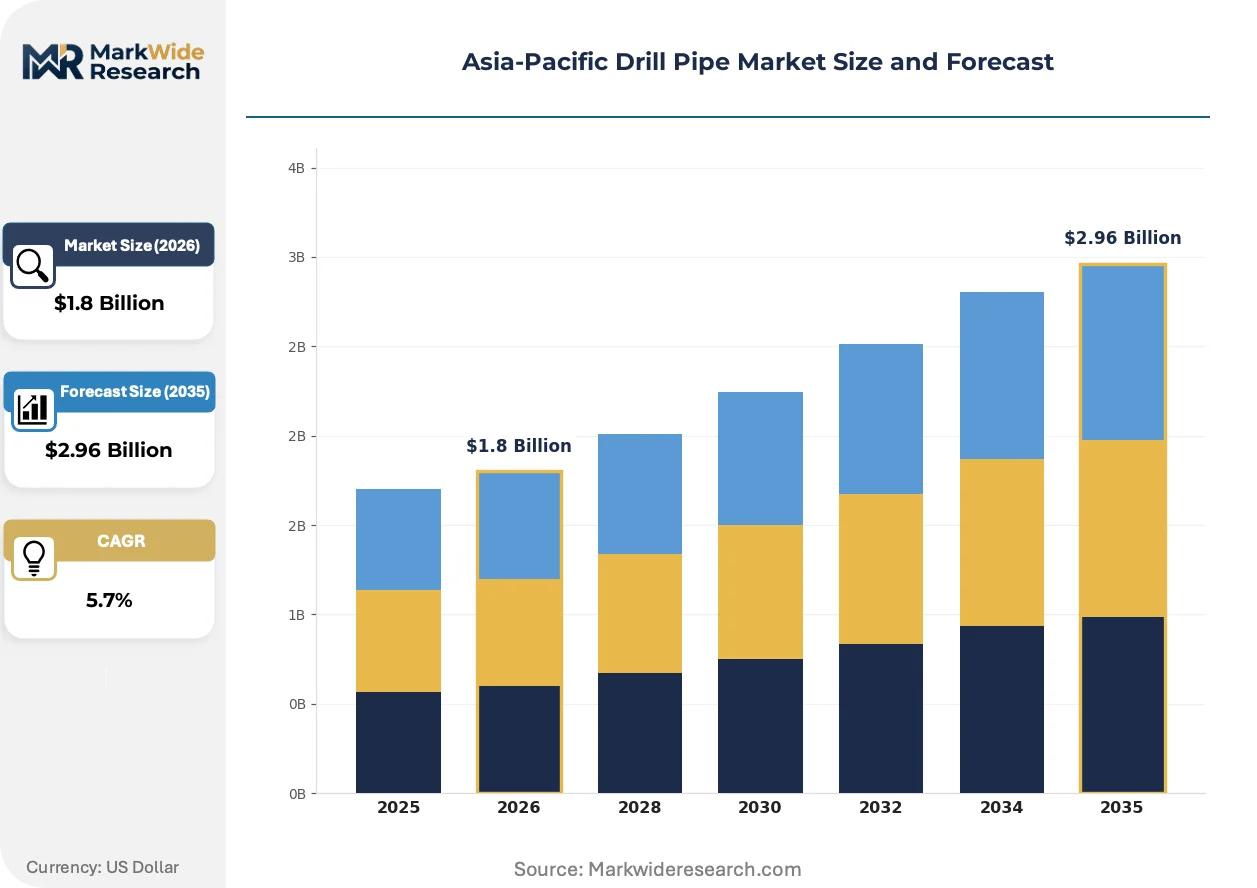
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavyweight Drill Pipe, Standard Drill Pipe, Premium Drill Pipe, Drill Collars Material: Carbon Steel, Alloy Steel, Stainless Steel, Composite Materials End User: Oil & Gas Companies, Mining Corporations, Geothermal Energy Providers, Offshore Operators Application: Onshore Drilling, Offshore Drilling, Exploratory Drilling, Directional Drilling |
| Companies Covered | Hilong Group of Companies, Drill Pipes International LLC, NOV Inc., Oil Country Tubular Ltd., Tenaris S.A., TMK Group, Vallourec S.A., Tejas Tubular Products, Inc., Texas Steel Conversion, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Drill Pipe Market Trends and Innovations
Digital thread inspection and predictive fatigue modeling are compressing traditional asset management cycles across Asia-Pacific offshore fleets, forcing recalibration of procurement specifications and maintenance protocols.
Advanced ultrasonic testing combined with machine-learning defect classification is virtualizing conventional visual and magnetic particle inspection workflows. Offshore rig operators in Malaysia and Vietnam are adopting these systems at accelerated cadence to meet NOPSEMA-aligned well integrity mandates. The technology is virtualizing legacy third-party inspection contracts and shifting liability retention toward equipment suppliers.
Japan's METI has tightened JIS G 3441 alloy steel tube standards with enhanced traceability requirements for seamless tubulars used in pressure-critical applications. The regulation forces Indonesian and Thai rig contractors to source exclusively from certified Japanese or premium-grade Chinese mills, compressing available supplier pools. Heavyweight drill pipe categories face the steepest compliance cost escalation as material certification documentation expands.
Integrated drill string management contracts are displacing discrete equipment procurement across Australian Cooper Basin workovers. Contractors now bundle premium pipe supply, inspection, and replacement scheduling under single-source agreements with threading facilities in Perth. This concentration is most visible in sour-service environments where NACE MR0175 compliance liability shifts from operator to supplier.
Asia-Pacific Drill Pipe Market Segmentation
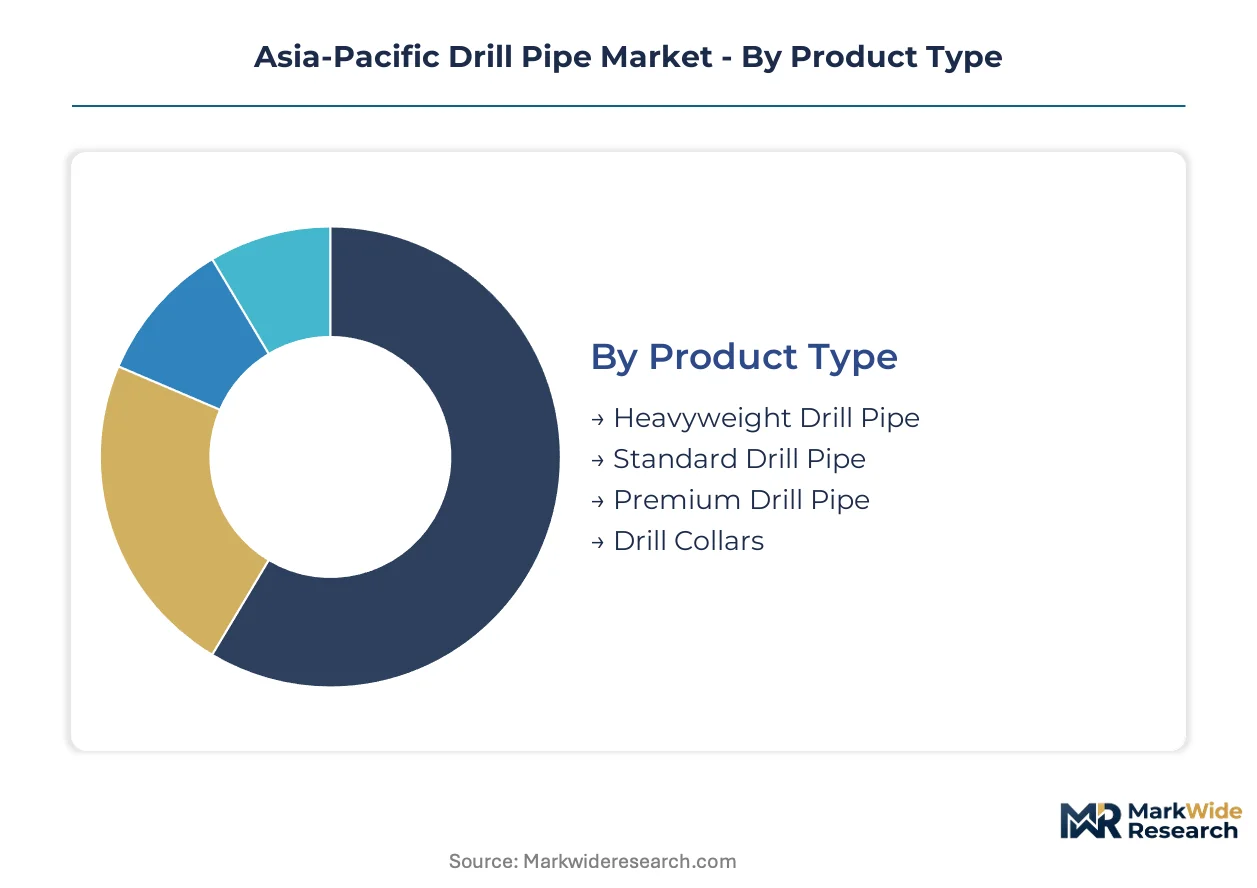
Drill pipe procurement in the Asia-Pacific region fragments across four distinct dimensions. Specification premiums, material certification requirements, and end-use liability profiles create divergent margin structures that reshape supplier positioning across Australia's Cooper Basin, China's Sichuan shale belt, and Southeast Asian offshore blocks.
Product Type:
Cost tier stratification separates commodity tubulars from engineered solutions with hardbanding overlays and fatigue-rated connections.
- Premium Drill Pipe:Manufactured from AISI 4145H modified alloy steel with internal plastic coatings and tungsten carbide hardbanding. Demand concentrates in Malaysia and Vietnam subsea tieback projects where sour-service qualification under NACE MR0175 is mandatory.
- Heavyweight Drill Pipe:Engineered with wall thicknesses exceeding 0.500 inches and yield strengths above 135 ksi. Australian offshore operators in the Browse Basin specify these for extended-reach horizontal sections where compressive loading exceeds standard ratings.
- Standard Drill Pipe:API 5DP-compliant tubulars serving India's Cambay Basin onshore campaigns where procurement teams prioritize unit economics over specification premiums.
- Drill Collars:Solid steel bars with boreholes for instrumentation, deployed in China's Sichuan shale plays to provide bottom-hole assembly weight without buckling risk.
Standard drill pipe holds installed capacity across Indian and Australian onshore fleets. Premium grades are rotating up the share rankings as Southeast Asian deepwater campaigns accelerate.
Material:
Application severity and corrosive exposure dictate alloy selection, with China's MIIT mandates forcing domestic mills toward higher-specification metallurgy.
- Alloy Steel:AISI 4145H modified grades dominate premium connections for sour-service environments. Tenaris and Hilong Group facilities in China and Singapore certify these to API 5DP and GB/T 19830 dual standards for regional offshore contractors.
- Carbon Steel:Lower-cost tubulars serve Australia's Newcastle coal seam gas corridor where formation chemistry permits reduced corrosion resistance. Perth fabricators thread these for rapid-turnaround onshore campaigns.
- Stainless Steel:Duplex and super-duplex grades address chloride stress cracking in Vietnam's Ca Mau offshore province. Japanese mills under METI JIS G 3441 standards supply limited volumes due to import eligibility constraints.
- Composite Materials:Experimental fiberglass and carbon fiber tubulars tested in Japan's geothermal sector for non-magnetic directional drilling applications.
Carbon steel maintains volume leadership in Australian standard-grade procurement. Alloy steel is gaining share fastest as China's domestic certification velocity accelerates.
End User:
Customer type determines contract structure, with integrated operators favoring bundled supply agreements and independents pursuing discrete procurement.
- Offshore Operators:Malaysian and Vietnamese rig contractors under Petronas and PetroVietnam specify sour-service-qualified heavyweight strings with full material traceability. These contracts bundle inspection, maintenance, and replacement scheduling under single-source agreements.
- Oil & Gas Companies:CNPC and Sinopec in China's Sichuan shale belt drive demand for premium connections with enhanced fatigue ratings. Domestic mills compete on GB/T 19830 compliance velocity.
- Mining Corporations:Australian iron ore and coal producers in Western Australia and Queensland specify standard drill pipe for blast-hole drilling with shorter asset lifecycles.
- Geothermal Energy Providers:Indonesian and Philippine developers source corrosion-resistant alloys for high-temperature, high-salinity formation conditions.
Oil and gas companies hold installed procurement infrastructure. Offshore operators are climbing the fastest as subsea tieback project pipelines expand.
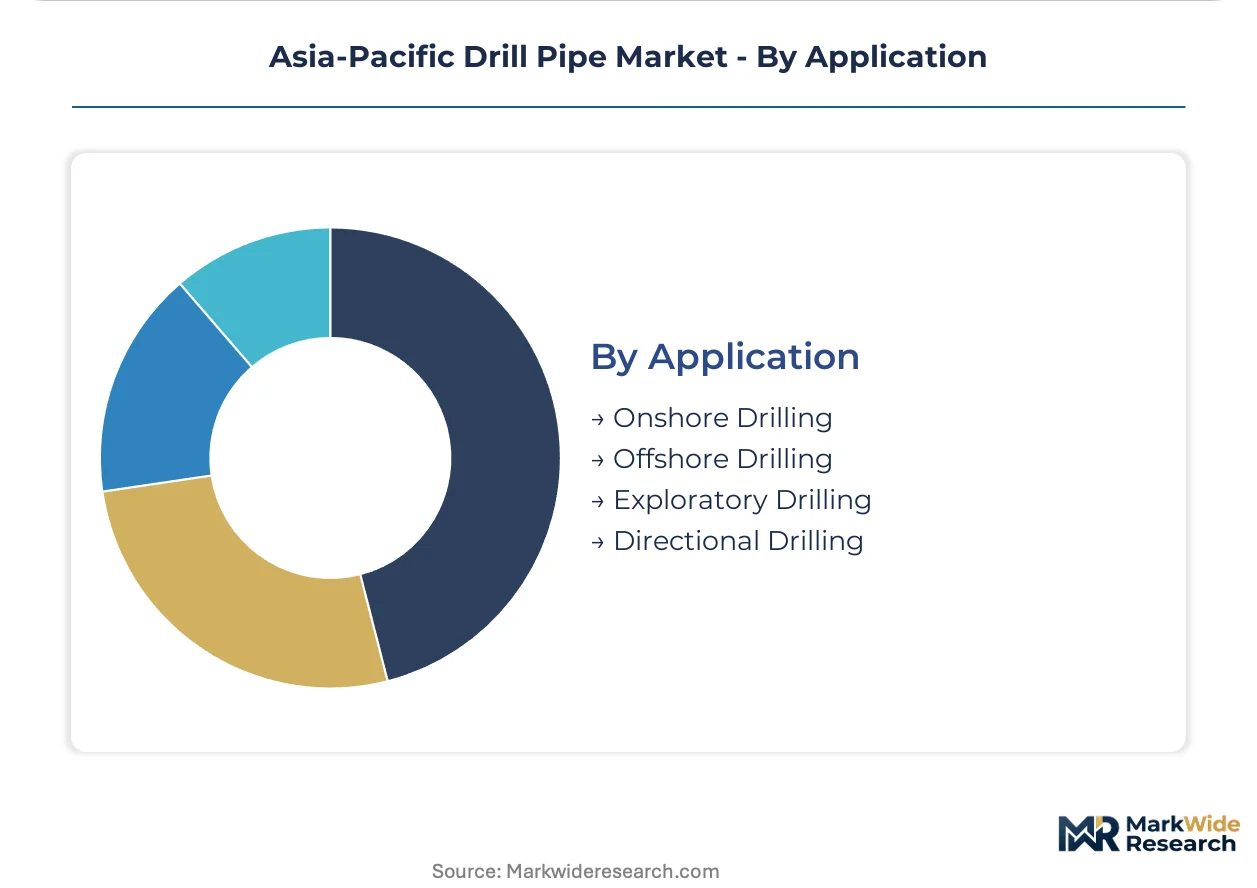
Application:
Geography and well architecture combine to determine specification intensity, with offshore environments imposing the steepest technical barriers.
- Offshore Drilling:Subsea tiebacks in Malaysia's Sarawak basin and Vietnam's Nam Con Son basin require heavyweight drill pipe with 135 ksi yield strength and premium threaded connections. NOPSEMA-aligned well integrity mandates extend to Australian offshore operations.
- Onshore Drilling:Australia's Perth and Newcastle corridors sustain volume demand for standard-grade tubulars in coal seam gas development. Cost sensitivity overrides hardbanding specifications in these campaigns.
- Directional Drilling:Extended-reach horizontal sections in China's Sichuan shale plays demand premium pipe with enhanced torque capacity and fatigue resistance.
- Exploratory Drilling:Wildcat campaigns in India's KG-D offshore blocks and frontier Indonesian acreage specify premium grades for uncertain formation conditions.
Onshore drilling retains the largest installed base of standard-grade inventory. Offshore drilling is expanding most quickly as Southeast Asian deepwater exploration intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Sichuan and Hebei provinces concentrate the bulk of heavyweight drill pipe fabrication capacity, creating geographic chokepoints that Australian and Indian rig contractors must navigate through Singapore distribution nodes.
China
Sichuan shale operators under CNPC and Sinopec drive premium connection demand with enhanced fatigue ratings. MIIT mandates on high-strength alloy standards force domestic mills to abandon legacy lines and retool for API-compliant grades. Hebei and Sichuan fabrication clusters now certify dual GB/T 19830 and API 5DP specifications for regional offshore contractors.
Australia
Coal seam gas development in Newcastle and Perth corridors sustains volume demand for standard-grade tubulars with rapid-turnaround threading. NOPSEMA well integrity mandates extend material traceability requirements to subsea drill strings. Perth-based fabricators are capturing decommissioning procurement through proposed domestic content thresholds.
India
KG-D offshore blocks off Andhra Pradesh generate white-space demand for 135 ksi yield-strength premium connections. CEA technical regulations on offshore electrical safety shape drill pipe inspection intervals through integrated rig certification. Cambay Basin onshore campaigns prioritize unit economics over specification premiums.
Japan
METI administration of JIS G 3441 alloy steel tube standards constrains import eligibility for Indonesian and Thai rig contractors. Enhanced traceability requirements for seamless tubulars pressure-certify exclusively through Japanese or premium-grade Chinese mills. Domestic mills supply limited duplex and super-duplex volumes for chloride stress cracking applications.
Vietnam
Nam Con Son basin subsea tiebacks require sour-service-qualified heavyweight strings with full material traceability. PetroVietnam contractors bundle inspection, maintenance, and replacement scheduling under single-source agreements. Ca Mau offshore province drives corrosion-resistant alloy demand for high-salinity formation conditions.
Asia-Pacific Drill Pipe Market Competitive Landscape
Integrated threading specialists and scale-driven distributors split the market between specification-intensive offshore contracts and volume-driven onshore campaigns. The vendor base organizes around three strategic archetypes: domestic Chinese mills with GB/T 19830 certification velocity, Singapore-based distribution hubs stocking API heavyweights, and Australian threading facilities capturing decommissioning procurement. Capacity expansion and strategic partnerships dominate competitive moves as mills upgrade heat-treatment lines and rig contractors consolidate inspection contracts.
Among Asia-Pacific-based fabricators, Hilong Group of Companies represents the domestic Chinese mill archetype with integrated threading and heat-treatment positioning. NOV Inc. anchors the distribution-hub model through Singapore stocking facilities. Tenaris S.A. occupies the premium-tier specialist position with NACE MR0175 sour service certification. These three exemplify how regional players map to divergent contract structures across Southeast Asian offshore blocks and Australian onshore basins.
| Leading Market Players |
|---|
| Hilong Group of Companies |
| Drill Pipes International LLC |
| NOV Inc. |
| Oil Country Tubular Ltd. |
| Tenaris S.A. |
| TMK Group |
| Vallourec S.A. |
| Tejas Tubular Products, Inc. |
| Texas Steel Conversion, Inc. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on China's Hebei and Sichuan fabrication clusters determines both pricing tier spreads and supply chain shape across Asia-Pacific drill pipe procurement. MIIT-mandated alloy upgrades and SAMR enforcement of GB/T 19830 standards compress margin buffers for regional offshore operators while redirecting procurement flows through Singapore distribution nodes.
Pricing Analysis
China's SAMR enforcement of GB/T 19830 national standards dictates the pricing tier structure across premium, standard, and economy levels. Certification velocity under dual API 5DP and domestic standards creates price differentiation between Hebei-milled premium grades and Perth-threaded standard tubulars. Cost compression in standard-grade procurement intensifies as Indian Cambay Basin operators prioritize unit economics over hardbanding specifications. Offshore contractors under Petronas and PetroVietnam exhibit least price sensitivity due to bundled inspection and replacement scheduling.
Supply Chain Analysis
Hebei and Sichuan province mills hold dominant contract-manufacturing capacity for heavyweight drill pipe serving Southeast Asian offshore blocks. Raw material feeds draw from AISI 4145H modified alloy suppliers and tungsten carbide hardbanding overlay specialists concentrated in Singapore and Perth service centers. Geographic concentration risk in China's fabrication corridors creates single-source vulnerability for Australian and Indian rig contractors. Distribution runs through Singapore stocking hubs that buffer API-specification inventory for Malaysian and Vietnamese subsea tieback projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital thread inspection and predictive fatigue modeling constitute a technological inflection that compresses asset management cycles and redirects procurement specifications toward integrated supplier contracts. This disruption favors threading specialists with captive inspection capabilities over discrete equipment distributors.
For Market Incumbents: Entrench sour-service certification leadership by upgrading heat-treatment lines for NACE MR0175 compliance velocity. Add threading capacity in Perth to capture Australia's proposed domestic content thresholds for decommissioning procurement. Hardbanding technician scarcity at Singapore service centers threatens margin capture for mills without captive welding expertise. For New Entrants and Emerging Players: Establish a beachhead in India's KG-D offshore blocks where 135 ksi yield-strength premium connections face underpenetrated demand. Target corrosion-resistant alloy supply for Vietnam's Ca Mau high-salinity formations. Partner with Indonesian geothermal developers to pilot non-magnetic composite tubulars outside JIS G 3441 import constraints. For Investors and Strategic Acquirers: The market sits at a certification-upgrade phase that favors vertically integrated threading specialists with GB/T 19830 and API 5DP dual compliance. Long-term viability rests on mills that control heat-treatment and hardbanding rather than distributors holding inventory risk. Monitor MIIT enforcement timelines as inflection indicator for domestic Chinese mill consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Line Upgrade | GB/T 19830 certification velocity unlocks CNPC and Sinopec contract eligibility. |
| Perth Threading Facility Expansion | NOPSEMA-aligned domestic content thresholds redirect decommissioning procurement. |
| Hardbanding Technician Training Program | Tungsten carbide matrix overlay capacity captures premium connection margins. |
| Integrated Inspection Contract Bundling | Single-source agreements shift NACE MR0175 liability from operator to supplier. |
| Singapore Distribution Hub Strengthening | API-specification heavyweight inventory buffers Southeast Asian offshore demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across drilling contractors, mill procurement directors, and threading facility managers. Secondary validation drew from SAMR regulatory filings, NOPSEMA well integrity directives, API specification documentation, and customs trade data for alloy steel tubulars. Bottom-up rig fleet inventory analysis and top-down regional exploration capex triangulation anchored volume estimates.
Calibration across historical procurement patterns and announced exploration campaign pipelines shaped projections over the analysis window. Segmentation modeling captured product type, material grade, end-user category, and application severity dimensions. CAGRs derived from rig count expansion rates and replacement cycle compression in sour-service environments. Forecast inputs included MIIT mandate implementation timelines and PetroVietnam subsea tieback project pipelines.
Stress conditions across alloy input pricing volatility, JIS G 3441 import restriction severity, and Australian domestic content threshold adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification audit cycle durations and hardbanding capacity scaling. Quarterly review of SAMR enforcement actions and NOPSEMA procurement rulemaking is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Geology and Mine Planning Solution Market
Mining Equipment
Mining Shovel Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Latin America Mining Equipment Market
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Drilling Stabilizers Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Global Dozers Market
Mining Equipment
Mining Drill Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Rock-Socketed Drilling Rig Market