
 Drilling Rigs Market | 2026-2036
Drilling Rigs Market Size, Share, and Industry Trends Forecast 2026-2036
Drilling Rigs Market Analysis
The EU Green Deal is realigning offshore rig specifications across European basins, forcing upgrades to low-emission power systems and methane monitoring packages. Transocean Ltd. dominates ultra-deepwater drillship deployment through its high-specification fleet positioned in the Gulf of Mexico and West Africa. Schlumberger Limited leverages integrated drilling services to anchor long-term contracts with national oil companies prioritizing emissions transparency. Nabors Industries Ltd. specializes in land rig automation, competing on drilling efficiency metrics that reduce per-well carbon intensity.
Drilling rigs are steel structures engineered to rotate drill strings, circulate drilling fluid at pressures exceeding 10,000 psi, and withstand torsional loads from formations thousands of meters below surface; their purpose is to create boreholes for hydrocarbon extraction, mineral recovery, or subsurface access. Offshore rigs command premium day rates due to technical complexity and limited shipyard capacity, while land rigs benefit from standardization and faster mobilization cycles. Directional drilling technology leads growth as operators target complex shale geometries and sub-salt reservoirs, whereas cable tool systems occupy a shrinking niche in shallow water well applications.
The US EPA enforces New Source Performance Standards for methane emissions from offshore and onshore drilling, compelling rig operators to retrofit pneumatic controllers and flare recovery systems. The EU F-Gas Regulation restricts hydrofluorocarbon use in rig HVAC and refrigeration, shaping equipment procurement for North Sea contractors. China's MEE implements dual carbon goals through provincial emissions caps that affect rig fleet deployment in the Bohai Bay and South China Sea. Stakeholders must monitor how diverging national methane protocols fragment equipment certification requirements and alter fleet redeployment economics between basins.
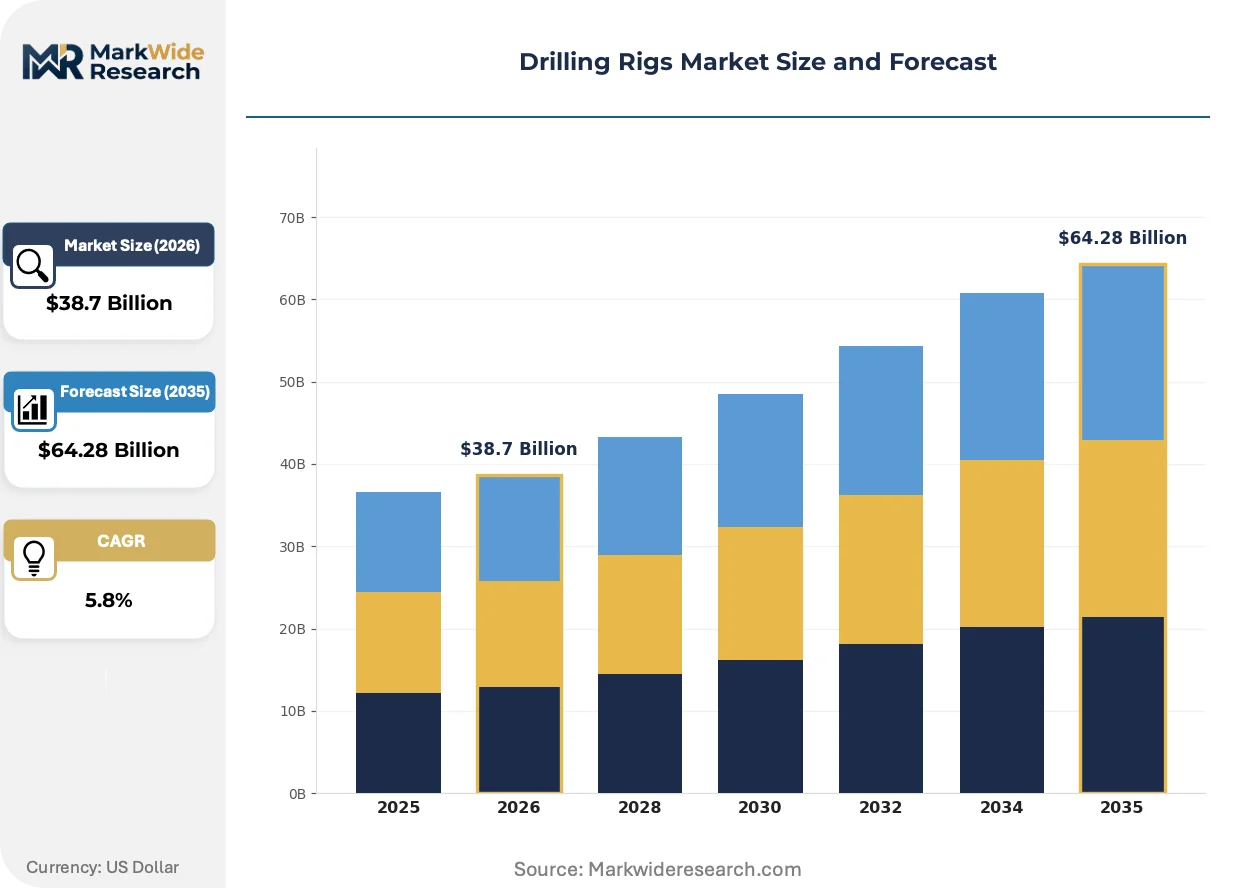
Market Dynamics
The US Gulf Coast concentration of deepwater lease activity and LNG export terminal construction is pulling high-specification jack-up and semi-submersible rigs away from other basins, tightening global fleet availability and compressing day-rate spreads between premium and standard assets.
Growth Catalysts
- Deepwater lease rounds:The US Bureau of Ocean Energy Management's scheduled Gulf of Mexico auctions are locking in multi-year drilling commitments that absorb floating rig capacity for extended campaigns.
- EU Green Deal methane frameworks:Offshore operators in the North Sea and Norwegian Continental Shelf face mandatory emissions monitoring, creating retrofit demand for low-emission power systems and flare recovery packages.
- Directional drilling systems:Advances in rotary steerable technology enable complex well geometries in sub-salt reservoirs, expanding recoverable reserves in Brazil's pre-salt basins and West African deepwater blocks.
Market Restraints
- Shipyard capacity bottlenecks:South Korean and Singaporean yards specializing in offshore vessel construction face order backlogs extending eighteen to twenty-four months, constraining newbuild rig delivery.
- Specialized steel alloy costs:High-strength quenched and tempered plate grades required for jack-up leg construction track volatile nickel and molybdenum commodity prices, pressuring rig fabrication economics.
- F-Gas Regulation compliance:The EU's phasedown of hydrofluorocarbons forces North Sea contractors to replace HVAC and refrigeration systems ahead of mechanical end-of-life, accelerating capital obsolescence.
Strategic Opportunities
- Automation retrofit packages:Land rig operators in the Permian Basin and Eagle Ford are integrating robotic pipe handling and automated drilling control systems to reduce crew counts and improve consistency.
- Methane monitoring as a service:Continuous emissions detection systems bundled with rig contracts create recurring revenue streams for equipment providers serving US and EU regulatory jurisdictions.
- Decommissioning rig redeployment:Late-life North Sea assets are transferring to Southeast Asian and West African markets where lower day-rate thresholds match mature field economics.
Industry Challenges
- Subsea electronics technician scarcity:The specialized skill set combining hydraulic systems, ROV operations, and pressure-rated electrical engineering commands premium wages and limits fleet expansion velocity.
- Classification society recertification timelines:ABS, DNV, and Lloyd's Register inspection backlogs for aging jack-up rigs extend drydock periods, compressing revenue-generating operating days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drilling Rigs Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Land Rigs, Offshore Rigs, Mobile Rigs, Modular Rigs End User: Oil & Gas Companies, Mining Industries, Construction Firms, Geothermal Operators Technology: Rotary Drilling, Directional Drilling, Undercutting, Cable Tool Application: Exploration, Production, Water Wells, Environmental |
| Companies Covered | Schlumberger Limited, Transocean Ltd., Nabors Industries Ltd., Halliburton Company, Baker Hughes Company, Valaris Limited, Seadrill Limited, Helmerich & Payne Inc., China Oilfield Services Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drilling Rigs Market Emerging Trajectories
Digital twin systems and autonomous drilling algorithms are compressing the feedback loop between subsurface geology and surface operations, enabling real-time trajectory adjustments that reduce non-productive time and improve target precision.
Hybrid power architectures combining battery storage with conventional diesel-electric generators are decentralizing energy management on offshore platforms. Transocean and Seadrill are retrofitting select drillships with megawatt-scale lithium-ion banks to optimize load balancing and reduce generator runtime. This shift is decentralizing maintenance schedules and creating new vendor relationships with battery system integrators previously outside maritime supply chains.
The EU F-Gas Regulation's phasedown schedule is tightening equipment procurement specifications for North Sea contractors. HVAC and refrigeration system replacements must now use natural refrigerants or ultra-low global warming potential alternatives, eliminating standard hydrofluorocarbon options from approved vendor lists. Jack-up rigs operating under UK and Norwegian flags face accelerated replacement cycles for climate control equipment, with compliance deadlines compressing capital planning horizons.
Integrated service contracts are displacing discrete equipment procurement as national oil companies prioritize emissions transparency and performance guarantees. Saudi Aramco and ADNOC now bundle drilling services, real-time data analytics, and carbon accounting into single-source agreements that penalize methane leakage and reward drilling efficiency metrics. This restructuring concentrates vendor selection authority with integrated service providers and marginalizes standalone rig operators lacking comprehensive emissions monitoring capabilities.
Drilling Rigs Market Segmentation
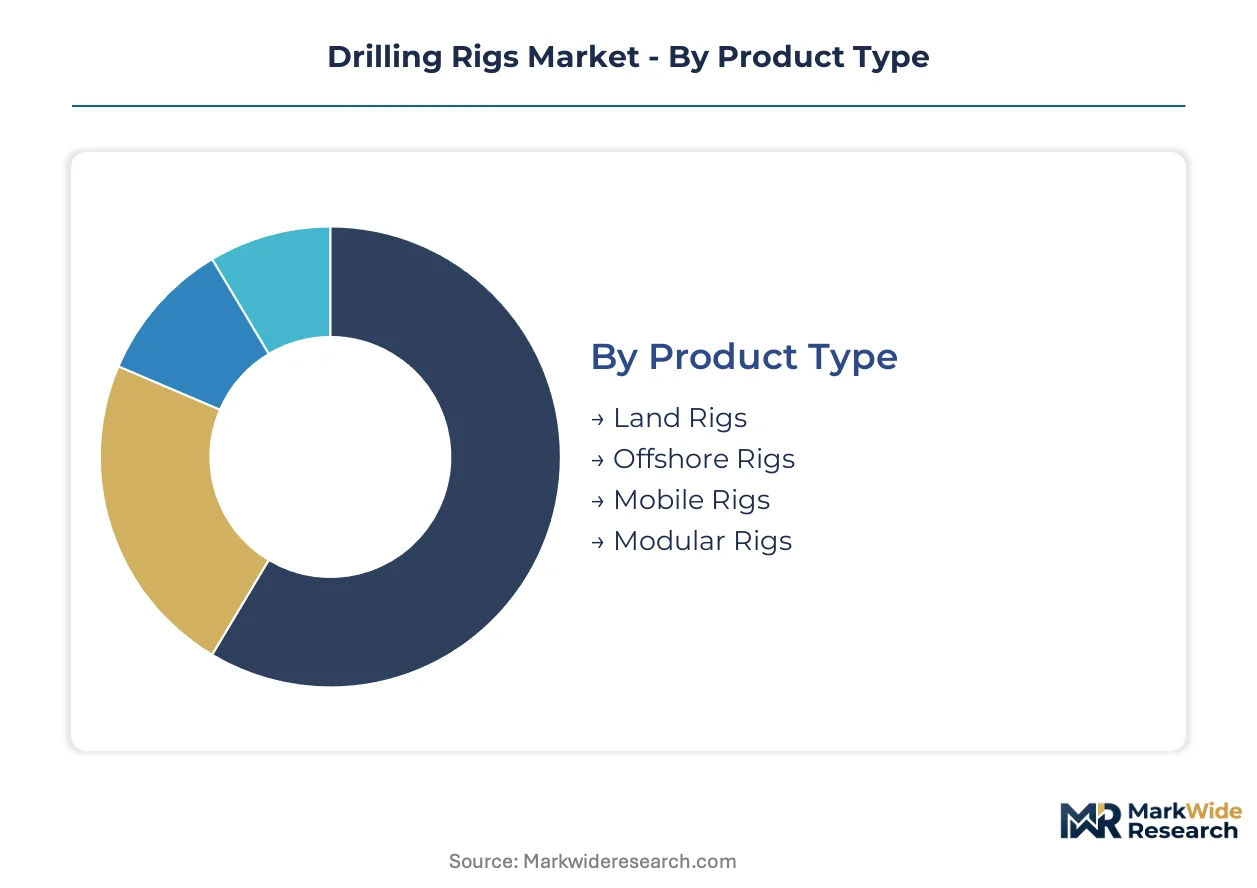
Segmentation in the Drilling Rigs Market reveals how certification requirements, operational complexity, and basin-specific economics fragment procurement patterns across operator types. Understanding these divisions exposes where capital concentrates and which technology packages command premium pricing.
Product Type:
Offshore rigs face the heaviest certification burden through ABS, DNV, and Lloyd's Register standards for structural integrity and dynamic positioning, while land rigs navigate simpler API specifications and faster state-level permitting.
- Land Rigs:Steel-mast structures rated for 1,000 to 3,000 horsepower with modular skidding systems enable multi-well pad drilling. Demand concentrates in the Permian Basin and Eagle Ford where pad development economics favor rapid rig mobilization between well slots.
- Offshore Rigs:Jack-up units with rack-and-chord leg systems and semi-submersible hulls withstand North Sea wave spectra and Gulf of Mexico hurricane loading. Norwegian Continental Shelf operators require DNV-ST-C203 fatigue assessments that extend design verification timelines.
- Mobile Rigs:Truck-mounted and self-propelled units serve frontier exploration in remote basins where infrastructure is absent.
- Modular Rigs:Component-based designs split into transportable sub-assemblies for helicopter or ice-road access in Arctic frontiers.
Land rigs sit at the top of the volume ranking, with offshore rigs climbing the fastest as deepwater lease commitments absorb available fleet capacity.
End User:
Cost tier segmentation separates integrated supermajors with bundled service contracting power from independent operators seeking day-rate flexibility.
- Oil & Gas Companies:Supermajors and national oil companies anchor long-term rig demand through multi-year drilling commitments. Saudi Aramco and ADNOC now bundle emissions monitoring into integrated service contracts that penalize methane leakage.
- Mining Industries:Blast hole and exploration drilling for copper, iron ore, and rare earth extraction employs modified land rig configurations with larger diameter capabilities.
- Construction Firms:Foundation piling and geotechnical investigation rigs operate on shorter mobilization cycles with lower specification thresholds.
- Geothermal Operators:Binary and flash steam projects in Iceland and Kenya deploy adapted oilfield rigs for high-temperature hard rock penetration.
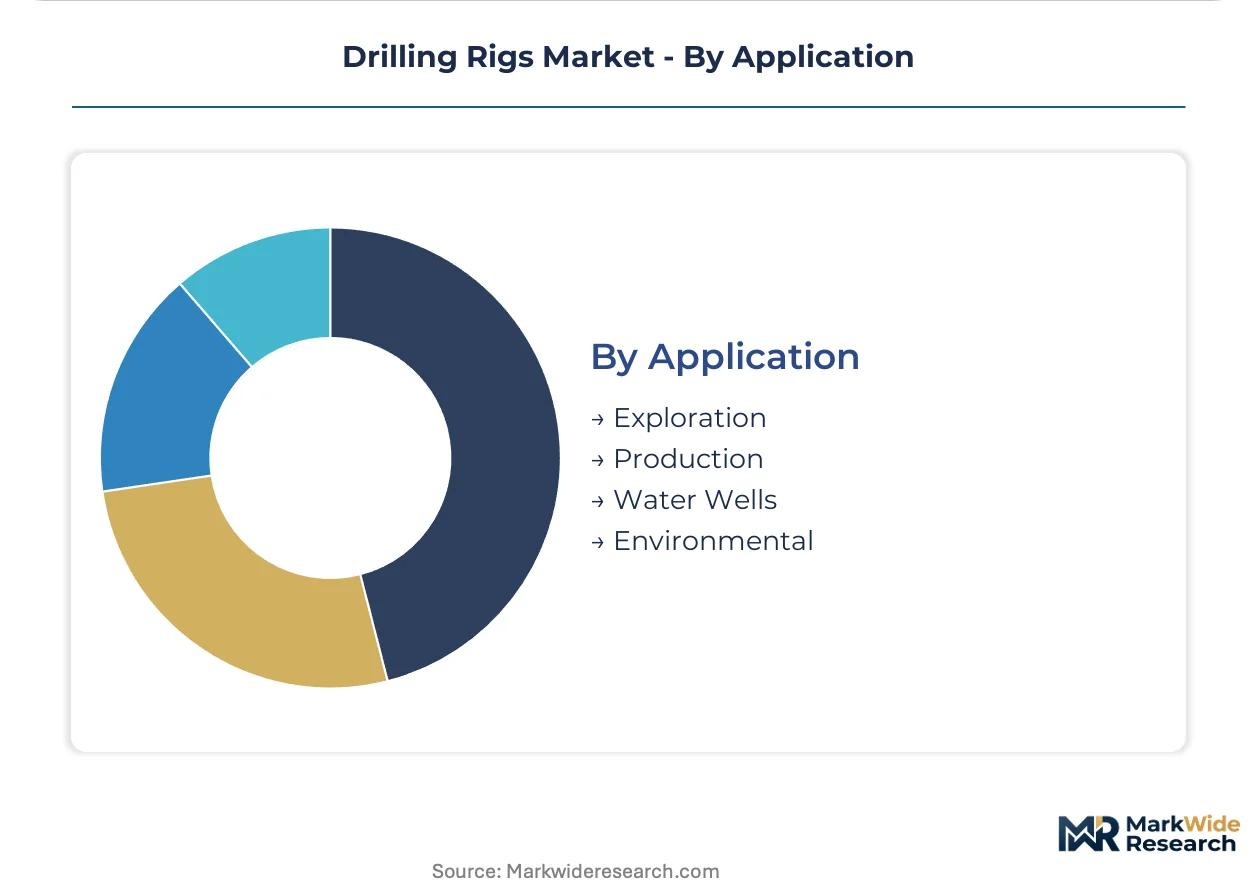
Oil and gas companies dominate capital deployment, with geothermal operators expanding most quickly as baseload renewable targets accelerate drilling programs.
Technology:
Application complexity determines which drilling systems justify the capital intensity of automated control packages and real-time telemetry.
- Rotary Drilling:Conventional rotary table or top-drive systems rotate drill strings through torque ratings exceeding 50,000 foot-pounds. Standard configurations serve vertical well programs in conventional sandstone reservoirs where trajectory complexity is minimal.
- Directional Drilling:Rotary steerable systems and measurement-while-drilling telemetry enable complex well geometries in sub-salt reservoirs. Brazil's pre-salt basins and West African deepwater blocks absorb high-specification directional packages.
- Undercutting:Specialized slot recovery and sidetrack drilling technologies access bypassed pay zones in mature fields.
- Cable Tool:Percussion drilling with spudding beams persists in shallow water well applications where capital constraints exclude rotary alternatives.
Rotary drilling maintains the largest installed base, with directional drilling gaining share fastest as reservoir complexity escalates.
Application:
Customer maturity separates frontier exploration programs with high technical risk from production drilling with predictable repeatability.
- Exploration:Wildcat and appraisal drilling in unproven basins requires highest-specification rigs with redundant blowout preventer stacks. US Gulf of Mexico lease rounds commit operators to multi-year exploration campaigns that absorb floating rig capacity.
- Production:Development drilling from established platforms and pads employs standardized rig configurations with optimized batch drilling sequences.
- Water Wells:Aquifer access and groundwater monitoring employs smaller truck-mounted rigs with simplified fluid systems.
- Environmental:Remediation, carbon sequestration monitoring, and site characterization drilling serves regulatory compliance and closure obligations.
Production drilling anchors steady demand, with environmental applications climbing fastest as carbon capture and site remediation obligations expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsea electronics technicians and specialized marine engineers cluster around North Sea oil hubs and Gulf of Mexico port cities, anchoring regional rig deployment patterns. Their geographic concentration shapes where high-specification jack-up and semi-submersible units concentrate for maintenance and crew rotation cycles.
United States
Deepwater lease rounds in the Gulf of Mexico absorb floating rig capacity through multi-year drilling commitments mandated by the Bureau of Ocean Energy Management. The EPA enforces New Source Performance Standards for methane emissions, compelling retrofit of pneumatic controllers and flare recovery systems. Houston anchors the world's densest concentration of offshore rig contractors and subsea engineering firms.
Norway
North Sea operators face mandatory emissions monitoring under EU Green Deal methane frameworks implemented through Norwegian national regulations. DNV-ST-C203 fatigue assessments extend design verification timelines for jack-up rigs operating on the Norwegian Continental Shelf. Stavanger hosts the primary engineering cluster for low-emission power system retrofits and flare recovery package integration.
Brazil
Pre-salt basin development programs drive demand for high-specification directional drilling packages capable of complex sub-salt trajectories. The national petroleum regulator mandates local content requirements for rig operations, shaping procurement patterns for Brazilian-flagged assets. Rio de Janeiro concentrates national oil company headquarters and subsea equipment integration yards serving Campos and Santos basin campaigns.
China
Provincial emissions caps under the MEE dual carbon goals constrain rig fleet deployment in Bohai Bay and South China Sea development zones. GB standards for offshore platform safety interface with international classification society rules for foreign-contracted rigs. Tianjin and Shenzhen anchor domestic rig construction capacity and subsea equipment manufacturing clusters.
Saudi Arabia
Long-term drilling commitments from national oil companies absorb premium jack-up and land rig capacity for multi-year field development programs. The national regulator integrates emissions transparency requirements into integrated service contracts that penalize methane leakage. Dhahran concentrates engineering resources for automated drilling control system deployment across onshore and offshore campaigns.
Drilling Rigs Market Vendor Landscape
Capital-heavy rig owners compete with asset-light drilling service integrators for contract margins and customer relationships. The market structures around three tiers: ultra-deepwater drillship operators commanding premium day rates, land rig automation specialists competing on efficiency metrics, and integrated service providers bundling equipment with real-time data analytics. Consolidation pressures favor scale players with balance sheet capacity for fleet renewal, while niche specialists defend position through basin-specific operational expertise and regulatory compliance capabilities.
Among asset-heavy drillship operators, Transocean Ltd. and Seadrill Limited occupy positions exemplifying the premium-tier fleet archetype, with units positioned for Gulf of Mexico and West African deepwater campaigns. Nabors Industries Ltd. represents the land rig automation specialist model, competing on drilling efficiency metrics that reduce per-well carbon intensity in Permian Basin and Eagle Ford operations. Schlumberger Limited anchors the integrated service provider archetype, bundling drilling services with emissions monitoring capabilities for national oil companies prioritizing methane transparency.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Transocean Ltd. |
| Nabors Industries Ltd. |
| Halliburton Company |
| Baker Hughes Company |
| Valaris Limited |
| Seadrill Limited |
| Helmerich & Payne Inc. |
| China Oilfield Services Ltd. |
| Others |
Supply Flow & Price Mechanics
High-strength quenched and tempered steel plate costs cascade from nickel and molybdenum commodity markets through jack-up leg fabrication economics, concentrating pricing power with South Korean and Singaporean yards that command eighteen-to-twenty-four-month delivery backlogs for offshore rig newbuilds.
Pricing Analysis
Bundled integrated service contracts are displacing unbundled day-rate pricing as national oil companies prioritize emissions transparency. Pricing stratifies across premium high-specification drillships, standard jack-up units, and economy land rigs based on certification tier and automation package depth. Cost compression in standard jack-up segments is intensifying because shipyard capacity constraints force buyers toward premium tier acceptance. Independent operators in the Permian Basin exhibit highest price sensitivity, while Saudi Aramco and ADNOC anchor least sensitive demand through multi-year bundled commitments.
Supply Chain Analysis
Regional distribution centers in Houston, Stavanger, and Singapore anchor hub-and-spoke patterns for subsea equipment and specialized rig components. Manufacturing concentrates in South Korea, Singapore, and China for hull construction and topside integration. The supply chain draws from high-grade steel alloys, lithium-ion battery systems, and low-emission power packages. Single-source vulnerability around subsea electronics technicians in North Sea and Gulf of Mexico clusters threatens fleet expansion velocity. Distribution runs through contractor-owned logistics networks and third-party marine equipment specialists serving basin-specific mobilization cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities emerge between EU Green Deal compliance costs in the North Sea and lower regulatory thresholds in Southeast Asian and West African markets where mature field economics absorb redeployed North Sea assets.
For Market Incumbents: Lock in long-term charter coverage with national oil companies before shipyard delivery slots tighten further. Secure backward integration into battery system integration partnerships to defend against emerging automation specialists. Prioritize DNV-ST-C203 certification investment for Norwegian Continental Shelf positioning.
For New Entrants and Emerging Players: The EU F-Gas Regulation in the North Sea opens a window for natural refrigerant HVAC retrofit specialists serving accelerated replacement cycles. Target decommissioning rig redeployment services for Southeast Asian markets. Pursue methane monitoring as a service bundling with regional contractors lacking in-house emissions capabilities.
For Investors and Strategic Acquirers: Consolidation pressure builds where balance sheet capacity for fleet renewal separates scale players from marginal standalone operators. Focus acquisition screening on land rig automation specialists with Permian Basin operational density. Watch jack-up drydock recertification timeline extensions as an inflection signal for available fleet compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Low-Emission Power Retrofit | Battery-diesel hybrid systems satisfy EU Green Deal methane frameworks for North Sea contractors. |
| Automated Drilling Control Integration | Robotic pipe handling reduces crew counts and carbon intensity in Permian Basin operations. |
| Methane Monitoring Service Bundling | Continuous emissions detection creates recurring revenue under EPA New Source Performance Standards. |
| Classification Society Pre-Certification | ABS and DNV pre-approval compresses drydock recertification timelines for aging jack-up assets. |
| Regional Distribution Hub Establishment | Singapore and Houston clusters optimize spare parts logistics for Gulf of Mexico and Asian campaigns. |
Methodological Framework
Multiple input streams — rig contractor operations executives, subsea engineering directors, national oil company procurement leads, and classification society surveyors — were reconciled against customs trade data, Bureau of Ocean Energy Management lease records, EPA enforcement disclosures, and fleet status databases. Bottom-up rig deployment counts across the US Gulf Coast, Norwegian Continental Shelf, and Brazilian pre-salt basins were triangulated with top-down capital expenditure estimates from integrated service provider filings.
Historical day-rate trajectories were cross-referenced against panel input from fleet managers and shipyard planners across the projection horizon. Segmentation modeling captured rig type, water depth rating, automation tier, and regional regulatory cluster. CAGRs were derived from lease commitment absorption rates and shipyard delivery schedules. Industry-specific forecast inputs included jack-up leg steel alloy cost indices and subsea electronics technician wage benchmarks.
Revisions become necessary when shipyard capacity constraints extend beyond modeled backlogs or when divergent national methane protocols fragment equipment certification requirements. Forecasts reflect documented assumptions around regulatory implementation timelines and commodity price stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Auger Drilling Machine Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Drilling Stabilizers Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Logging Cable Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Drill Pipe Market