
 Solar Animal Repeller Market | 2026-2036
Solar Animal Repeller Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Animal Repeller Market Insights
Buyer concentration in commercial agriculture is decoupling from traditional residential demand as vineyard operators and orchard managers scale deployment across hundreds of acres. Bird-X leverages its ultrasonic specialization to sustain premium positioning in North American vineyard protection. Aspectek competes through broad SKU coverage across motion-activated and light-based formats. Hoont anchors European distribution through agricultural cooperatives in France and Italy.
A solar animal repeller converts photovoltaic energy into ultrasonic frequencies, strobe pulses, or ground vibrations to deter wildlife without physical barriers or chemical agents; typical units integrate monocrystalline panels generating 5–20W, PIR sensors with 8–12 meter detection ranges, and IP65-rated housings for continuous outdoor operation. Ultrasonic repellers dominate unit volume in agricultural end use where frequency modulation prevents habituation among deer and rodent populations. Motion-activated devices command higher per-unit pricing in commercial wildlife management due to battery conservation algorithms and programmable deterrence sequences. Light-based repellers occupy a niche in aviation and landfill applications where FAA and EPA guidelines restrict acoustic emissions near populated corridors.
EPA pesticide re-registration reviews and state-level neonicotinoid bans are redirecting procurement budgets toward non-chemical alternatives, while FCC Part 15 compliance governs ultrasonic emission limits for devices sold in US interstate commerce. The EU Green Deal's Farm to Fork strategy and REACH chemical restrictions are creating parallel demand migration in European member states. Stakeholders must monitor evolving frequency allocation rules and wildlife corridor designations that could restrict deployment in protected habitats.
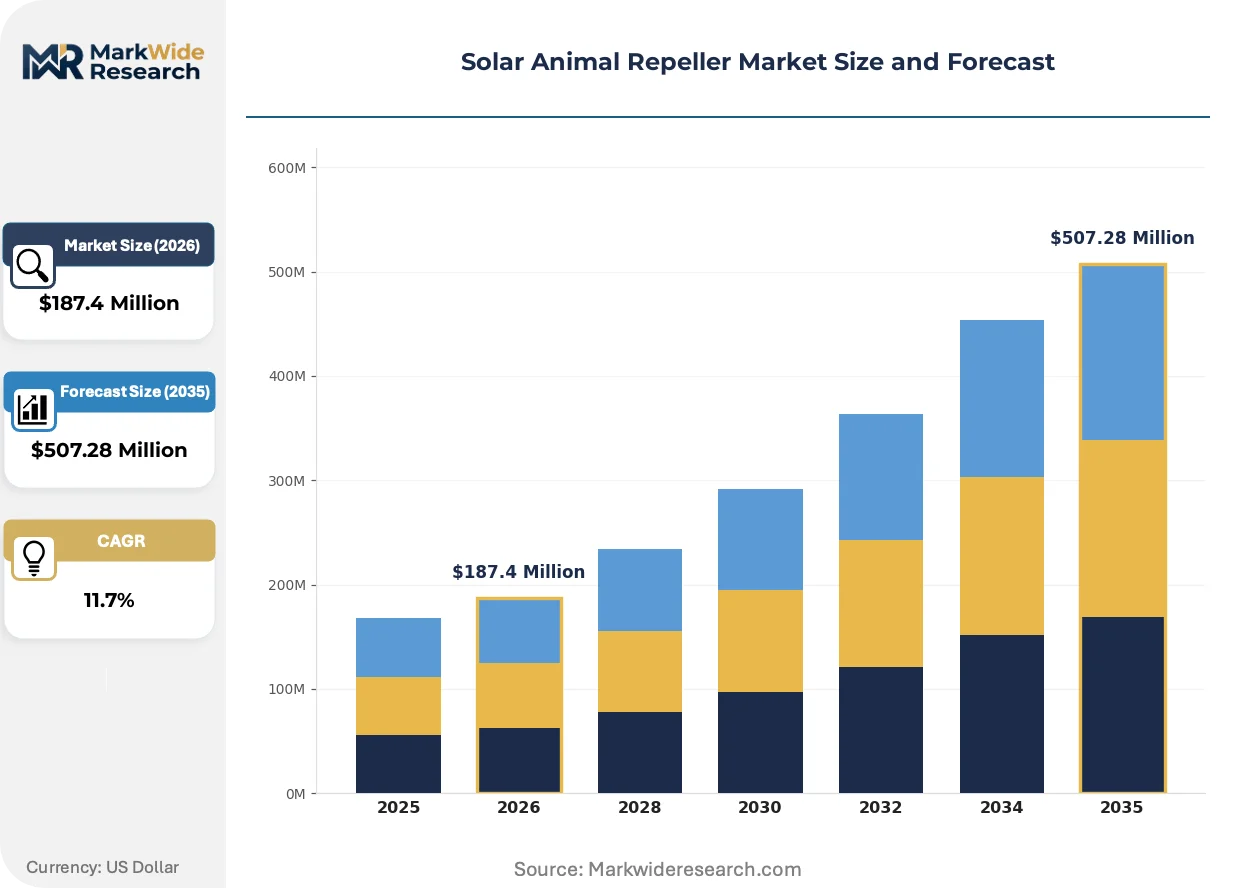
Market Dynamics
EPA pesticide re-registration reviews and state-level neonicotinoid bans are redirecting agricultural procurement budgets toward non-chemical wildlife management alternatives, compressing substitution timelines for solar-powered deterrent systems.
Growth Catalysts
- California's Central Valley concentration:Large-scale vineyard and orchard operators across Fresno and Kern counties are deploying ultrasonic units across contiguous acreage, creating demonstration effects for neighboring properties.
- EU Green Deal Farm to Fork strategy:REACH chemical restrictions and biodiversity targets are accelerating member state subsidies for pesticide-free crop protection technologies in French and Italian wine regions.
- Frequency modulation algorithms:Programmable ultrasonic patterns prevent habituation among deer and rodent populations, sustaining deterrent effectiveness over multi-year deployment cycles.
Market Restraints
- Monocrystalline silicon input volatility:Photovoltaic panel costs fluctuate with polysilicon supply from Xinjiang-based producers, compressing margin buffers for finished device assemblers.
- FCC Part 15 emission limits:Ultrasonic frequency caps for interstate commerce restrict maximum effective range in US agricultural deployments versus unrestricted international variants.
- Physical barrier substitution:Electric fencing maintains cost advantages per linear meter for perimeter-heavy livestock operations, limiting addressable market in cattle ranching segments.
Strategic Opportunities
- Aviation corridor compliance:FAA acoustic emission guidelines near populated corridors are creating specification demand for light-based repellers at municipal landfills and airports.
- Indian agricultural cooperative channels:Maharashtra and Karnataka state horticulture departments are piloting solar deterrent programs for mango and grape export zones facing EU residue standards.
- IoT sensor convergence:Integration of soil moisture and pest detection modules transforms standalone repellers into vineyard management nodes, opening software subscription revenue streams.
Industry Challenges
- IP65 certification timelines:Third-party validation for continuous outdoor operation extends product launch cycles by 4-6 months, delaying seasonal sales windows.
- Wildlife corridor deployment restrictions:Protected habitat designations in California and EU Natura 2000 zones require pre-installation environmental review, complicating large-scale farm planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Animal Repeller Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Repellers, Motion-Activated Devices, Light-Based Repellers, Vibrational Models End User: Agriculture, Residential, Commercial, Wildlife Management Technology: Solar-Powered, Battery-Operated, Plug-In, Hybrid Systems Distribution Channel: Online Retail, Home Improvement Stores, Agricultural Supply Shops, Direct Sales |
| Companies Covered | Bird-X, Aspectek, Hoont, PestAway, Bell & Howell, SWISSINNO, Vitax Limited, Solar Pest Solutions, EcoGuard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Animal Repeller Market Trends and Innovations
Active frequency modulation and photovoltaic efficiency gains are compressing replacement cycles for legacy battery-powered deterrents while regulatory pressure on chemical agents accelerates specification changes in procurement documents.
Adaptive ultrasonic emitters with machine learning-driven pattern variation are rewriting effectiveness benchmarks for agricultural wildlife management. Vineyard operators in Napa and Sonoma counties are retrofitting existing posts with these units during dormant season maintenance windows. The technology is compressing acceptable habituation timelines from 18 months to under 6 months for premium wine grape protection.
REACH chemical restrictions and EU Green Deal biodiversity targets are mandating pesticide reduction pathways across member state agricultural subsidies. French and Italian wine cooperatives are rewriting technical specifications to exclude chemical deterrents from approved input lists. Light-based repeller categories are capturing specification share in aviation-adjacent applications where acoustic emission limits apply.
Buyer concentration among thousand-plus-acre vineyard operators is consolidating procurement decisions through agricultural cooperative technical committees. Equipment distributors in California's Central Valley are losing specification influence to direct manufacturer relationships with estate managers. This pattern is most visible in Sonoma County where three cooperatives coordinate seasonal deployment timing across contiguous properties.
Solar Animal Repeller Market Segmentation
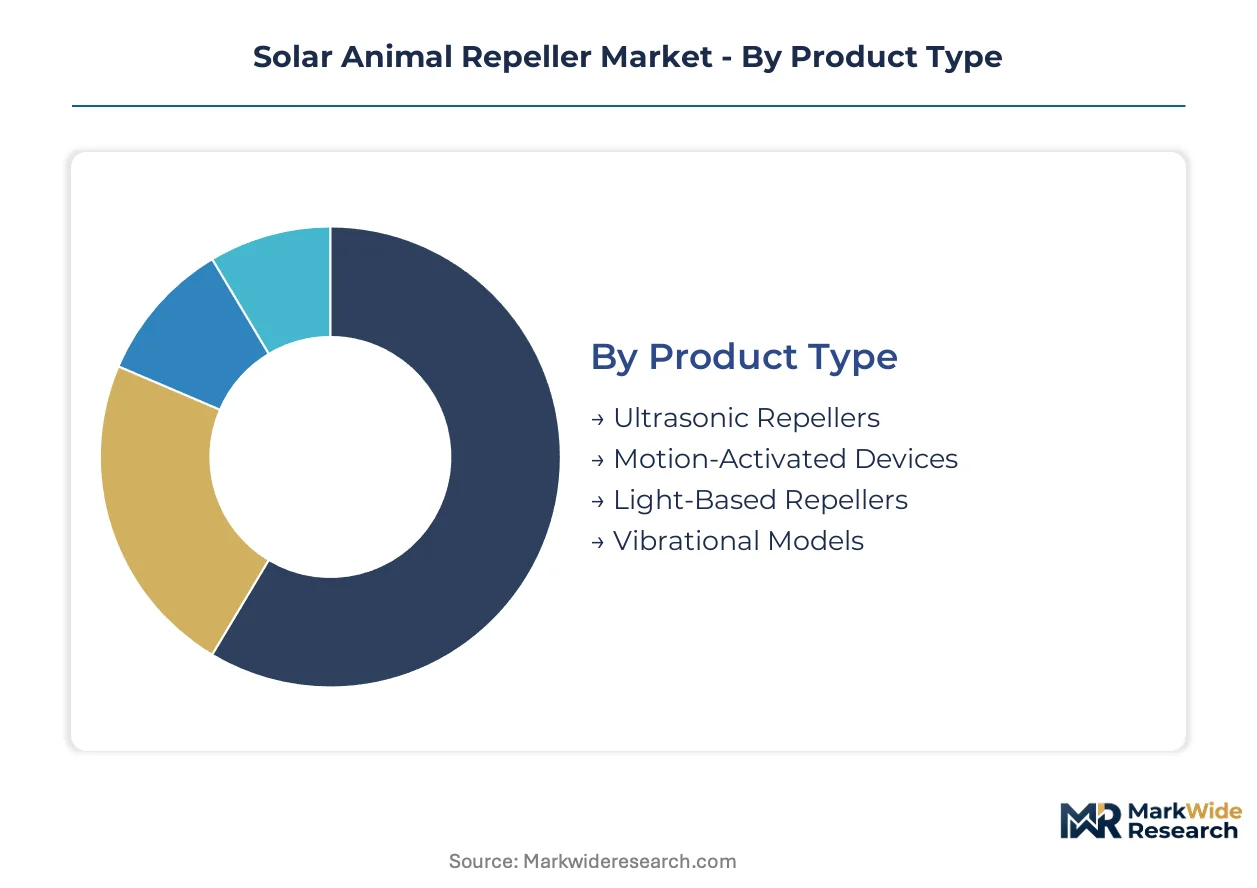
Solar animal repeller procurement patterns diverge sharply between standalone perimeter installations and embedded vineyard management systems. Equipment specification committees at agricultural cooperatives now weight integration compatibility as heavily as standalone deterrent efficacy.
Product Type:
Ultrasonic repellers deploy as discrete units along field perimeters, while motion-activated and light-based formats increasingly embed within broader farm automation architectures.
- Ultrasonic Repellers:Emit frequency-modulated sound waves above human hearing thresholds, typically 15–65 kHz, with programmable patterns preventing wildlife habituation. Demand concentrates in California's Central Valley vineyard corridors where contiguous acreage deployment creates network effects across neighboring estates. FCC Part 15 emission caps constrain maximum effective range in US interstate commerce versus unrestricted international variants.
- Motion-Activated Devices:Combine PIR sensors with battery conservation algorithms and programmable deterrence sequences, commanding premium per-unit pricing in commercial wildlife management. French and Italian wine cooperatives specify these units for perimeter-heavy estates facing EU Green Deal pesticide reduction mandates.
- Light-Based Repellers:Strobe and LED pulse configurations serve aviation-adjacent applications where FAA acoustic emission guidelines restrict ultrasonic deployment near populated corridors.
- Vibrational Models:Ground-buried transducers transmit seismic disturbance patterns through soil substrates, finding niche uptake in rodent-dense root vegetable operations.
Volume placements concentrate in Ultrasonic Repellers; the faster expansion belongs to Motion-Activated Devices.
End User:
Cost tier stratification separates thousand-acre commercial operators from residential hobbyists, with procurement authority migrating from distributors to direct manufacturer relationships at scale.
- Agriculture:Vineyard and orchard operators across California, France, and Italy deploy ultrasonic and motion-activated units across contiguous acreage, with technical specifications written by cooperative committees rather than individual farm managers. REACH chemical restrictions and state-level neonicotinoid bans redirect procurement budgets toward these non-chemical alternatives.
- Residential:Single-unit purchases through home improvement stores and online retail dominate, with price sensitivity highest in this tier and feature requirements limited to basic PIR detection and weatherproofing.
- Commercial:Municipal landfills, airports, and golf courses specify light-based repellers to comply with FAA and EPA acoustic emission guidelines near populated areas.
- Wildlife Management:Professional services contractors deploy hybrid configurations across heterogeneous terrain, requiring equipment interoperability with trapping and relocation protocols.
Revenue concentration sits with Agriculture; Commercial applications are climbing the fastest as aviation corridor compliance tightens.
Technology:
Supply chain configuration for photovoltaic components directly determines technology tier accessibility, with monocrystalline silicon input volatility compressing margin buffers for solar-powered assemblers.
- Solar-Powered:Monocrystalline panels generating 5–20W integrate with IP65-rated housings for continuous outdoor operation, eliminating battery replacement labor costs across multi-year deployment cycles. Polysilicon supply fluctuations from Xinjiang-based producers introduce pricing instability.
- Battery-Operated:Alkaline and lithium-ion configurations persist in shaded canopy environments where photovoltaic efficiency drops below operational thresholds, particularly in dense orchard settings.
- Plug-In:Grid-tethered units serve perimeter-adjacent buildings and equipment sheds with reliable electrical infrastructure, offering consistent output regardless of weather conditions.
- Hybrid Systems:Combine photovoltaic generation with battery backup and grid failover, specified by estate managers requiring guaranteed uptime during critical harvest protection windows.
Deployment scale favors Solar-Powered; Hybrid Systems are gaining share fastest among risk-averse premium vineyard operators.
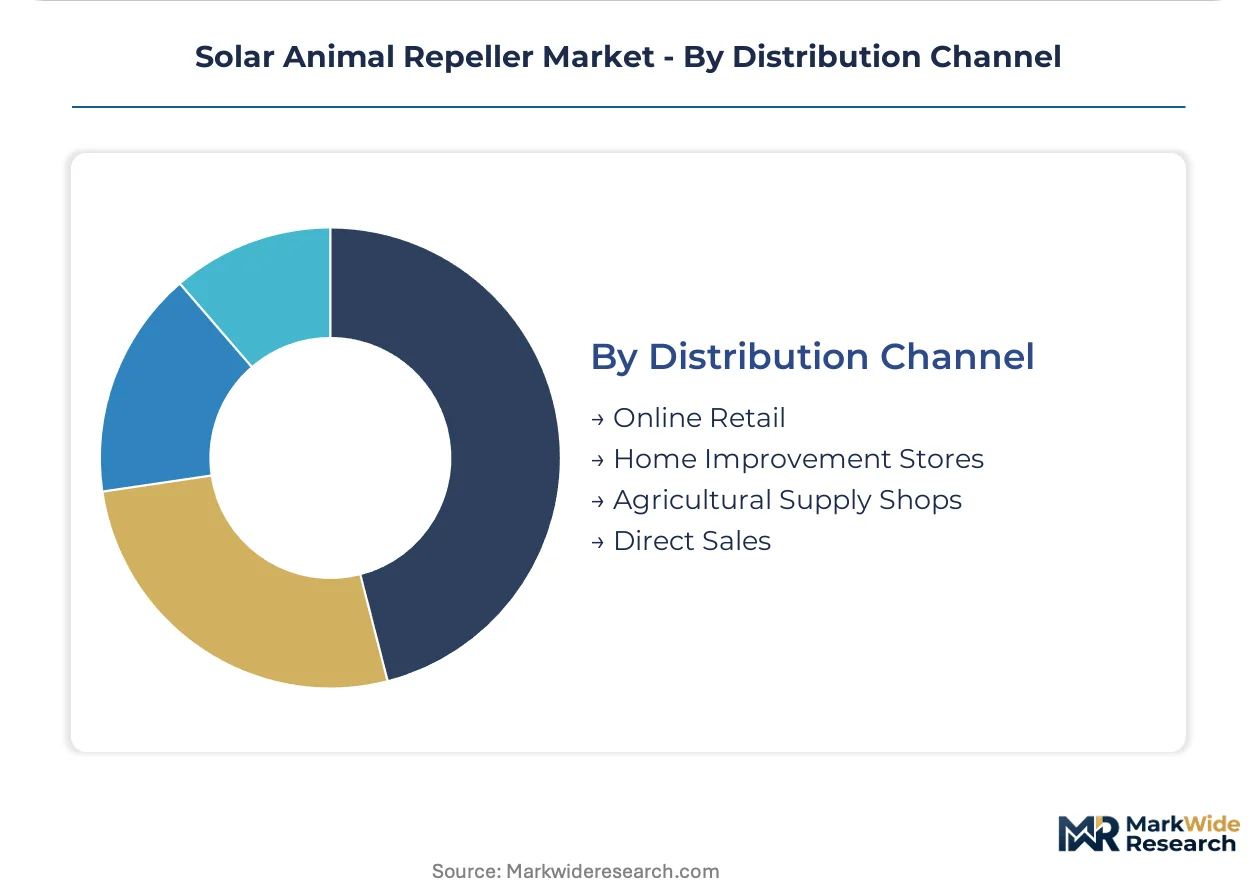
Distribution Channel:
Customer type fragmentation drives channel bifurcation, with agricultural cooperatives consolidating procurement decisions while residential buyers fragment across digital and physical retail.
- Online Retail:Amazon and specialized agricultural equipment marketplaces capture residential and small-holding demand, with review-driven selection criteria dominating purchase decisions.
- Home Improvement Stores:Lowe's and Home Depot serve suburban residential demand with seasonal merchandising aligned to planting and harvest calendars.
- Agricultural Supply Shops:California's Central Valley equipment distributors retain influence in mid-scale operations, though losing specification authority to direct manufacturer relationships at thousand-plus-acre estates.
- Direct Sales:Manufacturers cultivate relationships with estate managers and cooperative technical committees, bypassing distributor margins for large-scale vineyard and orchard deployments.
Transaction volume concentrates in Agricultural Supply Shops; Direct Sales channels show the steepest expansion trajectory as buyer concentration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial agriculture operators in California's Central Valley and France's wine regions are driving procurement concentration for solar-powered wildlife deterrent systems, with regulatory pressure on chemical pesticides accelerating specification changes across multiple jurisdictions.
United States
Fresno and Kern county vineyard operators deploy ultrasonic units across contiguous acreage, creating demonstration effects for neighboring estates. EPA pesticide re-registration reviews and California's state-level neonicotinoid bans redirect procurement budgets toward non-chemical alternatives. Sonoma County cooperatives coordinate seasonal deployment timing across thousand-plus-acre properties.
France
Bordeaux and Burgundy wine cooperatives specify motion-activated devices for perimeter-heavy estates facing biodiversity targets. The EU Green Deal's Farm to Fork strategy and REACH chemical restrictions mandate pesticide reduction pathways across agricultural subsidies. Technical committees at regional cooperatives now exclude chemical deterrents from approved input lists.
Italy
Tuscany and Piedmont orchard managers scale deployment of frequency-modulated systems to protect premium wine grape harvests. ECHA enforcement of REACH restrictions accelerates substitution timelines for vineyard protection technologies. Agricultural cooperatives in Chianti Classico coordinate procurement decisions through direct manufacturer relationships.
India
Maharashtra and Karnataka state horticulture departments pilot solar deterrent programs for mango and grape export zones. DGFT export standards and EU residue compliance requirements drive specification changes for chemical-free crop protection. Nashik district vineyard clusters represent the primary deployment concentration for ultrasonic perimeter systems.
Germany
Baden-Württemberg viticulture operations adopt hybrid photovoltaic systems with battery backup for critical harvest protection windows. ECHA chemical restrictions and EU biodiversity corridor designations complicate deployment planning in protected habitats. Lake Constance wine cooperatives integrate deterrent specifications into broader farm automation architectures.
Solar Animal Repeller Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue IoT convergence and aviation-corridor compliance specializations. The vendor base stratifies across ultrasonic specialists, motion-activation generalists, and light-based niche providers. Three archetypes dominate: frequency-modulation technology leaders, agricultural cooperative channel anchors, and aviation-compliance specialists. Competitive moves concentrate on direct estate manager relationship cultivation and cooperative technical committee specification capture.
Within the ultrasonic specialization tier, Bird-X exemplifies premium positioning in North American vineyard protection, while Aspectek occupies the broad-format generalist position across motion-activated and light-based categories. Hoont anchors European distribution through agricultural cooperative channels in France and Italy. These three represent distinct strategic postures: technology differentiation, SKU breadth coverage, and regional channel depth respectively.
| Leading Market Players |
|---|
| Bird-X |
| Aspectek |
| Hoont |
| PestAway |
| Bell & Howell |
| SWISSINNO |
| Vitax Limited |
| Solar Pest Solutions |
| EcoGuard |
| Others |
Pricing and Supply Chain Analysis
Backward integration into monocrystalline silicon wafer sourcing anchors both supply security and pricing power for solar animal repeller manufacturers, with Xinjiang-based polysilicon concentration forcing tiered procurement strategies across premium and standard product lines. California vineyard cooperatives and French agricultural technical committees now mandate dual-source photovoltaic qualification in specifications, compressing margins for assemblers locked into single-source panel arrangements.
Pricing Analysis
Volume placements in ultrasonic repellers run on thin per-unit margins, while motion-activated devices capture premium positioning through programmable deterrence sequences and battery conservation algorithms. Price differentiation hinges on FCC Part 15 certification tier and volume scale, with thousand-acre estate managers extracting favorable terms through direct manufacturer relationships. Cost compression in standard-tier units is intensifying because polysilicon input volatility from Xinjiang-based producers compresses margin buffers. Residential buyers through Amazon and home improvement channels exhibit highest price sensitivity; premium vineyard operators in Napa and Sonoma counties demonstrate least sensitivity due to harvest protection criticality.
Supply Chain Analysis
Dual-sourcing requirements from California agricultural cooperatives and French wine technical committees mandate qualified suppliers across China, Vietnam, and Malaysia for IP65-rated housings and PIR sensor modules. Component dependencies rest on monocrystalline silicon wafers, lithium-ion battery cells, and ultrasonic transducer arrays. Single-source vulnerability concentrates in Xinjiang polysilicon purification, exposing assemblers to forced labor due diligence disruptions and tariff exposure. Distribution runs through direct sales channels for estate-scale deployments, with agricultural supply shops retaining mid-scale influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
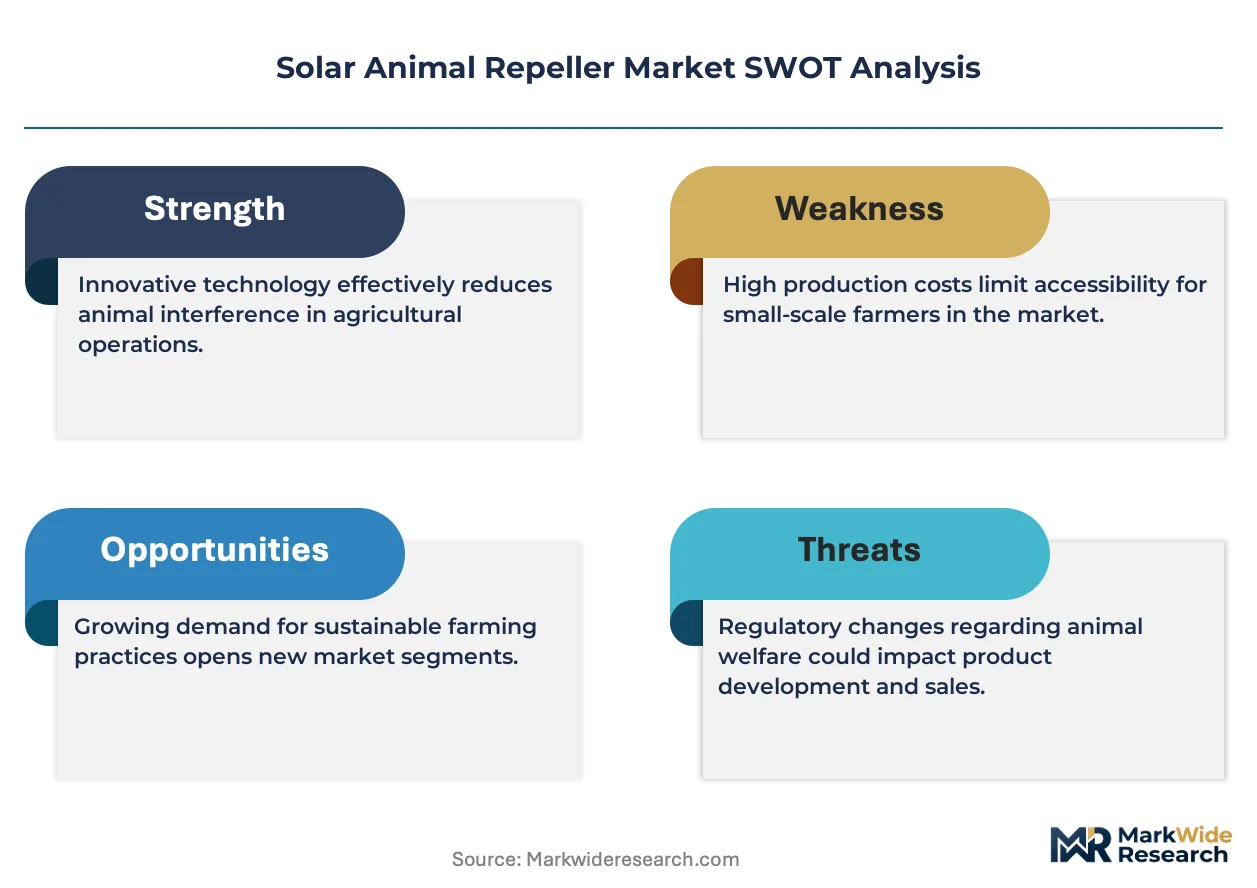
This market consolidates around frequency-modulation technology leaders and cooperative channel anchors, with polysilicon cost volatility and REACH compliance investments forcing sub-scale assemblers toward exit or acquisition.
For Market Incumbents: Acquire machine learning-driven pattern variation capabilities to compress habituation timelines below six months for premium vineyard protection. Defensive priorities center on locking multi-year supply agreements with Malaysian and Vietnamese panel assemblers to offset Xinjiang concentration risk, while embedding soil moisture and pest detection modules to capture software subscription revenue streams from estate managers. For New Entrants and Emerging Players: Agricultural cooperatives in Maharashtra and Karnataka state horticulture departments represent the most penetrable channel entry point, with EU residue compliance requirements creating specification demand for chemical-free crop protection. Target aviation-corridor compliance specialization for municipal landfill and airport applications where FAA acoustic emission guidelines restrict ultrasonic deployment. Go-to-market execution should prioritize direct technical committee engagement over distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by ultrasonic specialists seeking IoT convergence capabilities or agricultural equipment conglomerates building vineyard management system portfolios. Long-term viability favors vendors with captive frequency-modulation IP and cooperative channel depth across California, France, and Italy. Watch for ECHA enforcement acceleration on REACH chemical restrictions as inflection indicator for substitution timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Pattern Variation Development | Adaptive ultrasonic emitters with algorithm-driven frequency modulation compress deer habituation timelines below six months for Napa vineyard protection. |
| Dual-Source Photovoltaic Qualification | Malaysia and Vietnam panel supplier onboarding reduces Xinjiang polysilicon concentration risk for IP65-rated housing assemblers. |
| IoT Sensor Module Integration | Soil moisture and pest detection convergence transforms standalone repellers into vineyard management nodes with subscription revenue. |
| Aviation-Corridor Light-Based Repeller Launch | FAA acoustic emission compliance positions strobe pulse configurations for municipal landfill and airport perimeter specifications. |
| Indian Cooperative Channel Partnership | Maharashtra and Karnataka horticulture department pilots open mango and grape export zone deployment for EU residue compliance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across estate managers at California Central Valley vineyards, technical committee leads at French wine cooperatives, procurement directors at Italian agricultural supply shops, and R&D heads at ultrasonic device manufacturers. EPA pesticide re-registration documentation, FCC Part 15 emission filings, ECHA REACH restriction updates, and EU Green Deal Farm to Fork strategy implementation reports provided regulatory trajectory validation. Bottom-up unit shipment estimates triangulated against top-down agricultural cooperative procurement budget allocations.
Data-stream reconciliation across manufacturer shipment records, distributor inventory positions, and end-user installation reports informed the analytical framework across the analysis window. Segmentation modeling incorporated product type, end-user tier, power technology, and distribution channel dimensions, with particular weighting for integration compatibility specifications in cooperative technical committee procurement documents. CAGRs derived from polynomial trend fitting against historical substitution patterns for chemical deterrents, with photovoltaic efficiency gain curves and frequency modulation patent filings as industry-specific forecast inputs.
Caveats apply where polysilicon supply disruptions from Xinjiang-based producers, ECHA enforcement acceleration on REACH restrictions, or FAA emission limit revisions could materially shift the outlook. Deviation in California neonicotinoid ban implementation timing or EU Green Deal subsidy allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Snow Sports Apparel Market
Others
Next Gen Video Codecs Market
Others
Global Healthcare/Medical Simulation Market
Others
Global Tobacco Market
Others
North America Medical Simulation Market
Others
Level Measuring Instrument Market
Others
Global Military Lighting Market
Others
Smart Electric Curtain Market
Others
Wingboards Market
Others
Bulgur Market
Others
Video Conferencing Hardware Market
Others
Content Experience Platforms Market
Others
US Legal Services Market
Others
One-Way Degassing Valve Market
Others
Security Envelopes Market
Others
Europe Intercom Devices Market