
 Global Olanzapine Market | 2026-2036
Global Olanzapine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Olanzapine Market Foresight
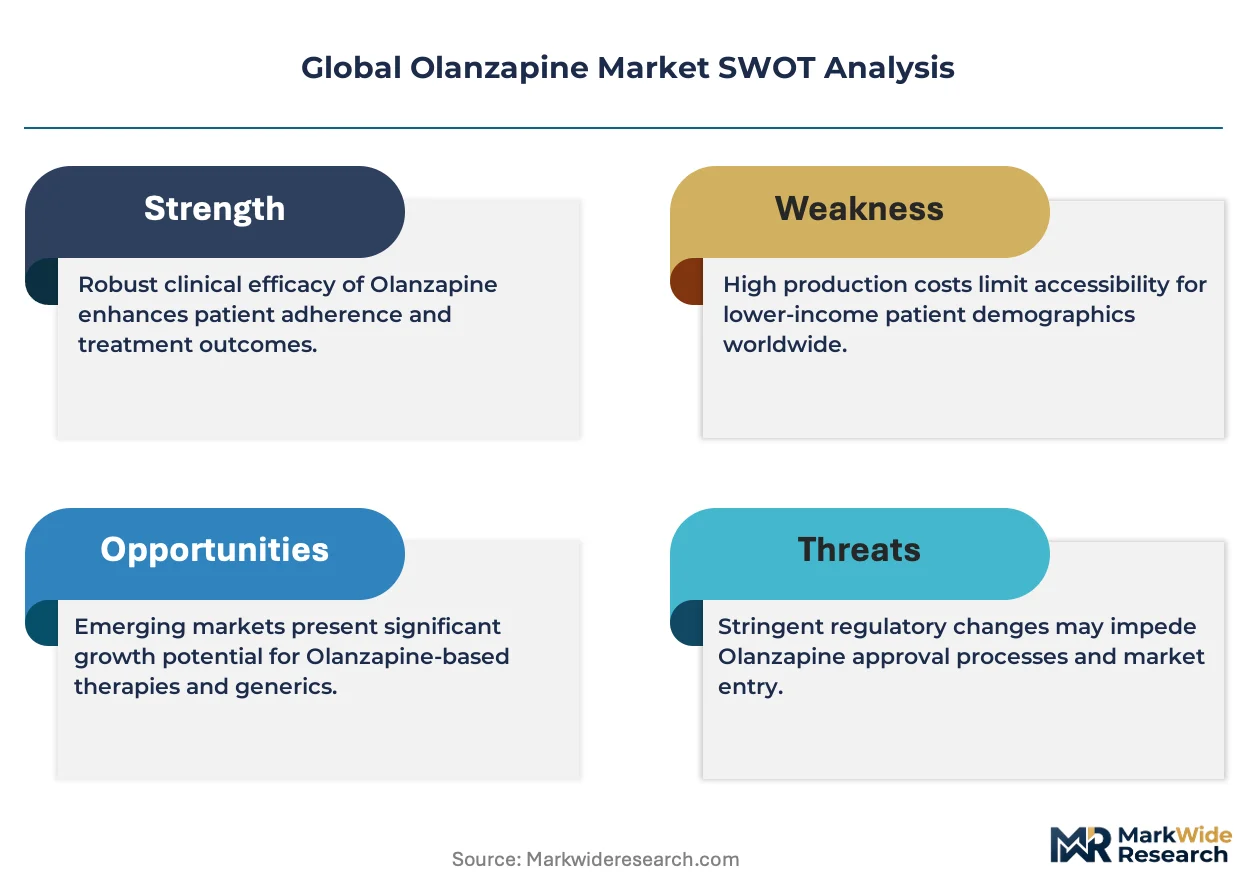
The gap between originator-grade olanzapine and high-volume generic supply is broadening across dosage forms and purity certifications. Eli Lilly and Company sustains its position through residual brand recognition in extended-release formulations. Teva Pharmaceutical Industries Ltd. leverages vertical integration across API and finished-dose production to control cost structures. Dr. Reddy's Laboratories Ltd. anchors its competitive stance with concentrated manufacturing scale in Indian export facilities.
Olanzapine is a thienobenzodiazepine-class atypical antipsychotic with molecular formula C17H20N4S, functioning primarily as a multi-receptor antagonist targeting dopamine D2 and serotonin 5-HT2A pathways for schizophrenia and bipolar disorder management. Oral tablet formulations occupy the largest volume position due to decades of clinical familiarity and reimbursement stability, while disintegrating tablets represent the fastest-expanding segment driven by patient compliance advantages in institutional settings. Injectable solutions command premium pricing corridors through depot administration protocols in specialized mental health centers.
FDA bioequivalence standards and EMA quality guidelines shape product approval timelines and manufacturing investment requirements across export-oriented producers. India's CDSCO enforces escalating local clinical trial and stability data mandates that filter market access for foreign manufacturers. Stakeholders must monitor evolving pharmacovigilance reporting obligations from WHO prequalification programs and national regulators to sustain distribution continuity.
Market Dynamics
Generic substitution pressure is fragmenting value capture across olanzapine dosage forms, forcing manufacturers to differentiate through depot formulations and purity-tier positioning rather than molecule exclusivity.
Growth Catalysts
- CDSCO expansion protocols:India's psychiatric clinic licensing reforms accelerate olanzapine prescribing for bipolar disorder management, creating institutional volume anchors.
- Depot administration adoption:Injectable long-acting formulations reduce hospital readmission rates, driving procurement preference shifts in specialized mental health centers.
- WHO prequalification pathways:Emerging market tender eligibility for API-certified suppliers opens procurement access in Sub-Saharan African public health systems.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in select Indian manufacturing zones create single-source vulnerability for finished-dose producers.
- FDA bioequivalence barriers:Extended-release formulation approval timelines exceed standard oral tablet pathways, compressing effective patent cliff windows for complex generics.
- Metabolic side-effect liability:Weight gain and diabetes risk profiles limit olanzapine first-line positioning against aripiprazole in treatment-naive schizophrenia protocols.
Strategic Opportunities
- Brazilian public tender expansion:ANVISA streamlined registration for prequalified suppliers creates access to Latin America's largest institutional psychiatry procurement pool.
- Orally disintegrating tablet segments:Compliance advantages in forensic and geriatric institutional settings drive premium pricing acceptance for rapid-dissolve formulations.
- EMA quality guideline harmonization:Mutual recognition agreements with Health Canada and Swissmedic reduce duplicate stability study burdens for multi-territory launches.
Industry Challenges
- Pharmacovigilance reporting scale:Post-market adverse event surveillance obligations across FDA, EMA, and CDSCO jurisdictions strain quality assurance headcount in mid-tier manufacturers.
- Legacy batch record digitization:Paper-based manufacturing documentation in older Indian and Chinese facilities impedes real-time supply chain transparency for international audit requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Olanzapine Market |
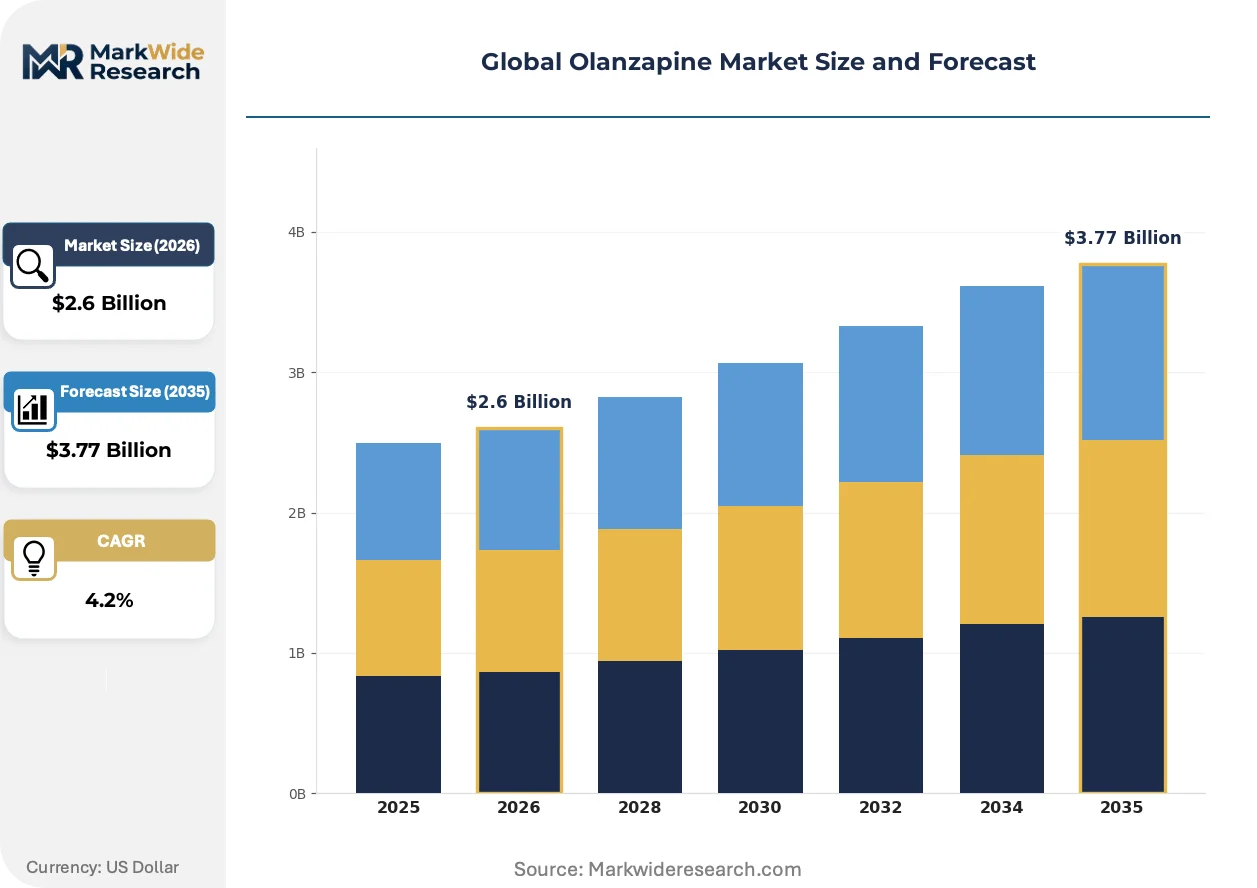
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $3.77 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Tablet, Injectable Solution, Disintegrating Tablet, Extended Release Capsule Therapy Area: Schizophrenia, Bipolar Disorder, Major Depressive Disorder, Off-Label Psychiatric Uses End User: Psychiatric Clinics, Specialized Mental Health Centers, General Hospitals, Outpatient Facilities Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Dr. Reddy's Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Aurobindo Pharma Ltd., Eli Lilly and Company, Mylan N.V., Apotex Inc., Lupin Limited, Cipla Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Olanzapine Market Shifts & Advancements
Formulation technology maturation and regulatory data harmonization are compressing development timelines while fragmenting competitive moats across oral and injectable delivery platforms.
Long-acting injectable depot technologies are consolidating market positioning for olanzapine pamoate monohydrate formulations, enabling monthly administration intervals that reduce caregiver burden in community mental health programs. Psychiatric hospitals in Germany and Australia are standardizing these protocols for medication adherence management. The technology is consolidating procurement decisions around single-supplier depot contracts that displace multi-source oral tablet purchasing.
EMA's updated bioequivalence guideline for highly variable drugs tightens statistical criteria for olanzapine Cmax and AUC parameters, extending generic development timelines for European market access. Finished-dose manufacturers are responding with larger pilot study cohorts and adaptive trial designs to mitigate failure risk. The regulation most impacts Indian and Chinese exporters seeking centralized EMA approval rather than mutual recognition through national competent authorities.
Institutional procurement consolidation through centralized hospital pharmacy networks is displacing decentralized physician prescribing autonomy in North American and Western European markets. Group purchasing organizations now negotiate multi-year olanzapine supply agreements that bundle oral and injectable formularies, compressing supplier margins in exchange for volume guarantees. This pattern is most visible in US academic medical centers and NHS England trust procurement frameworks.
Global Olanzapine Market Segmentation
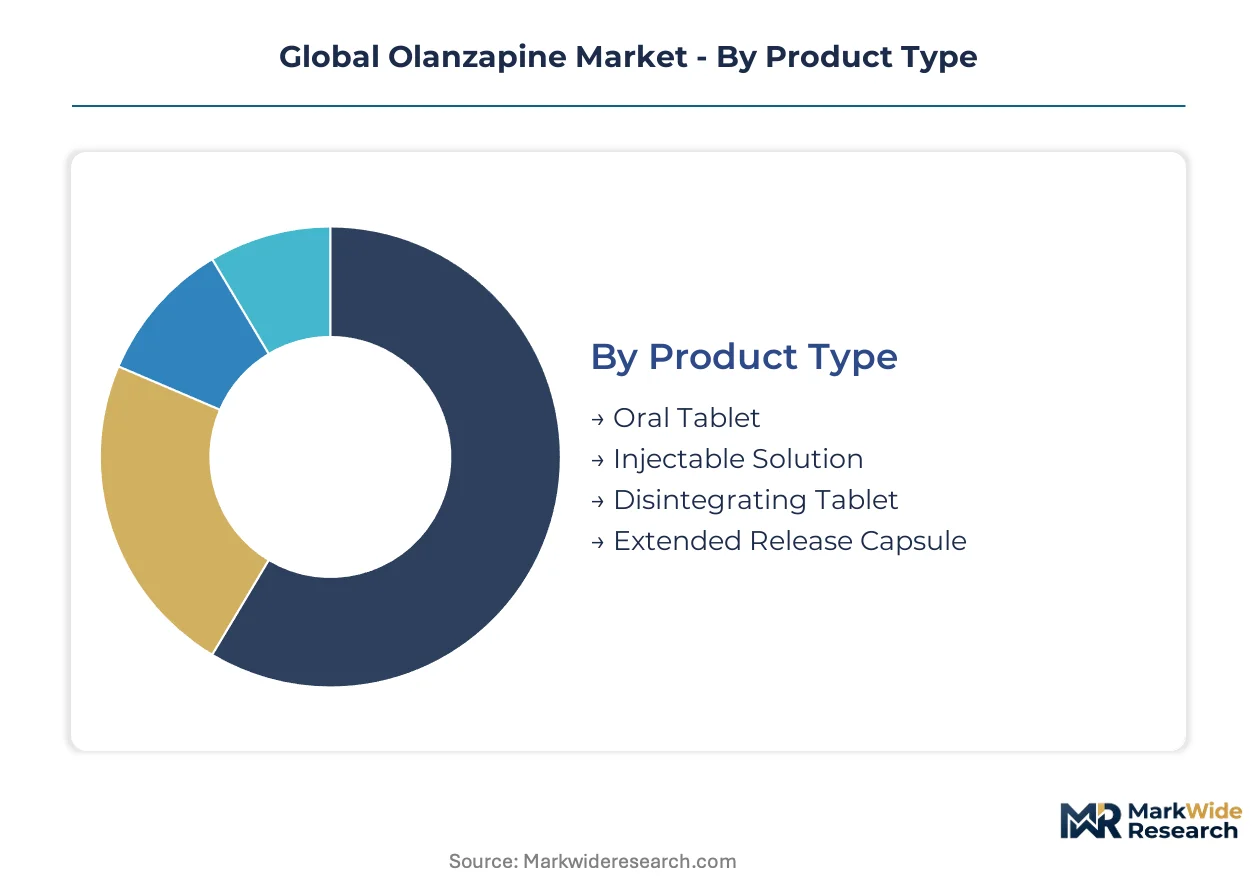
Supply concentration across dosage forms and purity tiers fragments value capture differently than molecule exclusivity would predict. Manufacturers now compete through depot formulation mastery and institutional procurement relationships rather than patent protection alone.
Product Type:
API production clusters in Indian manufacturing zones concentrate finished-dose supply for specific delivery technologies, creating sourcing dependencies that shape competitive positioning.
- Oral Tablet:Standard immediate-release tablets containing olanzapine base dominate procurement volumes through decades of clinical familiarity and stable reimbursement coding. Hospital pharmacy networks in the United States and Germany anchor demand through multi-year supply agreements that bundle oral and injectable formularies.
- Injectable Solution:Long-acting depot formulations using olanzapine pamoate monohydrate enable monthly administration intervals that reduce caregiver burden in community mental health programs. Psychiatric hospitals in Germany and Australia are standardizing these protocols for medication adherence management.
- Disintegrating Tablet:Rapid-dissolve formulations address compliance challenges in forensic and geriatric institutional settings where swallowing difficulties limit conventional tablet use.
- Extended Release Capsule:Sustained-release technologies face extended FDA bioequivalence approval timelines that compress effective market windows for complex generic entrants.
Oral tablets absorb the bulk of installed capacity; disintegrating tablets are expanding most quickly.
Therapy Area:
Prescribing protocols stratify across diagnostic categories based on metabolic side-effect profiles and comparative effectiveness against newer atypical antipsychotics.
- Schizophrenia:First-line positioning for acute psychotic episodes and maintenance therapy drives volume through hospital pharmacy channels and specialized mental health centers. FDA labeling and EMA guidelines reinforce olanzapine's established efficacy profile against positive and negative symptoms.
- Bipolar Disorder:Manic and mixed episode management represents the fastest-expanding prescription category as India's CDSCO expands psychiatric clinic licensing reforms that accelerate institutional prescribing authority.
- Major Depressive Disorder:Adjunctive use with selective serotonin reuptake inhibitors occupies a narrower niche limited by metabolic monitoring requirements and payer prior authorization protocols.
- Off-Label Psychiatric Uses:Agitation in dementia and treatment-resistant anxiety disorders generate discretionary prescribing outside formal indication coverage, concentrating in academic medical center psychiatry departments.
Schizophrenia applications command the largest share of clinical trial investment; bipolar disorder management is climbing the fastest.
End User:
Institutional procurement consolidation through centralized pharmacy networks is displacing decentralized physician autonomy across North American and Western European markets.
- Psychiatric Clinics:Outpatient mental health facilities in India are expanding under CDSCO oversight reforms that streamline olanzapine prescribing authority for bipolar disorder management.
- Specialized Mental Health Centers:Germany and Australia are standardizing long-acting injectable depot protocols that consolidate procurement around single-supplier contracts.
- General Hospitals:Emergency department and inpatient psychiatric unit formularies anchor acute-phase prescribing volumes through group purchasing organization agreements.
- Outpatient Facilities:Community-based prescribing faces escalating pharmacovigilance reporting obligations across FDA, EMA, and CDSCO jurisdictions that strain mid-tier manufacturer quality assurance capacity.
Specialized mental health centers absorb the bulk of depot formulation capacity; psychiatric clinics are gaining share fastest.
Distribution Channel:
Channel economics reflect reimbursement pathway complexity and inventory carrying cost structures that favor different logistics models across geographies.
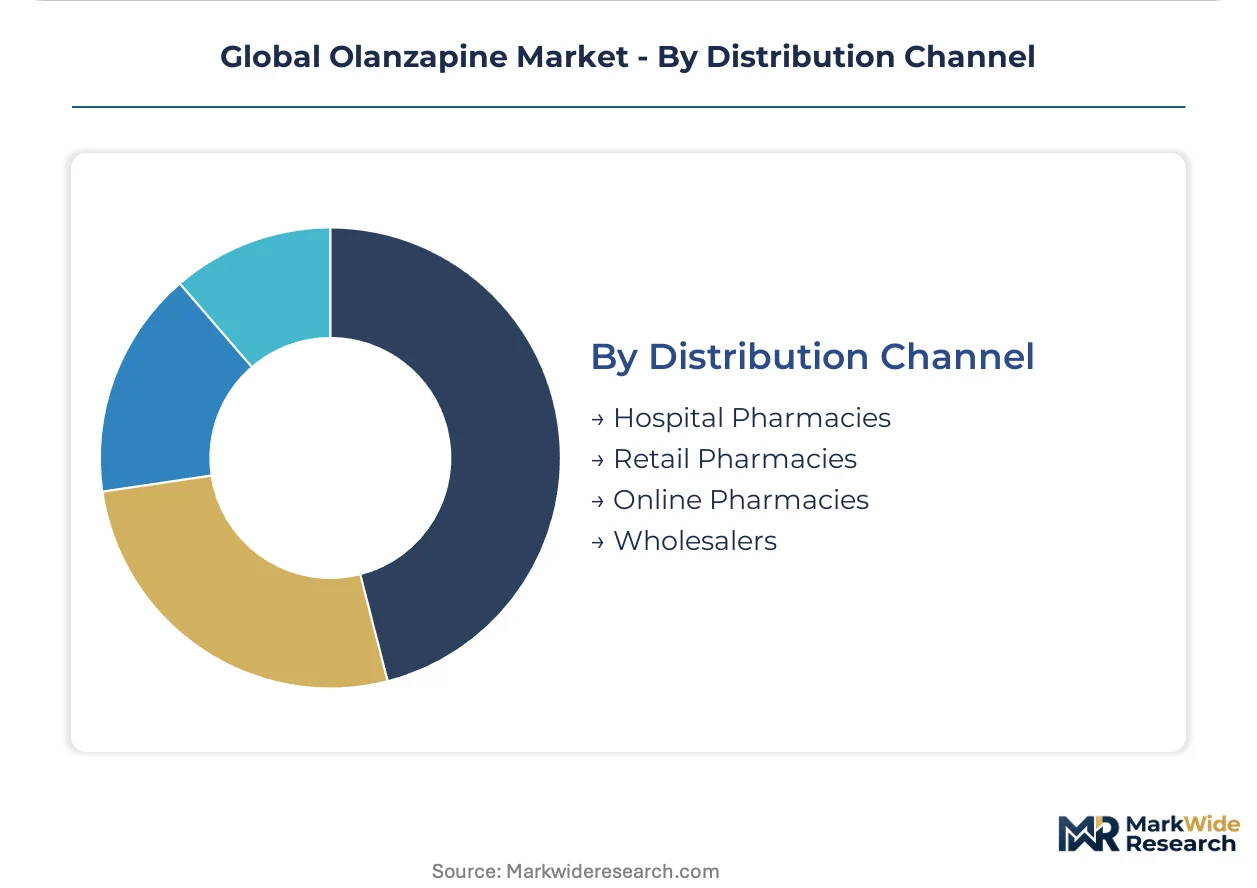
- Hospital Pharmacies:Group purchasing organizations in US academic medical centers and NHS England trust frameworks negotiate multi-year supply agreements that compress supplier margins in exchange for volume guarantees.
- Retail Pharmacies:Generic substitution pressure fragments value capture for oral tablet formulations through automated therapeutic interchange protocols and preferred pharmacy network incentives.
- Online Pharmacies:Direct-to-patient dispensing faces regulatory fragmentation across national pharmacy board jurisdictions that limits cross-border fulfillment for controlled substance classifications.
- Wholesalers:Three-tier distribution structures in Brazil and Sub-Saharan African markets create working capital intensity for API-certified suppliers seeking WHO prequalification tender eligibility.
Hospital pharmacies absorb the bulk of institutional procurement volume; online pharmacies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors API production for finished-dose manufacturers serving psychiatric institutions across three continents. The city's pharmaceutical corridor concentrates olanzapine active pharmaceutical ingredient synthesis under CDSCO oversight. Export volumes from this cluster supply hospital pharmacy networks in Germany, the United States, and Australia.
United States
Academic medical centers in Boston and New York Metro standardize long-acting injectable protocols for medication adherence management. FDA bioequivalence requirements for extended-release formulations exceed standard oral tablet approval timelines. Group purchasing organizations negotiate multi-year supply agreements that bundle oral and injectable formularies across hospital pharmacy networks.
Germany
Psychiatric hospitals in Bavaria and North Rhine-Westphalia consolidate procurement around single-supplier depot contracts. EMA bioequivalence guidelines for highly variable drugs tighten statistical criteria for Cmax and AUC parameters. The Rhine-Main industrial corridor hosts finished-dose packaging operations for Central European distribution.
India
Psychiatric clinics in Maharashtra and Telangana expand prescribing authority under CDSCO licensing reforms for bipolar disorder management. The country's national pharmaceutical regulator enforces escalating local clinical trial and stability data mandates. Hyderabad and Visakhapatnam manufacturing zones concentrate API synthesis for export-oriented producers.
Australia
Specialized mental health centers in New South Wales and Victoria adopt monthly depot administration intervals to reduce caregiver burden. TGA alignment with EMA quality guidelines facilitates streamlined registration for prequalified suppliers. Sydney and Melbourne hospital networks drive procurement preference shifts toward long-acting formulations.
Brazil
ANVISA streamlined registration creates access to Latin America's largest institutional psychiatry procurement pool. Public tender expansion in São Paulo and Rio de Janeiro concentrates demand through centralized hospital pharmacy networks. Three-tier distribution structures create working capital intensity for API-certified suppliers seeking tender eligibility.
Global Olanzapine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and purity certification tiers. The market structures around three distinct archetypes: originator-brand specialists with residual recognition in extended-release formats, vertically integrated generic houses controlling API-to-finished-dose cost structures, and export-focused Indian manufacturers leveraging concentrated manufacturing scale. Capacity expansion and strategic partnerships constitute the dominant competitive moves as patent cliffs erode molecule exclusivity.
Within the vertically integrated tier, Teva Pharmaceutical Industries Ltd. exemplifies backward integration across API and finished-dose production. Dr. Reddy's Laboratories Ltd. anchors the export-specialist archetype with concentrated manufacturing scale in Indian facilities. Eli Lilly and Company occupies a position representing originator-grade residual brand recognition in extended-release formulations.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Aurobindo Pharma Ltd. |
| Eli Lilly and Company |
| Mylan N.V. |
| Apotex Inc. |
| Lupin Limited |
| Cipla Inc. |
| Others |
Supply & Pricing Matrix
Long-acting injectable depot technology maturation simultaneously compresses manufacturing cost curves and concentrates procurement power around single-supplier contracts in specialized mental health centers. This formulation shift restructures value capture away from commodity oral tablets toward premium-positioned depot formulations with monthly administration protocols.
Pricing Analysis
Medication adherence outcomes anchor value-based pricing for long-acting injectable depot formulations, with psychiatric hospitals in Germany and Australia accepting premium positioning for reduced readmission rates. Three-tier pricing structure across originator-grade extended-release, complex generic depot, and commodity oral tablet levels reflects FDA bioequivalence certification tiers and purity-grade differentiation. Price erosion runs through immediate-release oral tablets as automated therapeutic interchange protocols intensify generic substitution pressure. Retail pharmacy channels exhibit highest price sensitivity through preferred network incentives, while specialized mental health centers demonstrate lowest sensitivity given bundled formulary procurement.
Supply Chain Analysis
Regional distribution centers in Hyderabad and Visakhapatnam anchor hub-and-spoke patterns serving hospital pharmacy networks across Germany, the United States, and Australia. API synthesis clusters in Indian manufacturing zones draw from thienobenzodiazepine precursor chemicals, specialized reactor equipment, and CDSCO-certified quality assurance capacity. Single-source vulnerability concentrates in select Indian API production zones where finished-dose manufacturers lack alternative qualified suppliers. Distribution runs through three-tier structures in Brazil and Sub-Saharan African markets, creating working capital intensity for WHO prequalification-seeking suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API synthesis capacity bottlenecks in Indian manufacturing zones prop pricing power for backward-integrated finished-dose producers capable of captive supply assurance.
For Market Incumbents: To counter generic substitution pressure fragmenting oral tablet margins, incumbents should deepen captive API production in Hyderabad and Visakhapatnam manufacturing corridors while securing multi-year depot formulation contracts with group purchasing organizations in US academic medical centers. For New Entrants and Emerging Players: Psychiatric clinics in Maharashtra and Telangana present the most penetrable institutional channel under CDSCO licensing reforms, with new entrants advised to pursue WHO prequalification pathways for Sub-Saharan African tender eligibility as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with export-focused Indian manufacturers possessing concentrated API-to-finished-dose scale given EMA bioequivalence guideline harmonization with Health Canada and Swissmedic. Long-term viability favors acquisition targets with depot formulation mastery and institutional procurement relationships. Watch for CDSCO stability data mandate escalation as the inflection indicator signaling regulatory barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Formulation Manufacturing Scale-Up | Monthly administration protocols reduce caregiver burden in community mental health programs across Germany and Australia. |
| WHO Prequalification Pathway Advancement | API-certified suppliers unlock procurement access in Sub-Saharan African public health systems through tender eligibility. |
| EMA Bioequivalence Guideline Harmonization | Mutual recognition agreements with Health Canada and Swissmedic reduce duplicate stability study burdens for multi-territory launches. |
| Backward Integration into API Synthesis | Captive thienobenzodiazepine production in Indian manufacturing zones insulates against single-source supply vulnerability. |
| Group Purchasing Organization Contracting | Multi-year supply agreements with NHS England trusts and US academic medical centers secure volume guarantees. |
Research Methodology
Independent corroboration across regulatory affairs leads at EMA and CDSCO, formulary directors at German psychiatric hospitals, and procurement managers at US group purchasing organizations underwrites the qualitative findings. Secondary validation draws from FDA bioequivalence filings, EMA quality guideline updates, ClinicalTrials.gov olanzapine protocol registrations, and WHO prequalification databases. Bottom-up demand modeling across dosage forms and therapy areas triangulates with top-down market sizing through API production volume estimates and finished-dose trade flow analysis.
Rate-of-change decomposition across the projection horizon separates volume growth from pricing dynamics and mix-shift effects toward depot formulations. Segmentation dimensions include dosage form, therapy area, end-user institution type, and regional regulatory cluster. CAGRs derive from regression-based trend extrapolation incorporating CDSCO expansion protocol adoption curves, FDA approval timeline distributions, and WHO prequalification penetration rates.
Caveats apply where CDSCO stability data mandate escalation, EMA bioequivalence statistical criteria tightening, or depot formulation supply concentration disruption could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Aspirin API Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Medication Adherence Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Cough Remedies Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Global Pharmacokinetics Services Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Global Artemisinin Combination Therapy Market
Pharmacology
Apixaban Market
Pharmacology
Ibuprofen API Market
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Influenza Medication Market