
 Laminated Tube Closure Market | 2026-2036
Laminated Tube Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Laminated Tube Closure Market Foresight
Modular closure configurations with integrated applicator tips and tamper-evident bands is rebalancing procurement criteria across oral care and cosmetic tube portfolios. Essel Propack Ltd. leverages its integrated laminate-to-closure manufacturing footprint to anchor contract positions with multinational toothpaste brands. Berry Global Inc. sustains North American supply dominance through high-volume injection molding capacity for flip-top and screw-cap formats. Albea Group differentiates via specialty metal-over-shell closures targeting prestige cosmetic lines.
A laminated tube closure is a precision-molded or formed dispensing and sealing component engineered to mate with multi-layer laminated tube shoulders, typically manufactured through injection molding, compression molding, or metal stamping processes with specified torque-release and barrier-seal performance parameters. Its primary commercial purpose is to preserve product integrity, enable controlled dispensing, and provide consumer ergonomics across viscous and semi-solid formulations. Flip-top closures lead volume in oral care applications due to one-hand operation convenience, while composite material closures represent the fastest-expanding segment as brands pursue aluminum reduction targets without sacrificing barrier performance. Plastic closures remain the mature margin pool, though resin cost volatility continues compressing value capture for undifferentiated commodity formats.
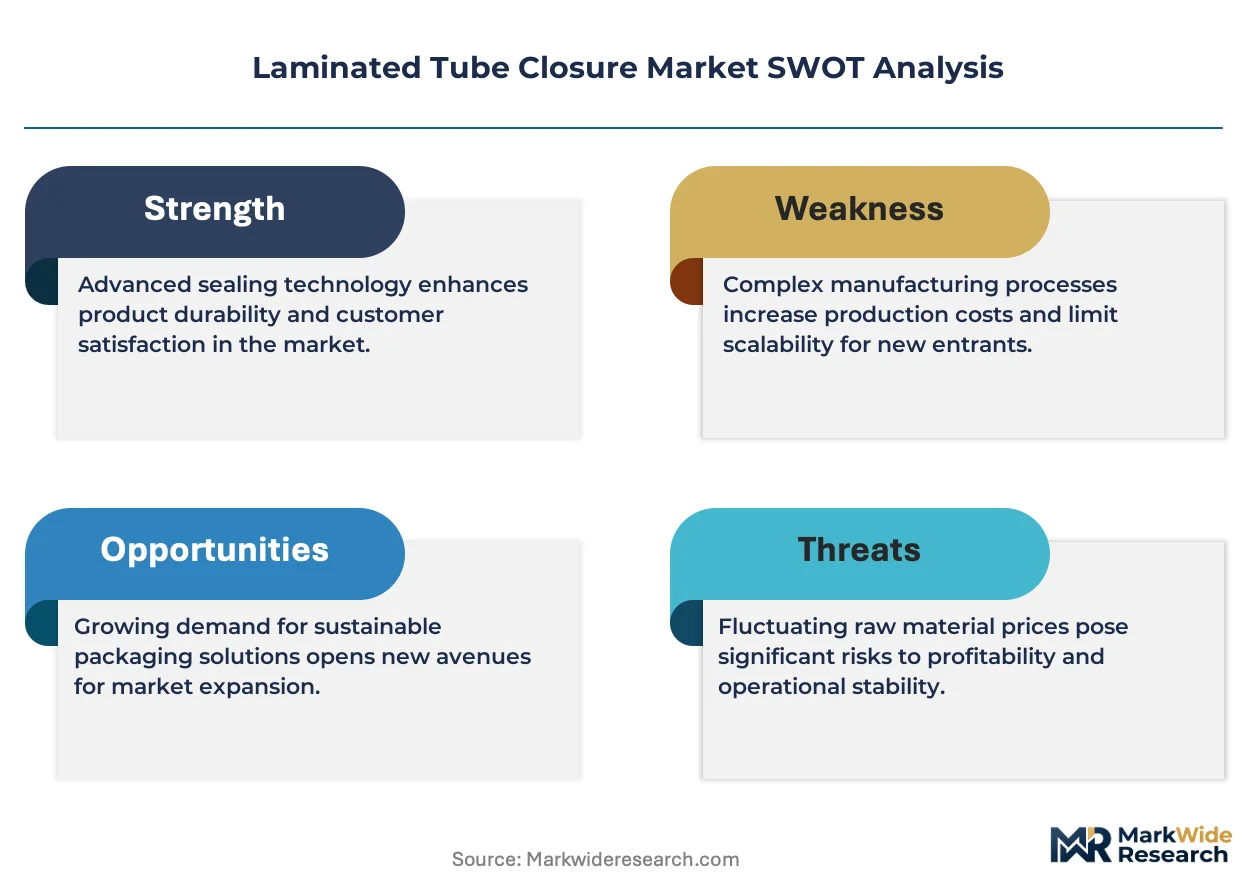
FDA regulations governing pharmaceutical primary packaging, EPA guidelines on recycled content mandates, and REACH chemical authorization requirements in Europe collectively elevate compliance costs while accelerating material substitution programs. ISO 15378 pharmaceutical packaging standards and EU MDR device labeling rules further constrain closure design flexibility, particularly for topical drug applications. Stakeholders must monitor evolving extended producer responsibility frameworks and biopolymer certification schemes to preempt supply disqualification risks.
Market Dynamics
Pharmaceutical packaging regulations are compressing material substitution timelines as oral care and topical drug manufacturers accelerate compliance investments ahead of REACH authorization deadlines and FDA guidance updates.
Growth Catalysts
- REACH Chemical Authorization:European ECHA mandates on phthalate restrictions in polymer formulations are forcing laminate reformulation investments that favor certified closure suppliers with pre-validated material portfolios.
- Oral Care Dispensing Convenience:Flip-top closure configurations with integrated tamper-evident bands are capturing preference share from screw-cap formats in toothpaste and gel applications due to one-hand operation requirements.
- India Manufacturing Cluster Expansion:Domestic personal care brand proliferation around Mumbai and Ahmedabad is generating contract manufacturing demand for laminated tube closures with localized torque-release specifications.
Market Restraints
- Resin Cost Volatility:Polypropylene and polyethylene input price swings are compressing margin capture for undifferentiated commodity closure formats without volume-scale offsets.
- Aluminum Barrier Dependency:EVOH and metallized film alternatives still fail to match aluminum foil oxygen transmission rates for oxygen-sensitive pharmaceutical formulations, limiting material substitution depth.
- Injection Molding Equipment Concentration:High-volume flip-top and screw-cap production capacity concentrates among a limited supplier base in Germany and the United States, creating allocation risk during demand surges.
Strategic Opportunities
- Biopolymer Certification Schemes:TUV Austria OK Compost and BPI certification programs are opening premium positioning channels for polylactic acid and bio-based polyethylene closure variants in European cosmetic lines.
- Topical Drug Delivery Systems:Transdermal patch and medicated cream formulations requiring child-resistant closure integration represent an underpenetrated application segment with specialized torque-performance specifications.
- Extended Producer Responsibility Frameworks:French and Italian packaging waste directives with modulated eco-modulation fees are incentivizing lightweight closure designs that reduce overall tube-head assembly mass.
Industry Challenges
- ISO 15378 Certification Timelines:Pharmaceutical packaging quality management system audits require 12-18 month validation cycles that delay new closure format commercialization for topical drug applications.
- Multi-Material Separation Complexity:Post-consumer recycling infrastructure lacks automated sorting capability for metal-over-shell and composite material closures, complicating circular economy claims and EPR compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminated Tube Closure Market |
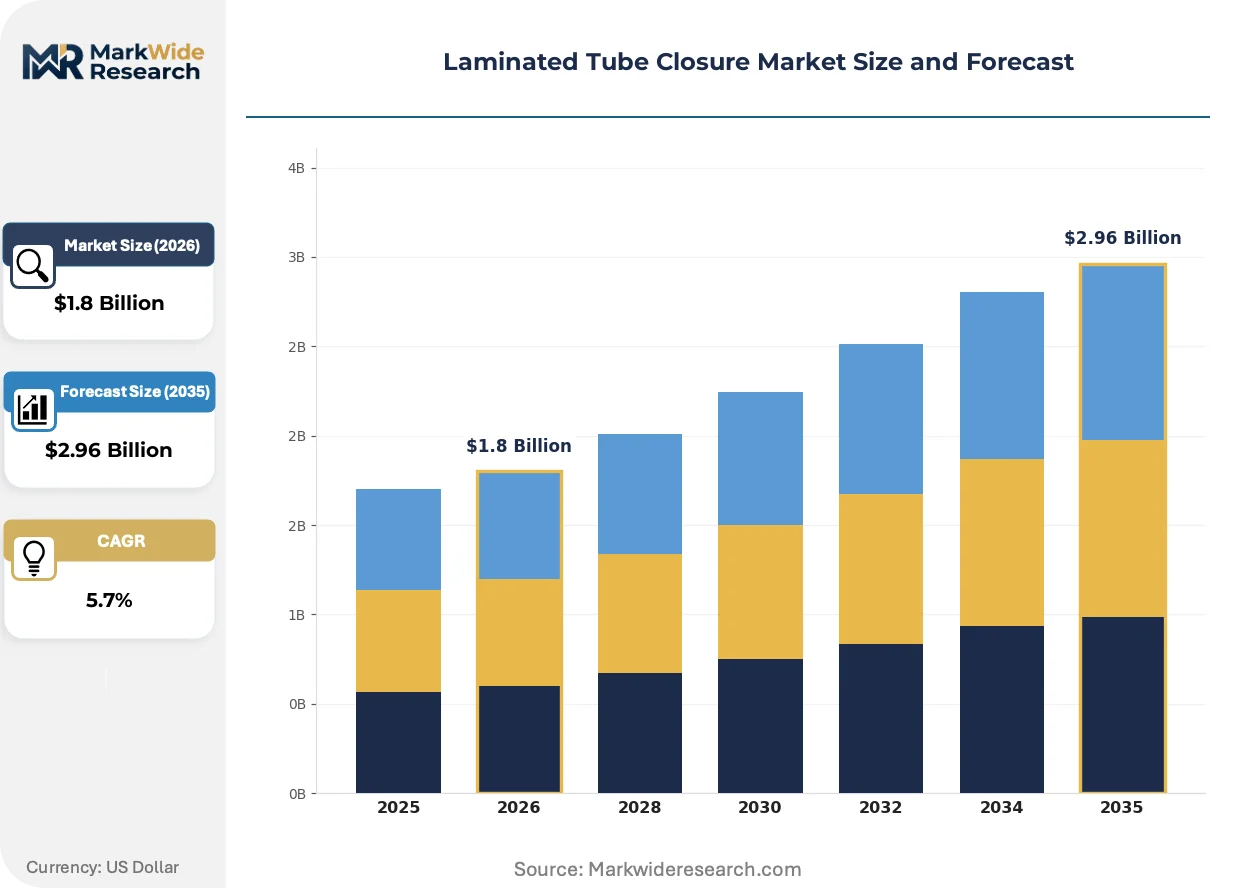
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
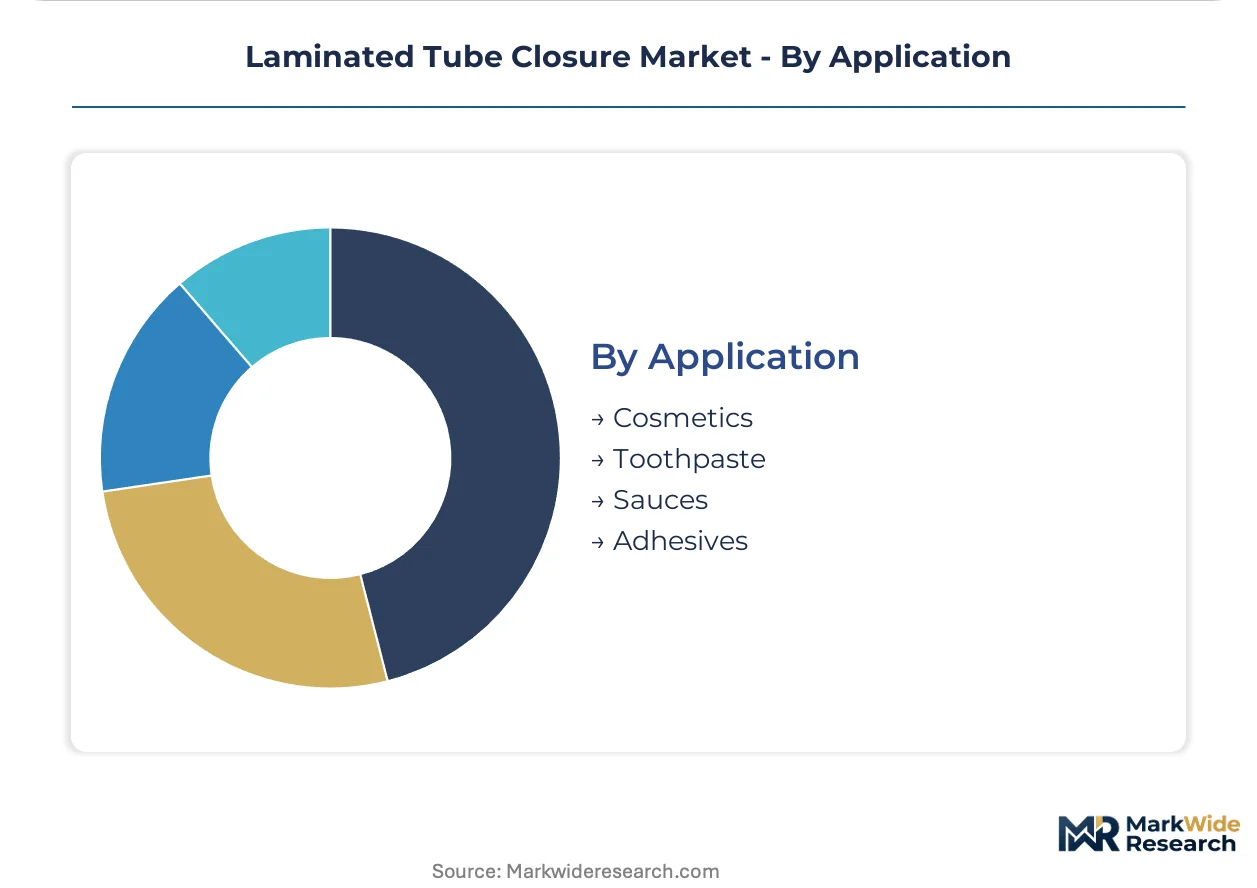
| Segmentation | Closure Type: Screw Cap, Flip Top, Snap On, Push-Pull Material: Plastic, Aluminum, Composite, Metal End User: Pharmaceutical, Personal Care, Food & Beverage, Household Application: Cosmetics, Toothpaste, Sauces, Adhesives |
| Companies Covered | Amcor Plc, Berry Global Inc., Albea Group, Essel Propack Ltd., IntraPac International, CCL Industries, Silgan Holdings Inc., AptarGroup, Inc., Hoffmann Neopac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminated Tube Closure Market Shifts & Advancements
Closure engineering is pivoting toward modular platform architectures that accommodate applicator tip integration, tamper-evident band variants, and dispensing orifice customization within standardized shoulder interfaces.
Biopolymer closure compounds with mechanical properties matching fossil-based polypropylene are consolidating specification positions in European personal care portfolios. Essel Propack and Albea Group formulation teams have validated polylactic acid blends for screw-cap applications with torque-release parameters within 5% of conventional resin performance. This material transition is consolidating procurement criteria around certified compostability credentials rather than virgin resin cost benchmarks.
EU MDR device labeling rules and FDA pharmaceutical primary packaging guidance are tightening closure design flexibility for topical drug applications. The European Medical Device Regulation now classifies certain medicated cream tubes as Class IIa devices, imposing traceability and biocompatibility testing burdens on closure suppliers. Pharmaceutical contract manufacturers are responding by qualifying single-source closure platforms with pre-submitted drug master files to accelerate regulatory submission timelines.
Brand procurement teams are consolidating supplier relationships around integrated laminate-to-closure manufacturing partners capable of shoulder-thread torque optimization and barrier-seal validation as a single deliverable. This specification bundling is displacing discrete component sourcing models where tube converters and closure molders operated at arm's length. Oral care multinationals in Germany and the United States are most advanced in this transition, with personal care brands in India and Brazil following at 18-24 month lag intervals.
Laminated Tube Closure Market Segmentation

Laminated tube closure procurement splits sharply between high-volume oral care contracts and precision pharmaceutical specifications. Material substitution pressures and dispensing ergonomics are redefining how converters prioritize torque performance against unit cost targets.
Closure Type:
Flip-top configurations dominate oral care volume while screw-cap formats retain pharmaceutical preference for tamper-evident security.
- Flip Top:Injection-molded polypropylene shells with integrated living hinges enable one-hand dispensing. Toothpaste manufacturers in Germany and India specify this format for shelf differentiation and consumer convenience metrics.
- Screw Cap:Threaded closure systems with specified torque-release windows ensure barrier integrity across temperature cycling. Pharmaceutical contract manufacturers favor this format for topical drug applications requiring child-resistant compliance.
- Snap On:Press-fit closures with audible engagement feedback suit single-use cosmetic samples and travel-size personal care tubes.
- Push-Pull:Dual-position orifice control mechanisms concentrate in adhesive and sealant applications requiring precise flow regulation.
Today's leader: Flip Top. Tomorrow's challenger: Screw Cap.
Material:
Plastic compounds anchor volume economics while composite laminates capture sustainability-driven specification shifts.
- Plastic:Polypropylene and polyethylene homopolymer formulations deliver torque consistency at scale. Resin cost volatility compresses margin capture for undifferentiated commodity grades without volume offsets.
- Composite:Multi-layer structures combining polymer shells with metallized or EVOH barrier films enable aluminum reduction without oxygen transmission penalties. European cosmetic brands specify this material for EPR compliance and circular economy claims.
- Aluminum:Rolled metal shells with polymer liner systems retain dominance in oxygen-sensitive pharmaceutical formulations where barrier performance is non-negotiable.
- Metal:Stamped steel and aluminum closures with over-molded polymer grips target prestige cosmetic lines requiring tactile differentiation.
Plastic commands current volume. Composite structures are climbing the fastest.
End User:
Pharmaceutical qualification timelines stretch procurement cycles while personal care brands compress supplier selection windows.
- Pharmaceutical:FDA primary packaging guidance and EU MDR device classification impose 12-18 month validation cycles on closure suppliers. Topical cream and transdermal patch applications require biocompatibility documentation and drug master file submissions.
- Personal Care:Cosmetic and skincare brands in France and Italy prioritize lightweight closure designs that reduce eco-modulation fees under extended producer responsibility frameworks.
- Food & Beverage:Condiment and sauce manufacturers specify oxygen barrier closures with flavor scalping resistance for extended shelf-life targets.
- Household:Adhesive and cleaning product brands emphasize chemical resistance and child-resistant functionality over aesthetic refinement.
Personal Care drives unit volume. Pharmaceutical commands specification premiums.
Application:
Toothpaste dispensing convenience sets ergonomic standards that adjacent categories increasingly reference.
- Toothpaste:Flip-top configurations with 22-24mm shoulder interfaces constitute the largest single application segment. Multinational oral care brands consolidate procurement around integrated laminate-to-closure suppliers.
- Cosmetics:Prestige skincare and color cosmetic tubes demand metal-over-shell closures with custom metallization and soft-touch overmolding for shelf presence.
- Sauces:Food-grade polypropylene closures with vented dispensing orifices address viscosity variation across ketchup, mayonnaise, and condiment formulations.
- Adhesives:Precision orifice control and chemical resistance specifications dominate procurement criteria for construction and industrial sealant applications.
Toothpaste anchors scale economics. Cosmetics delivers margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered high-volume laminated tube closure manufacturing in the 1960s, establishing injection molding standards that persist across European pharmaceutical packaging. Today, production clusters span four continents with regulatory divergence reshaping material specifications and procurement patterns.
United States
Oral care multinationals headquartered in Cincinnati and New York drive specification standardization for flip-top configurations. FDA pharmaceutical primary packaging guidance imposes biocompatibility documentation burdens on closure suppliers serving topical drug manufacturers. Chicago-area injection molders maintain captive capacity for high-torque screw-cap formats serving contract pharmaceutical packagers.
Germany
REACH chemical authorization deadlines are accelerating laminate reformulation investments among polymer compounders in the Rhine-Ruhr industrial corridor. ECHA phthalate restrictions in polymer formulations favor certified closure suppliers with pre-validated material portfolios. Essen-based integrated laminate-to-closure manufacturers anchor contract positions with multinational toothpaste brands across European markets.
India
Domestic personal care brand proliferation around Mumbai and Ahmedabad generates contract manufacturing demand for localized torque-release specifications. CDSCO pharmaceutical packaging standards extend validation timelines for topical drug applications requiring child-resistant functionality. Gujarat-based manufacturing clusters capture rising demand from regional brand expansions into Southeast Asian export markets.
China
Yangtze River Delta packaging converters are scaling composite material closure production to serve European cosmetic brand sustainability mandates. NMPA pharmaceutical packaging regulations align gradually with ISO 15378 quality management standards, compressing supplier qualification windows. Zhejiang-based molders invest in high-cavitation injection equipment to offset resin cost volatility through scale economics.
Brazil
ANVISA pharmaceutical packaging regulations create compliance barriers for imported closure formats lacking local torque-validation testing. São Paulo-state personal care manufacturers prioritize lightweight designs to reduce logistics costs across continental distribution networks. Campinas industrial park hosts regional conversion capacity for flip-top configurations serving Mercosur oral care markets.
Laminated Tube Closure Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and integrated manufacturing scope. The vendor base stratifies between multinational laminate-to-closure integrators, specialized pharmaceutical-grade molders, and regional commodity converters. Three archetypes dominate: integrated packaging conglomerates with captive resin compounding, mid-cap specialists with ISO 15378 pre-certification, and emerging-market fabricators competing on unit cost. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with pharmaceutical qualification timelines favoring incumbent retention over supplier switching.
Within the integrated conglomerate tier, Amcor Plc and Berry Global Inc. exemplify scale-driven positioning through captive injection molding networks spanning multiple continents. Albea Group occupies a specialty position representing metal-over-shell closure expertise targeting prestige cosmetic lines. Essel Propack Ltd. anchors the emerging-market integration archetype, leveraging laminate-to-closure manufacturing footprints to secure contract manufacturing relationships with multinational oral care brands.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Albea Group |
| Essel Propack Ltd. |
| IntraPac International |
| CCL Industries |
| Silgan Holdings Inc. |
| AptarGroup, Inc. |
| Hoffmann Neopac |
| Others |
Supply & Pricing Matrix
ISO 15378 certification tiers split procurement economics between validated pharmaceutical-grade suppliers and commodity converters serving personal care brands. This bifurcation concentrates pricing power with pre-certified molders in Germany and the United States while compressing margins for undifferentiated polypropylene closure producers in India and China.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors laminated tube closure procurement. Premium tiers capture ISO 15378 certification and REACH-compliant material documentation; standard tiers trade on volume scale and torque consistency; economy tiers compete on resin cost alone. Price differentiation hinges on certification depth and captive compounding capability. Margins are tightening due to polypropylene input volatility. Pharmaceutical contract manufacturers show least price sensitivity; regional personal care brands in Southeast Asia show most.
Supply Chain Analysis
Direct-to-OEM channels handle multinational oral care brand demand while distributor networks serve mid-tier cosmetic converters. Supply concentrates in Germany, the United States, and India for high-cavitation injection molding. Raw material flows draw from Saudi Arabian polypropylene feedstock, Belgian EVOH barrier films, and Chinese metallized substrates. Single-source vulnerability concentrates around German molders with captive torque-validation equipment. Distribution runs through integrated laminate-to-closure partners rather than discrete component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laminated tube closure market compounds steadily as pharmaceutical packaging regulations permanently elevate compliance investment thresholds. Oral care and topical drug delivery expansion provides durable demand underpinning.
For Market Incumbents: Anticipate resin cost volatility and REACH authorization deadlines by securing backward integration into certified polymer compounding. Prioritize capacity expansion in Gujarat and Zhejiang to capture regional brand procurement consolidation. Defend against emerging biopolymer specialists by accelerating TUV Austria OK Compost certification timelines. For New Entrants and Emerging Players: Capture underpenetrated topical drug delivery segments requiring child-resistant torque specifications and drug master file submissions. Target Brazilian and Southeast Asian markets where ANVISA and CDSCO validation requirements create incumbent retention risk. Lead with ISO 15378 pre-certification to compress pharmaceutical supplier qualification windows. For Investors and Strategic Acquirers: Consolidation pressure builds where pharmaceutical qualification timelines and EPR compliance burdens outstrip mid-cap investment capacity. Five-to-ten-year viability favors integrated laminate-to-closure platforms with captive shoulder-thread optimization. Watch biopolymer certification adoption curves in European cosmetic lines as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Pre-Certification Investment | Compresses 12-18 month pharmaceutical validation cycles for topical drug closure suppliers. |
| Backward Integration into Polymer Compounding | Captures margin from resin volatility while securing REACH-compliant material documentation. |
| Biopolymer Certification Program Enrollment | Opens premium positioning channels under French and Italian EPR eco-modulation frameworks. |
| Integrated Laminate-to-Closure Manufacturing Expansion | Displaces discrete component sourcing for multinational toothpaste brand procurement consolidation. |
| Child-Resistant Closure Platform Development | Addresses underpenetrated transdermal patch and medicated cream torque-performance specifications. |
Research Methodology
Direct dialogue with injection molding plant managers, pharmaceutical packaging procurement leads, cosmetic brand supply planners, and regulatory affairs directors grounded qualitative findings. Secondary validation drew from FDA guidance documents, ECHA authorization registers, CDSCO packaging standards, and customs trade data for polypropylene and EVOH flows. Bottom-up and top-down triangulation cross-checked volume estimates against resin consumption patterns and end-use brand procurement disclosures.
Top-down macroeconomic modeling anchored demand projections while bottom-up segment analysis traced closure format adoption across oral care, pharmaceutical, and personal care portfolios. Segmentation dimensions included closure type, material compound, end-use vertical, and regional regulatory cluster. CAGRs derived from curve-fitting historical shipment data against pharmaceutical packaging investment cycles and personal care brand expansion patterns. Forecast inputs incorporated REACH authorization timelines and EPR framework implementation schedules.
Underlying measurement precision varies by segment; pharmaceutical-grade closures carry tighter precision than commodity personal care formats due to validated supplier concentration. Forecasts reflect assumptions around regulatory compliance cost trajectories and biopolymer mechanical property convergence timelines. Periodic stress-testing of base assumptions is recommended against resin price volatility and EPR fee modulation updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Poland Plastic Caps and Closures Market
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
PCR Closures Market
Caps and Closures
Low Profile Compact System Closures Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Smooth Hinge Caps and Closure Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Buttress Closures Market
Caps and Closures
Hinged Dispensing Caps Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Spouted Dispensing Closures Market