
 Ribbed Closures Market | 2026-2036
Ribbed Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Ribbed Closures Market Analytics
Polypropylene is shifting into ribbed closure formulations as converters seek alternatives to polystyrene amid resin volatility. Berry Global Group leverages captive resin compounding across North American plants to stabilize input costs. Amcor sustains technology leadership through advanced injection molding platforms for pharmaceutical-grade closures. Guala Closures Group anchors European supply through specialized tamper-evident designs for spirits and wine applications.
Ribbed closures are threaded dispensing and sealing devices featuring external circumferential ridges that enhance grip torque and facilitate automated capping line engagement, typically manufactured through injection or compression molding in diameters ranging from 18mm to 89mm. Plastic closures dominate volume through cost-efficient polyolefin platforms, while metal segments retain premium positioning in carbonated beverage and spirits applications where oxygen ingress control determines shelf life. Injection molding technology leads throughput economics for high-volume food and beverage contracts, whereas compression molding commands pharmaceutical and personal care segments requiring tighter dimensional tolerances for child-resistant mechanisms.
FDA 21 CFR regulations for child-resistant packaging and EU MDR device labeling requirements directly shape closure design specifications and testing protocols for pharmaceutical applications. REACH compliance and evolving EFSA food contact material assessments constrain additive formulations and migration limits across European supply chains. ISO 8317 child-resistant standards and forthcoming packaging waste directives in multiple jurisdictions will force stakeholders to recertify existing product lines while evaluating mono-material designs for recyclability compliance.
Market Dynamics
EU MDR child-resistant mandates and FDA 21 CFR packaging standards are forcing pharmaceutical closure manufacturers to retool entire production lines for tamper-evident certification, compressing supplier qualification timelines and concentrating orders among molders with validated cleanroom capabilities.
Growth Catalysts
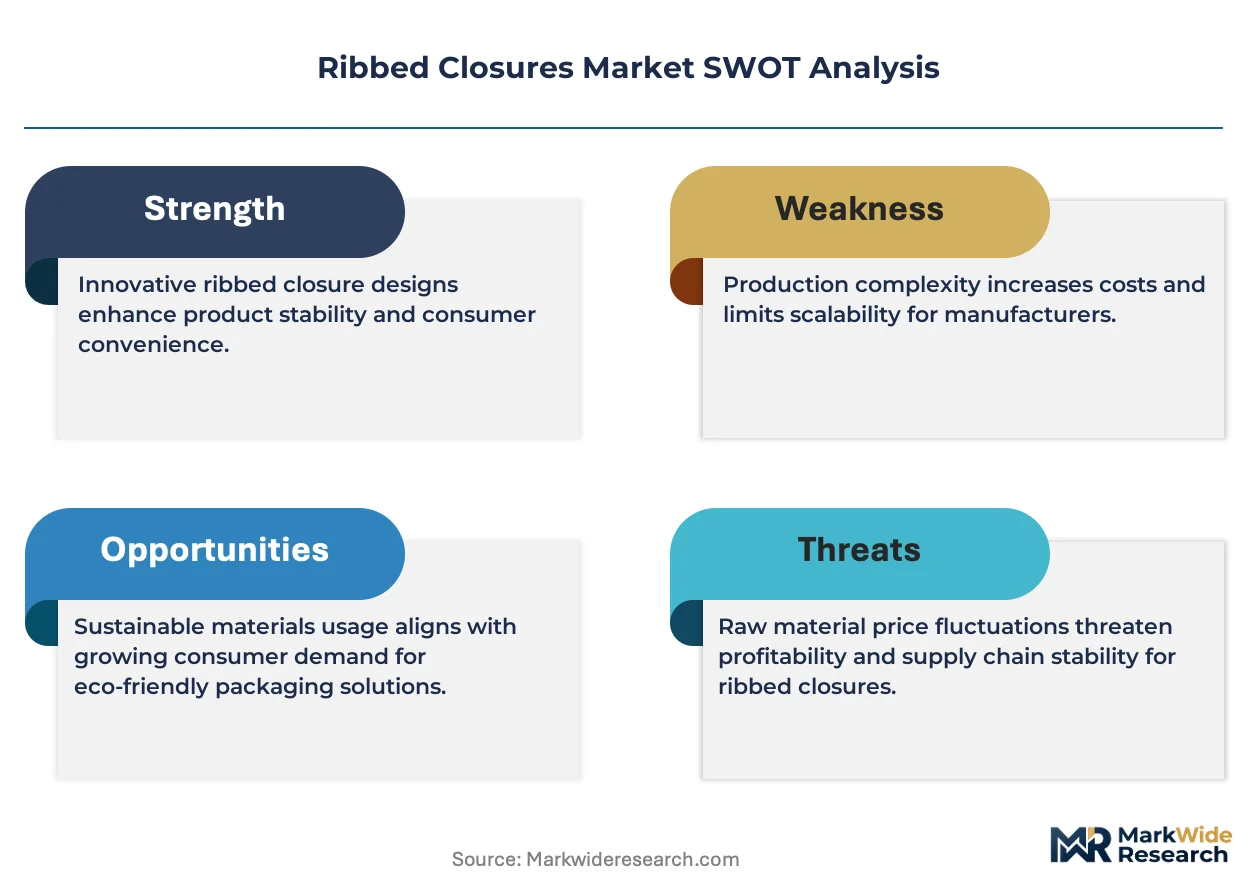
- EU MDR device labeling mandates:Pharmaceutical packagers must upgrade to tamper-evident ribbed closures, pulling demand toward certified European molders with validated cleanroom injection platforms.
- Polypropylene resin substitution:Converters are reformulating away from polystyrene amid price volatility, expanding addressable volume for polyolefin closure specialists with captive compounding assets.
- Germany precision molding clusters:Bavarian and Baden-Württemberg tooling hubs serve pan-European pharmaceutical and cosmetics brands with sub-0.1mm dimensional tolerance capabilities.
Market Restraints
- Propylene monomer cost volatility:Crude-linked feedstock swings compress converter margins and destabilize annual contract pricing for high-volume beverage accounts.
- Chinese virgin resin oversupply:State-subsidized polyolefin capacity floods Asian export markets, eroding price floors for European and North American domestic producers.
- Compression molding throughput ceiling:Pharmaceutical-grade dimensional tolerances require slower cycle times than injection alternatives, capping unit economics for child-resistant closure contracts.
Strategic Opportunities
- Indian pharmaceutical packaging expansion:CDSCO serialization mandates and rising domestic generic drug output create demand for certified child-resistant closures with integrated tamper-evident bands.
- Mono-material recyclable designs:EFSA food contact assessments and forthcoming EU packaging waste directives favor single-polymer closure-body-liner systems over multi-component assemblies.
- Direct-to-brand e-commerce channels:Small-batch craft spirits and cosmetics startups are bypassing traditional distributor networks, creating demand for low-MOQ custom ribbed closure programs.
Industry Challenges
- ISO 8317 recertification timelines:Child-resistant testing protocol updates require 12-18 month revalidation cycles, freezing product development pipelines and delaying contract awards.
- Multi-cavity mold commissioning costs:Pharmaceutical-grade 32-cavity injection tools with hot-runner systems demand capital deployment exceeding mid-tier converter balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ribbed Closures Market |
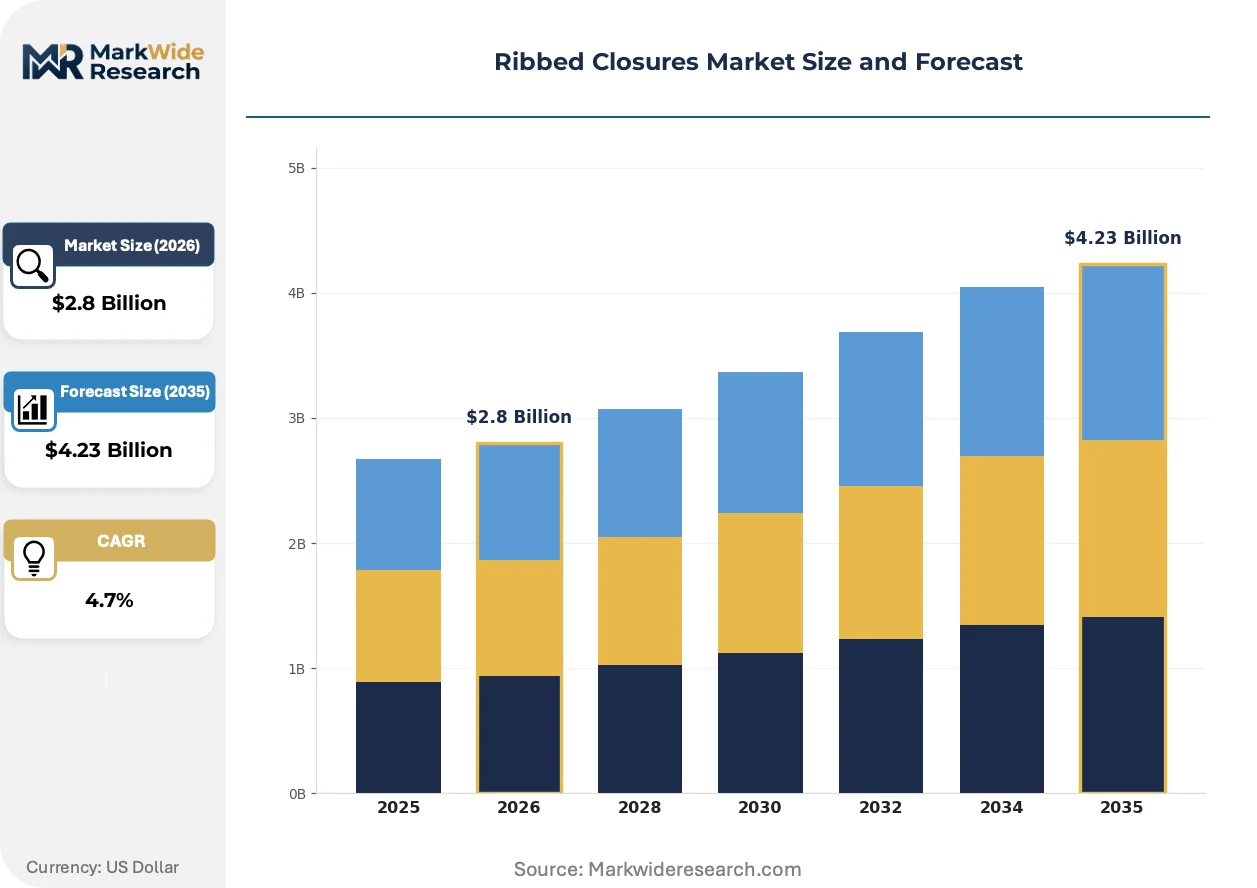
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Glass, Composite End User: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Technology: Injection Molding, Compression Molding, Extrusion, Blow Molding Size: Small, Medium, Large, Custom |
| Companies Covered | Berry Global Group, Amcor, MJS Packaging, Alpha Packaging, Gosselin Group, Olcott Plastics, Mold-Rite Plastics, Phoenix Closures, Guala Closures Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ribbed Closures Market Evolving Landscape
Digital manufacturing workflows and polymer formulation advances are compressing product development cycles while regulatory pressure on recyclability is reshaping material selection criteria across pharmaceutical and beverage end-uses.
Digital mold simulation coupled with real-time cavity pressure monitoring is decentralizing quality control from centralized metrology labs to production floor feedback loops. Pharmaceutical contract packagers in Germany and Switzerland are adopting these platforms to cut first-article approval times. The technology is decentralizing validation authority from third-party certification bodies toward manufacturer-integrated process analytical technology systems.
REACH Annex XVII restrictions on intentionally added microplastics are constraining additive packages in European food-contact closures. EFSA migration limit reassessments for certain plasticizers are forcing reformulation of liner compounds in tamper-evident bands. Personal care brands with pan-European distribution are responding by accelerating mono-material polypropylene closure-body development to simplify compliance documentation.
Brand procurement teams are consolidating closure specifications across regional SKU portfolios to reduce supplier qualification overhead. Beverage multinationals are shifting from country-specific closure designs toward continental platform standards, compressing mold inventory requirements. This consolidation pattern is most visible in North American carbonated soft drink and spirits categories where parent companies are rationalizing legacy diameter variations.
Ribbed Closures Market Segmentation
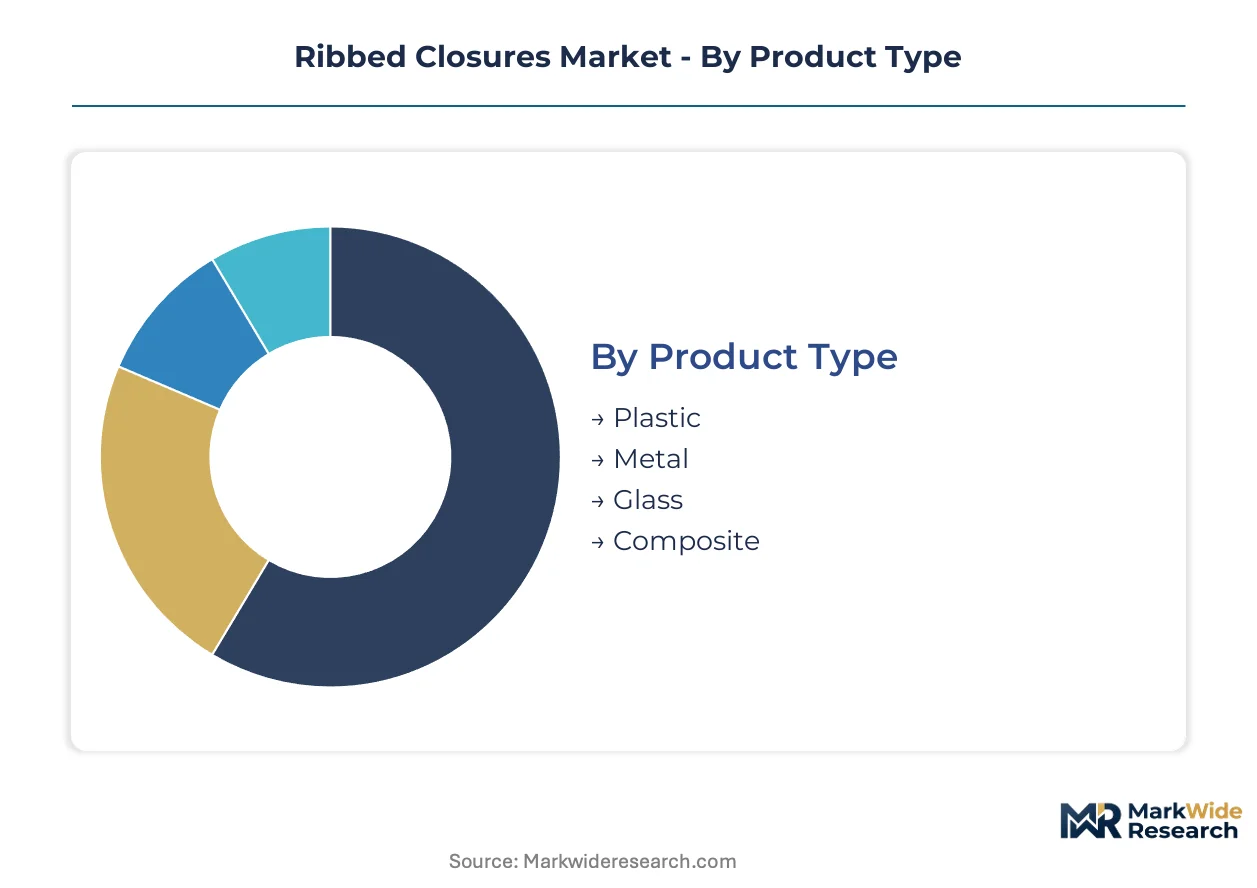
Ribbed closure specifications diverge sharply across pharmaceutical certification requirements and beverage throughput economics. Material selection and molding technology choices determine which converters can serve regulated versus commodity end-uses.
Product Type:
Upgrade cycles from polystyrene to polyolefin platforms are redrawing material tier boundaries as converters seek resin cost stability.
- Plastic:Polypropylene and polyethylene formulations dominate pharmaceutical and food applications through injection-molded precision. German precision molding clusters in Bavaria supply tamper-evident designs to EU pharmaceutical packagers facing MDR compliance deadlines.
- Metal:Aluminum and steel closures retain premium positioning in carbonated beverages and spirits where oxygen ingress control determines shelf life. Crown cork derivatives with ribbed sidewalls serve European wine and champagne houses requiring controlled release mechanisms.
- Glass:Ceramic and glass closures occupy niche premium cosmetics and artisanal spirits segments where tactile weight signals quality positioning.
- Composite:Multi-material assemblies combining plastic bodies with metal liners serve child-resistant pharmaceutical applications requiring dual-performance characteristics.
Volume placements concentrate in Plastic; the faster expansion belongs to Metal as spirits producers revive traditional closure aesthetics.
End User:
Customer procurement patterns split between regulated pharmaceutical qualification protocols and high-volume beverage contract economics.
- Food & Beverage:Carbonated soft drink and bottled water producers drive throughput demands with 28mm and 38mm standard diameters. North American bottlers consolidate SKU specifications across continental platforms to compress mold inventory requirements.
- Pharmaceuticals:Child-resistant and tamper-evident designs command premium positioning through FDA 21 CFR and EU MDR certification requirements. Swiss and German contract packagers source from molders with validated cleanroom injection capabilities.
- Personal Care:Cosmetics brands favor ribbed closures with ergonomic grip profiles for serum and lotion dispensing applications.
- Household Products:Cleaning chemical containers require chemical-resistant polypropylene formulations with vented liner systems.
Contract values peak in Pharmaceuticals; the steepest expansion trajectory sits in Personal Care as direct-to-brand e-commerce channels proliferate.
Technology:
Capital deployment thresholds separate pharmaceutical-grade precision molders from commodity beverage converters.
- Injection Molding:High-cavity hot-runner systems deliver economies of scale for food and beverage volumes exceeding 100 million units annually. Berry Global Group deploys captive resin compounding across North American plants to stabilize input costs for this platform.
- Compression Molding:Slower cycle times achieve tighter dimensional tolerances required for ISO 8317 child-resistant mechanisms. Amcor sustains technology leadership through advanced platforms serving pharmaceutical-grade specifications.
- Extrusion:Continuous profile forming serves specialty liner and seal gasket production for multi-component closure assemblies.
- Blow Molding:Hollow-body forming accommodates integrated dispensing features in personal care flip-top designs.
Equipment utilization rates favor Injection Molding; margin sustainability depends on Compression Molding certification depth.
Size:
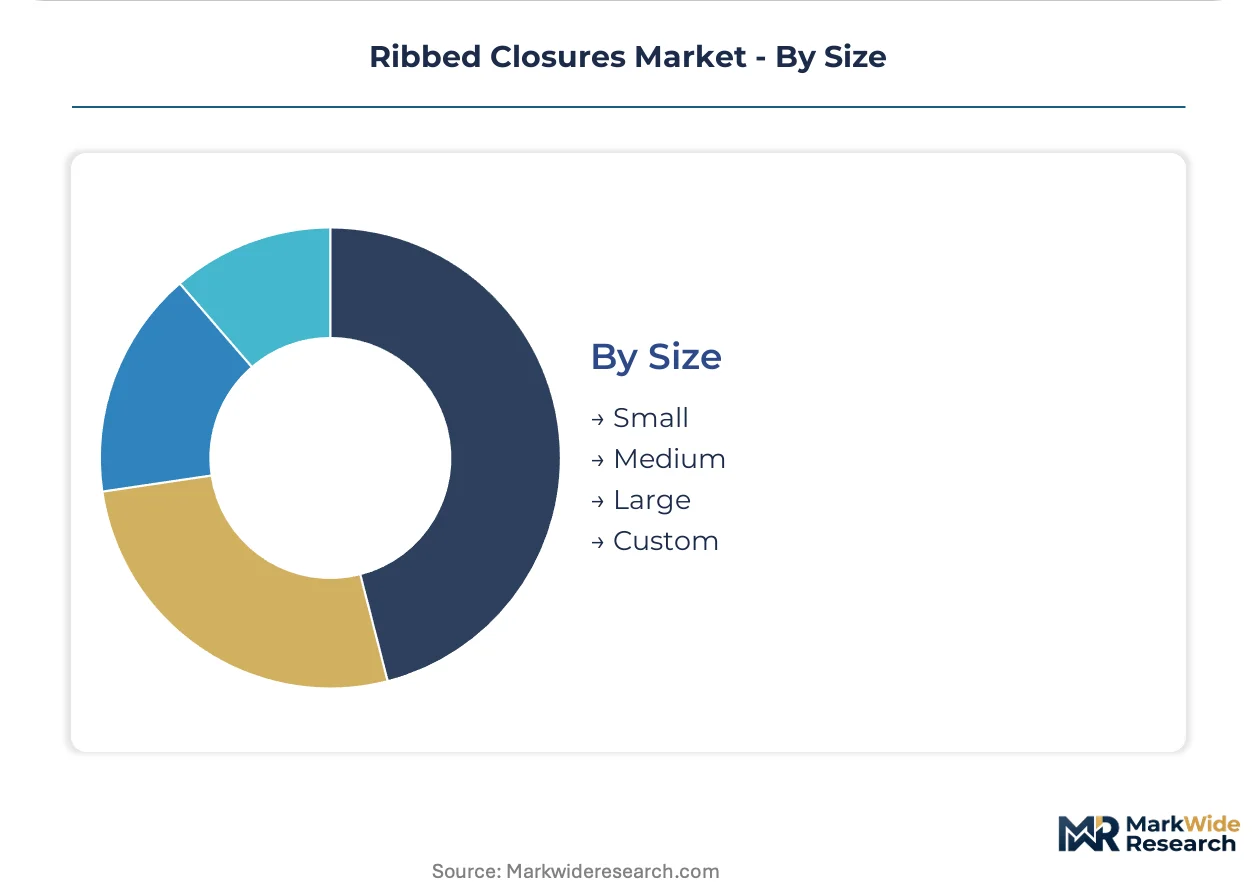
Diameter standardization pressures are compressing custom specification demand as brand procurement teams consolidate portfolios.
- Small:18mm to 24mm diameters serve pharmaceutical vials and essential oil containers with precision thread engagement.
- Medium:28mm to 38mm specifications dominate beverage and personal care applications with established capping line compatibility.
- Large:53mm to 89mm closures accommodate wide-mouth jars in nutraceutical and household chemical segments.
- Custom:Non-standard diameters and proprietary thread profiles serve craft spirits and luxury cosmetics brands seeking differentiation.
Procurement consolidation is squeezing Custom specifications; Medium diameters capture the greatest placement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical packaging demand concentrates in Germany, where precision molding clusters supply tamper-evident closures across European markets. Beverage and spirits applications anchor secondary demand centers in North America and select Asian manufacturing hubs.
Germany
Bavarian and Baden-Württemberg tooling hubs serve pan-European pharmaceutical brands with sub-0.1mm dimensional tolerance capabilities. EU MDR device labeling mandates force packagers to upgrade closure specifications, pulling orders toward certified molders with validated cleanroom injection platforms. Stuttgart-area converters specialize in child-resistant mechanisms for prescription drug containers.
United States
FDA 21 CFR packaging standards drive pharmaceutical closure qualification protocols, compressing supplier timelines among contract packagers. Berry Global Group leverages captive resin compounding across North American plants to stabilize input costs for high-volume beverage accounts. Chicago and New Jersey corridor molders dominate carbonated soft drink closure supply.
India
CDSCO serialization mandates and rising domestic generic drug output create demand for certified child-resistant closures with integrated tamper-evident bands. Mumbai and Ahmedabad pharmaceutical packaging corridors expand molding capacity to serve export markets. Domestic converters invest in ISO 8317 testing infrastructure to accelerate certification cycles.
Switzerland
Swissmedic pharmaceutical regulations enforce stringent closure performance standards for prescription and over-the-counter medications. Basel-area contract packagers source precision-molded closures from adjacent German and domestic suppliers. Swiss precision engineering traditions translate into tight quality tolerances for high-value pharmaceutical applications.
China
SAMR food contact material assessments and evolving GB standards constrain additive formulations for closure exports to Western markets. State-subsidized polyolefin capacity floods Asian export channels, pressuring price floors for European and North American producers. Zhejiang and Guangdong molding clusters serve domestic beverage brands with cost-optimized 28mm and 38mm specifications.
Ribbed Closures Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade certification depth determining supplier concentration in regulated end-uses. The vendor base organizes into three strategic archetypes: integrated resin-to-closure conglomerates with captive compounding assets, precision molding specialists serving pharmaceutical qualification protocols, and regional fabricators competing on turnaround speed for custom specifications. Capacity expansion and portfolio diversification toward mono-material recyclable designs represent the dominant competitive moves as EFSA assessments and EU packaging waste directives reshape material selection criteria.
Among integrated packaging conglomerates, Berry Global Group and Amcor exemplify the scale-driven archetype with captive resin operations and multi-continental manufacturing footprints. Guala Closures Group occupies a specialized position within the premium spirits and wine closure segment, representing European design-led differentiation. These three entities anchor distinct competitive vectors—resin integration, pharmaceutical certification depth, and brand-aligned aesthetics—rather than competing directly across identical specification ranges.
| Leading Market Players |
|---|
| Berry Global Group |
| Amcor |
| MJS Packaging |
| Alpha Packaging |
| Gosselin Group |
| Olcott Plastics |
| Mold-Rite Plastics |
| Phoenix Closures |
| Guala Closures Group |
| Others |
Value Network & Pricing Analysis
Precision mold engineering talent clusters in Bavaria and Baden-Württemberg create labor-cost differentials that widen pricing spreads between pharmaceutical-grade and commodity beverage closures. German toolmakers command premium rates for sub-0.1mm tolerance capabilities, while Asian fabricators compete on turnaround speed for standard 28mm and 38mm specifications.
Pricing Analysis
High-volume beverage contracts trade on razor-thin unit margins, while pharmaceutical-grade child-resistant closures capture substantial premiums through FDA 21 CFR and EU MDR certification requirements. Price differentiation hinges on cleanroom validation depth and ISO 8317 testing infrastructure. Cost compression in commodity polypropylene closures is intensifying because Chinese state-subsidized resin capacity floods export channels. Generic drug packagers in India exhibit the highest price sensitivity; Swiss and German pharmaceutical brands prioritize certification reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Chicago, and Mumbai orchestrate hub-and-spoke patterns that position inventory close to pharmaceutical packaging corridors. Manufacturing concentrates in Germany, the United States, and China, with each hub serving distinct certification tiers. The supply chain draws from propylene monomer feedstocks, precision mold tooling, and hot-runner system components. Single-source vulnerability looms for pharmaceutical-grade cleanroom molding capacity. Distribution runs through converter-direct and distributor-mediated channels, with large beverage multinationals favoring direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cleanroom injection molding capacity operates as the binding constraint, propping pricing power for certified European suppliers serving EU MDR compliance deadlines.
For Market Incumbents: Deepen backward integration into captive resin compounding to buffer propylene monomer volatility. Expand multi-cavity mold commissioning partnerships in Germany to defend against emerging Indian converters building ISO 8317 testing infrastructure. Certification investment represents the critical lever for margin preservation. For New Entrants and Emerging Players: CDSCO serialization mandates in India open a window for certified child-resistant closure supply to domestic generic drug manufacturers. Target the direct-to-brand e-commerce channel for craft spirits and cosmetics startups requiring low-MOQ custom programs. Pursue toll manufacturing arrangements with established German toolmakers to bypass capital-intensive mold ownership. For Investors and Strategic Acquirers: Re-rating potential sits with precision molding specialists possessing validated pharmaceutical-grade capabilities given EU MDR device labeling mandates. The five-to-ten year viability window favors converters with mono-material recyclable design pipelines. Watch EFSA migration limit reassessments as the inflection signal for liner compound reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Injection Platform Expansion | EU MDR compliance deadlines pull orders toward certified German molders with validated capabilities. |
| Captive Resin Compounding Investment | Berry Global Group stabilizes input costs across North American beverage accounts through backward integration. |
| Mono-Material Closure Development | REACH Annex XVII restrictions on microplastics accelerate polypropylene-only tamper-evident designs. |
| ISO 8317 Testing Infrastructure Buildout | Indian converters in Mumbai and Ahmedabad compress certification cycles for export market access. |
| Direct-to-Brand E-Commerce Channel Entry | Craft spirits startups bypass traditional distributors, creating demand for low-MOQ custom ribbed programs. |
Research Methodology
Independent corroboration across converter production data, pharmaceutical packager procurement records, and resin trade flow statistics underwrites the qualitative findings. Primary interviews engaged injection molding plant managers, pharmaceutical regulatory affairs leads, beverage category procurement directors, and precision tooling engineers. Secondary validation drew from FDA 21 CFR filings, EMA MDR submission databases, EU customs polyolefin trade records, and REACH Annex XVII restriction updates. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the analysis window.
Comparable-period anchoring linked the projection horizon to historical pharmaceutical packaging output cycles and beverage industry capital expenditure patterns. The analytical framework modeled segmentation across material grade tiers, end-use certification requirements, molding technology platforms, and regional regulatory clusters. CAGRs derived from trend extrapolation of resin substitution patterns and compliance-driven upgrade cycles. Forecast inputs incorporated propylene monomer price volatility indices and pharmaceutical packaging line automation rates.
Caveats apply where EU packaging waste directive finalization or EFSA migration limit reassessments could materially shift the outlook. Forecasts reflect documented assumptions regarding certification timeline stability and resin supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
Aerosol Caps Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Dispensing Spouts Market
Caps and Closures
Dropper Caps Market
Caps and Closures
Disc Top Caps Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
Low Profile Compact System Closures Market
Caps and Closures
Plastic Caps and Closure Market