
 Foamed End Caps Market | 2026-2036
Foamed End Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Foamed End Caps Market Foresight
Modular packaging configurations is shifting how industrial buyers specify protective components, with bundled foam-and-cradle systems replacing standalone commodity purchases. Sealed Air Corporation leverages its global manufacturing footprint to supply standardized end cap modules across multiple continents. Sonoco Products Company anchors its position through specialized molded foam solutions tailored to precision equipment sectors. Pregis Corporation differentiates via integrated film-and-foam offerings that combine surface protection with impact absorption in single-source contracts.
Foamed end caps are engineered cellular polymer closures manufactured through expansion molding or block-cutting processes, with densities typically ranging from 1 to 6 pounds per cubic foot to achieve controlled compression and recovery characteristics. These components serve primarily to seal pipe terminals, cushion packaged goods against mechanical shock, and dampen vibration in rotating machinery assemblies. Polyethylene formulations dominate volume demand due to their closed-cell moisture resistance and recyclability profile, while polyurethane grades command premium positioning in thermal insulation applications where lambda values below 0.025 W/m·K are specified. Polystyrene remains entrenched in cost-sensitive packaging protection segments despite regulatory pressure on residual monomer content. The application split reveals packaging protection as the mature revenue base, with pipe insulation and vibration damping representing faster-growing adjacencies tied to infrastructure and precision manufacturing investments.
The EPA regulates volatile organic compound emissions from foam manufacturing under Clean Air Act Title V permitting, while OSHA enforces workplace exposure limits for isocyanates in polyurethane production facilities. REACH restricts certain flame retardant additives in European polystyrene grades, compelling reformulation toward halogen-free alternatives. China's MEE implements dual carbon goals that elevate energy efficiency standards for industrial insulation materials. Stakeholders must monitor evolving chemical substance restrictions and carbon accounting requirements that will determine which foam chemistries retain market access across major economies.
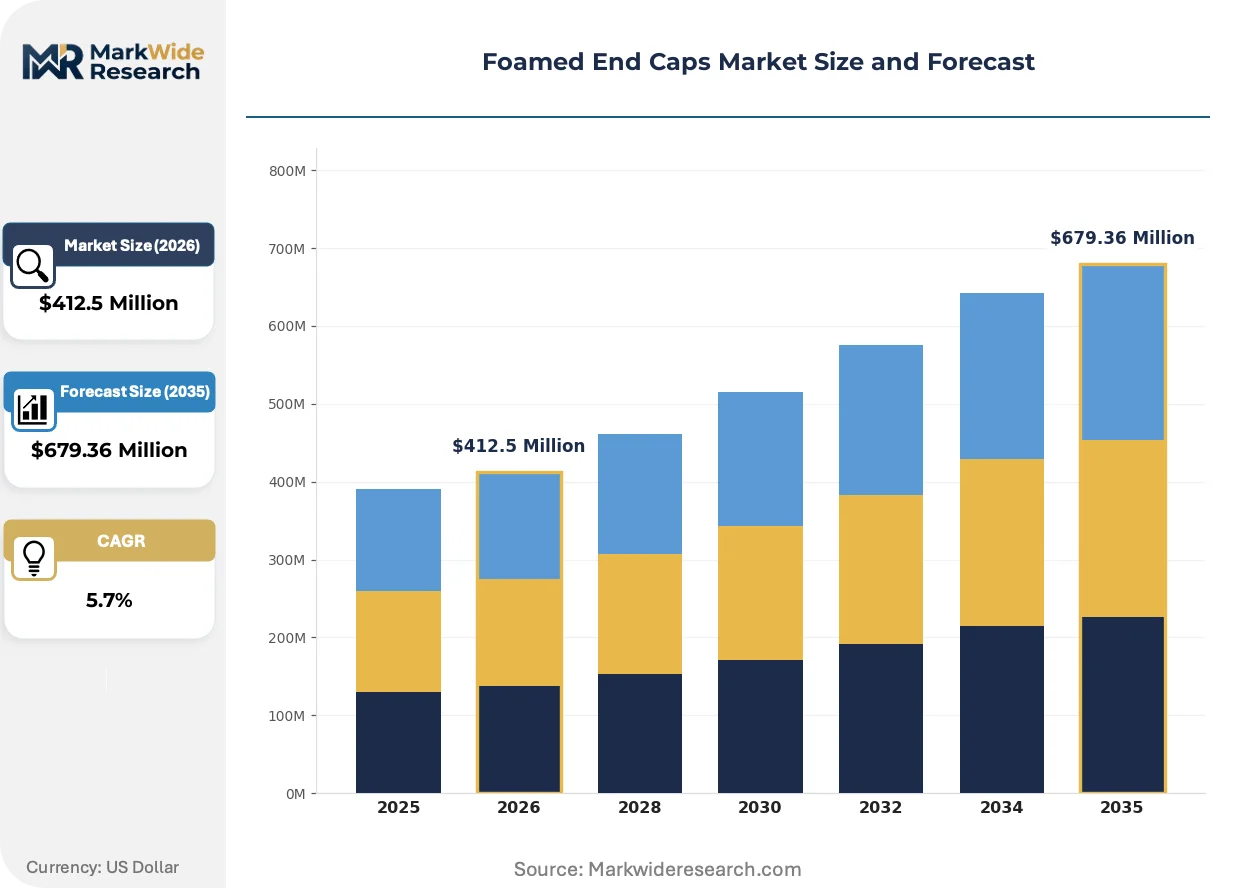
Market Dynamics
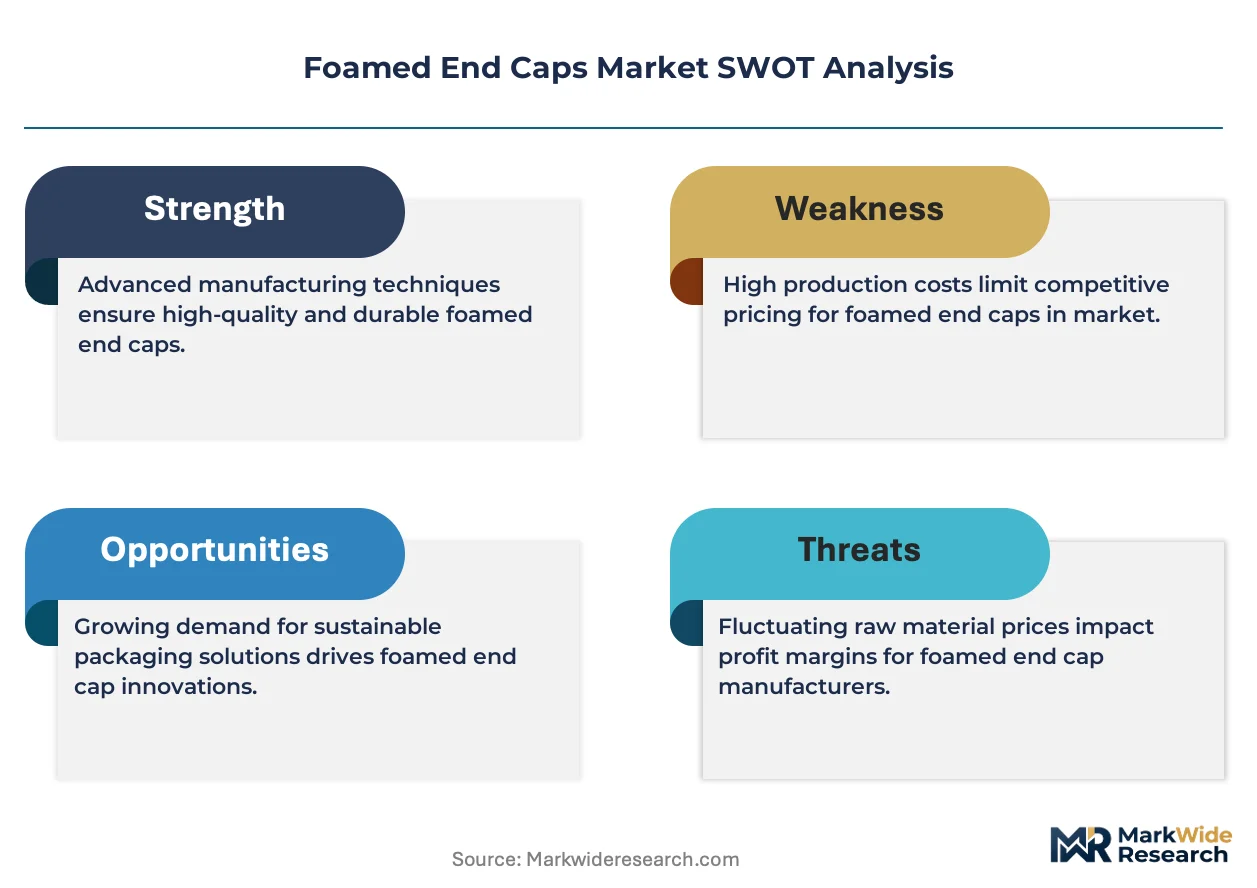
REACH compliance deadlines in Europe and EPA Title V permitting expansions in the United States are forcing polyethylene and polystyrene reformulations, compressing legacy chemistries while opening certified-alternative supply channels.
Growth Catalysts
- HVAC infrastructure investment:Germany, the United States, and China are accelerating pipe insulation deployments in commercial building retrofits and district heating networks, pulling foamed end cap demand into construction supply chains.
- REACH flame retardant restrictions:ECHA mandates on halogenated additives in polystyrene grades are accelerating halogen-free formulation adoption, creating first-mover advantages for compliant European compounders.
- Precision equipment packaging:Semiconductor and medical device manufacturers are specifying molded foam cradles with integrated end cap modules, bundling protection components into single-source contracts.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and benzene price swings compress margin predictability for polyethylene and polystyrene converters, forcing inventory risk onto smaller molders.
- Isocyanate supply concentration:Polyurethane precursor production clusters in the US Gulf Coast and northwest Europe expose foam manufacturers to weather-related disruption and force majeure events.
- Residual monomer limits:Polystyrene grades face technical ceilings on styrene reduction without sacrificing cell structure integrity, constraining regulatory compliance pathways.
Strategic Opportunities
- India industrial packaging:BIS certification requirements and PLI scheme incentives for electronics manufacturing are creating localized demand for protective foam components in Mumbai and Bengaluru corridors.
- Dual carbon goals in China:MEE energy efficiency mandates for building insulation are elevating lambda-rated polyurethane specifications in HVAC applications, opening premium positioning for thermal-performance foam grades.
- Film-foam convergence:Surface protection films laminated to molded end caps are displacing separate film-and-foam procurement, enabling single-source contract capture in precision logistics.
Industry Challenges
- Reformulation chemistry expertise:Halogen-free flame retardant compounding requires polymer scientists familiar with intumescent systems, a skill set concentrated at large compounders and scarce at regional molders.
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, and MEE compliance documentation extends product launch cycles by 8-14 months for cross-border foam suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foamed End Caps Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $679.36 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polyethylene, Polystyrene, EVA, Neoprene Application: Pipe Insulation, Packaging Protection, Vibration Damping, Electrical Insulation, Thermal Insulation End User Industry: Construction Contractors, Packaging Manufacturers, Electrical Equipment Producers, HVAC Technicians, Marine Fabricators Distribution Channel: Direct Sales, Distributors, E-Commerce Platforms, Wholesale Suppliers, Industrial Retailers |
| Companies Covered | Sealed Air Corporation, Sonoco Products Company, Pregis Corporation, ACH Foam Technologies, Plastifoam Company, Atlas Molded Products, UFP Technologies, ProtoPak Engineering Corporation, EnviroPAK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foamed End Caps Market Shifts & Advancements
Material science advances and regulatory chemistry mandates are compressing traditional foam specifications while opening bio-based and recycled-content alternatives. The competitive frontier is shifting toward certified circularity and thermal performance differentiation.
Expanded recycled polyethylene (rPE) formulations are integrating post-industrial scrap from automotive and appliance sectors into closed-cell end cap production. Packaging buyers in Germany and the Netherlands are specifying rPE content thresholds in tender documents. This material stream is integrating circularity metrics into supplier scorecards, compressing virgin resin dependence in European supply chains.
REACH restrictions on HBCDD and emerging restrictions on additional brominated flame retardants are compelling polystyrene reformulation toward phosphorus-nitrogen intumescent systems. Molded foam producers serving construction and electronics packaging are absorbing 12-18 month requalification cycles. The regulatory pressure is concentrating compliant supply among compounders with in-house flame retardant R&D, marginalizing toll converters.
Consolidated procurement of protection systems is displacing discrete component purchasing across industrial packaging. Electronics OEMs in Shenzhen and Dallas are issuing single-source contracts for foam-and-cradle modules rather than sourcing end caps, corner blocks, and surface films separately. This bundling behavior is most visible in semiconductor and server equipment logistics, where damage liability thresholds have tightened below 0.3% incident rates.
Foamed End Caps Market Segmentation
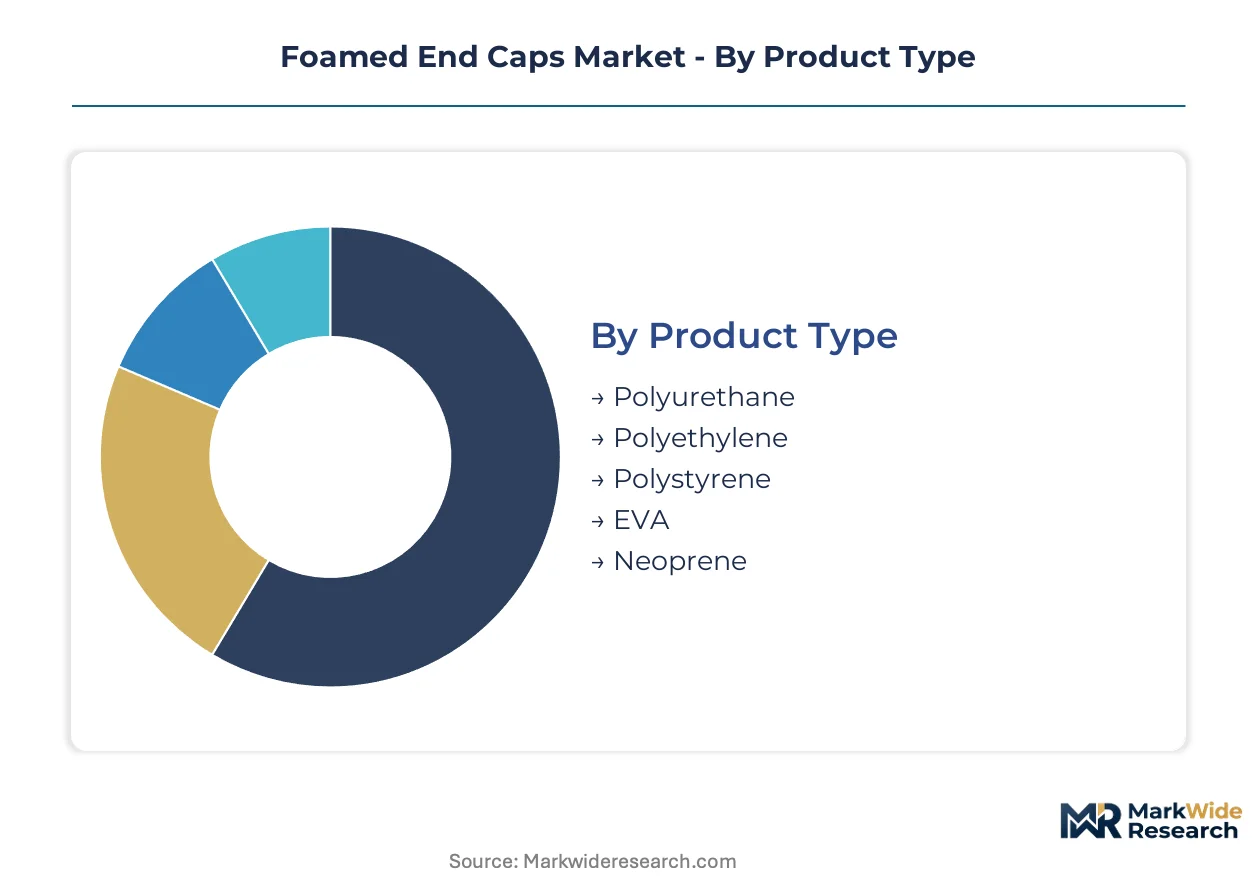
Foamed end caps serve divergent functional requirements across thermal, mechanical, and electrical protection domains. Segmentation reveals how material chemistry and distribution economics partition value capture between commodity converters and specialized compounders.
Product Type:
Polyethylene formulations dominate standalone cushioning applications, while polyurethane grades anchor embedded thermal systems requiring lambda-rated performance.
- Polyurethane:Closed-cell structures achieve thermal conductivity below 0.025 W/m·K, qualifying for district heating networks in Germany and commercial HVAC retrofits in the United States. MEE energy efficiency mandates in China are elevating specification density for high-performance insulation grades.
- Polyethylene:Moisture-resistant closed-cell chemistry supports recyclable packaging protection for electronics shipments. Procurement concentrates in Dutch and German automotive supply chains where post-industrial scrap integration meets circularity scorecards.
- Polystyrene:Cost-sensitive packaging protection remains entrenched despite REACH flame retardant restrictions compelling halogen-free reformulation.
- EVA:Shore hardness tunability suits medical device cushioning and precision instrument cradles requiring compression set recovery.
- Neoprene:Oil resistance and weathering stability serve marine fabrication and outdoor electrical enclosure sealing in coastal construction zones.
Volume placements concentrate in Polyethylene; the faster expansion belongs to Polyurethane.
Application:
Packaging protection commands the mature revenue base, while infrastructure-linked segments pull specialized foam grades into construction supply chains.
- Pipe Insulation:District heating deployment across German municipalities and commercial building retrofits in the United States specify molded end caps for thermal bridge elimination. BIS certification requirements in India are localizing procurement for Mumbai infrastructure corridors.
- Packaging Protection:Semiconductor and server equipment logistics in Shenzhen and Dallas specify bundled foam-and-cradle modules with damage liability thresholds below 0.3% incident rates. Consolidated procurement is displacing discrete component purchasing.
- Vibration Damping:Precision manufacturing investments in rotating machinery assemblies specify density-graded cellular structures for frequency isolation.
- Electrical Insulation:Dielectric strength requirements in switchgear and transformer applications favor cross-linked polyethylene formulations.
- Thermal Insulation:Lambda-rated specifications in cold chain logistics and building envelopes compete with mineral wool and aerogel alternatives.
Revenue gravity sits with Packaging Protection; Pipe Insulation is climbing the fastest on infrastructure stimulus.
End User Industry:
Construction and packaging buyers operate on divergent procurement calendars, with project-based contracting versus continuous replenishment determining inventory positioning.
- Construction Contractors:German district heating and US commercial retrofit pipelines specify certified thermal performance with 8-14 month compliance documentation cycles for cross-border suppliers.
- Packaging Manufacturers:Electronics OEMs in Shenzhen and Dallas issue single-source contracts for integrated protection systems rather than discrete foam components.
- Electrical Equipment Producers:Switchgear and transformer manufacturers specify dielectric-grade foams with flame retardant compliance under evolving EPA and REACH frameworks.
- HVAC Technicians:Service and installation channels pull standardized end cap modules through distributor networks for field replacement.
- Marine Fabricators:Neoprene and EPDM-foam hybrids serve saltwater-exposed sealing applications with MIL-spec durability requirements.
Contract volume concentrates with Packaging Manufacturers; Construction Contractors show the steepest specification upgrade trajectory.
Distribution Channel:
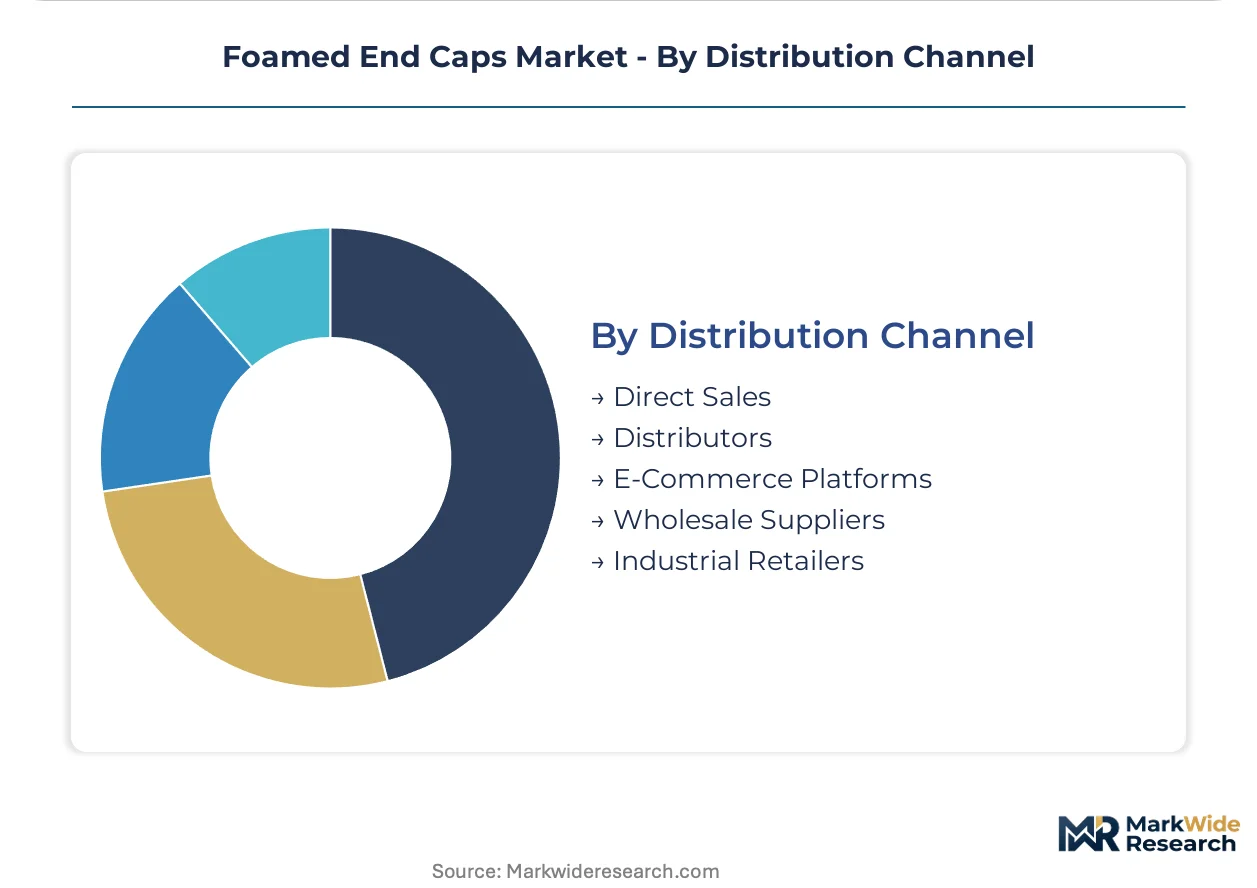
Channel selection tracks buyer scale and technical specification complexity, with direct relationships dominating certified thermal grades and distributors capturing maintenance replenishment.
- Direct Sales:Large-format construction projects and electronics OEMs negotiate single-source contracts for customized foam-and-cradle modules with integrated surface films.
- Distributors:Industrial supply houses stock standardized polyethylene and polystyrene grades for HVAC service channels and packaging converters.
- E-Commerce Platforms:Small-batch procurement for prototyping and maintenance applications concentrates on specialized industrial marketplaces.
- Wholesale Suppliers:Volume polyethylene formulations move through construction material wholesalers serving regional contractor networks.
- Industrial Retailers:Localized pickup options support just-in-time replenishment for maintenance, repair, and operations inventories.
Transaction value concentrates in Direct Sales; E-Commerce Platforms are gaining share fastest among small-batch technical buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany, China, and the United States while consumption spreads across industrial packaging and construction corridors. Manufacturing concentrates near petrochemical feedstock sources and molded foam converter networks. Demand fragmentation pulls specialized grades into district heating, electronics logistics, and HVAC retrofit channels.
United States
Commercial building retrofits and data center construction specify lambda-rated polyurethane for thermal bridge elimination. EPA Title V permitting tightens volatile organic compound controls on foam manufacturing. Dallas and Austin electronics corridors bundle foam-and-cradle protection systems for semiconductor equipment shipments.
Germany
District heating network expansions across municipalities drive molded end cap procurement for pipe insulation terminals. REACH flame retardant restrictions on halogenated additives compel polystyrene reformulation toward phosphorus-nitrogen systems. The Ruhr industrial belt hosts compounders integrating post-industrial polyethylene scrap into circular packaging grades.
China
Dual carbon goals elevate energy efficiency standards for building insulation materials in commercial HVAC applications. MEE mandates accelerate lambda-rated polyurethane specifications in district heating and cold chain infrastructure. Shenzhen electronics manufacturers issue single-source contracts for integrated protection modules serving server equipment logistics.
India
PLI scheme incentives for electronics manufacturing localize demand for protective foam components in precision equipment supply chains. BIS certification requirements tighten material specifications for industrial packaging used in export shipments. Mumbai and Bengaluru corridors develop molded foam converter capacity to serve automotive and medical device sectors.
Foamed End Caps Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material formulation and application engineering dimensions. The vendor base stratifies into three tiers: multinational packaging conglomerates with global manufacturing footprints, regional molded foam converters serving construction and industrial channels, and specialized compounders with in-house flame retardant R&D. Consolidation pressure concentrates compliant supply among larger players while margin compression forces smaller toll converters toward niche certification segments. Dominant competitive moves include backward integration into resin compounding and geographic expansion through distributor network capture.
Among North American packaging conglomerates, Sealed Air Corporation and Sonoco Products Company exemplify scale-driven archetypes with modular product platforms spanning multiple continents. Pregis Corporation occupies a position within the integrated protection systems tier, representing film-foam convergence strategies that bundle surface protection with impact absorption. These three anchors illustrate how procurement consolidation toward single-source contracts favors vendors with cross-material engineering capabilities and multi-jurisdiction compliance documentation.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Sonoco Products Company |
| Pregis Corporation |
| ACH Foam Technologies |
| Plastifoam Company |
| Atlas Molded Products |
| UFP Technologies |
| ProtoPak Engineering Corporation |
| EnviroPAK Corporation |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up foam converters in the United States and Germany have consolidated regional molding capacity, tightening supply discipline while extracting procurement leverage from fragmented packaging buyers. This ownership pattern concentrates pricing power among scaled compounders capable of absorbing REACH reformulation costs, forcing smaller toll molders toward niche certification segments or exit.
Pricing Analysis
Margin tightening in polystyrene grades reflects benzene feedstock volatility and 12-18 month requalification cycles for halogen-free flame retardant reformulation. Three-tier pricing structure across premium, standard, and economy levels separates lambda-rated polyurethane for district heating from commodity polyethylene packaging grades and residual monomer-constrained polystyrene. Cost-down pressure on standard-tier polyethylene accelerates because automotive OEMs are integrating post-industrial scrap thresholds into supplier scorecards. Small-batch precision equipment packers show least price sensitivity; construction contractors bidding municipal pipe insulation contracts exhibit highest sensitivity.
Supply Chain Analysis
Returns of non-conforming foam lots to compounders for regrind processing are tightening circularity metrics in Dutch and German supply chains. Manufacturing concentrates in Germany, China, and the United States near petrochemical feedstock clusters and converter networks. Raw material flows draw from ethylene crackers along the US Gulf Coast, benzene derivatives in northwest Europe, and isocyanate precursors concentrated in Belgium and Texas. Single-source vulnerability in isocyanate supply exposes foam manufacturers to weather-related disruption. Distribution runs through industrial supply houses stocking standardized grades for HVAC service channels and direct sales for customized foam-and-cradle modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market hinges on backward integration into resin compounding and captive flame retardant R&D, with first-mover advantages accruing to compounders that internalize reformulation expertise ahead of REACH deadlines.
For Market Incumbents: Cement supply security by acquiring regional toll molders with BIS certification capability in India and EPA Title V permits in the United States. Integrate in-house production of phosphorus-nitrogen intumescent systems to marginalize dependent converters when REACH restrictions tighten on residual brominated additives. For New Entrants and Emerging Players: Bio-based polyurethane formulations from agricultural feedstocks offer a technology-first wedge into premium cold chain logistics where lambda-rated performance commands specification premiums. Target underpenetrated medical device cushioning segments in Bengaluru and Dallas corridors where EVA compression set recovery requirements filter out commodity suppliers. Lead with film-foam lamination capabilities to capture single-source contracts displacing separate procurement. For Investors and Strategic Acquirers: First-mover halogen-free compounders securing ECHA pre-registration are the leading indicator that regulatory compliance is concentrating supply among scalable players. Five-to-ten year viability favors vertically integrated specialists with in-house flame retardant R&D and multi-jurisdiction documentation teams. Monitor EPA Title V permitting backlogs as early signals of supply constraint in US polyurethane manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of REACH-compliant polyethylene grades insulates margin from feedstock volatility. |
| Halogen-Free Flame Retardant R&D Investment | In-house phosphorus-nitrogen formulation capability accelerates requalification cycles ahead of ECHA deadlines. |
| Geographic Expansion into India | BIS certification and PLI scheme alignment localize supply for Mumbai electronics manufacturing corridors. |
| Film-Foam Lamination Capability Buildout | Integrated surface protection modules displace separate procurement in Shenzhen semiconductor logistics. |
| Post-Industrial Scrap Integration Programs | Automotive OEM circularity scorecards in Germany favor rPE content thresholds in supplier selection. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with foam compounder R&D directors, packaging procurement managers at electronics OEMs, HVAC contractor purchasing leads, and construction materials distributors. Secondary sources included ECHA restriction proposals, EPA Clean Air Act Title V permit databases, MEE energy efficiency standards, and BIS certification registries. Bottom-up modeling of molded foam converter capacity triangulated against top-down demand estimates from district heating deployment pipelines and electronics shipment volumes.
Granularity-level modeling disaggregated volume and value across the analysis window by material chemistry, application function, end-use industry procurement calendar, and distribution channel structure. CAGRs derived from regression of historical placement data against infrastructure investment schedules and regulatory compliance timelines. Industry-specific inputs included lambda-value specification density in German district heating tenders and damage liability thresholds in Dallas semiconductor logistics contracts.
Several conditions sit outside the modeled scope, including force majeure disruptions in US Gulf Coast petrochemical complexes, accelerated REACH restrictions beyond current ECHA consultation timelines, and substitution by aerogel or vacuum insulation panels in premium thermal applications. Forecasts reflect documented assumptions on feedstock price stability and regulatory implementation schedules. Practitioners should monitor EPA permitting backlogs, ECHA restriction proposal comment periods, and MEE dual carbon goal enforcement intensity for early signals of supply constraint or specification upgrade.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Crown Caps Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Brush Caps Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Indonesia Plastic Caps and Closures Market
Caps and Closures
Laminated Tube Closure Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Poland Plastic Caps and Closures Market
Caps and Closures
Spout Closures Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Metal Closures Market