
 Drone-As-A-Service Market | 2026-2036
Drone-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Drone-As-A-Service Market Insights
Certified remote pilot availability is reorganizing how Drone-As-A-Service providers scale regional operations. Terra Drone Corporation leverages its Asia-Pacific training infrastructure to sustain technician pipelines across multiple jurisdictions. PrecisionHawk anchors North American agricultural analytics through proprietary multispectral imaging workflows. Aerodyne Group dominates Southeast Asian infrastructure inspection with localized maintenance hubs.
Drone-As-A-Service denotes the commercial provision of unmanned aerial vehicle operations—typically platforms under 55 pounds with lithium-polymer power systems and RTK-GNSS positioning—on a contracted or subscription basis rather than through capital purchase. The model shifts capital burden from end users to operators while embedding sensor calibration, data processing, and regulatory compliance within service deliverables. Infrastructure Assessment applications command premium pricing due to structural defect liability exposure and specialized payload requirements. Delivery services represent the fastest-expanding application segment, though operational density remains constrained by beyond-visual-line-of-sight authorization bottlenecks. Surveying and Mapping services occupy mature margin pools where photogrammetry software commoditization pressures per-acre pricing.
FAA Part 107 waivers and the EU's U-Space regulatory framework shape market access by defining operational altitude ceilings, geofencing protocols, and remote identification mandates. EASA's specific category certification requirements for urban air mobility corridors are forcing operators to segregate fleet capabilities between rural and metropolitan deployment zones. Stakeholders must decide whether to build in-house regulatory affairs capabilities or outsource compliance to specialized aviation law consultancies as operational complexity scales.
Market Dynamics
Beyond-visual-line-of-sight authorization bottlenecks are forcing Drone-As-A-Service operators to segregate fleet capabilities between rural agricultural corridors and metropolitan infrastructure zones, compressing route economics and reshaping capital deployment priorities.
Growth Catalysts
- FAA Part 107 Remote Pilot Certification:Agricultural cooperatives across Texas, California, and Florida are expanding contracted crop monitoring services under standardized operator credentialing frameworks.
- Multispectral Imaging Workflows:Infrastructure Assessment applications command premium pricing through specialized payload integration and structural defect liability coverage.
- Lithium-Polymer Power Density:Extended flight endurance is unlocking corridor-scale surveys for pipeline and transmission line operators previously requiring manned aviation.
Market Restraints
- RTK-GNSS Component Concentration:Precision positioning module supply concentrates among specialized semiconductor fabricators, exposing operators to lead time volatility.
- EASA U-Space Geofencing Mandates:Urban air mobility corridor segregation requirements force redundant fleet configurations and maintenance hub duplication.
- Manned Aviation Substitution:Helicopter-based inspection retains altitude and payload flexibility advantages in mountainous terrain and offshore environments.
Strategic Opportunities
- EU Green Deal Agricultural Subsidies:European Union carbon monitoring mandates for precision farming are creating contracted service demand for soil carbon quantification flights.
- Photogrammetry Software Commoditization:Per-acre Surveying and Mapping pricing compression is opening white space for vertically integrated operators bundling capture-to-delivery workflows.
- Subscription-Based Fleet Access:Capital burden shifting from end users to operators enables smaller agricultural producers to access enterprise-grade sensor platforms without purchase commitments.
Industry Challenges
- Remote Identification Compliance:FAA broadcast requirements and EU networked remote ID mandates demand firmware retrofitting across legacy fleet assets.
- Battery Swapping Infrastructure:High-frequency delivery operations require distributed charging station networks with localized maintenance technician availability.
- Cross-Jurisdictional Certification Portability:Operator credentials recognized under Part 107 lack automatic reciprocity with EASA specific category or Civil Aviation Administration of China unmanned aerial vehicle operator frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone-As-A-Service Market |
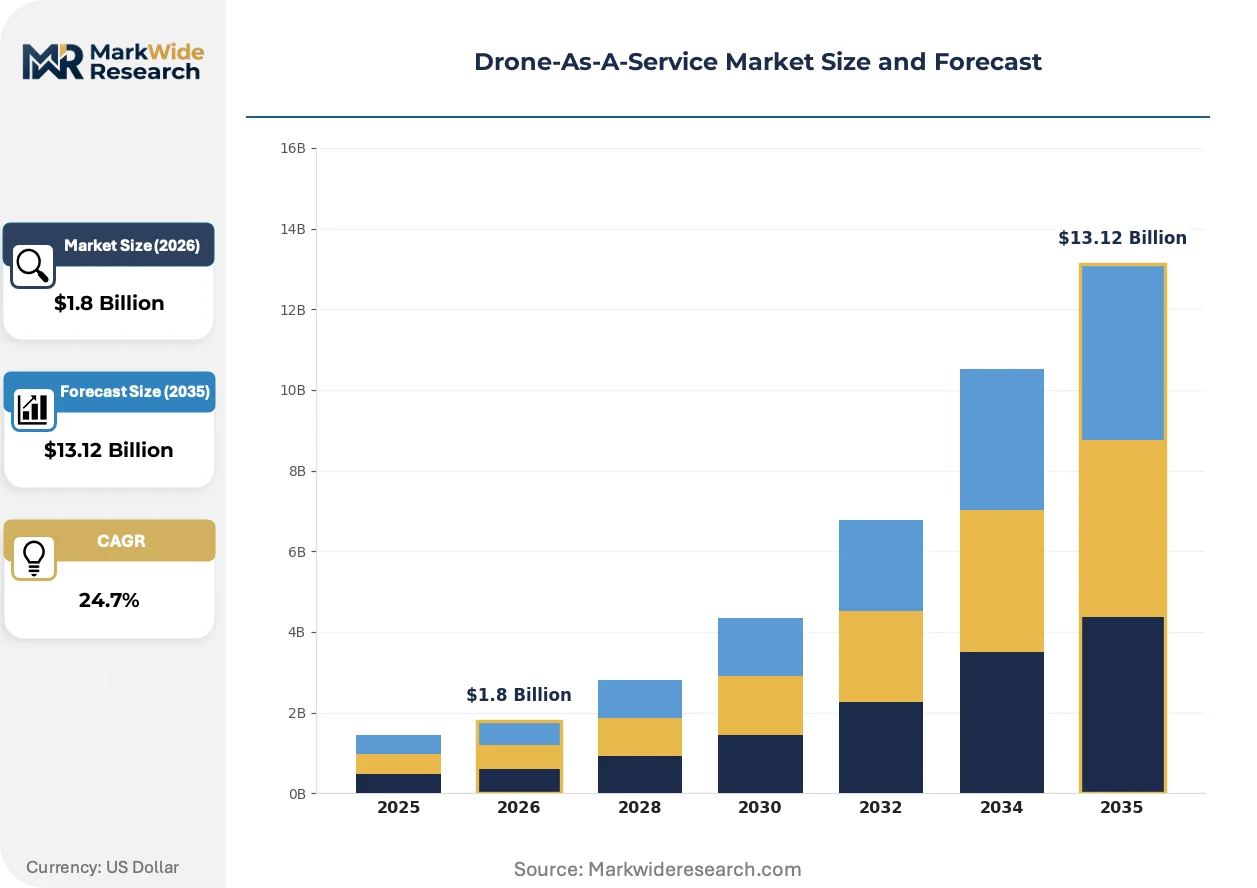
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.12 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
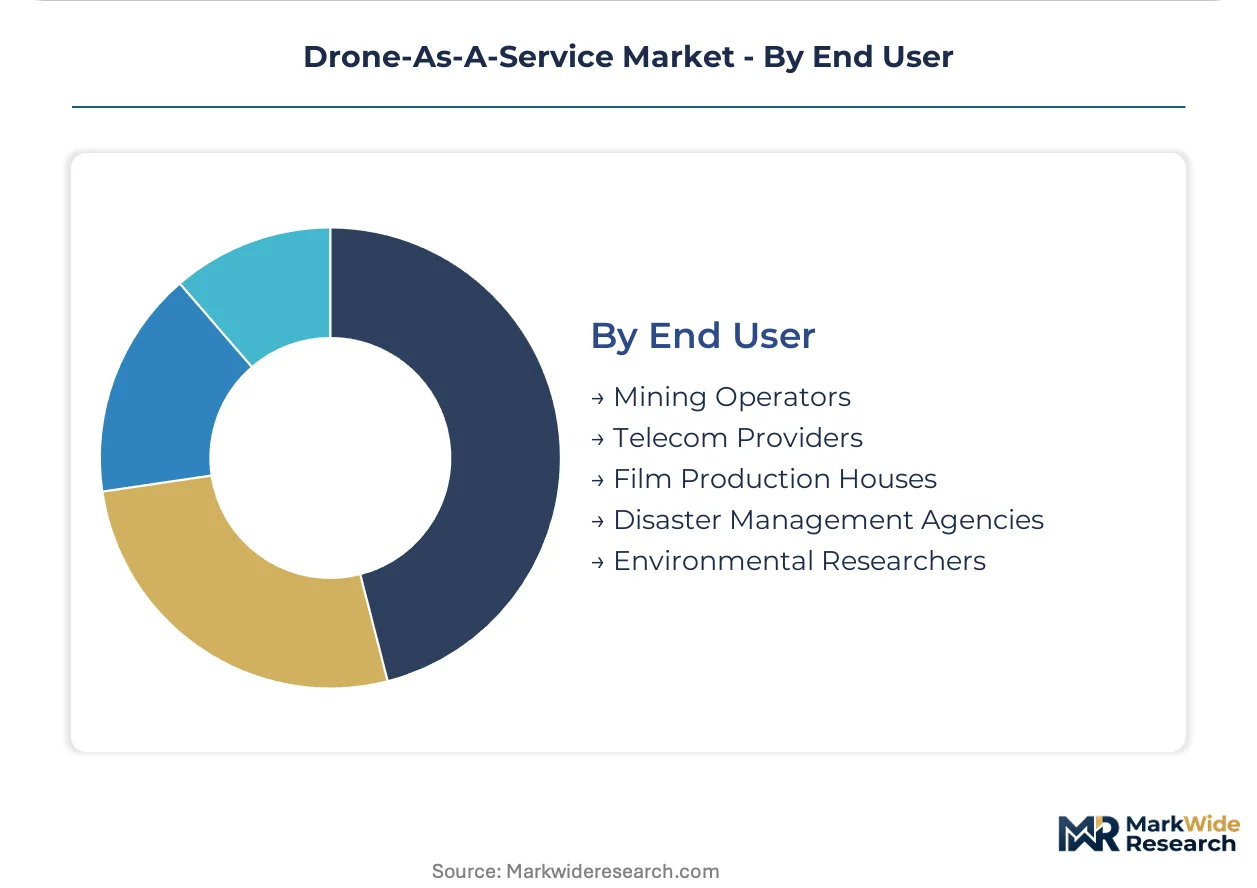
| Segmentation | Service Type: Surveying, Inspection, Delivery, Surveillance, Mapping, Event Coverage Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Application: Agriculture Monitoring, Infrastructure Assessment, Media Production, Emergency Response, Wildlife Tracking, Construction Management End User: Mining Operators, Telecom Providers, Film Production Houses, Disaster Management Agencies, Environmental Researchers |
| Companies Covered | Terra Drone Corporation, PrecisionHawk, Aerodyne Group, Cyberhawk Innovations Limited, DroneDeploy, Sky-Futures Ltd., Parrot Drones SAS, Delair, ZenaTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone-As-A-Service Market Trends and Innovations
Autonomous flight control architectures and edge-computing payload processing are compressing the latency between aerial capture and actionable intelligence delivery, reshaping competitive differentiation around real-time decision support rather than data volume.
Hybrid-electric propulsion architectures are bifurcating service fleet strategies across endurance-optimized fixed-wing platforms and maneuverability-focused multirotor systems. Agricultural corridor operators in the American Midwest are adopting fixed-wing assets for thousand-acre daily coverage, while infrastructure inspectors in Southeast Asian metropolitan zones prioritize multirotor precision. This technical segmentation is forcing operators to maintain dual maintenance pipelines and pilot certification tracks.
EASA's specific category certification requirements for urban air mobility corridors are mandating detect-and-avoid system integration and redundant flight control computers for metropolitan operations. Rural agricultural service providers face lighter compliance burdens under certified category frameworks, creating a two-tier regulatory environment. Operators are responding by segregating fleet assets between metropolitan and rural deployment zones with incompatible technical specifications.
Service contract structures are migrating from per-flight pricing to annual subscription models bundling sensor calibration, regulatory compliance, and data processing. Agricultural cooperatives and infrastructure asset managers are consolidating vendor relationships around integrated service platforms. This consolidation is most visible across Texas, California, and Florida where multi-year crop monitoring and corridor survey agreements are displacing transactional flight purchasing.
Drone-As-A-Service Market Segmentation
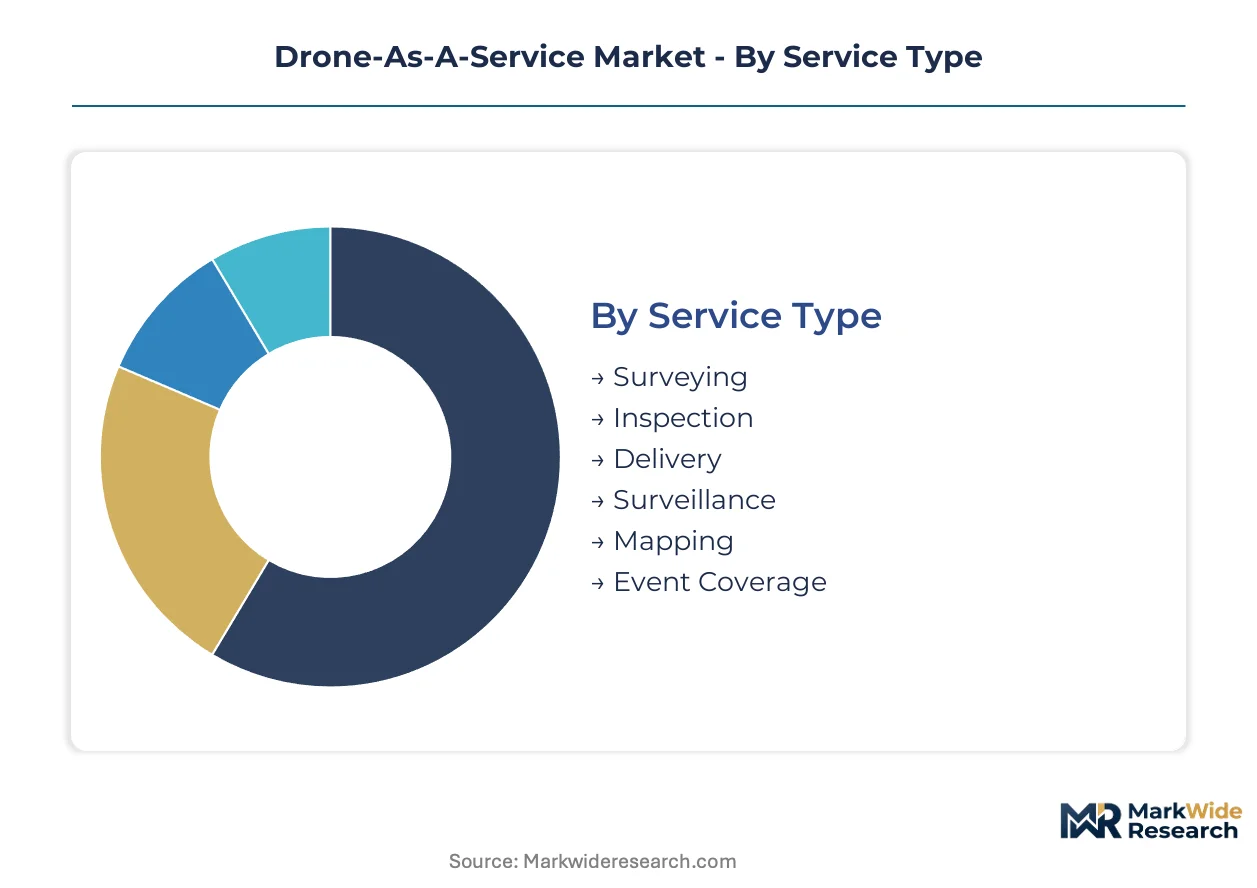
Drone-As-A-Service segmentation reveals how capital deployment and regulatory exposure concentrate across distinct operational profiles. Service type and application selection directly determine fleet configuration, pilot certification requirements, and liability coverage structures for operators.
Service Type:
Margin pools concentrate in inspection and surveying workflows where specialized payloads and structural defect liability exposure justify premium pricing tiers.
- Surveying:Photogrammetry-driven terrain modeling with RTK-GNSS positioning accuracy below 3 centimeters. Demand clusters in Texas pipeline corridors and California utility corridors where per-mile data collection contracts displace manned helicopter surveys. Per-acre pricing compression from software commoditization is forcing operators toward bundled capture-to-delivery workflows.
- Inspection:Structural defect detection using thermal and multispectral imaging payloads for transmission towers, bridges, and offshore assets. Infrastructure Assessment commands premium pricing due to liability exposure and specialized sensor integration requirements. EASA specific category certification mandates for urban corridors are bifurcating fleet capabilities between metropolitan and rural deployment zones.
- Delivery:Last-mile package transport under beyond-visual-line-of-sight waivers. Battery swapping infrastructure requirements and FAA authorization bottlenecks constrain operational density.
- Surveillance:Persistent monitoring for security and perimeter applications. Remote identification compliance mandates demand firmware retrofitting across legacy fleet assets.
- Mapping:Cartographic data collection for urban planning and land registry updates. Subscription contract migration is displacing transactional flight purchasing.
- Event Coverage:Aerial cinematography for sports and entertainment productions. Crowded airspace coordination requirements limit scalable deployment.
Inspection holds installed capacity. Delivery is rotating up the share rankings.
Deployment Model:
Cost tier separation runs from capital-intensive on-premises installations to variable-cost public cloud arrangements, with hybrid configurations capturing mid-market agricultural cooperatives.
- Public Cloud:Multi-tenant data processing infrastructure with subscription-based sensor platform access. Smaller agricultural producers in the American Midwest leverage this model to access enterprise-grade multispectral imaging without capital purchase commitments.
- Private Cloud:Dedicated compute environments for sensitive infrastructure data with enhanced cybersecurity protocols. Telecom providers and mining operators mandate this tier for proprietary corridor survey data.
- Hybrid Cloud:Edge-computing payload processing with cloud-based archival and analytics. Agricultural cooperatives across Texas, California, and Florida are consolidating vendor relationships around this integrated service platform.
- On-Premises:Fully captive data infrastructure for classified government and defense applications. Disaster Management Agencies require air-gapped processing for emergency response coordination.
Public Cloud is climbing the fastest. Hybrid Cloud retains the largest active contract base.
Application:
Volume concentration sits in agriculture where thousand-acre daily coverage contracts standardize around fixed-wing platforms, while infrastructure assessment generates superior unit economics through specialized payload requirements.
- Agriculture Monitoring:Crop health assessment via multispectral and thermal imaging with nitrogen deficiency and irrigation stress detection. FAA Part 107 remote pilot certification frameworks enable agricultural cooperatives across Texas, California, and Florida to expand contracted monitoring services.
- Infrastructure Assessment:Structural integrity evaluation for pipelines, transmission lines, and transportation assets. Premium pricing reflects defect liability exposure and RTK-GNSS precision requirements.
- Media Production:Cinematic aerial cinematography with maneuverability-optimized multirotor systems. Film Production Houses drive demand in metropolitan zones with complex airspace coordination.
- Emergency Response:Rapid deployment for search-and-rescue and disaster damage assessment. Disaster Management Agencies require BVLOS authorization for effective coverage.
- Wildlife Tracking:Ecological monitoring with minimal-disturbance flight protocols. Environmental Researchers prioritize acoustic payload integration for species identification.
- Construction Management:Progress monitoring and earthwork volume calculation. Lithium-polymer power density improvements enable corridor-scale surveys previously requiring manned aviation.
Agriculture Monitoring retains contract volume leadership. Infrastructure Assessment is gaining share fastest.
End User:
Customer type determines procurement sophistication, with mining and telecom operators driving multi-year integrated service agreements while environmental researchers remain transactional.
- Mining Operators:Pit wall stability monitoring and haul road condition assessment with dust-resistant payload enclosures. Volume-based contracts span multiple extraction sites with standardized reporting protocols.
- Telecom Providers:Cell tower inspection and line-of-sight verification for network expansion. Multi-tenant infrastructure sharing agreements are consolidating vendor relationships.
- Film Production Houses:Aerial cinematography with real-time director monitoring capabilities. Metropolitan airspace complexity favors established operators with FAA waiver portfolios.
- Disaster Management Agencies:Rapid damage assessment and supply chain restoration prioritization. On-premises data processing mandates limit vendor eligibility.
- Environmental Researchers:Carbon stock quantification and habitat fragmentation analysis. EU Green Deal agricultural subsidies are creating contracted demand for soil carbon monitoring flights.
Telecom Providers anchor recurring revenue. Environmental Researchers are expanding contract frequency fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 107 certification frameworks anchor the United States as the dominant geography for commercial drone services, with regulatory clarity enabling scaled agricultural and infrastructure operations across multiple state jurisdictions.
United States
Agricultural cooperatives across Texas, California, and Florida are expanding contracted crop monitoring services under standardized operator credentialing. FAA Part 107 remote pilot certification requirements create entry barriers that favor established training pipelines. The American Midwest corridor concentrates thousand-acre daily coverage contracts for fixed-wing agricultural surveys.
China
Precision farming subsidies and dual carbon monitoring goals are accelerating soil carbon quantification flight demand across Yangtze River Delta agricultural zones. MIIT unmanned aerial vehicle operator frameworks lack automatic reciprocity with Western certifications, fragmenting cross-border technician mobility. Shenzhen and Beijing anchor domestic fleet manufacturing and maintenance hub networks.
Germany
Industrial corridor inspection contracts for pipeline and transmission operators concentrate in North Rhine-Westphalia and Bavaria. EASA U-Space geofencing mandates force redundant fleet configurations for metropolitan versus rural deployment zones. Stuttgart and Munich host specialized aviation law consultancies serving operator compliance outsourcing demand.
Australia
Mining pit wall stability monitoring and haul road condition assessment drive volume-based multi-site contracts across Western Australia and Queensland. The country's national aviation regulator maintains distinct certification tracks for beyond-visual-line-of-sight operations in remote extraction zones. Perth anchors dust-resistant payload integration and maintenance technician networks.
Japan
Metropolitan infrastructure inspection demand concentrates in Tokyo and Osaka corridors under METI urban air mobility corridor guidelines. JIS standards for detect-and-avoid system integration create compliance premiums for metropolitan fleet assets. Nagoya hosts hybrid-electric propulsion testing facilities bifurcating fixed-wing and multirotor service strategies.
Drone-As-A-Service Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with specialized sensor integrators commanding premium pricing in infrastructure assessment while scale-driven operators compress per-acre agricultural margins. The vendor base organizes around three strategic archetypes: Asia-Pacific training infrastructure owners sustaining technician pipelines, North American analytics platforms embedding proprietary multispectral workflows, and Southeast Asian maintenance hub operators dominating localized inspection markets. Consolidation pressure is accelerating through multi-year integrated service agreements and subscription-based fleet access models that displace transactional purchasing.
Within the Asia-Pacific training infrastructure tier, Terra Drone Corporation exemplifies the jurisdiction-spanning operator archetype. PrecisionHawk occupies a position representing North American agricultural analytics specialization. Aerodyne Group anchors the Southeast Asian metropolitan infrastructure inspection segment. These three entities illustrate how geographic certification portability constraints and localized maintenance requirements shape competitive positioning without automatic cross-border credential recognition.
| Leading Market Players |
|---|
| Terra Drone Corporation |
| PrecisionHawk |
| Aerodyne Group |
| Cyberhawk Innovations Limited |
| DroneDeploy |
| Sky-Futures Ltd. |
| Parrot Drones SAS |
| Delair |
| ZenaTech |
| Others |
Pricing and Supply Chain Analysis
Lithium-polymer battery density improvements substituting for manned aviation fuel costs are redrawing procurement geography across American Midwest agricultural corridors and Southeast Asian metropolitan zones while compressing per-mile survey economics below helicopter-based benchmarks.
Pricing Analysis
Texas-to-California pricing spreads for thousand-acre crop monitoring contracts exceed infrastructure corridor surveys in Florida by margins reflecting RTK-GNSS payload certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates EASA specific category-certified metropolitan fleets from FAA Part 107 rural agricultural operations. Cost compression in standard-tier agricultural monitoring is intensifying because photogrammetry software commoditization erodes per-acre data value. Mining operators exhibit lowest price sensitivity due to defect liability exposure, while environmental researchers drive hardest bargain terms.
Supply Chain Analysis
Inventory lead times for RTK-GNSS positioning modules stretch across specialized semiconductor fabricators in Taiwan, South Korea, and Germany, exposing operators to procurement volatility. Lithium-polymer cells, carbon-fiber airframes, and multispectral imaging sensors feed from concentrated East Asian manufacturing clusters. Single-source vulnerability concentrates in precision navigation chipsets where alternative qualification cycles extend deployment readiness. Distribution runs through regional maintenance hubs with localized technician certification tracks rather than direct OEM fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beyond-visual-line-of-sight authorization frameworks represent a regulatory inflection accelerating Drone-As-A-Service disruption, with operators capturing corridor-scale contracts previously requiring manned aviation capital deployment.
For Market Incumbents: Compound training infrastructure advantages across multiple FAA Part 107 and EASA U-Space jurisdictions to lock in technician pipeline scarcity. Acquire specialized sensor calibration capabilities to defend premium pricing in infrastructure assessment segments against emerging analytics platforms. Vertical integration into lithium-polymer battery swapping networks secures operational density in delivery corridors. For New Entrants and Emerging Players: Subscription-based fleet access for smaller agricultural producers represents an underserved service layer where capital burden shifting creates vendor consolidation opportunities. Target American Midwest cooperatives with bundled capture-to-delivery workflows bypassing commoditized per-acre pricing. Lead with hybrid cloud deployment models embedding edge-computing payload processing. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors Asia-Pacific training infrastructure owners with cross-jurisdictional certification portability. Long-term viability hinges on regulatory compliance capabilities spanning FAA, EASA, and MIIT frameworks. Watch for BVLOS authorization density as the signal indicating which metropolitan corridors will support scaled delivery economics.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Training Infrastructure | Cross-border technician pipelines under FAA Part 107 and EASA U-Space sustain fleet scaling. |
| Hybrid-Electric Propulsion Certification | Fixed-wing and multirotor dual qualification unlocks agricultural and infrastructure segmentation. |
| Edge-Computing Payload Integration | Real-time defect detection differentiates inspection services from post-flight data processing competitors. |
| Subscription Fleet Access Models | Capital burden shifting consolidates smaller agricultural producers around integrated service platforms. |
| Detect-and-Avoid System Deployment | EASA specific category compliance enables metropolitan corridor entry with premium liability coverage. |
Research Methodology
Operator-level perspectives from remote pilot certification directors, agricultural cooperative procurement officers, infrastructure asset managers, and aviation law compliance consultants anchored the qualitative base. FAA Part 107 waiver databases, EASA U-Space implementation trackers, EU Green Deal agricultural subsidy filings, and customs records for RTK-GNSS component trade flows provided secondary validation. Bottom-up service contract enumeration across Texas, California, and Florida triangulated against top-down fleet deployment estimates.
Sensitivity analysis tested forecast robustness across BVLOS authorization timeline scenarios and lithium-polymer battery cost trajectories throughout the projection horizon. Segmentation dimensions modeled include service type, deployment model, application, and end-user procurement sophistication. CAGRs derived from fitted growth curves applied to operator-reported contract volumes. Industry-specific inputs incorporated EASA specific category certification adoption rates and MIIT unmanned aerial vehicle operator framework expansion.
Forecasts assume regulatory continuity in FAA Part 107, EASA U-Space, and MIIT unmanned aerial vehicle regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Ultra-Long Endurance Drone Market
UAV
Drone Payload Market
UAV
Fixed Wing Military Drones Market
UAV
United States Drone Services Market
UAV
Toy Drones Market
UAV
UAV Battery Market
UAV
North America Small UAV Market
UAV
Combat Drone Market
UAV
Asia Pacific Commercial Drone Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Commercial Drone-Enabled Services Market
UAV
Drone Inspection Service Market
UAV
UAV Simulator Software Market
UAV
Counter Drone System Market
UAV
North America Drones Market
UAV
Asia-Pacific Drone Motor Market